
 Pipe Wrapping Machines Market | 2026-2036
Pipe Wrapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Wrapping Machines Market Analytics
Chinese equipment fabricators is realigning export capacity toward higher-specification wrapping systems for corrosion protection. Signode Industrial Group LLC leverages its strapping and containment heritage to anchor position in heavy-gauge pipe bundling. ProMach Inc. competes through modular platform architectures that span semi-automatic and fully automatic configurations. Maillis Group S.A. differentiates via integrated stretch film and woven strapping solutions for multi-material pipeline projects.
Pipe wrapping machines apply protective films, tapes, or extruded coatings around cylindrical metal, concrete, or composite pipes to prevent corrosion, abrasion, and environmental degradation during storage, transport, and burial, typically operating at line speeds between 5 and 50 meters per minute depending on pipe diameter and material thickness. Automatic systems now dominate new capital expenditure in oil and gas applications where throughput requirements exceed 1,000 pipe segments per shift, while semi-automatic units sustain margin pools among regional water supply contractors with variable batch sizes. Polyethylene material configurations are capturing fastest-growing share as operators substitute solvent-based coatings with thermoplastic barrier layers that simplify waste handling and reduce volatile organic compound exposure.
OSHA workplace exposure limits and EPA National Emission Standards for Hazardous Air Pollutants constrain coating chemistry choices and ventilation design for domestic manufacturing facilities, while EU machinery safety directives enforced by national notified bodies mandate interlocked guarding and emergency stop architectures on equipment imported into European member states. Stakeholders must monitor evolving PFAS restrictions under state-level environmental regulations and assess backward integration into recyclable polymer feedstocks before supplier qualification requirements tighten.
Market Dynamics
Pipeline integrity mandates from PHMSA are forcing oil and gas operators to replace manual wrapping stations with automated systems capable of real-time coating thickness verification and digital audit trails. This regulatory compression is redistributing capital budgets toward integrated wrapping lines and away from standalone equipment purchases.
Growth Catalysts
- PHMSA Integrity Management Rules:US pipeline operators must demonstrate corrosion prevention through documented coating application, driving systematic replacement of manual stations with automated wrapping systems that generate compliance-ready data logs.
- Polyethylene Barrier Substitution:Thermoplastic film configurations are displacing solvent-based coatings as operators seek to eliminate volatile organic compound handling and simplify hazardous waste disposal protocols.
- German Industrial Equipment Cycles:Steel-intensive manufacturing clusters in the Ruhr region are modernizing pipe handling infrastructure to align with EU machinery safety directives and carbon reduction targets.
Market Restraints
- Steel Price Volatility:Fluctuations in hot-rolled coil costs inflate the delivered price of heavy-gauge pipe bundling systems, compressing margins for regional water supply contractors with fixed municipal budgets.
- Control System Concentration:Programmable logic controller and servo motor supply chains concentrate in East Asian manufacturing hubs, exposing European and North American fabricators to extended lead times during logistics disruptions.
- PFAS Regulatory Uncertainty:Evolving state-level restrictions on per- and polyfluoroalkyl substances in the US create formulation compliance risk for fluoropolymer-based corrosion barrier suppliers.
Strategic Opportunities
- Modular Platform Architectures:Equipment suppliers can capture margin pools among regional contractors by offering field-upgradable semi-automatic systems that transition to fully automatic configurations as throughput requirements expand.
- Recyclable Polymer Feedstocks:Backward integration into post-industrial polyethylene recycling streams positions suppliers ahead of tightening EU supplier qualification requirements under the Green Deal.
- Multi-Material Pipeline Projects:Integrated stretch film and woven strapping solutions address emerging demand from composite pipe installations in offshore wind cable protection systems.
Industry Challenges
- Interlocked Guarding Certification:EU machinery safety directives enforced by German notified bodies mandate complex emergency stop architectures that extend design validation timelines for equipment imported into European member states.
- Legacy System Integration:Oil and gas operators with existing SCADA infrastructure face protocol compatibility barriers when connecting new wrapping line sensors to decades-old distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Wrapping Machines Market |
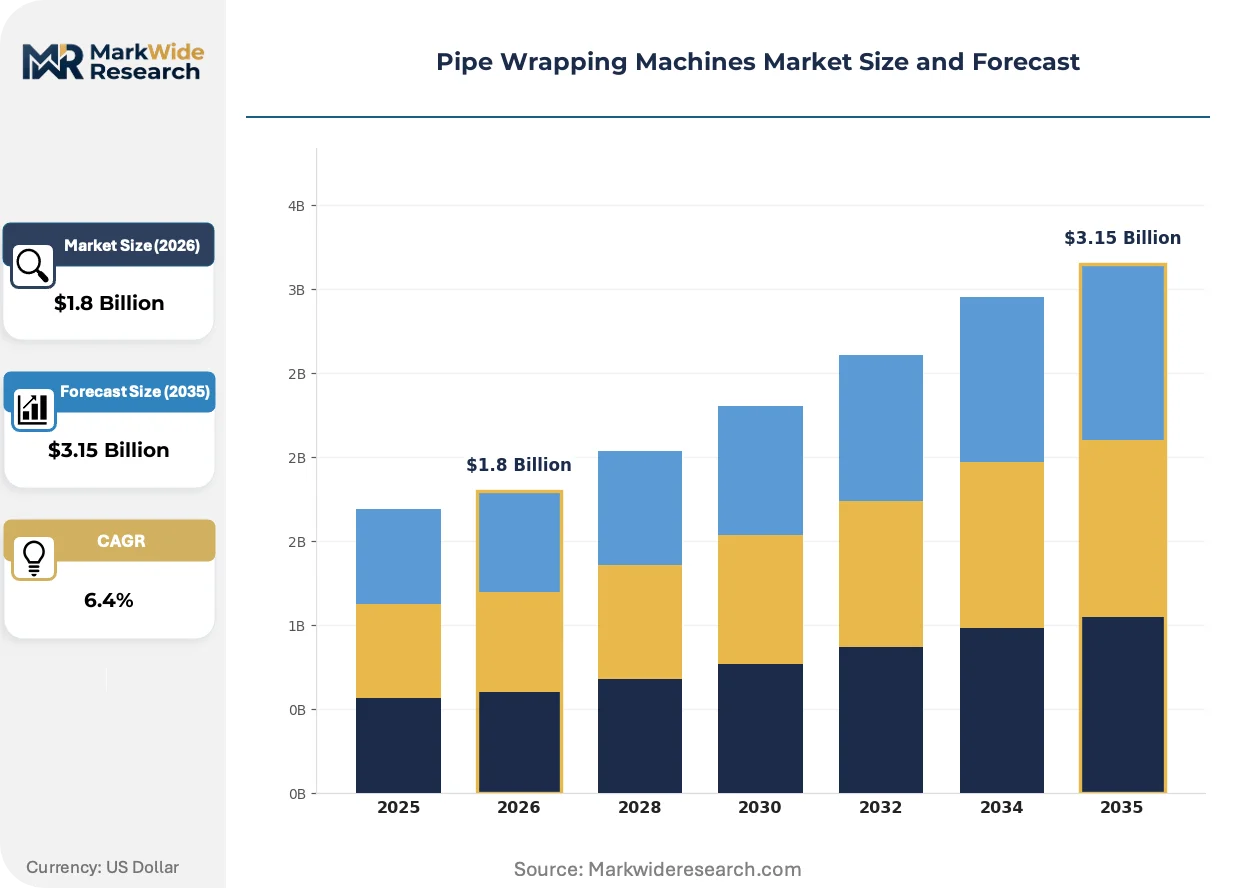
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customized Material: PVC, PE, Polypropylene, Aluminum Application: Construction, Oil & Gas, Water Supply, Chemical Processing End User: Manufacturers, Contractors, Distributors, Resellers |
| Companies Covered | Signode Industrial Group LLC, ProMach Inc., Maillis Group S.A., LanTech LLC, Grupo ULMA S. Coop., Aetna International S.p.A., Wulftec International Inc., Lantech, Technowrapp s.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Wrapping Machines Market Evolving Landscape
Digital coating verification systems are compressing quality assurance cycles from offline laboratory testing to inline spectral analysis. Equipment architecture is converging around modular platforms that span manual, semi-automatic, and fully automatic configurations.
Ultrasonic and eddy-current inline inspection modules are unifying corrosion barrier application with real-time defect detection, eliminating the buffer inventory previously required between wrapping stations and shipping yards. Offshore pipeline contractors in the Gulf of Mexico are adopting these integrated lines most aggressively, compressing project schedules by removing discrete inspection handling steps.
EPA National Emission Standards for Hazardous Air Pollutants are constraining coating chemistry choices and ventilation design for domestic manufacturing facilities. Equipment suppliers must now engineer enclosed application chambers with negative pressure containment and thermal oxidizer integration. Water supply contractors in California face the steepest compliance cost escalation as local air quality management districts layer additional solvent exposure limits atop federal baselines.
Specification-driven procurement now dominates oil and gas capital expenditure, with engineering firms consolidating vendor qualification around pre-certified platform architectures rather than evaluating equipment on a project-by-project basis. This concentration is displacing regional equipment brokers who previously intermediated between fabricators and contractors. The shift is most visible in Texas and Alberta, where integrated energy companies have centralized procurement through approved vendor lists.
Pipe Wrapping Machines Market Segmentation
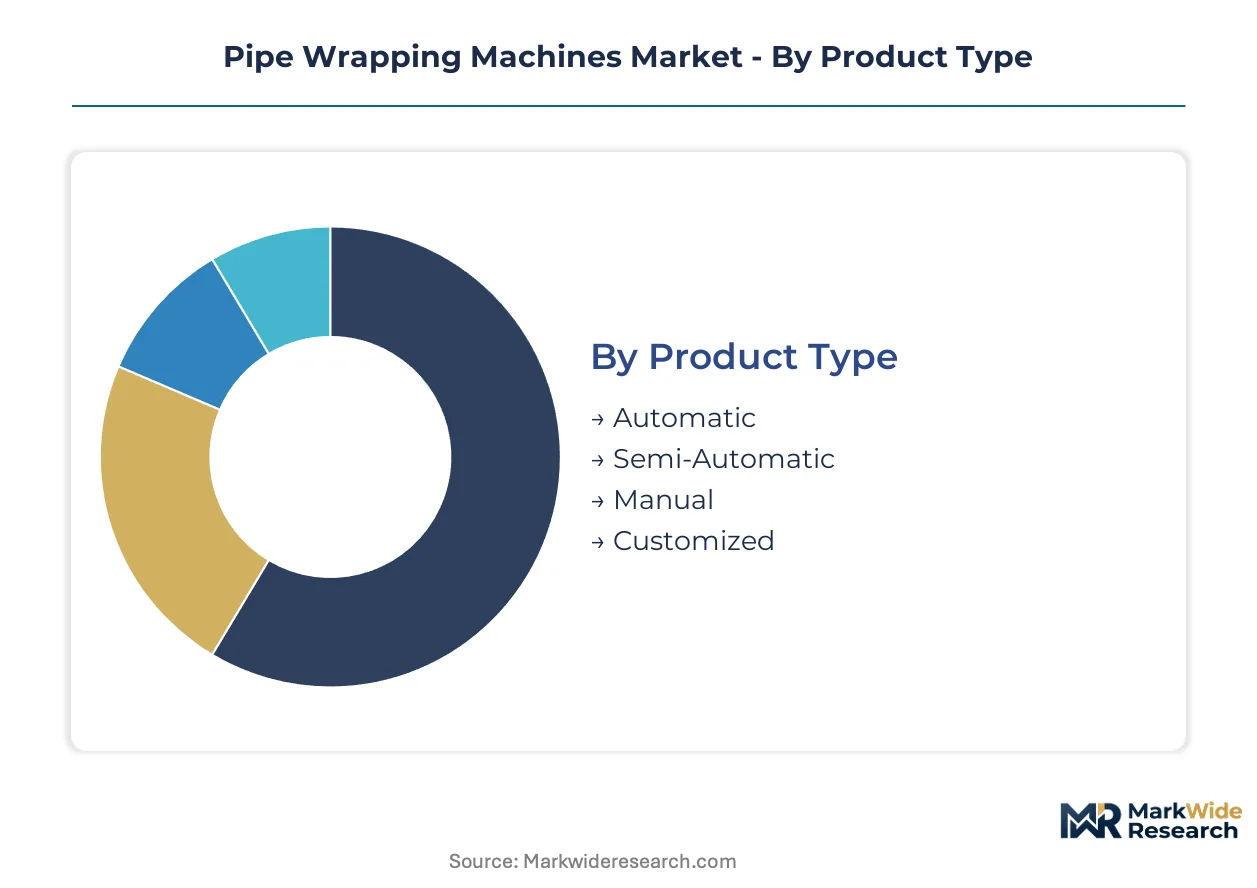
Segmentation in pipe wrapping machines reveals how equipment specifications align with distinct operational environments. Each dimension—automation level, material compatibility, application intensity, and buyer type—carries different margin structures and regulatory exposure.
Product Type:
Integration depth varies sharply across automation tiers, with standalone units dominating maintenance budgets while embedded lines capture new capital expenditure.
- Automatic:These systems integrate programmable logic controllers with real-time coating thickness verification and digital audit trail generation. Oil and gas pipeline operators in Texas and Alberta are systematically replacing manual stations to satisfy PHMSA integrity management documentation requirements.
- Semi-Automatic:Field-upgradable architectures allow regional water supply contractors to defer full automation capital until throughput thresholds justify the investment. German steel fabricators in the Ruhr region favor these configurations for batch flexibility amid variable project pipelines.
- Manual:Portable wrapping stations serve repair contractors and small-diameter pipe specialists with intermittent demand patterns.
- Customized:Engineered-to-order systems address non-standard pipe geometries or extreme corrosion environments in offshore installations.
Volume placements concentrate in Automatic systems; the faster expansion belongs to Semi-Automatic configurations as mid-tier contractors seek upgrade pathways.
Material:
Material selection determines chemical compliance burden and end-of-life handling protocols across manufacturing facilities.
- PE:Thermoplastic polyethylene films displace solvent-based coatings as EPA National Emission Standards constrain volatile organic compound exposure in domestic production. Water supply contractors in California face layered compliance costs as local air districts impose additional limits.
- Polypropylene:High-temperature stability suits chemical processing pipelines where thermal cycling degrades alternative barriers. German manufacturers align procurement with EU Green Deal recyclability requirements for post-industrial feedstock integration.
- PVC:Cost-effective barrier properties sustain demand in municipal water infrastructure with fixed budget constraints.
- Aluminum:Metallic foil laminates serve high-temperature oil and gas gathering lines where mechanical damage risk exceeds polymer limitations.
Procurement volume tilts toward PE; polypropylene is climbing the fastest as chemical processing capacity expands.
Application:
Application segmentation maps directly to regulatory intensity and inspection frequency mandates.
- Oil & Gas:PHMSA corrosion prevention rules mandate documented coating application with inline inspection integration. Gulf of Mexico offshore contractors are adopting unified wrapping and defect detection lines most aggressively.
- Water Supply:Municipal procurement cycles favor semi-automatic equipment with lower capital thresholds. Regional contractors in the US Southwest manage variable batch sizes across aging distribution network replacement programs.
- Construction:General infrastructure projects prioritize cost efficiency over automation depth.
- Chemical Processing:Aggressive service environments demand material specifications exceeding standard commercial offerings.
Capital allocation concentrates in Oil & Gas; Water Supply is gaining share fastest as federal infrastructure funding flows to distribution system modernization.
End User:
Buyer type determines specification authority and equipment financing structures.
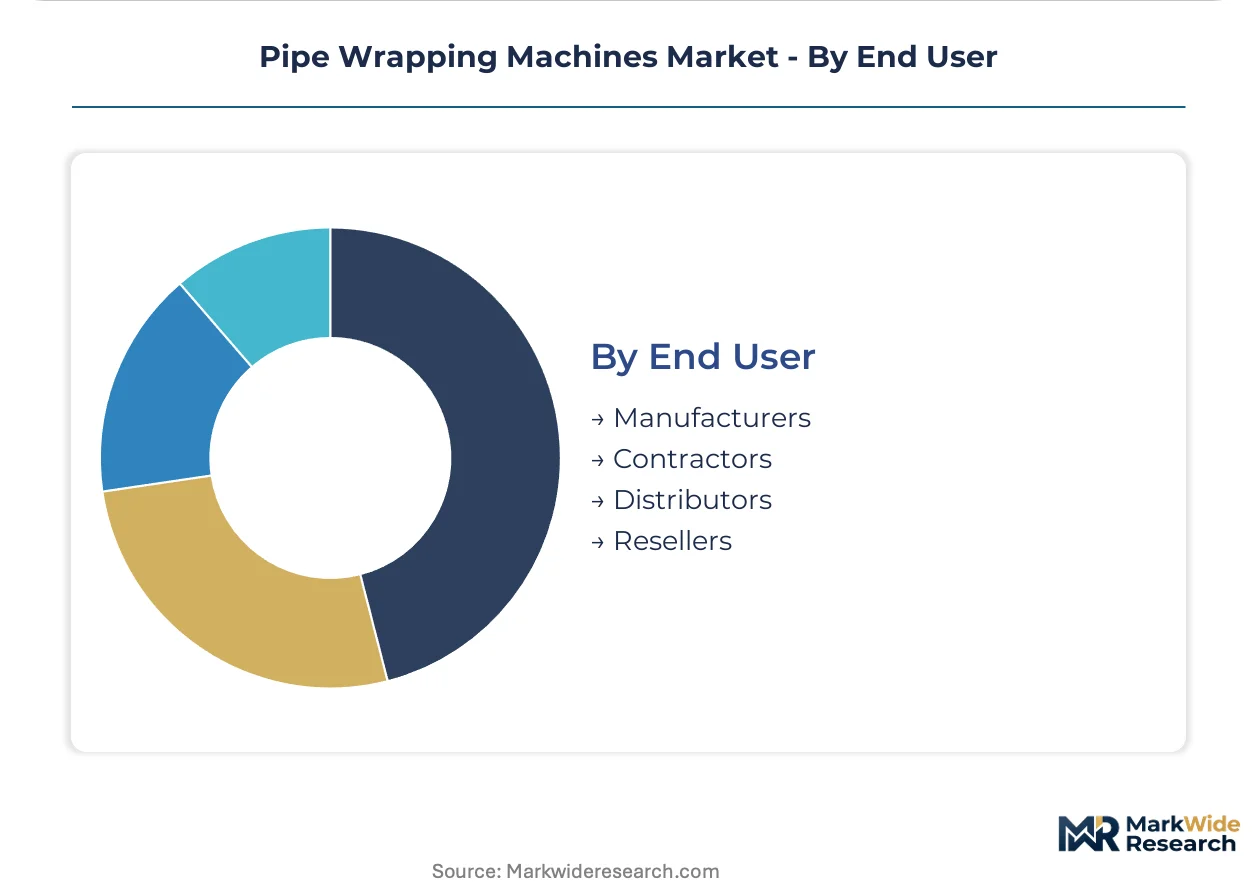
- Manufacturers:Steel pipe mills integrate wrapping lines directly into continuous production sequences. German producers modernize Ruhr-region facilities to satisfy EU machinery safety directive interlocked guarding requirements.
- Contractors:Project-based procurement drives rental and lease demand for specialized offshore configurations.
- Distributors:Inventory positioning strategies concentrate on semi-automatic units with broad application flexibility.
- Resellers:Regional equipment brokers face displacement as engineering firms consolidate vendor qualification around pre-certified platform architectures.
Transaction volume concentrates among Manufacturers; Contractors are expanding most quickly as project outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel coil supply from Ruhr-region mills and polyethylene resin production along the US Gulf Coast anchor geographic demand patterns for pipe wrapping equipment. Regulatory divergence between PHMSA corrosion mandates in North America and EU machinery safety directives in Europe drives specification fragmentation. Fabricators in East Asian manufacturing hubs concentrate control system component supply, exposing lead time volatility.
United States
PHMSA integrity management rules compel oil and gas operators in Texas and the Gulf of Mexico to automate coating verification with digital audit trails. EPA National Emission Standards constrain solvent-based coating formulations, pushing thermoplastic barrier adoption. Houston-area pipeline service contractors are consolidating procurement through pre-certified vendor lists, displacing regional equipment brokers.
Germany
Ruhr-region steel fabricators modernize pipe handling infrastructure to satisfy EU machinery safety directive interlocked guarding requirements. The national regulator enforces complex emergency stop architectures that extend design validation timelines for imported equipment. Industrial equipment upgrade cycles in North Rhine-Westphalia align procurement with carbon reduction targets for steel-intensive manufacturing clusters.
China
Equipment fabricators in Yangtze River Delta manufacturing zones realign export capacity toward higher-specification corrosion protection systems. MIIT industrial upgrading policies accelerate domestic substitution of programmable logic controllers and servo motors. Zhengzhou and Shandong equipment production clusters supply semi-automatic configurations for water infrastructure contractors across Southeast Asia and Africa.
Canada
Alberta oil sands operators and British Columbia LNG export terminal contractors drive demand for heavy-gauge pipe bundling systems. Health Canada workplace exposure guidelines layer atop federal environmental baselines, constraining coating chemistry choices. Toronto-area engineering firms consolidate vendor qualification around platform architectures that span manual through fully automatic configurations.
India
Steel Authority of India and private pipe mills in Maharashtra and Gujarat integrate wrapping lines into continuous production sequences. BIS certification requirements and state-level environmental clearances create compliance complexity for imported machinery. Infrastructure investment in water distribution networks across Delhi-NCR and Tamil Nadu sustains semi-automatic equipment demand among regional contractors with variable batch sizes.
Pipe Wrapping Machines Market Competitive Landscape
Global majors compete with regional champions across automation tiers and material specialization vectors. The vendor base clusters around three strategic archetypes: integrated packaging conglomerates with strapping heritage, modular platform specialists spanning semi-automatic to fully automatic configurations, and film-and-tape integrated solution providers. Dominant competitive moves include backward integration into recyclable polymer feedstocks and field-upgradable architecture development that captures margin pools among mid-tier contractors.
Among US-based packaging conglomerates, Signode Industrial Group LLC anchors the heavy-gauge pipe bundling segment through its industrial containment heritage. ProMach Inc. exemplifies the modular platform archetype with configurations spanning manual through fully automatic systems. Maillis Group S.A. represents the integrated materials specialist tier, combining stretch film and woven strapping capabilities for multi-material pipeline projects.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| ProMach Inc. |
| Maillis Group S.A. |
| LanTech LLC |
| Grupo ULMA S. Coop. |
| Aetna International S.p.A. |
| Wulftec International Inc. |
| Lantech |
| Technowrapp s.r.l. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up packaging conglomerates anchor pricing discipline through captive aftermarket service networks, compressing margin pools for independent fabricators while consolidating procurement leverage over polyethylene resin suppliers and programmable logic controller distributors.
Pricing Analysis
Warranty and field-service bundling separates premium-tier automatic systems from unbundled semi-automatic configurations where regional contractors bear maintenance risk. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and PHMSA compliance documentation depth. Cost compression in economy-tier manual equipment intensifies because municipal water contractors face fixed-budget constraints. Regional water supply contractors exhibit highest price sensitivity; offshore oil and gas operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Texas and Alberta engineering firms require qualified backup suppliers for servo motors and programmable logic controllers, extending vendor qualification timelines. Manufacturing concentrates in China, Germany, and the United States. Production draws from hot-rolled steel coil, polyethylene resin, and precision motion control components. Single-source vulnerability in East Asian semiconductor fabrication for industrial automation chips threatens equipment delivery schedules. Distribution runs through approved vendor lists maintained by integrated energy companies and engineering procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PHMSA integrity management rules erect a cost-of-compliance barrier that favors incumbents with pre-certified platform architectures and documented coating verification capabilities, locking out undercapitalized regional fabricators.
For Market Incumbents: Extend backward integration into recyclable polyethylene feedstocks ahead of EU Green Deal supplier qualification tightening. Fortify position against modular platform specialists by embedding ultrasonic inspection modules directly into wrapping line architectures. Capacity addition in Ruhr-region service hubs addresses German machinery safety directive validation bottlenecks.
For New Entrants and Emerging Players: Direct-to-contractor digital procurement portals bypass entrenched engineering firm vendor lists for semi-automatic equipment in India's state-level water infrastructure programs. White-space concentrates in composite pipe wrapping for offshore wind cable protection systems. Field-upgradable architecture subscriptions capture margin pools among mid-tier contractors with variable throughput requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed-asset framing: distressed-cycle entries favor family-owned Italian film-and-tape specialists in Emilia-Romagna with stranded technology but intact customer relationships in Mediterranean pipeline projects. Long-term viability hinges on regulatory compliance moat durability rather than cyclical equipment replacement demand. Monitor PHMSA enforcement action frequency as inflection indicator for capital expenditure acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recyclable Feedstocks | Captures margin ahead of EU Green Deal supplier qualification tightening for polyethylene barrier systems. |
| Modular Platform Architecture Development | Enables field-upgrade pathways from semi-automatic to fully automatic configurations for mid-tier contractors. |
| Inline Inspection Module Integration | Unifies coating application with real-time defect detection for Gulf of Mexico offshore contractors. |
| PHMSA Compliance Documentation Systems | Generates digital audit trails that satisfy integrity management rules for Texas and Alberta operators. |
| Regional Service Hub Expansion | Reduces design validation timelines for equipment imported under German machinery safety directives. |
Research Methodology
Document review covered trade association technical standards, customs shipment records, and regulatory filing databases, complemented by interviews with plant engineers at steel pipe mills, procurement leads at oil and gas pipeline operators, aftermarket service heads at packaging equipment distributors, and technical R&D directors at polymer film manufacturers. Secondary sources included PHMSA integrity management guidance documents, EPA National Emission Standards compliance records, EU machinery safety directive notified body certifications, and SEC filings from listed packaging conglomerates. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure estimates from energy infrastructure project databases.
Cross-referencing historical automation adoption curves against expert panel input on regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation tier, material compatibility, application intensity, and buyer type. CAGRs derived from equipment replacement cycle analysis and infrastructure investment flow projections. Industry-specific inputs incorporated PHMSA rulemaking timelines and EU carbon border adjustment mechanism implementation phases.
The model holds under steady regulatory enforcement and polyethylene resin supply continuity; deviation in PHMSA penalty escalation or East Asian logistics disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Forklift Tire Market