
 Industrial Dryers Market | 2026-2036
Industrial Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Dryers Market Intelligence
European process equipment manufacturers is rebalancing capacity toward energy-optimized systems after natural gas price volatility disrupted thermal dryer economics. ANDRITZ AG leverages its Austrian engineering base to sustain leadership in pulp and paper drying installations across Nordic markets. GEA Group anchors its position through captive refrigeration technology integration into freeze dryer lines for pharmaceutical clients. SPX Flow competes in North American dairy and food processing segments where hygienic design standards command premium positioning.
Industrial dryers are thermal or mechanical systems that reduce moisture content in bulk solids, slurries, or pastes through controlled heat transfer and mass transfer, typically operating between 40°C and 600°C depending on material sensitivity and process requirements. Their primary purpose centers on preserving product stability, enabling downstream handling, and meeting moisture specifications for storage or further processing. Rotary dryers dominate mineral and chemical processing applications where high throughput tolerance for abrasive feedstocks defines equipment selection. Spray dryers capture expanding margin pools in pharmaceutical and nutraceutical manufacturing where particle engineering and aseptic operation justify capital intensity. Microwave drying technology leads growth in food processing segments seeking reduced thermal degradation and shorter residence times for heat-sensitive ingredients.
EPA emissions standards under the Clean Air Act constrain direct-fired dryer installations in US chemical and petrochemical corridors, pushing demand toward indirect heating and thermal oxidizer integration. EU Ecodesign regulations and REACH compliance requirements enforce minimum thermal efficiency thresholds and material safety documentation for dryers processing coated or treated substrates. China's GB standards and dual carbon goals from MEE are tightening energy intensity benchmarks for building materials and mineral processing dryers in Shandong and Jiangsu provinces. Stakeholders must monitor regulatory divergence between efficiency mandates and emissions caps as equipment specification cycles lengthen and retrofit economics shift across jurisdictions.
Market Dynamics
Natural gas price volatility has compressed thermal dryer operating margins across European chemical processing corridors, forcing operators toward heat pump integration and waste-heat recovery architectures that alter equipment replacement cycles and vendor selection criteria.
Growth Catalysts
- EPA Clean Air Act enforcement:Emissions caps on direct-fired systems in US petrochemical clusters are accelerating indirect heating retrofits and thermal oxidizer attachments.
- Pharmaceutical particle engineering:Aseptic spray dryer demand from injectable drug manufacturers is expanding capital deployment in freeze dryer and containment dryer lines.
- Shandong province mineral processing:China's MEE dual carbon targets are mandating energy intensity upgrades for building materials dryers, concentrating procurement among state-owned cement and gypsum producers.
Market Restraints
- Stainless steel input volatility:Grade 316L and duplex alloy price swings are compressing fabrication margins for hygienic food and pharmaceutical dryer builders.
- German component supply concentration:Precision burner controls and refractory linings from Bavarian and North Rhine-Westphalia suppliers create single-source vulnerability for global dryer OEMs.
- Heat pump technical ceiling:Current refrigerant temperature limits restrict heat pump dryers to sub-150°C applications, excluding high-temperature mineral and chemical processing segments.
Strategic Opportunities
- India food processing corridor expansion:FSSAI shelf-life mandates and PLI scheme incentives for cold chain infrastructure are driving dehydrated ingredient capacity builds in Maharashtra and Gujarat.
- Microwave-radio frequency convergence:Hybrid drying systems combining volumetric heating with conventional conduction are penetrating spice and nutraceutical applications where thermal degradation limits product quality.
- EU Ecodesign regulation tailwind:Minimum thermal efficiency thresholds for industrial ovens and dryers are creating replacement demand among mid-scale coating and finishing operations in Poland and Czechia.
Industry Challenges
- Thermal process engineering talent scarcity:Experienced dryer system designers capable of integrating heat and mass transfer modeling with controls architecture are concentrated among retiring cohorts in Germany and Austria.
- Legacy DCS integration friction:Brownfield chemical plants running Honeywell TDC or Yokogawa CENTUM systems face protocol mismatches when retrofitting smart dryer monitoring and predictive maintenance modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Dryers Market |
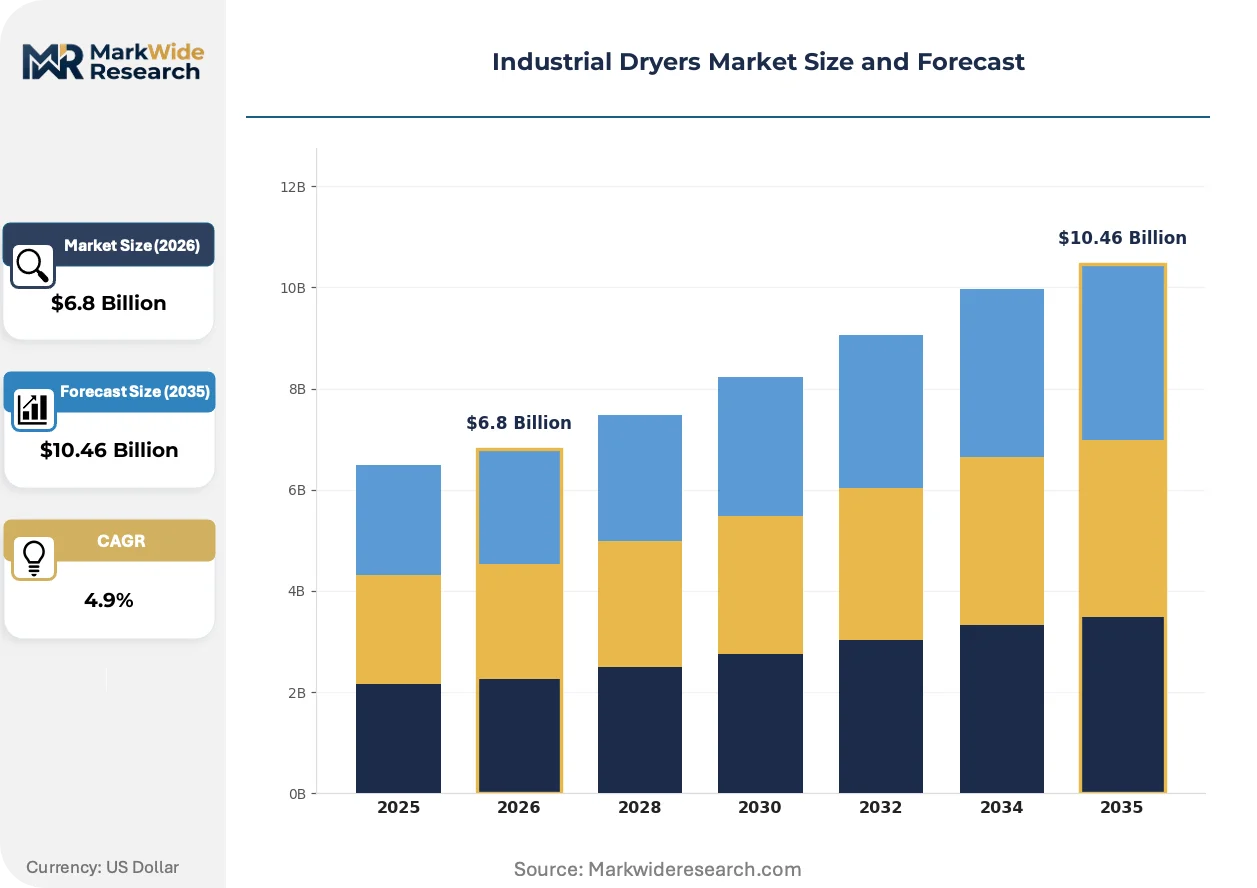
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Dryers, Flash Dryers, Spray Dryers, Drum Dryers, Freeze Dryers Technology: Conduction Drying, Convection Drying, Microwave Drying, Infrared Drying, Vacuum Drying Application: Chemical Processing, Food Processing, Mineral Processing, Pulp & Paper, Textile Manufacturing End User Industry: Pharmaceutical Manufacturers, Petrochemical Plants, Food & Beverage Producers, Chemical Producers, Building Materials Manufacturers |
| Companies Covered | ThyssenKrupp AG, ANDRITZ AG, GEA Group, Metso, FLSmidth & Co. A/S, Bühler Holding AG, SPX Flow, Carrier Vibrating Equipment, ANIVI Ingenieria SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Dryers Market Strategic Shifts & Innovations
Equipment architecture is fragmenting into standardized subsystems that permit rapid reconfiguration between batch and continuous operation, compressing project engineering timelines and enabling regional assembly strategies.
Heat pump dryer technology is modularizing around reversible vapor compression skids that swap between drying and dehumidification modes. Pharmaceutical and food processors in the Netherlands and Denmark are deploying these units for intermediate moisture product lines. The technology is modularizing project delivery into skid-mounted packages that slash site installation labor and permit factory acceptance testing prior to shipment.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick dryer coatings from European pharmaceutical and food equipment specifications. Manufacturers are accelerating ceramic and plasma-sprayed alternative qualification programs. German and Swiss dryer builders face the tightest compliance timelines with coating reformulation costs concentrated in fluid bed and tray dryer product lines.
Buyer preference is gravitating toward performance-guaranteed service contracts where vendors retain operational risk for energy consumption and moisture uniformity outcomes. North American dairy processors are piloting these arrangements for spray dryer fleets. The model is displacing traditional capex-plus-maintenance procurement in California and Wisconsin whey protein concentration facilities where energy arbitrage value exceeds equipment ownership economics.
Industrial Dryers Market Segmentation
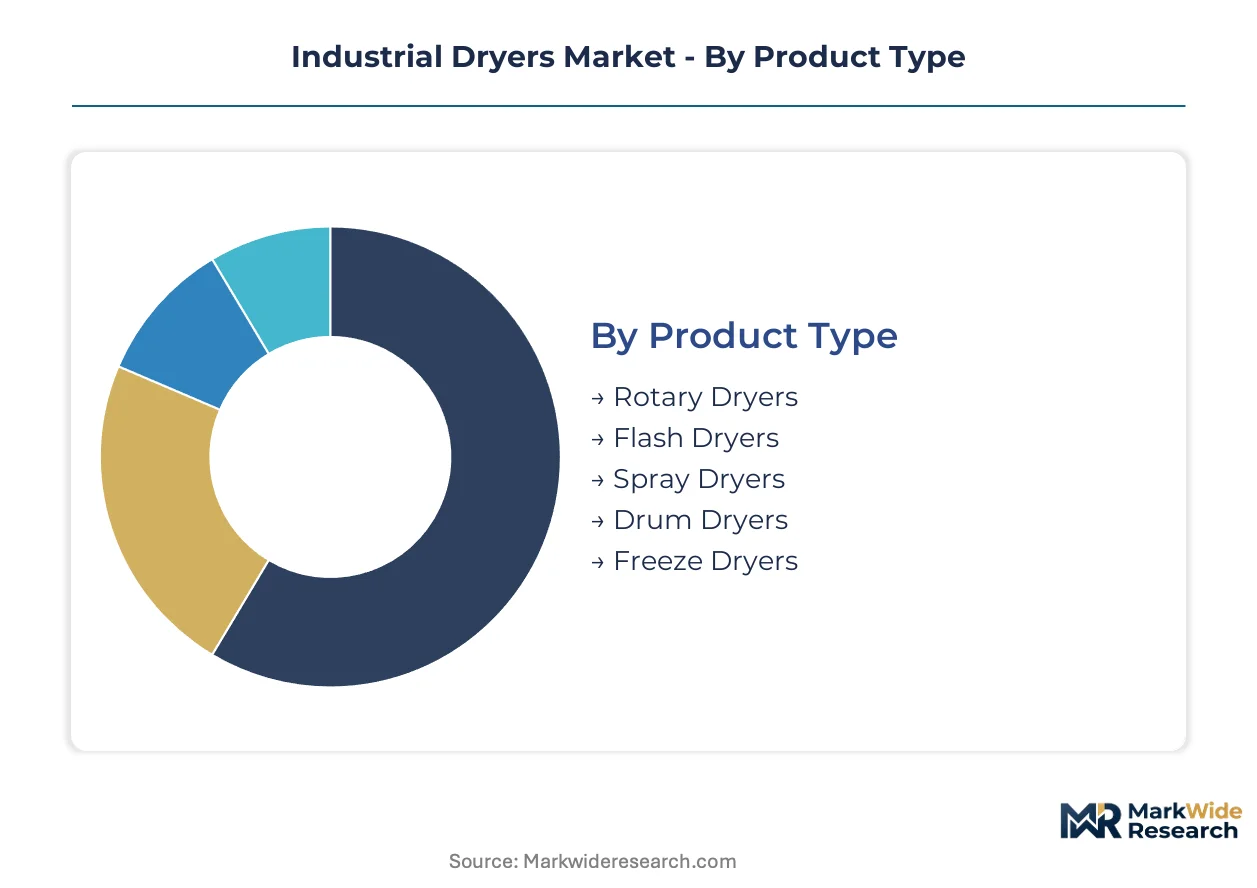
Dryer specification cycles diverge sharply across operational contexts. Standalone units for bulk mineral processing face entirely different procurement logic than embedded pharmaceutical systems where containment and aseptic integration dominate capital decisions.
Product Type:
Integration depth separates rotary and flash systems operating as standalone process islands from freeze dryers embedded within validated pharmaceutical production lines.
- Rotary Dryers:Cylindrical drums with cascading flights expose bulk solids to concurrent or counter-current hot gas streams, handling abrasive feedstocks up to 600°C. Demand concentrates in Shandong and Jiangsu province cement and gypsum clusters where MEE dual carbon mandates are forcing thermal efficiency retrofits.
- Freeze Dryers:Vacuum sublimation systems operating below -40°C preserve protein structure in injectable biologics and live vaccines. Procurement clusters among Maharashtra pharmaceutical manufacturers supplying CDSCO-regulated sterile fill-finish operations.
- Flash Dryers:Pneumatic conveying systems flash-dry heat-sensitive pigments and starches in sub-10 second residence times.
- Spray Dryers:Atomization chambers producing engineered particle morphologies for instant solubility and controlled release.
- Drum Dryers:Thin-film evaporation on heated rolls for viscous pastes and slurries in dairy and starch processing.
Volume placements concentrate in rotary dryers for mineral and chemical corridors; the faster expansion belongs to freeze dryers as aseptic injectable capacity expands.
Technology:
Cost tier stratification separates mature conduction and convection systems from premium microwave and vacuum technologies commanding 3-4x capital intensity per unit throughput.
- Convection Drying:Hot gas impingement dominates high-throughput applications where direct-fired or indirect heating systems move large moisture loads through rotary, flash, or fluid bed configurations. Installations span German chemical parks and US Gulf Coast petrochemical corridors where EPA Clean Air Act enforcement is accelerating thermal oxidizer attachments.
- Vacuum Drying:Reduced-pressure environments lower boiling points to protect thermolabile pharmaceutical actives and food bioactives. Adoption concentrates among Swiss and German freeze dryer builders serving EMA-regulated sterile manufacturing suites.
- Conduction Drying:Contact heat transfer through heated surfaces for slurries and pastes in drum and paddle configurations.
- Microwave Drying:Volumetric heating penetrating dielectric materials for rapid moisture removal without surface case-hardening.
- Infrared Drying:Radiant energy absorption for thin-film coatings and surface moisture in textile and paper finishing.
Capital deployment concentrates in convection systems for bulk processing; vacuum technology is climbing the fastest as pharmaceutical containment requirements tighten.
Application:
Customer type fragmentation separates specification-driven pharmaceutical and food processors from price-sensitive mineral and building materials operators.
- Food Processing:Hygienic design standards govern equipment selection for dehydrated ingredients, dairy powders, and ready-to-eat components. FSSAI shelf-life mandates are driving capacity builds in Gujarat and Maharashtra food corridors where PLI scheme incentives offset capital costs.
- Chemical Processing:Corrosion-resistant alloys and explosion-proof electrical classifications dominate dryer specifications for specialty chemicals and agrochemical intermediates. Procurement clusters in German North Rhine-Westphalia and US Texas-Louisiana chemical processing corridors.
- Mineral Processing:Abrasion-resistant linings and high-temperature metallurgy for ores, sands, and clays.
- Pulp & Paper:High-speed Yankee dryers and through-air systems for tissue and packaging grades.
- Textile Manufacturing:Stenter frames and conveyor dryers for fabric finishing and coating.
Installed base concentrates in chemical processing; food processing applications are gaining share fastest as cold chain infrastructure expands.
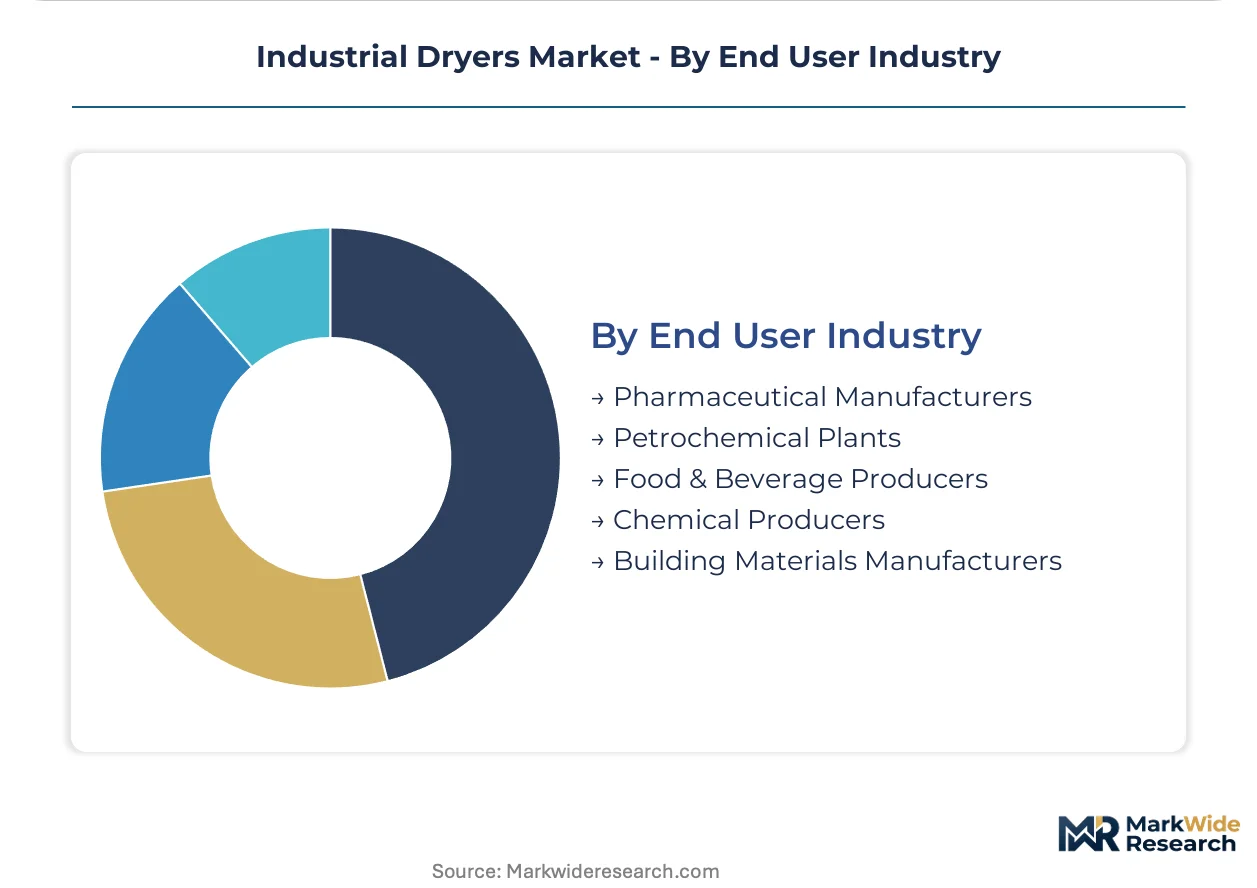
End User Industry:
Supply concentration aligns with regional industrial clustering — pharmaceutical manufacturers concentrate procurement among Swiss and German OEMs, while building materials producers source from Chinese fabricators serving Shandong and Hebei province cement corridors.
- Pharmaceutical Manufacturers:Containment requirements, batch documentation, and FDA/EMA validation protocols drive specification toward isolator-integrated freeze dryers and spray dryers with in-process particle monitoring. Demand clusters among injectable drug producers in Switzerland, Germany, and Maharashtra's Biotech Park.
- Building Materials Manufacturers:Energy intensity regulations from China's MEE and EU Ecodesign minimum thermal efficiency thresholds are forcing rotary dryer replacements across cement, gypsum, and lime operations. Procurement concentrates among state-owned enterprises in Shandong province.
- Petrochemical Plants:Direct-fired and indirect heating systems for polymer resins and synthetic fiber intermediates.
- Food & Beverage Producers:Hygienic spray dryers and drum dryers for dairy, beverage, and ingredient applications.
- Chemical Producers:Corrosion-resistant conduction and convection systems for specialty and commodity chemicals.
Procurement volume concentrates in building materials manufacturing; pharmaceutical manufacturers are expanding capital deployment most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mineral deposits in Shandong province and the Rhine-Ruhr corridor anchor dryer procurement clusters where cement, gypsum, and chemical processors face tightening energy intensity mandates. Natural gas price shocks and emissions regulations are reshaping equipment replacement cycles across these feedstock-dense geographies.
United States
Petrochemical processors along the Texas-Louisiana Gulf Coast are retrofitting direct-fired dryers with thermal oxidizer attachments. EPA Clean Air Act enforcement is accelerating indirect heating system adoption among polymer resin manufacturers. Houston corridor engineering firms are integrating smart monitoring modules into legacy Honeywell TDC control architectures.
Germany
Chemical parks in North Rhine-Westphalia and Bavaria are demanding heat pump-compatible dryer architectures after natural gas price volatility disrupted thermal economics. EU Ecodesign minimum thermal efficiency thresholds are forcing rotary dryer replacements among coating and finishing operations. Precision burner controls from Bavarian suppliers create single-source vulnerability for global OEM procurement.
China
Building materials producers in Shandong and Jiangsu provinces are upgrading rotary dryers to meet MEE dual carbon energy intensity benchmarks. State-owned cement and gypsum enterprises are concentrating procurement among domestic fabricators serving these coastal clusters. GB standards enforcement is tightening emissions caps on mineral processing thermal systems.
India
Food processors in Maharashtra and Gujarat are expanding dehydrated ingredient capacity to meet FSSAI shelf-life mandates. PLI scheme incentives for cold chain infrastructure are offsetting capital costs for spray dryer installations. Maharashtra's Biotech Park is anchoring freeze dryer demand from CDSCO-regulated sterile fill-finish operations.
Switzerland
Pharmaceutical manufacturers are specifying isolator-integrated freeze dryers for EMA-regulated aseptic manufacturing suites. REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick coatings from equipment specifications. Swiss dryer builders face compressed compliance timelines for ceramic and plasma-sprayed alternative qualification.
Industrial Dryers Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue heat pump integration and microwave-radio frequency convergence. The vendor base separates into three distinct maturity tiers: diversified process equipment conglomerates with captive refrigeration technology, mid-scale specialists in hygienic design standards, and regional fabricators serving mineral processing corridors. Strategic differentiation centers on energy-optimized system architectures and performance-guaranteed service contracts displacing traditional capex procurement. Competitive moves concentrate on M&A for thermal process engineering talent and geographic expansion into India's food processing corridors.
Within the diversified conglomerate tier, ANDRITZ AG and GEA Group exemplify contrasting strategic anchors. ANDRITZ leverages its Austrian engineering base to sustain positioning in pulp and paper drying installations across Nordic markets. GEA anchors its presence through captive refrigeration technology integration into pharmaceutical freeze dryer lines. SPX Flow occupies a distinct position among North American dairy and food processing specialists where hygienic design standards command premium positioning. ThyssenKrupp AG and Metso represent the scale-driven end, serving mineral and chemical processing corridors with high-throughput rotary and flash dryer architectures. Bühler Holding AG exemplifies the mid-scale specialist archetype focused on food and feed processing applications.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| ANDRITZ AG |
| GEA Group |
| Metso |
| FLSmidth & Co. A/S |
| Bühler Holding AG |
| SPX Flow |
| Carrier Vibrating Equipment |
| ANIVI Ingenieria SA |
| Others |
Cost & Logistics Intelligence
State-owned cement and gypsum enterprises in Shandong province anchor procurement volume for rotary dryer systems, locking in project-based contract pricing with energy-performance guarantees rather than pure equipment transactions. Their concentration among domestic fabricators creates asymmetric bargaining power that compresses margins for mid-scale hygienic equipment builders serving pharmaceutical and food processing segments.
Pricing Analysis
Performance-guaranteed service contracts bundle energy consumption and moisture uniformity outcomes into multi-year agreements, displacing traditional capex-plus-maintenance procurement among North American dairy processors. Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated freeze dryers with EMA validation documentation from basic rotary units for mineral applications. Cost compression in stainless steel fabrication is intensifying because Grade 316L and duplex alloy price swings compress margins for hygienic food and pharmaceutical dryer builders. Mineral and building materials operators exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize containment certification over unit cost.
Supply Chain Analysis
Skilled thermal process engineering talent availability concentrates in Germany and Austria, where retiring cohorts threaten knowledge transfer continuity for heat and mass transfer modeling capabilities. Precision burner controls and refractory linings draw from Bavarian and North Rhine-Westphalia suppliers, while stainless steel inputs hinge on global commodity markets. Single-source vulnerability for critical German components creates structural supply chain risk. Distribution runs through regional engineering offices that coordinate factory acceptance testing prior to site installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial dryer architecture is transitioning from standalone thermal systems to modular, heat pump-integrated platforms that displace legacy direct-fired installations under tightening emissions regulations. Microwave-radio frequency convergence technologies are capturing share in food and nutraceutical applications where thermal degradation limits conventional processing.
For Market Incumbents: Deepen captive refrigeration technology integration to defend pharmaceutical freeze dryer positioning against emerging heat pump specialists. Invest in thermal process engineering talent retention programs in Germany and Austria to offset retiring cohort concentration. Prioritize backward integration into precision burner control supply to reduce Bavarian supplier dependency. For New Entrants and Emerging Players: The mid-tier price gap between premium isolator-integrated systems and economy rotary units opens white-space for hybrid microwave-convection dryers in Indian spice processing corridors. Target Maharashtra and Gujarat food processing clusters where FSSAI shelf-life mandates drive dehydrated ingredient capacity builds. Deploy skid-mounted heat pump packages with factory acceptance testing protocols to compress project delivery timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale hygienic design specialists with captive pharmaceutical validation expertise in Switzerland and Germany. Long-term viability over the coming decade rests on energy-optimized system architectures rather than commodity mineral processing equipment. Watch for MEE dual carbon enforcement intensity in Shandong province as inflection indicator for Chinese domestic fabricator consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Integration | Captive refrigeration capability anchors pharmaceutical freeze dryer margins against emerging competitors. |
| Backward Integration into Precision Controls | In-house burner control production reduces Bavarian supplier concentration risk for global OEMs. |
| Regional Assembly Footprint Expansion | Maharashtra and Gujarat facilities capture PLI scheme incentives for Indian food processing corridor demand. |
| Ceramic Coating Qualification Programs | REACH-compliant alternatives replace legacy PFAS coatings in EMA-regulated pharmaceutical equipment specifications. |
| Performance-Guaranteed Service Contracts | Energy arbitrage value in California and Wisconsin dairy facilities displaces traditional capex procurement models. |
Research Approach
Multi-period observation of MEE dual carbon enforcement patterns, EPA Clean Air Act violation proceedings, and EU Ecodesign implementation timelines anchored the trend analysis, supplemented by interviews with plant engineers at Shandong cement facilities, pharmaceutical sterile manufacturing directors in Maharashtra's Biotech Park, and dairy processing maintenance heads in Wisconsin and California. Secondary validation drew from customs trade data for dryer equipment imports, SEC filings of listed process equipment manufacturers, and CDSCO regulatory submission databases. Bottom-up procurement tracking across state-owned enterprise tender portals combined with top-down market sizing triangulation.
Segment-weighting approaches modeled rotary, freeze, spray, flash, and drum dryer categories against convection, vacuum, conduction, microwave, and infrared technology tiers. Application dimensions spanned food processing, chemical processing, mineral processing, pulp and paper, and textile manufacturing, with end-user industry splits across pharmaceutical manufacturers, building materials producers, petrochemical plants, and food and beverage operators across the analysis window. CAGRs were derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and capacity expansion announcement tracking.
Inputs from Chinese state-owned enterprise procurement portals, Indian PLI scheme beneficiary disclosures, and European pharmaceutical equipment validation records were available through the study window; gaps in real-time natural gas price impact quantification for European chemical park operators introduce uncertainty bands around heat pump adoption trajectory assumptions. Material deviation in MEE enforcement intensity, REACH substance restriction timelines, or stainless steel commodity volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Used Machine Tools Market