
 Global Automatic Palletizer and Depalletizer Market | 2026-2036
Global Automatic Palletizer and Depalletizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Palletizer and Depalletizer Market Foresight
Carbon fiber-reinforced polymer is decoupling end-of-arm tooling from traditional aluminum assemblies, cutting cycle-weight ratios by nearly half while extending actuator lifespans. KUKA AG leverages its Stuttgart manufacturing base to sustain captive production of servo-driven layer-forming heads for beverage clients. FANUC Corporation anchors its palletizer portfolio with proprietary vision-guided pick-and-place controllers that dominate high-speed food bagging lines across North America and Japan. ABB competes through integrated force-torque sensing in its robotic depalletizers, enabling mixed-case handling without pre-programmed load maps.
Automatic palletizer and depalletizer systems are electromechanical material-handling machines designed to arrange, stack, or unstack unit loads onto pallets at throughputs ranging from 10 to 200 cases per minute, depending on layer-forming or robotic architecture. Their primary industrial purpose is to eliminate manual lifting injuries, standardize load cube efficiency for transport, and synchronize with upstream packaging lines through programmable logic controllers and warehouse management system interfaces. Robotic palletizers are capturing margin pools in pharmaceutical packaging, where batch-size flexibility and cleanroom compatibility command premium positioning. Conventional palletizers retain volume dominance in beverage handling, where uniform case dimensions and extreme throughput requirements favor mechanical layer-forming over adaptive gripping. Hybrid palletizers that switch between robotic and conventional modes are gaining traction among contract manufacturers serving multiple end-user industries with volatile SKU profiles.
ISO 10218 robot safety standards, the EU Machinery Directive, and OSHA mechanical power-press regulations collectively shape machine design, guarding requirements, and market access documentation for cross-border equipment shipments. FDA cGMP guidelines for pharmaceutical packaging further constrain surface finishes, washdown protocols, and validation documentation for depalletizers feeding aseptic filling lines. Stakeholders must monitor divergence between regional safety certification timelines and the accelerating pace of collaborative robot payload advances that blur the line between caged and uncaged palletizing architectures.
Market Dynamics
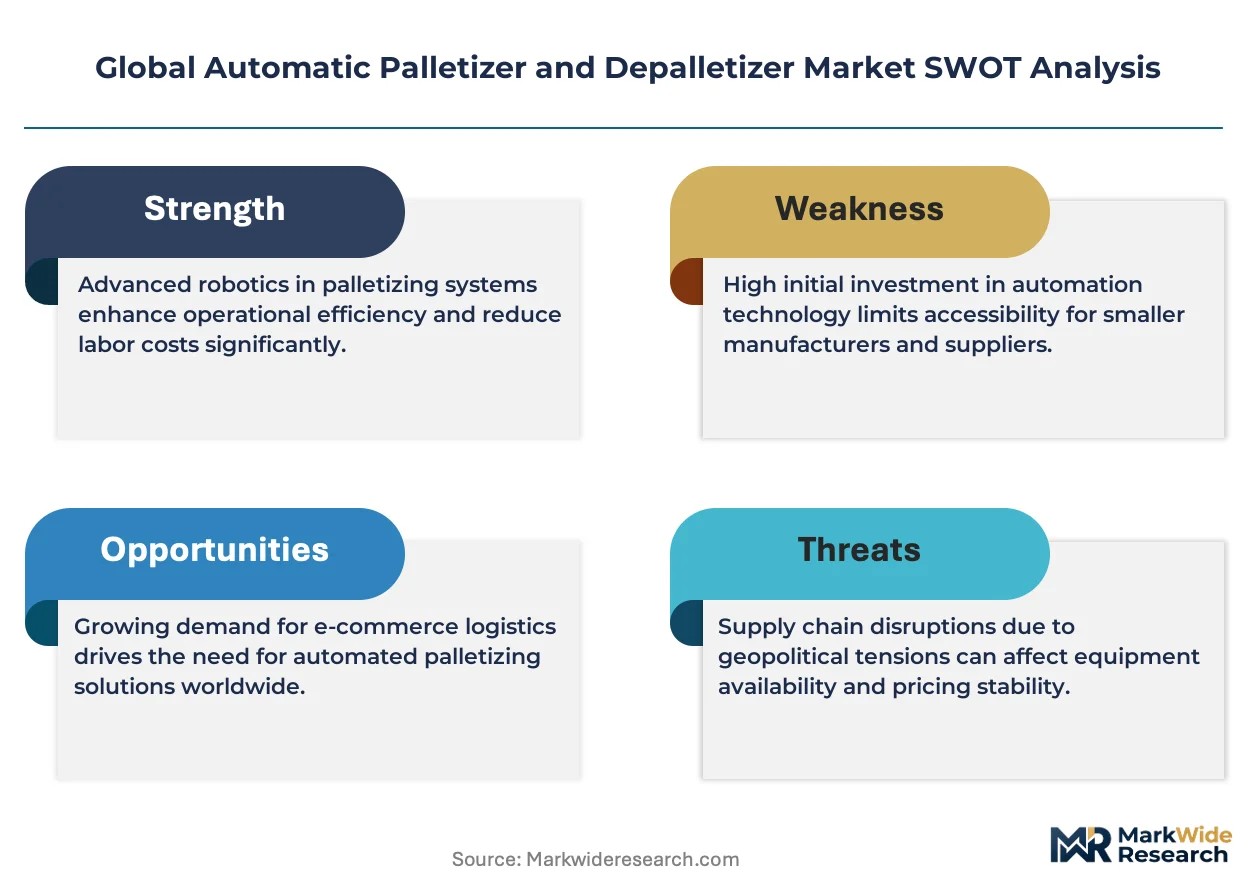
The collision between ISO 10218 safety mandates and collaborative robot payload advances is forcing equipment vendors to redesign guarding architectures while preserving throughput. This structural tension between compliance velocity and technical capability is redrawing competitive boundaries across installation types.
Growth Catalysts
- EU Machinery Directive compliance deadlines:German automotive supplier parks are accelerating depalletizer procurement to meet synchronized safety certification timelines for just-in-line feeding cells.
- Carbon fiber-reinforced polymer tooling:End-of-arm assemblies are shedding weight ratios by half, extending actuator lifespans in high-cycle beverage operations.
- Pharmaceutical batch-size flexibility:Robotic palletizers are capturing premium positioning in aseptic packaging where cleanroom compatibility and rapid changeover dominate vendor selection.
Market Restraints
- Aluminum servo motor supply concentration:Captive production of layer-forming heads by Stuttgart-based manufacturers limits third-party sourcing options for mid-scale integrators.
- FDA cGMP validation documentation:Pharmaceutical depalletizers face extended approval cycles for surface finishes and washdown protocols feeding aseptic lines.
- Mechanical layer-forming substitution risk:Conventional palletizers retain volume dominance in uniform-case beverage handling, compressing robotic penetration in high-throughput segments.
Strategic Opportunities
- Hybrid architecture adoption:Contract manufacturers serving volatile SKU profiles are sourcing palletizers that switch between robotic and conventional modes without line reconfiguration.
- OSHA mechanical power-press harmonization:North American facilities are retrofitting existing lines to preempt cross-border equipment shipment documentation requirements.
- India contract packaging expansion:Food processing clusters in Maharashtra and Gujarat are deploying first-generation robotic cells to manage labor volatility and export compliance.
Industry Challenges
- Collaborative robot safety engineer scarcity:The gap between caged and uncaged palletizing architectures requires specialized integrators familiar with force-torque sensing calibration.
- Warehouse management system interface complexity:Legacy PLC synchronization protocols are creating integration friction with cloud-based inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Palletizer and Depalletizer Market |
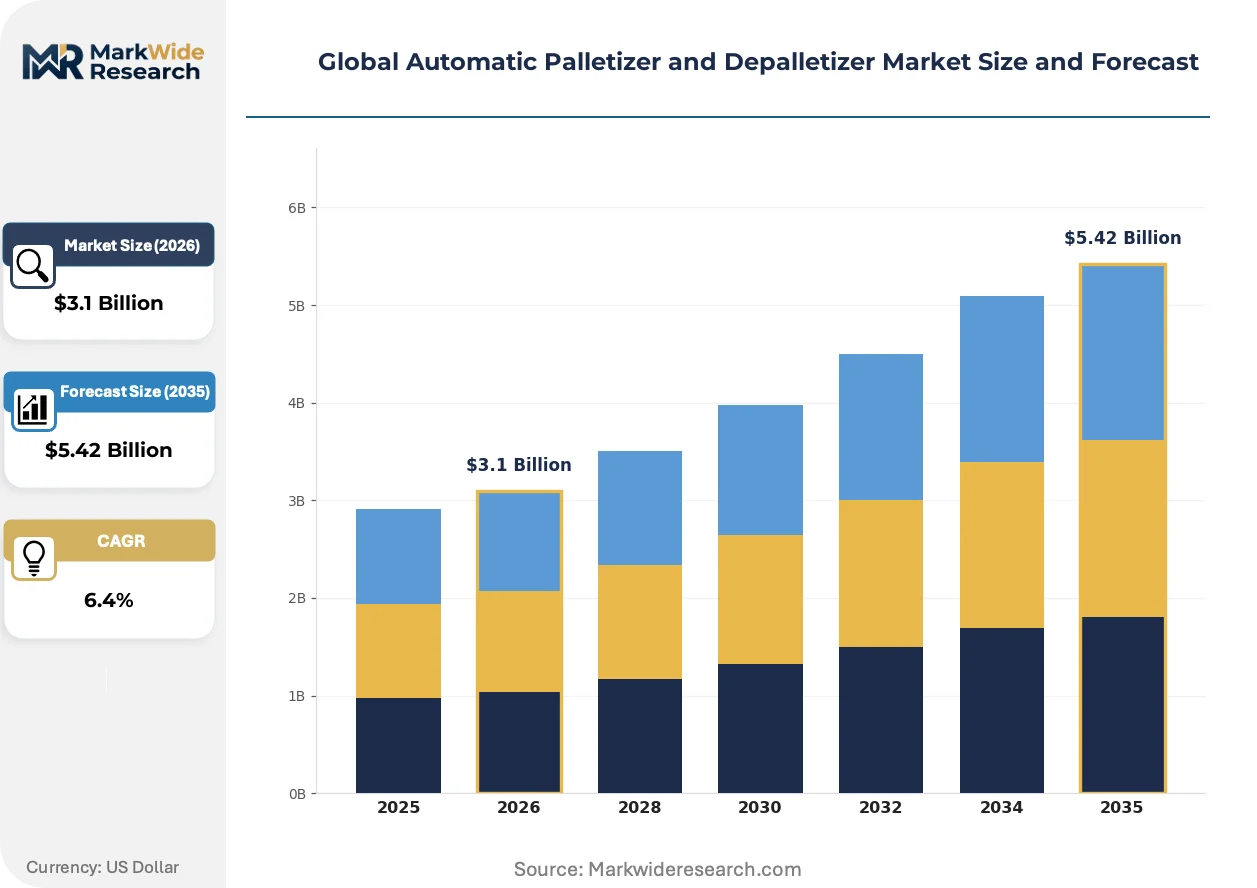
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Palletizer, Conventional Palletizer, Depalletizer, Hybrid Palletizer Technology: Pick and Place, Rotary Arm, Layer Forming, Gantry Systems, Vacuum Gripper Application: Food Processing, Beverage Handling, Pharmaceutical Packaging, Consumer Goods, Electronics Assembly End User Industry: Logistics Service Providers, Packaging Manufacturers, Warehousing Operators, Contract Manufacturers |
| Companies Covered | Honeywell International Inc, Krones AG, FANUC Corporation, Schneider Packaging Equipment Company, Columbia Machine, KUKA AG, Yaskawa Electric Corp, RMH Systems, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Palletizer and Depalletizer Market Shifts & Advancements
Material substitution and safety standard convergence are compressing equipment design cycles while expanding the addressable application set. Vendors are racing to decouple mechanical performance from regulatory risk.
Vision-guided pick-and-place controllers are automating adaptive gripping in high-speed food bagging operations. North American and Japanese facilities are retrofitting existing lines with these systems to handle SKU proliferation without mechanical changeover. The technology is automating the transition from pre-programmed load maps to real-time case recognition, collapsing setup time differentials between robotic and conventional architectures.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are constraining lubricant and refrigerant choices in electromechanical systems. Equipment manufacturers are reformulating actuator maintenance protocols to eliminate restricted chemistries before certification deadlines. Pharmaceutical packaging lines in Germany and France are absorbing premium costs for compliant component sourcing to maintain CE marking continuity.
Service contract unbundling is fragmenting vendor-customer relationships in the installed base. End-users in Japan are separating hardware procurement from predictive maintenance subscriptions, forcing OEMs to price recurring revenue streams independently of capital sales. Food and beverage clusters in Aichi Prefecture are piloting outcome-based uptime guarantees that shift performance risk from operator to supplier.
Global Automatic Palletizer and Depalletizer Market Segmentation
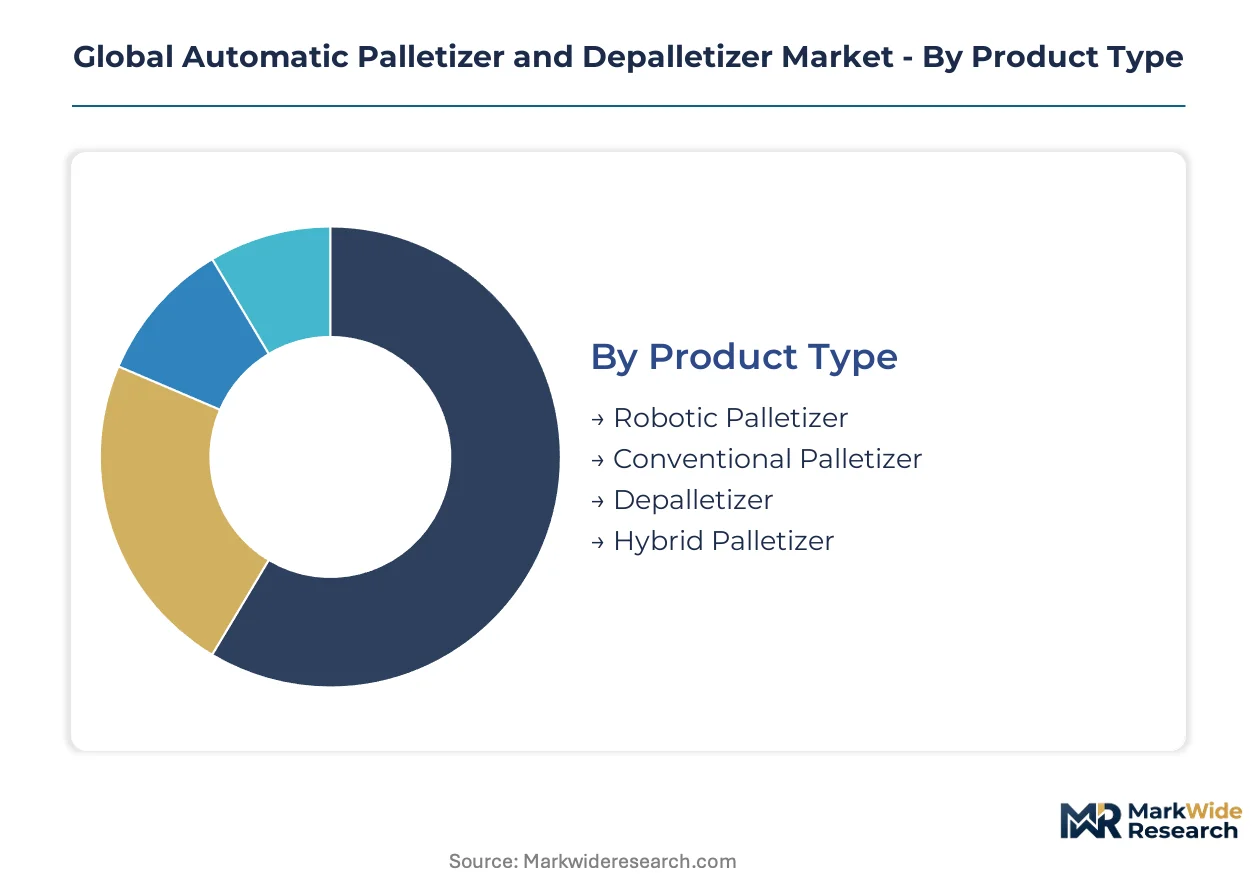
Segmentation in the automatic palletizer and depalletizer market reveals how certification requirements, throughput demands, and end-use flexibility divide procurement budgets across equipment classes. Buyers prioritize different performance attributes based on whether they serve regulated pharmaceutical lines or high-volume beverage operations.
Product Type:
Certification burdens vary sharply across product types, with pharmaceutical-facing robotic palletizers requiring FDA cGMP validation and ISO 10218-2 collaborative safety documentation, while conventional layer-forming units in beverage plants face lighter OSHA mechanical power-press compliance.
- Robotic Palletizer:Articulated-arm systems with servo-driven joints execute adaptive pick-and-place sequences for mixed-SKU loads. Demand concentrates in German pharmaceutical packaging facilities where cleanroom compatibility and batch-size flexibility command premium positioning against rigid mechanical alternatives.
- Conventional Palletizer:Mechanical layer-forming machines with fixed tooling arrays stack uniform cases at throughputs exceeding 150 units per minute. Beverage handling plants in Japan and the United States retain volume dominance here, prioritizing cycle speed over changeover agility.
- Depalletizer:Unstacking systems engineered for just-in-line feeding of production lines. Automotive supplier parks in Stuttgart and chemical export hubs in the Netherlands deploy these for synchronized inbound material flow.
- Hybrid Palletizer:Dual-mode architectures switch between robotic and conventional operation without line reconfiguration. Contract manufacturers serving volatile SKU profiles in Maharashtra and Gujarat are sourcing these to manage labor volatility and export compliance requirements.
Conventional palletizer sits at the top of the volume ranking, with hybrid palletizer climbing the fastest.
Technology:
Cost tiering separates precision servo technologies from pneumatic alternatives, with vacuum gripper and gantry systems commanding capital premiums over rotary arm configurations in cleanroom-compatible installations.
- Pick and Place:Cartesian-coordinate systems with programmable stroke lengths handle irregular package geometries. Vision-guided variants dominate high-speed food bagging lines across North America and Japan, automating real-time case recognition without mechanical changeover.
- Rotary Arm:Compact swing-arm mechanisms with limited reach envelopes serve space-constrained packaging halls. Mid-scale beverage bottlers in Aichi Prefecture favor these for their footprint efficiency and lower integration complexity.
- Layer Forming:Synchronized pusher-bar arrays construct pallet layers through mechanical collation. Carbon fiber-reinforced polymer tooling is decoupling these systems from traditional aluminum assemblies, cutting cycle-weight ratios by nearly half.
- Gantry Systems:Overhead-mounted linear actuators with extended work envelopes span multiple conveyor lanes. Large-format consumer goods distribution centers in France deploy these for simultaneous multi-line palletizing.
- Vacuum Gripper:Suction-cup end-of-arm tooling with zone-activated vacuum circuits handle porous and non-rigid packages. Pharmaceutical aseptic filling lines specify these for washdown compatibility and surface finish compliance.
Layer forming occupies the highest shipment volumes, with pick and place gaining share fastest through vision-guided retrofit adoption.
Application:
Application-driven procurement splits between regulated environments demanding validation documentation and high-throughput operations prioritizing uptime guarantees and predictive maintenance contracts.
- Food Processing:Robotic cells with stainless steel construction and IP65 washdown ratings manage SKU proliferation in protein and dairy packaging. Facilities are accelerating deployment to address labor volatility and allergen segregation protocols.
- Beverage Handling:Uniform case dimensions and extreme throughput requirements favor mechanical layer-forming over adaptive gripping. Conventional palletizers retain volume dominance here, though vision-guided retrofits are collapsing setup time differentials.
- Pharmaceutical Packaging:Aseptic filling lines require depalletizers with validated surface finishes, restricted lubricant chemistries, and FDA cGMP documentation. REACH substance restrictions and EU F-Gas Regulation phase-down schedules are constraining component sourcing.
- Consumer Goods:Mixed-case handling for e-commerce fulfillment drives demand for integrated force-torque sensing without pre-programmed load maps. Warehouse management system interface complexity creates integration friction with cloud-based inventory platforms.
- Electronics Assembly:ESD-safe construction and precision placement tolerances characterize semiconductor and display panel handling. Japanese facilities are piloting outcome-based uptime guarantees that shift performance risk from operator to supplier.
Beverage handling leads in installed base scale, with pharmaceutical packaging expanding most quickly through premium robotic penetration.
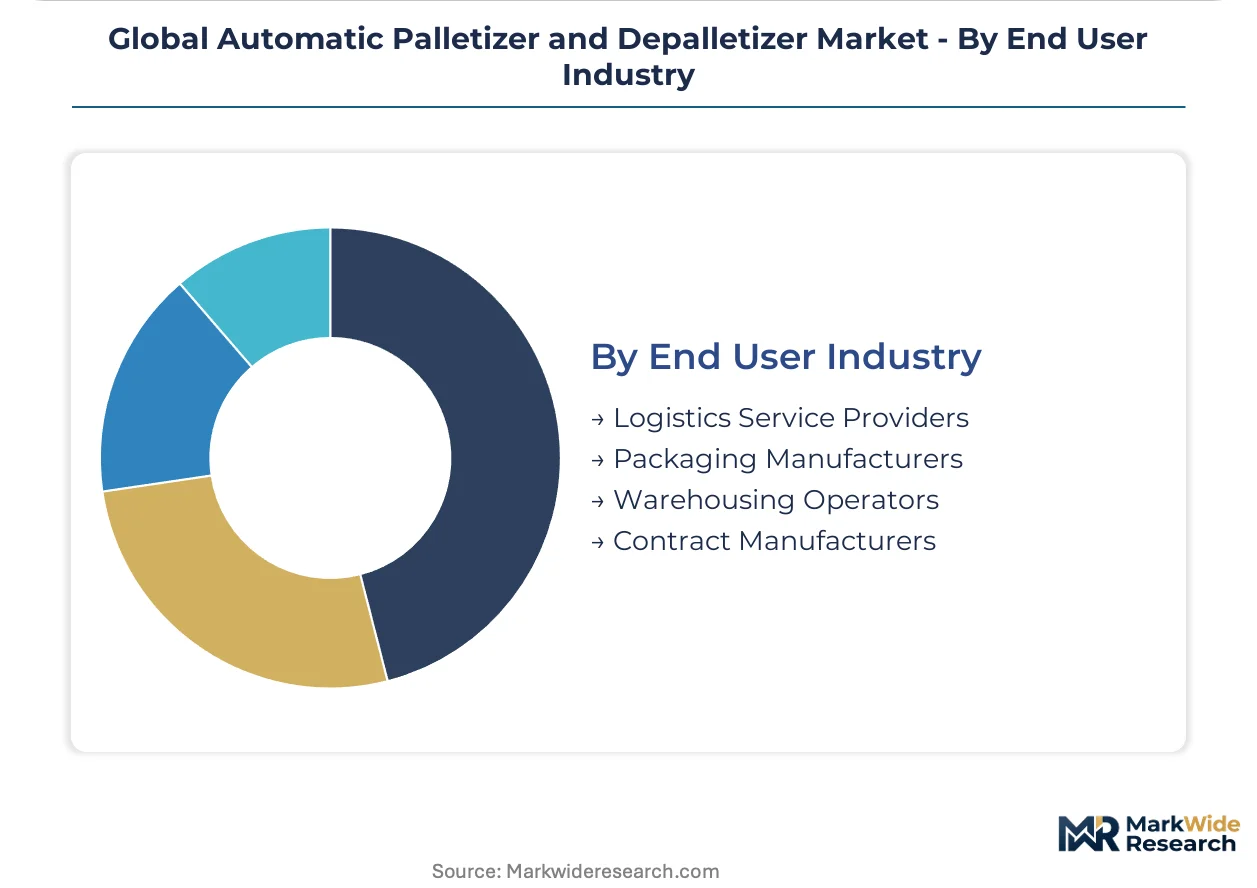
End User Industry:
Customer type determines whether procurement emphasizes capital efficiency or operational flexibility, with contract manufacturers prioritizing hybrid architectures against asset-heavy warehousing operators.
- Logistics Service Providers:Third-party fulfillment networks with volatile client portfolios require rapid reconfiguration capabilities. These operators are separating hardware procurement from predictive maintenance subscriptions, forcing OEMs to price recurring revenue streams independently.
- Packaging Manufacturers:Captive production lines with dedicated SKU ranges favor conventional mechanical systems for throughput maximization. Aluminum servo motor supply concentration limits third-party sourcing options for mid-scale integrators.
- Warehousing Operators:Asset-intensive distribution centers prioritize equipment longevity and spare parts availability. Legacy PLC synchronization protocols are creating integration friction with cloud-based inventory platforms in these installations.
- Contract Manufacturers:Multi-industry service providers with volatile SKU profiles are sourcing palletizers that switch between robotic and conventional modes without line reconfiguration. India contract packaging expansion in Maharashtra and Gujarat is deploying first-generation robotic cells for export compliance.
Packaging manufacturers command the largest equipment installed base, with contract manufacturers showing the steepest expansion trajectory through hybrid architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive supplier parks anchor global demand for high-throughput depalletizing systems. German chemical export hubs and beverage processing clusters across Bavaria and North Rhine-Westphalia drive synchronized procurement for just-in-line feeding cells.
United States
OSHA mechanical power-press regulations are accelerating retrofit investments across Midwest packaging corridors. FDA cGMP documentation requirements constrain pharmaceutical depalletizer approvals for surface finishes and washdown protocols. Chicago-area food processing facilities deploy vision-guided pick-and-place controllers to manage SKU proliferation without mechanical changeover.
Germany
EU Machinery Directive compliance deadlines are compressing safety certification timelines for collaborative robot installations. REACH substance restrictions and EU F-Gas Regulation phase-down schedules constrain lubricant choices in electromechanical systems. Stuttgart-based manufacturers sustain captive production of servo-driven layer-forming heads for beverage clients.
Japan
METI industrial automation incentives support precision placement tolerances in semiconductor and display panel handling. JIS standards shape ESD-safe construction requirements for electronics assembly applications. Aichi Prefecture food and beverage clusters pilot outcome-based uptime guarantees that shift performance risk from operator to supplier.
India
PLI scheme benefits for manufacturing automation are accelerating first-generation robotic cell deployment in export-oriented processing. FSSAI allergen segregation protocols drive stainless steel construction specifications in protein and dairy packaging. Maharashtra and Gujarat contract packaging facilities source hybrid palletizers to manage labor volatility and SKU profile volatility.
China
GB standards for industrial robot safety are tightening compliance documentation for cross-border equipment shipments. MIIT smart manufacturing initiatives prioritize warehouse management system integration with cloud-based inventory platforms. Yangtze River Delta consumer goods distribution centers deploy gantry systems for simultaneous multi-line palletizing.
Global Automatic Palletizer and Depalletizer Market Competitive Landscape
Technology licensing dominates the current landscape as vendors race to decouple mechanical performance from regulatory risk. The vendor base clusters around three strategic archetypes: integrated automation conglomerates with captive component production, specialized material-handling fabricators with regional installation density, and emerging hybrid-system developers serving contract manufacturing volatility. Portfolio diversification and geographic expansion constitute the primary competitive vectors, with particular emphasis on separating hardware procurement from predictive maintenance subscriptions.
Among Germany-based integrated automation providers, KUKA AG and Krones AG exemplify the captive-production archetype, anchoring premium positioning through in-house manufacturing of servo-driven layer-forming heads. FANUC Corporation occupies a distinct position among Japan-based precision automation specialists, representing the vision-guided controller segment that automates adaptive gripping in high-speed operations. These three entities collectively illustrate how geographic manufacturing concentration and technology specialization stratify competitive positioning across certification-intensive and throughput-maximizing market segments.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Krones AG |
| FANUC Corporation |
| Schneider Packaging Equipment Company |
| Columbia Machine |
| KUKA AG |
| Yaskawa Electric Corp |
| RMH Systems |
| ABB |
| Others |
Supply & Pricing Matrix
Contract manufacturers serving volatile SKU profiles in Maharashtra and Gujarat operate on project-based equipment procurement with outcome-based uptime guarantees. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling.
Pricing Analysis
Carbon fiber-reinforced polymer tooling costs pass through to end-users via servo motor and actuator pricing tiers. Price differentiation centers on ISO 10218-2 collaborative safety certification and FDA cGMP validation documentation. Cost compression in standard-tier conventional palletizers is intensifying because aluminum servo motor supply concentration limits third-party sourcing. Beverage handling plants show highest price sensitivity; pharmaceutical packaging facilities absorb premium positioning for cleanroom compatibility.
Supply Chain Analysis
Aluminum servo motor production rests on captive manufacturing in Germany, Japan, and China. Carbon fiber-reinforced polymer feedstock draws from aerospace composite suppliers; vacuum gripper suction circuits hinge on precision pneumatic component specialists. Single-source vulnerability concentrates in Stuttgart-based layer-forming head production. Distribution runs through systems integrators and direct OEM sales to automotive supplier parks and chemical export hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive compliance timeline in Germany runs 18-24 months ahead of OSHA mechanical power-press harmonization in the United States, creating arbitrage for vendors with dual-certification capabilities.
For Market Incumbents: Lock in captive production of servo-driven layer-forming heads to defend against emerging hybrid-system developers. Invest in ISO 10218-2 collaborative safety certification ahead of EU deadlines to capture premium positioning in pharmaceutical packaging. For New Entrants and Emerging Players: Systems integrators familiar with force-torque sensing calibration represent the most accessible channel into collaborative robot installations. Target contract manufacturing clusters in India with first-generation robotic cells for export compliance. Lead with hybrid architecture pilots that switch between robotic and conventional modes without line reconfiguration. For Investors and Strategic Acquirers: Packaging automation conglomerates are the most active acquirer in this space, seeking vision-guided controller specialists and carbon fiber tooling fabricators. The 5-10 year viability window favors targets with integrated force-torque sensing and pharmaceutical validation capabilities. Watch for divergence between collaborative robot payload advances and regional safety certification timelines as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Development | Enables contract manufacturers in Maharashtra to switch between robotic and conventional modes without reconfiguration. |
| Carbon Fiber Tooling Integration | Decouples end-of-arm assemblies from aluminum to cut cycle-weight ratios in high-cycle beverage operations. |
| Vision-Guided Controller Acquisition | Automates adaptive gripping for high-speed food bagging lines across North America and Japan. |
| Dual-Certification Investment | Positions vendors to serve EU Machinery Directive and OSHA harmonization timelines simultaneously. |
| Predictive Maintenance Unbundling | Separates hardware procurement from recurring revenue streams in Japanese food and beverage clusters. |
Research Methodology
Coverage spans Germany, Japan, the United States, India, and China, with primary inputs from each. Plant engineers, OEM procurement teams, aftermarket service heads, and systems integrators provided operational data. Secondary validation drew from EU Machinery Directive filings, OSHA mechanical power-press regulations, FDA cGMP guidance documents, and customs/trade data. Bottom-up equipment shipment analysis triangulated with top-down end-use industry demand modeling.
Rate-of-change decomposition structured the analytical framework across the analysis window. Segmentation dimensions included product type, technology architecture, application vertical, and end-user industry. CAGRs derived from equipment procurement velocity in automotive supplier parks, pharmaceutical packaging facilities, and beverage handling plants. Forecast inputs incorporated collaborative robot payload advancement curves and regional safety certification timeline divergence.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation phase-down schedules and REACH substance restriction enforcement. Forecasts reflect documented assumptions about labor volatility in food processing and SKU proliferation trajectories. A small set of named triggers warrants ongoing watch: collaborative robot safety engineer scarcity, warehouse management system interface complexity, and aluminum servo motor supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Tipper Pads Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Shiplifts & Transfer Systems Market