
 Material Handling Equipment Tires Market | 2026-2036
Material Handling Equipment Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Material Handling Equipment Tires Market Analytics
Skilled tire technician availability is bifurcating the competitive landscape as OEM service networks struggle to match independent distributor coverage. Bridgestone Corporation leverages its captive dealer network to sustain aftermarket loyalty across Japanese and North American warehousing hubs. Michelin Group anchors premium positioning through advanced polyurethane formulations for clean-room material handling environments. Continental AG competes on integrated telematics-enabled tire monitoring systems that reduce unplanned downtime for fleet operators.
Material handling equipment tires are engineered elastomeric structures designed to withstand concentrated loads, puncture hazards, and repetitive duty cycles on industrial surfaces, typically manufactured through compression molding or calendering processes with reinforcement layers of steel or textile cord. These components transfer motive power, absorb shock, and maintain stability for forklifts, reach trucks, and tow tractors operating in warehouses, manufacturing floors, and construction sites. Solid tires dominate high-intensity warehousing applications where puncture elimination outweighs ride comfort considerations, while pneumatic variants retain structural importance in outdoor construction and uneven surface operations. Non-marking tire formulations command margin premiums in food processing and pharmaceutical verticals where floor contamination protocols restrict carbon black content.
FDA regulations govern tire materials in food-contact warehousing environments, OSHA standards mandate load capacity labeling and inspection protocols, and EPA guidelines influence volatile organic compound emissions from tire manufacturing facilities. The EU REACH framework restricts specific chemical additives in rubber compounds, compelling reformulation investments across suppliers serving European manufacturing and retail distribution chains. Stakeholders must monitor evolving electrification standards from NHTSA and corresponding weight distribution changes in battery-powered forklift fleets that alter tire load specifications and wear patterns.
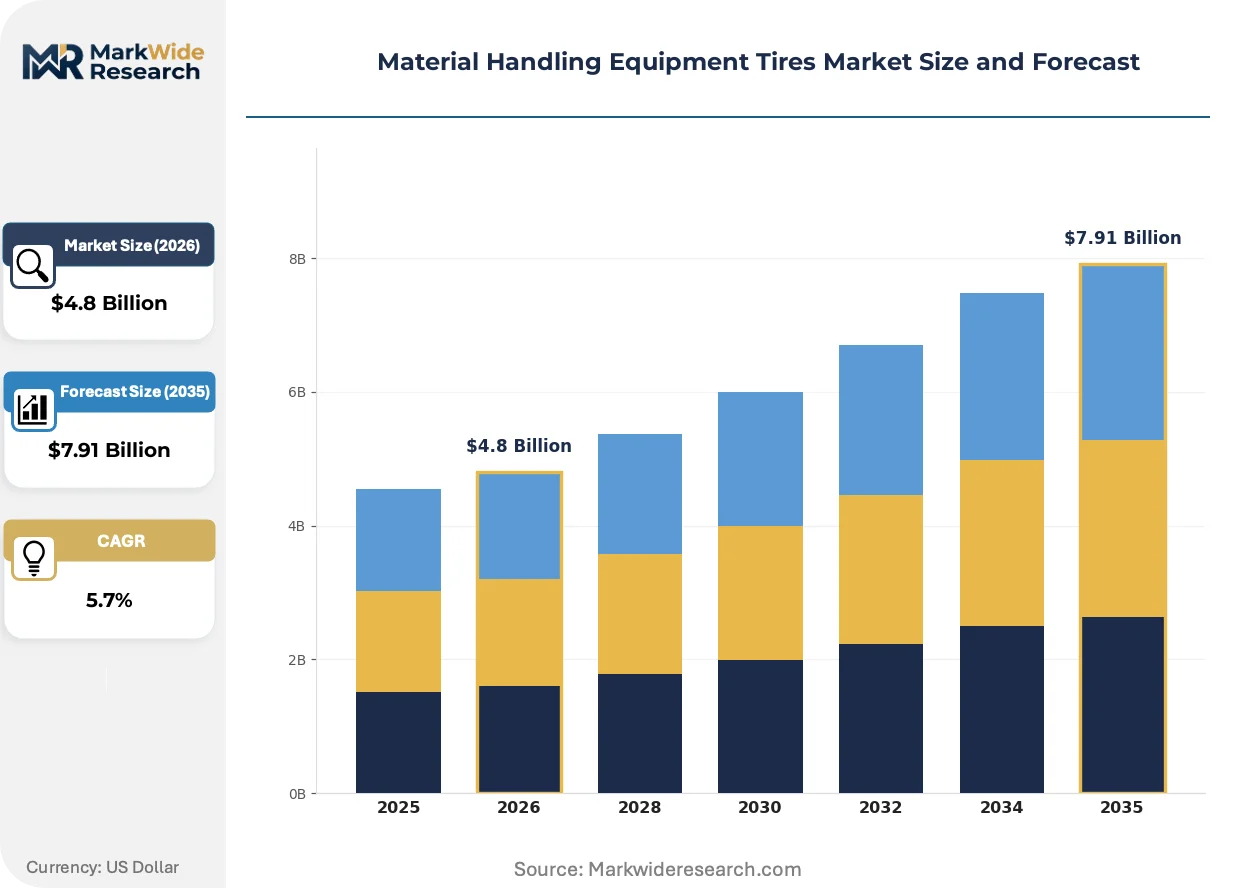
Market Dynamics
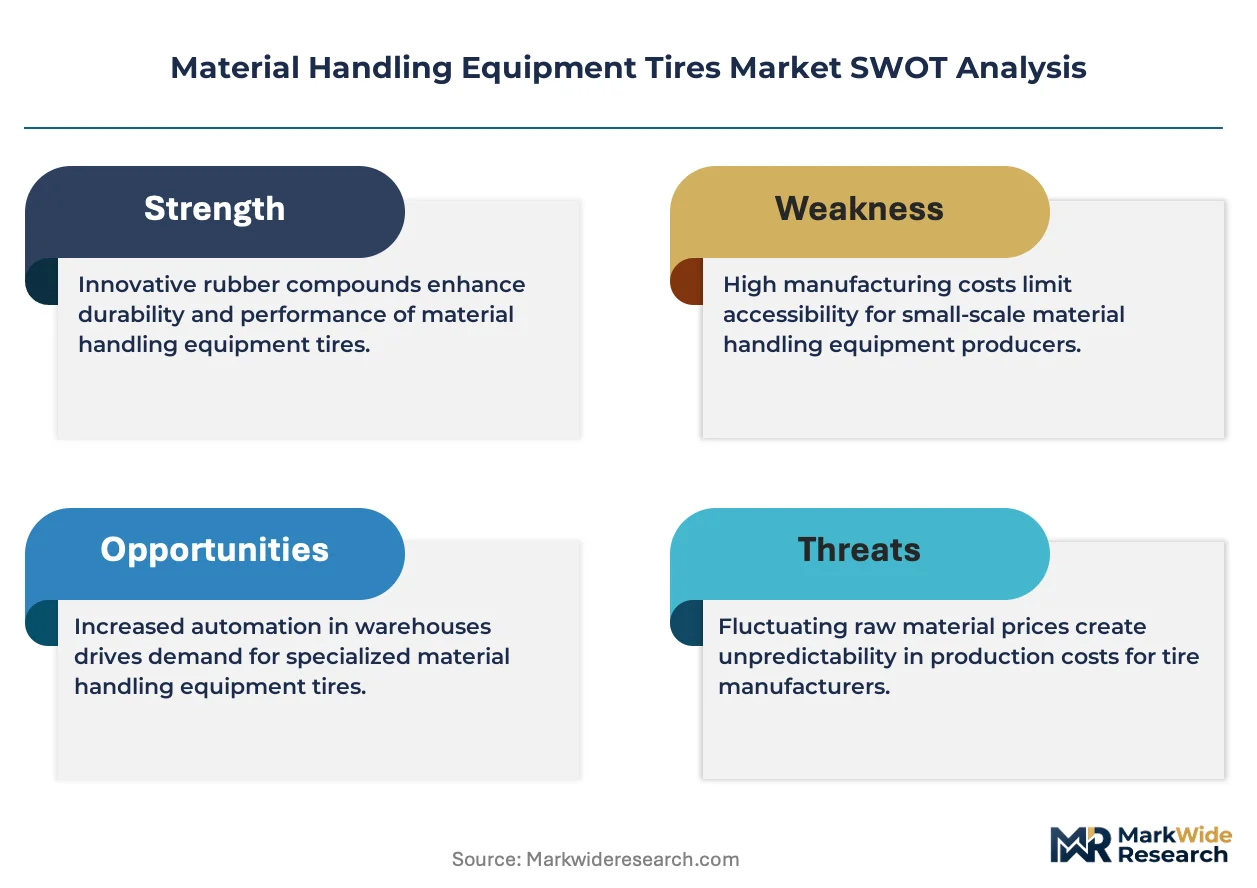
Warehouse electrification is compressing replacement cycles as battery-powered forklifts impose distinct load distributions and thermal stresses on tire compounds compared to internal combustion equivalents.
Growth Catalysts
- EU F-Gas Regulation:Phasedown mandates for fluorinated greenhouse gases are accelerating fleet turnover toward electric material handling equipment, which requires specialized low-rolling-resistance tire formulations.
- Polyurethane formulation advances:Enhanced cast polyurethane compounds now deliver load-bearing capacity rivaling solid rubber while reducing floor marking in food processing and pharmaceutical clean rooms.
- Germany's industrial logistics corridor:Concentrated distribution hub development around the Rhine-Ruhr and Stuttgart regions sustains premium demand for non-marking tire specifications.
Market Restraints
- Natural rubber price volatility:Input cost swings tied to Southeast Asian supply disruptions compress margin stability for manufacturers dependent on conventional elastomer compounds.
- REACH compliance burden:ECHA restrictions on specific chemical additives in rubber formulations force costly reformulation investments without immediate price recovery mechanisms.
- Pneumatic tire substitution ceiling:Solid and polyurethane variants face technical limitations in outdoor construction applications where pneumatic structures retain irreplaceable shock absorption performance.
Strategic Opportunities
- India's warehouse automation wave:PLI scheme incentives for logistics infrastructure expansion create first-mover positioning for tire suppliers establishing local compounding facilities.
- Telematics-integrated tire monitoring:Convergence of IoT sensors with predictive maintenance platforms enables outcome-based service contracts for fleet operators seeking unplanned downtime reduction.
- OSHA inspection protocol alignment:Mandated load capacity labeling requirements create compliance-driven replacement demand among smaller fleet operators previously deferring maintenance.
Industry Challenges
- Certified tire technician scarcity:Specialized skills for polyurethane casting and solid tire press mounting concentrate in OEM service networks, limiting independent distributor service capabilities.
- Legacy fleet integration friction:Electrification-driven specification shifts create inventory complexity as distributors must stock parallel tire ranges for mixed IC and battery-powered equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Handling Equipment Tires Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Tires, Pneumatic Tires, Press-on Band Tires, Non-Marking Tires Industry Vertical: Warehousing, Construction, Retail, Manufacturing Application: Forklifts, Pallet Jacks, Tow Tractors, Reach Trucks Material: Rubber, Polyurethane, Plastic, Others |
| Companies Covered | Bridgestone Corporation, Michelin Group, Continental AG, Camso, Trelleborg AB, Hankook Tire, The Goodyear Tire & Rubber Company, Balkrishna Industries Limited, Sumitomo Rubber Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Handling Equipment Tires Market Evolving Landscape
Material composition and monitoring intelligence are converging to redefine performance benchmarks across warehousing and manufacturing floor applications.
Advanced polyurethane formulations with engineered microcellular structures are displacing conventional solid rubber in high-intensity clean-room environments. Pharmaceutical and semiconductor manufacturers in Japan and South Korea are specifying these compounds for their combined load capacity and contamination control properties. The shift is compressing demand for carbon-black-heavy traditional solid tires in premium verticals.
REACH framework amendments are tightening restrictions on polycyclic aromatic hydrocarbons and specific plasticizers in rubber compounds. Tire manufacturers serving European material handling fleets must reformulate curing agents and accelerators to maintain market access. German and French distributors are consolidating supplier relationships to ensure batch-level compliance documentation.
Fleet operators are unbundling tire procurement from OEM equipment purchases and establishing direct relationships with specialized distributors. Large third-party logistics providers in North American distribution hubs are negotiating volume contracts that bypass traditional dealer networks. This disintermediation is most pronounced among e-commerce fulfillment operators with standardized forklift fleets exceeding five hundred units.
Material Handling Equipment Tires Market Segmentation
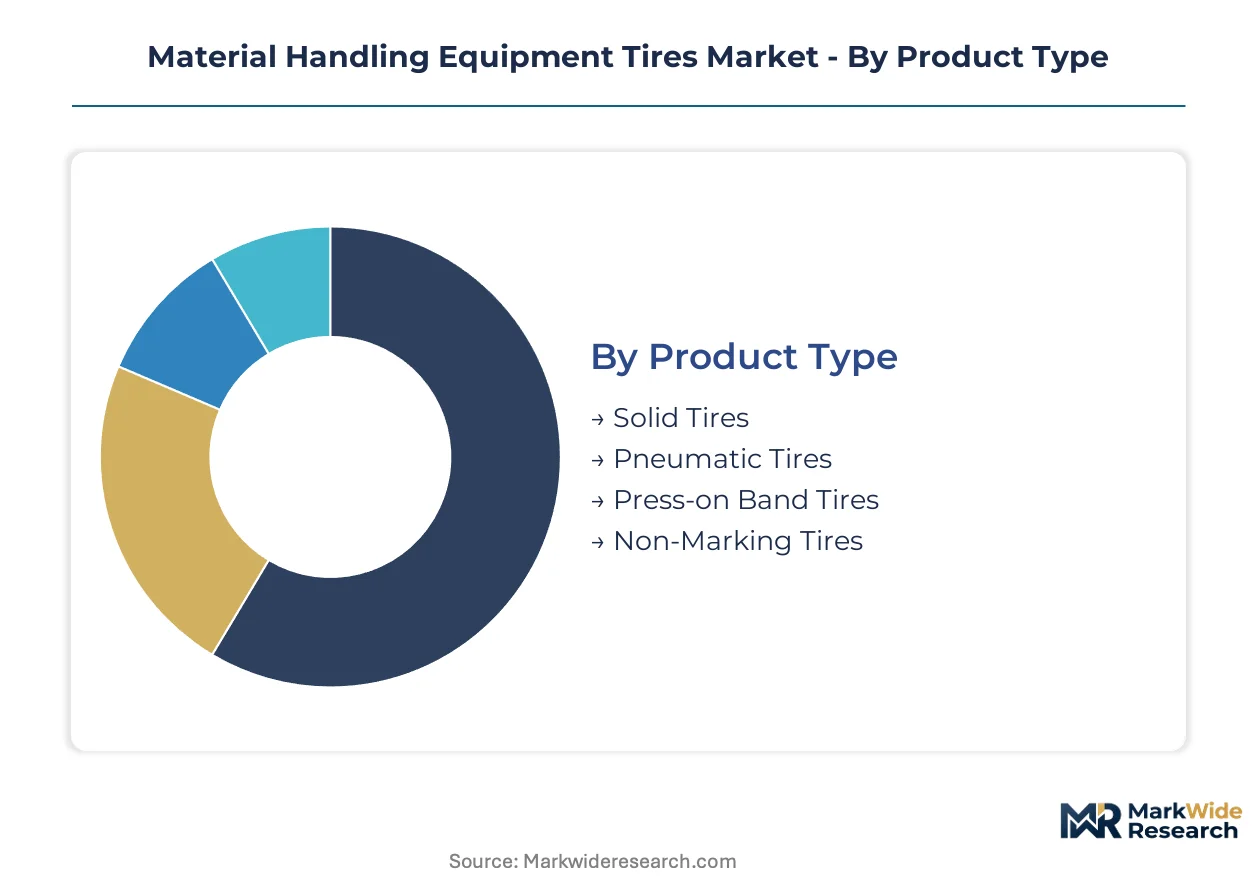
Tire specification diversity across product types, industry verticals, and equipment applications creates distinct margin architectures. Procurement patterns diverge sharply between cost-sensitive construction fleets and compliance-driven food processing operations.
Product Type:
Margin pools concentrate in specialized formulations where technical differentiation commands premium positioning over commodity solid rubber.
- Solid Tires:Molded elastomer structures with steel or textile reinforcement layers eliminate puncture risk entirely. High-intensity warehousing operations in German distribution hubs specify these for three-shift continuous duty cycles where downtime costs exceed tire replacement premiums.
- Non-Marking Tires:Carbon-black-free formulations using silica or alternative reinforcing agents prevent floor contamination in FDA-regulated food processing environments. Pharmaceutical clean rooms and semiconductor fabs in Japan and South Korea mandate these specifications despite 40-60% cost premiums over standard compounds.
- Pneumatic Tires:Air-filled chambers deliver irreplaceable shock absorption for outdoor construction and uneven surface operations.
- Press-on Band Tires:Cylindrical bands press-mounted onto wheel cores enable rapid field replacement without specialized equipment.
Solid tires hold installed capacity. Non-marking tires are rotating up the share rankings.
Industry Vertical:
Application environments dictate specification complexity, with clean-room protocols generating the steepest margin expansion.
- Warehousing:Three-shift e-commerce fulfillment centers drive replacement cycle compression as battery-powered fleets impose distinct thermal and load distribution stresses. Amazon and Walmart distribution hubs in the US specify predictive maintenance contracts tied to telematics-enabled tire monitoring.
- Manufacturing:Just-in-time production floors demand zero-failure reliability where unplanned downtime halts assembly lines. Automotive plants in Stuttgart and Toyota City negotiate integrated tire-service contracts spanning multiple facility locations.
- Construction:Pneumatic retention dominates outdoor rough-terrain applications where shock absorption outweighs puncture elimination priorities.
- Retail:Mixed indoor-outdoor operations at big-box distribution centers create specification fragmentation across single fleets.
Warehousing holds installed capacity. Manufacturing is rotating up the share rankings.
Application:
Equipment weight classes and duty cycles segment demand by load-bearing requirements and replacement frequency.
- Forklifts:Counterbalanced designs impose concentrated loads on drive tires during acceleration and braking cycles. Battery-powered Class I and II forklifts in North American distribution hubs require low-rolling-resistance compounds to preserve electric range.
- Reach Trucks:Narrow-aisle designs place asymmetric lateral stresses on tires during mast extension and retraction. High-rack warehousing in the Rhine-Ruhr corridor specifies polyurethane compounds for combined load capacity and floor protection.
- Tow Tractors:Continuous low-speed operation creates distinct wear patterns favoring abrasion-resistant formulations.
- Pallet Jacks:Manual and electric variants span economy through premium tiers based on duty cycle intensity.
Forklifts hold installed capacity. Reach trucks are rotating up the share rankings.
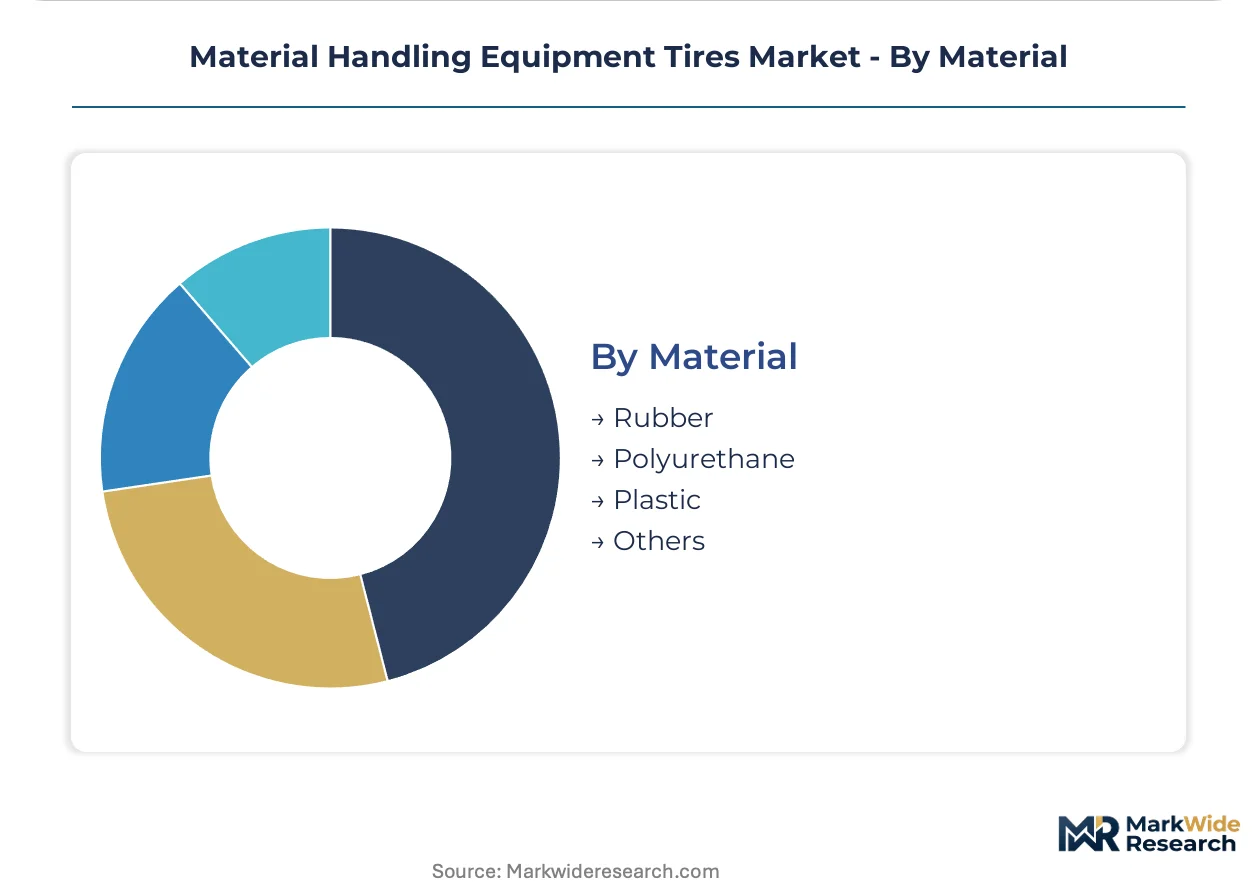
Material:
Compound chemistry determines performance ceilings and regulatory compliance pathways across end-use verticals.
- Polyurethane:Cast microcellular structures deliver load-bearing capacity rivaling solid rubber with superior floor marking resistance. ECHA REACH restrictions on aromatic amines and plasticizers compel reformulation investments for European market access.
- Rubber:Natural and synthetic elastomer blends dominate volume production through compression molding and calendering processes. Southeast Asian supply disruptions for natural rubber create input cost volatility compressing margin stability.
- Plastic:Thermoplastic compounds serve light-duty applications with reduced load requirements.
- Others:Experimental compounds including recycled content and bio-based alternatives address emerging sustainability procurement criteria.
Rubber holds installed capacity. Polyurethane is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Material handling equipment tires see divergent consumption patterns across major economies, with European markets prioritizing regulatory-compliant low-rolling-resistance formulations while Asian markets emphasize cost-optimized solid rubber compounds for high-volume warehousing operations.
United States
E-commerce fulfillment center expansion drives replacement cycle compression as battery-powered forklift fleets impose distinct thermal stresses on tire compounds. OSHA mandates load capacity labeling and inspection protocols that create compliance-driven demand among mid-sized fleet operators. Distribution hubs around Chicago, Dallas-Fort Worth, and the Inland Empire sustain concentrated demand for telematics-integrated tire monitoring systems.
Germany
Industrial logistics corridor development around the Rhine-Ruhr and Stuttgart regions anchors premium demand for non-marking tire specifications. EU F-Gas Regulation and REACH compliance standards compel reformulation investments for European market access. Automotive manufacturing clusters in Baden-Württemberg negotiate integrated tire-service contracts spanning multiple facility locations with zero-failure reliability requirements.
China
Domestic warehouse automation expansion creates scale opportunities for local compounding facilities serving standardized forklift fleets. GB standards and MIIT electrification guidelines reshape material specifications for battery-powered material handling equipment. Yangtze River Delta manufacturing zones concentrate demand for abrasion-resistant formulations in high-intensity three-shift operations.
Japan
Pharmaceutical and semiconductor clean-room manufacturers specify advanced polyurethane compounds for contamination control properties. METI industrial standards govern tire performance benchmarks in precision manufacturing environments. Toyota City automotive production floors demand zero-failure reliability where unplanned downtime halts assembly lines entirely.
India
PLI scheme incentives for logistics infrastructure expansion create first-mover positioning for suppliers establishing local manufacturing presence. BIS certification requirements and DGFT import regulations shape procurement patterns for domestic fleet operators. Maharashtra and Gujarat warehouse automation clusters drive specification shifts toward solid tire variants for puncture elimination in high-intensity operations.
Material Handling Equipment Tires Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through captive distribution networks and the lower tier competing on service proximity and application-specific formulations. The market structure rewards backward integration into rubber compounding and polyurethane casting capabilities while penalizing pure distribution plays. Two strategic archetypes dominate: telematics-enabled service integrators and formulation specialists serving clean-room verticals. Competitive intensity concentrates on geographic expansion into underpenetrated warehouse automation markets and portfolio diversification beyond commodity solid rubber into advanced polyurethane compounds.
Among Japanese and European tire manufacturers, Bridgestone Corporation, Michelin Group, and Continental AG exemplify divergent strategic positioning within the premium tier. Bridgestone leverages its captive dealer network structure to sustain aftermarket loyalty across established warehousing hubs. Michelin anchors its positioning through advanced formulation capabilities for contamination-sensitive environments. Continental competes on integrated monitoring systems that reduce unplanned downtime for fleet operators. These three occupy distinct vectors within the premium-competitive space without direct overlap in core capability claims.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Continental AG |
| Camso |
| Trelleborg AB |
| Hankook Tire |
| The Goodyear Tire & Rubber Company |
| Balkrishna Industries Limited |
| Sumitomo Rubber Industries |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Southeast Asian natural rubber processing facilities directly shapes both supply concentration and price floors for material handling tire manufacturers. German and Japanese compounders leverage scale advantages to absorb input volatility, while smaller distributors face margin compression during supply disruptions.
Pricing Analysis
Long-term offtake contracts dominate procurement between large fleet operators and tier-one manufacturers, insulating buyers from spot-market volatility in natural rubber and synthetic elastomer inputs. Pricing stratifies across premium, standard, and economy tiers based on certification grade for FDA food-contact compliance and volume scale for multi-facility logistics contracts. Cost compression in economy-grade solid rubber compounds is intensifying because Indian and Chinese manufacturers are expanding press-on band capacity. Third-party logistics providers with standardized fleets exceeding five hundred units exhibit the lowest price sensitivity, while independent warehouse operators defer replacement cycles during input cost spikes.
Supply Chain Analysis
Just-in-time inventory strategies prevail among North American and European distributors serving high-intensity warehousing corridors, though strategic stockpiling of REACH-compliant polyurethane precursors is emerging among German distributors anticipating ECHA restriction amendments. Raw material sourcing draws from Thailand and Indonesia for natural rubber, China and South Korea for synthetic elastomers, and Germany and Japan for specialized polyurethane curing agents. Single-source vulnerability concentrates in advanced polyurethane casting equipment where Japanese and German OEMs control proprietary machinery designs. Distribution runs through captive dealer networks for OEM-anchored service contracts and independent distributors for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehouse electrification represents an early-cycle expansion tailwind as battery-powered forklift penetration accelerates replacement cycle compression across North American and European distribution hubs.
For Market Incumbents: Secure backward integration into polyurethane casting capabilities to defend margin stability against REACH-driven reformulation costs and emerging Chinese compounders. Consolidate certified technician training programs to limit independent distributor service encroachment in high-value telematics-integrated contracts. Capacity expansion in India's Maharashtra and Gujarat clusters captures PLI scheme tailwinds before local competitors establish compounding footholds.
For New Entrants and Emerging Players: Telematics-enabled predictive maintenance services present a service-layer gap where incumbent OEM networks under-serve mid-sized fleet operators with sub-five-hundred-unit bases. India's warehouse automation wave offers the most penetrable geography for first-mover positioning through local manufacturing partnerships. A direct-to-fleet go-to-market angle bypassing traditional dealer networks aligns with e-commerce fulfillment operator procurement centralization trends.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated service providers with multi-year fleet maintenance contracts spanning automotive and pharmaceutical clean-room verticals. Long-term viability favors compounders with demonstrated REACH compliance pathways and established relationships with German automotive manufacturing clusters. The signal to watch is battery-electric forklift fleet penetration rates crossing thresholds that trigger specification shifts toward low-rolling-resistance tire demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Casting | REACH compliance investments by Continental and Michelin secure European market access against reformulation risks. |
| Telematics-Integrated Service Contracts | Amazon and Walmart distribution hubs in the US specify predictive maintenance tied to IoT-enabled tire monitoring. |
| Local Manufacturing Expansion in India | PLI scheme incentives for logistics infrastructure create first-mover positioning for suppliers establishing Gujarat compounding facilities. |
| REACH-Compliant Formulation Development | ECHA restrictions on aromatic amines compel reformulation investments for tire manufacturers serving Rhine-Ruhr distribution corridors. |
| Certified Technician Training Programs | Specialized skills for solid tire press mounting concentrate in OEM networks, limiting independent distributor capabilities. |
Research Methodology
Initial hypotheses were tested against primary input from fleet maintenance directors, OEM procurement managers, aftermarket service heads, and tire compound technical directors, and refined through secondary validation across customs trade data, SEC 10-K filings, ECHA regulatory submissions, and automotive production databases. Bottom-up triangulation aggregated replacement cycle data from individual warehouse operators and distribution hubs, while top-down validation cross-referenced against macroeconomic indicators for logistics infrastructure investment and electrification adoption rates.
Variance decomposition across the projection horizon isolated volume drivers by product type, industry vertical, equipment application, material composition, and regional regulatory cluster. CAGRs were derived through segment-level modeling of replacement frequency, fleet electrification penetration, and specification shift elasticities. Industry-specific inputs included OSHA inspection protocol compliance rates, EU F-Gas Regulation phase-down timelines, and battery-electric forklift load distribution characteristics altering tire wear patterns.
Underlying assumptions cover sustained warehouse automation capital expenditure, REACH framework stability, and natural rubber supply continuity from Southeast Asian processing facilities, with deviation risk concentrated in regulatory amendment timing and battery-electric forklift fleet conversion rates. Revision becomes warranted when battery-electric penetration crosses thresholds that accelerate specification shifts beyond modeled replacement cycle compression rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Lump Breaker Machines Market