
 Robotic Palletizers and De-Palletizers Market | 2026-2036
Robotic Palletizers and De-Palletizers Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Palletizers and De-Palletizers Market Analytics
Aftermarket service revenue is reconfiguring margin pools away from pure hardware sales across the robotic palletizer landscape. FANUC Corporation leverages its global spare parts network to capture recurring service contracts. ABB Ltd. anchors its position through predictive maintenance platforms integrated with motion control systems. KUKA AG competes by extending software licensing for palletizing path optimization.
Robotic palletizers and de-palletizers are automated material handling systems that stack or unstack products onto pallets using programmable multi-axis arms, typically operating at speeds of 10-40 cycles per minute with payload capacities from 10 kg to over 1,500 kg depending on arm configuration. These systems serve primary industrial functions in end-of-line packaging and warehouse inbound receiving, replacing manual labor in repetitive lifting operations. Articulated robots dominate installed capacity due to their reach flexibility and proven reliability in high-throughput food and beverage lines. Cobots represent the fastest-expanding product category as smaller manufacturers seek collaborative deployment without extensive safety caging. Vision systems technology commands premium pricing by enabling real-time product identification and defect rejection during palletizing cycles.
FDA regulations governing pharmaceutical packaging traceability shape validation requirements for de-palletizing systems in drug distribution. OSHA machine guarding standards and ISO 10218 robot safety protocols mandate protective enclosures or collaborative force-limiting designs that influence system architecture. EU machinery directives and CE marking requirements constrain market access for non-compliant equipment imports. Stakeholders must monitor evolving AI algorithm validation standards as autonomous palletizing decisions expand beyond pre-programmed routines.
Market Dynamics
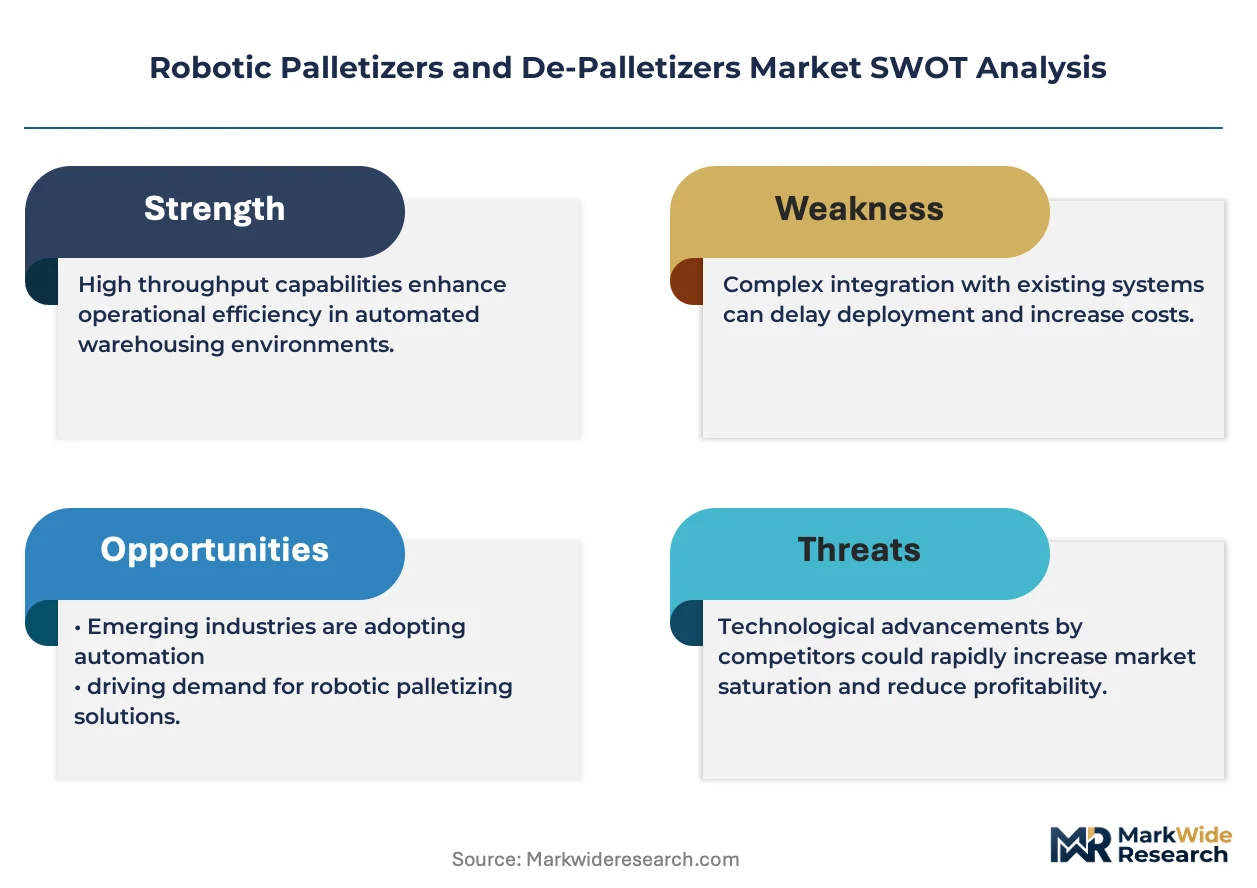
ISO 10218 robot safety protocols and EU machinery directives are compressing product development timelines while expanding the addressable market for collaborative force-limiting designs that eliminate protective caging.
Growth Catalysts
- Labor scarcity in food and beverage:European packaging lines face acute operator shortages, accelerating articulated robot deployment for repetitive lifting operations at speeds of 10-40 cycles per minute.
- EU machinery directive compliance:CE marking requirements for autonomous palletizing systems create certified product differentiation that locks out non-compliant imports.
- Cobot technology maturation:Collaborative arms with integrated vision systems enable smaller manufacturers to automate without extensive facility reconfiguration or dedicated safety infrastructure.
Market Restraints
- Steel and servo motor cost volatility:Payload capacities exceeding 1,500 kg require precision-machined arm components vulnerable to commodity price swings.
- German automotive supply concentration:Automation investment clusters around Stuttgart and Munich, creating geographic demand vulnerability.
- Pharmaceutical validation timelines:FDA traceability requirements for drug distribution de-palletizing extend commissioning cycles by 6-18 months.
Strategic Opportunities
- Indian contract manufacturing expansion:PLI scheme incentives for processed food and electronics assembly create first-mover advantages for cobot vendors establishing local service networks.
- Predictive maintenance platform convergence:Integration of motion control telemetry with AI-driven failure prediction transforms hardware vendors into recurring revenue service providers.
- Japan's pharmaceutical logistics modernization:PMDA serialization mandates drive demand for vision-equipped de-palletizers with real-time defect rejection capabilities.
Industry Challenges
- Multi-axis programming expertise scarcity:Path optimization for irregular product geometries requires specialized robotics engineers concentrated in automotive hubs.
- Legacy warehouse management system integration:Pre-2010 ERP installations lack native APIs for real-time palletizing coordination, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Palletizers and De-Palletizers Market |
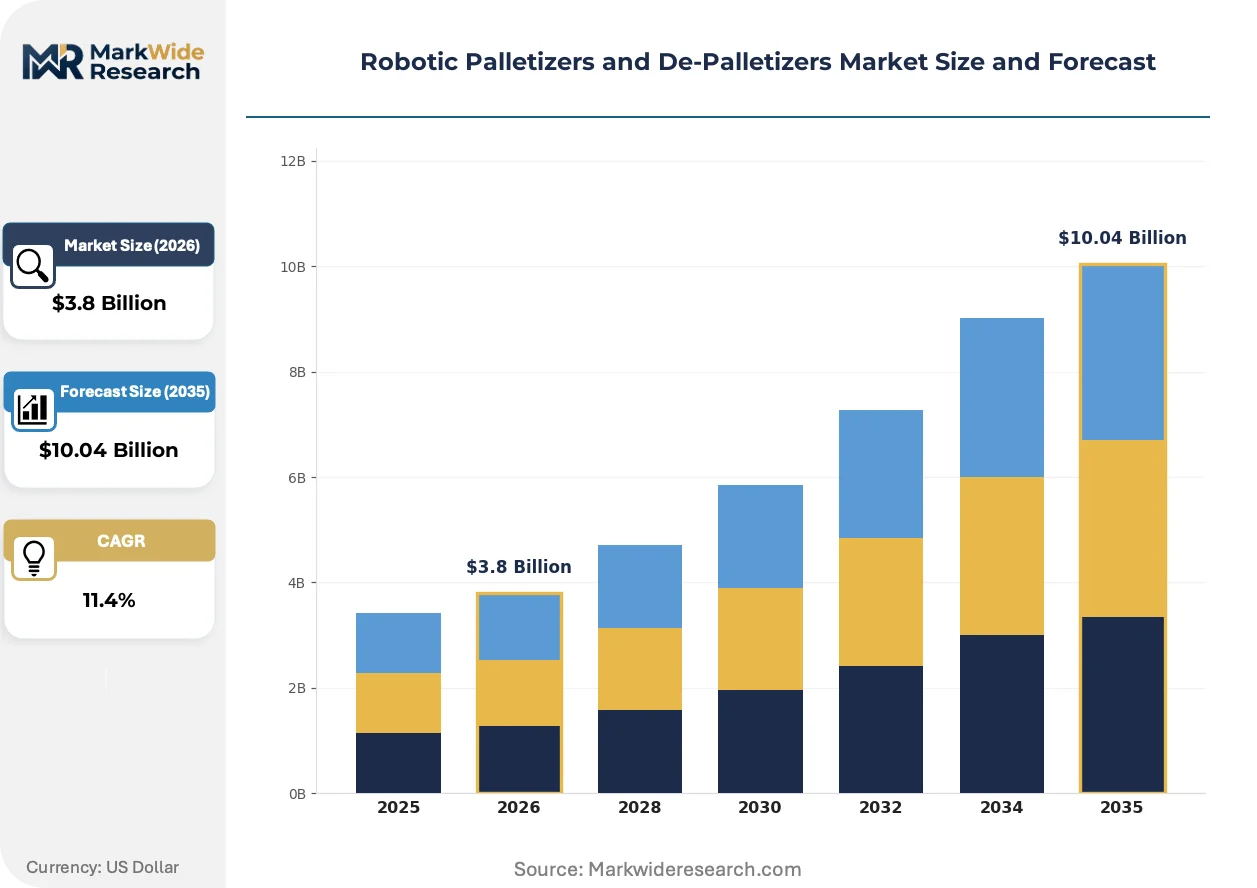
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Gantry Robots, Delta Robots, Cobots Application: Food & Beverage, Automotive, Consumer Goods, Pharmaceuticals End User: Manufacturing Facilities, Warehousing, Distribution Centers, Retail Technology: Vision Systems, AI Algorithms, IoT Integration, Motion Control |
| Companies Covered | FANUC Corporation, ABB Ltd., KUKA AG, KION GROUP AG, Krones AG, Yaskawa Electric Corporation, Schneider Packaging Equipment Company, Inc., Daifuku Co., Ltd., Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Palletizers and De-Palletizers Market Evolving Landscape
Vision-guided palletizing is collapsing the boundary between quality control and material handling, while regulatory pressure on collaborative safety and pharmaceutical traceability accelerates hardware-software convergence.
Embedded 3D vision systems with real-time product identification capabilities are collapsing the traditional separation between palletizing execution and inbound quality inspection. Food and beverage manufacturers in Germany and the Netherlands deploy these systems at line speeds previously requiring dedicated inspection stations. The technology is collapsing capital expenditure requirements for mid-volume producers by eliminating redundant handling equipment.
EU AI Act risk classification rules for autonomous decision-making systems are reshaping validation protocols for self-optimizing palletizing paths. Manufacturers must document algorithm training datasets and decision logic for CE marking renewal. Pharmaceutical distribution centers in Belgium and Ireland face the steepest compliance burden as their de-palletizing operations handle the highest product variety.
Service contract unbundling from hardware procurement is fragmenting traditional capital equipment sales models. Food producers in France and Italy now separately negotiate predictive maintenance subscriptions and software license renewals. The shift is most visible among mid-sized co-manufacturers lacking internal automation engineering capabilities.
Robotic Palletizers and De-Palletizers Market Segmentation
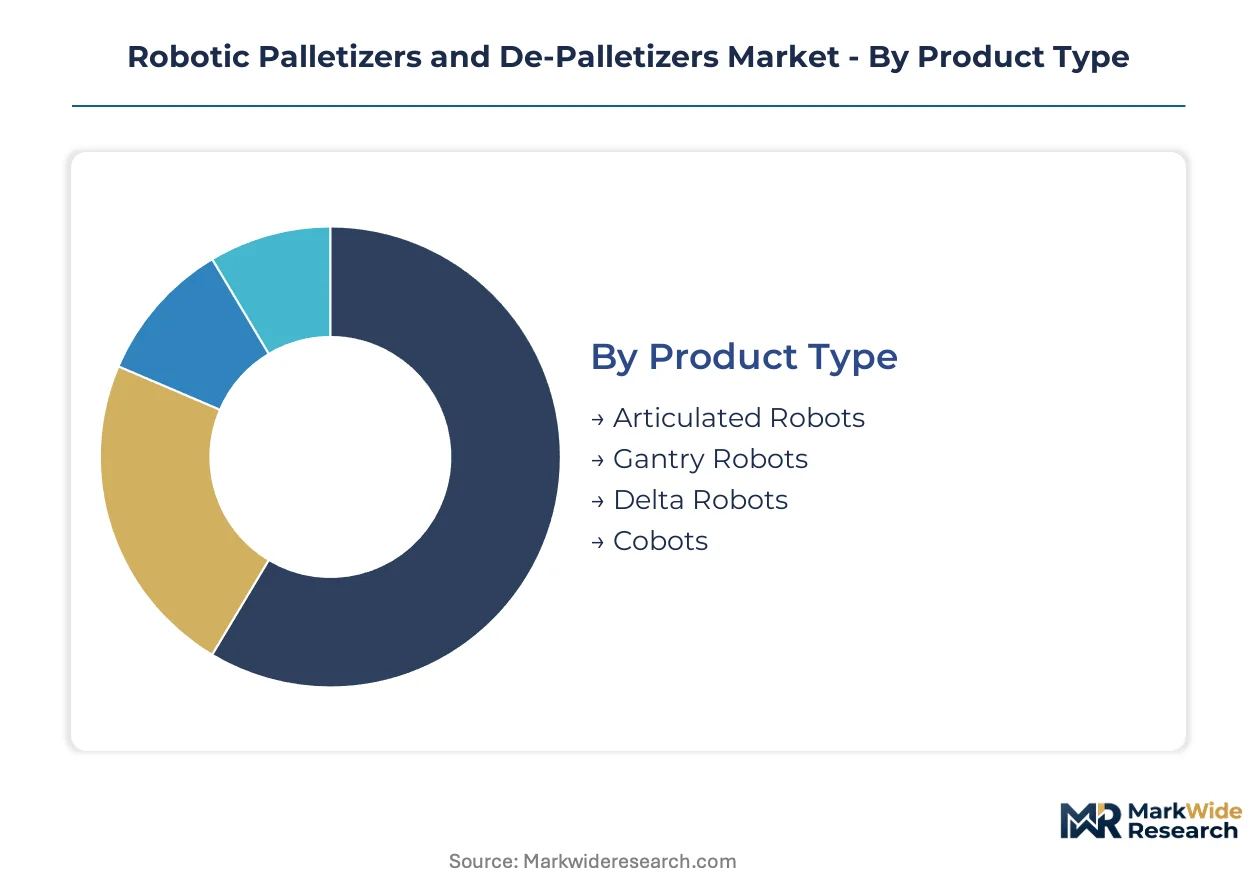
Segmentation in robotic palletizing reveals how payload requirements, facility footprints, and regulatory environments fragment procurement patterns across industrial verticals. Equipment buyers prioritize cycle speed, collaborative safety certification, or vision-guided precision depending on their product mix and labor constraints.
Product Type:
Mature articulated architectures dominate installed capacity while emerging collaborative formats capture greenfield deployment among smaller manufacturers.
- Articulated Robots:Six-axis configurations with payload capacities from 10 kg to over 1,500 kg deliver 10-40 cycles per minute through precision-machined servo-driven joints. Automotive suppliers in Stuttgart and Munich anchor demand for heavy-payload variants handling engine blocks and transmission assemblies.
- Cobots:Force-limiting collaborative arms with integrated safety sensors eliminate protective caging requirements, enabling deployment in existing packaging lines without facility reconfiguration. Food and beverage producers in France and Italy drive adoption as labor scarcity intensifies and CE marking for collaborative systems matures.
- Gantry Robots:Cartesian coordinate systems mounted on overhead rails provide rigid positioning accuracy for uniform pallet patterns across high-volume consumer goods lines.
- Delta Robots:Parallel kinematic structures achieve rapid pick-and-place speeds for lightweight pharmaceutical and confectionery products in cleanroom environments.
Articulated robots retain volume leadership; cobots hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive automotive installations from mid-scale food packaging deployments and high-validation pharmaceutical systems.
- Food & Beverage:End-of-line packaging operations demand stainless steel construction and washdown-rated components for sanitary compliance. European bottling facilities in Germany and the Netherlands deploy vision-guided systems at speeds previously requiring dedicated inspection stations.
- Pharmaceuticals:FDA traceability requirements and PMDA serialization mandates in Japan drive demand for de-palletizers with real-time defect rejection and full batch documentation capabilities.
- Automotive:Tier-1 suppliers require heavy-payload handling with millimeter-level placement accuracy for just-in-sequence assembly line feeding.
- Consumer Goods:High-mix, medium-volume operations prioritize rapid changeover between SKUs through programmable pallet patterns.
Food and beverage commands the largest installed base; pharmaceuticals exhibits the most rapid technology refresh cycles.
End User:
Facility type determines integration complexity, with manufacturing floors requiring line synchronization while distribution centers prioritize inbound receiving throughput.
- Manufacturing Facilities:Production-integrated palletizing demands real-time coordination with filling, wrapping, and labeling equipment through native ERP APIs.
- Distribution Centers:High-velocity de-palletizing for cross-dock operations requires adaptive handling of mixed-SKU inbound freight with minimal manual intervention.
- Warehousing:Buffer storage applications balance throughput density against retrieval flexibility in ambient and temperature-controlled environments.
- Retail:Store-ready pallet building with mixed-case configurations serves direct-to-store distribution networks with specific shelf-stocking sequences.
Distribution centers lead capital deployment; manufacturing facilities show the strongest service contract attachment rates.
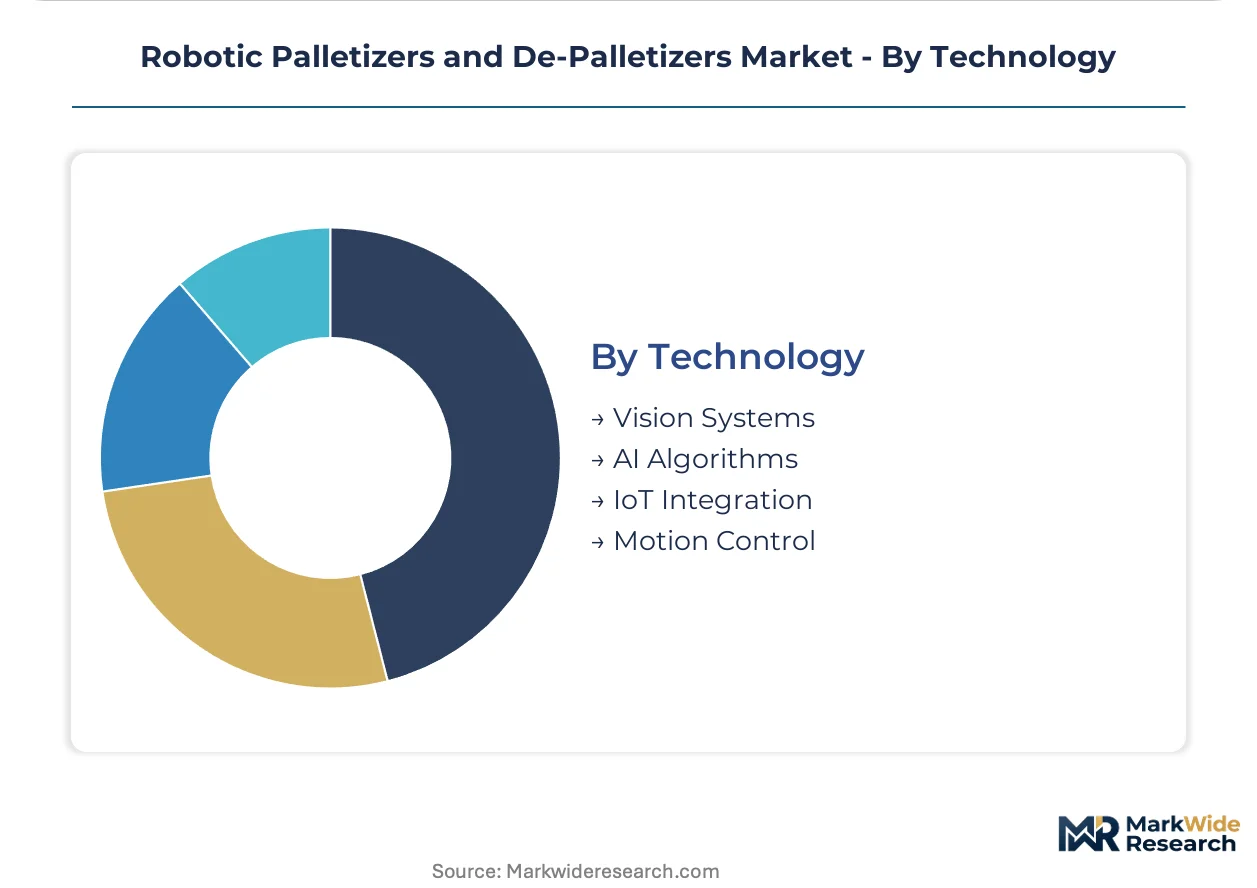
Technology:
Margin concentration follows software and sensor integration depth, with pure mechanical systems commoditizing while AI-augmented platforms capture premium pricing.
- Vision Systems:Embedded 3D cameras with real-time product identification collapse quality control and material handling into single stations, eliminating redundant capital expenditure for mid-volume producers.
- AI Algorithms:Self-optimizing path generation requires documented training datasets and decision logic for EU AI Act compliance, reshaping validation protocols for autonomous palletizing.
- IoT Integration:Telemetry-enabled predictive maintenance transforms hardware vendors into recurring revenue service providers through motion control data monetization.
- Motion Control:Precision servo systems with harmonic drive gearing deliver repeatability specifications that determine placement accuracy in high-value pharmaceutical handling.
Vision systems capture the highest technology premiums; AI algorithms face the steepest regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in manufacturing belts where automotive and food processing clusters coexist with stringent machinery safety regimes. German industrial demand anchors European investment volumes, while Asian contract manufacturing expansion reshapes deployment patterns.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich drive heavy-payload articulated robot procurement for just-in-sequence assembly lines. KBA vehicle safety standards and EU machinery directives mandate CE-marked collaborative designs that eliminate protective caging. Bavaria's packaging machinery corridor around Nuremberg hosts concentrated system integrator activity serving Central European bottling facilities.
United States
Food and beverage distributors in the Midwest and Southeast automate de-palletizing operations amid warehouse labor scarcity. OSHA machine guarding standards and FDA pharmaceutical traceability rules shape validation requirements for drug distribution centers. The Chicago-Detroit industrial corridor anchors demand for high-throughput systems handling mixed-SKU inbound freight.
China
Electronics contract manufacturers in the Yangtze River Delta deploy cobots for flexible end-of-line packaging. MIIT industrial robot subsidy programs and GB national standards accelerate domestic equipment procurement. Shenzhen's logistics technology cluster drives vision-guided palletizing adoption for cross-border e-commerce fulfillment.
Japan
Pharmaceutical distributors modernize de-palletizing infrastructure under PMDA serialization mandates requiring real-time defect rejection. METI productivity enhancement programs subsidize SME automation adoption. The Nagoya manufacturing belt concentrates automotive parts handling demand alongside precision motion control system production.
India
Processed food PLI scheme incentives attract cobot vendors establishing local service networks for mid-sized co-manufacturers. BIS machinery safety certification requirements and FSSAI food handling regulations constrain import-dependent procurement. Maharashtra's Pune-Nashik industrial corridor hosts emerging electronics assembly automation demand.
Robotic Palletizers and De-Palletizers Market Competitive Landscape
Integrated motion control specialists and pure-play material handling fabricators split the market along software-hardware capability lines. Consolidation pressure favors vendors with captive servo drive production and predictive maintenance platform architectures. Three archetypes dominate: Japanese precision automation conglomerates, European industrial engineering groups, and emerging Asian system integrators. Competitive moves center on predictive maintenance subscription unbundling and collaborative safety certification pre-loading.
Among Japanese precision automation conglomerates, FANUC Corporation and Yaskawa Electric Corporation exemplify the integrated motion control archetype through their dominance in servo-driven articulated configurations. ABB Ltd. anchors the European industrial engineering tier with its positioning across heavy-payload automotive installations. KUKA AG occupies a distinctive position within the German automation cluster, representing the convergence of automotive lineage and collaborative robotics capability.
| Leading Market Players |
|---|
| FANUC Corporation |
| ABB Ltd. |
| KUKA AG |
| KION GROUP AG |
| Krones AG |
| Yaskawa Electric Corporation |
| Schneider Packaging Equipment Company, Inc. |
| Daifuku Co., Ltd. |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
Japanese servo motor and precision gearing production in Nagoya and Hamamatsu concentrates upstream supply for motion control systems, anchoring margin pools in aftermarket service contracts and predictive maintenance platforms rather than pure hardware sales. Steel cost volatility and CE marking compliance investments are reshaping how vendors bundle software licensing with equipment procurement.
Pricing Analysis
Extended service contracts and predictive maintenance subscriptions now drive lifetime value beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates vision-integrated systems with AI path optimization from basic articulated configurations and entry-level cobot deployments. Price differentiation hinges on ISO 10218 safety certification tier and after-sales telemetry integration. Cost compression in mid-range articulated systems is intensifying because steel and rare-earth magnet inputs face commodity volatility. Mid-sized food and beverage co-manufacturers exhibit the highest price sensitivity, while pharmaceutical distributors prioritize validation documentation over unit cost.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended payment terms are becoming standard for system integrators serving capital-constrained mid-market buyers. Precision-machined arm components and harmonic drive gearboxes draw from Germany, Japan, and Taiwan, while servo motors and encoders rest on South Korean and Chinese production. Single-source vulnerability concentrates in high-torque servo drives from Fanuc and Yaskawa captive production. Distribution runs through authorized system integrator networks with regional service depots rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Path optimization programming expertise for irregular product geometries remains scarce outside Stuttgart and Munich automotive clusters, constraining deployment velocity for mid-volume manufacturers lacking internal robotics engineering capabilities.
For Market Incumbents: Build predictive maintenance platform moats by integrating motion control telemetry with AI-driven failure prediction algorithms. Consolidate position through captive servo drive production to insulate margins from commodity volatility. CE marking pre-loading for collaborative systems locks out non-compliant imports before EU AI Act validation requirements harden. For New Entrants and Emerging Players: Mid-market food and beverage co-manufacturers in France and Italy represent the most penetrable entry point, as labor scarcity intensifies and facility reconfiguration budgets remain constrained. Vision-guided cobot deployments without extensive safety caging address unmet demand among producers below automated line scale. Partner with established system integrators in Bavaria's packaging machinery corridor for channel access rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European industrial engineering groups that consolidated during the last automation investment wave. Five-to-ten year viability favors vendors with software-anchored recurring revenue streams over pure hardware fabricators. Monitor FDA validation timeline compression for pharmaceutical de-palletizing systems as an inflection indicator for premium pricing power in high-compliance segments.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Transforms FANUC and ABB from hardware vendors into recurring revenue service providers through telemetry monetization. |
| Collaborative Safety Certification Pre-loading | KUKA's CE-marked cobot designs eliminate protective caging requirements, accelerating deployment in existing packaging lines. |
| Vision System Integration Partnership | Embedded 3D cameras from Daifuku collapse quality control and palletizing into single stations for Dutch bottling facilities. |
| Local Service Network Establishment | Cobot vendors building Pune-Nashik service infrastructure capture PLI scheme incentives for Indian processed food automation. |
| AI Path Optimization Licensing | Software subscriptions for self-optimizing palletizing patterns address EU AI Act documentation requirements for algorithm validation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU machinery directive filings, ISO 10218 certification databases, and customs trade records for servo motor and precision component flows. Plant engineers at automotive tier-1 suppliers, aftermarket service heads at packaging machinery OEMs, and procurement leads at food and beverage co-manufacturers provided operational deployment data. Bottom-up equipment shipment analysis triangulates against top-down industrial automation capex tracking across the analysis window.
Forecast inputs include articulated versus cobot format adoption curves, vision system penetration rates by application vertical, and service contract attachment evolution. Segmentation models capture payload capacity tier, collaborative safety certification status, end-user facility type, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and greenfield automation investment intensity across food and beverage, pharmaceutical, and automotive demand verticals.
Practitioners should monitor steel and rare-earth magnet price volatility, EU AI Act algorithm validation protocol finalization, and FDA pharmaceutical traceability rule expansion for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Explosion Proof Crane Market