
 Middle East and Africa Automated Material Handling Market | 2026-2036
Middle East and Africa Automated Material Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automated Material Handling Market Insights
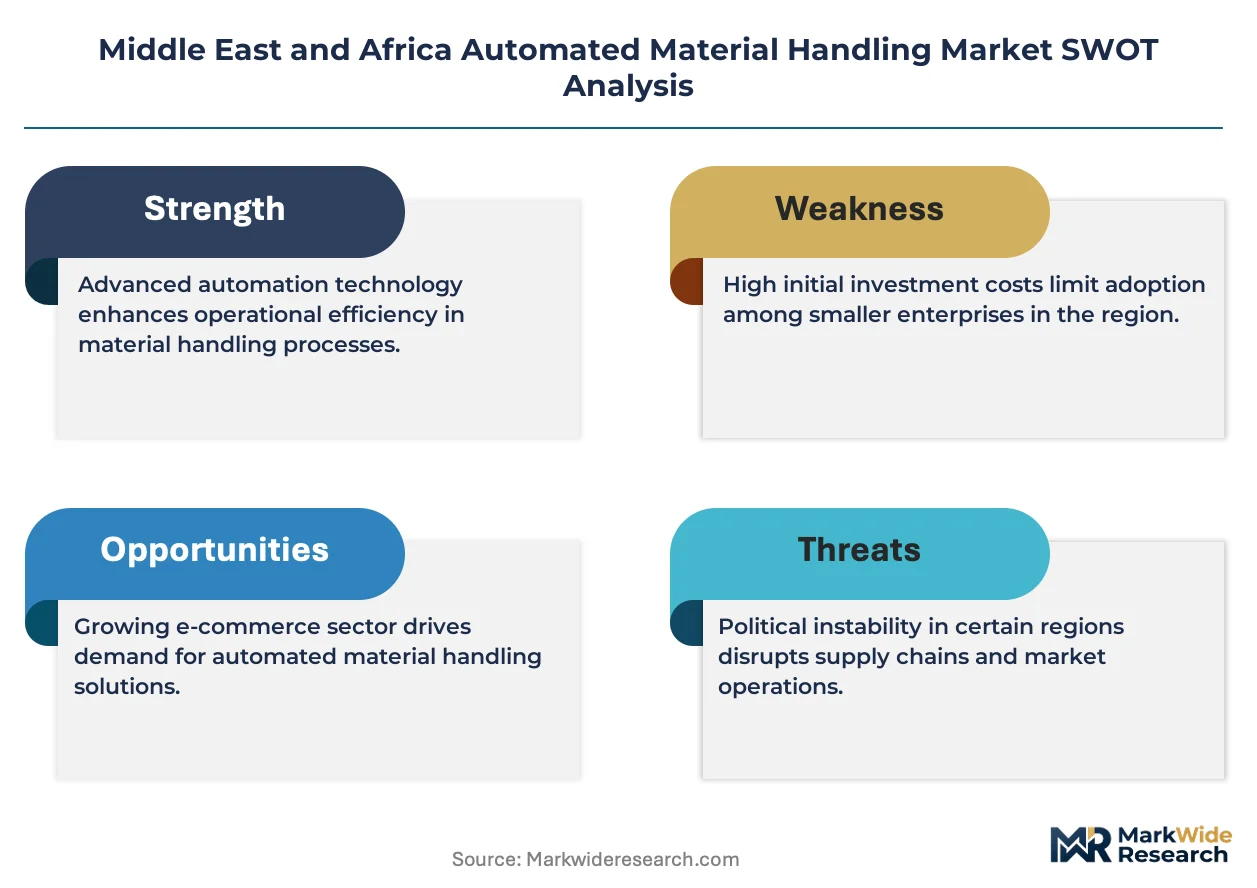
Asset-light leasing models for automated guided vehicles and conveyor systems is reconfiguring capital deployment across the Middle East and Africa, enabling mid-sized logistics operators to access enterprise-grade automation without full ownership burdens. Siemens AG leverages its regional service infrastructure to sustain long-term maintenance contracts across Gulf distribution hubs. Dematic Corporation anchors its competitive position through integrated software-hardware bundles tailored for ambient and cold-chain warehouses. Swisslog Middle East LLC differentiates via specialized pharmaceutical handling systems compliant with Gulf health authority traceability requirements.
Automated material handling encompasses electromechanical systems, software controls, and sensor networks that transport, sort, store, and retrieve goods within manufacturing plants, warehouses, and distribution centers, typically operating at throughput rates exceeding manual equivalents by an order of magnitude while reducing labor-dependent error rates. The primary commercial purpose centers on synchronizing inventory velocity with order fulfillment windows in multi-channel supply chains. Conveyors and automated guided vehicles currently occupy the largest installed base across the region, reflecting legacy infrastructure and gradual upgrade cycles. Artificial Intelligence and vision systems represent the fastest-expanding technology layer, as Gulf-based operators deploy predictive routing algorithms to mitigate peak-season congestion. Robotics applications in order fulfillment command premium pricing due to integration complexity and specialist technician scarcity.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) conformity schemes shape equipment certification timelines and import compliance costs for automation vendors entering Gulf markets. South Africa's National Regulator for Compulsory Specifications (NRCS) enforces electrical safety and electromagnetic compatibility standards that filter out uncertified Asian-origin components. Stakeholders must monitor evolving Gulf customs union harmonization timelines, as unified technical regulations would consolidate testing requirements but potentially extend approval durations during transitional implementation.
Market Dynamics
Asset-light leasing models for automated guided vehicles and conveyor systems are reconfiguring capital deployment across the Middle East and Africa, enabling mid-sized logistics operators to access enterprise-grade automation without full ownership burdens. This structural shift is compressing payback periods and expanding addressable demand beyond traditional large-facility adopters.
Growth Catalysts
- Saudi Arabia's National Industrial Development and Logistics Program:Warehouse modernization mandates are accelerating capital allocation toward automated sortation and retrieval systems in Riyadh and Jeddah distribution corridors.
- E-commerce fulfillment centers:Gulf Cooperation Council retail logistics operators are expanding adoption of high-throughput automated sortation systems to synchronize inventory velocity with same-day delivery windows.
- Vision-guided robotics:Artificial intelligence and camera-based routing algorithms are mitigating peak-season congestion in Dubai's Jebel Ali Free Zone anchor facilities.
Market Restraints
- Specialist technician scarcity:Robotics integration complexity commands premium pricing and extends deployment timelines due to limited regional certification programs for maintenance personnel.
- Import compliance costs:SASO technical regulations and ESMA conformity schemes create equipment certification bottlenecks for automation vendors entering Gulf markets.
- Legacy conveyor infrastructure:Gradual upgrade cycles in established warehousing operations delay full-stack automation transitions and fragment technology generations within single facilities.
Strategic Opportunities
- Pharmaceutical cold-chain automation:Swisslog Middle East LLC's specialized handling systems demonstrate unmet demand for Gulf health authority traceability-compliant infrastructure in ambient and temperature-controlled warehouses.
- South African NRCS electrical safety standards:Electromagnetic compatibility certification requirements filter uncertified Asian-origin components, creating protected market space for compliant European and domestic automation suppliers.
- Predictive routing algorithm convergence:Integration of AI with sensor networks enables dynamic warehouse floor reconfiguration during seasonal demand spikes in UAE and Saudi distribution hubs.
Industry Challenges
- Integration complexity with heterogeneous legacy systems:Facilities with mixed-vendor conveyor and retrieval infrastructure face protocol incompatibility and data silo fragmentation during automation upgrades.
- Gulf customs union harmonization uncertainty:Evolving unified technical regulations threaten to consolidate testing requirements but extend approval durations during transitional implementation, freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automated Material Handling Market |
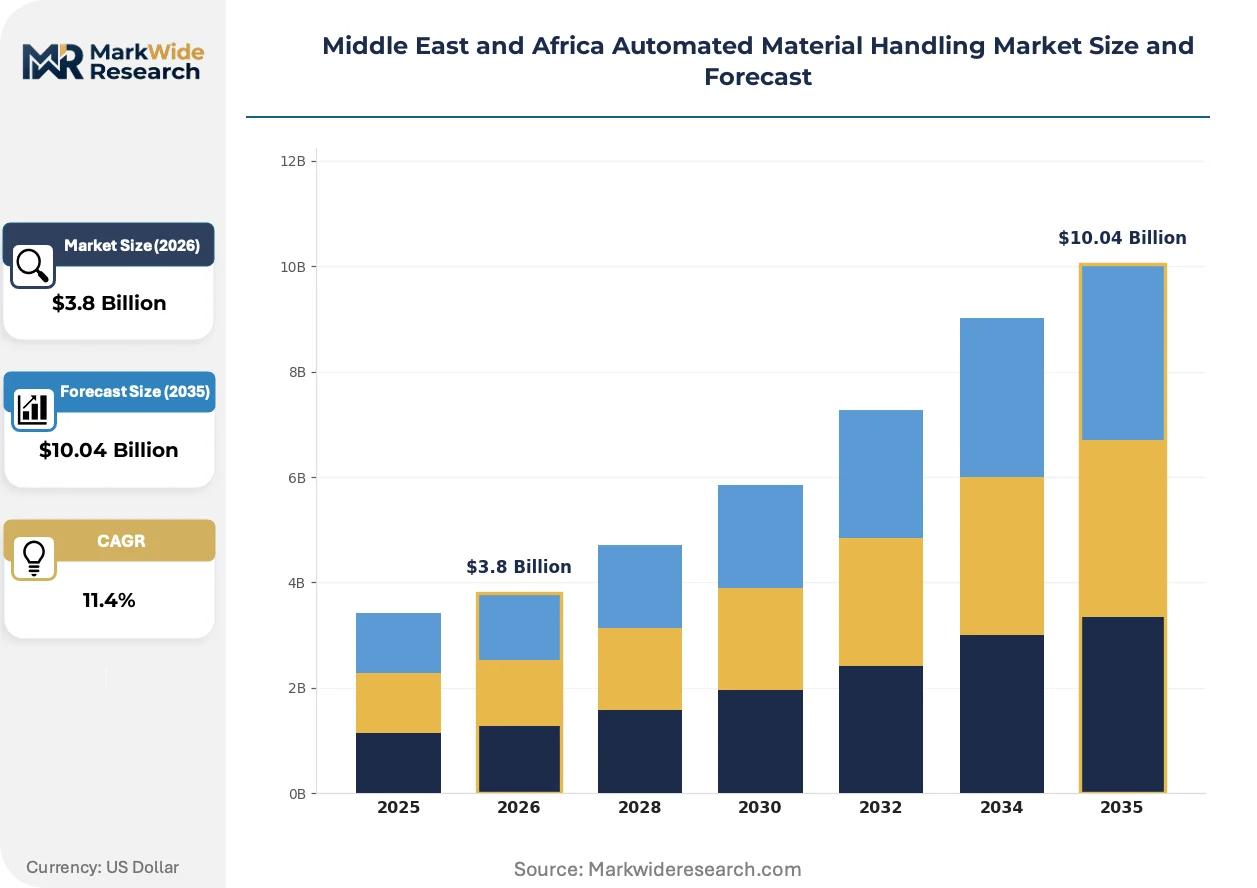
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Robotics, Conveyors, Integrated Systems End User: Retail, Manufacturing, Food & Beverage, Pharmaceuticals Technology: Vision Systems, Sensors, Software, Artificial Intelligence Application: Inventory Management, Order Fulfillment, Packaging, Transportation |
| Companies Covered | Siemens AG, KUKA AG, ABB Ltd, Rockwell Automation, Honeywell International Inc, Dematic Corporation, Swisslog Middle East LLC, Interroll Group, Famco, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automated Material Handling Market Trends and Innovations
Artificial intelligence and vision systems are actively reshaping competitive positioning in Middle East and Africa automated material handling, compressing the gap between sensing capability and real-time operational decision-making. This technological layer is displacing rule-based control architectures across Gulf distribution networks.
Machine learning-powered predictive maintenance platforms are digitizing equipment uptime assurance in Saudi and Emirati mega-warehouses. Third-party logistics operators are adopting these systems at accelerated pace to reduce unplanned downtime during Ramadan and year-end retail peaks. The technology is digitizing service contract structures from reactive break-fix models toward guaranteed availability subscriptions.
SASO and ESMA conformity schemes are tightening electromagnetic compatibility and electrical safety enforcement across Gulf Cooperation Council member states. Industrial consequence includes extended pre-market testing timelines and mandatory local representative appointments for foreign automation vendors. Pharmaceutical and food-grade cold-chain segments are most affected, responding by consolidating vendor relationships with regionally certified system integrators.
Leasing structures for automated guided vehicles and conveyor infrastructure are displacing outright purchase as the dominant procurement mode among mid-cap logistics operators. Equipment-as-a-service contracts bundle hardware, software, and maintenance into per-pallet-handled pricing. This shift is most visible in Dubai's Jebel Ali Free Zone, where third-party logistics providers prioritize operational flexibility over balance-sheet asset ownership.
Middle East and Africa Automated Material Handling Market Segmentation
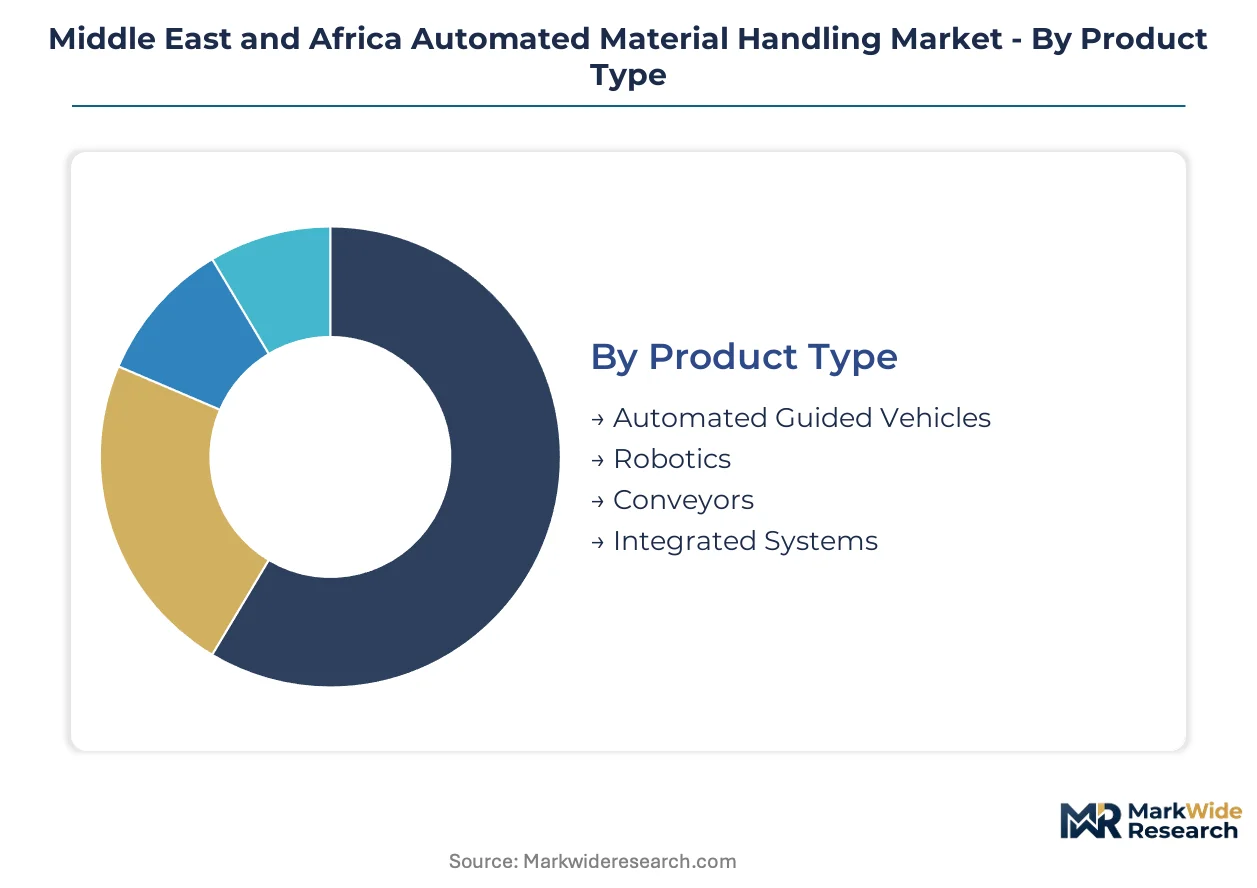
Segmentation in Middle East and Africa automated material handling reveals divergent capital recovery profiles. Conveyors and automated guided vehicles deliver predictable throughput with extended depreciation schedules. Robotics and AI layers compress payback through labor substitution but demand higher technical integration spend.
Product Type:
Cycle times vary sharply across equipment categories. Conveyors amortize over 10-15 year horizons with minimal software refresh requirements. Robotics platforms face 5-7 year obsolescence windows as vision and gripping technologies advance.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate warehouse floors via magnetic tape, laser guidance, or natural feature recognition. Saudi Arabia's Riyadh distribution corridor and UAE's Jebel Ali Free Zone anchor the largest regional deployments, driven by National Industrial Development and Logistics Program warehouse modernization mandates that prioritize flexible material transport over fixed infrastructure.
- Robotics:Articulated arms and autonomous mobile robots execute picking, palletizing, and depalletizing operations with sub-millimeter repeatability. Demand concentrates in Dubai's e-commerce fulfillment centers where same-day delivery windows force acceleration of order consolidation processes beyond manual throughput ceilings.
- Conveyors:Belt, roller, and chain-driven systems form the backbone of legacy warehouse infrastructure across Gulf Cooperation Council states.
- Integrated Systems:Software-orchestrated combinations of conveyors, sorters, and retrieval equipment deployed as unified platforms.
Conveyors dominate installed base across Middle East and Africa warehousing. Robotics is where expansion concentrates.
End User:
Capital deployment intensity tracks margin pressure and labor availability by sector. Pharmaceutical and food-grade operations justify premium automation spend through compliance and spoilage avoidance. Retail logistics prioritizes throughput velocity over precision handling.
- Retail:High-volume distribution centers serving omnichannel fulfillment networks with seasonal demand volatility. UAE-based third-party logistics operators in Dubai's free trade zones deploy automated sortation to synchronize inventory velocity with same-day delivery commitments mandated by Gulf e-commerce platforms.
- Pharmaceuticals:Temperature-controlled warehouses requiring traceability-compliant handling systems for serialised drug products. Swisslog Middle East LLC's specialized installations demonstrate unmet demand across Saudi Arabia and UAE for Gulf health authority compliant infrastructure in ambient and cold-chain facilities.
- Manufacturing:Assembly-line feed systems and work-in-progress buffering for automotive and electronics production.
- Food & Beverage:Hygienic conveyor designs and automated palletizing for perishable goods distribution.
Retail commands the largest share of new capital allocation. Pharmaceuticals is climbing the fastest.
Technology:
Technology layers stack from physical sensing through decision algorithms. Vision and AI components command recurring software subscription revenue. Sensors and base software layer into hardware margins with limited aftermarket value capture.
- Artificial Intelligence:Machine learning models predicting demand patterns, optimizing pick paths, and enabling dynamic warehouse floor reconfiguration during seasonal spikes. Saudi and Emirati mega-warehouses adopt predictive maintenance platforms to reduce unplanned downtime during Ramadan and year-end retail peaks.
- Vision Systems:Camera arrays and depth sensors enabling robotic piece-picking and barcode reading in variable lighting conditions. Integration complexity commands premium pricing and extends deployment timelines due to limited regional certification programs for maintenance personnel.
- Sensors:Proximity, load, and position detectors providing real-time equipment state feedback to control systems.
- Software:Warehouse management system modules and equipment control platforms orchestrating multi-vendor automation.
Software and sensors underpin legacy infrastructure. Artificial Intelligence is gaining share fastest.
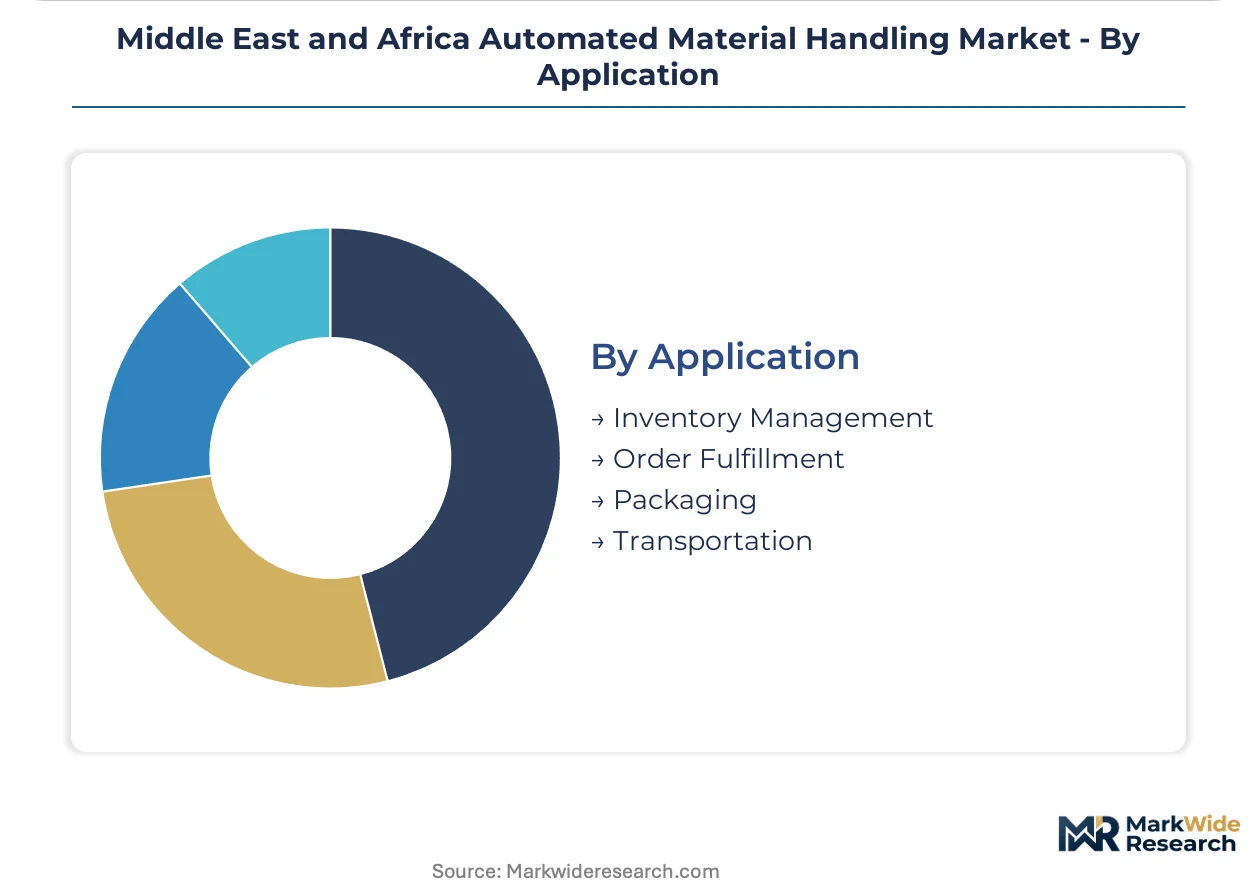
Application:
Application focus determines system architecture and integration depth. Order fulfillment demands real-time responsiveness with complex exception handling. Transportation and packaging applications tolerate higher latency with simpler control logic.
- Order Fulfillment:Wave-based picking, sortation, and consolidation processes synchronizing with customer delivery windows. Dubai's Jebel Ali Free Zone third-party logistics providers prioritize operational flexibility through equipment-as-a-service contracts bundling hardware, software, and maintenance into per-pallet-handled pricing.
- Inventory Management:Automated storage and retrieval systems, cycle counting robots, and real-time location tracking. SASO technical regulations and ESMA conformity schemes create equipment certification bottlenecks for automation vendors entering Gulf markets, particularly affecting pharmaceutical and food-grade cold-chain segments.
- Packaging:Automated case forming, filling, sealing, and labeling at distribution center outputs.
- Transportation:Yard management systems and automated truck loading bridges connecting warehouse to outbound logistics.
Inventory management anchors established facility investments. Order fulfillment is where technology refresh concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's National Industrial Development and Logistics Program is channeling state capital toward warehouse modernization mandates. This policy framework is accelerating automated material handling deployment across Gulf distribution corridors while reshaping procurement patterns among mid-sized logistics operators.
Saudi Arabia
Riyadh and Jeddah distribution corridors anchor the largest automated guided vehicle deployments in the Gulf. SASO technical regulations govern electromagnetic compatibility certification for imported automation components. The Riyadh-based mega-warehouse cluster is absorbing high-throughput sortation systems to synchronize with e-commerce fulfillment windows.
United Arab Emirates
Dubai's Jebel Ali Free Zone concentrates regional third-party logistics automation investment. ESMA conformity schemes create equipment certification timelines that filter uncertified Asian-origin components. The free zone's equipment-as-a-service contracting models are displacing outright purchase among mid-cap operators seeking operational flexibility.
South Africa
Johannesburg-Pretoria industrial corridor drives demand for conveyor modernization in legacy warehousing infrastructure. The National Regulator for Compulsory Specifications enforces electrical safety standards that protect compliant European and domestic automation suppliers. Cape Town's pharmaceutical distribution hubs are adopting traceability-compliant handling systems for serialized drug products.
Egypt
Suez Canal Economic Zone logistics operators are expanding cold-chain warehouse automation to capture transshipment volume growth. The country's national standards body regulates import compliance for electromechanical equipment entering Alexandria and Port Said ports. Cairo's retail distribution networks are piloting vision-guided robotics for order consolidation beyond manual throughput ceilings.
Middle East and Africa Automated Material Handling Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system providers capable of bundling hardware, software, and long-term maintenance contracts. European industrial automation conglomerates and specialized regional integrators form a tiered competitive structure. Three archetypes dominate: full-stack platform vendors, component specialists, and regionally certified system integrators. Dominant competitive moves include strategic partnerships with local service infrastructure and portfolio diversification into predictive maintenance subscriptions.
Within the full-stack platform tier, Siemens AG and ABB Ltd represent European industrial conglomerates leveraging established regional service networks. Dematic Corporation and Swisslog Middle East LLC exemplify specialists occupying positions in integrated software-hardware bundles and pharmaceutical cold-chain automation respectively. KUKA AG anchors the robotics-focused segment among German-origin automation suppliers.
| Leading Market Players |
|---|
| Siemens AG |
| KUKA AG |
| ABB Ltd |
| Rockwell Automation |
| Honeywell International Inc |
| Dematic Corporation |
| Swisslog Middle East LLC |
| Interroll Group |
| Famco |
| Others |
Pricing and Supply Chain Analysis
SASO and ESMA certification bottlenecks determine both pricing tier spreads and supply chain configuration, forcing Gulf-bound vendors to absorb extended pre-market testing timelines and mandatory local representative costs that stratify equipment economics across compliance-grade tiers.
Pricing Analysis
Certification level (SASO-grade versus ESMA-grade versus uncertified Asian-origin) creates the primary spread between premium European system integrators and price-competitive component traders. Equipment-as-a-service contracts bundling hardware, software, and maintenance into per-pallet-handled pricing are displacing outright purchase among mid-cap logistics operators in Dubai's Jebel Ali Free Zone. Cost compression in the uncertified tier is intensifying because South African NRCS electrical safety standards filter out non-compliant imports, protecting compliant suppliers. Retail logistics operators show highest price sensitivity due to thin omnichannel margins, while pharmaceutical cold-chain buyers prioritize traceability compliance over acquisition cost.
Supply Chain Analysis
Steel frame fabrication and servo motor assembly draw from Germany, China, and South Korea as the dominant upstream feedstock sources for regional automation deployment. Controller boards, lithium battery packs, and precision bearings constitute critical component dependencies with limited regional substitution. Single-source vulnerability concentrates in vision system sensors and AI accelerator chips sourced from Taiwan and USA. Distribution runs through Jebel Ali Free Zone bonded warehousing for Gulf markets, with direct port-of-entry clearance for South African and Egyptian destinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and guaranteed-availability service contracts are expanding faster than hardware sales, reframing this market as a service-attach opportunity where recurring revenue multiples exceed equipment margin profiles.
For Market Incumbents: Harden regional service infrastructure against specialist technician scarcity by embedding certified maintenance teams within Saudi Riyadh and UAE Jebel Ali distribution corridors. Deepen backward integration into software control layers to capture predictive routing algorithm revenue that third-party logistics operators increasingly demand. Vertical integration of AI maintenance platforms defends margin position against pure-play software entrants. For New Entrants and Emerging Players: Build out pharmaceutical cold-chain automation capabilities targeting SASO and ESMA traceability compliance gaps that Swisslog Middle East LLC currently dominates. Egyptian Suez Canal Economic Zone logistics operators present the most penetrable geography given transshipment volume growth and limited incumbent saturation. Lead with equipment-as-a-service contracting to bypass capital-constrained buyer procurement committees. For Investors and Strategic Acquirers: The market sits at a leasing-model transition phase that favors service-attach revenue aggregators over pure hardware manufacturers. Regional system integrators with certified maintenance networks and recurring software subscription bases offer superior long-term viability within a five-to-ten year holding window. Monitor Gulf customs union harmonization implementation timelines as the critical inflection signal for procurement decision velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Certification Investment | SASO and ESMA compliance unlocks Gulf Cooperation Council procurement channels for automation vendors. |
| Predictive Maintenance Platform Launch | AI-powered uptime assurance digitizes service contracts toward guaranteed availability subscriptions. |
| Equipment-as-a-Service Rollout | Per-pallet-handled pricing expands addressable demand beyond balance-sheet-constrained mid-cap operators. |
| Pharmaceutical Cold-Chain Specialization | Gulf health authority traceability requirements create protected margin pools in temperature-controlled warehousing. |
| Local Service Infrastructure Buildout | Certified technician networks in Riyadh and Jebel Ali compress deployment timelines and capture maintenance annuity. |
Research Methodology
Operator-level perspectives from warehouse operations directors, third-party logistics procurement heads, automation system integrators, and SASO certification consultants anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary validation from customs trade databases, SEC filings of listed automation suppliers, Gulf industrial development program disclosures, and NRCS electrical safety standard documentation. Bottom-up equipment shipment tracking and top-down macroeconomic absorption modeling converged on segment-level demand estimates.
Scenario-bracketing around Saudi National Industrial Development and Logistics Program implementation pace, Gulf customs union harmonization timelines, and e-commerce fulfillment center buildout velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use sector, technology layer, and application focus, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from equipment replacement cycle analysis and capital expenditure pipeline assessment, incorporating AI adoption curves and leasing penetration assumptions specific to Middle East and Africa logistics markets.
Sensitivities concentrate around Gulf customs union regulatory consolidation timing, specialist technician training program expansion rates, and Asian-origin component certification success rates. Cross-checking against disclosed capital expenditure plans of Dubai-based third-party logistics operators and Saudi sovereign wealth fund industrial deployment schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market