
 Fabric Ducting Market | 2026-2036
Fabric Ducting Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Ducting Market Analysis
Asset-light leasing models for HVAC infrastructure is narrowing the capital barrier for mid-sized contractors to deploy fabric ducting at scale. DuctSox Corporation leverages its North American manufacturing footprint to sustain rapid fulfillment timelines. PRIHODA anchors its competitive position through specialized R&D in porous textile engineering. KE Fibertec differentiates via deep vertical control over fabric weaving and finished duct production.
Fabric ducting comprises engineered textile conduits manufactured from woven or non-woven synthetic substrates, typically 50–600 mm in diameter, designed to distribute conditioned air through calibrated permeability or directional nozzle arrays. The primary industrial purpose centers on uniform air dispersion with minimal turbulence, thermal loss, and condensation risk in climate-controlled environments. Ventilation ducts lead volume deployment across food processing and pharmaceutical cleanrooms where particulate control mandates washable, antimicrobial surfaces. Suspended installation methods dominate commercial and industrial sites due to flexible ceiling integration and reduced structural load. Polyester materials capture the widest application scope given tensile strength, moisture resistance, and compatibility with antimicrobial coatings.
EPA ventilation efficiency standards and OSHA indoor air quality guidelines shape product certification requirements and installation compliance costs across US commercial and industrial deployments. EU F-Gas Regulation and REACH chemical restrictions drive material substitutions and sealant formulations in European manufacturing. Stakeholders must monitor evolving HVAC energy codes and textile flammability classifications to anticipate specification changes and qualification timelines.
Market Dynamics
EU F-Gas Regulation enforcement is compressing leakage tolerance thresholds and accelerating replacement cycles in commercial HVAC infrastructure across member states. Food processors and pharmaceutical cleanrooms face immediate specification upgrades to maintain operating licenses.
Growth Catalysts
- Hygienic air mandates:Food processing facilities in Germany's industrial corridor are mandating washable antimicrobial duct surfaces to satisfy EFSA hygiene protocols and reduce contamination vectors in high-care zones.
- REACH material compliance:ECHA restrictions on halogenated flame retardants are redirecting specification engineers toward polyester-knit substrates with inherent fire resistance and lower chemical load.
- Low-leakage textile engineering:Calibrated permeability weaving techniques are displacing rigid metal ductwork in climate-controlled warehouses where thermal uniformity directly affects product integrity.
Market Restraints
- Petrochemical input volatility:Polyester staple fiber prices fluctuate with crude oil derivatives, compressing margin buffers for fabric weavers without captive polymer sourcing.
- Specialized installation labor scarcity:Certified textile duct technicians concentrate in Northern European training centers, creating deployment bottlenecks for rapid-turnaround projects in peripheral markets.
- Rigid spiral metal substitution:Galvanized steel ductwork retains specification preference in high-pressure industrial ventilation above 2,000 Pa operating thresholds.
Strategic Opportunities
- Cleanroom pharmaceutical expansion:Antimicrobial-coated fabric systems are penetrating aseptic fill-finish suites in Ireland and Switzerland where washdown protocols favor textile over stainless steel.
- Asset-light leasing models:HVAC infrastructure-as-a-service contracts are eliminating upfront capital barriers for mid-sized contractors in France and the Netherlands.
- Dual carbon alignment:Lightweight textile logistics reduce transport emissions and installation energy, qualifying projects for EU Green Deal renovation subsidies in public building retrofits.
Industry Challenges
- Flammability certification timelines:EN 13501-1 fire classification testing extends product qualification cycles by four to six months, delaying specification approvals for novel weave densities.
- Legacy building integration friction:Suspended textile systems require structural load assessments and ceiling grid modifications in 1970s-era industrial facilities, complicating retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Ducting Market |
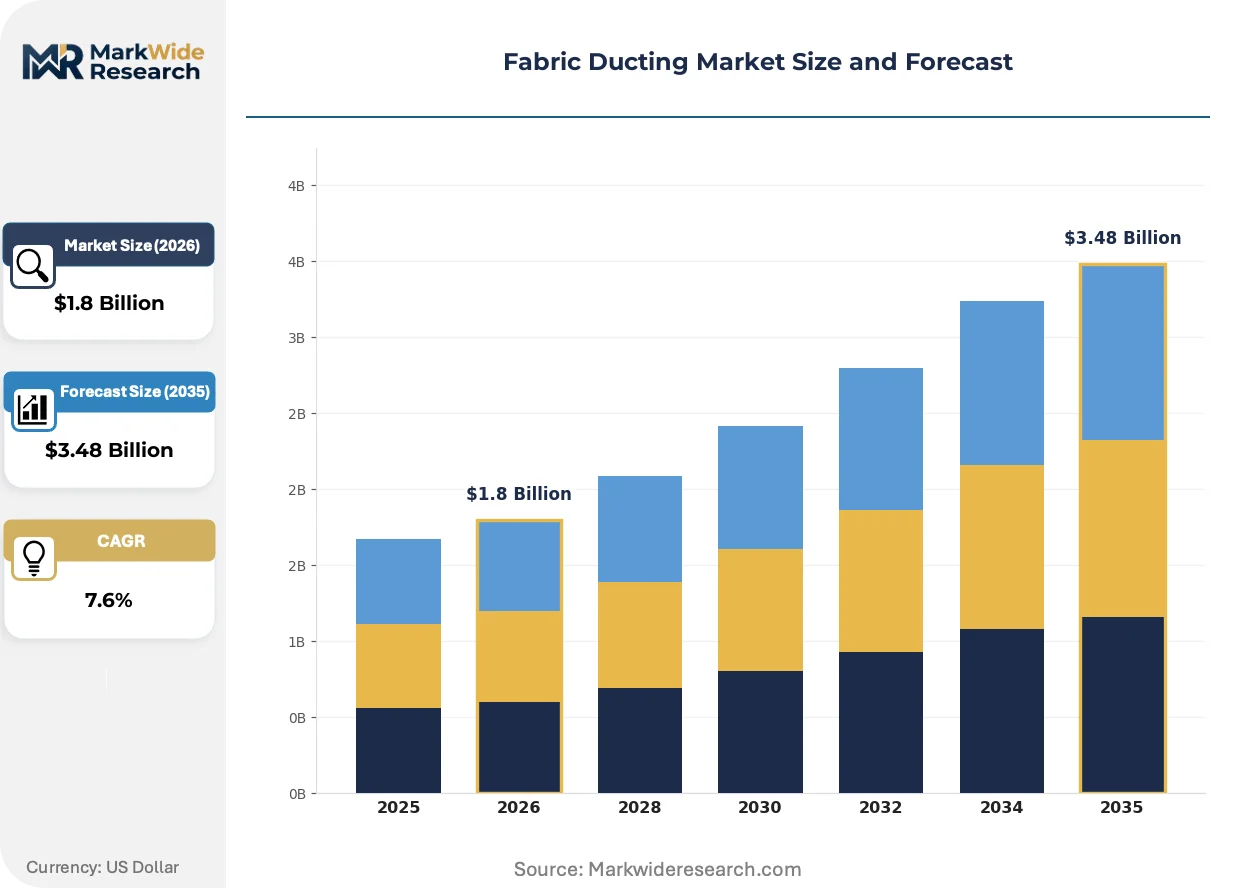
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Air Ducts, Ventilation Ducts, Heating Ducts, Humidification Ducts Installation Method: Suspended, Wall-Mounted, Integrated, Free Standing Application: Industrial, Commercial, Residential, Agricultural Material: Polyester, Nylon, Cotton, Fiberglass |
| Companies Covered | DuctSox Corporation, AIRMAX International, PRIHODA, Hurlstones Northern Ltd, Clever Engineering (Kent) Ltd, KE Fibertec, FabricAir, Air Distribution Concepts, Durkeesox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Ducting Market Emerging Trajectories
Textile engineering and regulatory chemistry are converging to redefine performance benchmarks for air distribution infrastructure. Material scientists and HVAC engineers are co-developing substrates that satisfy simultaneously for thermal efficiency, antimicrobial durability, and fire safety.
Smart textile manufacturing is hybridizing conductive thread integration with standard polyester weaves to enable real-time pressure and temperature monitoring within duct lumens. Pharmaceutical cleanroom operators in Denmark and Belgium are piloting these sensor-embedded systems to eliminate manual airflow verification protocols. The technology is hybridizing quality assurance workflows and compressing commissioning timelines from weeks to days.
EU F-Gas Regulation Phase-Down measures are banning refrigerants with global warming potential above 750, forcing specification engineers to prioritize leakage-minimizing distribution architectures. Fabric ducting with heat-sealed seams and calibrated permeability is capturing specification share in supermarket refrigeration and cold storage applications. German facility managers are leading adoption, driven by BImSchV federal emission control mandates and operational cost exposure to refrigerant replacement.
Specification authority is migrating from mechanical contractors to sustainability officers and ESG compliance teams within large facility portfolios. These buyers prioritize lifecycle carbon accounting and circular material recovery over first-cost procurement metrics. Dutch and Swedish industrial real estate developers are embedding textile duct specifications into BREEAM and LEED pre-certification templates, locking in preferred supplier relationships before construction tendering begins.
Fabric Ducting Market Segmentation
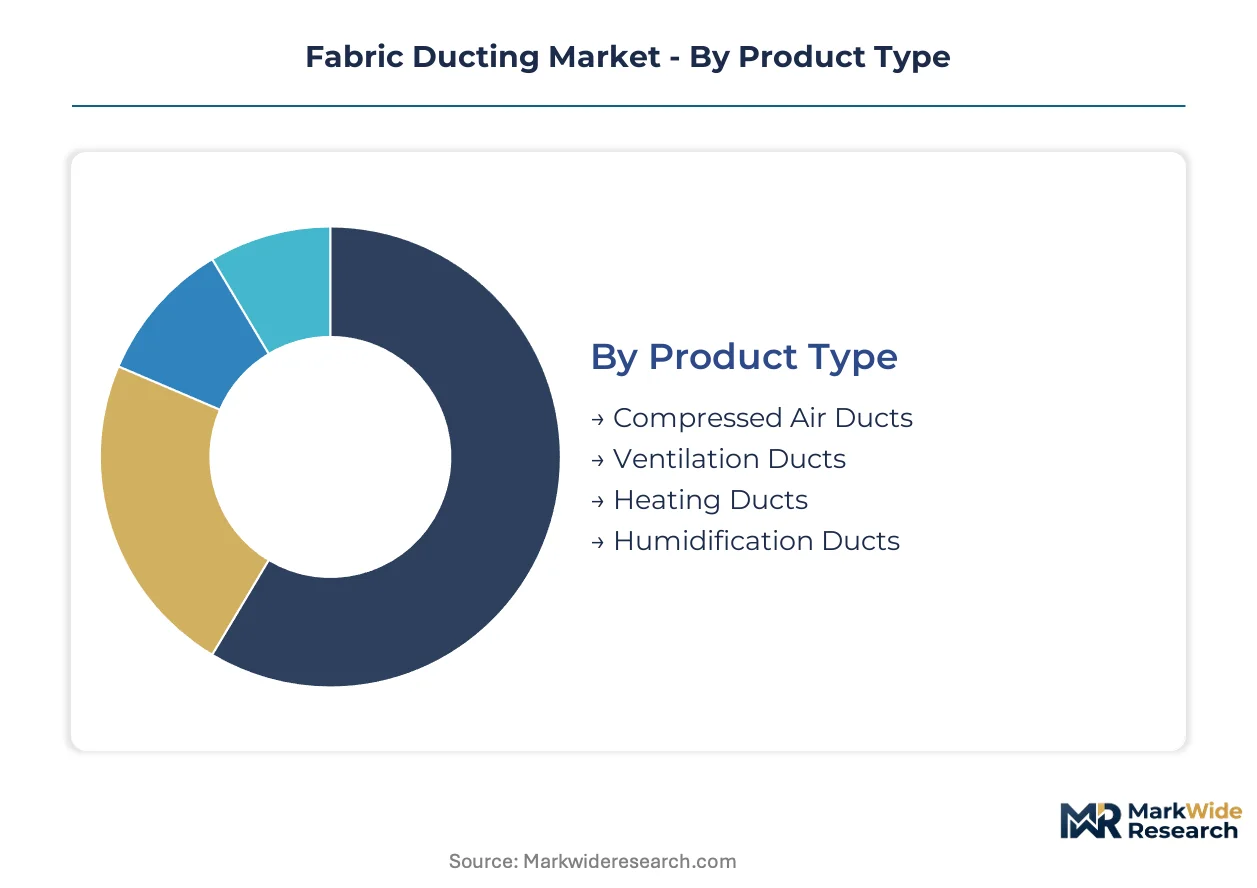
Fabric ducting performance varies sharply across substrate chemistry, mounting topology, and end-use environment. Specification engineers weight permeability calibration, antimicrobial durability, and structural load differently depending on whether the deployment serves a food processing cleanroom or a climate-controlled warehouse.
Product Type:
Mature ventilation configurations dominate specification volumes while emerging humidification systems capture the steepest adoption curves in controlled agriculture.
- Ventilation Ducts:Engineered polyester conduits with calibrated permeability or directional nozzle arrays distribute conditioned air through food processing and pharmaceutical cleanrooms. German facility managers specify washable antimicrobial surfaces to satisfy EFSA hygiene protocols and reduce contamination vectors in high-care zones.
- Heating Ducts:Thermal-resistant woven substrates maintain air temperature integrity across long distribution runs in climate-controlled warehouses. Demand concentrates in Germany's industrial corridor where thermal uniformity directly affects product integrity in cold storage applications.
- Compressed Air Ducts:High-pressure woven textiles withstand operating thresholds up to 2,000 Pa in industrial pneumatic systems.
- Humidification Ducts:Porous knit structures enable controlled moisture dispersion in greenhouse and vertical farming installations.
Ventilation ducts retain volume leadership; humidification ducts hold the steepest expansion curve.
Installation Method:
Cost tier differentiation separates premium suspended systems from economy free-standing alternatives, with mounting complexity driving both labor pricing and structural engineering requirements.
- Suspended:Ceiling-integrated textile systems reduce structural load and enable flexible spatial configuration in commercial and industrial sites. Dutch and Swedish industrial real estate developers embed suspended specifications into BREEAM and LEED pre-certification templates.
- Wall-Mounted:Perimeter-fixed conduits serve retrofit applications where ceiling grid modifications prove economically prohibitive in 1970s-era industrial facilities.
- Integrated:Factory-built HVAC modules incorporate fabric distribution during off-site construction for rapid on-site commissioning.
- Free Standing:Self-supporting textile columns deploy in temporary agricultural structures and event spaces requiring rapid installation cycles.
Suspended installations command premium pricing; integrated systems are gaining share fastest in modular construction.
Application:
Customer type stratification separates industrial buyers seeking durability certifications from commercial purchasers prioritizing aesthetic integration and rapid deployment.
- Industrial:Heavy-duty woven substrates withstand continuous operation in manufacturing environments with aggressive washdown protocols. Irish and Swiss pharmaceutical cleanrooms specify antimicrobial-coated systems for aseptic fill-finish suites.
- Commercial:Architecturally finished textiles integrate with exposed ceiling designs in retail and office environments. France and the Netherlands see HVAC infrastructure-as-a-service contracts eliminating upfront capital barriers for mid-sized contractors.
- Agricultural:Moisture-resistant polyester serves greenhouse humidity control and livestock ventilation with minimal maintenance requirements.
- Residential:Lightweight knit ducts penetrate high-end home automation systems for zoned climate control.
Industrial applications retain volume leadership; commercial deployments are climbing the fastest on leasing model adoption.
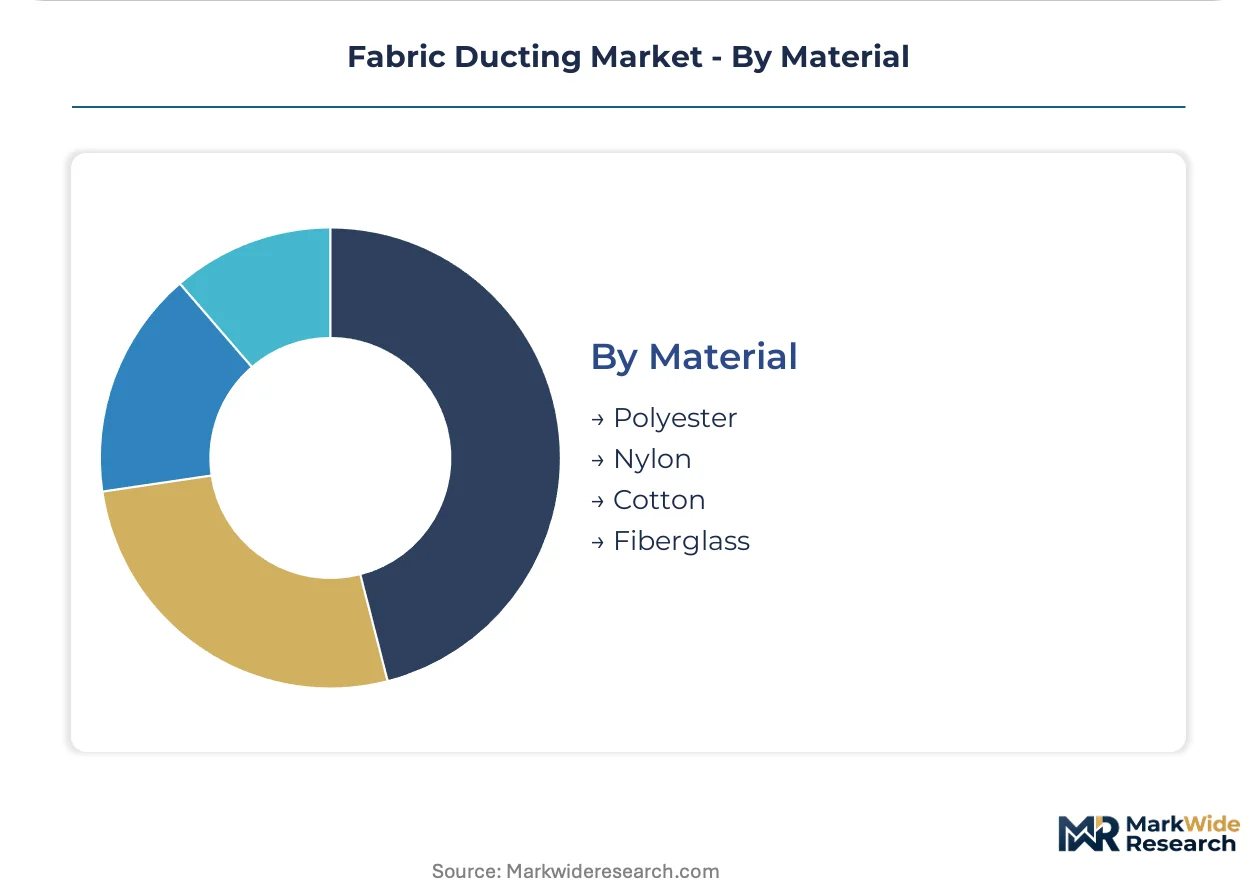
Material:
Supply concentration in Northern European weaving centers shapes availability and qualification timelines for specialized substrates.
- Polyester:Tensile strength, moisture resistance, and antimicrobial coating compatibility position this synthetic staple as the default specification across food processing and pharmaceutical cleanrooms. ECHA restrictions on halogenated flame retardants redirect engineers toward polyester-knit substrates with inherent fire resistance.
- Nylon:Abrasion-resistant polymers serve high-velocity industrial ventilation with extended service intervals in abrasive environments.
- Cotton:Natural fiber alternatives penetrate heritage building renovations and organic-certified agricultural facilities with strict synthetic material prohibitions.
- Fiberglass:Rigid composite structures supplement flexible textiles in high-temperature exhaust applications exceeding standard polymer thermal limits.
Polyester retains volume leadership; nylon holds the steepest expansion trajectory in heavy-duty industrial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fabric ducting track closely with HVAC equipment trade flows. Germany and the United States maintain structural trade surpluses in engineered textile systems. China and Southeast Asian manufacturing centers supply raw polyester substrates while importing finished duct assemblies for domestic commercial construction.
Germany
Food processing cleanrooms and pharmaceutical fill-finish suites drive specification volumes in the industrial corridor between Cologne and Frankfurt. BImSchV federal emission control mandates accelerate replacement of legacy metal ductwork with low-leakage textile systems. BASF Ludwigshafen and Bayer Leverkusen chemical complexes anchor demand for corrosion-resistant air distribution in aggressive process environments.
United States
EPA ventilation efficiency standards and OSHA indoor air quality guidelines shape certification requirements for commercial deployments. Cold storage and supermarket refrigeration applications expand as states adopt ASHRAE energy codes. Chicago and Dallas-Fort Worth metropolitan areas concentrate distribution infrastructure serving the Midwest and Southwest construction markets.
Netherlands
HVAC infrastructure-as-a-service contracts eliminate upfront capital barriers for mid-sized contractors in Rotterdam and Amsterdam industrial zones. BREEAM pre-certification templates embed textile duct specifications into new commercial developments. The Port of Rotterdam logistics cluster generates demand for climate-controlled warehousing with uniform thermal distribution.
Switzerland
Swissmedic pharmaceutical manufacturing standards mandate washable antimicrobial surfaces in aseptic production environments. Basel and Zurich pharmaceutical clusters specify textile systems for rapid washdown protocols. The country's dual carbon goals qualify lightweight textile logistics for federal building renovation subsidies.
Denmark
Smart textile manufacturing with conductive thread integration pilots real-time pressure monitoring in pharmaceutical cleanrooms near Copenhagen. Danish facility managers compress commissioning timelines through sensor-embedded quality assurance workflows. The Øresund Region cross-border industrial zone shares specification standards with southern Sweden.
Fabric Ducting Market Vendor Landscape
On the supply side, the industry is moderately concentrated with distinct tiering between integrated textile engineers and regional installation specialists. Three strategic archetypes dominate: North American manufacturers with captive distribution networks, European specialists in porous substrate R&D, and Asian fabricators competing on polyester conversion costs. Competitive moves center on geographic expansion through distribution partnerships and backward integration into polymer sourcing to buffer margin volatility.
Among European specialists, PRIHODA exemplifies the R&D-intensive archetype through its positioning in porous textile engineering. KE Fibertec occupies a comparable position with demonstrated vertical control over fabric weaving operations. DuctSox Corporation anchors the North American manufacturing tier, representing scale-driven fulfillment capabilities. These three entities collectively illustrate the geographic and functional segmentation governing competitive positioning.
| Leading Market Players |
|---|
| DuctSox Corporation |
| AIRMAX International |
| PRIHODA |
| Hurlstones Northern Ltd |
| Clever Engineering (Kent) Ltd |
| KE Fibertec |
| FabricAir |
| Air Distribution Concepts |
| Durkeesox |
| Others |
Supply Flow & Price Mechanics
Petrochemical input volatility determines both tiered pricing spreads across polyester substrate grades and the geographic shape of weaving capacity concentration in Northern European supply clusters. Buyers face widening cost differentials between captive-polymer producers and merchant-fiber converters as crude oil derivative fluctuations compress margin buffers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale driving price differentiation. Pricing pressure stems from polyester staple fiber cost compression, forcing merchant weavers to absorb margin erosion while integrated producers maintain buffer. Food processing facilities demonstrate lowest price sensitivity due to EFSA hygiene protocol mandates, whereas agricultural buyers exhibit highest sensitivity to first-cost procurement metrics.
Supply Chain Analysis
Contract manufacturing concentrates among specialized textile converters in Germany, the Czech Republic, and Poland, with regional weaving centers holding calibrated permeability engineering capabilities. Raw material dependencies center on purified terephthalic acid, ethylene glycol, and antimicrobial coating chemistries. Single-source vulnerability runs through Northern European training centers for certified textile duct technicians. Distribution runs through HVAC contractor networks and direct specification relationships with facility engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabric ducting sits in early-cycle expansion as EU F-Gas Regulation Phase-Down measures force specification migration from rigid metal systems toward low-leakage textile architectures.
For Market Incumbents: Insulate margin position through backward integration into polymer sourcing and captive weaving capacity in Germany's industrial corridor. PRIHODA and KE Fibertec demonstrate defensive positioning through specialized R&D in porous textile engineering. Threats concentrate in rigid spiral metal substitution above 2,000 Pa thresholds and emerging smart textile sensor integration by specialized competitors. For New Entrants and Emerging Players: Peripheral European markets present the most penetrable white-space, particularly France and the Netherlands where HVAC infrastructure-as-a-service contracts eliminate upfront capital barriers for mid-sized contractors. Agricultural humidification applications in controlled-environment agriculture offer secondary entry points with lower certification hurdles. A specification-engineer direct sales model bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: EU F-Gas Regulation Phase-Down measures reshape the acquisition landscape toward targets with EN 13501-1 fire classification pre-approval and heat-sealed seam engineering capabilities. Long-term viability favors vertically integrated textile engineers over pure-play installation specialists. Monitor refrigerant leakage penalty enforcement intensity as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Sourcing | Captive PTA/EG supply buffers margin volatility from crude oil derivative fluctuations. |
| Smart Textile Sensor Integration | Conductive thread embedding enables real-time pressure monitoring for pharmaceutical cleanroom operators. |
| EN 13501-1 Fire Classification Pre-Approval | Pre-qualified substrates compress four-to-six-month qualification cycles delaying specification approvals. |
| HVAC Infrastructure-as-a-Service Contracts | Asset-light leasing eliminates upfront capital barriers for mid-sized contractors in France and Netherlands. |
| Calibrated Permeability Weaving Capacity Expansion | Specialized R&D investment anchors competitive position in low-leakage textile engineering for cold storage applications. |
Methodological Framework
The analysis maps ventilation ducts, heating ducts, compressed air ducts, and humidification ducts, each validated through facility engineering directors, HVAC contractor procurement leads, textile weaving plant managers, and pharmaceutical cleanroom operators. Primary fieldwork combined with secondary validation from customs/trade data, SEC 10-K filings of publicly traded HVAC equipment manufacturers, ECHA REACH substance restriction updates, and EU F-Gas Regulation implementation guidance. Bottom-up volume triangulation across substrate chemistry, mounting topology, and end-use environment converged with top-down market sizing.
Assumptions held fixed include EU F-Gas Regulation enforcement trajectory and EFSA hygiene protocol maintenance across the projection horizon. Variables included polyester staple fiber price volatility bands and certified technician training pipeline expansion rates. Segmentation dimensions modeled encompass product type, installation method, application category, and material chemistry. CAGRs derived from weighted average of historical replacement cycle data and regulatory-driven acceleration factors, with pharmaceutical cleanroom penetration rates and supermarket refrigeration retrofit intensity serving as industry-specific forecast inputs.
Practitioners should monitor refrigerant leakage penalty enforcement schedules and EN 13501-1 testing backlog durations for early signals of specification timeline compression. Forecasts reflect these assumptions with acknowledged sensitivity to petrochemical input cost spikes and specialized installation labor scarcity in peripheral markets. Cross-checking against ECHA substance restriction amendment timelines and BImSchV federal emission control mandate updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Global Large-Scale Natural Refrigerant Heat Pump Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
US Heating Equipment Market