
 Woodworking Machines Market | 2026-2036
Woodworking Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking Machines Market Outlook
German equipment builders is pivoting toward modular CNC platforms that reduce reconfiguration downtime for batch-one production. HOMAG Group leverages its integrated software-hardware stack to anchor premium positioning in automated panel processing lines. SCM Group competes through deep specialization in edgebanding and sanding systems for mid-scale Italian furniture suppliers. Biesse Group sustains technology leadership in digital controls for five-axis machining centers serving aerospace-grade timber applications.
Woodworking machines encompass motorized equipment designed to cut, shape, join, or finish wood and wood-composite materials, typically operating at spindle speeds between 3,000 and 24,000 RPM depending on tooling configuration. Their primary industrial purpose centers on transforming raw lumber into dimensioned components, finished panels, or assembled furniture with repeatable precision. CNC routers represent the fastest-expanding product category as furniture manufacturers replace manual stations with servo-driven tooling paths that cut cycle times and scrap rates. Digital controls technology commands the highest margin pool within the technology dimension because proprietary software ecosystems lock in aftermarket service revenue and operator training dependencies. High-capacity units dominate capital expenditure flows among sawmills processing hardwood volumes exceeding 50,000 board feet daily.
OSHA machine guarding standards in the United States mandate interlocked safety enclosures on industrial saws and routers, directly shaping product design requirements for equipment sold into North American facilities. CE marking under the EU Machinery Directive and evolving F-Gas Regulation constraints on refrigerants used in dust collection systems create dual compliance burdens for European manufacturers exporting globally. Stakeholders must monitor how China's GB standards for woodworking machinery safety converge with or diverge from ISO 19085 series specifications, as alignment decisions will determine factory certification costs for multinational producers serving both domestic Chinese and export markets.
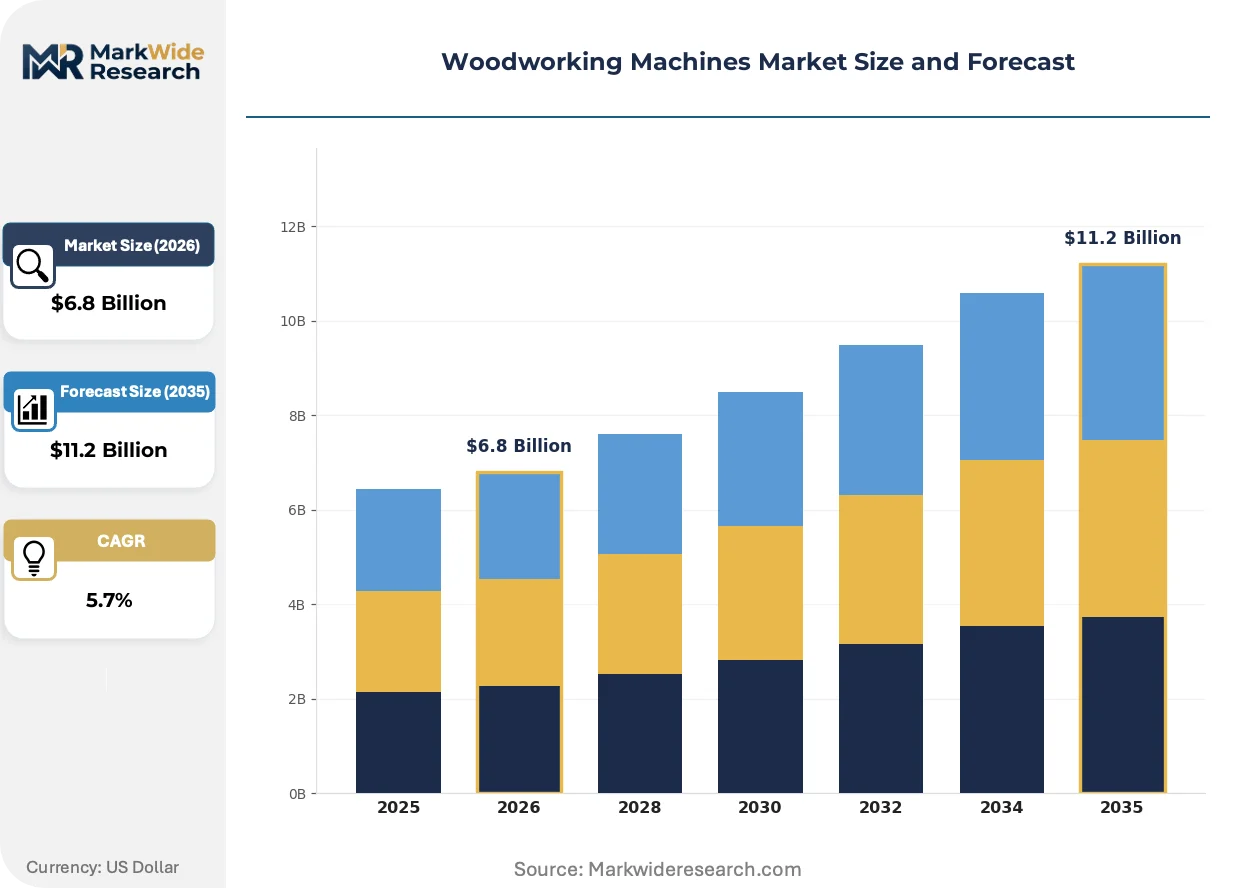
Market Dynamics
Furniture manufacturers in Germany, China, and the United States are consolidating capital deployment around automated CNC platforms that compress batch-one reconfiguration cycles. This equipment substitution wave is restructuring competitive advantage toward software-integrated hardware stacks and away from standalone mechanical systems.
Growth Catalysts
- CE marking under EU Machinery Directive:European producers are accelerating replacement cycles to secure digitally certified equipment that satisfies conformity assessment requirements for automated panel processing lines.
- Batch-one production economics:Modular CNC platforms that minimize changeover downtime are capturing capital allocation from Italian and German furniture suppliers serving customized residential orders.
- OSHA machine guarding standards:Interlocked safety enclosure mandates for industrial saws and routers are compelling North American facilities to upgrade legacy equipment toward compliant servo-driven systems.
Market Restraints
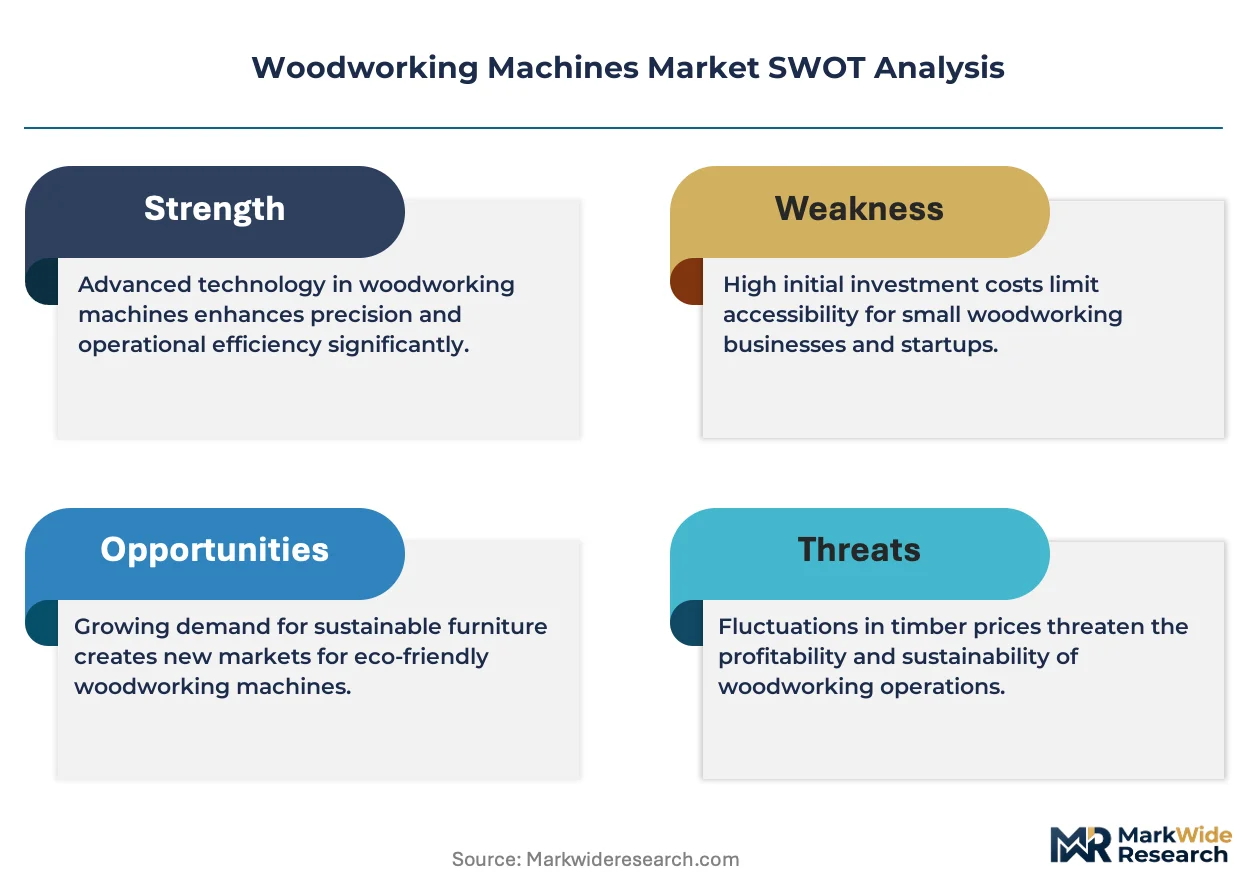
- High-grade steel and servo motor input volatility:Precision machining centers require specialized alloy components whose spot pricing fluctuates with energy-intensive smelter output in China and Germany.
- Control software vendor concentration:Proprietary digital ecosystems for five-axis timber machining concentrate among a handful of European developers, locking buyers into captive aftermarket service dependencies.
- F-Gas Regulation constraints:EU restrictions on refrigerants used in dust collection systems impose dual compliance burdens on manufacturers exporting beyond European markets.
Strategic Opportunities
- China GB standards convergence:Alignment between Chinese national safety specifications and ISO 19085 series would reduce factory certification costs for multinational producers serving domestic and export markets simultaneously.
- Aerospace-grade timber applications:Five-axis machining centers configured for high-performance composite materials represent an emerging demand vertical beyond traditional furniture and construction segments.
- Edgebanding-as-a-service models:Italian mid-scale suppliers are experimenting with unbundled equipment access that transfers capital risk from buyers to specialized system integrators.
Industry Challenges
- CNC programming talent scarcity:Servo-driven tooling path optimization requires operators trained in G-code and CAM software, creating recruitment bottlenecks for sawmills processing high-volume hardwood flows.
- Legacy mechanical integration friction:Digital control retrofits on existing spindle systems often demand custom mechanical adapters that extend commissioning timelines and inflate project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking Machines Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Saws, CNC Routers, Edgebanders, Planers Technology: Laser Cutting, Hydraulic Systems, Pneumatic Control, Digital Controls End User: Furniture Manufacturers, Cabinet Makers, Sawmills, DIY Enthusiasts Capacity: Low Capacity, Medium Capacity, High Capacity, Customizable Units |
| Companies Covered | HOMAG Group, SCM Group, Biesse Group, Felder Group, Holz-Her, Michael Weinig AG, IMA Schelling Group, Timesavers, Nanxing Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking Machines Market Strategic Shifts
Servo-driven tooling paths and integrated software-hardware stacks are compressing the traditional tradeoff between customization flexibility and production throughput. Equipment architecture is pivoting toward modular platforms that accommodate rapid reconfiguration without sacrificing precision.
Collaborative robotic loading systems paired with CNC routers are automating material handling in batch-one furniture production. German and Italian manufacturers are deploying these configurations to reduce operator exposure to repetitive lifting while maintaining spindle utilization rates. The technology is automating the final frontier of manual intervention in otherwise digitally controlled workflows.
F-Gas Regulation amendments under the EU Green Deal are tightening refrigerant specifications for industrial dust collection and climate control systems. Equipment builders must redesign thermal management subsystems to maintain CE conformity without relying on phased-out compounds. Panel processing lines sold into European facilities face the most immediate engineering redesign cycles.
Buyers are consolidating vendor relationships around integrated software-hardware providers that bundle operator training, predictive maintenance, and remote diagnostics into multi-year service agreements. Traditional equipment-only distributors are losing share to OEM-direct channels in Germany and the United States. Aerospace timber suppliers and high-end residential furniture builders exhibit the strongest preference for bundled capability contracts over transactional procurement.
Woodworking Machines Market Segmentation
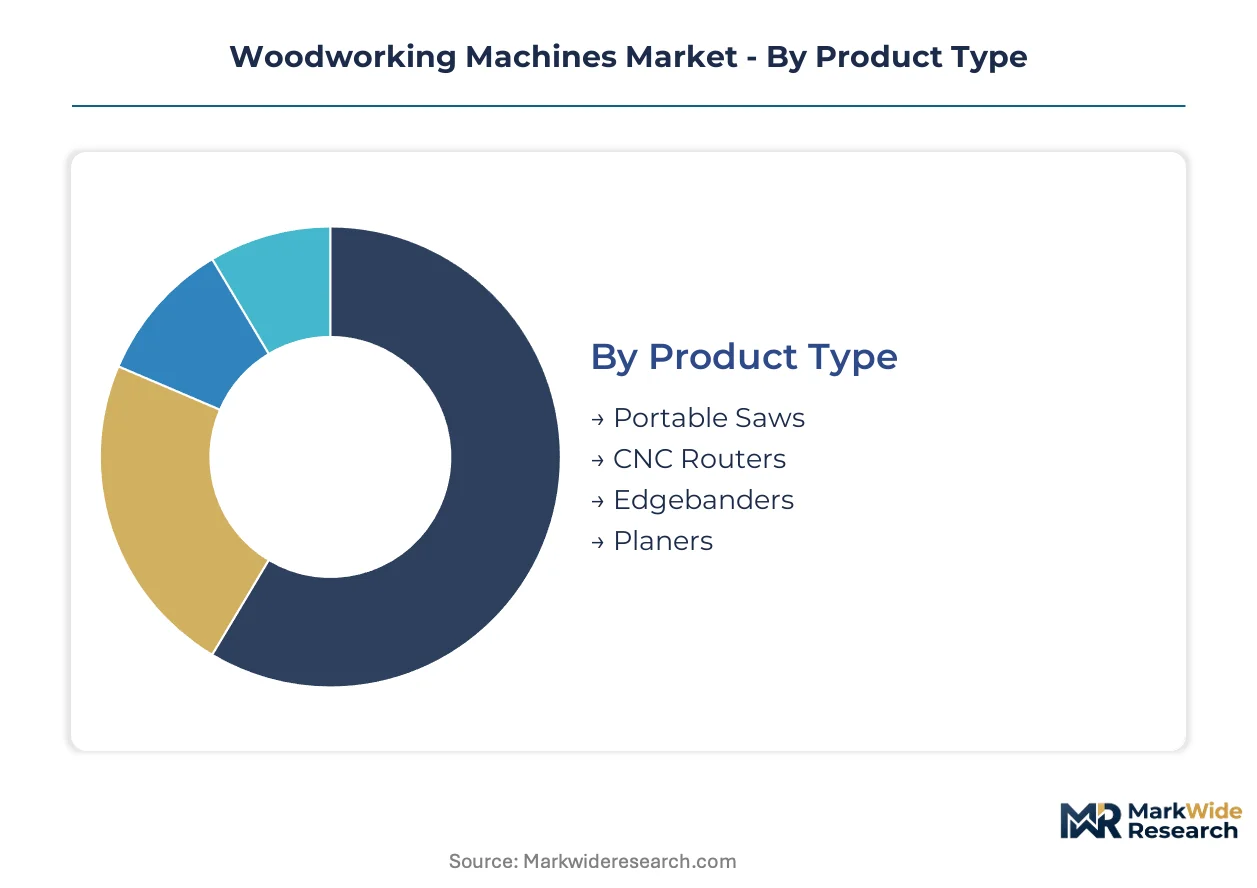
Woodworking machine buyers sort options across four intersecting dimensions that determine capital allocation priorities. Product type and technology choices lock in operational capabilities for years, while capacity and end-user alignment dictate margin profiles and aftermarket service dependencies.
Product Type:
CNC routers command premium pricing and capture the steepest expansion trajectory, while portable saws anchor volume flows across price-sensitive procurement channels.
- CNC Routers:Servo-driven multi-axis platforms execute complex tooling paths from digital CAD files with repeatability below 0.1mm tolerance. German and Italian furniture manufacturers are consolidating procurement around these systems to compress batch-one reconfiguration cycles for customized residential orders.
- Edgebanders:Automated feeding systems apply thermoplastic or wood veneer edgebanding to panel substrates at speeds exceeding 20 meters per minute. Mid-scale Italian suppliers are driving demand through unbundled equipment access models that transfer capital risk to specialized integrators.
- Portable Saws:Compact benchtop and jobsite units serve mobile contractors and small-scale cabinet shops requiring field flexibility.
- Planers:Thickness reduction systems dimension rough lumber to uniform specifications for flooring and millwork producers.
Today's leader: CNC routers. Tomorrow's challenger: Edgebanders.
Technology:
Digital controls extract the highest margin premiums through proprietary software ecosystems, whereas pneumatic and hydraulic systems compete on upfront capital efficiency for mechanical-heavy operations.
- Digital Controls:Integrated software-hardware stacks bundle operator training, predictive maintenance, and remote diagnostics into multi-year service agreements. OEM-direct channels in Germany and the United States are displacing traditional equipment-only distributors as buyers consolidate vendor relationships around bundled capability contracts.
- Laser Cutting:Non-contact beam systems cut intricate patterns in thin wood composites and veneers without tool wear or chip generation. Aerospace-grade timber suppliers in Bavaria and Washington State are adopting these configurations for high-performance composite machining.
- Hydraulic Systems:High-force actuation platforms power heavy-duty resaws and timber framing equipment in high-volume sawmill environments.
- Pneumatic Control:Compressed air actuation delivers cost-effective clamping and feed mechanisms for mid-market panel processing lines.
Digital controls dominate service revenue capture. Laser cutting gains fastest among specialized verticals.
End User:
Furniture manufacturers generate the largest equipment procurement volumes, though sawmills concentrate spending in the highest-capacity tier where single-machine investments exceed smaller shop annual capital budgets.
- Furniture Manufacturers:Residential and commercial segment producers are expanding automated production lines across Germany, China, and the United States. CE marking requirements under EU machinery directives are pushing European facilities toward digitally certified equipment that satisfies conformity assessment for automated panel processing.
- Sawmills:Hardwood processors exceeding 50,000 board feet daily dominate capital expenditure flows in the high-capacity equipment tier. OSHA machine guarding standards mandate interlocked safety enclosures that compel North American facilities to upgrade legacy equipment toward compliant servo-driven systems.
- Cabinet Makers:Custom kitchen and bath specialists prioritize compact CNC configurations for batch-one production of dimensional components.
- DIY Enthusiasts:Hobbyist and small contractor segments drive portable saw and benchtop planer volumes through retail and e-commerce channels.
Furniture manufacturers anchor equipment demand. Sawmills concentrate premium-tier procurement.
Capacity:
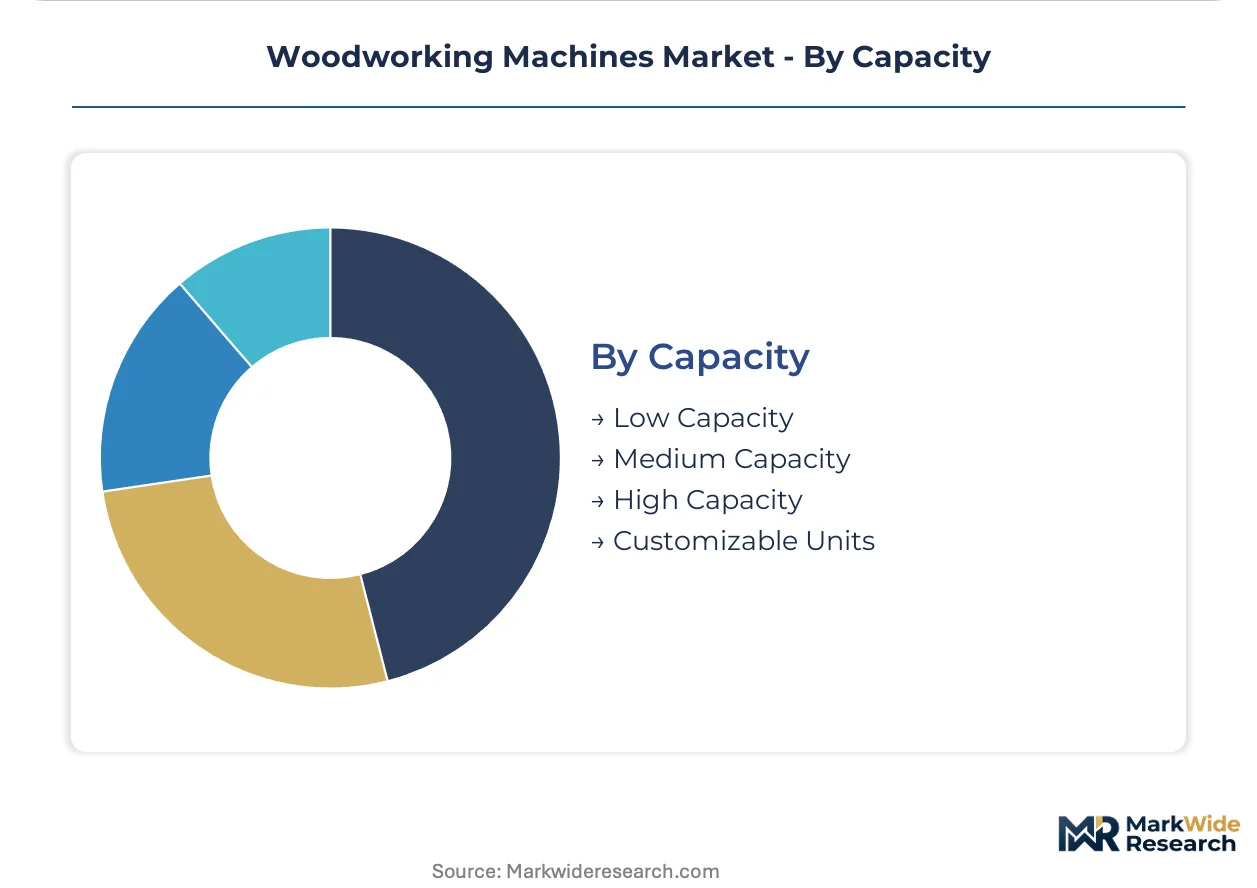
High-capacity units concentrate investment value in integrated production lines, while customizable configurations capture margin from buyers seeking operational flexibility without full automation premiums.
- High Capacity:Industrial-scale systems process continuous material flows exceeding 100 cubic meters per shift with automated loading and defect detection. Large-scale manufacturing clusters in Germany, China, and the United States dominate capital investment cycles for this tier.
- Customizable Units:Modular platforms accommodate rapid reconfiguration between product specifications without sacrificing precision. Italian mid-scale suppliers serving customized residential orders are allocating capital toward these systems to minimize changeover downtime.
- Medium Capacity:Semi-automated configurations serve regional furniture suppliers and commercial millwork operations with moderate throughput requirements.
- Low Capacity:Entry-level machines address cost-constrained cabinet shops and emerging market producers with limited capital access.
High capacity commands absolute investment dollars. Customizable configurations expand most quickly among flexibility-seeking buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting capital flows as manufacturers seek jurisdictions where compliance costs align with automation premiums. CE marking burdens in Europe contrast with OSHA-mandated upgrade cycles in North America, while China's evolving GB standards create certification uncertainty for exporters.
Germany
Batch-one furniture production drives demand for modular CNC platforms with sub-0.1mm repeatability. CE marking under the EU Machinery Directive compels producers toward digitally certified automated panel processing lines. The Black Forest manufacturing cluster around Schopfheim concentrates edgebanding system integrators serving mid-scale Italian suppliers.
United States
Hardwood sawmills processing 50,000+ board feet daily dominate high-capacity equipment procurement. OSHA machine guarding standards mandate interlocked safety enclosures that force legacy equipment upgrades toward servo-driven systems. The Pacific Northwest timber corridor spanning Oregon and Washington anchors aerospace-grade timber machining demand for five-axis centers.
China
Large-scale furniture manufacturing clusters in the Yangtze River Delta expand automated production lines for residential and commercial segments. GB standards for woodworking machinery safety are converging with ISO 19085 specifications, reducing factory certification costs for multinational producers. Dongguan and Foshan in the Pearl River Delta concentrate CNC router assembly operations serving domestic and export markets.
Italy
Mid-scale furniture suppliers prioritize customizable units minimizing changeover downtime for customized residential orders. EU F-Gas Regulation constraints on dust collection refrigerants impose engineering redesign cycles on panel processing lines. The Brianza furniture district north of Milan anchors edgebanding-as-a-service experimentation transferring capital risk to system integrators.
Japan
Precision timber component manufacturers seek digital controls bundling predictive maintenance and remote diagnostics. METI industrial standards emphasize operator training dependencies that lock buyers into proprietary software ecosystems. The Chubu region around Nagoya concentrates high-performance composite machining for specialized architectural applications.
Woodworking Machines Market Competitive Environment
German producers anchor one tier; Italian specialists hold differentiation in edgebanding and sanding configurations. The vendor structure concentrates around integrated software-hardware stacks that capture aftermarket service revenue through operator training lock-in. Three archetypes dominate: modular CNC platform builders, edgebanding system specialists, and digital controls developers. Competitive moves center on M&A to secure proprietary software ecosystems and capacity expansion in high-capacity sawmill equipment.
Among Germany-based fabricators, HOMAG Group GmbH and Michael Weinig AG exemplify the integrated-stack archetype, while SCM Group S.p.A. represents Italian specialization in mid-market configurations. These three occupy positions where proprietary digital ecosystems create captive aftermarket dependencies, with geography-encoded names signaling distinct regulatory compliance orientations toward CE marking and OSHA mandates respectively.
| Leading Market Players |
|---|
| HOMAG Group |
| SCM Group |
| Biesse Group |
| Felder Group |
| Holz-Her |
| Michael Weinig AG |
| IMA Schelling Group |
| Timesavers |
| Nanxing Machinery |
| Others |
Value Chain & Pricing Dynamics
Modular CNC platform adoption simultaneously compresses production economics and concentrates supply power among integrated software-hardware stack providers. CE marking compliance costs under the EU Machinery Directive and OSHA-mandated safety retrofits in North America create divergent cost baselines that equipment builders exploit through geography-specific pricing.
Pricing Analysis
Distributor margins in traditional equipment-only channels face compression as OEM-direct sales to German and United States furniture manufacturers capture premium service bundling. Three-tier pricing structure across premium, standard, and economy levels separates digitally certified automated panel processing lines from mechanical-heavy pneumatic systems and entry-level portable equipment. Pricing pressure stems from servo motor and high-grade steel input volatility tied to energy-intensive smelter output in China and Germany. DIY enthusiasts and small cabinet shops exhibit highest price sensitivity; aerospace-grade timber suppliers demonstrate least sensitivity due to performance-critical specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German, Chinese, and United States furniture manufacturing clusters, displacing traditional distributor networks. Component supply concentrates in Germany for precision machining centers, China for CNC router assembly operations, and Italy for edgebanding system specialization. Critical inputs include specialized alloy steel for spindle housings, servo motors from Japanese and German electromechanical suppliers, and proprietary control software from European developers. Single-source vulnerability in digital control ecosystems creates captive aftermarket dependencies. Distribution runs through bundled capability contracts spanning multi-year service agreements rather than transactional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between CE marking compliance burdens in Europe and OSHA-mandated upgrade cycles in North America, with cost differentials widest in safety-certified servo-driven equipment tiers.
For Market Incumbents: To counter proprietary software ecosystem concentration among European developers, German and Italian equipment builders should deepen backward integration into control system development and expand capacity in high-capacity sawmill equipment serving North American hardwood processors. CE marking investment and OSHA compliance certification anchor defensive positioning against emerging Asian competitors. For New Entrants and Emerging Players: System integrators offering edgebanding-as-a-service models present the most penetrable channel partner type for capital-risk transfer into Italian mid-scale furniture supply chains. White-space targets include customizable CNC configurations for batch-one residential orders and aftermarket service contracts for legacy mechanical system retrofits. Unbundled equipment access models bypass upfront capital barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone mechanical equipment distributors losing share to OEM-direct channels. Long-term viability favors integrated software-hardware stacks with captive operator training revenue over transactional equipment vendors. Acquisition target archetype: modular CNC platform builders with established aerospace timber certifications. Watch for convergence signals between China's GB standards and ISO 19085 specifications as inflection indicator for multinational certification cost reductions.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Software Ecosystem Acquisition | Control software vendor concentration in five-axis timber machining locks buyers into captive aftermarket service dependencies. |
| CE Marking Compliance Investment | EU Machinery Directive conformity assessment requirements accelerate replacement cycles toward digitally certified automated panel processing lines. |
| Modular CNC Platform Expansion | Batch-one production economics favor rapid reconfiguration capabilities that minimize changeover downtime for customized residential orders. |
| Backward Integration into Servo Motors | High-grade steel and servo motor input volatility from Chinese and German smelters threatens margin stability in precision machining centers. |
| Aerospace-Grade Timber Certification | Five-axis machining centers configured for high-performance composite materials unlock emerging demand beyond traditional furniture segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with plant engineers, OEM procurement teams, aftermarket service heads, and furniture manufacturing operations directors with secondary validation through customs and trade data, SEC filings from publicly listed equipment builders, ISO 19085 specification documents, and EU Machinery Directive regulatory filings. Bottom-up equipment shipment tracking and top-down capital expenditure analysis from manufacturing clusters in Germany, China, and the United States were triangulated against production capacity disclosures.
Segment-weighting approaches modeled product type differentiation between CNC routers and edgebanders, technology tiers separating digital controls from pneumatic and hydraulic systems, capacity classifications from high-volume sawmill configurations to customizable batch-one platforms, and end-user segmentation across furniture manufacturers, hardwood processors, and cabinet makers. CAGRs were derived from regression analysis of historical capital deployment patterns and forward projection of regulatory compliance upgrade cycles. Industry-specific inputs included CE marking adoption rates, OSHA machine guarding standard enforcement timelines, and convergence indicators between Chinese GB standards and ISO specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation amendments affecting dust collection system refrigerants, servo motor supply disruptions from energy-intensive smelter operations, and CNC programming talent scarcity constraining operator deployment. Forecasts reflect assumptions about regulatory alignment trajectories and input cost stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
India Lathe Machines Market