
 PU Casting Machine Market | 2026-2036
PU Casting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
PU Casting Machine Market Insights
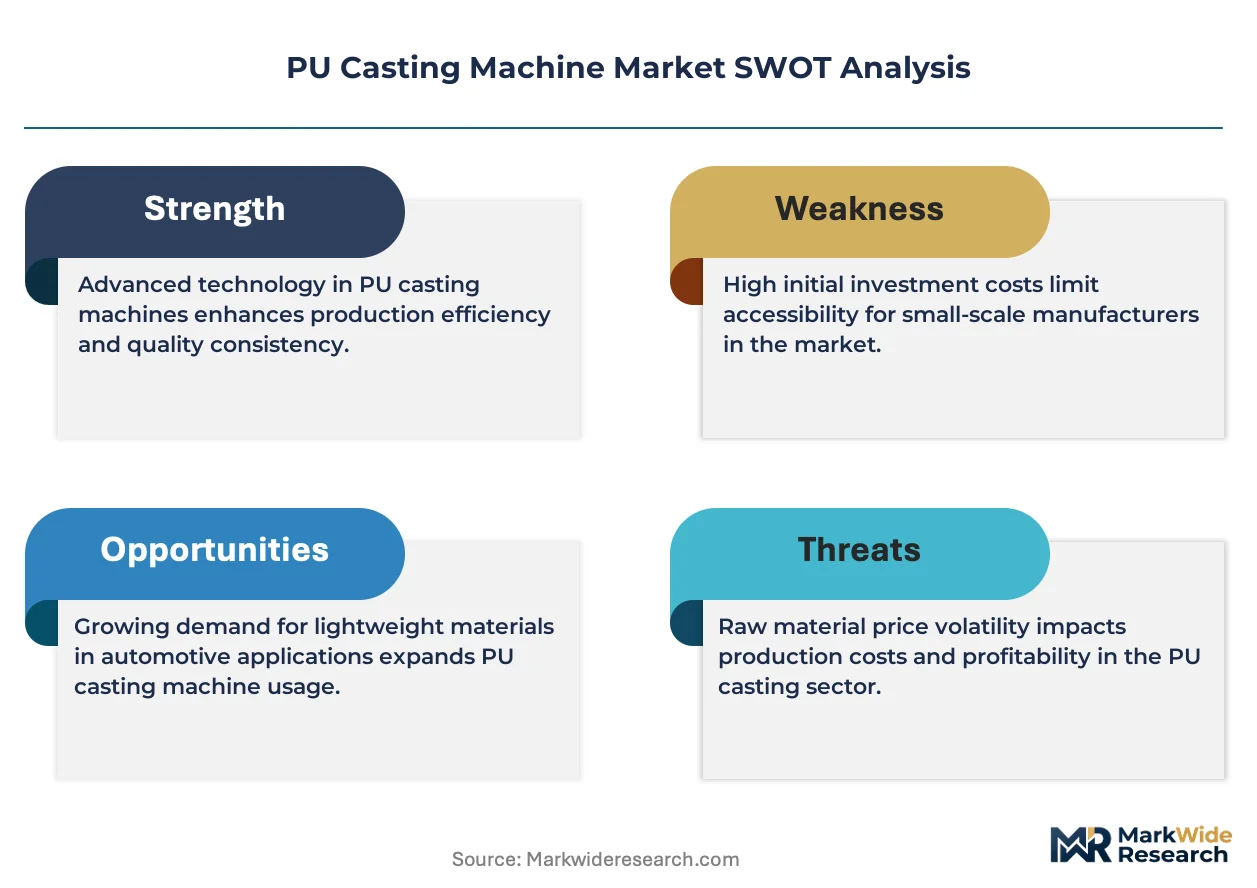
CE marking under the EU Machinery Directive 2006/42/EC is reorganizing competitive access across the PU casting machine landscape, forcing non-European suppliers to redesign control systems and safety interlocks for European market entry. Hennecke GmbH leverages its integrated dosing and mixing technology portfolio to sustain premium positioning in high-precision automotive applications. KraussMaffei Group anchors its presence through backward integration into polymer processing software and downstream mold engineering capabilities. Cannon Group differentiates via specialized high-pressure metering systems for complex multi-component polyurethane formulations.
PU casting machines are industrial processing systems that meter, mix, and dispense liquid polyurethane components—polyols and isocyanates—into molds under controlled temperature, pressure, and mixing ratios, typically achieving shot weights from grams to hundreds of kilograms with reaction times under sixty seconds. These systems serve primarily to manufacture elastomeric and rigid foam components for load-bearing, cushioning, and insulating applications across transportation and industrial sectors. Horizontal machines dominate volume deployments in high-throughput automotive seating operations where conveyor-integrated workflows maximize cycle efficiency. Robotic machines represent the fastest-expanding category as integrators deploy six-axis dispensing arms for complex medical device housings and aerospace interior panels requiring precision path control. Vacuum casting technology commands the strongest margin pool in electronics encapsulation and optical-grade component production where porosity elimination justifies premium system pricing.
The EPA regulates volatile organic compound emissions from polyurethane processing facilities under 40 CFR Part 63 Subpart HHH, while OSHA enforces permissible exposure limits for methylene diphenyl diisocyanate at 0.005 ppm as an eight-hour time-weighted average, directly constraining machine ventilation and operator enclosure designs. In Europe, ECHA administers REACH restrictions on aromatic amine catalysts and blowing agents, compelling equipment suppliers to validate compatibility with emerging aliphatic formulations and hydrofluoroolefin alternatives. Stakeholders must monitor evolving chemical authorization lists and carbon border adjustment mechanisms to anticipate which machine configurations and process chemistries will retain market access across major manufacturing jurisdictions.
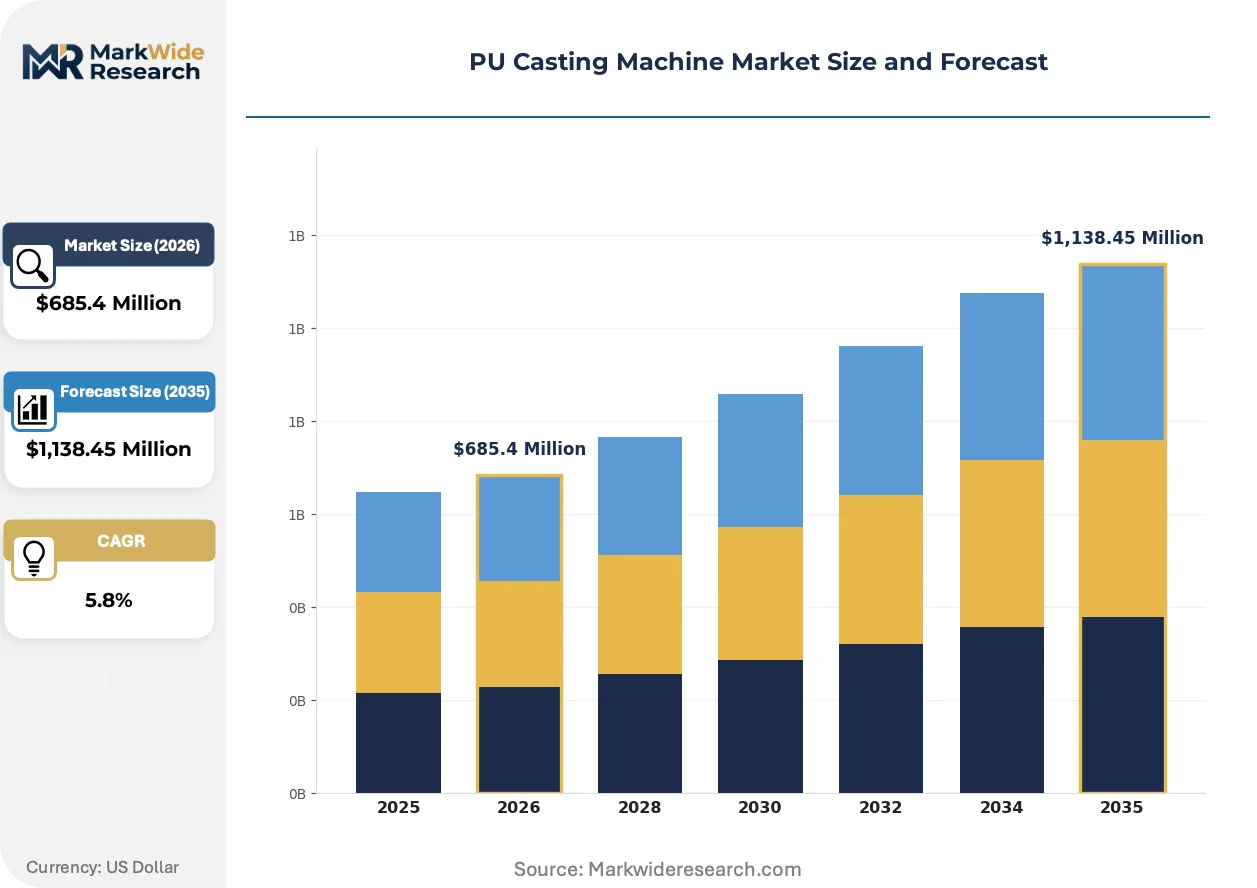
Market Dynamics
The EU F-Gas Regulation and REACH compliance protocols are forcing equipment suppliers to revalidate machine architectures for hydrofluoroolefin blowing agents and aliphatic catalyst systems, compressing design cycles and raising certification costs for cross-border market access.
Growth Catalysts
- Automotive Interior Mandates:OEM specifications for lightweight seating foam are pulling high-pressure metering systems into tier-one supplier facilities across Germany, China, and the United States.
- EPA VOC Enforcement:40 CFR Part 63 Subpart HHH emission limits are accelerating capital replacement cycles at polyurethane processing plants seeking compliant ventilation-integrated machines.
- Robotic Integration:Six-axis dispensing arms are penetrating medical device and aerospace applications where precision path control eliminates manual finishing steps.
Market Restraints
- Isocyanate Exposure Controls:OSHA's 0.005 ppm methylene diphenyl diisocyanate limit constrains operator enclosure designs and raises ventilation engineering costs.
- Raw Material Concentration:Polyol and isocyanate supply clusters in the US Gulf Coast and Northwestern Europe expose processors to regional logistics disruptions.
- Shot Weight Limitations:Existing low-pressure systems face technical ceilings below fifty kilograms, excluding them from heavy industrial roll and wheel manufacturing.
Strategic Opportunities
- Electronics Encapsulation:Vacuum casting systems command premium positioning in optical-grade component production where porosity elimination justifies system investment.
- India Manufacturing Scale-Up:The PLI scheme for automotive components is attracting polyurethane processor investments requiring localized machine deployment and service infrastructure.
- Carbon Border Adjustment:EU CBAM implementation is creating first-mover advantage for European-built machines with verified embedded carbon accounting.
Industry Challenges
- Control System Integration:CE marking under Machinery Directive 2006/42/EC demands safety interlock redesigns that extend validation timelines for non-European suppliers.
- Polymer Processing Expertise:Shortages of technicians fluent in both polyurethane chemistry and servo-driven dosing calibration constrain installation and commissioning capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PU Casting Machine Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Machines, Horizontal Machines, Robotic Machines, Automatic Machines End User: Aerospace, Automotive, Electronics, Furniture Application: Industrial Components, Consumer Goods, Automotive Parts, Medical Devices Technology: Vacuum Casting, Pressure Casting, Liquid Casting, Reaction Injection Molding |
| Companies Covered | Hennecke GmbH, KraussMaffei Group, Cannon Group, Graco Inc., FRIMO Group, SAIP S.r.l., Rim Polymer Industries Pte. Ltd., Linde plc, LEWA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PU Casting Machine Market Trends and Innovations
Digital dosing architectures and closed-loop reaction monitoring are displacing open-loop hydraulic systems, compressing cycle-to-cycle variance and enabling predictive maintenance contracts that restructure supplier-customer relationships.
Precision micro-shot metering technology is miniaturizing. These systems achieve gram-level dispensing accuracy for wearable medical devices and miniature acoustic components. Hearing aid manufacturers in Switzerland and Denmark are adopting these platforms at pilot scale. The technology is miniaturizing component geometries previously machined from solid elastomer, collapsing tooling lead times from weeks to hours.
REACH restrictions on aromatic amine catalysts are compelling formulation shifts across European polyurethane processors. ECHA authorization lists are disqualifying legacy blowing agents and tin-based catalysts from new machine specifications. Automotive seating suppliers in Germany and France are validating aliphatic systems that demand modified heating and mixing profiles, forcing equipment retrofits at tier-one facilities.
Service unbundling is fragmenting traditional procurement patterns. End-users are separating hardware acquisition from polymer supply contracts and maintenance agreements, treating each as distinct spend categories. This pattern is most visible among mid-cap automotive suppliers in the US Midwest seeking to optimize working capital through shorter depreciation schedules and third-party service provision.
PU Casting Machine Market Segmentation
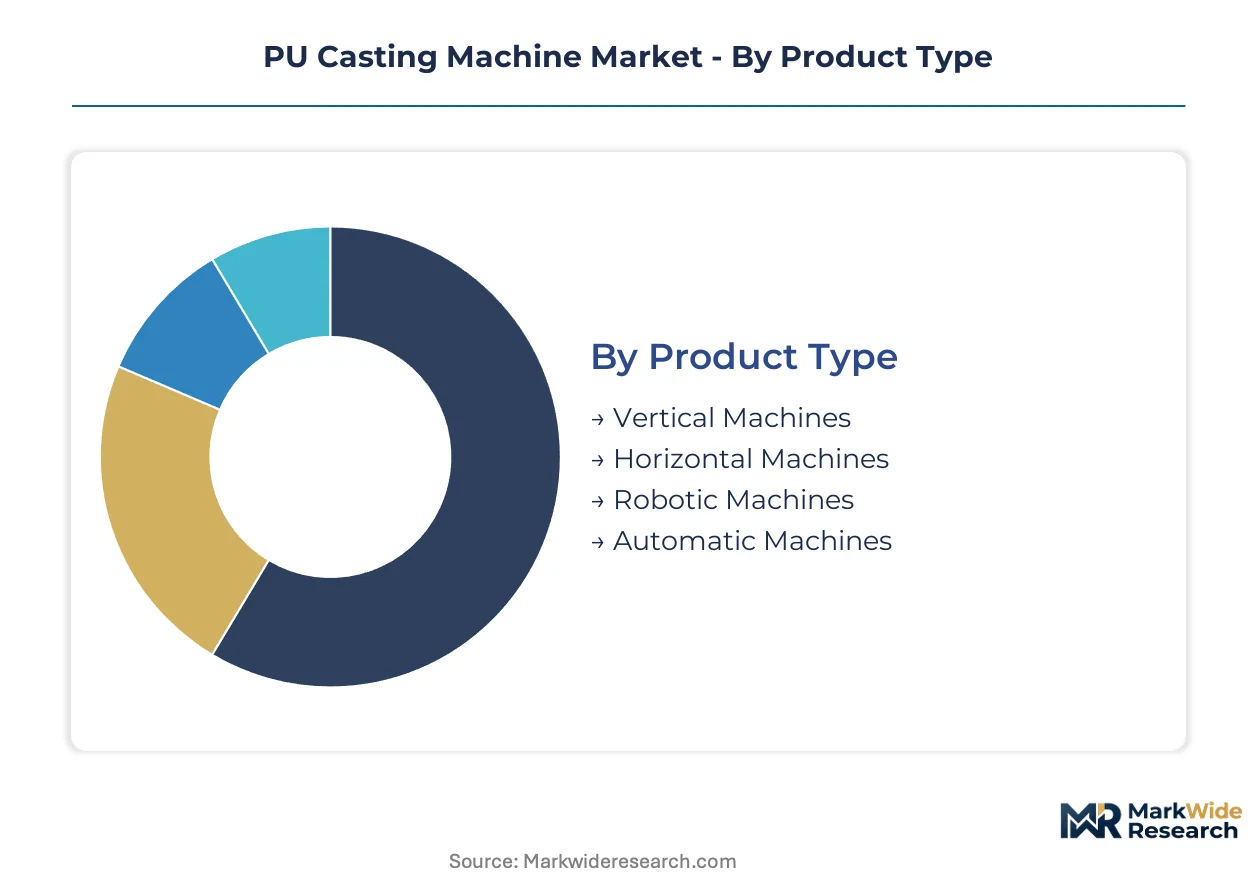
PU casting machine segmentation reveals distinct engineering requirements across product architectures, end-use industries, and process technologies. Regulatory pressures on chemical handling and emission controls are fragmenting specification standards, forcing buyers to match machine capabilities against jurisdiction-specific compliance burdens.
Product Type:
CE marking under the EU Machinery Directive 2006/42/EC imposes divergent safety interlock and control system requirements across machine orientations, favoring suppliers with modular architectures that adapt to regional certification protocols without complete redesign.
- Horizontal Machines:Conveyor-integrated configurations dominate high-throughput automotive seating operations where cycle efficiency determines line economics. German and US Midwest tier-one suppliers deploy these systems for continuous foam pouring across multi-station workflows.
- Robotic Machines:Six-axis dispensing arms achieve precision path control for complex geometries. Medical device manufacturers in Switzerland and aerospace panel producers in France are driving fastest adoption as manual finishing steps get engineered out.
- Vertical Machines:Space-efficient footprints suit batch-oriented electronics encapsulation workflows in Japanese and South Korean component plants.
- Automatic Machines:Fully integrated dosing-mixing-dispensing sequences reduce operator exposure to isocyanate vapors, addressing OSHA and REACH compliance priorities.
Horizontal machines handle the majority of throughput; robotic machines are expanding most quickly on share as precision applications multiply.
End User:
Cost tier differentiation separates capital-intensive aerospace specifications from high-volume automotive procurement patterns, with electronics and furniture occupying intermediate investment bands.
- Automotive:OEM lightweighting mandates for seating foam pull high-pressure metering systems into supplier facilities. German, Chinese, and US-based tier-one processors represent the densest concentration of casting capability investments.
- Electronics:Vacuum-dependent encapsulation demands porosity elimination for optical-grade components. Swiss hearing aid and Danish miniature acoustic device manufacturers validate gram-level shot accuracy at pilot scale.
- Aerospace:Interior panel specifications require complex multi-component formulations with fire-resistant chemistry, constraining machine supplier qualification timelines.
- Furniture:Cushion and bedding foam production favors mid-pressure systems with shorter payback periods, concentrating procurement among mid-cap European and North American processors.
Automotive absorbs the largest capital deployment; electronics shows the steepest expansion trajectory as miniaturization requirements intensify.
Application:
Volume concentration varies by shot weight capability, with heavy industrial components demanding low-pressure architectures that top out below fifty kilograms.
- Automotive Parts:Seating, steering wheels, and interior trim require consistent cell structure and density control. EPA VOC enforcement under 40 CFR Part 63 Subpart HHH accelerates replacement cycles at US-based processing plants.
- Medical Devices:Wearable housings and implantable components demand gram-level metering precision. Swiss and Danish manufacturers are collapsing tooling lead times from weeks to hours through micro-shot casting adoption.
- Industrial Components:Heavy rolls, wheels, and load-bearing elements face technical ceilings in legacy low-pressure systems, excluding some suppliers from this segment.
- Consumer Goods:Footwear soles and sporting equipment balance cost sensitivity with performance consistency, favoring standardized machine configurations.
Automotive parts command the dominant share of installed base; medical devices are climbing the fastest as regulatory quality requirements tighten.
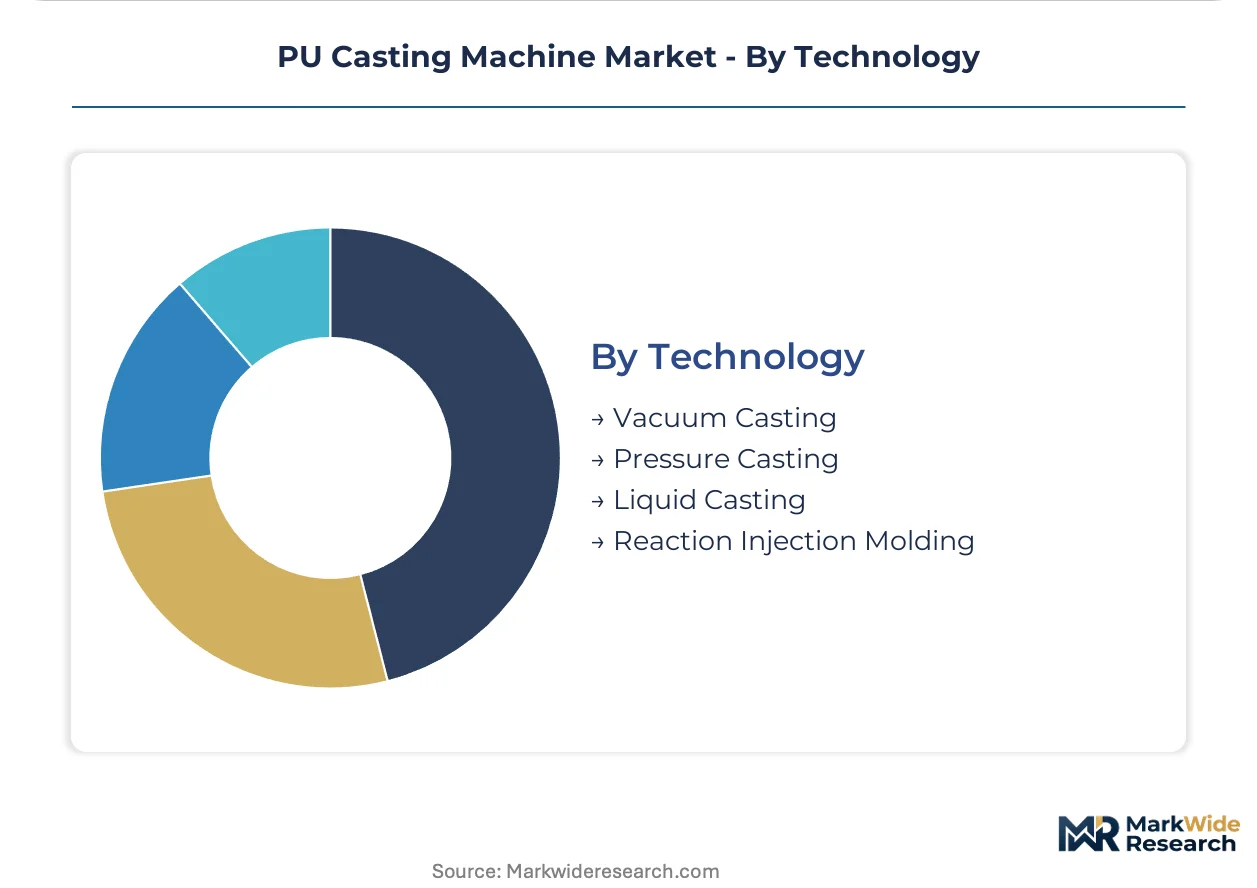
Technology:
Margin structure correlates inversely with process openness, with sealed vacuum systems capturing premium positioning against atmospheric pressure alternatives.
- Vacuum Casting:Porosity elimination justifies system investment in optical-grade and electronics encapsulation applications. ECHA REACH restrictions on aromatic amine catalysts are forcing validation of aliphatic-compatible heating and mixing profiles.
- Pressure Casting:High-pressure metering systems handle complex multi-component polyurethane formulations for automotive structural components. Cannon Group anchors differentiation in this technology tier.
- Liquid Casting:Open-atmosphere dispensing suits cost-sensitive furniture and consumer goods where surface finish tolerances relax.
- Reaction Injection Molding:Rapid reaction chemistry integration enables thin-wall structural parts, concentrating in automotive and industrial component workflows.
Vacuum casting captures the strongest margin pool; pressure casting maintains the broadest application footprint across end-use segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive seating and interior component manufacturers concentrate procurement in Germany, China, and the United States, where tier-one supplier density drives polyurethane processing investments. Equipment suppliers must navigate jurisdiction-specific chemical regulations and carbon accounting frameworks to retain market access.
Germany
Automotive OEM lightweighting mandates pull high-pressure metering systems into Baden-Württemberg and Bavaria supplier facilities. CE marking under Machinery Directive 2006/42/EC imposes safety interlock requirements that extend validation timelines for imported equipment. Stuttgart and Munich host the densest clusters of tier-one seating processors upgrading casting capabilities for next-generation vehicle platforms.
China
Dual carbon goals and MIIT industrial efficiency standards are accelerating replacement of legacy open-loop hydraulic systems in Yangtze River Delta manufacturing zones. GB standards for polyurethane processing emissions constrain machine ventilation designs. Shanghai and Suzhou concentrate the fastest-expanding installed base as domestic automotive brands scale premium seating production.
United States
EPA enforcement under 40 CFR Part 63 Subpart HHH drives capital replacement cycles at Gulf Coast polyol processing clusters. OSHA's methylene diphenyl diisocyanate exposure limit shapes operator enclosure specifications. Michigan and Ohio tier suppliers dominate procurement volumes for conveyor-integrated horizontal machines serving Detroit Three OEM contracts.
India
The PLI scheme for automotive components attracts polyurethane processor investments requiring localized machine deployment. BIS certification requirements for industrial equipment extend commissioning timelines for European and East Asian suppliers. Tamil Nadu and Maharashtra host emerging tier-one seating facilities supplying Maruti Suzuki and Hyundai-Kia export programs.
Switzerland
Gram-level micro-shot metering demand from hearing aid manufacturers in Zurich and Basel drives precision equipment adoption. Swissmedic quality requirements for wearable medical devices constrain validation protocols for casting system suppliers. The Jura Arc microtechnology cluster represents the steepest expansion trajectory for vacuum-dependent encapsulation systems.
PU Casting Machine Market Competitive Landscape
Player mix skews toward integrated polymer processing specialists with captive dosing technology and software capabilities. Market structure concentrates around three to five full-system suppliers with backward integration into mold engineering and process control architectures. Strategic archetypes separate premium precision specialists, scale-oriented automotive suppliers, and regional service-anchored fabricators. Dominant competitive moves include technology licensing partnerships for aliphatic formulation compatibility and geographic expansion through local service infrastructure deployment.
Among Germany-based integrated suppliers, Hennecke GmbH and KraussMaffei Group exemplify the premium precision archetype through combined dosing-mixing technology portfolios and polymer processing software integration. Cannon Group occupies a position within the high-pressure metering specialization tier. Graco Inc. represents the diversified industrial equipment anchor with cross-application fluid handling expertise. SAIP S.r.l. and Rim Polymer Industries Pte. Ltd. sit within the regional service-anchored fabricator category, with geographic naming indicating Italian and Singapore-based operational footprints respectively.
| Leading Market Players |
|---|
| Hennecke GmbH |
| KraussMaffei Group |
| Cannon Group |
| Graco Inc. |
| FRIMO Group |
| SAIP S.r.l. |
| Rim Polymer Industries Pte. Ltd. |
| Linde plc |
| LEWA GmbH |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German and Chinese dosing-system foundries shapes price floors across the PU casting machine landscape, compressing margins for mid-tier suppliers while concentrating procurement leverage with automotive OEMs demanding volume-scale discounts. This scale dynamic tightens supply-side discipline as tier-one processors consolidate machine orders around integrated technology portfolios.
Pricing Analysis
Cost-plus contracts with polyol and isocyanate indexation dominate procurement between tier-one automotive suppliers and equipment vendors, insulating machine margins from raw material volatility while transferring formulation risk downstream. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked precision systems from modified regional variants and refurbished legacy platforms. Pricing pressure stems from Indian and Southeast Asian fabricators offering stripped-down configurations without polymer supply bundling. Mid-cap furniture processors exhibit highest price sensitivity, whereas Swiss medical device manufacturers prioritize gram-level accuracy over capital expenditure optimization.
Supply Chain Analysis
Port congestion on Rotterdam-Shanghai lanes elevates inbound logistics costs for European-built high-pressure metering systems, compressing delivery windows for German tier-one seating suppliers. Component sourcing draws from Germany, China, and the United States for servo-driven dosing pumps, precision mixing heads, and temperature control modules. Single-source vulnerability concentrates in specialized aliphatic-compatible heating elements as REACH restrictions disqualify legacy catalyst systems. Distribution runs through captive service subsidiaries for premium suppliers and third-party industrial distributors for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PU casting machine procurement is approaching a platform-economics inflection as polymer processing software and hardware interoperability become the primary switching cost for tier-one automotive buyers. This ecosystem shift rewards suppliers with captive dosing-mixing-control integration over point-solution vendors.
For Market Incumbents: Shield installed-base relationships by embedding predictive maintenance contracts that restructure customer lifetime value calculations around uptime guarantees rather than upfront capital recovery. Deepen backward integration into aliphatic formulation validation capabilities as ECHA authorization lists disqualify legacy catalyst compatibility. Prioritize CE marking pre-certification for next-generation robotic dispensing architectures to compress validation timelines for European automotive contracts.
For New Entrants and Emerging Players: CE marking fast-track through notified-body partnerships in Germany or Italy accelerates market access for non-European suppliers facing Machinery Directive 2006/42/EC compliance barriers. White-space concentration sits with Indian tier-two automotive seating facilities under PLI scheme expansion, where localized service infrastructure gaps create procurement friction for incumbent European vendors. Target micro-shot metering for Danish and Swiss hearing aid manufacturers through precision-path software differentiation rather than hardware specification competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated polymer processing specialists with captive dosing technology and software capabilities over component suppliers facing margin compression. Long-term viability hinges on aliphatic formulation compatibility and carbon border adjustment readiness across the European installed base. Watch for ECHA authorization list expansions as the inflection signal determining which machine configurations retain market access versus stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Processing Software | Captive control architectures lock in tier-one automotive switching costs against modular competitors. |
| Aliphatic Formulation Validation Investment | REACH-compliant heating and mixing profiles secure European market access as ECHA restricts legacy catalysts. |
| Localized Service Infrastructure Deployment | India PLI scheme participants require Tamil Nadu and Maharashtra commissioning capacity unavailable from distant suppliers. |
| Predictive Maintenance Contract Structuring | Uptime-based pricing restructures supplier-customer relationships around operational expenditure rather than capital recovery. |
| CE Marking Pre-Certification for Robotic Architectures | Machinery Directive 2006/42/EC compliance compresses validation timelines for six-axis dispensing systems in medical device applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment supplier filings, and ECHA chemical authorization registers. Interviews with plant engineers at German and US tier-one seating suppliers, procurement leads at Chinese automotive OEMs, and aftermarket service heads at European distributors informed demand-side calibration. Bottom-up machine shipment tallies triangulate against top-down polyurethane processing capacity expansion announcements across major manufacturing jurisdictions.
Segmentation dimensions modeled span machine orientation, end-use industry concentration, shot weight capability tier, and regional regulatory cluster across the projection horizon. CAGRs derive from regression analysis of historical capital expenditure patterns against automotive production forecasts and chemical compliance timeline assumptions. Industry-specific inputs include EPA VOC enforcement trajectory under 40 CFR Part 63 Subpart HHH and MIIT industrial efficiency standard implementation pace in Yangtze River Delta manufacturing zones.
Decision-makers should treat outputs as directional under assumptions of continued automotive lightweighting mandate enforcement and REACH authorization list expansion; material deviation would warrant model refresh. Specific risk factors include isocyanate exposure limit tightening by OSHA, polyol supply disruption in US Gulf Coast clusters, and carbon border adjustment mechanism scope expansion beyond pilot phases. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Part Feeder Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Case Erectors Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Press Brakes Market
Construction Equipment
France Metal Fabrication Equipment Market