
 Europe Heat Exchanger Market | 2026-2036
Europe Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Heat Exchanger Market Intelligence
Asset-light leasing models for industrial thermal equipment are reshaping competitive dynamics across the European heat exchanger landscape. Alfa Laval leverages its service network to capture recurring revenue from performance-based contracts. Kelvion Holding GmbH anchors its position through specialized aftermarket support across Central European manufacturing clusters. GEA Group competes on engineering depth in hygienic designs for food and pharmaceutical processing.
A heat exchanger is a thermal transfer device engineered to move heat between two or more fluid streams at different temperatures without mixing, typically fabricated from stainless steel, copper, or aluminum alloys with plate gaps measured in millimeters to optimize surface-area-to-volume ratios. Its primary industrial purpose is energy recovery, temperature control, and process efficiency in closed-loop thermal systems. Plate heat exchangers dominate the European installed base due to compact footprint and modularity for HVAC retrofit projects. Shell and tube configurations sustain premium positioning in oil and gas applications along the North Sea basin where pressure ratings exceed standard plate limits. Air cooled variants are gaining share in water-stressed Southern European process facilities.
The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant charge volumes and mandate minimum energy performance thresholds for thermal equipment sold across member states. CE marking under the Pressure Equipment Directive governs market access for pressurized heat exchanger assemblies. Germany's Federal Environment Agency enforces national transpositions that tighten inspection intervals for chemical plant installations. Stakeholders must monitor evolving carbon border adjustment mechanisms that will penalize imported carbon steel components from non-EU suppliers.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant volumes across HVAC and process cooling systems, forcing equipment redesigns that favor compact plate-and-frame architectures over traditional shell-and-tube configurations.
Growth Catalysts
- Decarbonization mandates:The EU Green Deal and national building renovation waves in France and Italy are accelerating heat pump deployment, each installation requiring multiple brazed plate heat exchangers for hydronic distribution.
- Scandinavian district heating:Copenhagen, Stockholm, and Helsinki are expanding fourth-generation low-temperature networks that demand larger stainless steel plate units for substation retrofits.
- Hydrogen economy infrastructure:Electrolyzer stack cooling and fuel cell thermal management are creating new demand for nickel-brazed compact exchangers in the Netherlands and Germany.
Market Restraints
- Stainless steel price volatility:Nickel and molybdenum input costs from Indonesian and Russian supply channels create margin pressure for fabricators serving chemical processing.
- Specialized welding labor scarcity:Certified orbital TIG welders for pressure-rated assemblies are concentrated in Northern Italian and German industrial clusters, limiting production scaling.
- REACH compliance friction:Registration requirements for brazing alloys containing cobalt and nickel compounds extend qualification timelines for new product introductions.
Strategic Opportunities
- Polish and Romanian manufacturing corridors:Greenfield automotive battery plants in Lower Silesia and Ploiești need scalable cooling systems for cell formation and pack assembly.
- Data center liquid cooling:Direct-to-chip cold plate architectures are displacing air-handling units in Frankfurt, Amsterdam, and Dublin hyperscale facilities.
- Refrigerant transition services:The F-Gas phase-down creates aftermarket retrofit demand for lower-volume charge-compatible plate designs across existing Spanish and Portuguese commercial refrigeration.
Industry Challenges
- Pressure Equipment Directive certification backlog:Notified body queue times for Category IV exchanger approvals extend project delivery schedules by four to eight months.
- Legacy system integration complexity:Retrofitting compact plate units into existing shell-and-tube footprints requires custom piping and control logic, raising total installed cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Heat Exchanger Market |
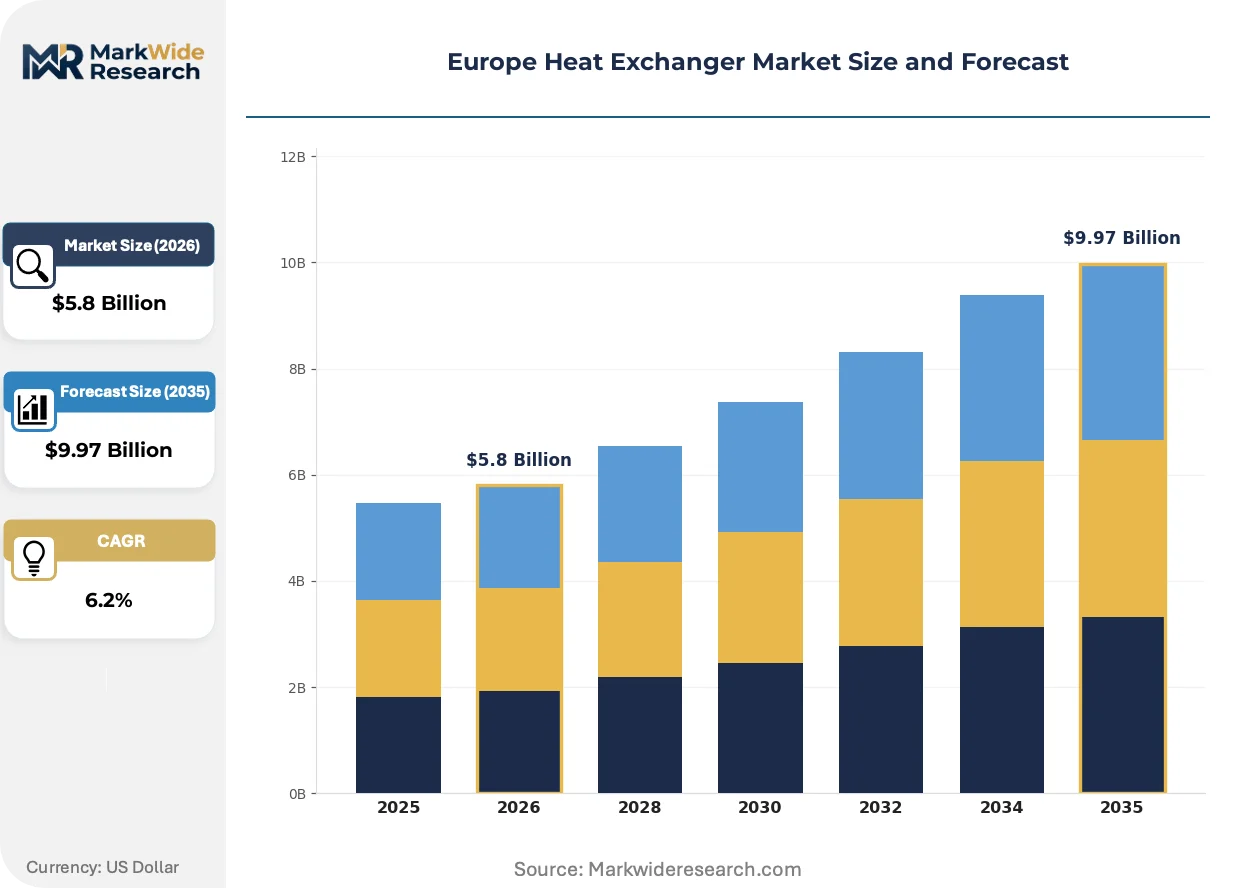
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.97 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell and Tube, Plate, Air Cooled, Double Pipe End User: Power Generation, Oil and Gas, HVAC, Chemical Processing Material: Stainless Steel, Copper, Carbon Steel, Aluminum Application: District Heating, Refrigeration, Process Heat Recovery, Marine |
| Companies Covered | GEA Group, SWEP International AB, Alfa Laval, Johnson Controls, FUNKE Wärmetauscher Apparatebau GmbH, Kelvion Holding GmbH, Mersen, LU-VE S.p.A., Danfoss, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Heat Exchanger Market Strategic Shifts & Innovations
Digital twin integration and additive manufacturing are reshaping how thermal equipment is specified, produced, and maintained across European industrial facilities.
Computational fluid dynamics coupled with IoT sensor arrays is digitizing predictive maintenance for critical process cooling. Chemical manufacturers along the Rhine corridor are deploying these systems to anticipate fouling and optimize cleaning cycles. Real-time thermal performance monitoring is compressing unplanned downtime and extending service intervals.
The EU Ecodesign Directive's expanding scope now covers industrial fans and pumps, tightening system efficiency requirements for packaged cooling skids. Manufacturers must demonstrate seasonal performance factors across variable load profiles. This is accelerating adoption of variable-speed drives and intelligent control algorithms in German and Austrian process engineering.
Equipment-as-a-service contracting is displacing traditional capital purchase for large-tonnage installations. Energy service companies in France and the UK now retain ownership of heat exchanger assets, charging for guaranteed thermal duty delivery. This transfers operational risk from plant operators to OEM service networks, concentrating aftermarket relationships with original suppliers.
Europe Heat Exchanger Market Segmentation
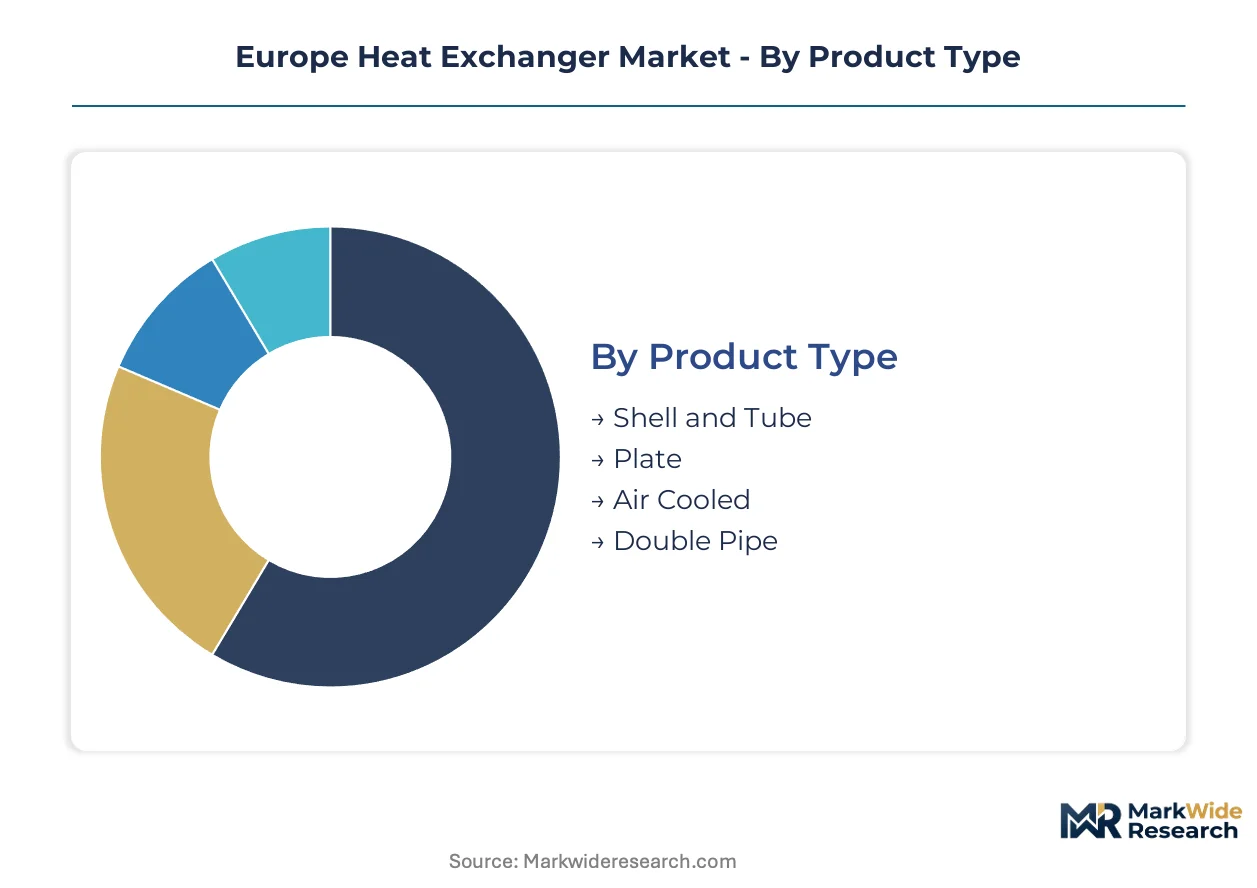
Heat exchanger procurement patterns across Europe diverge sharply by thermal duty, fluid compatibility, and regulatory exposure. Understanding these segment boundaries clarifies where equipment margins concentrate and which technical specifications command premium positioning.
Product Type:
Equipment selection spans compact modular designs through heavy-duty pressure-rated configurations, each occupying distinct niches in the thermal transfer spectrum.
- Shell and Tube:Cylindrical pressure vessels containing tube bundles handle aggressive fluids and extreme temperature differentials. North Sea oil platforms and German chemical complexes specify these units for duties exceeding 40 bar, where plate geometries would fail structurally.
- Plate:Corrugated metal plates stacked in parallel create turbulent flow with minimal refrigerant charge. The EU F-Gas Regulation is compressing charge volumes across HVAC retrofit projects in France and Italy, accelerating specification of these compact geometries over traditional alternatives.
- Air Cooled:Finned tube arrays dissipate heat directly to ambient air, eliminating water consumption. Spanish and Portuguese process facilities facing water stress are displacing cooling towers with these dry systems for moderate thermal loads.
- Double Pipe:Concentric tube arrangements serve low-flow, high-pressure applications with minimal fouling risk. These units maintain presence in small-scale pharmaceutical batch processing where cleanability trumps efficiency optimization.
The dominant share belongs to Plate designs, while Air Cooled configurations are closing the gap fastest in water-stressed Southern European installations.
End User:
Customer technical requirements range from standardized HVAC catalog products through bespoke corrosion-resistant process engineering.
- Power Generation:Condensers and feedwater heaters operate at massive scale with titanium or super-austenitic stainless metallurgy. Combined cycle plants along the Rhine corridor source these units under long-term service agreements that bundle predictive maintenance with capital equipment.
- Oil and Gas:Offshore platforms and refineries demand pressure-rated shell and tube units with seawater corrosion resistance. Norwegian North Sea operators specify duplex stainless steel metallurgy for subsea cooling loops exposed to chloride-rich environments.
- HVAC:Commercial building systems prioritize compact footprint and modularity for retrofit compatibility. Scandinavian district heating substations are driving procurement of brazed plate units sized for fourth-generation low-temperature network integration.
- Chemical Processing:Aggressive acid streams and thermal cycling demand specialized alloy selection. BASF and Bayer facilities along the German chemical corridor concentrate orders for Hastelloy and tantalum-clad units in sulfuric acid service.
Power Generation captures the largest equipment value per installation, though HVAC is expanding most quickly through building renovation mandates.
Material:
Metallurgy selection balances corrosion resistance, thermal conductivity, and carbon border exposure under evolving EU trade mechanisms.
- Stainless Steel:Austenitic grades dominate hygienic and corrosive applications across food, pharmaceutical, and chemical sectors. Nickel and molybdenum price volatility from Indonesian supply channels is compressing fabricator margins on these units.
- Copper:Superior thermal conductivity suits HVAC and refrigeration brazed plate constructions. REACH registration requirements for cobalt-containing brazing alloys are extending qualification timelines for new product introductions.
- Carbon Steel:Low-cost option for non-corrosive water and steam service in power and district heating. The EU Carbon Border Adjustment Mechanism will penalize imported carbon steel components from non-EU suppliers, reshaping sourcing strategies.
- Aluminum:Lightweight, corrosion-resistant option for automotive and aerospace thermal management. Battery cell formation lines in Polish and Romanian automotive corridors are specifying aluminum-brazed compact units for weight-sensitive pack cooling.
Stainless Steel retains the dominant installed base, while Aluminum is climbing the fastest on electric vehicle thermal management demand.
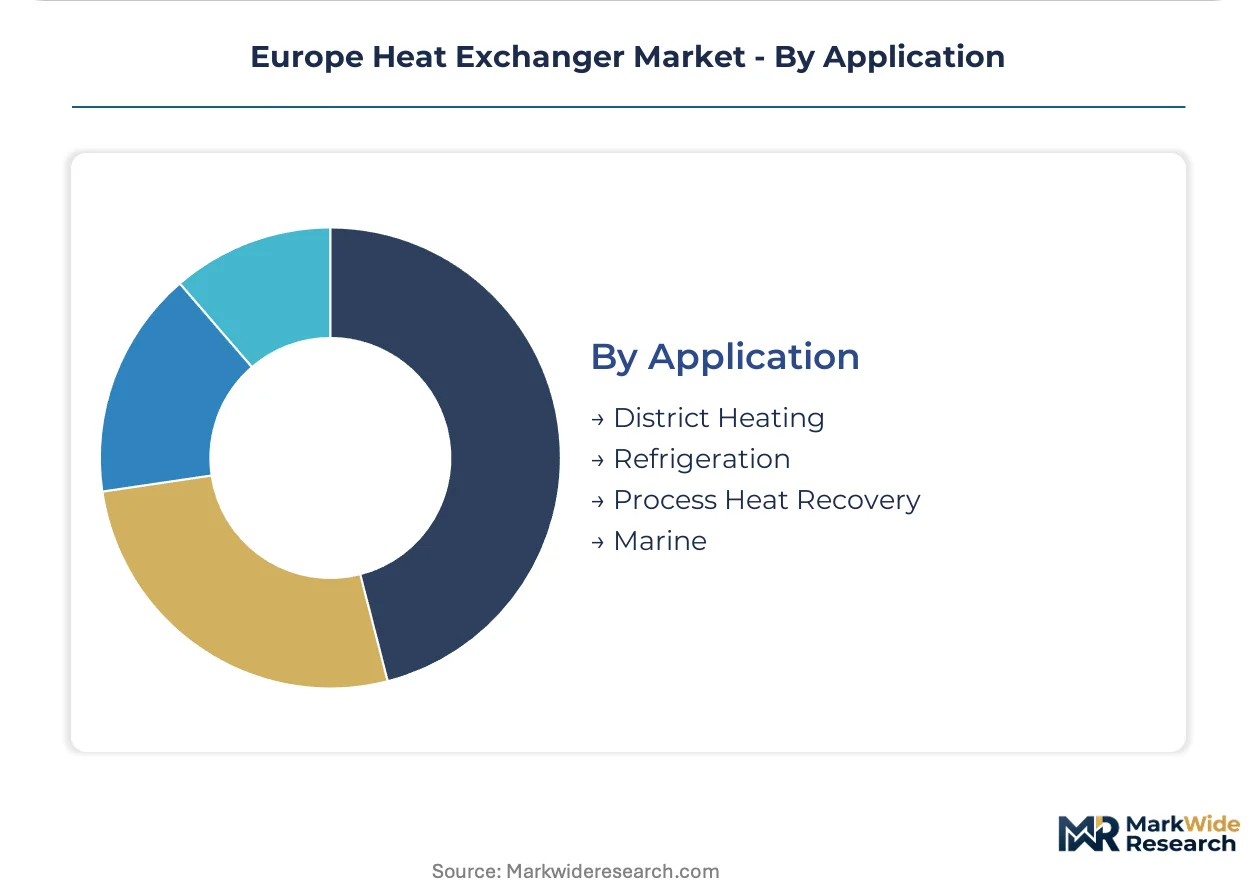
Application:
Functional deployment contexts determine specification priority, from efficiency optimization through extreme environment survivability.
- District Heating:Large-scale plate units transfer thermal energy from centralized plants to building substations. Copenhagen, Stockholm, and Helsinki network expansions are concentrating procurement of stainless steel plate configurations rated for 120°C supply temperatures.
- Refrigeration:Evaporators and condensers manage phase-change heat transfer with minimal refrigerant inventory. Spanish and Portuguese commercial refrigeration retrofit demand is accelerating for F-Gas-compliant lower-charge plate designs.
- Process Heat Recovery:Waste heat capture from exhaust streams and hot process fluids improves plant efficiency. Dutch and German electrolyzer installations are deploying nickel-brazed compact exchangers for stack cooling in hydrogen production.
- Marine:Seawater-cooled units face aggressive chloride corrosion and biofouling challenges. Mediterranean and Baltic shipping operators specify titanium or Cu-Ni alloy constructions for engine cooling and HVAC duties.
District Heating commands the dominant procurement volume, while Process Heat Recovery is gaining share fastest on industrial decarbonization incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and national building renovation mandates are redistributing heat exchanger procurement across member states, with regulatory pressure and infrastructure age determining regional intensity. Germany, France, and the Nordic bloc concentrate the heaviest equipment replacement cycles.
Germany
Industrial decarbonization targets under the Climate Action Programme 2030 are accelerating process heat recovery retrofits. The Federal Environment Agency enforces tightened inspection intervals for chemical plant installations. BASF and Bayer facilities along the Rhine corridor concentrate orders for corrosion-resistant stainless steel units in sulfuric acid service.
France
Building renovation mandates and heat pump deployment subsidies are expanding HVAC equipment procurement. The French Environment and Energy Management Agency (ADEME) administers rebate programs for fourth-generation district heating connections. Paris and Lyon metropolitan areas are driving brazed plate heat exchanger demand for low-temperature network substations.
Sweden
Fourth-generation district heating network expansion is concentrating large-scale plate unit procurement. The Swedish Energy Agency funds municipal low-temperature grid conversions. Stockholm's district heating operator is retrofitting substations with stainless steel plate configurations rated for 55°C supply temperatures.
Netherlands
Electrolyzer stack cooling and fuel cell thermal management are creating new demand for nickel-brazed compact exchangers. The national hydrogen strategy allocates funding for gigawatt-scale electrolyzer deployment. Rotterdam and Eindhoven industrial clusters are specifying compact cooling systems for hydrogen production facilities.
Poland
Greenfield automotive battery plants are driving scalable cooling system procurement for cell formation and pack assembly. EU Just Transition Mechanism funding supports industrial decarbonization in former coal regions. Lower Silesia manufacturing corridors are specifying aluminum-brazed compact units for weight-sensitive battery thermal management.
Europe Heat Exchanger Market Key Industry Players
On the supply side, the industry is moderately consolidated around specialized engineering groups with established aftermarket networks. Tier-one participants combine equipment manufacturing with service contracting to capture recurring revenue streams. Three archetypes dominate: full-service thermal engineering houses, focused plate heat exchanger specialists, and diversified industrial conglomerates with thermal divisions. Competitive moves center on performance-based service contracts and geographic expansion into Central European manufacturing corridors.
Among Nordic-based engineering groups, Alfa Laval and SWEP International AB exemplify the plate heat exchanger specialist archetype, anchoring positions through modularity and refrigerant charge optimization. German fabricators FUNKE Wärmetauscher Apparatebau GmbH and Kelvion Holding GmbH occupy positions within the full-service tier, emphasizing pressure-rated assemblies and aftermarket support density across Rhine corridor chemical clusters. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| GEA Group |
| SWEP International AB |
| Alfa Laval |
| Johnson Controls |
| FUNKE Wärmetauscher Apparatebau GmbH |
| Kelvion Holding GmbH |
| Mersen |
| LU-VE S.p.A. |
| Danfoss |
| Others |
Cost & Logistics Intelligence
Overcapacity in Southern European plate heat exchanger fabrication is compressing spot pricing for standard HVAC units while tightening margins for commodity-grade suppliers serving Spanish and Portuguese retrofit contractors. This utilization imbalance rewards certified fabricators in Northern Italy and Germany with pricing power on pressure-rated assemblies, forcing undifferentiated competitors toward project-based contracting or aftermarket service bundling.
Pricing Analysis
Certification level under the EU Pressure Equipment Directive creates the primary spread between premium Category IV assemblies and economy-grade catalog products. Three-tier pricing structure across premium, standard, and economy levels reflects metallurgy grade, with Hastelloy-clad units commanding substantial premiums over austenitic stainless alternatives. Cost compression in standard brazed plate configurations is intensifying because Indonesian nickel volatility feeds directly into raw material indices. HVAC contractors in France and Italy exhibit the highest price sensitivity, while Rhine corridor chemical processors prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Kelvion Holding GmbH and FUNKE Wärmetauscher Apparatebau GmbH in Germany, alongside Alfa Laval's Nordic fabrication network. Geographic supply concentration centers on Germany, Sweden, and Italy for finished assemblies, with raw material dependencies drawing from Indonesian nickel, Russian molybdenum, and Chinese brazing alloy precursors. Single-source vulnerability around certified orbital TIG welding labor in Northern Italian clusters threatens production scaling. Distribution runs through OEM direct sales for large-tonnage process units and specialized distributors for HVAC retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
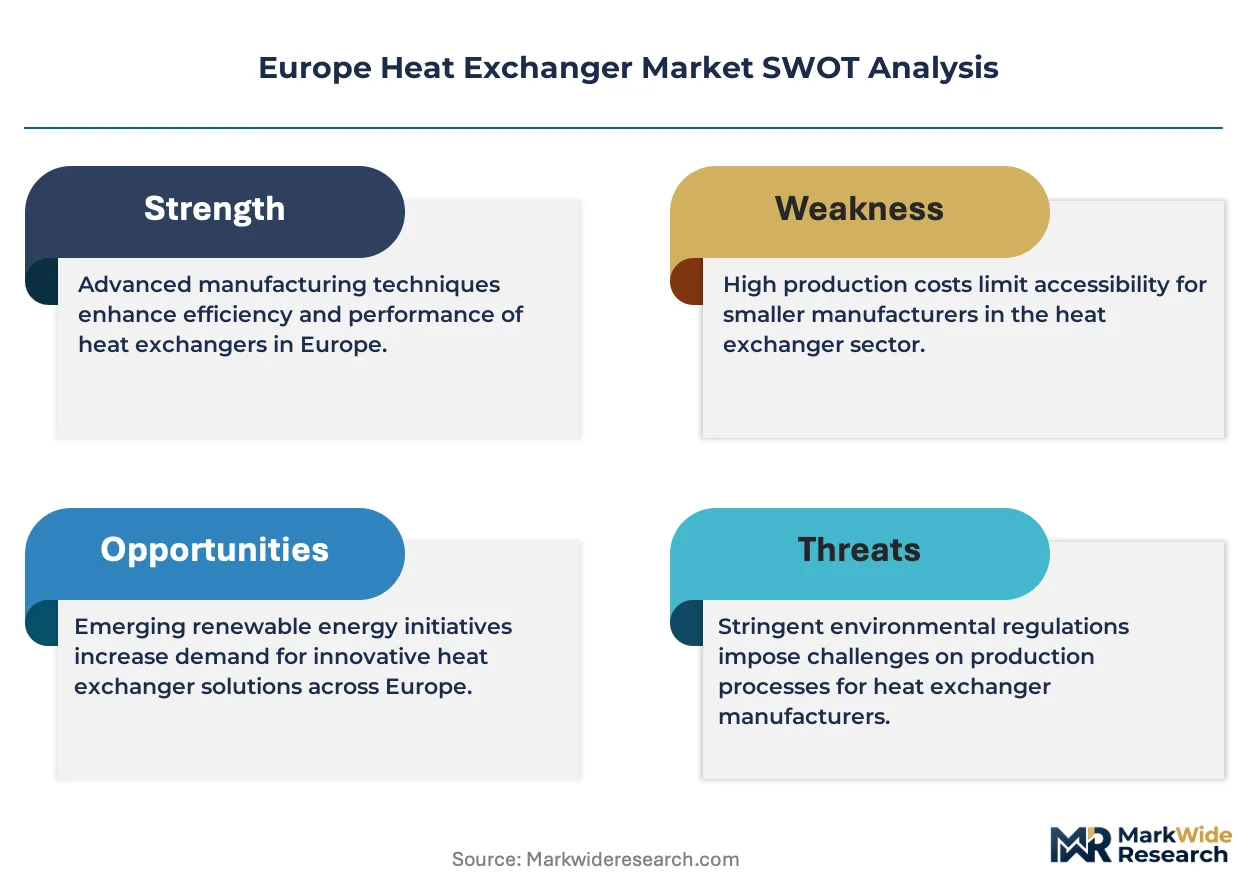
This market offers defensive moats through regulatory entrenchment: CE marking and Pressure Equipment Directive certification create switching costs that lock process plant operators into established supplier relationships for safety-critical thermal equipment.
For Market Incumbents: Pre-empt margin erosion in standard plate configurations by locking long-term service contracts with Rhine corridor chemical processors before emerging Polish fabricators achieve Category IV certification. Prioritize backward integration into nickel alloy supply through offtake agreements with Indonesian producers to hedge raw material volatility threatening stainless steel unit profitability. For New Entrants and Emerging Players: Romanian automotive battery cooling corridors remain underpenetrated by established European heat exchanger OEMs, presenting white-space opportunity for aluminum-brazed compact unit specialists. Target data center liquid cooling retrofits in Frankfurt and Amsterdam hyperscale facilities where direct-to-chip architectures displace legacy air-handling infrastructure. Lead with rapid CE marking turnaround and modular skid integration to differentiate against incumbent project timelines. For Investors and Strategic Acquirers: Capital is best deployed toward aftermarket service networks with dense Rhine corridor presence, where recurring revenue from performance-based thermal duty contracts compounds customer lifetime value. The 5-10 year viability window favors consolidators of specialized welding capabilities and notified body relationships. Watch electrolyzer stack cooling order flow from Dutch and German hydrogen clusters as inflection signal for nickel-brazed compact exchanger demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Equipment Directive Certification Investment | Category IV approvals from TÜV or DEKRA unlock Rhine chemical plant procurement pipelines. |
| Backward Integration into Nickel Alloy Supply | Captive sourcing from Indonesian producers hedges margin compression on stainless steel units. |
| Aftermarket Service Network Expansion | Performance-based thermal duty contracts in Scandinavia generate recurring revenue streams. |
| Hydrogen Economy Thermal System Development | Nickel-brazed compact designs for Dutch electrolyzer installations capture emerging demand. |
| Data Center Liquid Cooling Partnership | Direct-to-chip cold plate architectures for Frankfurt hyperscale facilities displace air-handling units. |
Research Approach
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service directors, and notified body certification specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from EU F-Gas Regulation implementation reports, Pressure Equipment Directive harmonized standards, and customs trade data for stainless steel heat exchanger imports. Bottom-up equipment shipment analysis and top-down industrial thermal system investment flows were triangulated to establish market sizing boundaries.
Scenario-bracketing around EU Green Deal implementation pace and hydrogen infrastructure deployment timelines framed the projection horizon. Segmentation modeling spanned product architecture, end-use industry, metallurgy grade, and regional regulatory cluster dimensions across the analysis window. CAGRs were derived from equipment replacement cycle analysis and new-build thermal system specification trends, with electrolyzer cooling demand and district heating network expansion serving as key industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Polish automotive cooling specialists or accelerated F-Gas phase-down schedules would shift outcomes beyond modeled ranges. Quarterly review of notified body certification queue times and Indonesian nickel spot price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Chilled Beams Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Tubular Heater Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
United States HVAC Equipment Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Air Humidifier and Dehumidifier Market