
 Australia Hair Transplant Market | 2026-2036
Australia Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Hair Transplant Market Insights
Asset-light franchise models is tilting competitive dynamics toward scalable clinic networks that lower capital barriers for new entrants. Gro Clinics leverages its multi-city presence to sustain brand recognition across eastern Australia. Dr Anh Medical Aesthetics anchors premium positioning through specialized surgical credentials. Epiclinic Adelaide competes via regional dominance in South Australia's underserved market.
Australia hair transplant procedures involve surgical relocation of follicular units from donor to recipient scalp sites, typically requiring local anesthesia and sessions lasting four to eight hours depending on graft count. The primary purpose is permanent restoration of hair density for androgenetic alopecia and trauma-related loss. Follicular unit extraction (FUE) leads procedure type demand due to minimized scarring and faster recovery timelines. Robotic-assisted technology commands premium pricing while manual extraction retains volume leadership across regional clinics. Male patients dominate customer type flows, though female and transgender segments expand fastest as marketing normalizes treatment access.
TGA regulates implantable medical devices and surgical instrument standards, while AHPRA governs practitioner registration and advertising compliance for cosmetic procedures. These frameworks elevate clinic operating costs but filter out unqualified providers, concentrating demand toward accredited facilities. Stakeholders must monitor TGA reclassification of automated extraction devices and AHPRA's evolving advertising guidelines as these will reshape competitive compliance burdens and patient acquisition channels.
Market Dynamics
Asset-light franchise models are compressing capital barriers for clinic networks across Australia, tilting competitive dynamics toward scalable multi-city operators that can amortize marketing costs across regional markets while TGA device reclassifications reshape compliance burdens.
Growth Catalysts
- Social destigmatization:Male patients now openly pursue cosmetic restoration as workplace appearance standards intensify across Sydney and Melbourne corporate sectors.
- FUE technique maturation:Minimized scarring and faster recovery timelines expand addressable patient pools beyond early adopters into mainstream demographics.
- AHPRA advertising clarity:Standardized practitioner disclosure requirements reduce consumer confusion and channel demand toward accredited facilities.
Market Restraints
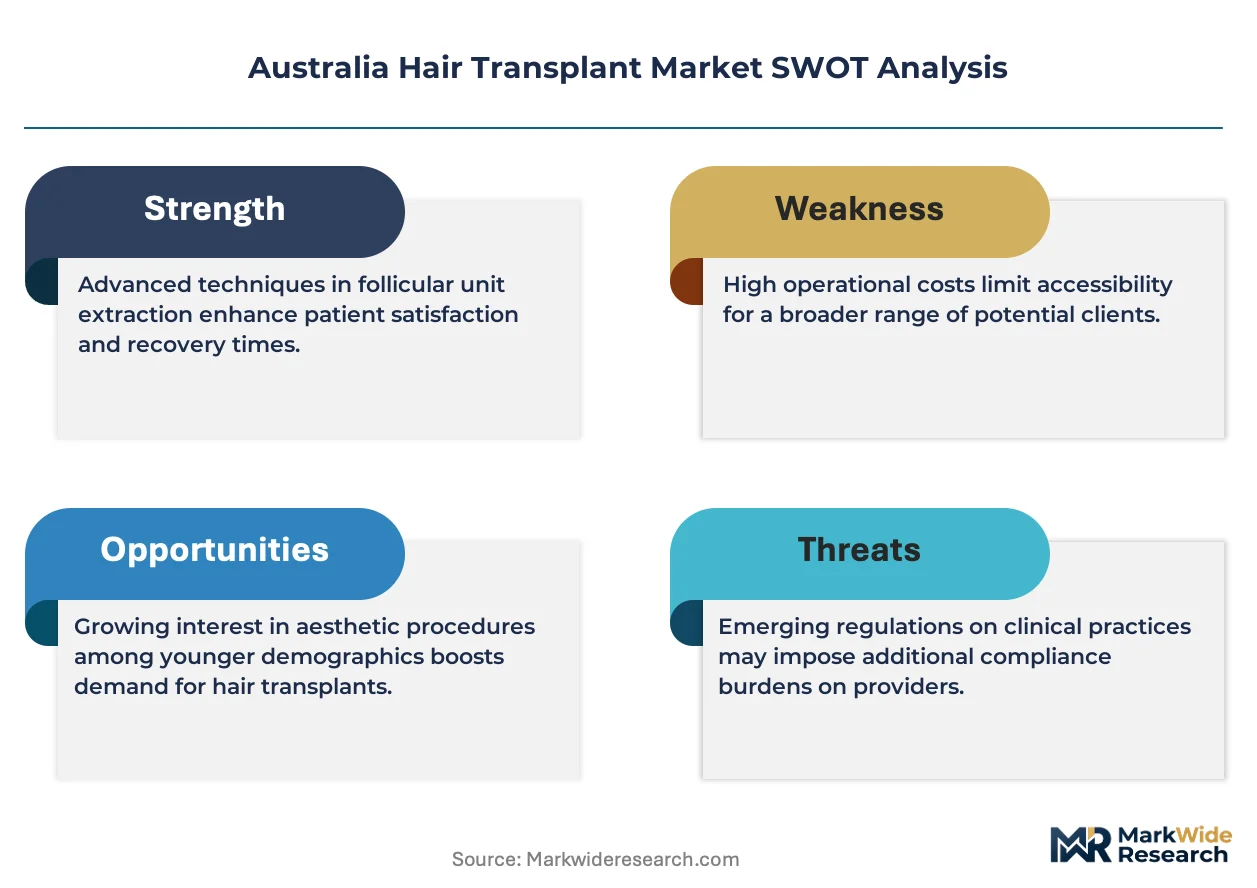
- Donor supply limitation:Finite follicular reserves from occipital scalp regions cap achievable density per patient, constraining revenue per procedure.
- TGA compliance costs:Device reclassification pathways impose multi-year approval timelines and clinical evidence burdens on automated extraction technologies.
- Skilled surgeon scarcity:Fellowship-trained hair restoration specialists concentrate in Sydney and Melbourne, leaving Adelaide and Perth markets underserved.
Strategic Opportunities
- Perth market penetration:Western Australia's resource-driven affluence supports premium pricing with minimal existing specialized competition.
- Female segment expansion:Diffuse pattern alopecia treatments for women represent an emerging application with limited current service provision.
- Robotic-assisted convergence:Integration of AI graft selection with automated extraction promises standardization across operator skill levels.
Industry Challenges
- AHPRA advertising investigations:Compliance teams must navigate evolving guidelines on before-and-after imagery and testimonial use.
- Equipment depreciation cycles:Robotic systems require capital replacement every five to seven years amid rapid technological iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Hair Transplant Market |
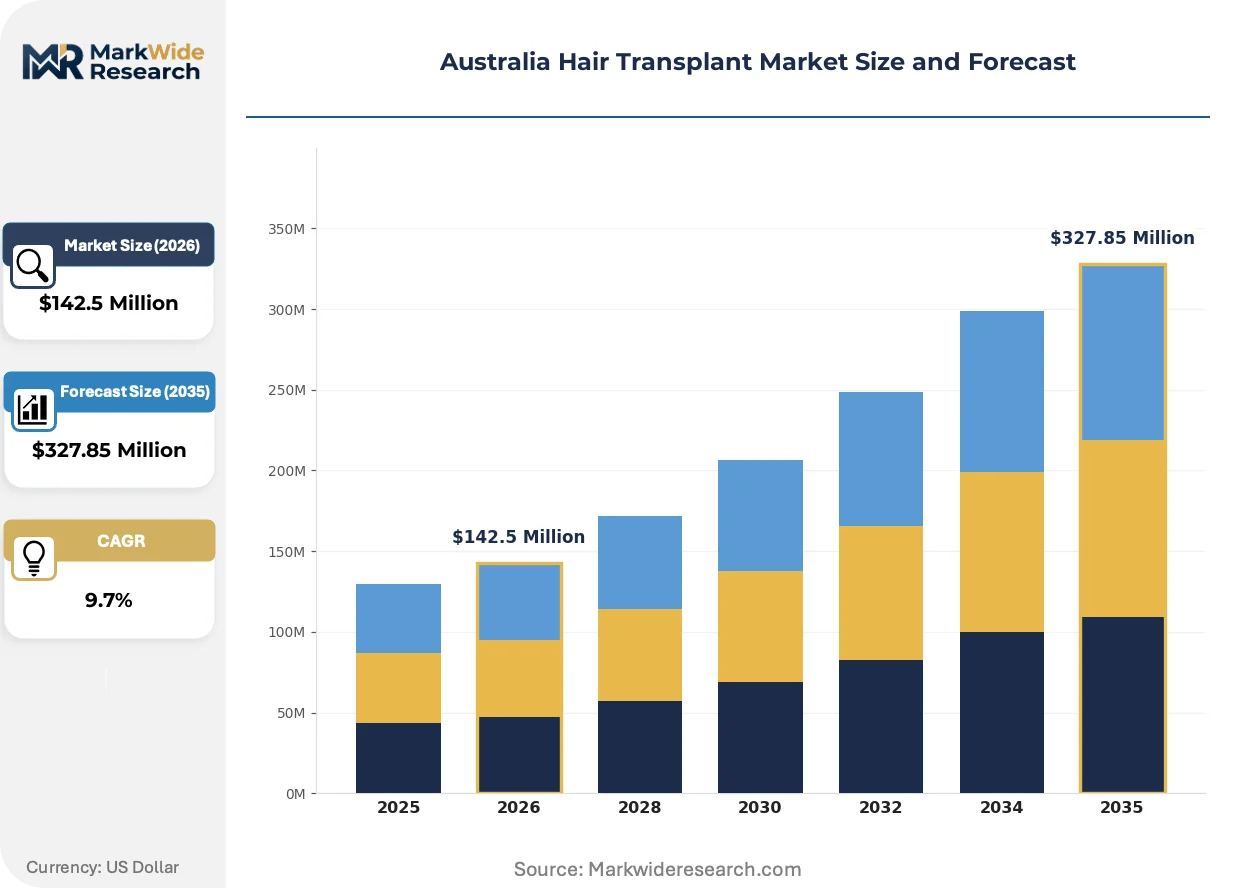
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $327.85 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUT, FUE, DHI, PRP Technology: Robotic-assisted, Manual Extraction, Laser Therapy, Platelet-rich Plasma End User: Clinics, Dermatology Centers, Hospitals, Cosmetic Surgery Centers Customer Type: Male Patients, Female Patients, Transgender Patients, Others |
| Companies Covered | Dr Hair Clinic, Epiclinic Adelaide, Dr Anh Medical Aesthetics, Gro Clinics, MediHair Hair Clinic, The Crown Clinic, Eleventh Heaven Hair Clinic, Hair Doctors, Elite Hair Clinic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Hair Transplant Market Trends and Innovations
Technological substitution and regulatory recalibration are compressing traditional service delivery models while patient acquisition channels fragment across digital platforms and referral networks.
Robotic follicular unit extraction systems combine stereoscopic vision with AI-driven graft selection algorithms. Premium Sydney clinics are adopting these platforms at accelerating pace to differentiate surgical precision claims. Manual extraction techniques are rendering obsolete for high-volume operators seeking throughput scalability without proportional surgeon headcount expansion.
TGA consultation papers signal potential reclassification of automated hair extraction devices from Class IIa to Class IIb medical devices. This shift would mandate additional clinical evidence and quality management system audits for existing installations. Melbourne-based device distributors are pre-emptively restructuring technical documentation to accommodate expanded conformity assessment requirements.
Patient research behavior has migrated decisively toward video-centric social platforms where unfiltered procedure documentation drives provider selection. Traditional clinic websites and directory listings are losing primacy as discovery channels. Queensland and Victorian markets exhibit the sharpest platform pivot, with younger male demographics prioritizing transparency over institutional branding.
Australia Hair Transplant Market Segmentation
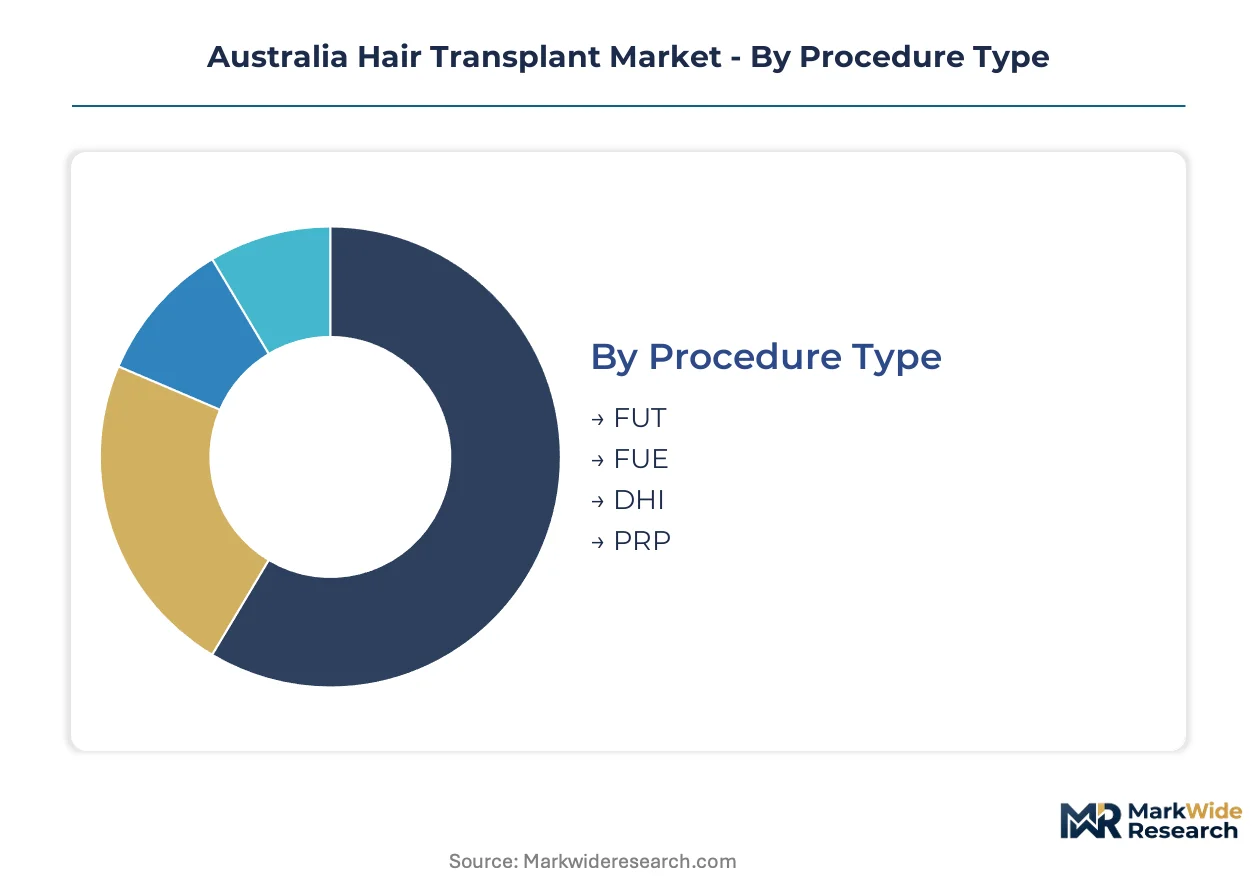
Australian hair transplant demand fragments across surgical technique preferences, automation levels, and care settings. Understanding these divisions reveals where capital deployment and compliance resources generate the strongest returns.
Procedure Type:
Hair restoration in Australia spans extraction methods that trade scar visibility against graft yield and session duration.
- FUE:Individual follicular units are harvested via micro-punch tools from donor zones, leaving dot-like scars that permit short hairstyles. Sydney and Melbourne clinics report strongest volume concentration as corporate professionals prioritize rapid return to workplace visibility.
- FUT:A strip of scalp tissue is excised from the occipital region and dissected into grafts under magnification. Adelaide operators maintain higher FUT penetration due to cost-conscious patient bases and longer-established surgical teams.
- DHI:Direct implantation via Choi pen devices enables simultaneous extraction and placement without pre-made incisions.
- PRP:Autologous plasma injections supplement surgical outcomes or address early-stage thinning without transplantation.
The dominant share belongs to FUE, while DHI is closing the gap fastest.
Technology:
Automation intensity determines capital requirements and pricing power across Australian metropolitan markets.
- Manual Extraction:Surgeons operate handheld punches and forceps without mechanical assistance, allowing tactile feedback during graft harvesting. Queensland regional clinics rely heavily on manual methods where equipment financing remains constrained.
- Robotic-assisted:Stereoscopic vision systems with AI graft selection algorithms standardize extraction depth and angle. Melbourne dermatology centers have accelerated adoption to differentiate precision claims against manual competitors.
- Laser Therapy:Low-level light devices stimulate follicular metabolism as adjunctive or standalone treatment.
- Platelet-rich Plasma:Centrifuged autologous plasma concentrates growth factors for injection therapy.
Manual extraction retains volume leadership, though robotic-assisted platforms are climbing the fastest as TGA clearance pathways mature.
End User:
Care delivery settings reflect regulatory compliance burdens and patient acquisition economics.
- Dermatology Centers:Specialist-led facilities combine hair restoration with broader skin health services, leveraging AHPRA-accredited practitioner pools. Melbourne and Sydney house the densest concentration of these integrated operations.
- Cosmetic Surgery Centers:Multi-procedure clinics amortize marketing and facility costs across rhinoplasty, liposuction, and hair transplant services. Perth's resource-wealthy patient base supports premium positioning in this channel.
- Clinics:Dedicated hair restoration facilities focus exclusively on transplantation and related services.
- Hospitals:Public and private hospital systems handle complex cases requiring general anesthesia or combined reconstructive procedures.
Dermatology centers command the highest patient trust scores, while cosmetic surgery centers are gaining share fastest through bundled procedure offerings.
Customer Type:
Demographic targeting shapes marketing channel selection and consultation messaging.
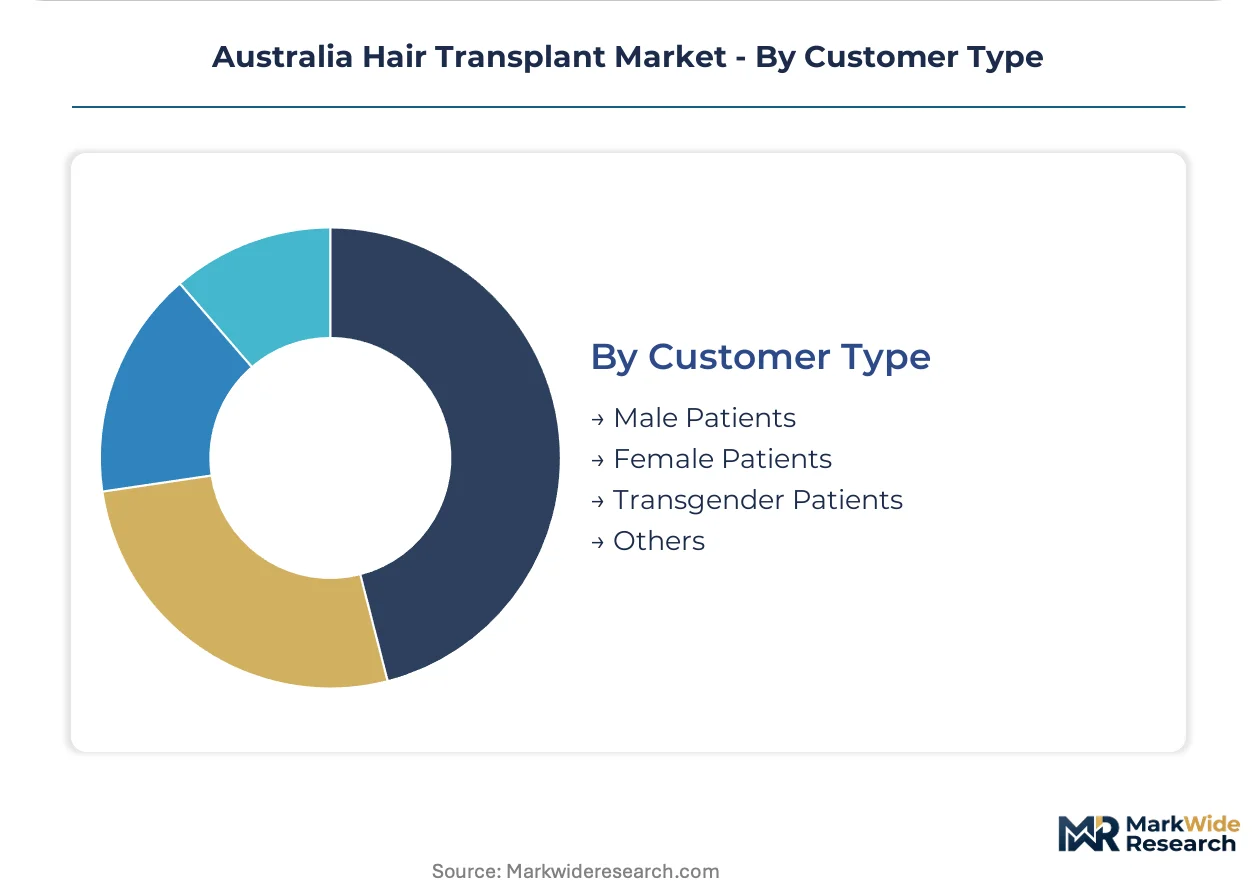
- Male Patients:Androgenetic alopecia cases dominate procedure volumes, with Norwood scale progression driving timing decisions. Sydney's finance and legal sectors generate concentrated demand as appearance standards intensify in client-facing roles.
- Female Patients:Diffuse pattern hair loss and traction alopecia present distinct surgical challenges requiring specialized graft distribution strategies.
- Transgender Patients:Hairline feminization and masculinization procedures address gender-affirming aesthetic goals.
- Others:Pediatric cases, trauma reconstruction, and burn-related restoration represent specialized applications.
Male patients anchor procedure volumes, though female patients are expanding most quickly as marketing normalizes treatment access for women.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's hair transplant services flow predominantly from domestic metropolitan demand rather than cross-border medical tourism, with interstate patient mobility concentrated between eastern seaboard capitals. The market exhibits pronounced geographic clustering around specialized dermatology infrastructure.
New South Wales
Sydney's finance and legal sectors generate concentrated corporate demand as appearance standards intensify in client-facing roles. TGA device reclassification consultations directly impact Sydney-based clinics deploying automated extraction platforms. The Eastern Suburbs and North Shore host the densest concentration of AHPRA-accredited surgical facilities.
Victoria
Melbourne's dermatology centers accelerate robotic-assisted adoption to differentiate precision claims against manual competitors. AHPRA advertising guidelines enforcement channels patient flow toward accredited metropolitan facilities. The inner-city medical precincts concentrate fellowship-trained hair restoration specialists unavailable in regional markets.
Queensland
Brisbane and Gold Coast clinics rely heavily on manual extraction methods where equipment financing remains constrained. TGA oversight of implantable medical devices shapes compliance investment priorities across the state. Southeast Queensland's younger male demographics drive sharp platform pivots toward video-centric social discovery channels.
Western Australia
Perth's resource-driven affluence supports premium pricing with minimal existing specialized competition. The state's geographic isolation limits interstate patient leakage toward eastern competitors. Subiaco and West Perth medical hubs attract investment from multi-city operators seeking uncontested market entry.
South Australia
Adelaide maintains higher FUT penetration due to cost-conscious patient bases and longer-established surgical teams. AHPRA practitioner registration requirements elevate barriers for new market entrants. Epiclinic Adelaide anchors regional dominance in an underserved market with limited interstate competitor presence.
Australia Hair Transplant Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in Australia's hair transplant market structure. The competitive field segments between multi-city scalable networks and single-location premium operators. Three archetypes dominate: asset-light franchise expanders, credential-anchored premium specialists, and regional dominance holders. Geographic expansion and technology licensing represent the dominant competitive moves as operators seek throughput scalability without proportional surgeon headcount growth.
Among multi-city network operators, Gro Clinics exemplifies the scalable platform archetype through eastern Australian presence. Dr Anh Medical Aesthetics occupies a position within the premium specialist tier leveraging surgical credentials. Epiclinic Adelaide represents the regional dominance model in South Australia's concentrated market. These three anchors illustrate how competitive positioning fragments across geographic scale, credential depth, and local market control rather than converging on a single optimal structure.
| Leading Market Players |
|---|
| Dr Hair Clinic |
| Epiclinic Adelaide |
| Dr Anh Medical Aesthetics |
| Gro Clinics |
| MediHair Hair Clinic |
| The Crown Clinic |
| Eleventh Heaven Hair Clinic |
| Hair Doctors |
| Elite Hair Clinic |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Perth and Adelaide surgical facilities compresses wait times and elevates pricing power for established operators, while Sydney and Melbourne overcapacity forces clinics toward volume discounting and bundled service packaging to maintain utilization rates.
Pricing Analysis
Corporate professionals in Sydney's finance and legal sectors anchor premium pricing tiers, with robotic-assisted FUE commanding substantial markups over manual extraction. Price differentiation rests on surgeon credential tier and TGA device classification status, with AHPRA-accredited specialists capturing brand premiums. Cost compression in the manual extraction tier intensifies as franchise networks expand, while regional markets exhibit lower price sensitivity due to limited specialist availability.
Supply Chain Analysis
Upstream follicular extraction devices and implantation instruments flow predominantly from Germany, South Korea, and the United States, with robotic systems sourced through Melbourne-based distributors holding exclusive territorial licenses. Raw material dependencies center on surgical-grade stainless steel, precision micro-motors, and optical sensor arrays. Single-source vulnerability concentrates in AI-enabled graft selection software licenses. Distribution runs through specialized medical device wholesalers serving accredited dermatology and cosmetic surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained surgical talent scarcity constrains clinic expansion velocity across Australia, with Perth and Adelaide markets particularly exposed to capacity bottlenecks as patient demand outstrips qualified practitioner supply.
For Market Incumbents: Build regulatory compliance moats through preemptive TGA Class IIb device reclassification preparation and AHPRA advertising guideline adherence. Secure robotic technology exclusivity agreements in underserviced Western Australia before competitor entry. Counter emerging franchise network threats by anchoring premium positioning through specialized surgical credentials and outcome documentation systems. For New Entrants and Emerging Players: Build out Perth metropolitan presence to capture resource-sector affluence with minimal incumbent competition. Target female diffuse pattern alopecia segments where current service provision remains limited. Deploy video-centric social discovery channels to bypass established clinic brand recognition advantages in Queensland and Victorian markets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because asset-light franchise models favor scalable multi-city networks over fragmented single-location operators. Acquisition targets should display established AHPRA compliance frameworks and robotic technology access pathways. Monitor TGA device reclassification timelines as inflection indicators for compliance cost escalation and competitive filtering effects.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Technology Licensing | Secures AI-enabled graft selection capabilities ahead of TGA Class IIb reclassification requirements. |
| Perth Market Entry | Captures Western Australia's resource-driven patient affluence with minimal specialized competitor presence. |
| Female Segment Service Development | Addresses diffuse pattern alopecia treatment gap with limited current market provision. |
| AHPRA Compliance Investment | Channels patient flow toward accredited facilities as advertising guideline enforcement tightens. |
| Multi-City Franchise Expansion | Amortizes marketing costs across regional markets while lowering capital barriers for network growth. |
Research Methodology
A spread of perspectives from hair restoration surgeons, clinic operations directors, TGA regulatory affairs consultants, and AHPRA compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through TGA consultation papers, AHPRA advertising guideline updates, hospital procurement databases, and dermatology center accreditation records. Bottom-up procedure volume estimates and top-down market sizing triangulated across metropolitan clinic capacity assessments and regional patient flow patterns.
Demand-supply balance modeling anchored forecast construction across the projection horizon, with segmentation dimensions spanning procedure type, automation level, end-user setting, and customer demographic. CAGRs derived from historical growth trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated TGA device reclassification timelines, AHPRA enforcement patterns, and interstate patient mobility trends between eastern seaboard capitals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multi-city franchise networks or international clinic chains would shift outcomes beyond modeled ranges. Cross-checking against Australian Bureau of Statistics healthcare service utilization data and private health insurance claims patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Medical Products Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Incontinence Products Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Organ Care Products Market