
 Japan Minimally Invasive Surgery Devices Market | 2026-2036
Japan Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Minimally Invasive Surgery Devices Market Foresight
Japan's aging surgical workforce is rotating toward robotic-assisted techniques faster than replacement rates for trained laparoscopic specialists. Olympus Corporation leverages its domestic manufacturing base to sustain endoscope supply leadership. Intuitive Surgical competes through installed-base expansion of da Vinci systems across prefectural medical centers. Medicoroid Corp anchors emerging competition with its Hinotori robotic platform designed for Japanese operating-room specifications.
Minimally invasive surgery devices encompass instruments enabling therapeutic intervention through natural orifices or small incisions under image guidance, typically employing rigid or flexible endoscopes with working channels of two to ten millimeters and integrated electrosurgical or laser energy delivery. These systems reduce perioperative trauma, shorten hospital stays, and lower complication rates compared to open procedures. Robotic surgical systems command premium positioning due to capital intensity and recurring instrument revenue, while laparoscopes occupy mature volume leadership across gynecological and urological applications. Electrosurgery technology dominates installed-base energy platforms, though laser surgery segments gain share in precision-cut specialties.
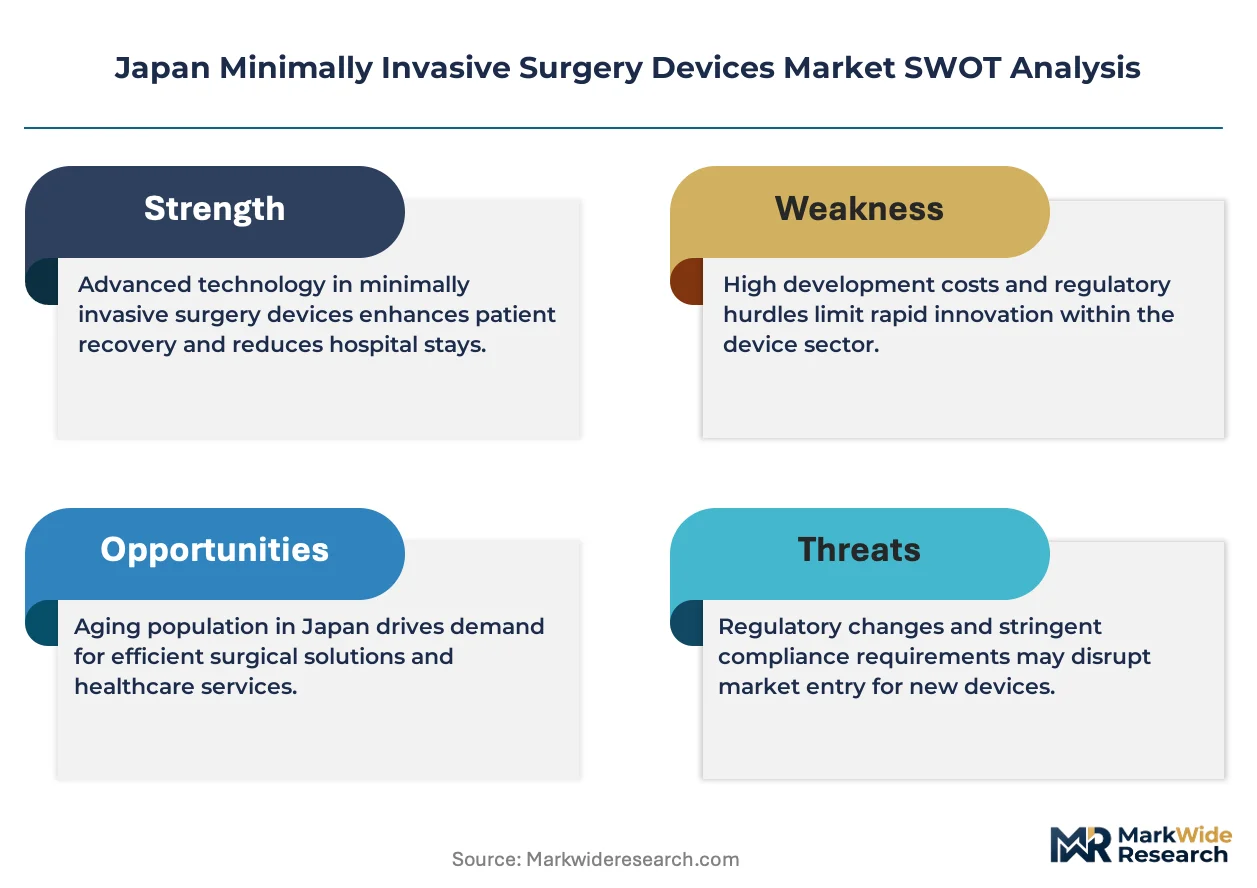
PMDA's streamlined Sakigake designation accelerates approval for breakthrough surgical devices, while METI's medical-device pricing reforms reshape reimbursement incentives toward cost-effective minimally invasive procedures. JIS standards for electromagnetic compatibility and sterilization validation create compliance thresholds that favor established manufacturers with domestic testing infrastructure. Stakeholders must monitor how Japan's next revision of the medical fee schedule recalibrates reimbursement differentials between robotic, laparoscopic, and open surgical procedures.
Market Dynamics
PMDA's Sakigake fast-track pathway compresses approval timelines for AI-integrated surgical platforms, accelerating hospital procurement cycles while METI's pricing reforms recalibrate reimbursement incentives toward minimally invasive modalities. This regulatory momentum concentrates competitive advantage among manufacturers with established domestic testing infrastructure.
Growth Catalysts
- Surgical Robotics Integration:Prefectural medical centers expand da Vinci and Hinotori system deployments as aging demographics concentrate complex caseloads in metropolitan clusters. Hospital administrators prioritize capital equipment that extends specialist productivity.
- METI Medical Fee Revisions:Reimbursement differentials increasingly favor laparoscopic and robotic procedures over open surgery, redirecting hospital investment toward minimally invasive platforms. Fee schedule adjustments create direct financial incentives for technology adoption.
- Tokyo Metropolitan Demand Concentration:Surgical backlogs in Japan's largest hospital cluster drive capacity expansion, with university hospitals leading platform upgrades. Patient volume density justifies capital-intensive robotic system investments.
Market Restraints
- Capital Intensity Barriers:Robotic surgical systems require substantial upfront investment and recurring instrument expenditures, limiting adoption to well-capitalized institutions. Smaller prefectural hospitals face procurement constraints.
- Specialist Training Bottlenecks:Replacement rates for trained laparoscopic specialists lag behind workforce retirement, creating procedural capacity constraints. Robotic credentialing programs extend deployment timelines.
- JIS Compliance Thresholds:Electromagnetic compatibility and sterilization validation standards favor established manufacturers with captive domestic testing facilities. New entrants face extended certification cycles.
Strategic Opportunities
- AI-Assisted Surgical Platforms:Sakigake-designated breakthrough devices accelerate regulatory clearance for machine learning-integrated imaging and navigation systems. PMDA streamlined pathways reward innovation in computer-assisted intervention.
- Osaka-Kobe Medical Cluster Expansion:Western Japan's secondary metropolitan area presents underpenetrated demand for robotic-assisted procedures. Hospital consolidation creates centralized procurement leverage.
- Single-Port Laparoscopy Convergence:Miniaturized instrumentation combined with advanced optics enables reduced-incision procedures across gynecological and urological applications. Technology integration opens procedural expansion.
Industry Challenges
- Robotic System Integration Complexity:Operating room retrofit requirements for da Vinci and Hinotori platforms demand substantial facility reconfiguration. Hospital engineering teams face compressed installation timelines.
- Electrosurgical Platform Standardization:Legacy energy delivery systems create interoperability friction with next-generation robotic arms. Manufacturers must navigate backward compatibility requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Minimally Invasive Surgery Devices Market |
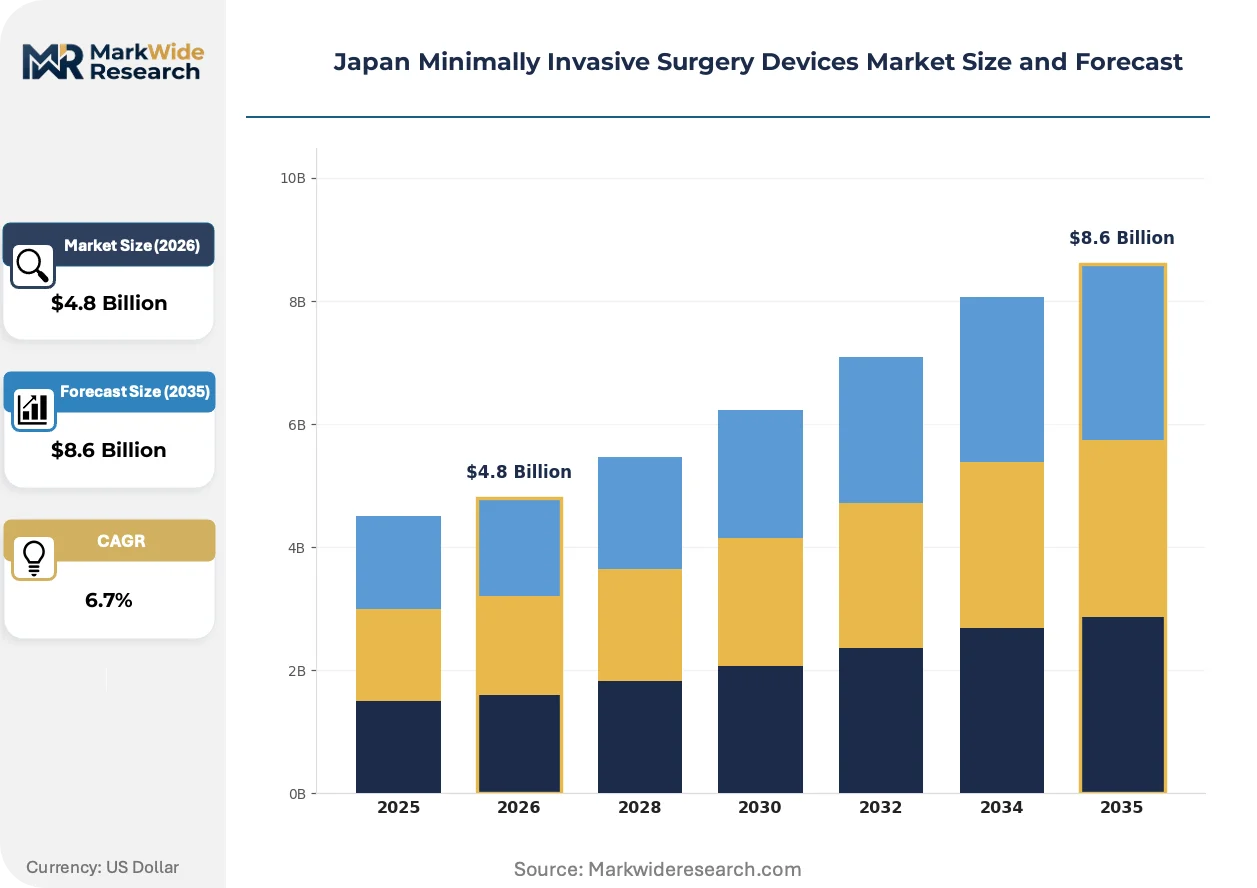
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Endoscopes, Laparoscopes, Robotic Surgical Systems, Dilators Application: Cardiac Surgery, Orthopedic Surgery, Gynecological Surgery, Urological Surgery End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers Technology: Electrosurgery, Laser Surgery, Video Technology, Robotics |
| Companies Covered | Koninklijke Philips NV, Intuitive Surgical, Medtronic PLC, Smith & Nephew, Stryker Corporation, Olympus Corporation, GE Healthcare, Medicoroid Corp, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Minimally Invasive Surgery Devices Market Shifts & Advancements
Japanese surgical device development concentrates on platform convergence, with imaging, energy delivery, and robotic articulation merging into unified intervention systems. Regulatory acceleration and reimbursement reform create simultaneous pull and push forces.
Flexible endoscope technology is bifurcating between ultra-high-definition rigid systems for precision specialties and disposable single-use alternatives for infection-sensitive procedures. Tokyo's university hospitals adopt 4K and 3D visualization platforms for complex oncological resections, while regional medical centers transition toward sterilization-cost-optimized single-use scopes. This technological divergence compresses mid-tier reusable instrument margins while expanding addressable market boundaries.
METI's medical-device pricing reform reshapes procurement evaluation frameworks, embedding cost-effectiveness metrics alongside clinical outcome benchmarks. Hospital purchasing committees now weight total procedure cost against open surgery alternatives when evaluating minimally invasive platform investments. Surgical robotics segments face intensified scrutiny as reimbursement differentials narrow between technological tiers.
Hospital procurement committees consolidate vendor relationships, favoring integrated platform suppliers over discrete instrument vendors. Olympus leverages endoscope installed base to bundle energy and imaging systems, while Intuitive Surgical extends service contract penetration. Tokyo metropolitan clusters lead this consolidation, with consolidated purchasing organizations extracting volume-based pricing concessions.
Japan Minimally Invasive Surgery Devices Market Segmentation
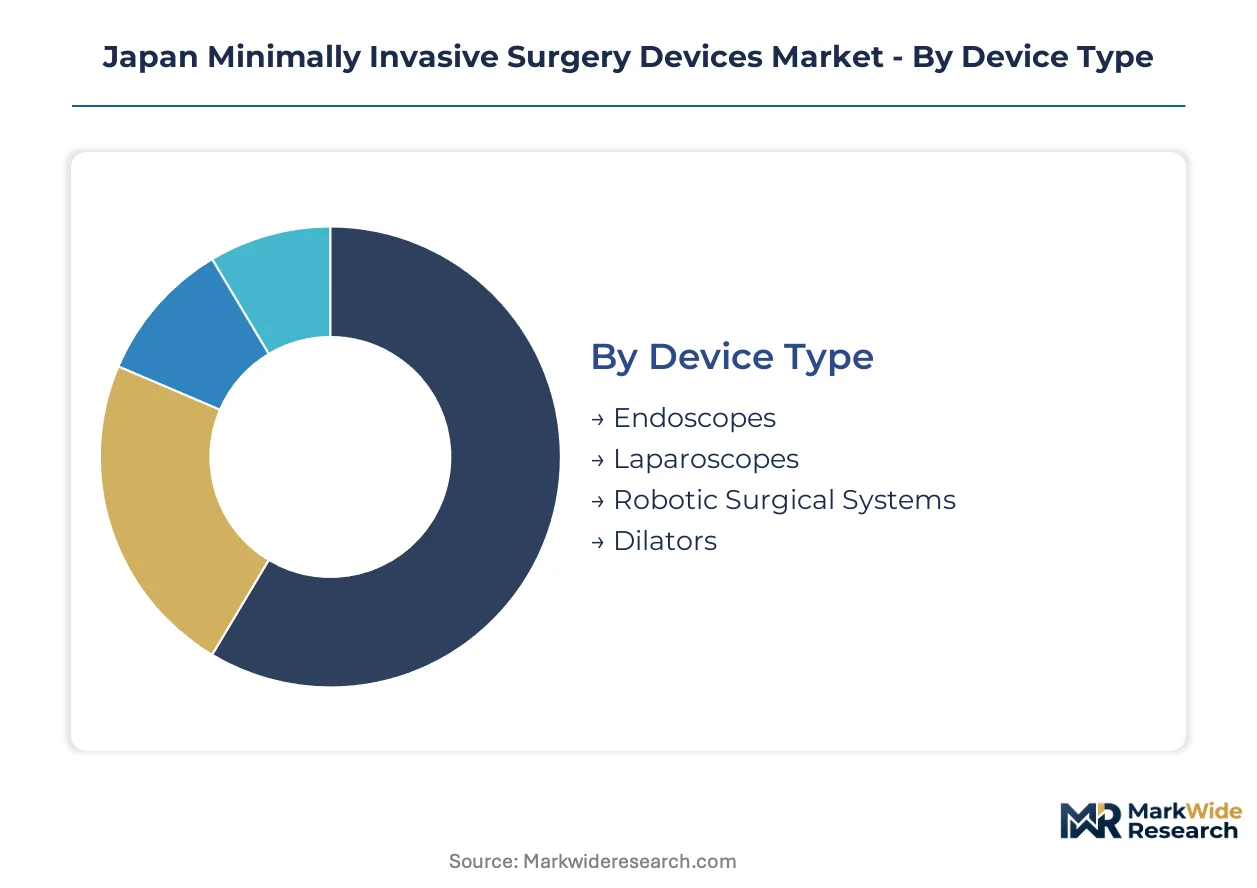
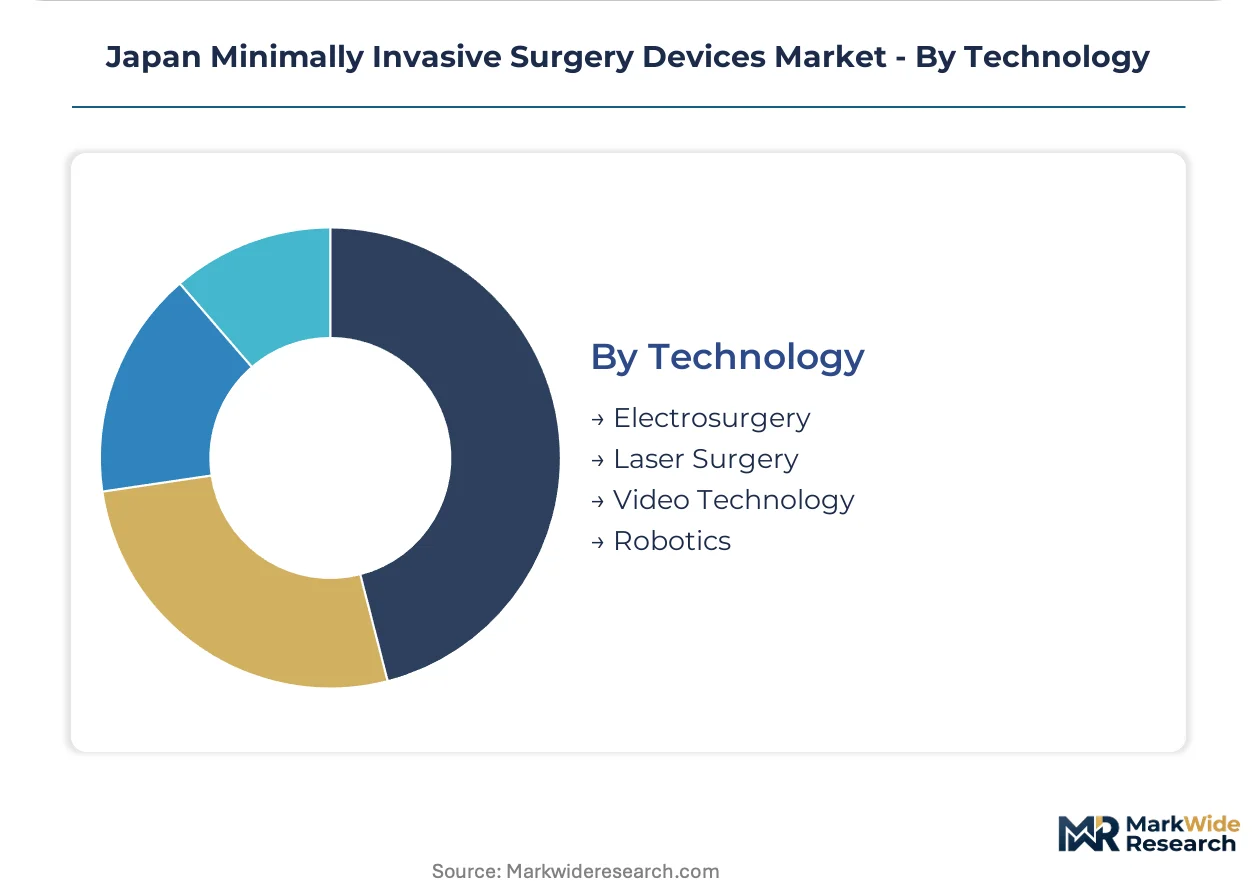
Segmentation reveals how PMDA regulatory pathways and METI reimbursement tiers concentrate investment across distinct technology categories. Hospital procurement committees evaluate each segment through divergent capital intensity and clinical outcome frameworks.
Device Type:
PMDA's Sakigake fast-track pathway applies differentially across capital equipment categories, compressing timelines for AI-integrated platforms while maintaining standard review for mature instrument classes.
- Robotic Surgical Systems:Capital-intensive platforms integrating articulated instrument arms with haptic feedback and 3D visualization. Tokyo's university hospitals concentrate procurement as aging demographics justify specialist productivity extension. PMDA streamlined pathways accelerate hospital adoption cycles.
- Endoscopes:Flexible and rigid optical systems with working channels enabling diagnostic and therapeutic intervention. Metropolitan hospital clusters drive demand bifurcation between 4K reusable platforms and sterilization-cost-optimized single-use alternatives. Olympus leverages domestic manufacturing for supply leadership.
- Laparoscopes:Rigid optical instruments for abdominal cavity visualization through small incisions. Prefectural medical centers maintain volume leadership in gynecological and urological procedural applications.
- Dilators:Mechanical instruments for tissue expansion and access creation. Standardized reimbursement categories limit premium positioning compared to integrated platform categories.
Established volume favors laparoscopes; emerging adoption favors robotic surgical systems.
Application:
Procedure-specific demand concentrates where aging-related disease burden intersects with demonstrable minimally invasive outcome advantages.
- Gynecological Surgery:Hysterectomy and myomectomy procedures drive platform standardization around single-port laparoscopic techniques. Tokyo metropolitan hospitals lead robotic system deployment for complex oncological resections.
- Urological Surgery:Prostatectomy and nephrectomy applications command premium robotic system utilization due to nerve-sparing precision requirements. University hospital clusters concentrate procedural volume and specialist training programs.
- Cardiac Surgery:Valve repair and coronary bypass applications require specialized instrumentation with limited installed base. METI reimbursement differentials remain underdeveloped compared to abdominal specialties.
- Orthopedic Surgery:Arthroscopic and joint replacement applications favor rigid endoscope platforms with established sterilization protocols. Regional medical centers maintain procedural volume leadership.
Reimbursement maturity favors gynecological surgery; technology integration favors urological surgery.
End User:
Procurement authority and capital allocation capacity segment sharply across institutional categories.
- Hospitals:University and prefectural medical centers command capital equipment budgets for robotic platform acquisition. Tokyo's metropolitan cluster concentrates installed base expansion.
- Clinics:Outpatient surgical facilities prioritize disposable endoscope alternatives and compact laparoscopic sets. Cost-effectiveness metrics dominate procurement evaluation.
- Research Institutions:Academic medical centers drive early adoption of AI-integrated platforms under Sakigake designation pathways. PMDA breakthrough device status accelerates clinical validation.
- Diagnostic Centers:Endoscopic screening facilities concentrate flexible scope utilization for cancer detection protocols. JIS sterilization standards shape equipment selection.
Capital concentration favors hospitals; procedural expansion favors clinics.
Technology:
Energy delivery and visualization platforms segment by integration depth with robotic articulation systems.
- Robotics:Integrated platforms combining mechanical articulation with AI-assisted navigation and haptic feedback. PMDA regulatory acceleration rewards computer-assisted intervention development.
- Electrosurgery:Radiofrequency and ultrasonic energy delivery systems dominate installed base across laparoscopic applications. Legacy platform standardization creates interoperability requirements for next-generation system integration.
- Video Technology:4K and 3D visualization systems enable precision intervention across oncological resections. Tokyo university hospitals lead platform upgrade cycles.
- Laser Surgery:Precision-cut energy delivery gains procedural share in ophthalmic and dermatological applications. Limited penetration in abdominal specialties constrains volume scaling.
Installed base dominance favors electrosurgery; regulatory momentum favors robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's minimally invasive surgery device consumption concentrates in metropolitan hospital clusters where aging demographics and surgical backlogs create divergent demand patterns from regional prefectures. Tokyo's university hospitals prioritize capital-intensive robotic platforms, while smaller cities emphasize cost-optimized laparoscopic sets.
Kanto/Tokyo
Tokyo's metropolitan hospital cluster commands the largest installed base of robotic surgical systems as university medical centers address concentrated complex caseloads. PMDA's Sakigake fast-track pathway accelerates procurement cycles for AI-integrated platforms in this region. The Tokyo-Kanagawa-Saitama corridor leads national adoption of 4K visualization systems for oncological resections.
Kansai/Osaka
Osaka prefectural medical centers expand robotic-assisted procedures across urological and gynecological applications as patient volume density justifies capital investment. METI's medical fee revisions create direct reimbursement incentives for minimally invasive modalities in this western hub. The Osaka-Kobe medical cluster presents underpenetrated demand compared to Tokyo, driving accelerated platform deployment.
Chubu/Nagoya
Nagoya's manufacturing heritage supports domestic surgical device supply chains with proximity to precision instrumentation producers. JIS electromagnetic compatibility standards shape equipment selection as regional hospitals upgrade aging laparoscopic platforms. Aichi prefecture's medical centers concentrate single-port laparoscopy adoption in gynecological surgery.
Kyushu
Fukuoka's regional medical centers face specialist training bottlenecks that constrain procedural capacity despite available equipment budgets. The national government's regional healthcare revitalization programs direct capital subsidies toward minimally invasive platform acquisition. Kyushu's aging population density drives demand for productivity-extending robotic systems in university-affiliated hospitals.
Hokkaido
Hokkaido's dispersed rural hospital network limits capital-intensive robotic adoption, favoring portable laparoscopic sets and disposable endoscope alternatives. METI pricing reforms embed cost-effectiveness metrics that disadvantage high-fixed-cost platforms in low-volume settings. Sapporo's university hospital anchors specialist referral patterns for complex robotic procedures from surrounding prefectures.
Japan Minimally Invasive Surgery Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's minimally invasive surgery device market. Olympus Corporation leverages captive domestic manufacturing and endoscope installed base to bundle imaging and energy systems, while Intuitive Surgical extends service contract penetration across prefectural medical centers. Two strategic archetypes dominate: diversified medical technology conglomerates with full-platform portfolios, and focused robotics specialists with premium positioning. Competitive moves concentrate on hospital procurement committee consolidation and integrated platform contracting rather than discrete instrument sales.
Among the integrated tier, Olympus Corporation and Intuitive Surgical occupy positions as archetypal platform bundlers, while Medicoroid Corp represents the emerging domestic robotics challenger. Koninklijke Philips NV and Siemens Healthineers sit within the imaging and navigation subsystem segment, supplying visualization infrastructure without full robotic integration. Medtronic PLC and Stryker Corporation exemplify diversified device manufacturers spanning energy delivery and laparoscopic instrumentation. Smith & Nephew and GE Healthcare occupy specialized positions in orthopedic and diagnostic imaging adjacencies respectively.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Intuitive Surgical |
| Medtronic PLC |
| Smith & Nephew |
| Stryker Corporation |
| Olympus Corporation |
| GE Healthcare |
| Medicoroid Corp |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Long-term service contracts with bundled instrument replenishment clauses lock in both supply continuity and predictable per-procedure costs for Japanese hospital systems navigating METI's reimbursement reforms. These multi-year agreements tether capital-intensive robotic platforms to recurring revenue streams while insulating manufacturers from spot-market volatility in precision electromechanical components.
Pricing Analysis
Project-based capital procurement with tiered after-sales service bundles dominates university hospital acquisitions, separating premium AI-integrated platforms from standard laparoscopic configurations through specialist training inclusion and extended warranty terms. Price differentiation hinges on JIS electromagnetic certification tier and domestic assembly content, with Tokyo metropolitan clusters showing lowest sensitivity due to concentrated surgical backlogs. Cost compression in mid-tier reusable endoscopes is intensifying because regional medical centers prioritize sterilization-cost-optimized single-use alternatives. Clinics and outpatient surgical facilities exhibit highest price sensitivity, driving demand for compact laparoscopic sets with standardized energy delivery compatibility.
Supply Chain Analysis
Inventory buffers for precision optical assemblies and electromechanical articulation modules extend lead times for robotic system fulfillment, particularly affecting prefectural medical centers outside Tokyo's distribution hub. Domestic manufacturing concentrates in Aichi and Tokyo prefectures for endoscope production, while South Korea and Taiwan supply CMOS imaging sensors and miniature motor assemblies. Raw material dependencies encompass rare-earth magnets for surgical arm actuators, high-purity sapphire for optical windows, and medical-grade stainless steel for instrument shafts. Single-source vulnerability in haptic feedback controller chips creates procurement risk for next-generation platform integration. Distribution runs through consolidated medical device GPOs and direct hospital contracting channels, with university hospital clusters extracting volume-based concessions through centralized purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as METI's reimbursement tier differentiation creates distinct procurement constituencies—premium robotic adopters, cost-optimized laparoscopic converters, and disposable endoscope transitioners—each demanding tailored platform configurations.
For Market Incumbents: Compound installed-base advantage through captive service contract expansion and backward integration into domestic sterilization validation infrastructure. Threat from Medicoroid's Hinotori platform and emerging AI-navigation entrants demands accelerated PMDA Sakigake pathway utilization for breakthrough device designation. Priority lever rests on bundling imaging, energy, and robotic systems into unified procurement packages that raise switching costs for hospital purchasing committees.
For New Entrants and Emerging Players: PMDA's Sakigake fast-track certification pathway offers regulatory acceleration for AI-integrated surgical navigation platforms targeting underpenetrated prefectural medical centers. White-space concentrates in Osaka-Kobe cluster robotic deployment and single-port laparoscopy instrumentation for gynecological applications. Go-to-market angle should emphasize JIS compliance pre-certification and direct contracting with consolidated purchasing organizations outside Tokyo's saturated installed base.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic robotics challengers with platform-level software differentiation and established hospital validation partnerships. Long-term viability over the projection horizon hinges on reimbursement policy continuity and specialist training pipeline expansion. Acquisition target archetype encompasses AI-navigation software specialists with regulatory clearance momentum and embedded clinical workflow integration. Signal to watch is METI's next medical fee schedule revision and its differential treatment of robotic versus laparoscopic procedure reimbursement tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sakigake Pathway Utilization | Accelerates regulatory clearance for AI-integrated platforms ahead of standard review timelines. |
| Hospital System Partnership | Locks in multi-year service contracts with Tokyo metropolitan university medical centers. |
| Software Companion Development | Enables machine learning-integrated imaging navigation for precision oncological resections. |
| Reimbursement Strategy | Aligns platform positioning with METI medical fee schedule differential incentives. |
| Domestic Manufacturing Scale-Up | Leverages JIS standards proximity and captive sterilization validation infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and PMDA regulatory affairs specialists; and secondary validation through hospital procurement databases, METI medical device pricing disclosures, JIS standards documentation, and GPO contract award records. Bottom-up triangulation across prefectural medical center capital expenditure patterns and top-down reconciliation with national healthcare infrastructure investment flows anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning device type, application specialty, end-user institutional category, and technology integration depth alongside regional prefecture clustering. CAGRs derived from procedure volume elasticity to reimbursement tier adjustments and specialist workforce replacement dynamics. Industry-specific inputs incorporated PMDA approval pipeline velocity and METI fee schedule revision timing assumptions.
Decision-makers should treat outputs as directional under sustained reimbursement incentive structures and stable regulatory acceleration pathways; material deviation in either would warrant model refresh. Specific risk factors encompass PMDA pathway congestion, specialist training bottleneck severity, and JIS standards revision scope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Airway Management Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Surgical Monitors Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
Ingestible Smart Pills Market