
 Catheter-Directed Thrombolysis Market | 2026-2036
Catheter-Directed Thrombolysis Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter-Directed Thrombolysis Market Outlook
Hospital emergency departments is decoupling from traditional surgical suites as the primary site for acute thrombus management. Boston Scientific leverages its integrated electrophysiology and interventional portfolio to cross-sell thrombolysis platforms into existing cath lab relationships. Medtronic anchors its position through deep vascular franchise infrastructure that sustains physician training and service density across major health systems. Penumbra differentiates via specialized neurovascular and peripheral thrombectomy expertise that extends into catheter-directed lytic delivery systems.
Catheter-directed thrombolysis employs infusion catheters with multi-sidehole designs to deliver thrombolytic agents directly into occluded vessels, typically operating through 4-6 French access sheaths with infusion durations ranging from 12 to 24 hours. The technology's primary purpose is to achieve clot dissolution in deep vein thrombosis, pulmonary embolism, and peripheral arterial occlusion while minimizing systemic bleeding risk. Ultrasound-assisted technology leads the technology dimension by accelerating lytic penetration through acoustic cavitation, though pharmacomechanical systems are capturing faster growth as hybrid devices reduce total treatment time. Balloon catheters command the largest product type share by occupying the established percutaneous transluminal angioplasty infrastructure, while specialty catheters for isolated limb perfusion represent the concentrated margin pool.
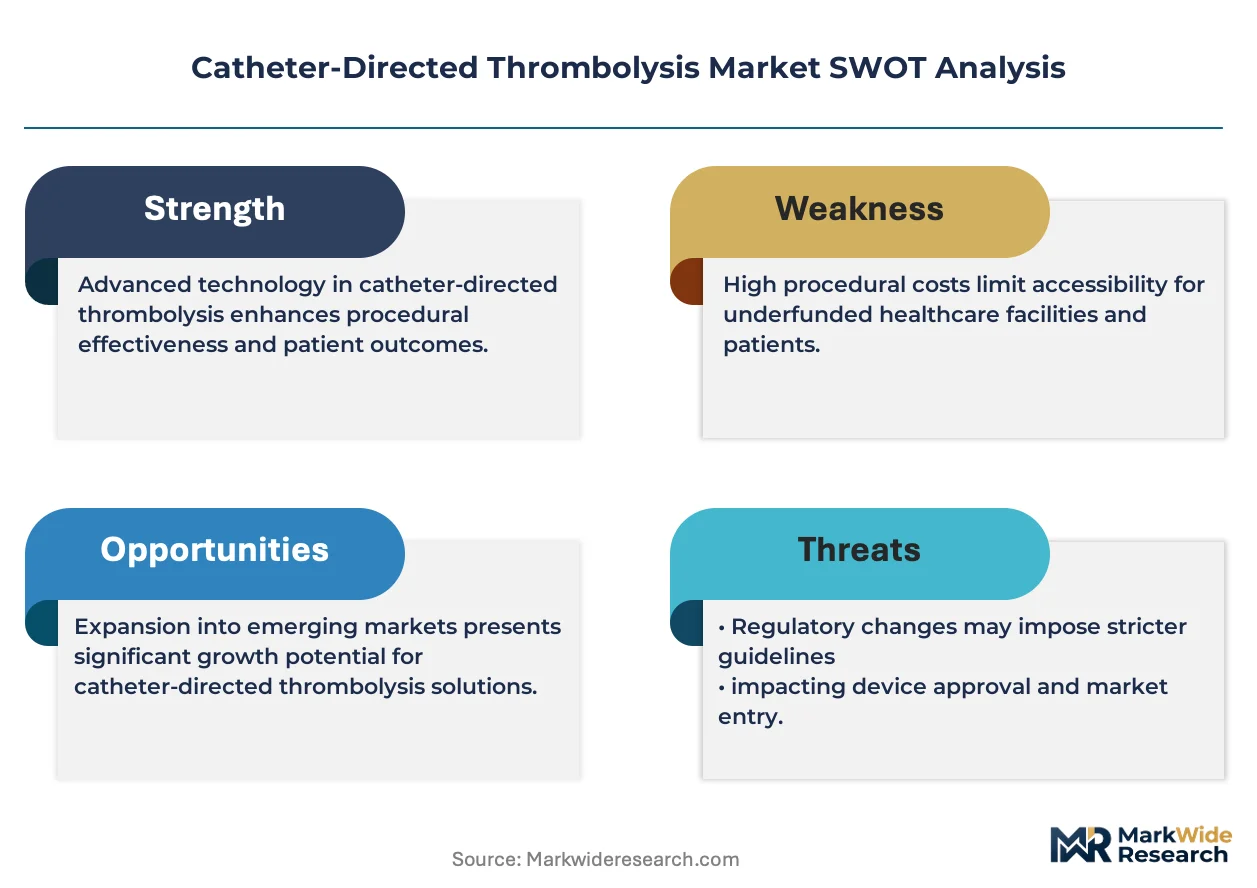
The FDA's combination product regulations and the EU MDR's heightened clinical evidence requirements for class III devices are extending development timelines and consolidating market access around well-capitalized manufacturers. Japan's PMDA maintains distinct reimbursement categorization for ultrasound-enhanced thrombolysis that shapes technology adoption patterns in that market. Stakeholders must monitor evolving CMS hospital outpatient prospective payment system rates for catheter-directed thrombolysis procedures, as reimbursement compression would force device pricing concessions or shift site-of-care toward ambulatory surgical centers.
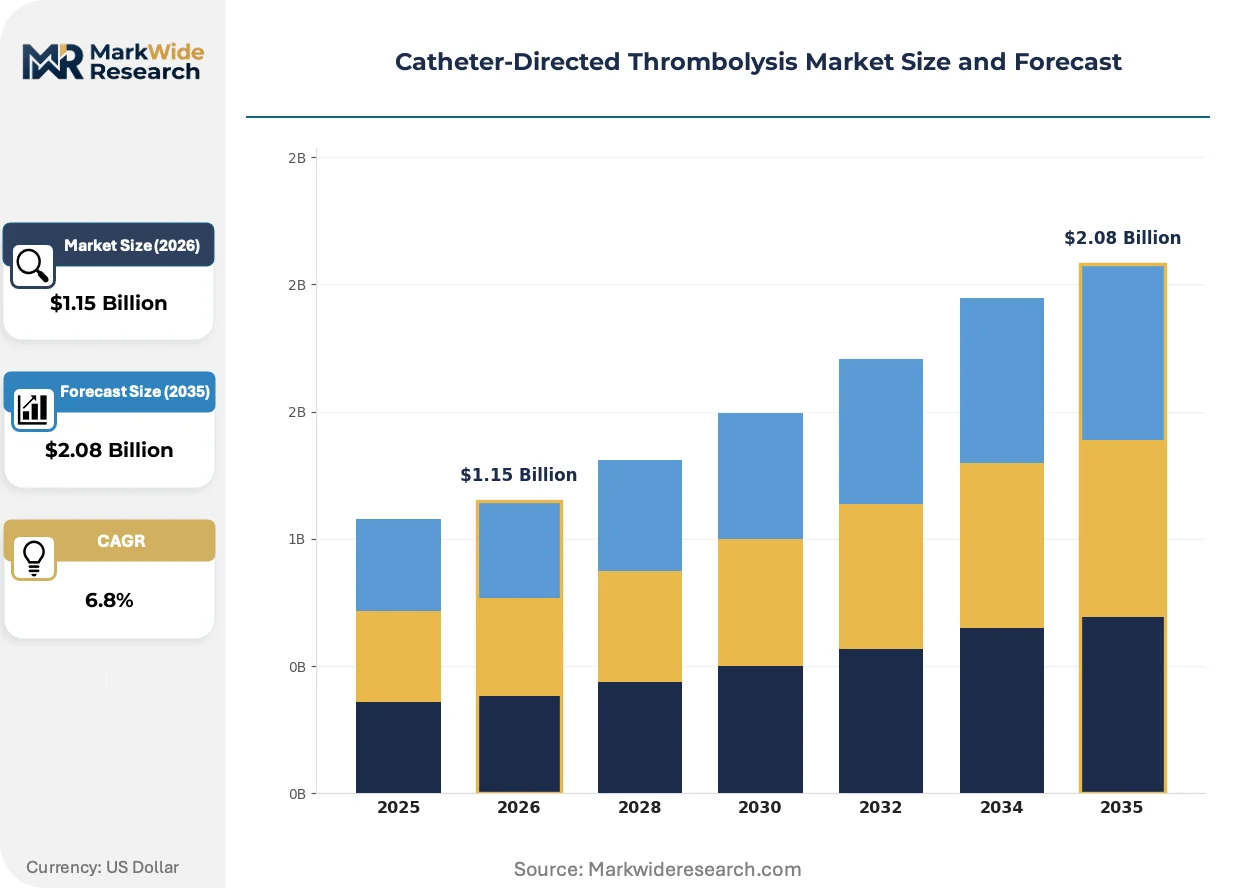
Market Dynamics
Hospital emergency departments are decoupling from traditional surgical suites as the primary site for acute thrombus management, driven by reimbursement frameworks that favor minimally invasive clot management over open surgical alternatives and the expansion of interventional radiology infrastructure within acute care settings.
Growth Catalysts
- Ultrasound-Enhanced Delivery:Acoustic cavitation technology accelerates lytic penetration into organized thrombus, reducing infusion durations from 24 hours toward 12-hour protocols. Hospital-based interventional radiology departments in the United States and Germany are expanding dedicated pulmonary embolism response teams around this capability.
- Japan's PMDA Reimbursement Distinction:Japan's pharmaceutical and medical device agency maintains separate reimbursement categorization for ultrasound-enhanced thrombolysis, creating direct financial incentives for technology adoption that shape procurement patterns in that market.
- Deep Vein Thrombosis Protocol Expansion:Shifting clinical guidelines now endorse catheter-directed lysis for iliofemoral DVT to prevent post-thrombotic syndrome, expanding addressable patient populations beyond pulmonary embolism into chronic venous disease management.
Market Restraints
- EU MDR Clinical Evidence Burden:The European Union's Medical Device Regulation imposes heightened clinical evidence requirements for Class III devices, extending development timelines and consolidating market access around manufacturers with substantial regulatory affairs infrastructure.
- Thrombolytic Agent Supply Concentration:Recombinant tissue plasminogen activator production concentrates among a limited supplier base, creating input cost volatility and supply security concerns for device manufacturers dependent on coordinated drug-device combination product submissions.
- Systemic Bleeding Risk Profile:The fundamental pharmacological limitation of thrombolytic agents—hemorrhagic complication potential—restricts application in post-surgical patients and those with recent trauma, constraining addressable case mix regardless of delivery technology refinement.
Strategic Opportunities
- Ambulatory Surgical Center Migration:CMS hospital outpatient prospective payment system rate evolution creates structural incentives for site-of-care shift toward ambulatory surgical centers, opening channel expansion opportunities for manufacturers with streamlined capital equipment footprints.
- Pharmacomechanical Hybrid Convergence:Integration of mechanical thrombectomy with localized lytic delivery is unifying treatment modalities, enabling single-session clot clearance that challenges traditional overnight infusion protocols and compresses total treatment economics.
- Isolated Limb Perfusion Specialization:Specialty catheter development for isolated pharmacomechanical perfusion of arterial occlusions represents concentrated margin pools with limited direct competition from balloon catheter commoditization pressures.
Industry Challenges
- Interventional Radiologist Training Pipeline:Procedural complexity and case volume requirements for maintaining thrombolysis competency strain fellowship program output, creating talent scarcity that constrains service expansion even where capital equipment is deployed.
- Combination Product Regulatory Navigation:FDA's evolving premarket submission pathways for drug-device combination products demand simultaneous pharmaceutical and engineering expertise within regulatory affairs functions, elevating compliance costs and timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter-Directed Thrombolysis Market |
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Infusion Catheters, Guide Catheters, Specialty Catheters Technology: Ultrasound-assisted, Pharmacomechanical, Conventional, Laser-assisted Delivery Mode: Intra-arterial, Intravenous, Direct Catheterization, Others End User: Hospitals, Ambulatory Surgical Centers, Clinics, Emergency Departments |
| Companies Covered | Boston Scientific, AngioDynamics, Medtronic, Terumo, Teleflex, Stryker, Cook Medical, Penumbra, Inari Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter-Directed Thrombolysis Market Strategic Shifts
Device architecture is converging around hybrid pharmacomechanical platforms that compress treatment duration while regulatory frameworks increasingly differentiate reimbursement based on technology modality rather than procedural outcome alone.
Multi-sidehole infusion catheter design is unifying localized drug delivery with aspiration capability, enabling simultaneous lytic instillation and thrombus extraction. Academic medical centers with established pulmonary embolism response teams are adopting these platforms at accelerated replacement cycles compared with community hospital settings. This convergence is compressing the traditional separation between thrombolysis and thrombectomy service lines within vascular surgery and interventional radiology departments.
The FDA's combination product regulations are reshaping commercialization timelines for drug-device thrombolysis systems by requiring coordinated review across device and pharmaceutical evaluation divisions. Manufacturers now face extended premarket approval pathways that demand substantial clinical evidence packages addressing both mechanical performance and pharmacological safety endpoints. This regulatory friction most affects ultrasound-assisted technology platforms where acoustic energy delivery mechanisms introduce novel safety considerations beyond standard infusion catheter evaluation.
Hospital purchasing committees are consolidating vendor relationships around integrated vascular portfolios rather than acquiring standalone thrombolysis devices. Interventional radiology departments increasingly specify platform compatibility with existing cath lab infrastructure as a primary selection criterion, displacing point-product procurement. This behavioral shift is most visible in United States health systems where Boston Scientific and Medtronic leverage electrophysiology and deep vascular franchise relationships to cross-sell thrombolysis platforms.
Catheter-Directed Thrombolysis Market Segmentation
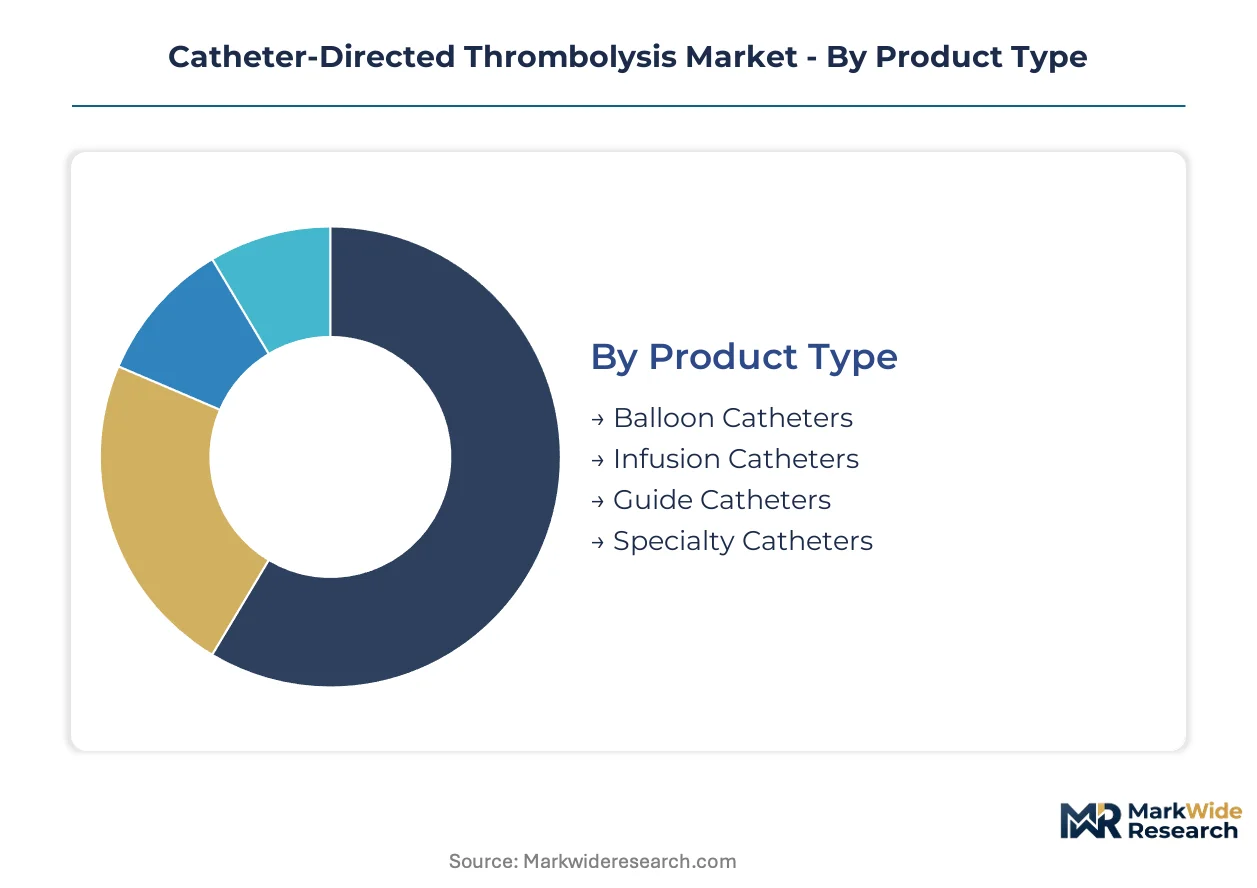
Catheter-directed thrombolysis devices stratify across four distinct taxonomies that determine regulatory pathway complexity, capital intensity, and site-of-care economics. Manufacturers navigate divergent FDA premarket submission requirements depending on whether platforms incorporate drug-device combination status, energy delivery mechanisms, or purely mechanical infusion capabilities.
Product Type:
FDA combination product classification hinges on whether catheter designs incorporate drug delivery lumens, balloon occlusion elements, or specialized sidehole geometries that trigger pharmaceutical co-review.
- Balloon Catheters:These devices integrate occlusion balloons with infusion lumens to achieve isolated thrombolytic delivery while preventing systemic agent dispersion. United States interventional radiology departments leverage existing percutaneous transluminal angioplasty infrastructure, driving procurement concentration among health systems with established cath lab footprints.
- Infusion Catheters:Multi-sidehole designs distribute thrombolytic agents across clot length through 4-6 French access sheaths, with infusion durations historically spanning 12-24 hours. Germany's hospital reimbursement framework favors these systems for deep vein thrombosis protocols given established clinical evidence bases and predictable episode economics.
- Guide Catheters:Access platforms enabling coaxial delivery of thrombolytic infusion systems and adjunctive mechanical devices.
- Specialty Catheters:Isolated limb perfusion configurations targeting arterial occlusions with limited direct competition from commoditized balloon alternatives.
Balloon catheters sit at the top of the volume ranking, with specialty catheters climbing the fastest as manufacturers target concentrated margin pools in complex arterial applications.
Technology:
Cost tier stratification separates premium energy-enhanced platforms from conventional mechanical infusion, with reimbursement differentiation in Japan and Germany accelerating technology migration.
- Ultrasound-assisted:Acoustic cavitation technology accelerates lytic penetration into organized thrombus, compressing infusion protocols toward 12-hour durations. Japan's PMDA maintains distinct reimbursement categorization for ultrasound-enhanced delivery, creating direct financial incentives that shape procurement patterns in that market.
- Pharmacomechanical:Hybrid platforms integrate mechanical thrombectomy with localized lytic delivery, enabling single-session clot clearance that challenges traditional overnight infusion economics. United States pulmonary embolism response teams are expanding dedicated programs around these systems given total treatment cost compression.
- Conventional:Passive infusion without energy enhancement or mechanical adjunct, occupying standard reimbursement tiers.
- Laser-assisted:Photothermal energy delivery to augment thrombolytic penetration in recalcitrant occlusions.
Conventional technology retains the highest installed base, though pharmacomechanical systems are expanding most quickly as hybrid architectures unify service lines.
Delivery Mode:
Application urgency dictates access site selection, with intra-arterial approaches dominating acute limb ischemia while intravenous configurations address pulmonary embolism.
- Intra-arterial:Direct arterial puncture enables targeted lytic delivery to peripheral arterial occlusions and select deep vein thrombosis cases. United States vascular surgery departments favor this approach for acute limb ischemia given rapid revascularization requirements and established femoral access techniques.
- Intravenous:Systemic venous access with pulmonary artery catheter placement for embolus-directed therapy, the dominant configuration for pulmonary embolism response teams. German emergency departments are expanding interventional radiology infrastructure specifically to accommodate intravenous catheter-directed protocols.
- Direct Catheterization:Percutaneous access to thrombosed vessels without traversing remote vascular beds.
- Others:Hybrid and experimental delivery configurations not yet standardized in clinical guidelines.
Intravenous delivery commands the greatest procedure volume, with intra-arterial approaches gaining share fastest as peripheral arterial disease protocols expand.
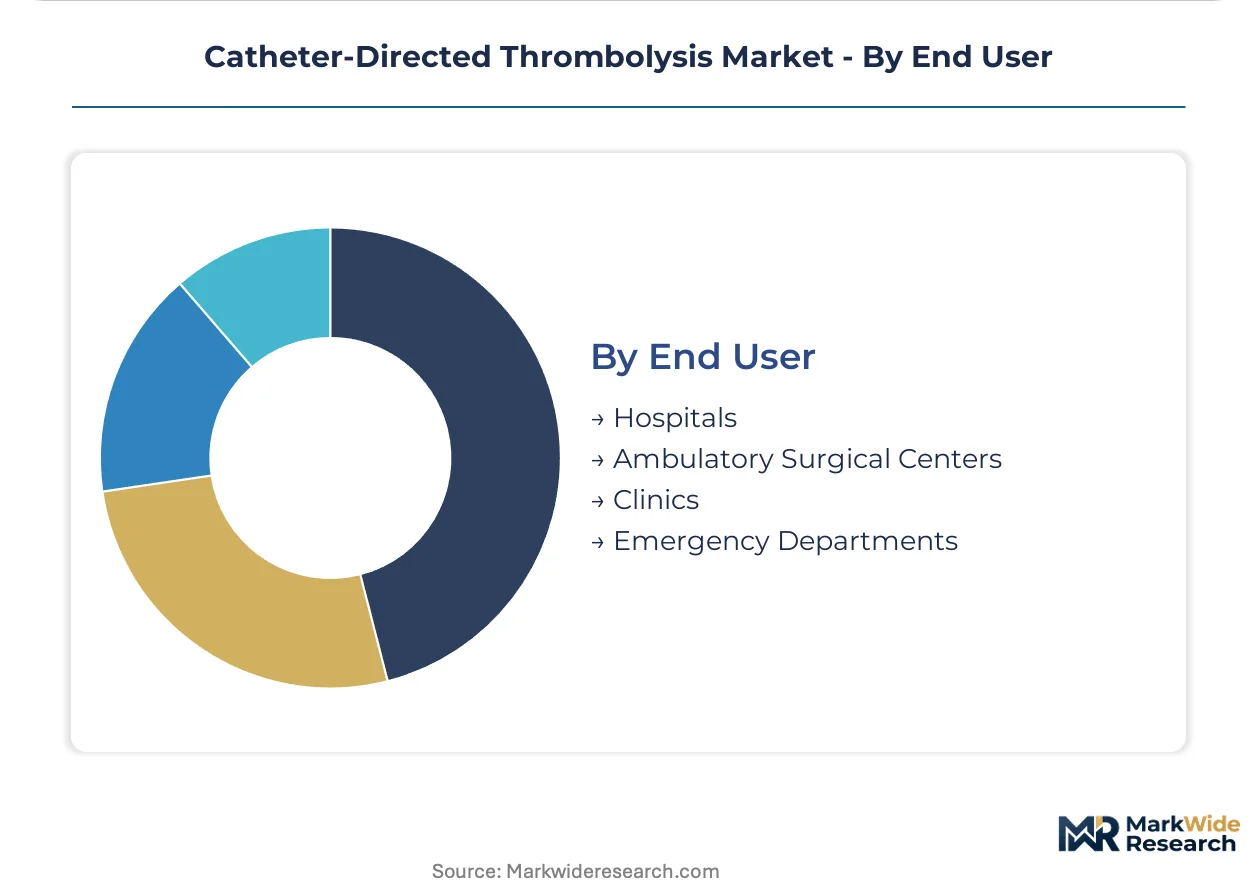
End User:
Customer type determines capital equipment requirements, with hospitals absorbing full cath lab infrastructure while ambulatory settings demand portable, streamlined configurations.
- Hospitals:Interventional radiology departments and vascular surgery services within acute care facilities house the predominant installed base of thrombolysis platforms. United States health systems are consolidating vendor relationships around integrated vascular portfolios rather than acquiring standalone devices.
- Ambulatory Surgical Centers:CMS hospital outpatient prospective payment system rate evolution creates structural incentives for site-of-care migration toward these settings. Manufacturers with streamlined capital footprints are targeting this channel as reimbursement compression forces procedure displacement from inpatient environments.
- Clinics:Outpatient vascular access centers with limited intervention capabilities.
- Emergency Departments:Acute care entry points increasingly decoupling from traditional surgical suites as primary thrombus management sites.
Hospitals retain dominant procedure volume, though ambulatory surgical centers are climbing the fastest as payment reform accelerates site-of-care shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States interventional radiology departments anchor the catheter-directed thrombolysis market, with hospital-based pulmonary embolism response teams expanding across major metropolitan clusters. Germany and Japan follow as concentrated demand centers where reimbursement frameworks favor minimally invasive clot management protocols.
United States
Hospital emergency departments and interventional radiology suites drive procedural volume, with CMS hospital outpatient prospective payment system rates shaping site-of-care economics. FDA combination product regulations extend premarket approval timelines for drug-device thrombolysis systems. The Greater Boston and Minneapolis medical device corridors host concentrated manufacturer headquarters and clinical training infrastructure.
Germany
Deep vein thrombosis protocols in university hospitals favor catheter-directed lysis for iliofemoral cases to prevent post-thrombotic syndrome. EU MDR clinical evidence requirements for Class III devices consolidate market access around well-capitalized manufacturers. The Rhine-Ruhr and Bavarian medical technology clusters sustain physician training density and service expansion across major health systems.
Japan
PMDA maintains distinct reimbursement categorization for ultrasound-enhanced thrombolysis, creating direct financial incentives for technology adoption. METI industrial policy supports domestic medical device innovation through targeted R&D subsidies. The Tokyo-Osaka corridor concentrates interventional radiology infrastructure and specialized pulmonary embolism response capabilities.
United Kingdom
NHS England specialized commissioning frameworks determine access to catheter-directed thrombolysis for acute pulmonary embolism cases. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines for novel devices. The Oxford-Cambridge-London golden triangle anchors academic medical center adoption of hybrid pharmacomechanical platforms.
India
Private hospital chains in metropolitan centers expand interventional radiology departments to capture vascular emergency cases. CDSCO medical device rules impose risk-based classification and registration requirements for thrombolysis catheters. Mumbai and Delhi-NCR clusters concentrate cath lab infrastructure and fellowship-trained interventional radiologists serving high-acuity patient populations.
Catheter-Directed Thrombolysis Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers cross-sell thrombolysis platforms into established cath lab relationships. The market structure concentrates around diversified medical technology conglomerates with deep vascular franchise infrastructure. Three archetypes prevail: integrated electrophysiology-interventional portfolios, specialized neurovascular-peripheral thrombectomy experts, and diversified surgical-device conglomerates. M&A activity and strategic partnerships represent the dominant competitive moves, with technology licensing agreements accelerating pharmacomechanical hybrid convergence.
Within the integrated portfolio tier, Boston Scientific leverages electrophysiology and interventional relationships to anchor thrombolysis platform placement, while Medtronic sustains physician training density through deep vascular infrastructure across major health systems. Penumbra occupies a distinct position as a specialized neurovascular and peripheral thrombectomy expert extending into catheter-directed lytic delivery systems.
| Leading Market Players |
|---|
| Boston Scientific |
| AngioDynamics |
| Medtronic |
| Terumo |
| Teleflex |
| Stryker |
| Cook Medical |
| Penumbra |
| Inari Medical |
| Others |
Value Chain & Pricing Dynamics
Hospital purchasing committee consolidation around integrated vascular portfolios is forcing catheter-directed thrombolysis manufacturers to bundle thrombolysis platforms with cath lab infrastructure, compressing standalone device margins while elevating total contract values. This procurement shift rewards manufacturers with broad electrophysiology and interventional portfolios, penalizing point-product specialists.
Pricing Analysis
Input-cost pass-through from recombinant tissue plasminogen activator supply concentration shapes catheter-directed thrombolysis pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels separates ultrasound-assisted platforms with distinct PMDA reimbursement categorization from conventional infusion catheters and commodity balloon configurations. Cost compression in standard-tier mechanical devices is intensifying because EU MDR clinical evidence requirements extend development timelines and consolidate procurement around well-capitalized manufacturers with regulatory affairs infrastructure. Ambulatory surgical centers exhibit highest price sensitivity as CMS outpatient payment system rate evolution forces site-of-care economics scrutiny, while academic medical centers with established pulmonary embolism response teams demonstrate lowest sensitivity given total treatment cost compression priorities.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale health system demand while specialized distributors serve ambulatory surgical center expansion. Manufacturing concentrates in the United States, Germany, and Japan where FDA, EU MDR, and PMDA regulatory infrastructure sustains quality certification density. Nitinol hypotube stock, multi-lumen extrusions, and recombinant thrombolytic agent supply draw from limited qualified supplier bases. Single-source vulnerability in recombinant tissue plasminogen activator production creates input cost volatility and supply security concerns for combination product submissions. Distribution runs through manufacturer direct sales organizations for major health systems and specialized interventional cardiology distributors for mid-tier hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The catheter-directed thrombolysis market reads as a late-cycle quality story where pharmacomechanical hybrid convergence and ultrasound-enhanced delivery protocols are elevating specification requirements toward premium platforms with demonstrated total treatment cost compression.
For Market Incumbents: Cement cath lab infrastructure lock-in by cross-selling thrombolysis platforms through existing electrophysiology and interventional radiology relationships. Deepen vertical integration into recombinant thrombolytic agent supply coordination to mitigate combination product regulatory timeline risk. Expand physician training density across pulmonary embolism response teams to create procedural volume dependencies that resist vendor switching.
For New Entrants and Emerging Players: Launch via ambulatory surgical center channel partnerships targeting CMS payment system rate evolution-driven site-of-care migration. Target isolated limb perfusion specialty catheter segments where concentrated margin pools offer limited direct competition from established balloon catheter manufacturers. Pursue white-label manufacturing arrangements with diversified vascular portfolios seeking to fill thrombolysis gaps without internal R&D investment.
For Investors and Strategic Acquirers: Asymmetric upside sits with pharmacomechanical hybrid platform specialists possessing simultaneous thrombectomy and lytic delivery capabilities. Long-term viability over the next decade hinges on reimbursement strategy execution across evolving CMS outpatient payment categories and EU MDR conformity assessment pathways. Monitor FDA combination product premarket approval timeline compression as inflection indicator for regulatory friction reduction enabling capital-efficient market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacomechanical Platform Convergence | Hybrid architectures unify thrombectomy and thrombolysis service lines, compressing total treatment economics for pulmonary embolism response teams. |
| EU MDR Conformity Assessment Pathway | Class III device clinical evidence requirements consolidate market access around manufacturers with substantial regulatory affairs infrastructure. |
| Hospital System Partnership | Integrated vascular portfolio procurement displaces standalone device acquisition, rewarding cross-selling capabilities across cath lab infrastructure. |
| Reimbursement Strategy Development | CMS outpatient prospective payment system rate navigation determines site-of-care economics and ambulatory surgical center channel viability. |
| Physician Training Program Expansion | Procedural competency requirements for interventional radiologists constrain service expansion, creating talent scarcity that protects incumbent positions. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional radiologists, vascular surgeons, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation against FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis provided cross-verification.
Segment-weighting across product type, technology modality, delivery mode, and end-user categories structured the analytical framework over the projection horizon. Technology migration curves modeled ultrasound-assisted and pharmacomechanical platform adoption against conventional infusion catheter replacement cycles. CAGRs derived from procedure volume growth, ASP evolution by tier, and site-of-care shift elasticity. Reimbursement pathway approval timelines and interventional radiologist fellowship program output constraints served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or recombinant thrombolytic agent supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Cryptogenic Stroke Treatment Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Ischemic Stroke Aspiration Systems Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Global Blood Pressure Cuffs Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Stent-Assisted Coiling Market