
 Mexico Respiratory Devices Market | 2026-2036
Mexico Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Respiratory Devices Market Foresight
Multi-source procurement strategies for critical care ventilators is realigning how Mexican hospital systems manage supplier risk. Medtronic leverages its broad critical care portfolio to sustain institutional contracts across major public health networks. ResMed anchors the sleep apnea therapy segment with dedicated home care distribution channels. Philips Respironics competes through integrated diagnostic-to-therapy workflows that reduce patient handoff friction.
Mexico respiratory devices encompass electromechanical and digital systems engineered to deliver controlled airflow, oxygen concentration, or aerosolized medication with precision parameters including pressure cycling, flow rates, and FiO2 accuracy for therapeutic intervention in obstructive and restrictive pulmonary conditions. The product type dimension shows inhalers and oxygen concentrators commanding stable volume while CPAP machines capture expanding home care margins. Among end users, hospitals retain the dominant installed base though home care represents the fastest structural shift as portable digital technologies enable remote patient management.
COFEPRIS, Mexico's national health regulator, enforces medical device registration and post-market surveillance that shapes import timelines and local manufacturing incentives. NOM standards compliance, particularly NOM-240 for medical device vigilance, dictates labeling, adverse event reporting, and quality system requirements for market access. Stakeholders must monitor pending regulatory harmonization with FDA-registered facilities to anticipate accelerated approval pathways and competitive positioning shifts.
Market Dynamics
Hospital procurement departments in Mexico City and Guadalajara are consolidating ventilator and oxygen concentrator contracts under multi-year framework agreements, compressing supplier margins while demanding integrated service capabilities that reshape competitive positioning across the respiratory device landscape.
Growth Catalysts
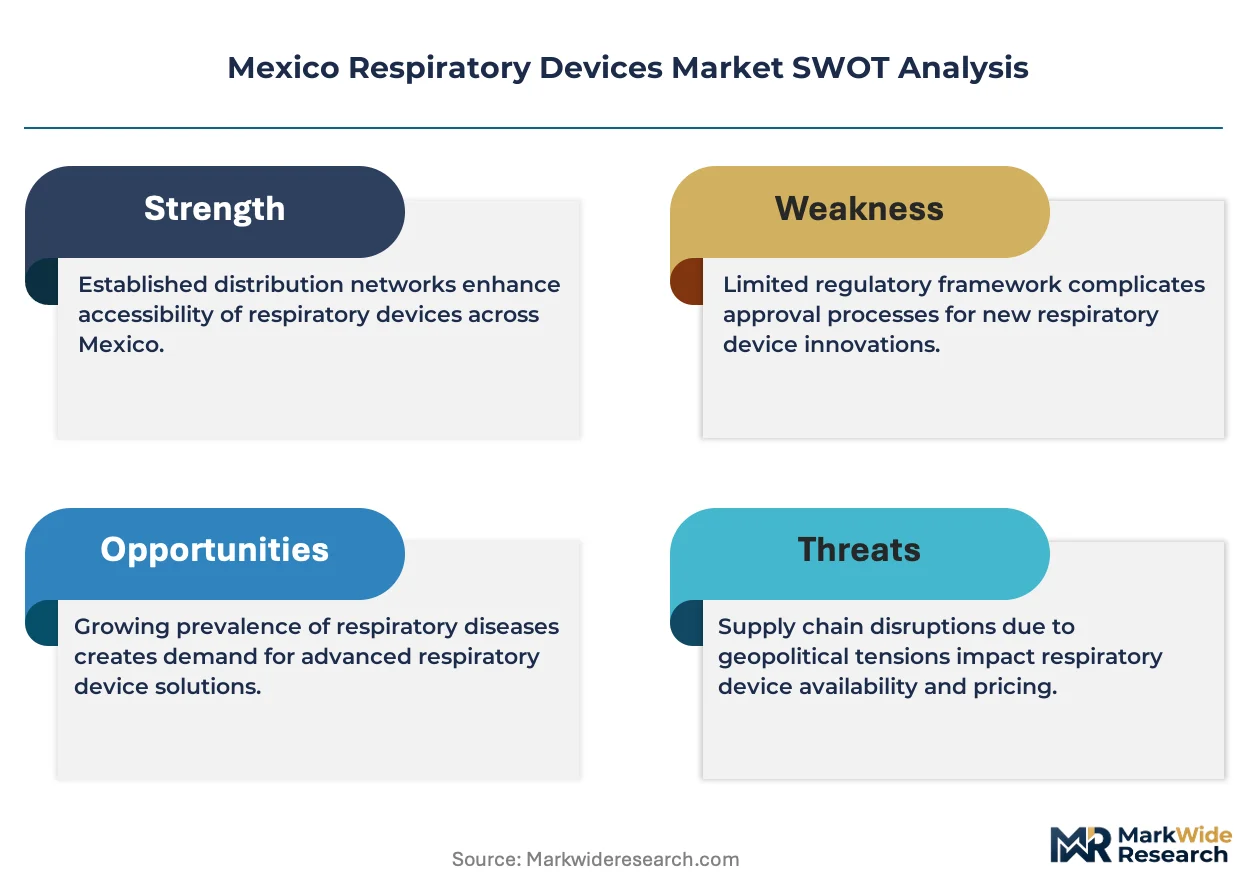
- Chronic respiratory disease prevalence:Rising COPD and asthma diagnosis rates among Mexico's aging population are expanding the addressable patient base for therapeutic devices.
- NOM-240 vigilance framework:Mexico's medical device adverse event reporting mandate is accelerating quality system investments that differentiate compliant suppliers from gray-market competitors.
- Home care infrastructure:Portable oxygen concentrator and CPAP device adoption is shifting treatment delivery from hospital wards to patient residences in Monterrey and Puebla metropolitan zones.
Market Restraints
- COFEPRIS registration timelines:Extended import approval cycles for novel respiratory devices create working capital strain and inventory planning complexity for distributors.
- Semiconductor input volatility:Flow sensor and microcontroller shortages disrupt ventilator production schedules and inflate electronic component procurement costs.
- Concentrated tertiary care demand:Bulk purchasing power concentrates among IMSS and ISSSTE hospital networks, compressing price realization for equipment vendors.
Strategic Opportunities
- Jalisco and Nuevo León expansion:Underpenetrated private hospital networks in Guadalajara and Monterrey offer whitespace for premium respiratory device placement.
- Remote patient monitoring convergence:Integration of pulse oximetry with cloud-based clinician dashboards enables subscription revenue models beyond device sales.
- COFEPRIS-FDA harmonization:Pending mutual recognition agreements for FDA-registered facilities promise accelerated market entry pathways for US-manufactured equipment.
Industry Challenges
- Biomedical technician scarcity:Specialized training for ventilator calibration and preventive maintenance outpaces Mexico's technical education pipeline capacity.
- Legacy system integration:New digital respiratory platforms face interoperability friction with hospital information systems deployed across public health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Respiratory Devices Market |
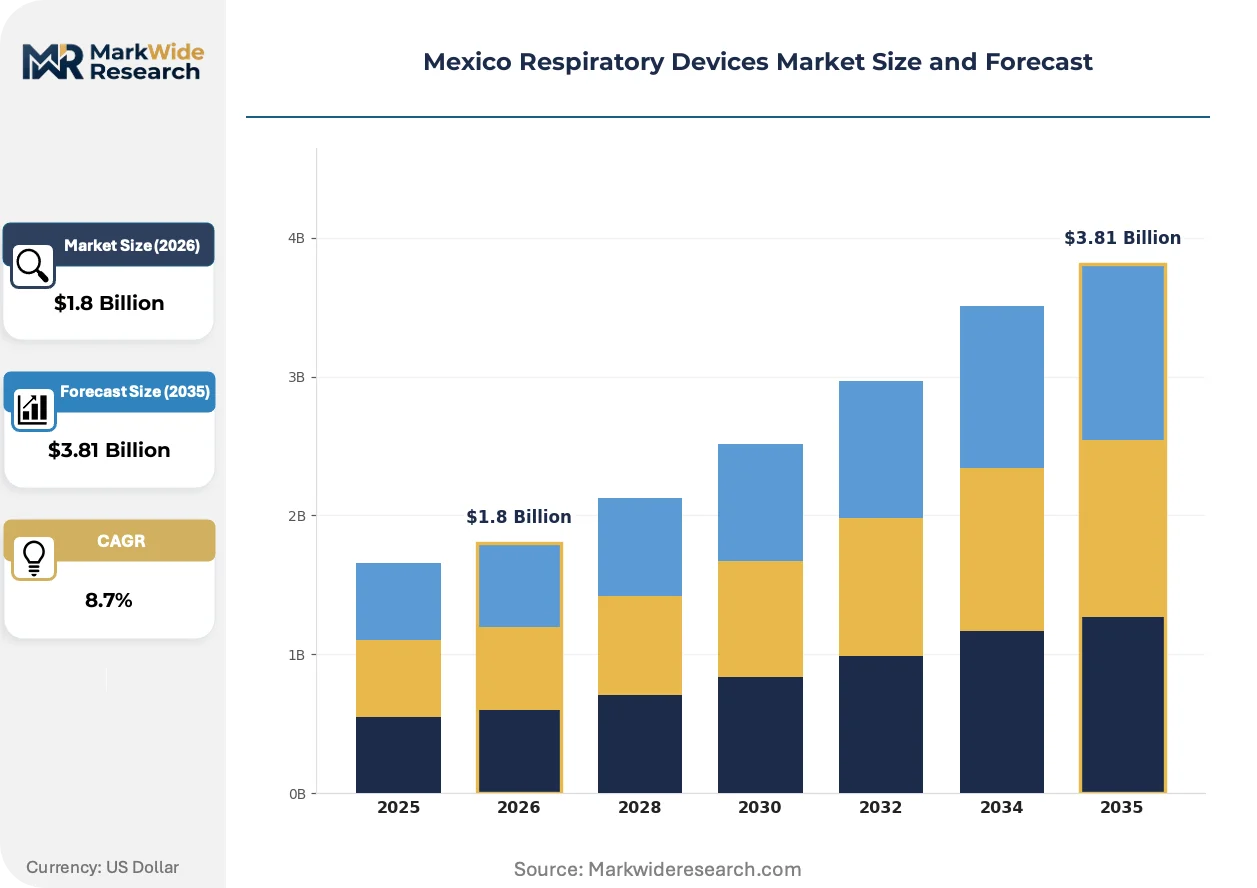
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, CPAP Machines, Oxygen Concentrators End User: Hospitals, Home Care, Clinics, Rehabilitation Centers Technology: Electromechanical, Manual, Portable, Digital Application: Asthma, COPD, Sleep Apnea, Respiratory Distress |
| Companies Covered | Fisher & Paykel Healthcare, Becton Dickinson and Co, Vyaire Medical, Medtronic, Dragerwerk, Philips Respironics, ResMed, GE Healthcare, Teleflex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Respiratory Devices Market Shifts & Advancements
Digital connectivity and portable form factors are redefining where respiratory therapy occurs, shifting clinical oversight from bedside to remote while compressing the traditional hospital-centric supply chain.
Portable oxygen concentrators with battery-operated pulse-dose delivery are decentralizing oxygen therapy from stationary concentrator installations to mobile patient management. Home care providers in Mexico City are deploying these units for post-acute COPD patients, reducing readmission rates while capturing margin that previously flowed to durable medical equipment rental networks.
COFEPRIS is tightening labeling and post-market surveillance requirements under NOM-240, compelling importers to maintain localized adverse event databases and quality management systems. Medical device distributors are responding by establishing in-country regulatory affairs capabilities, with the sleep apnea therapy segment experiencing the steepest compliance cost escalation due to high device turnover and patient follow-up obligations.
Hospital procurement departments are unbundling service contracts from equipment purchases, separating preventive maintenance from capital acquisition decisions. This behavioral shift is most pronounced among private hospital groups in Guadalajara, where clinical engineering directors now negotiate multi-vendor service agreements independent of initial device selection, compressing OEM service attach rates while expanding third-party technical service provider opportunities.
Mexico Respiratory Devices Market Segmentation
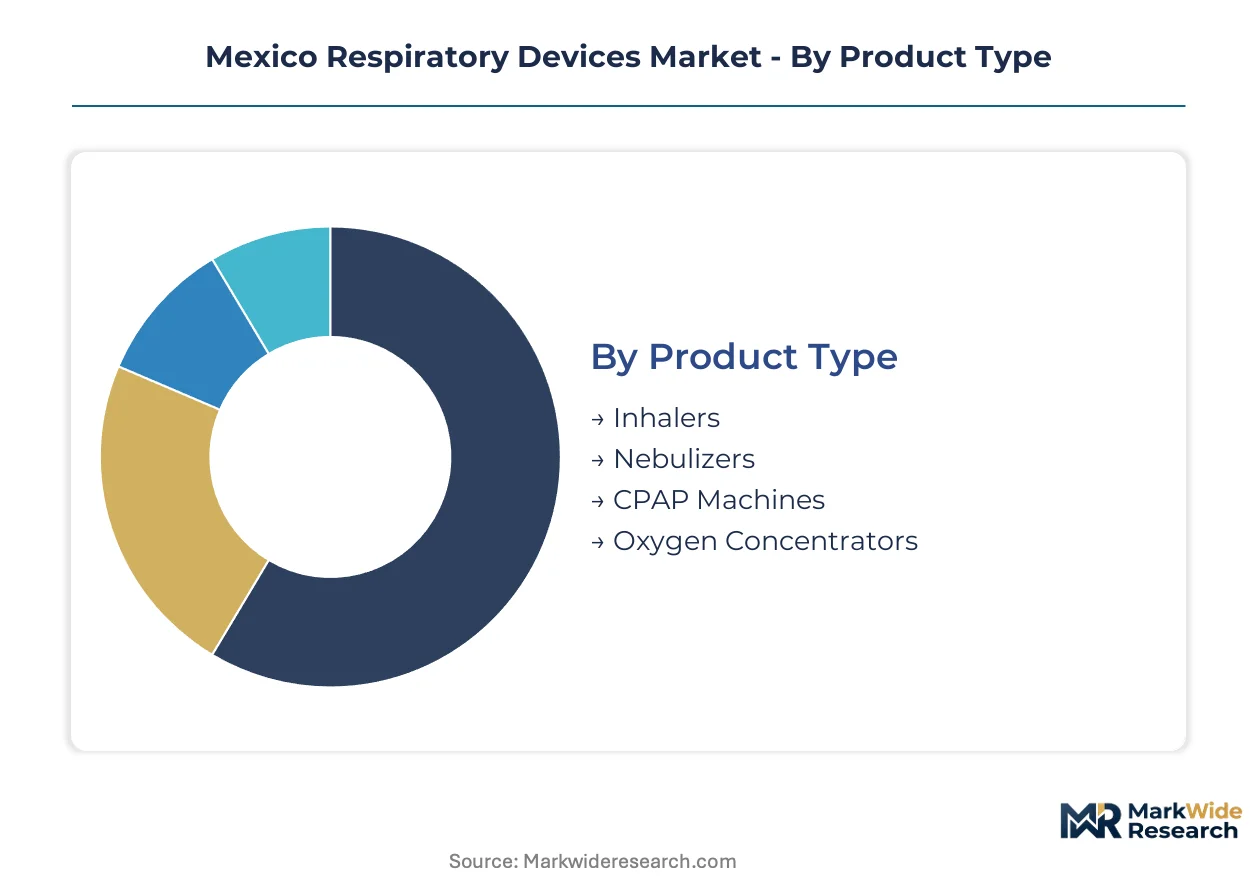
Respiratory device procurement in Mexico stratifies across clinical setting, patient mobility requirements, and disease severity. Manufacturers must align product specifications with COFEPRIS registration pathways and IMSS tender requirements to capture volume across these intersecting dimensions.
Product Type:
Technology sophistication and therapeutic precision define competitive positioning across device categories.
- Inhalers:Pressurized metered-dose and dry-powder inhalers deliver bronchodilators and corticosteroids with particle size optimization for distal airway deposition. Mexico City asthma clinics drive volume through subsidized public health programs while private pharmacies capture retail margin on branded formulations.
- Oxygen Concentrators:Pressure swing adsorption systems separate nitrogen from ambient air to deliver continuous flow oxygen at 90-96% concentration. Stationary units dominate IMSS hospital contracts; portable pulse-dose variants are expanding fastest in Monterrey home care markets where COPD prevalence outpaces clinical bed capacity.
- Nebulizers:Jet and mesh nebulizers aerosolize liquid medication for patients with severe airflow limitation. Pediatric asthma management in Guadalajara tertiary centers sustains institutional demand despite inhaler preference in stable patients.
- CPAP Machines:Continuous positive airway pressure devices maintain pharyngeal patency during sleep. Home sleep testing expansion and private insurance reimbursement growth are accelerating device placement outside traditional polysomnography centers.
Inhalers lead on scale; oxygen concentrators lead on momentum.
End User:
Care setting determines device specification, service intensity, and procurement channel.
- Hospitals:Tertiary facilities in Mexico City and Guadalajara deploy ventilators, high-flow nasal cannula systems, and ICU-grade oxygen concentrators under centralized biomedical engineering management. IMSS and ISSSTE networks exercise consolidated purchasing power that compresses supplier margins.
- Home Care:Portable oxygen concentrators, CPAP devices, and nebulizers shift therapeutic monitoring to patient residences. Durable medical equipment providers in Puebla and Monterrey metropolitan zones are building remote monitoring capabilities to capture recurring revenue beyond device rental.
- Clinics:Primary care and specialty respiratory clinics in Jalisco and Nuevo León utilize diagnostic spirometry and basic nebulization for stable patient management. These settings favor lower-acuity devices with simplified maintenance requirements.
- Rehabilitation Centers:Post-acute pulmonary rehabilitation facilities employ incentive spirometers and oxygen conservation devices to wean patients from hospital-based care. This segment remains underpenetrated relative to acute care infrastructure.
Hospitals dominate installed base; home care is gaining share fastest.
Technology:
Engineering architecture shapes device portability, power dependency, and integration with digital health platforms.
- Electromechanical:Motor-driven compressors and valves enable precise pressure cycling in ventilators and continuous-flow oxygen concentrators. These systems anchor hospital critical care infrastructure but require stable electrical supply and preventive maintenance protocols that strain biomedical technician availability.
- Digital:Microcontroller-based platforms with cellular or Wi-Fi connectivity enable remote parameter adjustment and adherence monitoring. Sleep apnea therapy and home oxygen management are converging on cloud-integrated architectures that support subscription revenue models.
- Portable:Battery-operated pulse-dose oxygen concentrators and travel CPAP units liberate patients from fixed installations. Semiconductor miniaturization and lithium-ion energy density improvements are extending operational duration between charging cycles.
- Manual:Hand-powered resuscitation bags and mechanical inhaler actuators persist in resource-constrained settings and emergency backup scenarios. These devices bypass electrical dependency but sacrifice dosing precision and monitoring capability.
Electromechanical systems anchor hospital procurement; digital platforms are climbing the fastest.
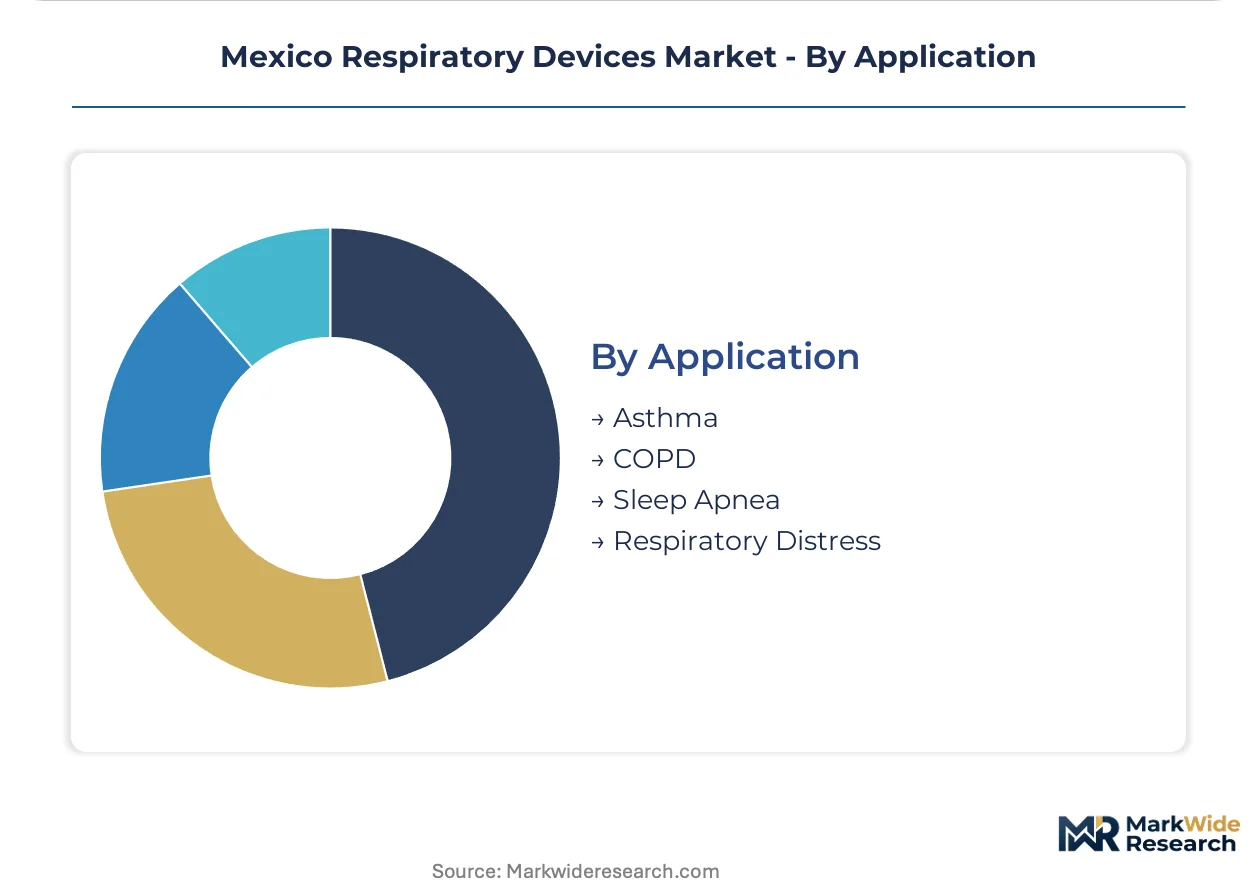
Application:
Disease-specific physiological requirements dictate device selection, pressure parameters, and monitoring intensity.
- COPD:Chronic obstructive pulmonary disease necessitates long-term oxygen therapy and bronchodilator delivery with exacerbation management protocols. Mexico's aging demographic and tobacco exposure history are expanding the addressable patient population across all care settings.
- Sleep Apnea:Obstructive sleep apnea responds to continuous or bilevel positive airway pressure with humidity control. Diagnostic pathway expansion through home sleep testing is reducing time-to-treatment and accelerating device penetration in private insurance markets.
- Asthma:Reversible airway obstruction management emphasizes inhaled corticosteroid adherence and rescue bronchodilator access. Pediatric and adolescent populations in metropolitan zones drive nebulizer and inhaler volume through school-based and primary care programs.
- Respiratory Distress:Acute hypoxemic or hypercapnic failure requires mechanical ventilation and high-flow oxygen delivery. ICU capacity constraints during seasonal respiratory virus surges create cyclical demand spikes for invasive and non-invasive ventilator support.
COPD leads on scale; sleep apnea leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City Metro anchors national respiratory device demand through its concentration of tertiary hospitals and IMSS procurement headquarters.
Mexico City Metro
IMSS and ISSSTE hospital networks drive bulk ventilator and oxygen concentrator procurement through centralized tenders. COFEPRIS maintains its regulatory headquarters here, streamlining registration pathways for distributors serving the metropolitan zone. Tlalpan and Coyoacán districts concentrate biomedical engineering service providers supporting hospital fleet maintenance.
Nuevo León
Monterrey's private hospital expansion and aging industrial workforce expand home oxygen therapy demand. State health authorities coordinate with federal NOM-240 implementation to strengthen post-market surveillance capabilities. San Pedro Garza García hosts regional distribution centers for sleep apnea device providers targeting northern Mexico.
Jalisco
Guadalajara's medical tourism infrastructure and private hospital networks create premium device placement opportunities. COFEPRIS regional offices process import registrations for Pacific coast distribution corridors. Zapopan's clinical engineering clusters support multi-vendor service contract negotiations independent of equipment purchases.
Bajío Region
Querétaro and Guanajuato manufacturing hubs attract respiratory device assembly operations seeking proximity to US export markets. State industrial development programs incentivize local production to bypass import duty structures. León's medical device supplier ecosystem supports component sourcing for regional fabricators.
Northern Border States
Chihuahua and Baja California maquiladora facilities produce electronic subassemblies for ventilator flow sensors and CPAP controllers. Cross-border logistics corridors enable rapid replenishment of semiconductor-dependent components. Tijuana's contract manufacturers serve US OEMs seeking FDA-registered production capacity with Mexican cost structures.
Mexico Respiratory Devices Market Competitive Landscape
Global majors compete with regional champions across procurement channel access, with hospital network contracts concentrating among diversified critical care portfolios and sleep therapy specialists. Market structure tilts toward consolidated institutional supply relationships in Mexico City and Guadalajara, while home care segments sustain fragmented durable medical equipment distribution. Three archetypes dominate: diversified critical care conglomerates, focused respiratory therapy specialists, and regional distribution integrators. Competitive moves center on multi-year service contract unbundling and COFEPRIS registration capability building.
Among diversified critical care portfolios, Medtronic, Philips Respironics, and ResMed occupy anchor positions across distinct therapeutic vectors. Medtronic exemplifies the institutional contract archetype through its breadth of acute care solutions. Philips Respironics represents integrated diagnostic-to-therapy workflow positioning. ResMed anchors the home care specialization tier with dedicated sleep apnea distribution infrastructure.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Becton Dickinson and Co |
| Vyaire Medical |
| Medtronic |
| Dragerwerk |
| Philips Respironics |
| ResMed |
| GE Healthcare |
| Teleflex |
| Others |
Supply & Pricing Matrix
IMSS and ISSSTE hospital network procurement concentration enforces contract-based long-term offtake pricing that compresses supplier margins while demanding integrated service bundling. This buyer archetype dominance forces manufacturers to absorb input cost volatility rather than pass through semiconductor and lithium-ion battery price swings to institutional customers.
Pricing Analysis
Input-cost pass-through remains constrained for ventilator and oxygen concentrator suppliers serving Mexican public health networks. Pricing stratifies across premium, standard, and economy tiers based on COFEPRIS registration tier and after-sales service bundling. Cost compression in the standard tier is intensifying because IMSS tender consolidation demands multi-year price locks. Private hospital groups in Guadalajara exhibit the lowest price sensitivity due to medical tourism revenue premiums, while primary care clinics in Puebla face acute budget constraints.
Supply Chain Analysis
Domestic-content rules under Mexico's manufacturing incentive programs are reshaping sourcing patterns for respiratory device assemblers. Production draws from China, Taiwan, and the United States for flow sensors, microcontrollers, and precision valves. Semiconductor input dependencies and single-source vulnerability for pulse-dose oxygen concentrator chips create inventory planning complexity. Distribution runs through IMSS central warehouses in Mexico City and regional biomedical engineering hubs in Monterrey and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico respiratory devices market functions as a regulatory compounder where COFEPRIS-FDA harmonization milestones are accelerating approval pathways and reshaping competitive entry barriers for imported equipment.
For Market Incumbents: Anchor institutional contracts through preemptive NOM-240 quality system investments that gray-market competitors cannot replicate. Deepen backward integration into ventilator calibration service capabilities to capture unbundled maintenance contracts that Guadalajara private hospitals now negotiate separately from capital purchases. Defend against emerging regional distribution integrators by locking multi-year IMSS framework agreements before harmonization protocols expand FDA-registered competitor access. For New Entrants and Emerging Players: Launch via home care durable medical equipment channels in Monterrey and Puebla where portable oxygen concentrator demand outpaces established supplier coverage. Target sleep apnea therapy whitespace created by ResMed's concentrated Mexico City presence through remote patient monitoring platform differentiation. Pursue reimbursement strategy partnerships with private insurers expanding coverage for cloud-connected CPAP adherence tracking. For Investors and Strategic Acquirers: Hospital system procurement groups are the most active acquirer in this space, consolidating third-party biomedical engineering service providers to internalize maintenance capabilities. The five-to-ten-year viability window favors targets with established COFEPRIS registration infrastructure and IMSS contract relationships over pure technology plays. Watch for COFEPRIS-FDA mutual recognition agreement finalization as the inflection signal triggering accelerated US manufacturer market entry.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Pathway Acceleration | FDA-registered facilities gain expedited market entry under pending harmonization protocols. |
| Hospital System Partnership | IMSS and ISSSTE multi-year framework agreements lock out competitors for ventilator fleet renewals. |
| Software Companion Development | Cloud-based adherence dashboards enable subscription revenue beyond CPAP device sales. |
| Reimbursement Strategy | Private insurance expansion for home sleep testing accelerates diagnostic-to-therapy capture rates. |
| CE Marking Pathway | European regulatory alignment supports dual-market positioning for Mexican assembly operations. |
Research Methodology
Multiple input streams — hospital procurement database analysis, biomedical engineering director interviews, and COFEPRIS registration record review — were reconciled with trade flow documentation and IMSS tender archives. Primary discussions with GPO contracts managers, respiratory therapists, and medical device distributors informed demand-side validation. Secondary sources included SEC filings of listed manufacturers, Mexican customs import records, and hospital equipment procurement disclosures. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated to anchor volume figures.
Data-stream reconciliation across product type, end user, technology architecture, and application severity dimensions shaped the analytical framework. Segmentation modeling captured electromechanical versus digital platform splits, hospital versus home care delivery settings, and COPD versus sleep apnea therapeutic applications. CAGRs were derived from patient population growth trajectories, device replacement cycles, and reimbursement expansion patterns across the projection horizon. Semiconductor supply constraints and NOM-240 compliance cost escalations fed scenario-weighted forecast ranges.
Several conditions sit outside the modeled scope, including pandemic-scale respiratory virus surges, currency crisis impacts on import purchasing power, and abrupt COFEPRIS regulatory reversals. Forecasts reflect documented assumptions about IMSS budget continuity and private hospital expansion timelines in Jalisco and Nuevo León. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Contact Lenses Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Surgical Monitors Market
Medical Devices
Auto Keratometer Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Medical Cyclotron Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Medical Tricorder Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Global Automated External Defibrillators Market