
 Cardiogenic Shock Treatment Market | 2026-2036
Cardiogenic Shock Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiogenic Shock Treatment Market Outlook
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for device manufacturers seeking CE marking for mechanical circulatory support systems. Abbott Laboratories leverages its vertically integrated cardiac portfolio to sustain regulatory compliance across multiple jurisdictions. Medtronic plc anchors its position through manufacturing scale in perfusion and circulatory support technologies. Johnson & Johnson (Abiomed) differentiates via technology leadership in percutaneous ventricular assist devices.
Cardiogenic shock treatment encompasses the clinical management of acute pump failure through pharmacological inotropes, mechanical circulatory support devices, and emergent revascularization procedures, typically requiring intra-aortic balloon counterpulsation or micro-axial flow pumps to maintain end-organ perfusion. Ventricular Assist Devices command the largest product segment due to expanding indications beyond bridge-to-transplant, while Percutaneous Coronary Intervention represents the fastest-growing treatment approach as cath lab capabilities proliferate. Hospitals absorb the majority of procedure volume, though Ambulatory Surgical Centers are capturing select elective revascularization cases as site-of-care economics shift.
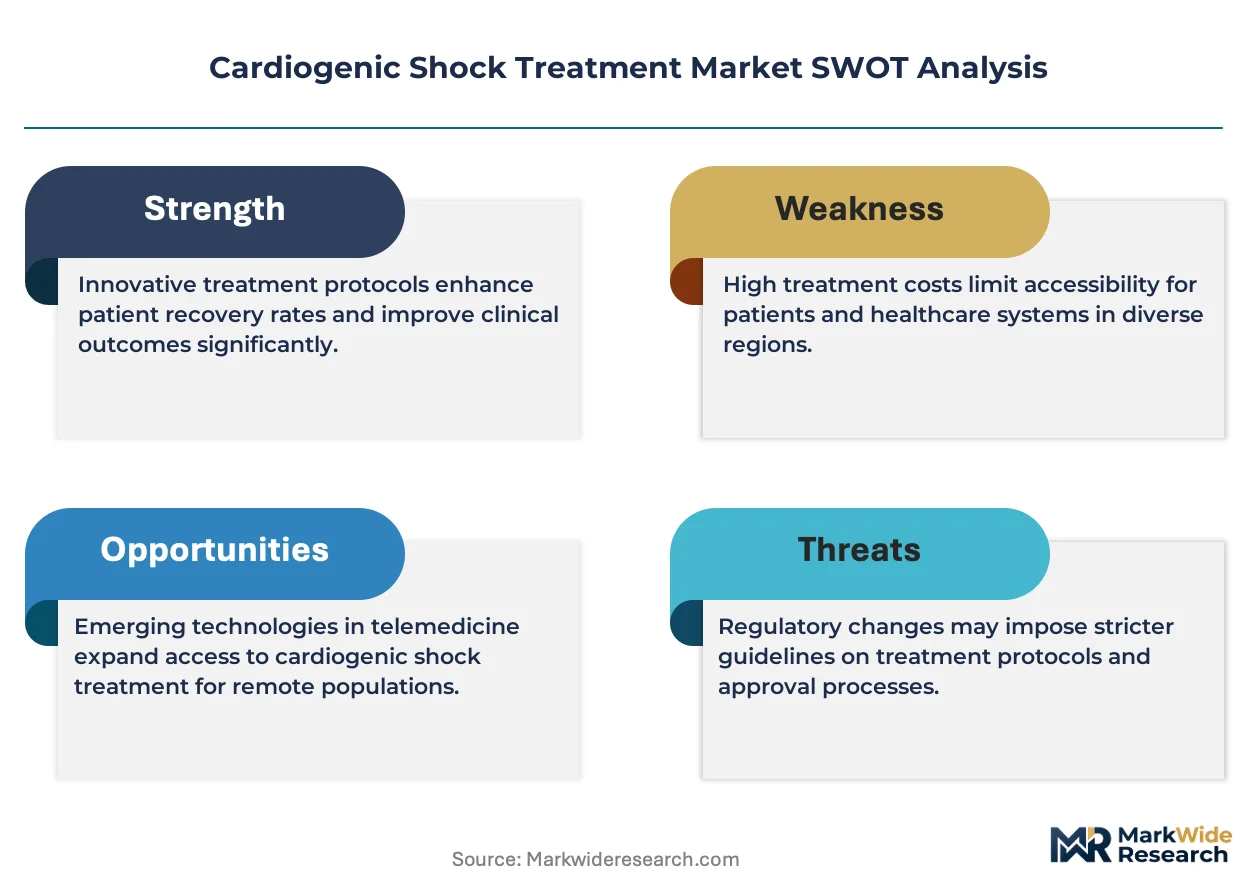
The FDA maintains stringent premarket approval pathways for Class III cardiovascular devices, while the EU MDR demands expanded clinical follow-up data for legacy product recertification. Japan's PMDA imposes additional local clinical trial requirements that extend timelines for multinational manufacturers. Stakeholders must weigh regulatory investment against the margin compression from evolving reimbursement benchmarks for mechanical circulatory support.
Market Dynamics
The EU MDR's expanded clinical evidence mandates for Class III cardiovascular devices are recalibrating capital deployment timelines across mechanical circulatory support portfolios. Manufacturers now face bifurcated investment decisions between legacy device recertification and next-generation platform development.
Growth Catalysts
- Japan's PMDA pathway acceleration:Streamlined approval timelines for breakthrough-designated ventricular assist devices are compressing market entry cycles for percutaneous interventions.
- Cath lab infrastructure proliferation:Urban tertiary centers in the United States and Germany are expanding 24/7 mechanical circulatory support capabilities, elevating intervention volumes for acute myocardial infarction complications.
- Bridge-to-recovery indications:Expanding reimbursement for temporary circulatory support beyond transplant candidacy is unlocking new patient pools in post-cardiotomy and myocarditis recovery protocols.
Market Restraints
- Biocompatibility material constraints:Polyurethane and silicone supply concentration among specialty polymer manufacturers creates input vulnerability for pump membrane production.
- EU MDR legacy recertification burden:Extended clinical follow-up requirements for predicate devices are diverting R&D resources from novel platform innovation toward regulatory maintenance.
- Pharmacological inotrope substitution:High-dose vasopressor protocols in resource-constrained settings continue to displace mechanical support adoption in emerging cardiac care networks.
Strategic Opportunities
- Ambulatory Surgical Center site migration:Selective elective revascularization cases are shifting to outpatient settings in the United States as reimbursement parity expands.
- AI-enabled hemodynamic monitoring convergence:Integration of machine learning algorithms with micro-axial flow pumps is enabling predictive intervention timing and reducing end-organ injury rates.
- Germany's Diagnosis-Related Group refinement:Updated reimbursement codes for complex cardiac interventions are improving margin profiles for hospitals investing in mechanical circulatory support programs.
Industry Challenges
- Perfusionist workforce scarcity:Specialized extracorporeal membrane oxygenation operation requires credentialing pipelines that academic medical centers struggle to fill.
- Interoperability with electronic health records:Device data integration into hospital information systems demands bespoke middleware development, extending implementation timelines.
- Supply chain reconfiguration for dual-source components:Magnet and bearing manufacturers in Japan and Germany require qualification redundancy to mitigate single-point-of-failure risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiogenic Shock Treatment Market |
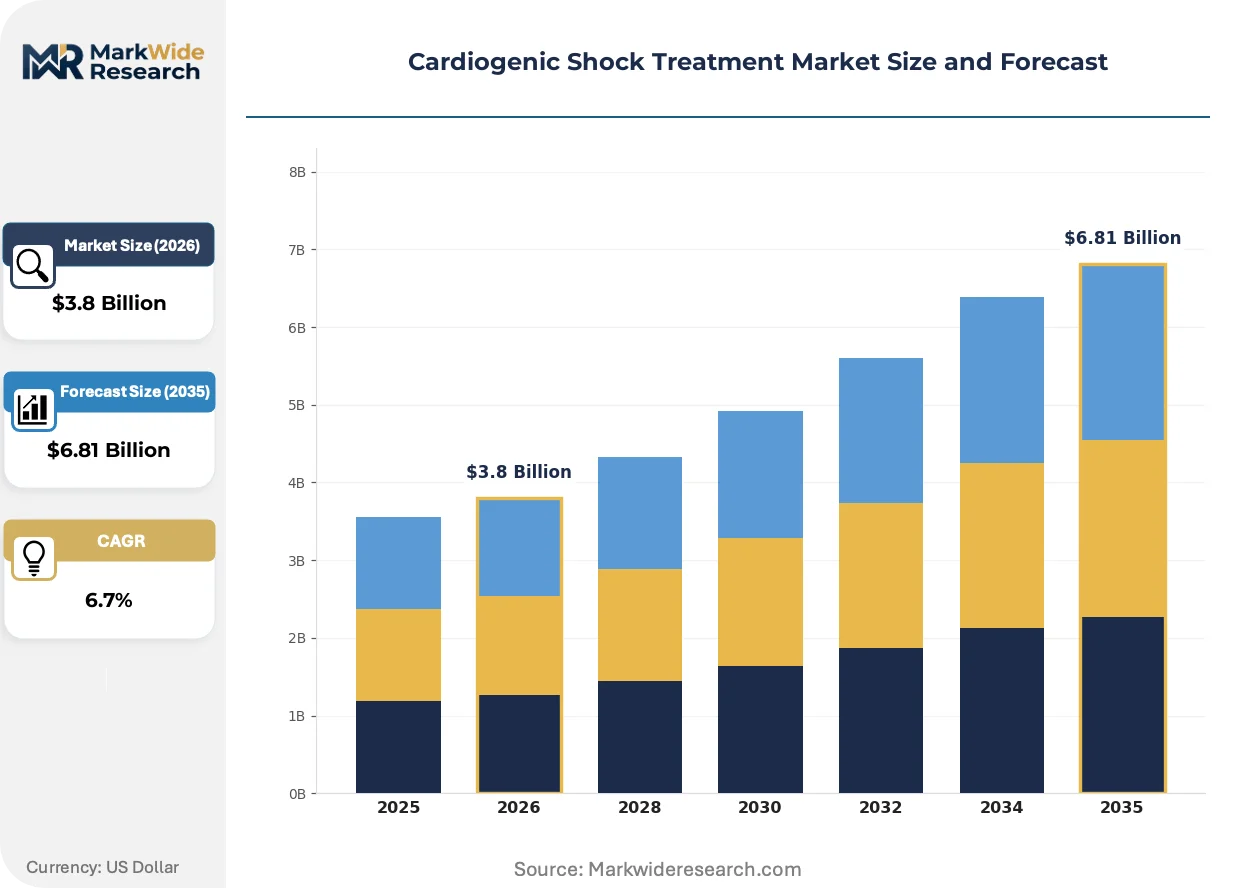
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intra-aortic Balloon Pump, Ventricular Assist Devices, Pharmacological Therapies, Percutaneous Coronary Intervention End User: Hospitals, Cardiac Care Units, Emergency Services, Ambulatory Surgical Centers Treatment Approach: Medical Management, Surgical Intervention, Device Implantation, Revascularization Procedure Type: Elective Procedures, Acute Care Procedures, Post-Operative Care, Emergency Interventions |
| Companies Covered | Abbott Laboratories, Medtronic plc, Johnson & Johnson (Abiomed), Getinge AB, LivaNova plc, Boston Scientific Corporation, Terumo Corporation, ZOLL Medical Corporation, Teleflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiogenic Shock Treatment Market Strategic Shifts
Active innovation in cardiogenic shock management is converging on miniaturization, intelligence integration, and site-of-care flexibility. These vectors are compressing intervention windows while expanding treatable patient populations.
Transvalvular micro-axial flow pumps are electrifying acute mechanical circulatory support by delivering 4-5 liters per minute through 9Fr femoral access. Academic medical centers in the United States and Germany are adopting these platforms for high-risk PCI and acute decompensated heart failure. The technology is electrifying competitive positioning by collapsing the functional gap between percutaneous and surgical ventricular assist alternatives.
The EU MDR's post-market surveillance requirements for legacy cardiovascular devices are forcing systematic clinical data regeneration across mechanical circulatory support portfolios. Manufacturers must now maintain active implant registries with 15-year follow-up protocols for predicate devices. This regulatory pressure is concentrating investment among firms with established European notified body relationships and existing clinical infrastructure.
Hospital purchasing committees are consolidating mechanical circulatory support vendor relationships through single-source agreements that bundle capital equipment, disposables, and technical support. This procurement compression is displacing fragmented multi-vendor arrangements that previously characterized cath lab supply chains. The shift is most pronounced in United States integrated delivery networks and German hospital federations seeking standardized training protocols and volume-based pricing.
Cardiogenic Shock Treatment Market Segmentation
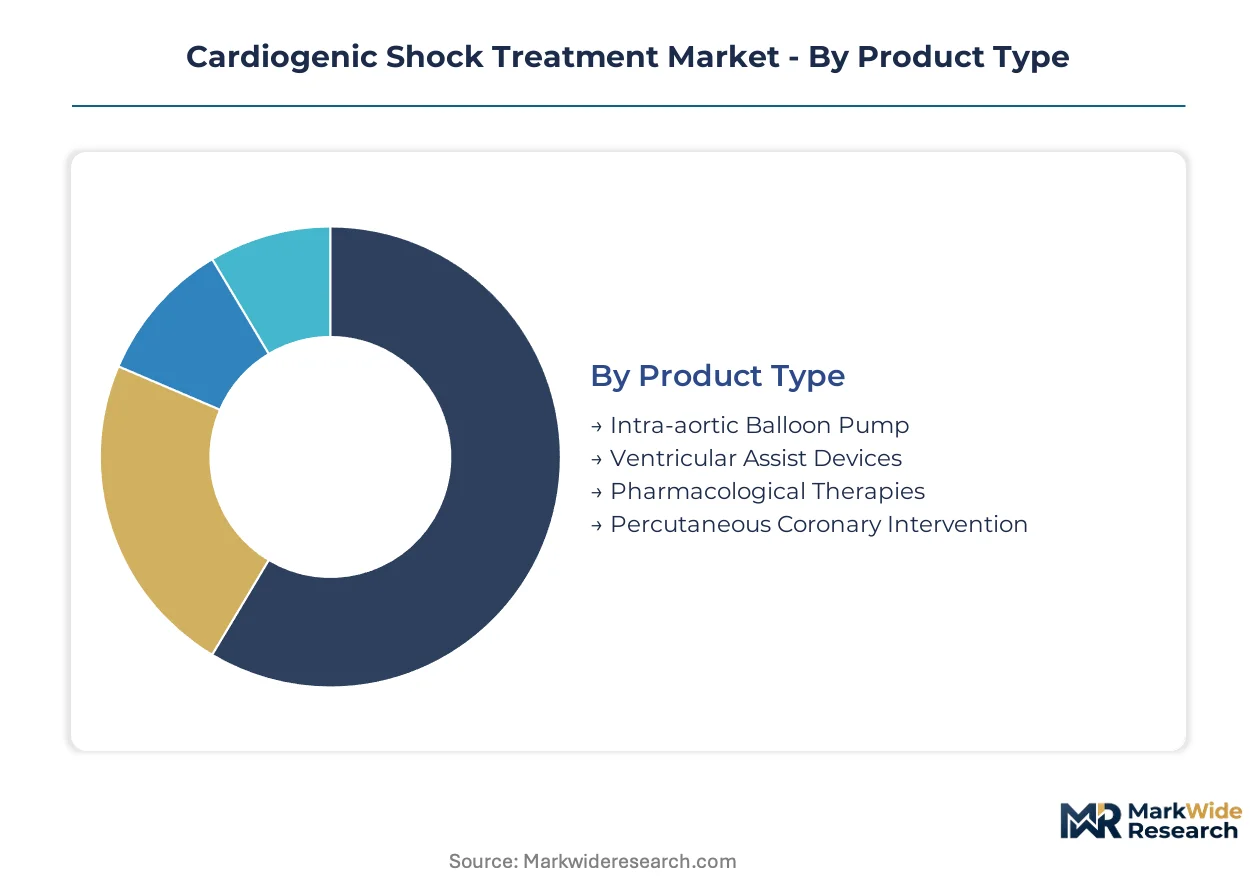
Segmentation in cardiogenic shock treatment reveals distinct technology adoption curves across acute care settings. Product configurations range from standardized pharmacological protocols to highly customized mechanical circulatory support deployments. Understanding these divisions exposes where capital investment concentrates and where reimbursement arbitrage creates margin variation.
Product Type:
Customization intensity spans from off-the-shelf drug formulations to patient-matched device configurations with programmable hemodynamic parameters.
- Ventricular Assist Devices:Implantable or percutaneous pumps deliver 3-10 liters per minute of cardiac output through continuous or pulsatile flow mechanisms. Demand clusters in United States academic medical centers and German heart centers where bridge-to-transplant and bridge-to-recovery protocols require durable mechanical support. The FDA's Class III PMA pathway and EU MDR's clinical evidence mandates favor established manufacturers with active implant registries.
- Intra-aortic Balloon Pump:Counterpulsation technology augments diastolic coronary perfusion through 7.5-8Fr femoral or subclavian access. United States community hospitals and Japanese tertiary centers maintain high deployment volumes for acute myocardial infarction complications, though transvalvular micro-axial pumps are displacing indications in high-risk PCI.
- Percutaneous Coronary Intervention:Catheter-based revascularization with adjunct mechanical support for hemodynamically unstable patients. Cath lab infrastructure expansion in urban United States markets drives utilization.
- Pharmacological Therapies:Inotropic and vasopressor protocols using dobutamine, milrinone, and norepinephrine infusions. Resource-constrained settings in emerging cardiac care networks default to pharmacological first-line management.
Leading the category by volume: Ventricular Assist Devices. Expanding most quickly: Percutaneous Coronary Intervention with integrated mechanical support.
End User:
Capital intensity and staffing requirements create sharp tiering across care delivery sites, from fully equipped surgical centers to mobile emergency platforms.
- Hospitals:Tertiary and quaternary centers with 24/7 cardiac surgery backup, extracorporeal membrane oxygenation capabilities, and multidisciplinary shock teams. United States integrated delivery networks and German hospital federations concentrate procedure volume through standardized training protocols and single-source vendor agreements.
- Cardiac Care Units:Dedicated step-down and intensive care environments with invasive hemodynamic monitoring. Japan's PMDA pathway acceleration for breakthrough-designated devices expands CCU-based percutaneous interventions.
- Emergency Services:Pre-hospital and emergency department stabilization with mechanical CPR and pharmacological protocols. Field deployment of automated CPR devices and rapid transport networks to PCI-capable centers.
- Ambulatory Surgical Centers:Outpatient settings capturing selective elective revascularization cases as United States reimbursement parity expands site-of-care migration.
Hospitals claim the dominant revenue share. Ambulatory Surgical Centers are climbing the fastest as cath lab economics shift toward outpatient settings.
Treatment Approach:
Intervention invasiveness correlates with reimbursement intensity and outcome accountability, creating strategic positioning opportunities across the risk spectrum.
- Device Implantation:Surgical or percutaneous placement of ventricular assist devices, intra-aortic balloon pumps, or temporary extracorporeal support. Requires specialized perfusionist and surgical teams concentrated in high-volume United States and German centers.
- Revascularization:Percutaneous or surgical restoration of coronary perfusion with adjunct mechanical circulatory support. United States urban tertiary centers and German interventional cardiology hubs drive volume through 24/7 cath lab availability.
- Medical Management:Pharmacological optimization without mechanical intervention. Default approach in settings lacking mechanical support infrastructure or for patients with contraindications to device therapy.
- Surgical Intervention:Emergent coronary artery bypass grafting, valve repair, or ventricular reconstruction with cardiopulmonary bypass. Reserved for anatomically complex disease or failed percutaneous approaches.
Revascularization dominates procedure counts. Device Implantation shows the steepest expansion trajectory as temporary mechanical support indications broaden.
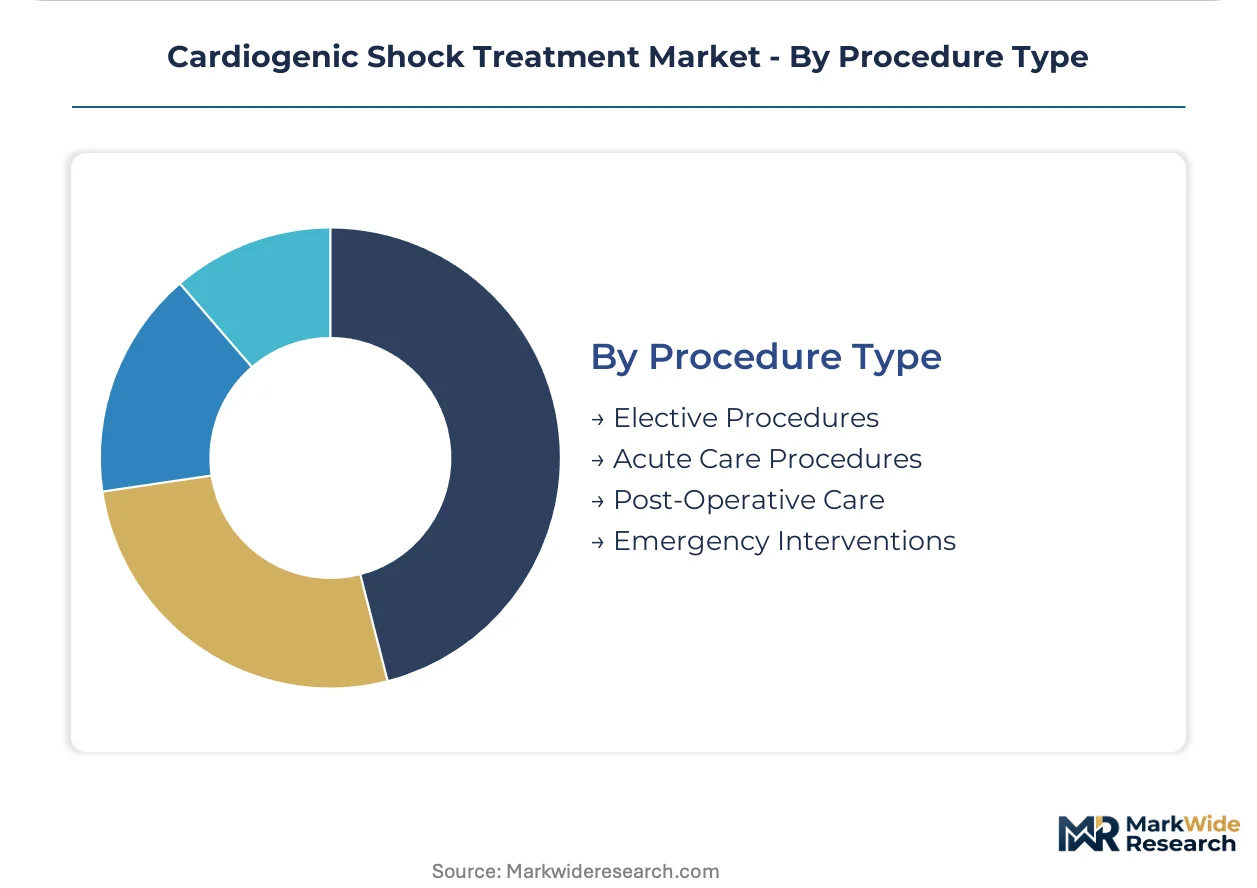
Procedure Type:
Scheduling flexibility versus clinical urgency determines resource allocation patterns and margin profiles across the procedure mix.
- Acute Care Procedures:Urgent interventions for acute myocardial infarction with cardiogenic shock, requiring immediate mechanical support activation. United States and German centers with 24/7 shock teams capture high-acuity volume.
- Emergency Interventions:Unscheduled procedures for acute decompensation, post-cardiotomy failure, or myocarditis. Japan's streamlined PMDA pathways accelerate device availability for emergent indications.
- Elective Procedures:Scheduled high-risk PCI with prophylactic mechanical support or planned VAD implantation. Ambulatory Surgical Centers in United States markets capture select cases as reimbursement evolves.
- Post-Operative Care:Mechanical support for cardiotomy shock or graft failure following cardiac surgery. Concentrated in surgical volume centers with dedicated perfusion and critical care infrastructure.
Acute Care Procedures lead by intervention frequency. Elective Procedures are gaining share fastest as risk stratification tools improve patient selection for outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cardiac care zones in the United States, Germany, and Japan concentrate mechanical circulatory support infrastructure through targeted hospital reimbursement incentives and device innovation clusters.
United States
Integrated delivery networks in Texas and the Northeast Corridor drive ventricular assist device implant volumes through bundled payment models for heart failure episodes. The FDA's Class III PMA pathway for cardiovascular devices maintains stringent premarket evidence standards. The Texas Medical Center in Houston anchors the highest annual mechanical circulatory support procedure counts nationally.
Germany
Heart centers in Bavaria and North Rhine-Westphalia capture complex cardiac intervention volume through refined Diagnosis-Related Group reimbursement codes. The EU MDR demands expanded clinical follow-up data for legacy device recertification across mechanical circulatory support portfolios. The German Heart Center Berlin maintains Europe's largest active implant registry for temporary ventricular assist devices.
Japan
Academic medical centers in Tokyo and Osaka prefectures accelerate percutaneous intervention adoption through PMDA breakthrough-designated device pathways. Japan's pharmaceutical and medical device agency imposes additional local clinical trial requirements that extend multinational manufacturer timelines. The Sakakibara Heart Institute in Tokyo leads Asia-Pacific volumes for transvalvular micro-axial flow pump deployments.
United Kingdom
NHS England's specialized commissioning frameworks concentrate cardiogenic shock care in London and Manchester tertiary centers. The MHRA's post-Brexit regulatory alignment with EU MDR clinical evidence standards affects device market entry timelines. The Royal Brompton and Harefield NHS Foundation Trust maintains the UK's largest extracorporeal membrane oxygenation retrieval service.
France
University hospital clusters in Île-de-France and Auvergne-Rhône-Alpes coordinate national cardiogenic shock networks through the French Society of Cardiology protocols. ANSM oversight of high-risk medical devices requires notified body conformity assessment for Class III circulatory support systems. The Hôpital Européen Georges-Pompidou in Paris anchors France's highest-volume mechanical circulatory support program.
Cardiogenic Shock Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across mechanical circulatory support portfolios, creating a tiered competitive structure. The market consolidates around three to four integrated device manufacturers with active implant registries and established notified body relationships. Strategic archetypes include vertically integrated cardiac portfolio holders, manufacturing-scale perfusion technology anchors, and percutaneous intervention pure-plays. Competitive moves concentrate on regulatory maintenance investments for legacy device recertification and next-generation platform miniaturization.
Among diversified medical technology conglomerates, Abbott Laboratories and Medtronic plc occupy positions as portfolio-scale competitors with broad cardiovascular device footprints. Johnson & Johnson's Abiomed unit exemplifies the focused specialist archetype in percutaneous ventricular assist technology. These three anchors represent distinct strategic postures: integrated cardiac care ecosystems, manufacturing-scale circulatory support infrastructure, and technology leadership in catheter-based hemodynamic support.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Johnson & Johnson (Abiomed) |
| Getinge AB |
| LivaNova plc |
| Boston Scientific Corporation |
| Terumo Corporation |
| ZOLL Medical Corporation |
| Teleflex |
| Others |
Value Chain & Pricing Dynamics
United States integrated delivery networks and German hospital federations concentrate purchasing power through single-source vendor agreements, compressing mechanical circulatory support pricing into bundled contracts that tie capital equipment, disposables, and technical support. This procurement consolidation rewards scale and punishes fragmentation, anchoring a contract-based long-term offtake model where volume commitments secure preferential unit economics.
Pricing Analysis
Premium pricing attaches to devices available on compressed lead times for emergency deployment, while spot inventory of legacy intra-aortic balloon pumps trades at discounts. Three-tier pricing structure across premium transvalvular micro-axial pumps, standard ventricular assist devices, and economy intra-aortic balloon systems differentiates by FDA breakthrough designation and CE marking tier. Pricing pressure stems from EU MDR recertification costs that manufacturers must absorb or pass through. Ambulatory surgical centers exhibit highest price sensitivity due to reimbursement parity constraints; quaternary academic centers show lowest sensitivity given bundled episode payments.
Supply Chain Analysis
Regional distribution centers in the United States Midwest and German industrial corridors maintain hub-and-spoke patterns for just-in-time device delivery to cath labs. Manufacturing concentrates in United States, Germany, and Japan for magnet-bearing assemblies, pump membranes, and control electronics. Polyurethane and silicone for pump membranes draw from specialty polymer producers in Germany and Japan. Single-source vulnerability pervades magnet supply from Japanese rare-earth processors. Distribution runs through manufacturer-direct field inventory systems with hospital consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfusionist workforce scarcity and EU MDR clinical evidence mandates constrain effective supply, propping pricing power for manufacturers with established training infrastructure and active implant registries.
For Market Incumbents: Acquire active implant registry databases and notified body relationships to defend against EU MDR recertification burden diverting R&D resources. Secure backward integration into specialty polymer supply for pump membrane production to mitigate biocompatibility material constraints. Lock in long-term perfusionist training partnerships with academic medical centers to preempt workforce scarcity from limiting procedure volume expansion. For New Entrants and Emerging Players: Telehealth-integrated remote hemodynamic monitoring platforms offer a digital-channel route to bypass capital-intensive cath lab sales cycles. Target ambulatory surgical centers in United States markets where reimbursement parity is shifting site-of-care economics and incumbent presence remains thin. Lead with AI-enabled predictive intervention timing as a software-companion value proposition rather than hardware displacement. For Investors and Strategic Acquirers: The window for entry favors pure-play percutaneous intervention specialists with PMDA breakthrough designation and established European notified body relationships. Long-term viability hinges on regulatory maintenance capabilities rather than novel platform innovation. Watch for EU MDR legacy recertification failures as an inflection signal for distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence mandates recalibrate capital deployment timelines for mechanical circulatory support portfolios. |
| Hospital System Partnership | Single-source vendor agreements with United States integrated delivery networks consolidate procurement and standardize training protocols. |
| Software Companion Development | AI-enabled hemodynamic monitoring convergence enables predictive intervention timing and reduces end-organ injury rates. |
| Reimbursement Strategy | Germany's Diagnosis-Related Group refinement improves margin profiles for hospitals investing in mechanical circulatory support programs. |
| Perfusionist Training Pipeline | Academic medical center credentialing partnerships address workforce scarcity constraining extracorporeal membrane oxygenation expansion. |
Study Parameters
Multi-period observation of mechanical circulatory support implant volumes, cath lab infrastructure expansion, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with perfusionists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA PMA filings, PMDA breakthrough designation records, EU MDR notified body assessment reports, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Input-output matrices mapped device shipments to end-user segments across the projection horizon, modeling product type, treatment approach, procedure urgency, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion curves fitted to mechanical support adoption rates and cath lab capability expansion trajectories. Forecast inputs incorporated EU MDR recertification timelines, Japan PMDA pathway acceleration effects, and United States bundled payment model penetration.
The model holds under stable regulatory enforcement intensity and reimbursement parity evolution; deviation in EU MDR implementation strictness or CMS episode payment expansion would shift manufacturer investment priorities and hospital adoption curves. Forecasts reflect documented assumptions about workforce pipeline development and polymer supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Lower Limb Arterial Stents Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Atherosclerotic Renovascular Treatment Market