
 Cellulose Esters and Ethers Market | 2026-2036
Cellulose Esters and Ethers Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Esters and Ethers Market Intelligence
Consolidation among large-scale pharmaceutical and food processing end-users is realigning procurement strategies for specialty chemical inputs. Eastman Chemical Company leverages its extensive product portfolio to serve these multi-regional buyers. Meanwhile, Shin-Etsu Chemical Co., Ltd. specializes in high-purity grades for niche electronics applications. Dow Inc. competes on manufacturing scale and supply chain efficiency across multiple sectors.
Cellulose esters and ethers are chemically modified derivatives of natural cellulose sourced from wood pulp or cotton linters. The modification process, via etherification or esterification, alters properties like solubility and viscosity, enabling their use as thickeners, binders, and film-formers. Hydroxypropyl Methylcellulose (HPMC) leads in volume due to its widespread application in construction and pharmaceuticals. The food and beverage application segment shows significant expansion, driven by needs for clean-label additives.
The US Food and Drug Administration (FDA) sets stringent purity standards for use in pharmaceuticals and food. Concurrently, the European Union's REACH regulation and China's GB standards dictate chemical registration and market access protocols. Producers must now decide whether to invest in bio-based feedstock innovation or optimize existing production for cost-competitiveness in commoditized segments.
Market Dynamics
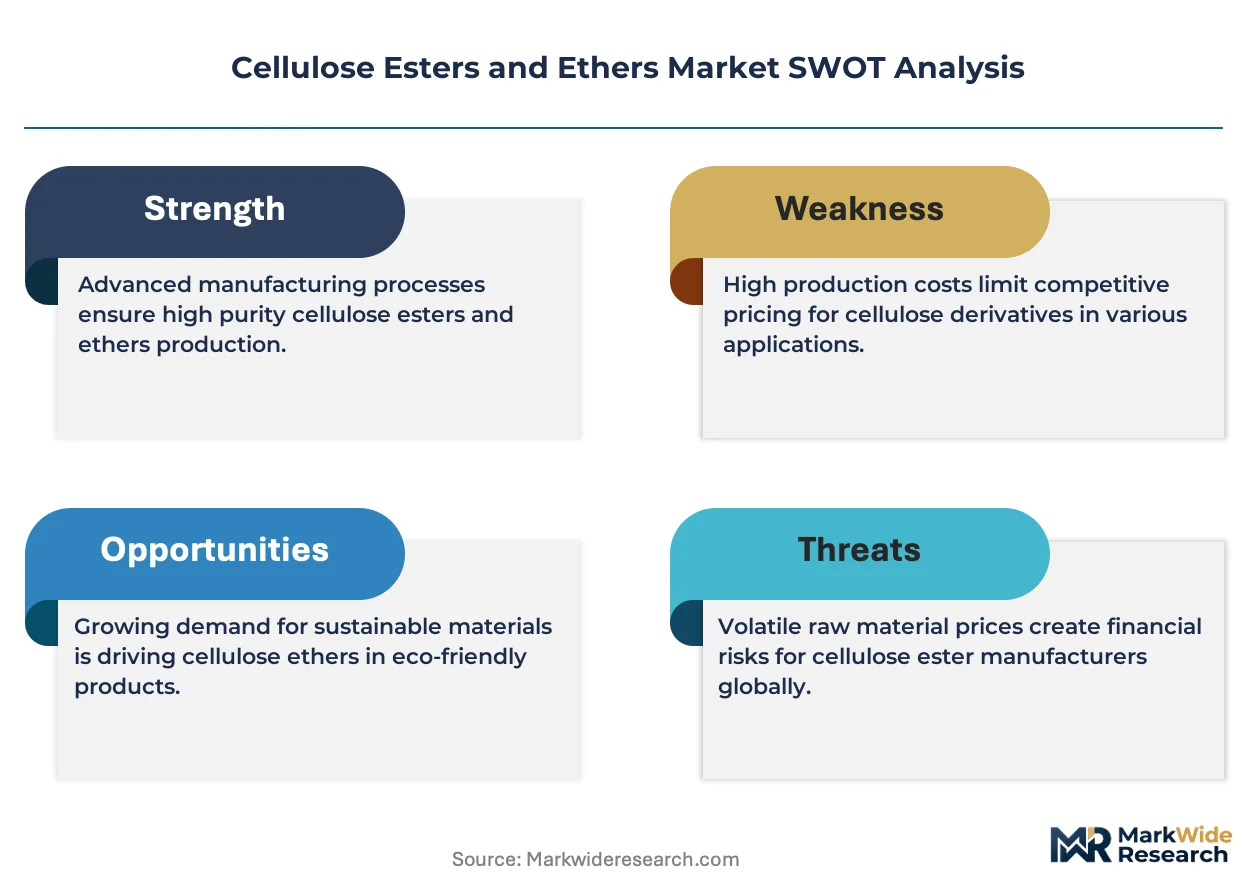
The central dynamic shaping the cellulose esters and ethers market is the persistent tension between its natural, bio-based feedstock origins and the intensive chemical processing required for functionalization, which draws significant regulatory scrutiny from bodies like the EU's ECHA.
Growth Catalysts
- Pharmaceutical Excipient Demand:Stringent regulations from the US FDA and European Medicines Agency (EMA) for drug formulation consistency and safety are driving the use of high-purity cellulose ethers like HPMC as controlled-release agents and binders in oral solid dosage forms.
- Construction Sector Modernization:In emerging economies, the shift from traditional job-site mixing to pre-mixed dry mortars and tile adhesives relies heavily on cellulose ethers for workability, water retention, and adhesion, improving construction quality and efficiency.
- Clean-Label Food Ingredients:Consumer preference for plant-based and minimally processed foods, codified by standards like China's GB regulations, is increasing the use of cellulose derivatives as thickeners, stabilizers, and fat replacers in dairy, bakery, and beverage products.
Market Restraints
- Feedstock Price Volatility:The market is sensitive to price fluctuations in key raw materials like wood pulp and cotton linters, which are influenced by global forestry management policies, agricultural yields, and competing demand from the paper and textile industries.
- Substitution from Synthetic Polymers:In cost-sensitive, lower-performance applications such as basic paints and adhesives, cellulose derivatives face competition from synthetic alternatives like polyacrylates and polyvinyl alcohol, which can offer a lower price point.
- Regulatory Compliance Burden:The significant cost and time required to register new or modified substances under chemical control laws like the EU's REACH regulation can deter innovation and slow the introduction of novel cellulose derivatives to the market.
Strategic Opportunities
- Niche Electronics Applications:There is an opportunity for highly purified and specialized cellulose esters in advanced electronics, such as serving as binders in lithium-ion battery electrodes or as substrates for flexible, biodegradable electronic displays.
- Bio-based Feedstock Innovation:Developing commercially viable processes to source cellulose from agricultural waste (e.g., straw, bagasse) or through microbial fermentation presents an opportunity to diversify away from traditional wood and cotton sources and improve sustainability credentials.
- Pharmaceutical Manufacturing in Southeast Asia:The expanding pharmaceutical production hubs in countries like Vietnam and Indonesia represent an underpenetrated market for suppliers of high-grade, pharmacopeia-compliant cellulose excipients.
Industry Challenges
- Capital-Intensive Purification:Upgrading or constructing manufacturing facilities to meet the increasingly stringent purity requirements for pharmaceutical and food-grade products, as mandated by regulators like the US FDA, demands significant capital investment.
- Global Supply Chain Complexity:Managing a bifurcated supply chain, which involves sourcing raw cellulose from geographically dispersed agricultural or forestry regions while serving industrial end-users in different global manufacturing centers, creates significant logistical hurdles.
- Harmonization of Standards:Producers face the operational challenge of manufacturing products that must comply with multiple, non-equivalent pharmacopeial standards (e.g., USP, Ph. Eur., JP), which complicates production planning and inventory management for global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Esters and Ethers Market |
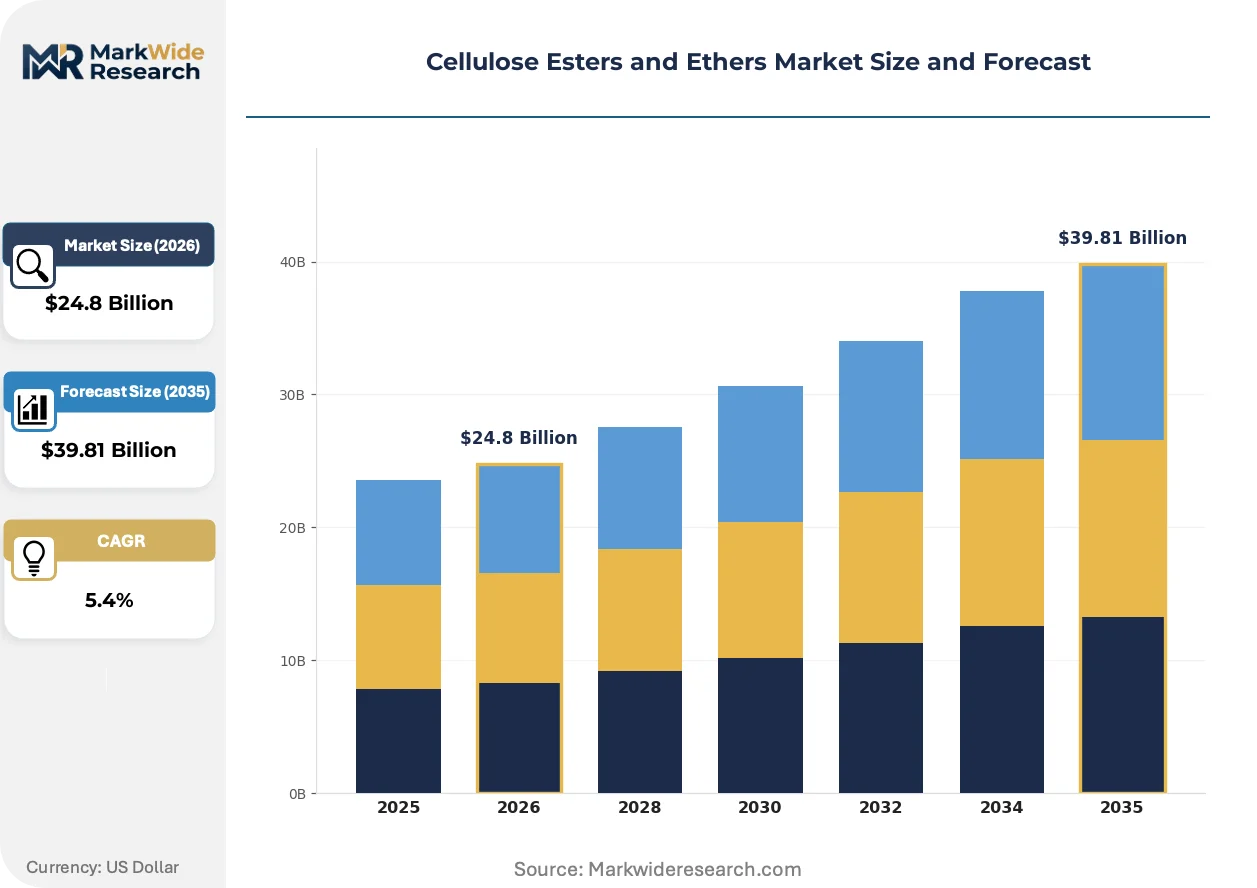
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Acetate, Cellulose Nitrate, Ethyl Cellulose, Hydroxypropyl Methylcellulose Application: Pharmaceuticals, Food & Beverage, Cosmetics, Textiles End User: Manufacturers, Research Laboratories, Healthcare Providers, Food Processing Formulation Type: Coatings, Films, Powders, Gels |
| Companies Covered | Eastman Chemical Company, AkzoNobel, Borregaard AS, Daicel Corporation, Celanese Corporation, Dow Inc, Ashland Global Holdings, Shin-Etsu Chemical Co., Ltd., Rayonier Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Esters and Ethers Market Strategic Shifts & Innovations
Functional specialization is defining the market's trajectory, with producers engineering derivatives for precise performance characteristics in high-value sectors. This shift moves products away from commodity status and toward tailored, application-specific solutions that command higher value.
Multi-functional cellulose ethers combine several properties, such as thickening, water retention, and sag resistance, into a single additive. The construction industry is a primary adopter, using these advanced materials to improve the performance of tile adhesives and self-leveling compounds. This technology is expanding into novel applications like 3D concrete printing, where its ability to provide precise rheological control is essential for layer-by-layer construction.
The European Union's REACH regulation continues to influence market access and product development. Its stringent requirements for chemical safety data are forcing producers to invest heavily in toxicological and environmental impact studies for their entire portfolios. This regulatory pressure particularly affects specialty and low-volume cellulose derivatives, where the high cost of compliance can make production economically unviable, leading to portfolio rationalization.
A notable shift in buying behavior involves large food and pharmaceutical end-users consolidating their supplier base. This trend favors global cellulose derivative manufacturers who can guarantee consistent product quality, provide comprehensive regulatory documentation, and manage a resilient supply chain across multiple continents. This pattern is most pronounced in North American and European markets, where multinational corporations seek to de-risk their procurement of critical raw materials.
Cellulose Esters and Ethers Market Segmentation
Understanding the segmentation of the cellulose esters and ethers market is crucial for identifying specific demand drivers and competitive landscapes. This granular analysis reveals how diverse product forms and applications cater to distinct industry requirements, influencing both procurement and innovation strategies across the value chain.
Product Type:
Buyer decisions for cellulose derivatives often hinge on specific functional requirements for their end products, dictating the choice among various chemically modified cellulose forms.
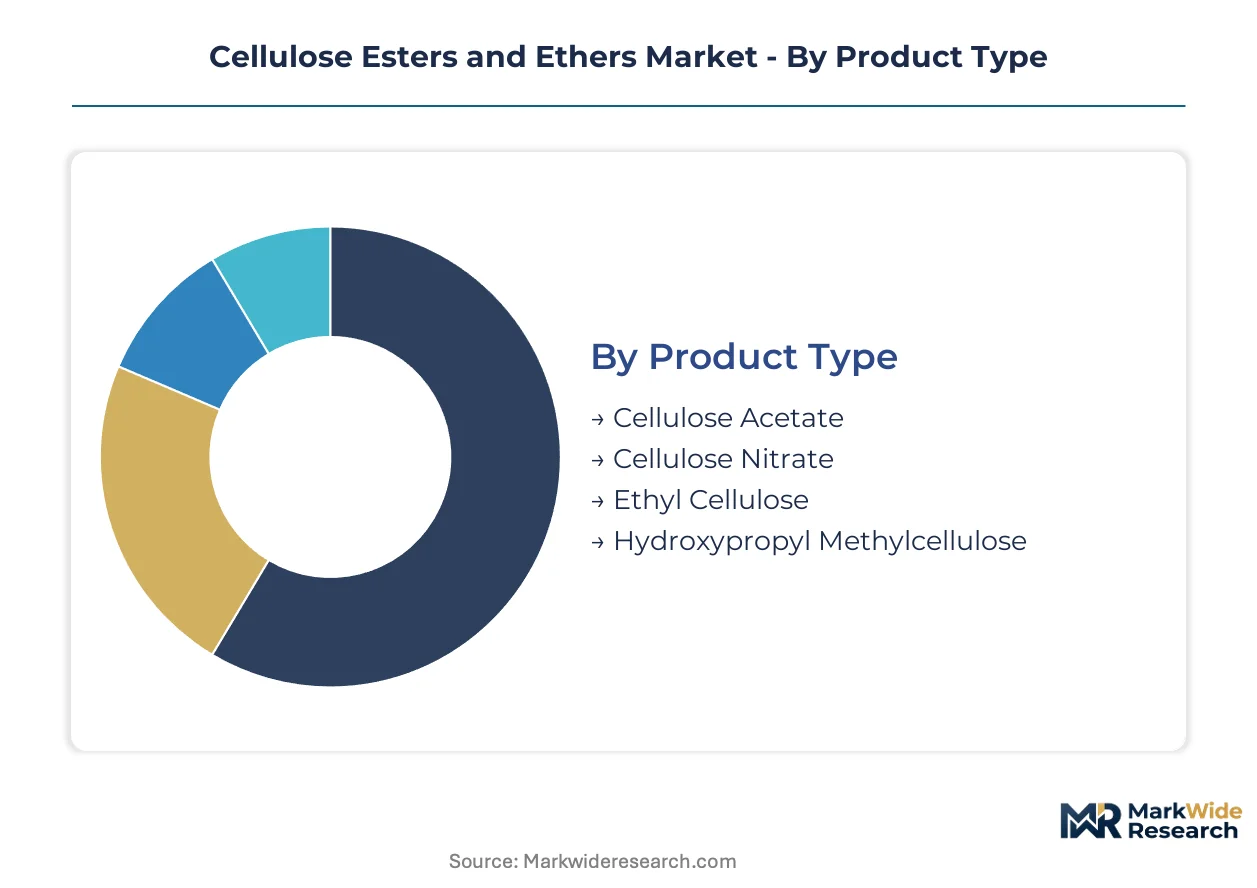
- Hydroxypropyl Methylcellulose:This ether is a non-ionic, water-soluble polymer derived from cellulose, widely used for its thickening, binding, and film-forming properties. Its primary demand stems from the pharmaceutical sector for controlled-release drug formulations and the construction industry for dry-mix mortars in emerging economies.
- Cellulose Acetate:An ester synthesized from cellulose and acetic anhydride, it is known for its clarity, toughness, and biocompatibility, making it suitable for films, fibers, and plastics. Demand concentrates in filtration membranes and specialized electronics applications, where its purity and optical properties are critical.
- Cellulose Nitrate:This highly flammable ester finds applications in lacquers, inks, and propellants due to its rapid drying and film-forming capabilities. Industrial coatings and certain adhesive formulations represent its consistent usage areas.
- Ethyl Cellulose:A water-insoluble, organosoluble cellulose ether, it serves as a binder, film-former, and coating agent in pharmaceutical tablets and food products. Its use in controlled-release systems and hot-melt adhesives drives steady demand.
Volume sits with Hydroxypropyl Methylcellulose; growth tilts toward specialized Cellulose Acetate applications.
Application:
Demand for cellulose esters and ethers is primarily shaped by the performance characteristics required across diverse industrial applications, each with unique regulatory and technical specifications.
- Pharmaceuticals:Cellulose derivatives act as excipients, binders, disintegrants, and controlled-release agents in oral solid dosage forms and topical preparations. Stringent regulations from the US FDA and European Medicines Agency (EMA) compel the use of high-purity grades for drug formulation consistency and safety.
- Food & Beverage:These derivatives function as thickeners, stabilizers, emulsifiers, and fat replacers, contributing to texture, shelf life, and nutritional profiles in various products. Consumer preference for clean-label ingredients and China's GB standards for food additives are significantly expanding this segment.
- Cosmetics:Cellulose ethers provide thickening, emulsifying, and film-forming properties in personal care products like lotions, shampoos, and makeup. Formulators leverage these ingredients for texture enhancement and product stability.
- Textiles:Cellulose esters and ethers are used in textile sizing, printing, and finishing processes to improve fabric strength, drape, and dye uptake. This application maintains a mature but consistent demand profile.
Pharmaceutical applications drive significant value, while food and beverage uses demonstrate the steepest expansion trajectory.
End User:
End-user procurement strategies heavily influence the adoption patterns for various cellulose derivative grades, reflecting their specific operational needs and scale of production.
- Manufacturers:This broad category includes chemical, construction, and general industrial producers integrating cellulose derivatives into their product lines as functional additives. These entities prioritize consistent supply, technical support, and cost-effectiveness for large-volume purchases.
- Food Processing:Companies in this sector utilize cellulose derivatives to enhance the texture, stability, and nutritional aspects of processed foods and beverages. Their purchasing decisions are guided by food safety standards and the need for clean-label compliance.
- Research Laboratories:These facilities use small quantities of high-purity cellulose derivatives for product development, quality control, and scientific investigation. Specificity and analytical certification are paramount for these buyers.
- Healthcare Providers:Hospitals and clinics primarily consume cellulose derivatives indirectly through pharmaceutical products, but also directly in some medical devices or wound care applications. Product safety and regulatory compliance are critical.
Large-scale manufacturers represent the primary consumers, with food processing entities rapidly increasing their consumption.
Formulation Type:
The physical form of cellulose derivatives determines their utility and ease of integration into manufacturing processes, influencing handling, dissolution, and final product characteristics.
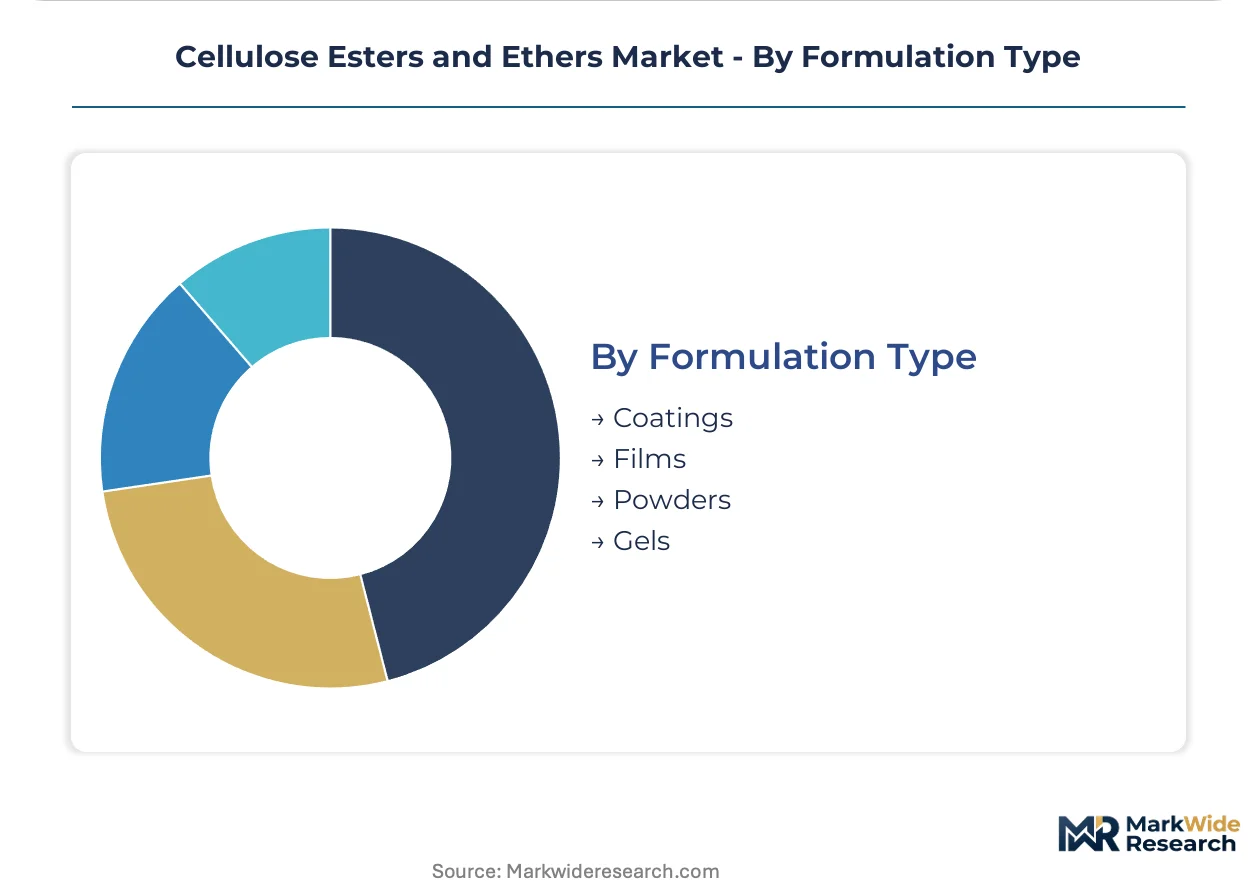
- Powders:This is the most common and versatile formulation, offering ease of storage, transport, and precise dosing across various industrial applications. Powders are widely used in dry-mix construction materials, pharmaceutical tablets, and food ingredient blends due to their excellent dispersibility.
- Films:Cellulose esters are frequently cast into thin, transparent films for packaging, optical applications, and specialized electronic components. Their mechanical strength, clarity, and barrier properties are critical for these high-performance uses.
- Coatings:Cellulose derivatives are applied as protective or functional coatings on substrates in industries ranging from pharmaceuticals to wood and metal finishing. These coatings provide barrier properties, gloss, or controlled release.
- Gels:These viscous, semi-solid formulations are utilized in cosmetics, pharmaceuticals, and some food products for their thickening and stabilizing effects. Gels provide specific rheological properties essential for product texture and application.
Powder formulations dominate industrial usage, while films are gaining share fastest in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cellulose esters and ethers is concentrating in high-growth application segments across key global regions. The pharmaceutical sector, driven by advanced drug delivery needs, and the food and beverage industry, seeking clean-label additives, are primary consumption hubs. Stringent regulatory environments in Europe and North America further shape market dynamics.
China
China's food and beverage industry generates substantial demand for cellulose derivatives as clean-label additives. The nation's GB standards stringently regulate food ingredient purity and market access. Industrial clusters in the Yangtze River Delta actively integrate these materials into processed foods and construction applications.
United States
United States pharmaceutical manufacturers require high-purity cellulose ethers for controlled-release drug formulations. US FDA regulations dictate strict quality and safety standards for all pharmaceutical excipients. Major pharmaceutical R&D and production centers in the Northeast corridor are significant consumers of these specialized materials.
Germany
German construction companies utilize cellulose ethers extensively for high-performance dry-mix mortars and tile adhesives. The EU's REACH regulation imposes rigorous chemical safety and registration requirements on all imported and domestically produced substances. Chemical manufacturing hubs in North Rhine-Westphalia are central to both the production and consumption of these specialized building materials.
India
India's expanding pharmaceutical production hubs represent a growing market for high-grade cellulose excipients. The country's national pharmaceutical regulator sets quality standards for drug formulation ingredients, influencing procurement. Major pharmaceutical manufacturing clusters in Gujarat and Telangana are increasing their consumption of pharmacopeia-compliant cellulose derivatives.
Japan
Japanese electronics manufacturers seek specialized cellulose esters for advanced applications like flexible displays and battery binders. METI guidelines encourage innovation in high-performance materials and sustainable chemical processes. Technology centers around Tokyo and Osaka are driving R&D and consumption of ultra-high purity cellulose derivatives for cutting-edge devices.
Cellulose Esters and Ethers Market Key Industry Players
North American and European producers anchor one tier of the cellulose esters and ethers market; Asian specialists hold another. The market exhibits a tiered structure, with global diversified chemical companies coexisting with regional niche players. Archetypes include large-scale volume manufacturers, high-purity specialty chemical providers, and bio-based feedstock innovators. Strategic partnerships and portfolio diversification are common competitive moves.
Within the global diversified chemical tier, US-based Eastman Chemical Company and Dow Inc. represent significant market presence. Eastman Chemical Company leverages an extensive product portfolio, reflecting its broad market reach across various applications and geographies. Dow Inc. occupies a position characterized by manufacturing scale and supply chain efficiency, serving diverse industrial sectors globally. Japan-based Shin-Etsu Chemical Co., Ltd. exemplifies the high-purity specialist archetype, anchoring its offerings in niche electronics applications and other demanding segments where precision and purity are paramount. These players, alongside others, continually adapt their strategies to evolving regulatory landscapes.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| AkzoNobel |
| Borregaard AS |
| Daicel Corporation |
| Celanese Corporation |
| Dow Inc |
| Ashland Global Holdings |
| Shin-Etsu Chemical Co., Ltd. |
| Rayonier Advanced Materials |
| Others |
Cost & Logistics Intelligence
Bio-based feedstock innovation simultaneously reshapes cost economics and diversifies supply concentration for cellulose derivatives. Investing in sustainable sourcing can command premium pricing while reducing reliance on traditional wood pulp.
Pricing Analysis
Volume-driven segments like construction materials operate on lower margins, while high-purity pharmaceutical grades command significant price premiums. A three-tier pricing structure across premium, standard, and economy levels characterizes the market, driven by quality grade and pharmacopeia-compliant certification. Cost compression in commoditized segments stems from competition with synthetic polymers, making the construction sector highly price-sensitive. Pharmaceutical manufacturers prioritize product consistency and regulatory compliance over price.
Supply Chain Analysis
Certification and qualification requirements from bodies like the US FDA and EMA gate market access, shaping the cellulose derivatives supply chain. Supply concentration for finished products is notable in China, the United States, and Germany, while raw cellulose sources from wood pulp and cotton linters are globally dispersed. The market relies heavily on these bio-based feedstock inputs, with feedstock price volatility representing a significant structural risk. Distribution runs through global manufacturers serving multi-regional buyers, particularly in food and pharmaceutical sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellulose esters and ethers market is fundamentally a cost-of-compliance story. The EU's REACH regulation creates a substantial barrier-to-entry moat for compliant players, favoring those capable of extensive safety data investment.
For Market Incumbents: Anchor existing market share by investing in advanced purification technologies for pharmaceutical and food-grade derivatives. This mitigates the threat from emerging low-cost producers and reinforces regulatory compliance. Deepen vertical integration into bio-based feedstock sourcing to control raw material costs and ensure supply stability. Expand capacity in pharmacopeia-compliant facilities within key growth regions like Southeast Asia.
For New Entrants and Emerging Players: Specialized distributors represent a critical channel for new entrants targeting niche electronics applications. Focus on developing ultra-high purity cellulose esters, an underpenetrated segment with high-value potential. Leverage partnerships with R&D laboratories in Japan to co-develop novel materials for flexible displays. This go-to-market angle bypasses high-volume commodity segments and capitalizes on performance-driven demand.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical manufacturers with strong intellectual property in bio-based innovation or high-purity production capabilities. Long-term viability for this market depends on sustained investment in regulatory compliance and application-specific R&D, extending over the next decade. Target mid-sized firms with established relationships in the pharmaceutical or advanced electronics sectors. The signal to watch is the commercialization rate of cellulose derivatives from agricultural waste.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal objectives for cellulose derivative producers. |
| Capacity Expansion for High-Purity Grades | Addresses growing US FDA and EMA demand for excipients in pharmaceutical formulations. |
| Long-term Supply Agreements for Bio-based Feedstock | Mitigates feedstock price volatility and ensures supply security for global manufacturers. |
| R&D Investment in Multi-functional Cellulose Ethers | Develops tailored solutions for construction sector modernization and 3D concrete printing applications. |
| Geographic Expansion into Southeast Asian Pharma Hubs | Penetrates under-served markets like India and Vietnam for pharmacopeia-compliant cellulose excipients. |
Research Approach
Customs and trade data, SEC 10-K filings, and ACC/Cefic reports formed the secondary backbone for market sizing and trend identification. This was triangulated with primary interviews involving R&D directors, procurement leads at downstream OEMs, and distribution channel partners. These discussions validated market dynamics and pricing structures. Bottom-up and top-down approaches ensured comprehensive data synthesis.
A bottom-up approach estimated market size by aggregating demand across key application segments, complemented by a top-down validation against overall industry growth. This framework projected market value across the analysis window, modeling segmentation dimensions including grade tier, end-use industry, and regional production hub. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected technological advancements, with key inputs including regulatory changes like REACH and global pharmaceutical R&D spending.
Caveats apply where significant shifts in global forestry management policies or new environmental regulations could materially shift the outlook. Forecasts reflect assumptions documented at the time of analysis. A model refresh is warranted upon material change in feedstock availability or major regulatory updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Carnauba Wax Market