
 Bleached Linter Cellulose Market | 2026-2036
Bleached Linter Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Bleached Linter Cellulose Market Analysis
Multi-source procurement of raw cotton linters is consolidating toward vertically integrated pulp processors with captive linter supply. Georgia-Pacific LLC leverages its integrated pulp-to-specialty-chemicals chain to secure linter supply continuity. Shandong Silver Hawk Chemical Fibre Co., Ltd. anchors its position through captive dissolving pulp capacity in Shandong Province. Rayonier Advanced Materials specializes in high-purity cellulose derivatives for regulated end-uses.
Bleached linter cellulose consists of alpha-cellulose derived from cotton seed coat fibers, typically refined to purity levels exceeding 98.5% through alkaline extraction and hypochlorite bleaching sequences for pharmaceutical and food-grade applications. Microcrystalline cellulose dominates value generation due to its irreplaceable function as a direct compression excipient in tablet manufacturing. Filter paper applications sustain stable demand from analytical laboratories and industrial quality control protocols, while granulated cellulose competes in food additive segments where flow properties determine formulation acceptance.
EMA pharmaceutical guidelines, FDA Current Good Manufacturing Practice standards, and REACH chemical registration requirements collectively elevate barrier-to-entry for new bleached linter cellulose suppliers targeting medical applications. Product standards now mandate residual lignin below 0.05% and heavy metal thresholds stricter than food-grade specifications for excipient-grade material. Stakeholders must monitor how EUDR deforestation-free supply chain verification reshapes cotton linter traceability requirements and sourcing economics.
Market Dynamics
The bleached linter cellulose market is consolidating around captive cotton linter supply chains as pharmaceutical-grade purity requirements harden under EMA and FDA enforcement. Processors with backward integration into dissolving pulp production now control material flow into excipient channels.
Growth Catalysts
- MDR compliance deadlines:European medical device manufacturers are stockpiling high-purity cellulose ahead of full MDR implementation, pulling forward excipient-grade volumes.
- Tablet direct compression:Pharmaceutical formulators favor microcrystalline cellulose for its flow and compressibility, locking in demand for refined alpha-cellulose feedstock.
- India:Domestic cotton processing capacity expansion in Gujarat and Maharashtra is reducing import dependency for linter raw material.
Market Restraints
- Input cost volatility:Cotton linter prices fluctuate with monsoon-dependent Indian harvests and global cotton commodity cycles.
- Supply concentration risk:High-purity dissolving pulp capacity clusters in Shandong Province and the US Southeast, creating geographic chokepoints.
- Substitution threat:Wood-derived specialty cellulose from sulfite pulping competes for non-pharmaceutical applications where purity thresholds permit.
Strategic Opportunities
- Brazil:Underdeveloped linter collection infrastructure leaves room for integrated processors to establish captive supply in Cerrado cotton belts.
- EUDR traceability:Early compliance with deforestation-free supply chain verification creates premium positioning for European pharmaceutical sales.
- Food-grade encapsulation:Granulated cellulose for nutraceutical and functional food coatings represents an adjacent growth vector with lower regulatory barriers than drug excipients.
Industry Challenges
- Pharmaceutical certification timelines:FDA Type II drug master file preparation and EMA excipient master file compilation demand 18-24 month lead times before commercial supply.
- Capex intensity:Hypochlorite-free bleaching sequences and closed-loop water systems require substantial capital for environmental compliance upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleached Linter Cellulose Market |
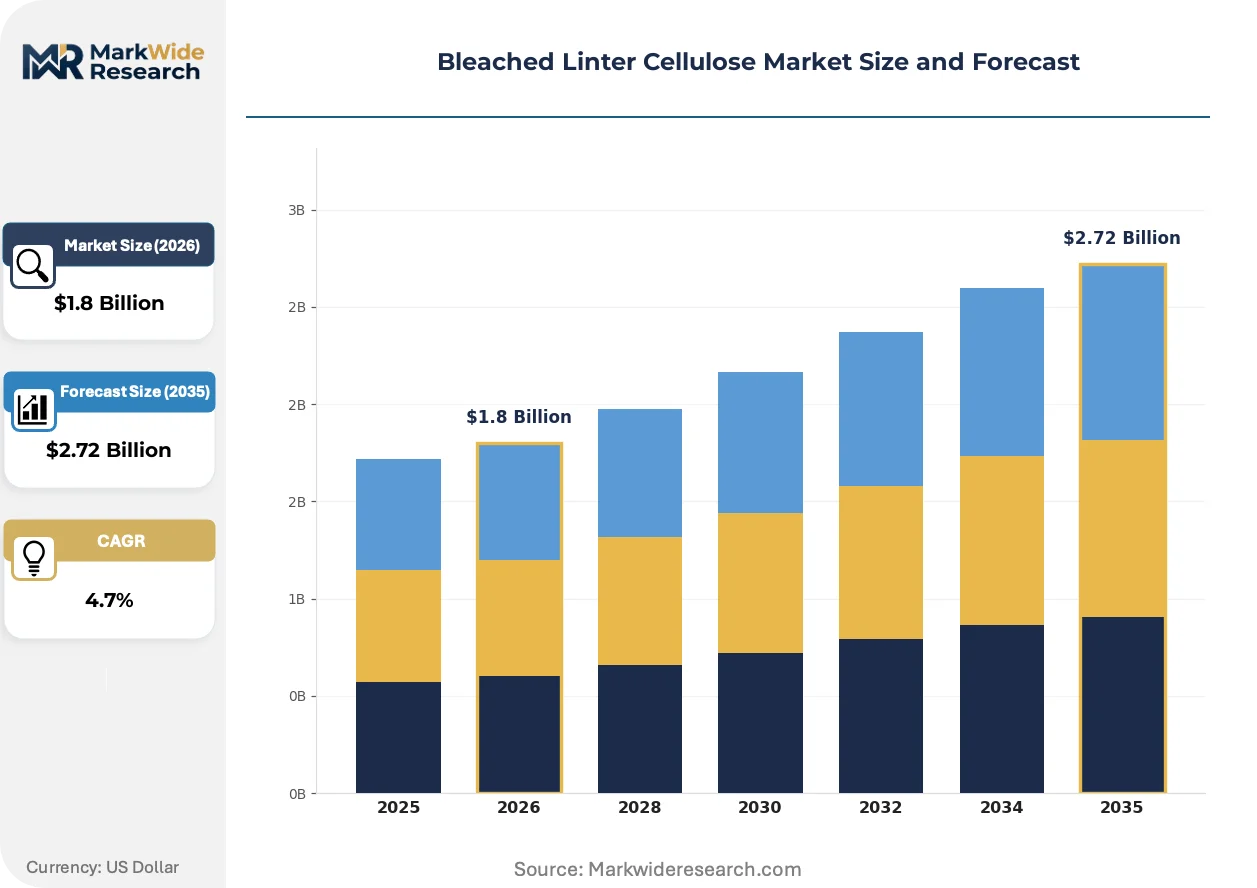
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Cellulose, Granulated Cellulose, Microcrystalline Cellulose, Filter Paper Application: Pharmaceuticals, Food Additives, Cosmetics, Personal Care Products End User: Healthcare, Food Industry, Cosmetic Manufacturers, Research Institutions Sales Channel: Direct Sales, Distributors, Online Retailers, Specialty Stores |
| Companies Covered | Georgia-Pacific LLC, Shandong Silver Hawk Chemical Fibre Co., Ltd., Linter Pak Co., GRN Cellulose Pvt. Ltd., Nippon Paper Industries Co., Ltd., Celanese Corporation, Sappi Limited, International Paper Company, Rayonier Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleached Linter Cellulose Market Emerging Trajectories
Process intensification and regulatory traceability are converging to reshape how bleached linter cellulose moves from cotton gin to pharmaceutical tablet. Innovation now centers on purity verification and supply chain authentication rather than basic processing efficiency.
Enzymatic bleaching sequences are unifying environmental compliance with pharmaceutical-grade output by replacing chlorine-based oxidation with laccase-mediator systems. European excipient manufacturers pilot these processes to preempt REACH restrictions on chlorinated byproducts. The technology is compressing the traditional multi-stage refining train while maintaining alpha-cellulose purity above 98.5%.
EMA's updated excipient guidelines now mandate documented supply chain risk assessments for critical raw materials entering the European Economic Area. Manufacturers must demonstrate linter provenance from farm-level cotton cultivation through bleaching and milling. Pharmaceutical contract manufacturers in Ireland and Germany are demanding batch-level polymerase chain reaction authentication to verify cotton species and geographic origin.
Formulators in North America and Western Europe now specify excipient quality agreements that unbundle technical support from material supply. Large pharmaceutical buyers negotiate direct quality audits of linter processors rather than relying on distributor certifications. This behavior concentrates purchasing power among the three to five processors with dedicated pharmaceutical-grade production lines and published drug master files.
Bleached Linter Cellulose Market Segmentation
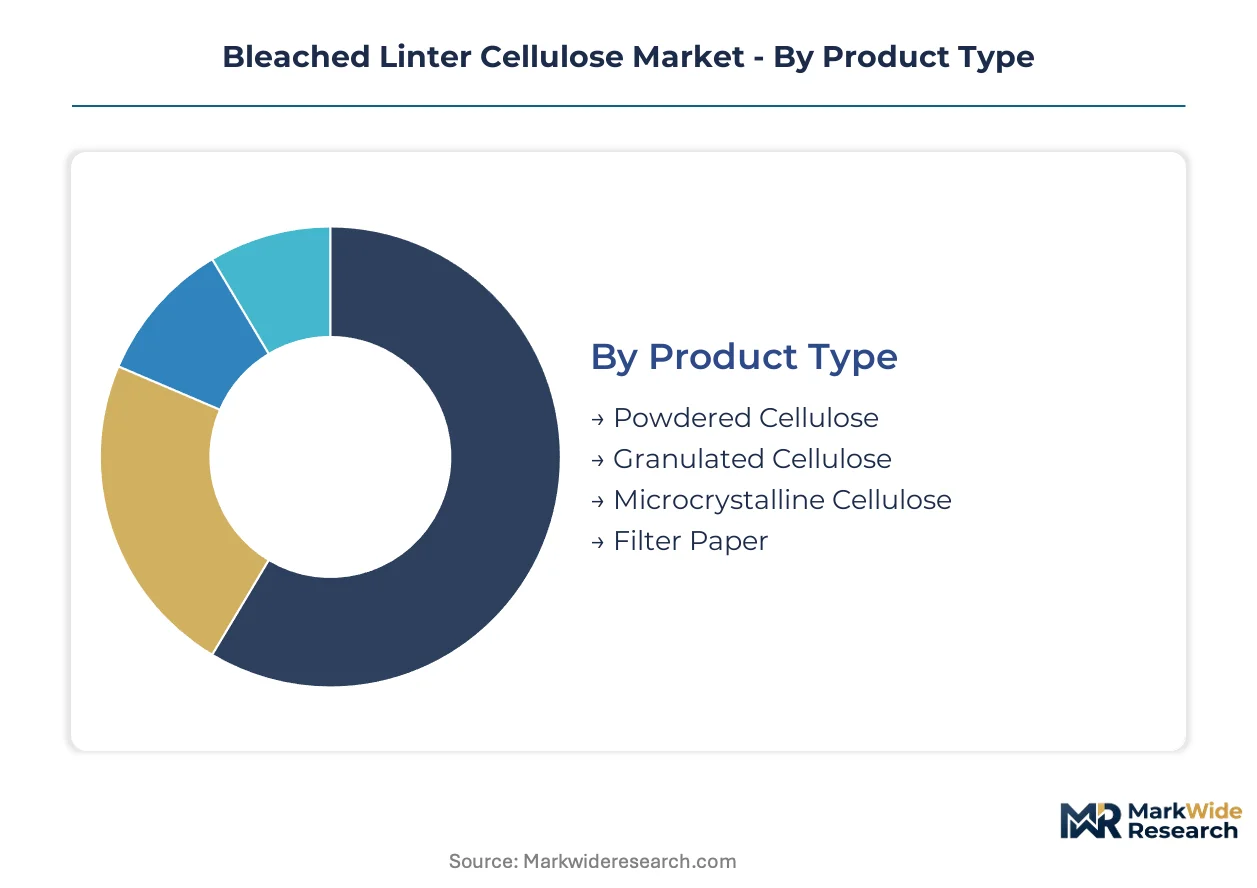
Pharmaceutical-grade purity tiers and excipient certification levels split buyer budgets and procurement workflows. Each segment carries distinct regulatory filing requirements that reshape supplier selection criteria and contract structures.
Product Type:
Buyers differentiate by compression performance needs and dissolution specifications rather than base material cost.
- Microcrystalline Cellulose:Refined alpha-cellulose with crystalline regions preserved through controlled hydrolysis, achieving particle sizes of 20-100 microns for direct compression tableting. Demand concentrates in oral solid dosage manufacturing facilities in Ireland and North Carolina where FDA Type II drug master files govern excipient qualification. EMA excipient guidelines now mandate batch-level traceability for this grade, extending procurement lead times.
- Filter Paper:High-purity sheet or disc formats with controlled porosity for gravimetric analysis and HPLC sample preparation. Laboratories in Germany and Switzerland sustain stable offtake through ISO 17025 quality system requirements, though substitution by membrane filtration is eroding growth in environmental testing applications.
- Powdered Cellulose:Mechanical disintegration of purified linter pulp yields fibrous particles used as anti-caking agents and tablet disintegrants. Food-grade specifications from FSSAI in India and FDA GRAS listings dominate qualification pathways.
- Granulated Cellulose:Agglomerated particles engineered for flow enhancement in nutraceutical coating applications. Cosmetic manufacturers in France and Italy favor this format for pressed powder formulations where moisture absorption must balance compressibility.
Volume sits with Filter Paper; growth tilts toward Microcrystalline Cellulose.
Application:
Regulatory burden intensity and certification timeline length determine segment profitability and supplier stickiness.
- Pharmaceuticals:Tablet binders, diluents, and disintegrants requiring USP-NF and Ph.Eur. compliance with residual solvent limits below ICH Q3C thresholds. MDR implementation in Europe has compressed excipient master file preparation timelines, concentrating purchasing among processors with published Type II DMFs.
- Food Additives:Anti-caking agents, texturizers, and fiber fortification in bakery and dairy applications. FSSAI standards in India and FDA GRAS self-affirmation create lower barriers than pharmaceutical channels, though EFSA novel food evaluations are lengthening for new cellulose derivatives.
- Cosmetics:Microbead replacements and rheology modifiers in skincare and color cosmetics. Formulators in South Korea and Japan favor linter-derived cellulose over wood alternatives for premium positioning.
- Personal Care Products:Absorbent substrates and film-forming agents in wipes and masks. Sustainability certifications from RSPO and BCI cotton programs increasingly gate retail distribution in Western European markets.
Revenue concentrates in Pharmaceuticals; expansion is steepest in Food Additives.
End User:
Scale economies and technical service requirements separate institutional buyers from commercial formulators.
- Healthcare:Multinational pharmaceutical manufacturers and contract development organizations with dedicated excipient qualification teams. Direct technical collaboration with cellulose processors reduces time-to-file for new molecular entities.
- Food Industry:Ingredient suppliers and finished goods manufacturers balancing cost position with clean-label positioning. Indian domestic processors are displacing imports in this channel through Gujarat-based cotton linter supply.
- Cosmetic Manufacturers:Mid-sized formulators in France, Italy, and South Korea specifying cosmetic-grade cellulose with heavy metal thresholds below 10 ppm. Smaller batch sizes and shorter lead times favor regional distributors over direct mill relationships.
- Research Institutions:Academic and government laboratories with intermittent demand for analytical-grade filter media. Price sensitivity and fragmented purchasing limit supplier investment in dedicated service infrastructure.
Procurement scale peaks with Healthcare; contract flexibility matters most to Cosmetic Manufacturers.
Sales Channel:
Documentation depth and audit access separate channels serving regulated versus unregulated end-uses.
- Direct Sales:Long-term supply agreements with pharmaceutical manufacturers including quality agreements, annual audits, and dedicated inventory buffers. Processors with captive linter supply and published DMFs dominate this channel.
- Distributors:Regional stocking points for cosmetic and food-grade volumes where batch sizes fall below mill minimums. European distributors are adding EUDR traceability documentation as a value-added service.
- Online Retailers:Laboratory supply platforms serving research institutions and small formulators with credit card purchasing and rapid fulfillment. Certificate of analysis availability varies by supplier integration.
- Specialty Stores:Niche channels for artisan food producers and natural cosmetics formulators seeking organic-certified cellulose derivatives. Limited volumes restrict processor direct engagement.
Transaction value aggregates through Direct Sales; channel expansion is fastest among Distributors adding compliance services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cotton belts in Gujarat and Maharashtra supply the raw linter feedstock reshaping regional processing economics. Pharmaceutical-grade purification capacity clusters where EMA and FDA compliance infrastructure intersect with captive pulp supply.
United States
Rayonier Advanced Materials anchors high-purity cellulose output from dissolving pulp facilities in the Southeast. FDA Type II drug master file requirements govern excipient qualification timelines for domestic pharmaceutical manufacturers. Jacksonville and Fernandina Beach processing complexes concentrate pharmaceutical-grade bleaching and milling capacity.
China
Shandong Province dissolving pulp mills feed downstream linter cellulose refineries serving both domestic and export pharmaceutical channels. NMPA pharmaceutical excipient registration and evolving environmental standards from MEE shape compliance investments. Qingdao and Yantai harbor zones concentrate export-oriented processing infrastructure with integrated logistics.
Germany
Contract manufacturing organizations in Hesse and North Rhine-Westphalia drive excipient-grade cellulose demand for MDR-compliant medical device production. EMA excipient master file compilation and REACH registration requirements elevate supplier qualification barriers. Frankfurt-Rhine-Main pharmaceutical clusters source through audited direct supply agreements with dedicated processors.
India
Gujarat cotton ginning cooperatives and Maharashtra textile belt processors are expanding captive linter collection and preliminary refining capacity. CDSCO excipient standards and FSSAI food-grade specifications govern dual-use production pathways. Ankleshwar and Vapi industrial zones attract pharmaceutical cellulose investments leveraging domestic raw material access.
Japan
PMDA pharmaceutical manufacturing standards and METI industrial policy support high-purity cellulose demand from domestic formulation houses. Osaka-Kobe pharmaceutical production clusters maintain strict excipient quality agreements with certified suppliers. Kansai region technical textile traditions inform specialty cellulose processing expertise for cosmetic and personal care applications.
Bleached Linter Cellulose Market Vendor Landscape
Backward integration into captive cotton linter supply dominates the current landscape as pharmaceutical-grade purity requirements harden. The market structure concentrates around three to five processors with dedicated excipient production lines and published regulatory filings. Strategic archetypes include integrated pulp-to-specialty-chemicals operators, regional dissolving pulp specialists with downstream refining capacity, and pharmaceutical-focused purity specialists. Capacity expansion in India and Brazil and EUDR traceability certification investments represent the dominant competitive moves reshaping positioning.
Among integrated North American operators, Georgia-Pacific LLC exemplifies the pulp-to-specialty-chemicals archetype through its control over upstream linter supply continuity. Shandong Silver Hawk Chemical Fibre Co., Ltd. occupies a parallel position in East Asia, anchoring regional capacity through captive dissolving pulp infrastructure. Rayonier Advanced Materials represents the purity-specialist vector, concentrating on regulated end-use channels where EMA and FDA compliance documentation governs supplier selection.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Shandong Silver Hawk Chemical Fibre Co., Ltd. |
| Linter Pak Co. |
| GRN Cellulose Pvt. Ltd. |
| Nippon Paper Industries Co., Ltd. |
| Celanese Corporation |
| Sappi Limited |
| International Paper Company |
| Rayonier Advanced Materials |
| Others |
Supply Flow & Price Mechanics
Enzymatic bleaching sequences replacing chlorine-based oxidation compress capital requirements for environmental compliance while simultaneously concentrating cost advantages among processors with captive dissolving pulp capacity. This technology shift tightens the link between upstream linter supply control and downstream pricing power in pharmaceutical-grade channels.
Pricing Analysis
Technical service bundling now separates pharmaceutical-grade supply agreements from commodity linter sales. Three-tier pricing structure across excipient-grade, food-grade, and industrial-grade levels reflects certification burden and DMF publication status. Price differentiation hinges on FDA Type II drug master file availability and batch-level traceability documentation. Cost compression in standard-grade material is intensifying because Indian domestic processors are expanding captive linter refining capacity. Contract manufacturers with published quality agreements exhibit the least price sensitivity; regional food additive distributors show the most.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle excipient-grade volumes requiring audit access and quality agreement negotiation. Raw material supply concentrates in India, China, and the United States. Processing draws from cotton linter feedstock, dissolving pulp intermediates, and hypochlorite or enzymatic bleaching chemicals. Single-source vulnerability runs through Shandong Province dissolving pulp clusters where environmental compliance upgrades are consolidating capacity. Distribution runs through audited direct agreements for pharmaceutical grades and regional distributors for cosmetic and food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity dissolving pulp capacity constraints in Shandong Province and the US Southeast are propping excipient-grade pricing premiums as MDR compliance deadlines pull forward demand.
For Market Incumbents: Extend pharmaceutical certification coverage by accelerating EUDR traceability documentation ahead of deforestation-free supply chain mandates. Deepen backward integration into captive cotton linter collection in Gujarat and Maharashtra to offset substitution pressure from wood-derived specialty cellulose. Prioritize enzymatic bleaching capacity additions that preempt REACH restrictions on chlorinated byproducts. For New Entrants and Emerging Players: EUDR in Europe opens a window for traceability-specialist positioning among mid-tier processors lacking legacy pharmaceutical infrastructure. Target Brazil's Cerrado cotton belts where linter collection infrastructure remains underdeveloped and integrated processors can establish captive supply. Pursue food-grade encapsulation segments where FSSAI and FDA GRAS pathways offer lower certification barriers than drug excipient channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pulp-to-specialty-chemicals operators seeking pharmaceutical-grade purification capabilities. Long-term viability favors processors with published DMFs and dedicated excipient production lines as buyer concentration intensifies. Monitor enzymatic bleaching adoption rates as the inflection signal for environmental compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Linter Supply | Georgia-Pacific and Shandong Silver Hawk anchor cost control through upstream cotton seed fiber access. |
| EUDR Traceability Certification Investment | Early compliance creates premium positioning for European pharmaceutical and medical device sales channels. |
| Enzymatic Bleaching Capacity Transition | Laccase-mediator systems preempt REACH chlorinated byproduct restrictions while maintaining alpha-cellulose purity. |
| Pharmaceutical DMF Publication Acceleration | FDA Type II and EMA excipient master files lock in supplier stickiness with contract manufacturing organizations. |
| Brazil Linter Collection Infrastructure Buildout | Integrated processors can secure captive supply in underdeveloped Cerrado cotton production regions. |
Methodological Framework
Independent corroboration across excipient procurement managers at contract manufacturing organizations, regulatory affairs leads at pharmaceutical formulators, and technical directors at dissolving pulp processors underwrites the qualitative findings. Primary interviews with CDSCO and FSSAI compliance officers in India supplemented secondary validation through FDA drug master file databases, EMA excipient guidelines documentation, and REACH registration records. Customs trade data from cotton linter and dissolving pulp categories anchored bottom-up volume estimates against top-down pharmaceutical production forecasts.
Comparable-period anchoring tied projection assumptions to historical excipient demand patterns across oral solid dosage manufacturing cycles. The analytical framework segments by product grade tier, end-use regulatory pathway, and regional production hub concentration throughout the forecast period. CAGRs were derived from elasticity-adjusted demand modeling incorporating tablet direct compression adoption rates and MDR implementation timelines. Forecast inputs include cotton harvest yield volatility in Gujarat and Maharashtra and enzymatic bleaching technology diffusion curves.
The model assumes a particular technology adoption path; alternative pathways for hypochlorite-free bleaching sequences would alter the outlook for environmental compliance capital requirements. Forecasts reflect assumptions about EUDR traceability mandate enforcement timing and pharmaceutical buyer concentration behavior. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Metal Fiber Felt Market
Fibers
Europe Carbon Fiber Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Carbon Fiber in Light Weight Pressure Vessels Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Basalt Fiber Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Viscose Staple Fiber Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Global Bicomponent Fiber Market
Fibers
Bioglass Fiber Market
Fibers
Global Fiberglass Market