
 Global Lactobionic Acid Market | 2026-2036
Global Lactobionic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lactobionic Acid Market Foresight
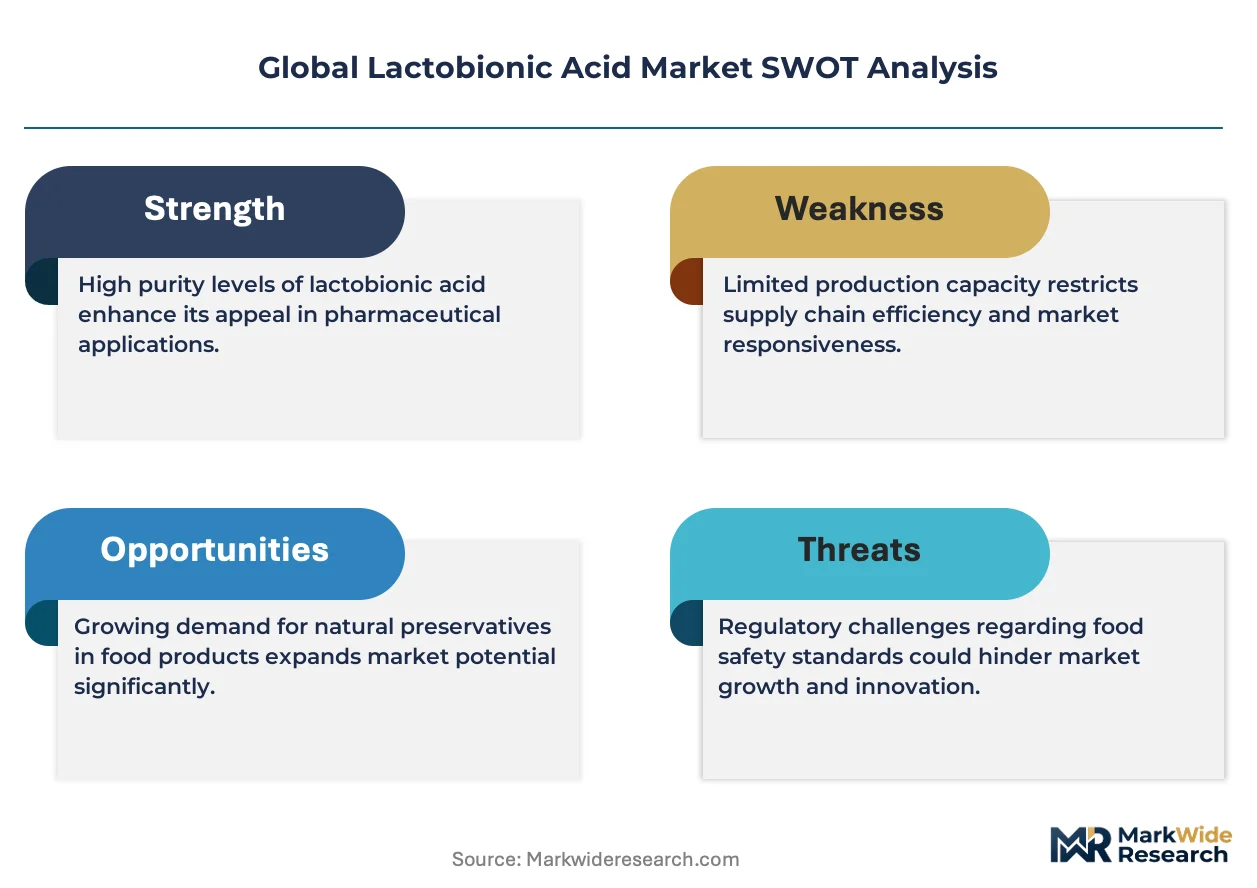
Biocatalytic fermentation using engineered lactobionic dehydrogenase is reconfiguring production economics for lactobionic acid suppliers. Merck & Co., Inc. leverages vertical integration from carbohydrate feedstocks through pharmaceutical-grade purification. Avantor, Inc. anchors North American supply chains with cGMP-certified distribution networks for biopharmaceutical excipients. Bio-Sugars Technology Co. LTD competes on specialized fermentation scale in Asia-Pacific manufacturing corridors.
Lactobionic acid is a disaccharide acid synthesized from lactose oxidation, yielding a molecular structure with one gluconic acid and one galactose unit that confers metal-chelating and antioxidant properties. Industrial production employs fungal carbohydrate oxidase or electrochemical catalysis, with purity thresholds varying by end-use from ninety-eight percent for food applications to ninety-nine point five percent for parenteral pharmaceutical formulations. Pharmaceutical Grade lactobionic acid commands premium positioning due to endotoxin and microbial limit requirements for intravenous drug compatibility. Cosmetic Grade supply expands fastest as Korean and French formulators incorporate the acid for its humectant and gentle exfoliant properties in barrier-support skin care. Food Grade applications remain mature, with preservative demand tracking processed dairy and prepared meal categories in established markets.
The FDA maintains lactobionic acid within its Inactive Ingredient Database for parenteral and oral dosage forms, while the EMA's excipient guidelines under the EU MDR impose strengthened nitrosamine and elemental impurity documentation. China's NMPA aligns pharmaceutical excipient oversight with ICH Q3D elemental impurity standards, tightening market access for uncertified imports. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and ChP monographs, as divergent heavy metal and microbial specification timelines reshape supplier qualification burdens and regional sourcing strategies.
Market Dynamics
Biocatalytic fermentation using engineered lactobionic dehydrogenase enzymes is compressing production costs and redrawing competitive boundaries between electrochemical and biological manufacturing routes for lactobionic acid supply.
Growth Catalysts
- EU MDR excipient documentation mandates:Pharmaceutical manufacturers across Germany, France, and Italy face tightened purity requirements for intravenous formulations, pulling certified supply through qualified channels.
- Fermentation scale-up in Jiangsu province:China's bioprocessing clusters now serve contract manufacturers for both cosmetic and pharmaceutical applications, anchoring regional production capacity.
- Korean cosmetic formulator demand:Barrier-support skin care incorporating lactobionic acid as a gentle exfoliant and humectant is expanding offtake from Seoul-based R&D laboratories.
Market Restraints
- Lactose feedstock price volatility:Dairy commodity fluctuations directly compress margins for oxidation-based production, particularly affecting non-integrated suppliers without captive carbohydrate sources.
- Pharmaceutical-grade purification bottlenecks:Endotoxin and microbial limit testing capacity concentrates among cGMP-certified facilities in Switzerland and Germany, creating supply chokepoints.
- Gluconolactone substitution in food preservation:Processed dairy and prepared meal manufacturers in mature markets increasingly specify alternative polyhydroxy acids with simpler regulatory pathways.
Strategic Opportunities
- Underpenetrated Brazilian pharmaceutical excipient market:ANVISA's alignment with ICH Q3D standards creates first-mover advantages for certified suppliers establishing local technical partnerships.
- Electrochemical-enzymatic hybrid processes:Converging catalytic technologies promise step-change yield improvements and reduced solvent waste profiles for next-generation manufacturing assets.
- Direct-to-formulator digital platforms:Cosmetic ingredient distributors in France and South Korea are building specification-matching tools that bypass traditional chemical broker networks.
Industry Challenges
- Pharmacopeial harmonization timelines:Divergent heavy metal and microbial specification schedules across USP-NF, EP, and ChP monographs extend supplier qualification cycles for multi-territory pharmaceutical contracts.
- Fermentation specialist talent scarcity:Industrial biotechnology programs in European and North American universities produce insufficient graduates with scaled carbohydrate oxidase process experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lactobionic Acid Market |
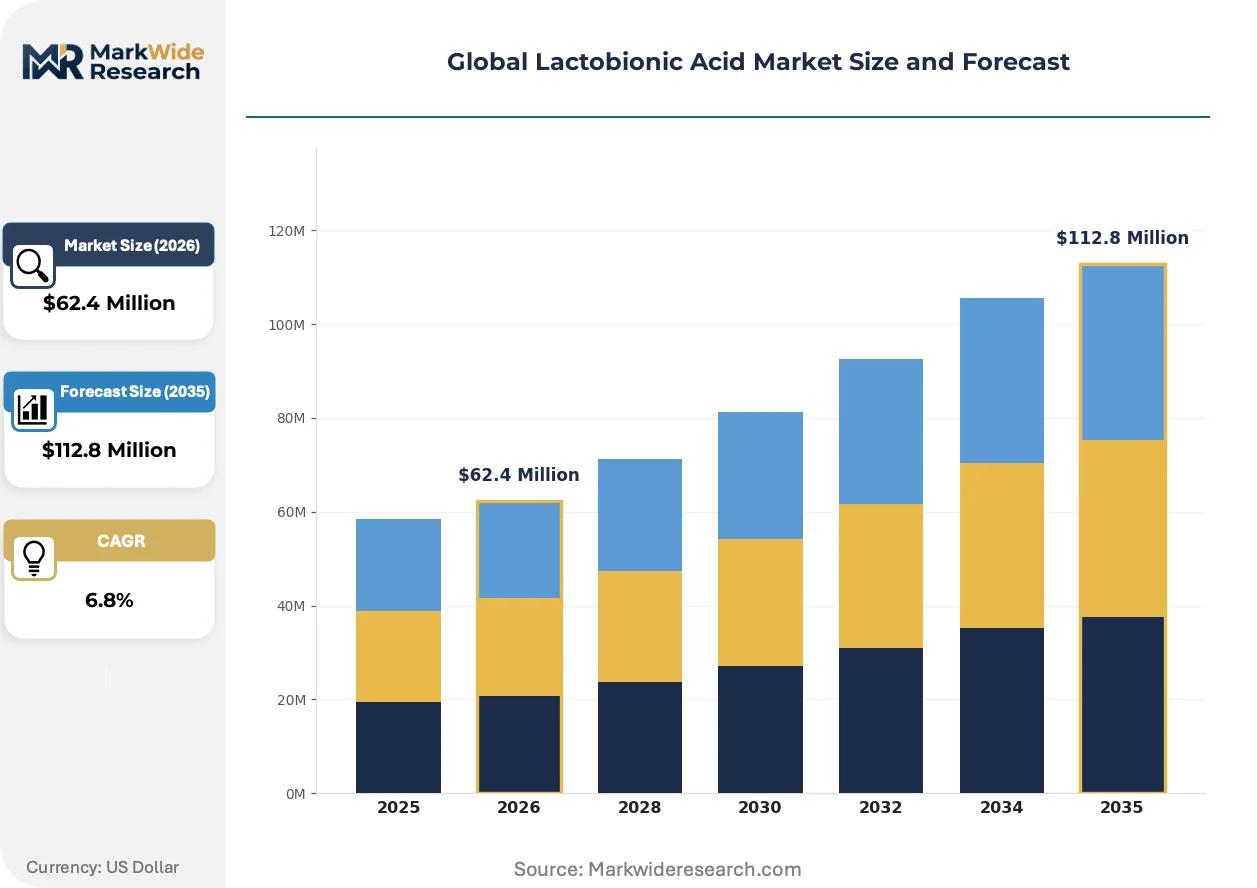
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $112.8 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Food Preservatives, Skin Care, Pharmaceutical Formulations, Chelating Agents End User: Pharmaceutical Manufacturers, Cosmetic Producers, Food Processing Companies, Chemical Suppliers Form: Powder, Liquid, Crystal, Granules |
| Companies Covered | Merck & Co., Inc., Avantor, Inc., Cayman Chemical Company, Novartis AG, DAYANG CHEM (HANGZHOU) CO., LTD., Bio-Sugars Technology Co. LTD, Wuxi Sigma Chemical Products Co. LTD., Manus Aktteva Biopharma, Sandoz INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lactobionic Acid Market Shifts & Advancements
Process analytical technology and real-time release testing are compressing batch cycle times while regulatory data integrity requirements reshape how manufacturers document and transmit quality attributes across supply chains.
Continuous manufacturing with inline Raman spectroscopy is digitizing quality control workflows for lactobionic acid crystallization. Pharmaceutical excipient producers in Germany and Switzerland are adopting these systems to eliminate offline testing delays. The technology is digitizing documentation trails for EU MDR compliance, reducing audit preparation labor while tightening release specifications.
REACH framework amendments on nanomaterial registration are forcing cosmetic-grade suppliers to reassess particle size distribution claims and safety dossier completeness. ECHA's evolving guidance on multi-constituent substances creates classification uncertainty for electrochemically produced lactobionic acid variants. French and Italian formulators are demanding expanded substance identity documentation from Asian suppliers to preempt authorization disruptions.
Specification-driven procurement contracts are replacing spot-market purchasing among mid-scale pharmaceutical manufacturers. Buyers in Japan and South Korea now require locked-in endotoxin certificates with eighteen-month validity windows, displacing traditional certificate-of-analysis acceptance. The shift concentrates volume with suppliers maintaining dedicated quality assurance teams and pharmacopeial liaison capabilities.
Global Lactobionic Acid Market Segmentation
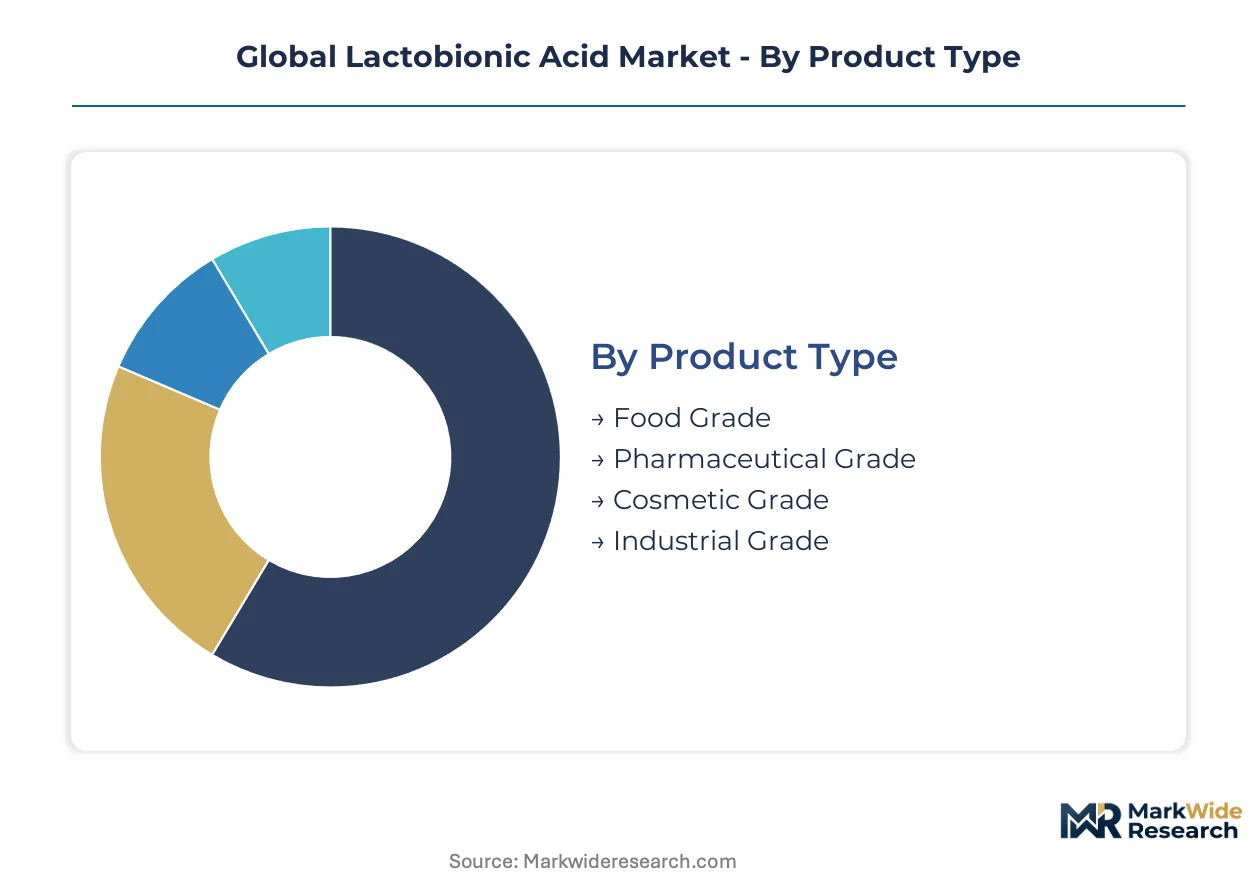
Lactobionic acid's functional versatility across metal chelation, humectancy, and biocompatibility creates distinct specification tiers that reshape procurement priorities. Each grade carries unique purity thresholds, regulatory documentation burdens, and end-use performance requirements that fragment supplier qualification pathways.
Product Type:
Mature pharmaceutical specifications coexist with emerging cosmetic-grade demand as formulators discover barrier-support applications.
- Food Grade:Ninety-eight percent purity suffices for processed dairy preservation and prepared meal acidification. Demand tracks established markets where gluconolactone substitution pressures volume growth.
- Pharmaceutical Grade:Endotoxin limits below five EU per gram and microbial specifications under ten CFU per gram command premium positioning. German and Swiss manufacturers anchor procurement for intravenous formulations under tightened EU MDR documentation mandates.
- Cosmetic Grade:Metal-chelating and gentle exfoliant properties drive Korean and French formulator offtake. Barrier-support skin care R&D in Seoul laboratories accelerates specification development for this segment.
- Industrial Grade:Lower-purity electrochemical output serves metal surface treatment and textile processing. Price-sensitive buyers in Chinese manufacturing corridors dominate procurement.
Pharmaceutical Grade retains volume leadership; Cosmetic Grade holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity preservation from high-value therapeutic and aesthetic deployment.
- Food Preservatives:Acidification and shelf-life extension in processed dairy and prepared meals. Mature demand faces gluconolactone displacement in Western European and North American markets.
- Skin Care:Humectant and mild exfoliant functions in barrier-support formulations. Korean cosmetic laboratories and French formulators drive specification innovation for sensitive-skin product lines.
- Pharmaceutical Formulations:Intravenous drug compatibility requires endotoxin-controlled supply chains. cGMP-certified distribution networks in Germany and Switzerland concentrate qualified procurement.
- Chelating Agents:Metal ion sequestration for pharmaceutical stabilization and industrial processes. Pharmaceutical applications command tenfold price multiples over industrial deployment.
Food Preservatives anchor revenue scale; Skin Care climbs the fastest as cosmetic R&D accelerates.
End User:
Customer type fragmentation separates integrated multinationals from specialized contract manufacturers and commodity distributors.
- Pharmaceutical Manufacturers:Merck and Avantor leverage captive carbohydrate feedstocks and cGMP purification. Locked-in endotoxin certificates with eighteen-month validity windows displace spot-market purchasing.
- Cosmetic Producers:French and Korean formulators build direct-to-supplier digital platforms that bypass traditional chemical broker networks. Specification-matching tools compress procurement cycles.
- Food Processing Companies:Processed dairy and prepared meal manufacturers in established markets specify alternative polyhydroxy acids with simpler regulatory pathways.
- Chemical Suppliers:Industrial-grade distributors serve metal treatment and textile applications through price-sensitive spot contracts. Chinese manufacturing corridors concentrate volume.
Pharmaceutical Manufacturers dominate value capture; Cosmetic Producers gain share fastest through platform disintermediation.
Form:
Supply concentration in Jiangsu province bioprocessing clusters shapes available physical formats for regional markets.
- Powder:Spray-dried crystalline form dominates pharmaceutical and cosmetic formulation for precise dosing and extended stability.
- Liquid:Aqueous solutions simplify food preservation and industrial chelation applications where solubility accelerates process integration.
- Crystal:High-purity recrystallized material serves analytical standards and specialty pharmaceutical synthesis.
- Granules:Agglomerated powder improves flow properties for high-speed tableting and direct compression manufacturing.
Powder retains formulation dominance; Liquid expands most quickly in food and industrial process integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation specialists in Jiangsu province export cosmetic-grade lactobionic acid to Seoul and Paris formulators, while Swiss and German cGMP facilities supply pharmaceutical-grade material for intravenous drug manufacturers across Western Europe.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and Bavaria expand procurement of endotoxin-controlled lactobionic acid for parenteral formulations. The EU MDR tightens excipient documentation requirements, forcing suppliers to maintain dedicated pharmacopeial liaison teams. cGMP-certified purification facilities in the Rhine-Main region concentrate qualified supply for intravenous compatibility.
China
Fermentation-based bioprocessing clusters in Jiangsu province serve contract manufacturers for both pharmaceutical and cosmetic applications. The NMPA aligns excipient oversight with ICH Q3D elemental impurity standards, screening uncertified imports. Yangtze River Delta facilities now anchor Asia-Pacific production capacity for metal-chelating grade supply.
South Korea
Seoul-based cosmetic R&D laboratories drive specification innovation for barrier-support skin care incorporating lactobionic acid humectancy. The MFDS maintains pharmaceutical-grade import standards that favor certified European suppliers. Gyeonggi-do formulators build direct-to-supplier digital platforms that bypass traditional chemical broker networks.
Switzerland
Swissmedic-certified facilities concentrate endotoxin and microbial limit testing capacity for pharmaceutical-grade lactobionic acid. Basel-area manufacturers leverage backward integration into carbohydrate feedstock processing. The country's excipient producers command premium positioning for intravenous drug compatibility across EU markets.
France
Paris and Lyon formulators incorporate lactobionic acid into sensitive-skin product lines as gentle exfoliant alternatives. ANSM guidance on cosmetic ingredient safety dossiers forces reassessment of particle size distribution claims. Provence-Alpes-Côte d'Azur laboratories demand expanded substance identity documentation from Asian suppliers to preempt REACH authorization disruptions.
Global Lactobionic Acid Market Competitive Landscape
On the supply side, the industry is bifurcated between fermentation-scale specialists and cGMP-certified pharmaceutical excipient distributors. Three archetypes dominate: integrated carbohydrate processors with captive feedstock supply, regional fermentation scale-up specialists serving cosmetic contract manufacturers, and pharmacopeial-grade distributors maintaining locked-in endotoxin certification systems. Competitive moves concentrate on strategic partnerships for bioprocessing technology licensing and geographic expansion into underpenetrated Brazilian and Southeast Asian pharmaceutical markets.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Avantor, Inc. occupy positions that exemplify backward integration from carbohydrate feedstocks through cGMP purification. Bio-Sugars Technology Co. LTD represents the Asia-Pacific fermentation specialist archetype, anchoring regional scale-up capacity for cosmetic and pharmaceutical contract manufacturing corridors.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Avantor, Inc. |
| Cayman Chemical Company |
| Novartis AG |
| DAYANG CHEM (HANGZHOU) CO., LTD. |
| Bio-Sugars Technology Co. LTD |
| Wuxi Sigma Chemical Products Co. LTD. |
| Manus Aktteva Biopharma |
| Sandoz INC. |
| Others |
Supply & Pricing Matrix
Shanghai-Rotterdam container freight corridors absorb dairy commodity volatility into landed cost spreads, compressing margins for non-integrated lactobionic acid suppliers while amplifying price premiums for cGMP-certified pharmaceutical grades. Electrochemical producers in Chinese manufacturing corridors compete on spot-market liquid formats, whereas Swiss and German purification facilities command contract-based offtake premiums for endotoxin-controlled intravenous supply.
Pricing Analysis
Electrochemical oxidation routes price fifteen to twenty percent below biocatalytic fermentation outputs, with next-generation enzymatic-electrochemical hybrid processes targeting mid-tier positioning. Pharmaceutical-grade lactobionic acid stratifies across premium, standard, and economy tiers keyed to endotoxin certification validity windows and pharmacopeial liaison capabilities. Cost compression in cosmetic-grade supply intensifies as Jiangsu province fermentation capacity expands, drawing price-sensitive industrial buyers toward spot-market liquid procurement while intravenous drug manufacturers absorb premium pricing for locked-in eighteen-month endotoxin certificates.
Supply Chain Analysis
EU MDR documentation requirements function as de facto export controls on uncertified excipient-grade supply, restricting flows from non-cGMP facilities into German and French pharmaceutical channels. Manufacturing concentrates in China's Jiangsu province, Switzerland's Basel region, and Germany's Rhine-Main corridor, with lactose feedstock sourcing anchored in New Zealand, EU dairy cooperatives, and North American whey processors. Single-source vulnerability concentrates in Swissmedic-certified endotoxin testing capacity, where Basel-area facilities feed qualified distribution through locked-in procurement contracts rather than spot-market brokerage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gluconolactone substitution in food preservation and barrier-support skincare formulations threatens lactobionic acid volume retention, forcing incumbents to defend pharmaceutical-grade positioning against alternative polyhydroxy acid incursions.
For Market Incumbents: Pre-empt gluconolactone displacement in cosmetic applications by accelerating Seoul and Paris laboratory partnerships for barrier-support formulation co-development. Anchor pharmaceutical-grade margins through captive lactose processing in Baden-Württemberg, eliminating feedstock price volatility exposure that compresses non-integrated competitors. Lock endotoxin certification systems into eighteen-month validity windows to displace spot-market purchasing among mid-scale Japanese and South Korean drug manufacturers.
For New Entrants and Emerging Players: Brazilian pharmaceutical excipient markets offer underpenetrated white-space as ANVISA aligns with ICH Q3D standards, rewarding first-movers with local technical partnerships before European suppliers establish qualified distribution. Electrochemical-enzymatic hybrid process licensing from Jiangsu province specialists enables cost-competitive entry into cosmetic-grade supply without cGMP infrastructure burdens. Direct-to-formulator digital platforms in Gyeonggi-do bypass traditional chemical broker networks, compressing procurement cycles for specification-matched cosmetic ingredient supply.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded lactobionic acid assets lacking pharmacopeial liaison capabilities or locked-in endotoxin certification systems. Long-term viability hinges on backward integration into carbohydrate feedstock processing and cGMP purification infrastructure rather than commodity fermentation scale. Watch for MFDS and NMPA alignment timelines on elemental impurity standards as inflection indicators for regional supply reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactose Processing | Captive feedstock supply eliminates dairy commodity margin compression for oxidation-based producers. |
| cGMP Certification Investment | EU MDR documentation mandates concentrate qualified procurement through Swiss and German facilities. |
| Direct-to-Formulator Digital Platforms | Seoul-based specification-matching tools disintermediate traditional chemical broker networks for cosmetic supply. |
| Electrochemical-Enzymatic Hybrid Licensing | Next-generation catalytic convergence promises yield improvements and reduced solvent waste profiles. |
| Brazilian Technical Partnership Establishment | ANVISA's ICH Q3D alignment creates first-mover advantages in underpenetrated pharmaceutical excipient markets. |
Research Methodology
Operator-level perspectives from fermentation plant managers, pharmaceutical procurement leads at intravenous drug manufacturers, cosmetic formulator R&D directors, and cGMP distribution channel partners anchored the qualitative base. Secondary validation drew from NMPA excipient guidance filings, EMA MDR implementation documents, USP-NF and EP monograph revision timelines, and Jiangsu province bioprocessing cluster investment disclosures. Bottom-up volume estimates triangulated against top-down pharmaceutical excipient market assessments across the analysis window.
Scenario-bracketing framed projections across biocatalytic fermentation scale-up, electrochemical yield improvement, and hybrid process commercialization pathways. Segmentation modeling captured grade-tier differentiation, end-use application fragmentation, and regional regulatory cluster alignment. CAGRs derived from installed capacity expansion schedules, locked-in procurement contract volumes, and substitution elasticity estimates for gluconolactone displacement in food preservation applications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese fermentation specialists or accelerated EU MDR enforcement timelines would shift outcomes. Material shifts in lactose feedstock price volatility, REACH nanomaterial registration amendments, or pharmacopeial harmonization schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Plastic Stabilizer Market