
 Bio-Ketones Market | 2026-2036
Bio-Ketones Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Ketones Market Outlook
The EU Green Deal is decoupling ketone production from petroleum feedstocks, forcing ingredient makers to certify bio-based carbon content. LANZATECH leverages gas-fermentation technology to convert industrial emissions into ethanol precursors for ketone synthesis. Merck KGaA anchors pharmaceutical-grade ketone supply through stringent GMP manufacturing protocols. Genomatica, Inc specializes in engineered microbial strains that boost fermentation yields for commercial bio-ketone output.
Bio-ketones are organic compounds containing a carbonyl group bonded to two carbon atoms, typically produced through microbial fermentation of sugars or syngas rather than petrochemical oxidation, with purity grades ranging from food-grade to pharmaceutical-grade depending on downstream application. These molecules serve as metabolic intermediates, flavor precursors, and nutritional supplements across food and health industries. BHB Salts dominate current volume flows due to established use in ketogenic dietary supplements, while BHB Esters command premium positioning in sports nutrition where rapid ketone elevation matters. Health Supplements represents the most mature application channel, whereas Pharmaceuticals offers the highest margin pool as clinical validation expands.
The European Food Safety Authority sets purity thresholds for novel food ingredients including bio-derived ketones, while the FDA exercises oversight through GRAS notification pathways for U.S. market entry. REACH compliance in Europe adds testing burdens that favor larger producers with dedicated regulatory affairs teams. Stakeholders must monitor fermentation feedstock cost volatility and evolving novel food approval timelines across jurisdictions to time capacity investments effectively.
Market Dynamics
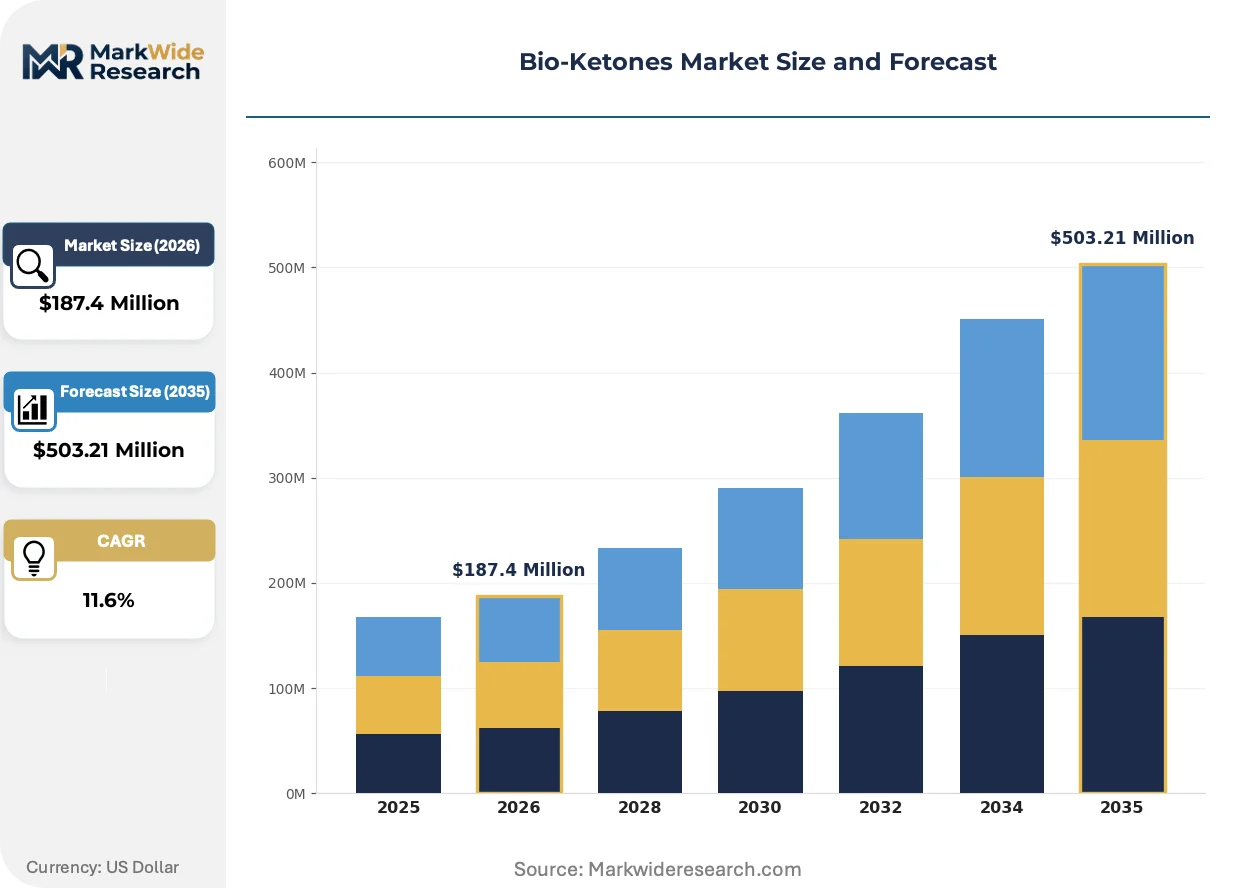
Fermentation pathway economics now dominate strategic positioning as petroleum-derived ketone margins compress under carbon pricing regimes. The EU Green Deal's tightening bio-based certification requirements are forcing capital reallocation toward gas-fermentation and sugar-fed bioreactor infrastructure.
Growth Catalysts
- REACH compliance architecture:European chemical registration protocols favor established fermentation operators with dedicated toxicology dossiers, creating regulatory moats against petrochemical imports.
- Ketogenic sports nutrition:Performance-focused athletes now prioritize rapid ketone elevation protocols, expanding addressable demand for BHB ester formulations in endurance and strength disciplines.
- Industrial biotechnology clusters:Germany's concentrated enzyme engineering and downstream processing capabilities reduce scale-up risk for novel microbial strain deployment.
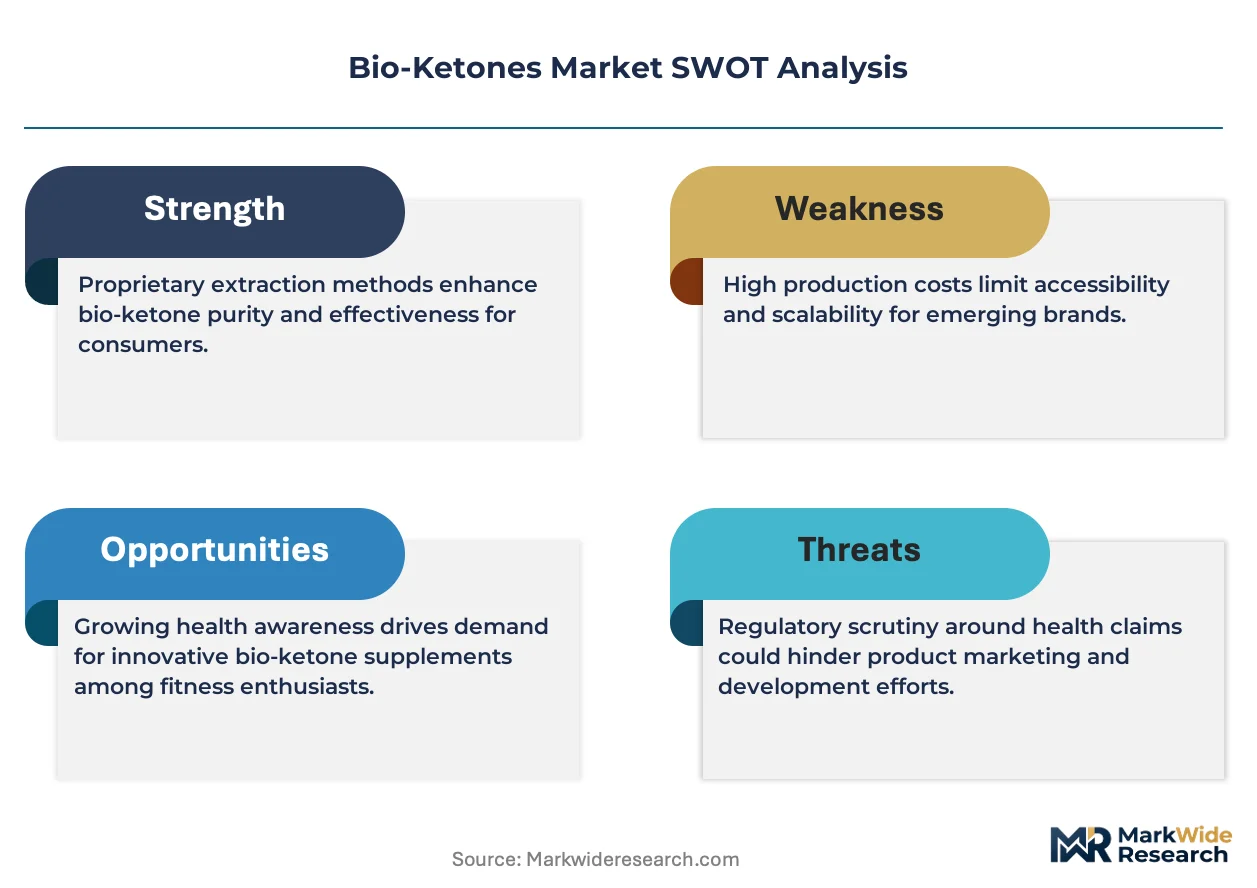
Market Restraints
- Feedstock cost volatility:Corn and sugarcane price swings directly compress fermentation margins, with Brazilian ethanol market shocks transmitting rapidly to ketone precursor economics.
- Purification bottlenecks:Pharmaceutical-grade ketone production requires chromatographic separation infrastructure that concentrates supply among three European contract manufacturers.
- Petrochemical substitution:Acetone and MEK from propylene oxidation retain cost advantages in industrial solvent applications where bio-based premiums face resistance.
Strategic Opportunities
- Clinical nutrition expansion:Hospital formulary adoption of ketone-based metabolic therapies for neurodegenerative conditions opens reimbursement-driven demand channels distinct from consumer supplements.
- Carbon credit monetization:Gas-fermentation operators capturing industrial CO2 streams can stack EU ETS allowances with voluntary carbon market instruments.
- Novel food approval pathways:EFSA's evolving guidance on microbial biomass ingredients creates first-mover advantages for GRAS-equivalent dossier holders seeking Asian market entry.
Industry Challenges
- Fermentation scale-up expertise:The talent pool for industrial bioprocess engineering remains thin relative to incumbent chemical engineering disciplines, extending commissioning timelines.
- Cross-jurisdictional certification:Divergent novel food approval timelines between EFSA, FDA GRAS, and China's SAMR create inventory stranding risks for global formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Ketones Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHB Salts, BHB Esters, MCT Oil, Medium-Chain Triglycerides Application: Health Supplements, Sports Nutrition, Functional Foods, Pharmaceuticals End User: Athletes, Weight Watchers, Diabetics, Elderly Population Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores |
| Companies Covered | LANZATECH, Merck KGaA, Eastman Chemical Company, Genomatica, Inc, Bio Brands LLC, Caldic B.V., Green Biologics Limited, Celanese Corporation, Biokemik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Ketones Market Strategic Shifts
Continuous bioprocessing is displacing batch fermentation as the dominant production paradigm, compressing capital intensity and enabling real-time quality control. This shift is reshaping facility design, supply contracts, and competitive positioning across the value chain.
Gas-fermentation technology is converging with carbon capture infrastructure to produce ethanol precursors for ketone synthesis. Steel and cement producers are piloting offtake agreements for captured CO2 streams. This convergence is collapsing the carbon accounting boundary between industrial emissions and nutritional ingredient production.
EFSA's tightened purity thresholds for novel food ingredients now mandate extensive metabolite profiling beyond traditional identity specifications. Ingredient makers must maintain dedicated analytical chemistry capabilities that smaller fermentation houses cannot afford. Pharmaceutical-grade ketone suppliers are capturing margin premiums through preemptive compliance investments.
Athlete-influencer networks are displacing traditional retail distribution for ketogenic supplements, with direct-to-consumer subscriptions capturing loyalty before brick-and-mortar shelf placement. Sports nutrition brands now prioritize content partnerships over pharmacy chain negotiations. This channel rotation is most visible in North American and Australian markets where fitness creator economies concentrate audience attention.
Bio-Ketones Market Segmentation
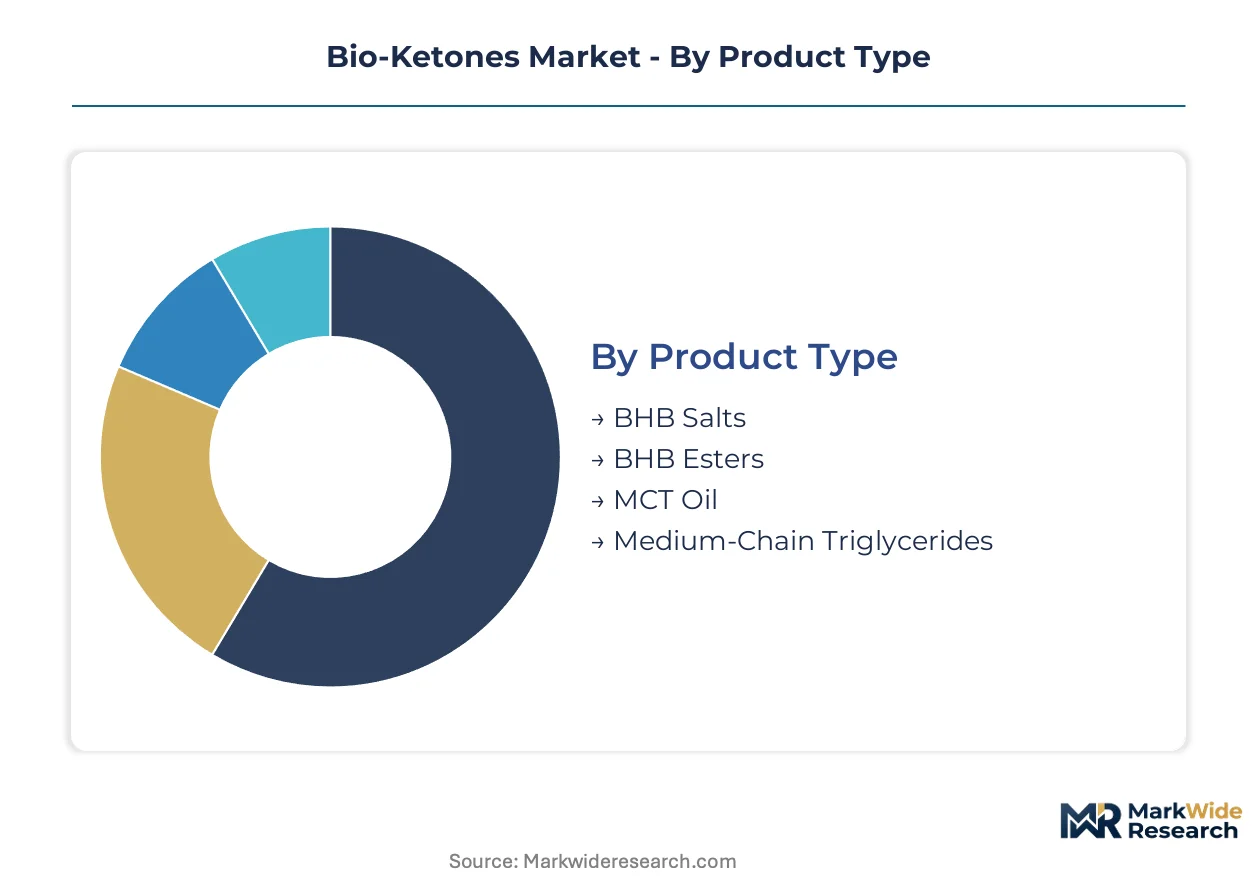
Bio-ketones serve distinct metabolic functions across consumer wellness and clinical applications. Segmentation reveals where fermentation economics align with formulation requirements versus where petrochemical alternatives still compete.
Product Type:
Standalone ketone ingredients dominate supplement formulations, while embedded ketone systems blend into broader nutritional matrices.
- BHB Salts:Beta-hydroxybutyrate bound to mineral carriers—sodium, calcium, magnesium—delivers gradual ketone elevation with electrolyte co-benefits. Demand concentrates in North American weight management supplements where powder formats and capsule stacks drive repeat purchase velocity.
- BHB Esters:Ketone esters achieve faster plasma elevation than salts through direct hepatic metabolism without mineral load. Sports nutrition brands in Australia and the United States command premium positioning for pre-workout and endurance protocols where rapid ketosis onset matters.
- MCT Oil:Medium-chain triglycerides convert hepatically to ketone bodies through beta-oxidation rather than direct ketone delivery.
- Medium-Chain Triglycerides:Structured MCT formulations with defined C8:C10 ratios optimize ketogenic yield per caloric unit.
Volume placements concentrate in BHB Salts; the faster expansion belongs to BHB Esters.
Application:
Cost tiers separate commodity nutritional supplements from reimbursement-backed clinical therapies.
- Health Supplements:The most mature channel with established GRAS status and direct-to-consumer distribution. Mass-market positioning in the United States and Germany relies on subscription models and influencer marketing rather than pharmacy retail.
- Sports Nutrition:Premium formulations target competitive athletes and fitness enthusiasts with performance claims requiring stricter substantiation. TGA registration in Australia and NSF Certified for Sport protocols in the United States create compliance moats against generic competitors.
- Functional Foods:Ketone fortification of beverages and bars demands heat-stable formulations and masking technologies for taste neutrality.
- Pharmaceuticals:Clinical-grade ketone therapies for neurodegenerative and metabolic indications require GMP manufacturing and investigational new drug pathways.
Revenue depth concentrates in Health Supplements; margin expansion is climbing the fastest in Pharmaceuticals.
End User:
Customer type determines dosing precision, delivery format preferences, and price elasticity.
- Athletes:Performance-focused consumers prioritize rapid ketone elevation and batch-tested purity for competition compliance. Demand clusters in endurance sports and strength disciplines where metabolic flexibility offers measurable output advantages.
- Weight Watchers:Sustained ketosis maintenance drives preference for palatable, convenient formats with clear macronutrient labeling.
- Diabetics:Glycemic management applications require clinical supervision and glucose monitoring integration.
- Elderly Population:Cognitive health positioning targets age-related metabolic decline with emphasis on swallowability and drug interaction profiles.
Current volume concentrates among Athletes; demographic expansion is gaining share fastest among the Elderly Population.
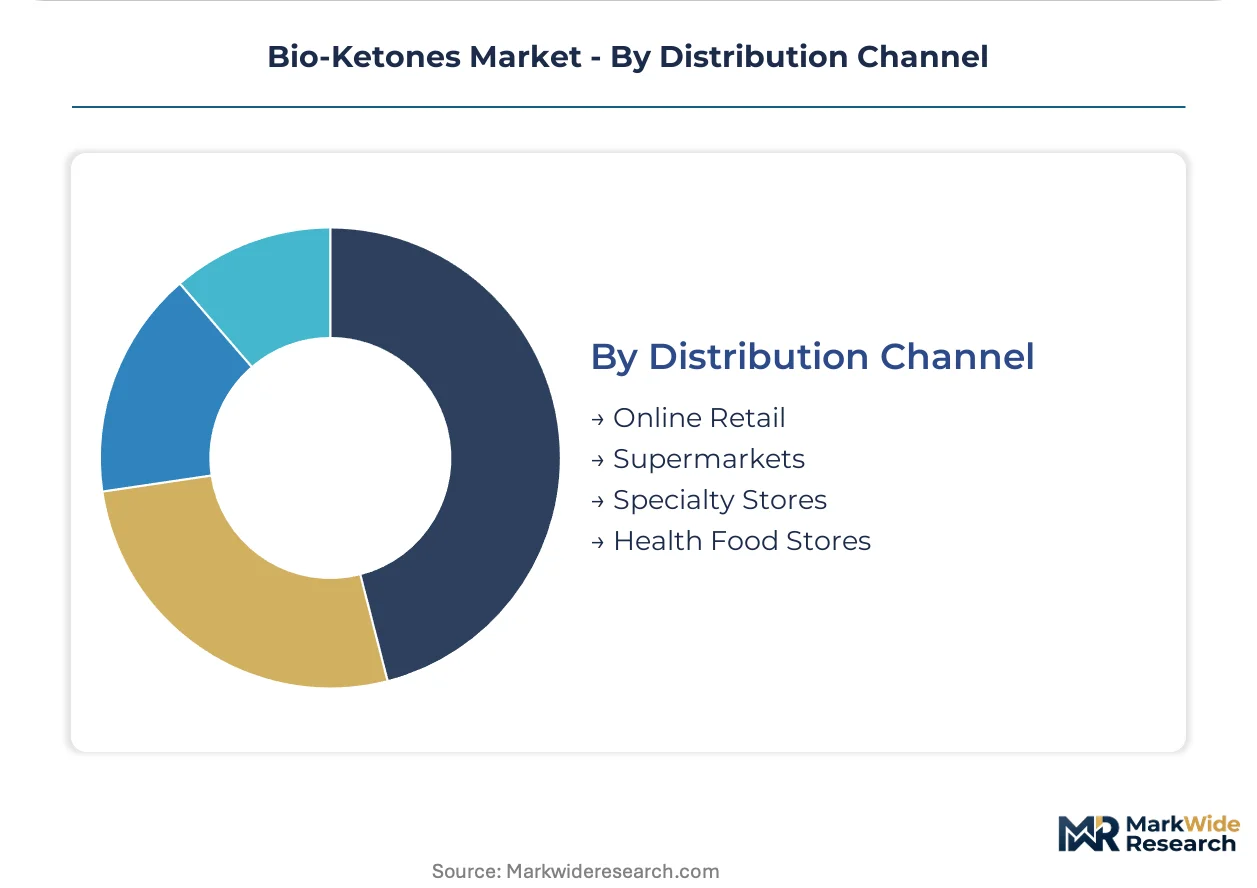
Distribution Channel:
Channel selection reflects purchase frequency, education requirements, and regulatory exposure.
- Online Retail:Direct-to-consumer platforms capture subscription revenue and first-party data for personalization. Amazon and specialized wellness platforms dominate in the United States, while European markets fragment across national e-pharmacy networks.
- Supermarkets:Mass retail placement requires slotting fees and standardized packaging for shelf efficiency.
- Specialty Stores:GNC and equivalent chains provide trained staff consultation for complex product comparisons.
- Health Food Stores:Independent retailers with naturopathic credentials influence early adopter purchase decisions.
Transaction volume concentrates in Online Retail; the steepest expansion trajectory belongs to Health Food Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leverkusen anchors European bio-ketone manufacturing through Bayer's legacy chemical infrastructure repurposed for fermentation-derived specialty ingredients. Industrial biotechnology clusters in Germany's Rhineland region concentrate GMP-certified production capacity for pharmaceutical-grade ketone supply chains.
Germany
Pharmaceutical-grade ketone demand from Merck KGaA's Darmstadt operations drives fermentation capacity expansion in the Rhine-Main cluster. REACH compliance protocols enforced by ECHA favor established operators with dedicated toxicology dossiers. The country's Baden-Württemberg region concentrates enzyme engineering expertise that reduces microbial strain scale-up risk for commercial bio-ketone output.
United States
Ketogenic sports nutrition brands in Austin and Los Angeles drive BHB ester formulation demand through direct-to-consumer subscription models. FDA GRAS notification pathways govern novel food ingredient market entry for fermentation-derived ketones. California's Bay Area biotech corridor hosts gas-fermentation pilots converting industrial emissions into ethanol precursors for ketone synthesis.
China
Feedstock cost advantages in Shandong Province support sugar-fed bioreactor operations for commodity ketone intermediate production. SAMR's evolving novel food approval timelines create inventory stranding risks for exporters targeting dual domestic and international markets. The Yangtze River Delta concentrates contract fermentation capacity serving global supplement brands.
Australia
Endurance athlete communities in Melbourne and Sydney command premium positioning for rapid ketone elevation protocols in pre-workout formulations. TGA registration requirements for performance claims create compliance moats against generic competitors entering the sports nutrition channel. Queensland's sugarcane belt provides regional feedstock security for fermentation-based ingredient manufacturing.
Netherlands
Food-grade certification infrastructure in Rotterdam's port zone supports premium ingredient re-export throughout European distribution networks. EFSA's tightened purity thresholds for novel food ingredients mandate metabolite profiling capabilities concentrated among Dutch analytical chemistry service providers. The Eindhoven region's industrial biotechnology ecosystem accelerates continuous bioprocessing adoption for ketone manufacturing.
Bio-Ketones Market Competitive Environment
The competitive structure tilts toward fermentation technology specialists with integrated regulatory affairs capabilities. Market concentration remains moderate, with distinct tiers separating pharmaceutical-grade GMP operators from commodity food-grade suppliers. Three archetypes dominate: gas-fermentation platform companies leveraging carbon capture economics, precision fermentation houses optimizing microbial strain yields, and diversified chemical incumbents retrofitting petrochemical assets. Capacity expansion and strategic technology licensing represent the dominant competitive moves as petroleum-derived ketone margins compress under carbon pricing regimes.
Within the gas-fermentation archetype, LANZATECH exemplifies platform technology positioning for industrial emissions conversion. Among diversified chemical incumbents, Eastman Chemical Company and Celanese Corporation occupy positions reflecting petrochemical heritage with bio-based pivot potential. Genomatica, Inc represents the precision fermentation specialist tier focused on engineered microbial strain development for commercial ketone output.
| Leading Market Players |
|---|
| LANZATECH |
| Merck KGaA |
| Eastman Chemical Company |
| Genomatica, Inc |
| Bio Brands LLC |
| Caldic B.V. |
| Green Biologics Limited |
| Celanese Corporation |
| Biokemik |
| Others |
Value Chain & Pricing Dynamics
Industrial bioprocess engineering talent pools in Germany's Rhine-Main cluster widen pricing-tier spreads between pharmaceutical-grade and commodity food-grade ketone outputs. Labor-cost differentials between GMP-certified fermentation specialists and standard bioreactor operators translate directly into margin structures that separate premium BHB ester formulations from bulk BHB salt powders.
Pricing Analysis
Plasma ketone elevation speed anchors value-based pricing for sports nutrition applications, with BHB esters commanding substantial premiums over mineral-bound salt alternatives. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade certification levels segments buyers by purity requirements and regulatory exposure. Cost compression in commodity ketone intermediates is intensifying because Brazilian ethanol market volatility transmits rapidly to fermentation feedstock economics. Contract manufacturers serving clinical nutrition channels exhibit lowest price sensitivity due to reimbursement-backed demand, while direct-to-consumer supplement brands face acute margin pressure from influencer marketing cost inflation.
Supply Chain Analysis
Single-source vulnerability sits with chromatographic separation infrastructure concentrated among three European contract manufacturers serving pharmaceutical-grade ketone demand. Production gravity centers on Germany, the United States, and China, with each geography specializing in distinct certification tiers and downstream applications. Feedstock supply draws from corn and sugarcane agricultural markets anchored in the American Midwest and Brazilian Center-South regions. Tariff exposure on fermentation-derived imports into the European Union creates inventory stranding risks for dual-market producers. Distribution runs through direct-to-consumer platforms capturing subscription revenue, with specialized e-pharmacy networks fragmenting European channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration dossiers and EFSA novel food approvals erect barrier-to-entry moats favoring incumbent operators with dedicated regulatory affairs infrastructure.
For Market Incumbents: Deepen backward integration into gas-fermentation carbon capture partnerships with steel and cement producers to secure feedstock cost advantages against sugar-dependent competitors. Expand GMP-certified capacity in Germany's Rhineland cluster to capture clinical nutrition demand as hospital formulary adoption accelerates. Petrochemical ketone substitution threats from propylene-derived acetone and MEK require continuous bioprocessing investments that compress capital intensity per unit output.
For New Entrants and Emerging Players: Hospital formulary directors for metabolic therapy protocols represent an underserved buyer archetype with reimbursement-driven purchasing power distinct from saturated consumer supplement channels. White-space concentration appears in neurodegenerative clinical applications where investigational new drug pathways precede commercial scale requirements. Australia's TGA-registered sports nutrition market offers lower regulatory friction than FDA GRAS notification timelines for rapid market entry. Partner with athlete-influencer networks for direct-to-consumer subscription traction before pursuing pharmacy retail placement.
For Investors and Strategic Acquirers: The window for entry favors precision fermentation specialists with engineered microbial strain IP and established EFSA dossier positions. Long-term viability over the next decade hinges on carbon credit monetization capabilities stacking EU ETS allowances with voluntary market instruments. Watch for first-mover advantages in SAMR novel food approvals as the signal indicating which platforms will capture Asian market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Real-time quality control capabilities at Dutch facilities compress capital intensity per fermentation run. |
| Gas-Fermentation Capacity Buildout | Carbon capture integration with steel plant emissions collapses accounting boundaries for sustainable ketone production. |
| Pharmaceutical-Grade Certification Investment | GMP manufacturing protocols at Merck KGaA's Darmstadt operations anchor clinical therapy supply chains. |
| Novel Food Approval Pathway Expansion | EFSA metabolite profiling capabilities preempt compliance requirements for premium ingredient positioning. |
| Direct-to-Consumer Channel Development | Subscription models bypass pharmacy retail slotting fees and capture first-party data for personalization. |
Study Parameters
Independent corroboration across fermentation technology licensors, contract manufacturing executives, and sports nutrition brand formulators underwrites the qualitative findings presented herein. Primary fieldwork encompassed technical directors at industrial biotechnology clusters, regulatory affairs specialists navigating EFSA and FDA pathways, procurement leads at downstream supplement brands, and analytical chemistry service providers supporting metabolite profiling requirements. Secondary validation drew from REACH registration databases, EFSA novel food opinions, FDA GRAS notification filings, and customs trade data tracking ketone intermediate flows. Bottom-up capacity assessments triangulated against top-down demand modeling across application segments.
Rate-of-change decomposition structured the analytical framework, disaggregating volume expansion into feedstock cost trajectory, certification timeline acceleration, and channel shift velocity across the projection horizon. Segmentation dimensions modeled encompassed product type tier, application channel, end-user archetype, and regional regulatory cluster. CAGRs derived from historical fermentation capacity commissioning patterns and elasticity estimates for ketone elevation protocols in sports nutrition. Industry-specific forecast inputs incorporated EU ETS carbon price scenarios and evolving EFSA purity threshold guidance.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to feedstock agricultural commodity volatility and cross-jurisdictional approval timeline divergence. Forecasts reflect documented assumptions regarding microbial strain yield improvements and carbon capture infrastructure deployment rates. Specific risks that could revise projections include SAMR regulatory acceleration in China, novel food approval delays at EFSA, and petrochemical ketone cost compression from propylene supply expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market