
 Dimethylolpropionic Acid (DMPA) Market | 2026-2036
Dimethylolpropionic Acid (DMPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethylolpropionic Acid (DMPA) Market Outlook
Polyester polyol is hardening its position as the preferred hydrophilic chain extender in waterborne polyurethane dispersions, displacing alternative carboxylated diols in cost-sensitive formulations. Perstorp Specialty Chemicals AB leverages its Scandinavian feedstock integration to sustain margin stability across high-purity grades. Jiangxi Selon Industrial Co., Ltd. anchors Chinese domestic supply through captive pentaerythritol derivatives capacity. Lanxess competes on REACH-registered product lines with specialized anionic DMPA variants for European coatings formulators.
Dimethylolpropionic acid is a dihydroxyl carboxylic acid with the molecular formula C5H10O4, synthesized via base-catalyzed condensation of formaldehyde with isobutyraldehyde followed by Cannizzaro oxidation, functioning primarily as an internal emulsifier and chain extender in water-dispersible polyurethane systems. Water-soluble DMPA dominates volume flows due to its compatibility with ambient-cure acrylic-polyurethane hybrid resins, while high-purity DMPA commands premium positioning in electronics-grade coatings where ionic contamination thresholds are stringent. Anionic DMPA variants are gaining share in automotive basecoat formulations as OEMs migrate from solvent-borne to water-borne refinish protocols.
REACH registration requirements under ECHA govern DMPA import and formulation placement in the European Union, while China's MEE enforces VOC content ceilings in industrial protective coatings through successive GB standard revisions. The US EPA maintains TSCA Section 5 scrutiny on new chemical modifications to DMPA derivatives used in adhesive applications. Stakeholders must monitor regulatory divergence between EU F-Gas phase-down timelines and China's dual carbon goals as these frameworks reshape polyurethane dispersion chemistry roadmaps and capital allocation priorities for chain extender capacity.
Market Dynamics
Automotive OEM waterborne coating mandates are compressing solvent-based polyurethane timelines and concentrating DMPA procurement among coatings formulators with verified low-VOC supply chains.
Growth Catalysts
- China's GB 30981 VOC ceilings:Industrial protective coatings must achieve waterborne formulation thresholds by 2025, forcing chain extender substitution toward DMPA-based dispersions.
- Electronics-grade purity requirements:Semiconductor fabrication equipment coatings now specify ionic contamination limits below 50 ppm, filtering demand toward high-purity DMPA grades.
- Yangtze River Delta cluster expansion:Captive formaldehyde-isobutyraldehyde integration at Jiangxi and Zhejiang production sites is reducing import dependency for Chinese polyurethane manufacturers.
Market Restraints
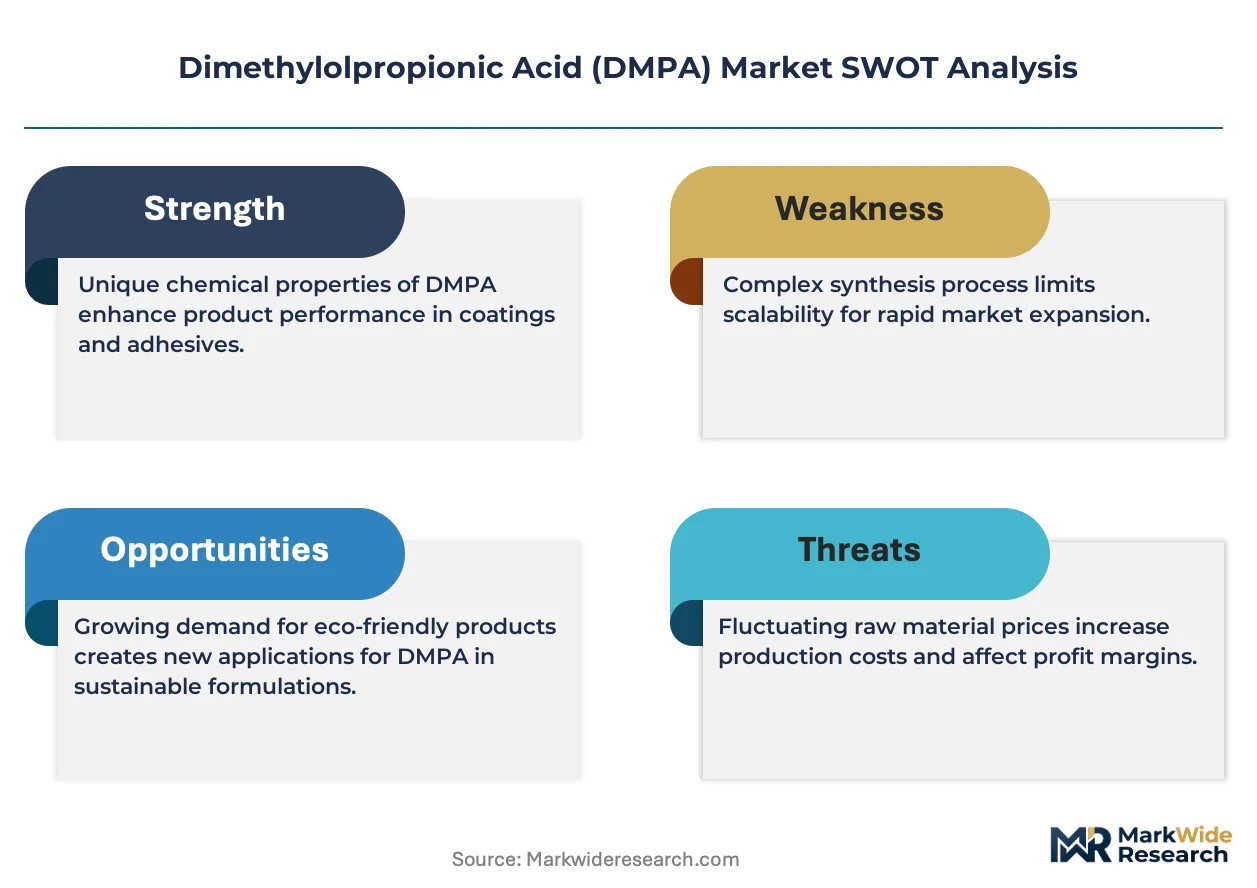
- Formaldehyde feedstock volatility:Methanol-to-formaldehyde cost swings propagate directly into DMPA unit economics, compressing margin stability for non-integrated producers.
- Scandinavian supply concentration:Perstorp's pentaerythritol derivative integration creates single-source risk for European high-purity grades during force majeure events.
- Carboxylated polyester diol substitution:Cost-sensitive footwear adhesive formulators in Southeast Asia are reverting to adipic acid-based chain extenders where water resistance requirements permit.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic DMPA production incentives under the production-linked initiative could localize supply for Mumbai-Pune automotive coatings corridors.
- UV-curable waterborne hybrid convergence:Photoinitiator-compatible DMPA variants are opening architectural wood coating applications with dual-cure performance requirements.
- EU F-Gas phase-down alignment:REACH-registered DMPA with reduced fluorinated surfactant dependency is capturing reformulation contracts from HVAC insulation foam producers.
Industry Challenges
- REACH registration data gap closure:ECHA's 2023 substance evaluation dossier updates require additional chronic toxicity studies, extending compliance timelines for import-dependent formulators.
- Waterborne-solvent hybrid line conversion:Automotive refinish shops face six-month equipment reconfiguration cycles when migrating basecoat spray systems to DMPA-dispersion compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethylolpropionic Acid (DMPA) Market |
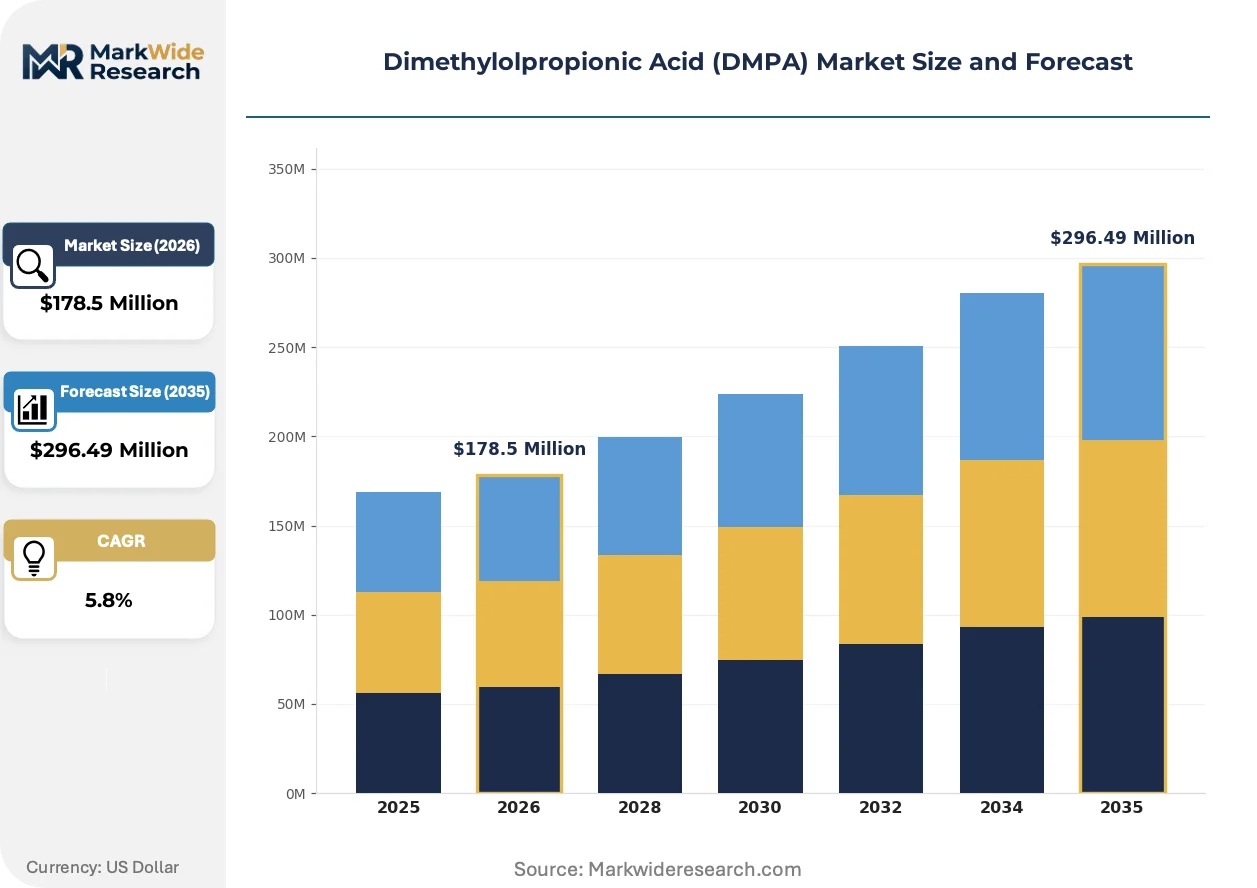
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $296.49 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Soluble DMPA, Anionic DMPA, Glycidyl DMPA, High-Purity DMPA Application: Acrylic Resins, Coatings, Adhesives, Paints End User: Construction, Automotive, Electronics, Consumer Goods Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Jiangxi Selon Industrial Co., Ltd., Lanxess, Perstorp Specialty Chemicals AB, Merck & Co., Inc., Dow Chemical Company, GEO Specialty Chemicals, BASF SE, Evonik Industries AG, Henan Tianfu Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethylolpropionic Acid (DMPA) Market Strategic Shifts
Reactive diluent chemistry and anionic stabilization protocols are converging to expand DMPA functionality beyond traditional polyurethane dispersions into radiation-curable and powder-coating hybrids.
Bio-based formaldehyde feedstock pathways are electrifying carbon accounting for DMPA production, with forestry-integrated methanol capture now qualifying for EU Green Deal taxonomy alignment. Automotive OEM sustainability scorecards are accelerating validation timelines for these grades. The structural consequence is a bifurcation between mass-market petrochemical-derived DMPA and premium bio-attributed certificates.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone (NMP) are forcing polyurethane dispersion producers to eliminate co-solvent carriers in favor of pure waterborne DMPA chain extension. German coatings formulators face the steepest compliance cliffs given their NMP-dependent legacy infrastructure. The response is accelerated pilot-line testing of high-solids DMPA variants at Leverkusen and Hamburg technical centers.
Specification-driven procurement now dominates DMPA buying, with Tier-1 automotive suppliers mandating lot-specific ionic contamination certificates and batch traceability to formaldehyde source. Direct mill-to-formulator contracts are displacing distributor intermediaries in the European automotive refinish channel. This pattern is most visible in Stuttgart and Munich supplier parks, where BASF and Covestro operate integrated dispersion laboratories.
Dimethylolpropionic Acid (DMPA) Market Segmentation
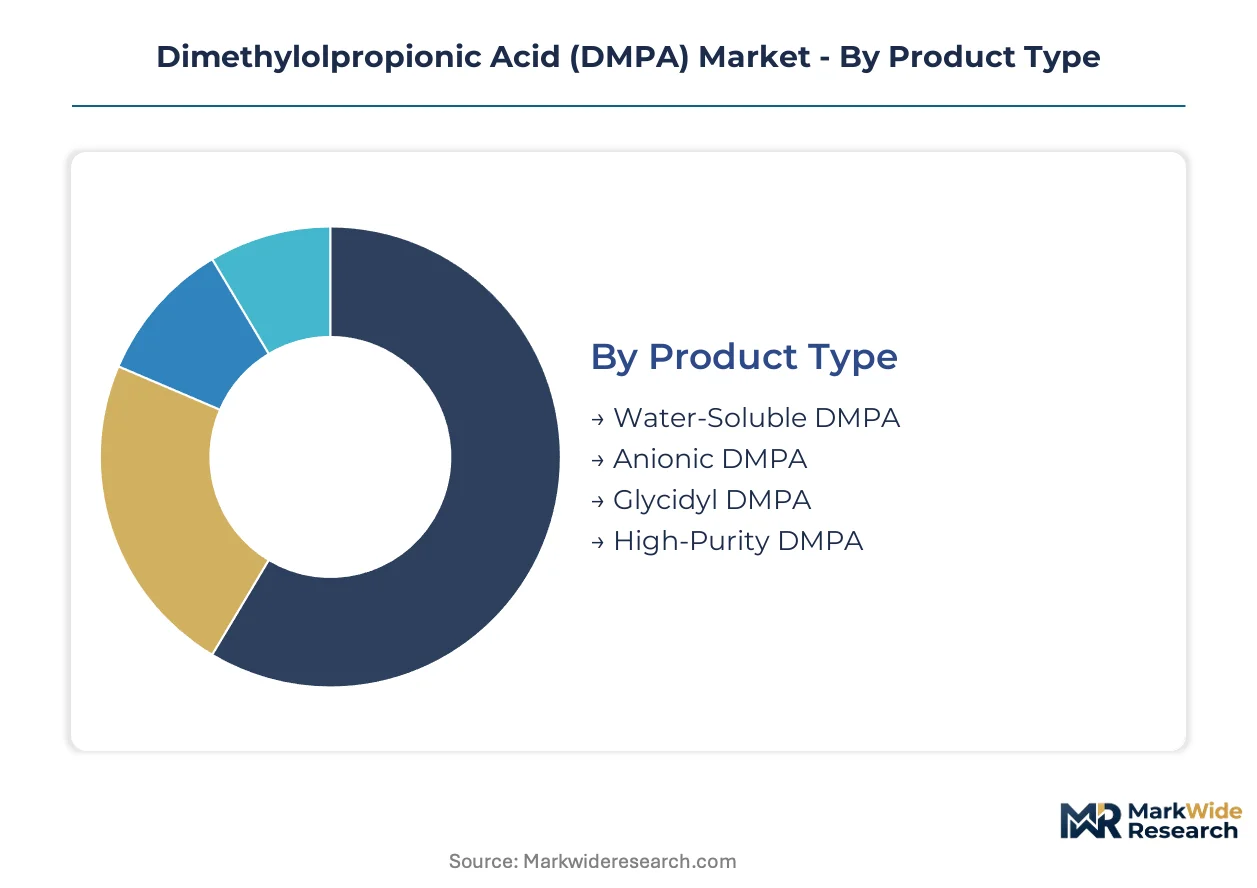
DMPA's functional versatility across polyurethane chemistry creates distinct demand profiles by purity grade and ionic character. Segmentation reveals how automotive OEM mandates, electronics contamination thresholds, and construction adhesive specifications partition the market into non-substitutable product tiers.
Product Type:
Integration depth varies sharply: water-soluble and anionic grades dominate embedded polyurethane dispersion formulations, while high-purity variants command standalone specification in semiconductor equipment coatings.
- Water-Soluble DMPA:Standard-grade dihydroxyl carboxylic acid with ambient-temperature dispersion stability. Demand concentrates in China's Yangtze River Delta for acrylic-polyurethane hybrid resins serving construction sealants, pressured by GB standard VOC compliance deadlines.
- Anionic DMPA:Carboxylate-functional chain extender with enhanced emulsion stability in neutral pH systems. Automotive basecoat formulators in Stuttgart and Munich supplier parks specify this grade for waterborne refinish protocols migrating from solvent-borne systems.
- Glycidyl DMPA:Epoxy-functional derivative for cationic electrodeposition primers.
- High-Purity DMPA:Electronics-grade specification with ionic contamination below 50 ppm for semiconductor fabrication equipment coatings.
Water-soluble DMPA leads volumes today; high-purity DMPA is gaining share fastest.
Application:
Cost tier stratification separates commodity coatings from specification-driven electronics and automotive segments where contamination certificates command premium positioning.
- Acrylic Resins:Hydrophilic chain extension for water-dispersible acrylic-polyurethane hybrids. Construction sealant formulators in India's Mumbai-Pune corridor under PLI scheme incentives drive procurement localization.
- Coatings:Internal emulsifier for industrial protective and automotive refinish systems. German formulators at Leverkusen and Hamburg technical centers pilot high-solids variants to eliminate NMP co-solvents under REACH Annex XVII pressure.
- Adhesives:Footwear and flexible packaging bonding applications.
- Paints:Architectural and decorative waterborne formulations.
Coatings dominate value capture; acrylic resins show steepest expansion trajectory.
End User:
Customer type segmentation maps directly to certification requirements: automotive and electronics buyers mandate batch traceability, while construction and consumer goods prioritize unit economics.
- Construction:Sealants, waterproofing membranes, and flooring adhesives. Chinese polyurethane manufacturers in Jiangxi and Zhejiang provinces leverage captive formaldehyde-isobutyraldehyde integration to reduce import dependency.
- Automotive:OEM basecoats, clearcoats, and refinish systems. Tier-1 suppliers in Stuttgart and Munich parks enforce lot-specific ionic contamination certificates, displacing distributor intermediaries with direct mill contracts.
- Electronics:Semiconductor fabrication equipment and printed circuit board coatings.
- Consumer Goods:Footwear, textiles, and flexible packaging adhesives.
Construction anchors volume today; automotive is climbing the fastest.
Distribution Channel:
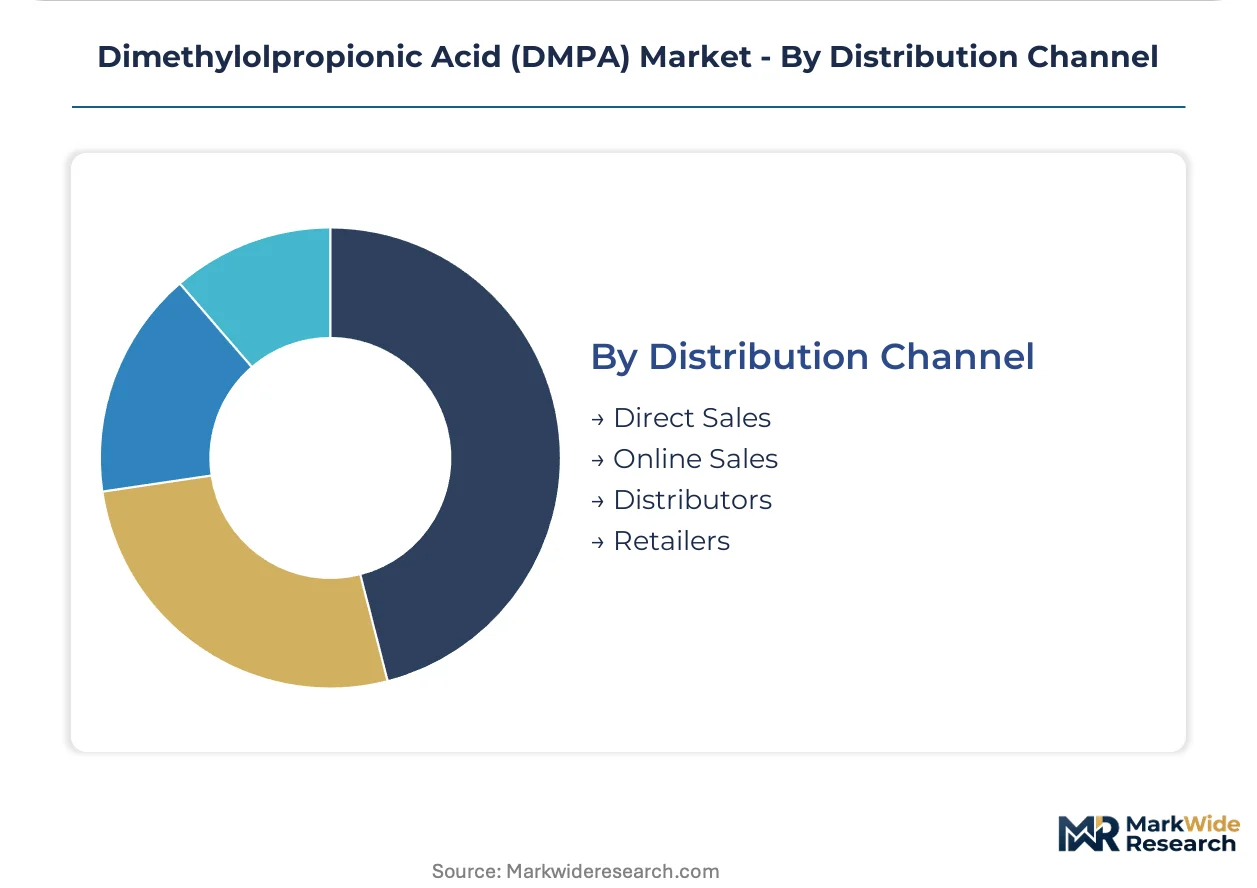
Supply concentration in Scandinavian and Chinese production clusters shapes channel economics, with direct sales capturing specification-driven segments and distributors retaining cost-sensitive flows.
- Direct Sales:Mill-to-formulator contracts with batch traceability and certificate of analysis documentation. European automotive refinish channel shows fastest displacement of intermediaries.
- Distributors:Regional inventory positioning for small-batch construction and consumer goods formulators.
- Online Sales:Technical data sheet access and sample procurement for R&D laboratories.
- Retailers:Limited presence in specialty chemical segments; negligible for DMPA.
Direct sales lead value capture; distributors retain volume share in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta chemical manufacturing corridor concentrates the dominant share of DMPA production capacity and derivative polyurethane formulation demand worldwide.
China
Automotive waterborne coating mandates and industrial protective coatings under GB 30981 VOC ceilings drive DMPA procurement acceleration. The Ministry of Ecology and Environment enforces successive GB standard revisions tightening solvent-based system compliance. Jiangxi and Zhejiang provinces host captive formaldehyde-isobutyraldehyde integration reducing import dependency for domestic polyurethane manufacturers.
Germany
Automotive basecoat formulators in Stuttgart and Munich supplier parks specify anionic DMPA grades for waterborne refinish protocols. ECHA REACH registration requirements govern import and formulation placement with Annex XVII N-methyl-2-pyrrolidone restrictions forcing co-solvent elimination. Leverkusen and Hamburg technical centers pilot high-solids DMPA variants to accelerate compliance timelines.
United States
Electronics-grade coatings for semiconductor fabrication equipment specify ionic contamination thresholds below 50 ppm filtering demand toward high-purity DMPA. The EPA maintains TSCA Section 5 scrutiny on new chemical modifications to DMPA derivatives in adhesive applications. Texas and Louisiana chemical corridors concentrate methanol-to-formaldehyde feedstock capacity propagating cost volatility into DMPA unit economics.
India
Construction sealant formulators in the Mumbai-Pune corridor drive procurement localization under PLI scheme incentives for specialty chemicals. The Bureau of Indian Standards enforces progressive industrial coating VOC content regulations aligning with automotive OEM sustainability scorecards. Maharashtra and Gujarat states anchor projected domestic DMPA production capacity to serve regional polyurethane dispersion demand.
Sweden
Scandinavian feedstock integration sustains margin stability for high-purity DMPA grades serving European electronics and automotive specification markets. EU F-Gas phase-down timelines and EU Green Deal taxonomy alignment accelerate bio-attributed formaldehyde pathway validation. Perstorp's pentaerythritol derivative integration creates concentrated supply positioning for REACH-registered product lines.
Dimethylolpropionic Acid (DMPA) Market Competitive Environment
Capacity expansion dominates the current landscape as producers secure captive formaldehyde-isobutyraldehyde integration to buffer feedstock volatility. The vendor base separates into three strategic tiers: integrated petrochemical majors with backward control over methanol derivatives, regional specialists leveraging geographic proximity to automotive and electronics clusters, and bio-attributed certificate pioneers qualifying for EU Green Deal procurement preferences. Geographic expansion and portfolio diversification toward high-purity and anionic variants represent the dominant competitive moves reshaping supply positioning.
Among Scandinavian-integrated specialists, Perstorp Specialty Chemicals AB exemplifies feedstock-anchored margin stability across high-purity grades. Within Chinese domestic supply, Jiangxi Selon Industrial Co., Ltd. occupies a position reflecting captive pentaerythritol derivatives capacity in the Yangtze River Delta corridor. On the European regulatory-compliance vector, Lanxess represents REACH-registered positioning with specialized anionic variants for coatings formulators navigating ECHA substance evaluation requirements.
| Leading Market Players |
|---|
| Jiangxi Selon Industrial Co., Ltd. |
| Lanxess |
| Perstorp Specialty Chemicals AB |
| Merck & Co., Inc. |
| Dow Chemical Company |
| GEO Specialty Chemicals |
| BASF SE |
| Evonik Industries AG |
| Henan Tianfu Chemical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Formaldehyde feedstock volatility propagates through DMPA unit economics from methanol derivative markets into three-tier pricing structures across premium, standard, and economy levels, with Scandinavian and Chinese production clusters anchoring divergent cost positions for coatings formulators.
Pricing Analysis
Input-cost pass-through from methanol-to-formaldehyde conversion dominates DMPA pricing, with Perstorp's Scandinavian pentaerythritol integration buffering margin compression against Jiangxi Selon's Yangtze River Delta captive supply. Price differentiation separates electronics-grade high-purity certificates from construction-grade water-soluble volumes. Cost compression in standard grades intensifies because Southeast Asian footwear adhesive formulators revert to adipic acid-based chain extenders. Construction sealant buyers in India's Mumbai-Pune corridor show highest price sensitivity; automotive Tier-1 suppliers in Stuttgart and Munich parks accept premium positioning for lot-specific ionic contamination documentation.
Supply Chain Analysis
Single-source vulnerability sits with Perstorp's Scandinavian high-purity grades during force majeure events, while Chinese formaldehyde-isobutyraldehyde integration at Jiangxi and Zhejiang sites reduces European import dependency. Supply concentrates in Sweden, China, and Germany for REACH-registered and GB-compliant specifications. Raw material dependencies include methanol derivatives, isobutyraldehyde, and pentaerythritol co-product streams. Tariff exposure looms for EU formulators sourcing Chinese water-soluble grades under evolving trade remedy frameworks. Distribution runs through direct mill-to-formulator contracts in automotive and electronics segments, with regional distributors retaining construction and consumer goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DMPA procurement patterns reward geographic arbitrage between EU REACH compliance costs and Chinese GB standard enforcement timelines, with feedstock-integrated producers capturing margin stability across divergent regulatory implementation schedules.
For Market Incumbents: Cement feedstock-anchored positioning by deepening backward integration into methanol-formaldehyde derivatives at Yangtze River Delta and Scandinavian production clusters. Carboxylated polyester diol substitution in Southeast Asian footwear adhesives threatens volume retention; counter via high-purity grade certification investment for semiconductor equipment coatings. Prioritize captive isobutyraldehyde supply over distributor channel control.
For New Entrants and Emerging Players: Launch via direct technical service partnerships with automotive refinish shops in India's PLI scheme corridors, bypassing established distributor relationships. White-space targets include UV-curable waterborne hybrid formulations for architectural wood coatings and bio-attributed formaldehyde pathways qualifying for EU Green Deal taxonomy. The most penetrable segment is construction sealants under India's Bureau of Indian Standards VOC alignment timeline.
For Investors and Strategic Acquirers: Consolidation pressure builds where formaldehyde feedstock volatility exposes non-integrated producers to margin compression against Scandinavian and Chinese captive supply bases. Long-term viability favors producers with dual REACH-GB registration coverage and high-purity grade portfolios. Acquisition target archetype: regional specialists with automotive cluster proximity and pending ionic contamination certification. The signal to watch is ECHA substance evaluation dossier updates extending compliance timelines for import-dependent formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive methanol-formaldehyde supply buffers Perstorp and Jiangxi Selon against feedstock volatility propagating from Texas and Louisiana chemical corridors. |
| High-Purity Grade Expansion | Ionic contamination certification below 50 ppm captures semiconductor fabrication equipment coatings specifying electronics-grade DMPA. |
| REACH-GB Dual Registration | Simultaneous ECHA compliance and GB 30981 alignment opens automotive basecoat procurement in Stuttgart, Munich, and Yangtze River Delta supplier parks. |
| Bio-Attributed Pathway Validation | Forestry-integrated methanol capture qualifies for EU Green Deal taxonomy alignment in automotive OEM sustainability scorecards. |
| Direct Mill-to-Formulator Contracts | Lot-specific batch traceability displaces distributor intermediaries in European automotive refinish channels demanding contamination certificates. |
Study Parameters
Direct dialogue with polyurethane dispersion plant managers, automotive OEM procurement leads, coatings formulator technical directors, and specialty chemical distribution channel partners grounded this analysis in operational reality. Secondary validation drew from ECHA REACH registration databases, Chinese customs and trade flow records, SEC 10-K disclosures from integrated chemical majors, and GB standard revision notices from China's Ministry of Ecology and Environment. Bottom-up segment sizing triangulated against top-down feedstock demand modeling across the analysis window.
Segment-level projections incorporated grade tier stratification, end-use industry demand profiles, and regional production hub economics throughout the forecast period. CAGRs derived from formaldehyde derivative cost curve analysis, polyurethane dispersion capacity expansion announcements, and automotive OEM waterborne coating mandate implementation schedules. Industry-specific inputs included semiconductor fabrication equipment coating contamination thresholds and India's PLI scheme incentive disbursement timelines for specialty chemicals.
Forecast precision tightens around the base case; tail outcomes carry wider variance under formaldehyde feedstock price spikes, ECHA substance evaluation delays, or accelerated NMP co-solvent elimination in German coatings formulator technical centers. Forecasts reflect documented assumptions about GB 30981 VOC ceiling enforcement timelines and EU F-Gas phase-down alignment with polyurethane dispersion chemistry roadmaps. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Salicylate Market