
 Bromocyclopentane Market | 2026-2036
Bromocyclopentane Market Size, Share, and Industry Trends Forecast 2026-2036
Bromocyclopentane Market Analysis
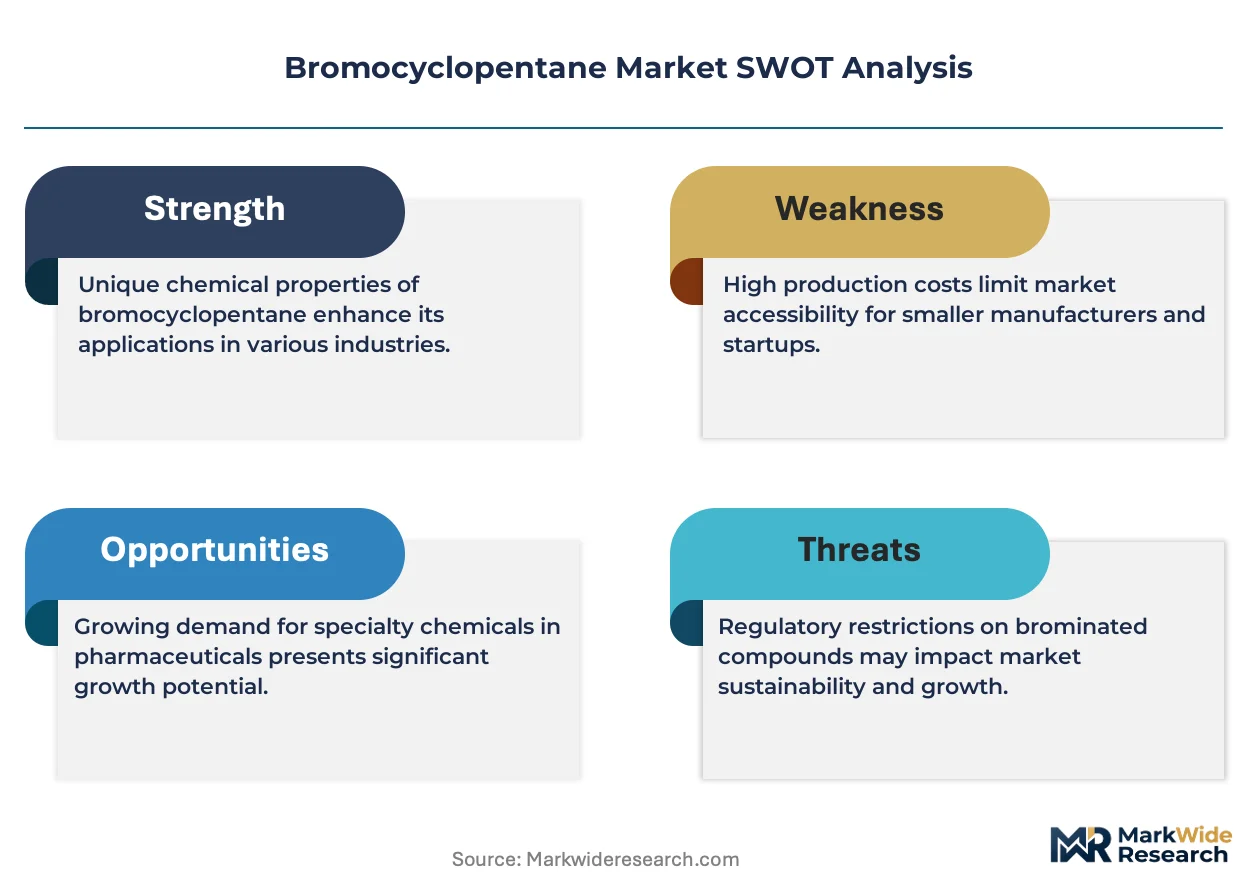
REACH compliance is restructuring the cost-of-entry calculus for European suppliers of bromocyclopentane, forcing reformulation investments that favor larger producers. Merck KGaA leverages its integrated pharmaceutical-grade supply chain to sustain premium positioning across EU member states. Wuxi Gonghe Chemical anchors volume production through backward integration into elemental bromine sourcing. Tokyo Chemical Industry Co., Ltd differentiates via ultra-high-purity catalog offerings for research institutions.
Bromocyclopentane is a cyclic alkyl bromide with the molecular formula C5H9Br, typically synthesized through free-radical bromination of cyclopentane or halogen exchange routes, and serves primarily as a versatile building block in organic synthesis and pharmaceutical intermediate production. Laboratory Grade material commands outsized margins due to stringent impurity specifications and lot-to-lot consistency requirements, while Industrial Grade volume flows predominantly into agrochemical contract manufacturing. The Reagent application segment exhibits the strongest structural momentum as flow chemistry adoption in custom synthesis shops expands demand for pre-packaged, analytically certified bromocyclopentane.
EPA oversight under the Toxic Substances Control Act shapes US market access thresholds for imported bromocyclopentane, while China's MEE enforces wastewater discharge limits on bromination facilities that elevate compliance costs for domestic producers. ECHA's ongoing substance evaluation under REACH drives substitution pressure in coatings and adhesive formulations. Stakeholders must monitor regulatory divergence between EU hazard classification updates and Asia-Pacific chemical control regimes to anticipate supply chain reconfiguration needs.
Market Dynamics
China's MEE wastewater discharge mandates are forcing bromination facilities to retool production lines, elevating compliance costs that smaller Jiangsu province operators cannot absorb. This regulatory compression is accelerating supply-side consolidation while pharmaceutical-grade demand concentrates among certified producers.
Growth Catalysts
- Flow chemistry adoption:Custom synthesis shops in Germany and Switzerland are integrating continuous-flow bromination protocols that require pre-certified reagent inputs. This technical shift locks in recurring procurement of analytically validated bromocyclopentane lots.
- India's PLI scheme for APIs:The production-linked incentive framework subsidizes domestic intermediate manufacturing, drawing contract manufacturers toward captive bromocyclopentane consumption for antiviral and oncology synthesis.
- REACH substance evaluation:ECHA's ongoing hazard review of alternative alkyl bromides is narrowing the approved intermediate list, preserving bromocyclopentane's regulatory status for EU pharmaceutical applications.
Market Restraints
- Elemental bromine price volatility:Dead Sea and Arkansas brine field output fluctuations transmit directly to bromocyclopentane feedstock costs, compressing margin predictability for non-integrated producers.
- Jiangsu supply concentration:Environmental enforcement has shuttered smaller bromination facilities, concentrating viable production among three dominant coastal operators and elevating single-source risk for international buyers.
- Fluorinated substitute development:Agrochemical formulators are piloting trifluoromethyl cyclopentane derivatives that bypass brominated intermediate steps, threatening volume erosion in crop protection applications.
Strategic Opportunities
- Vietnam chemical park expansion:The Dung Quat and Long Son industrial zones offer MEE-equivalent environmental standards with lower compliance overhead, attracting bromination facility relocation from cost-pressured Chinese producers.
- Bioconjugation demand surge:ADC linker chemistry for oncology therapeutics requires ultra-high-purity cyclic alkyl bromide building blocks, opening premium pricing tiers for GMP-certified manufacturers.
- Green chemistry procurement mandates:EU pharmaceutical multinationals are embedding atom-economy criteria into supplier scorecards, favoring bromocyclopentane producers with solvent-free bromination process certifications.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA DMF filing requirements for API intermediates extend validation cycles to 18-24 months, freezing new supplier entry and preserving incumbent positioning.
- Halogen handling workforce scarcity:Experienced bromination operators with process safety credentials are concentrating at established facilities, constraining capacity expansion at greenfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bromocyclopentane Market |
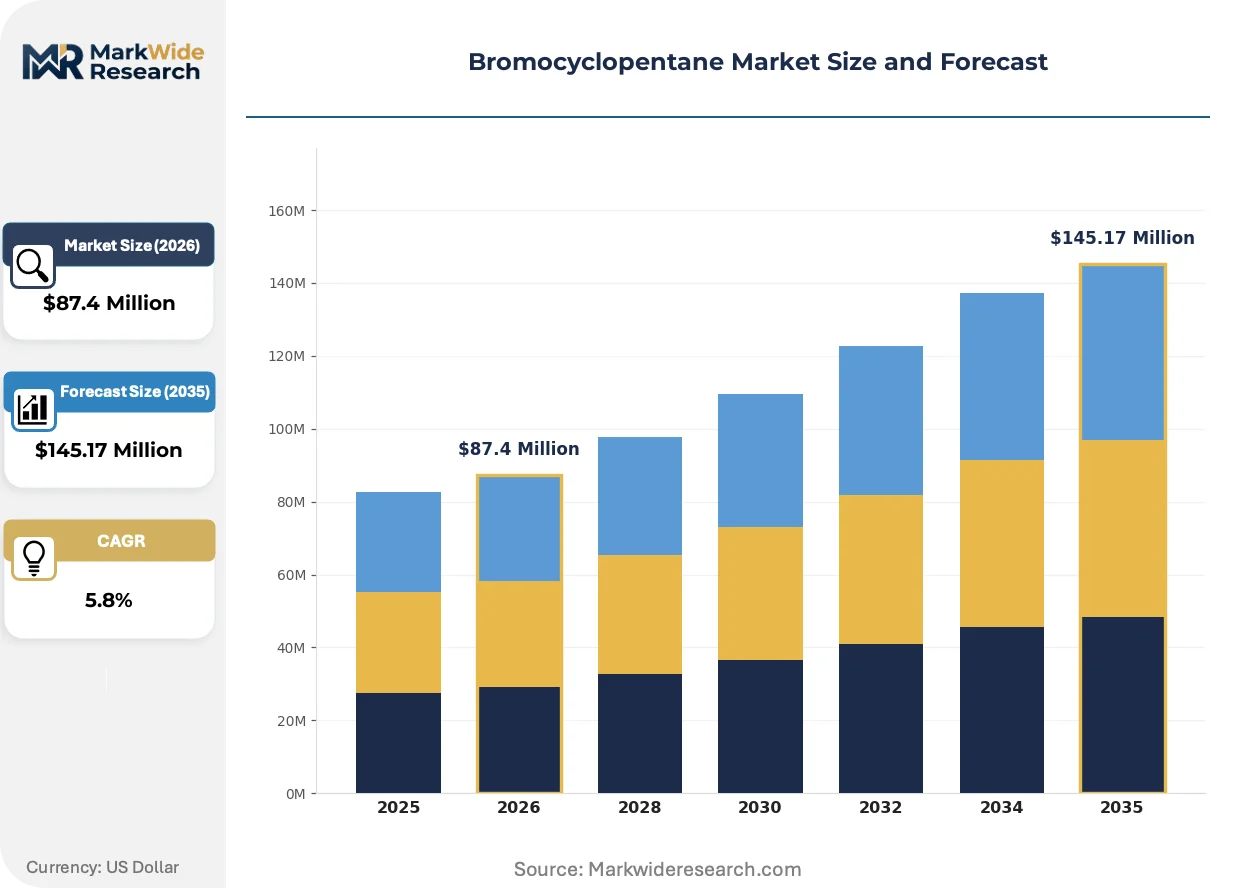
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Pharmaceutical Grade, Technical Grade Application: Solvent, Intermediate, Reagent, Additive End Use Industry: Pharmaceuticals, Agrochemicals, Automotive, Chemical Manufacturing Purity Level: ≥98%, ≥95%, ≥90%, ≥99% |
| Companies Covered | Wuxi Gonghe Chemical, Merck KGaA, Feihe Chemical, Famouschem Technology, TNJ Chemical, Triveni Chemicals, Tokyo Chemical Industry Co., Ltd, Alfa Aesar, Ningbo Inno Pharmchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bromocyclopentane Market Emerging Trajectories
Process intensification and regulatory hazard reclassification are jointly reshaping how bromocyclopentane is manufactured, certified, and procured across pharmaceutical and agrochemical value chains.
Continuous-flow bromination reactors are expanding into commercial-scale intermediate production, replacing batch-wise free-radical processes that generate solvent-intensive waste streams. German and Swiss custom synthesis CMOs are adopting these skid-mounted systems to meet atom-economy metrics embedded in EU pharmaceutical procurement tenders. The technology is expanding into Asian contract manufacturing as MEE discharge limits tighten, compressing the viable process window for conventional bromination.
REACH substance evaluation under ECHA's 2024-2026 work program is reclassifying hazard profiles for legacy alkyl bromide alternatives, narrowing the approved list for coatings and adhesive formulations. This regulatory compression preserves bromocyclopentane's regulatory standing while forcing reformulation investments among EU-based specialty chemical suppliers. Laboratory-grade suppliers are responding with expanded analytical certification packages to defend positioning against regulatory substitution pressure.
Pharmaceutical buyers are consolidating intermediate procurement through qualified supplier programs that bundle bromocyclopentane with complementary heterocyclic building blocks. This purchasing pattern shift is displacing spot-market transactions and elevating contract duration requirements for certified producers. The consolidation is most visible among mid-cap European API manufacturers seeking supply security for oncology and antiviral synthesis pipelines.
Bromocyclopentane Market Segmentation
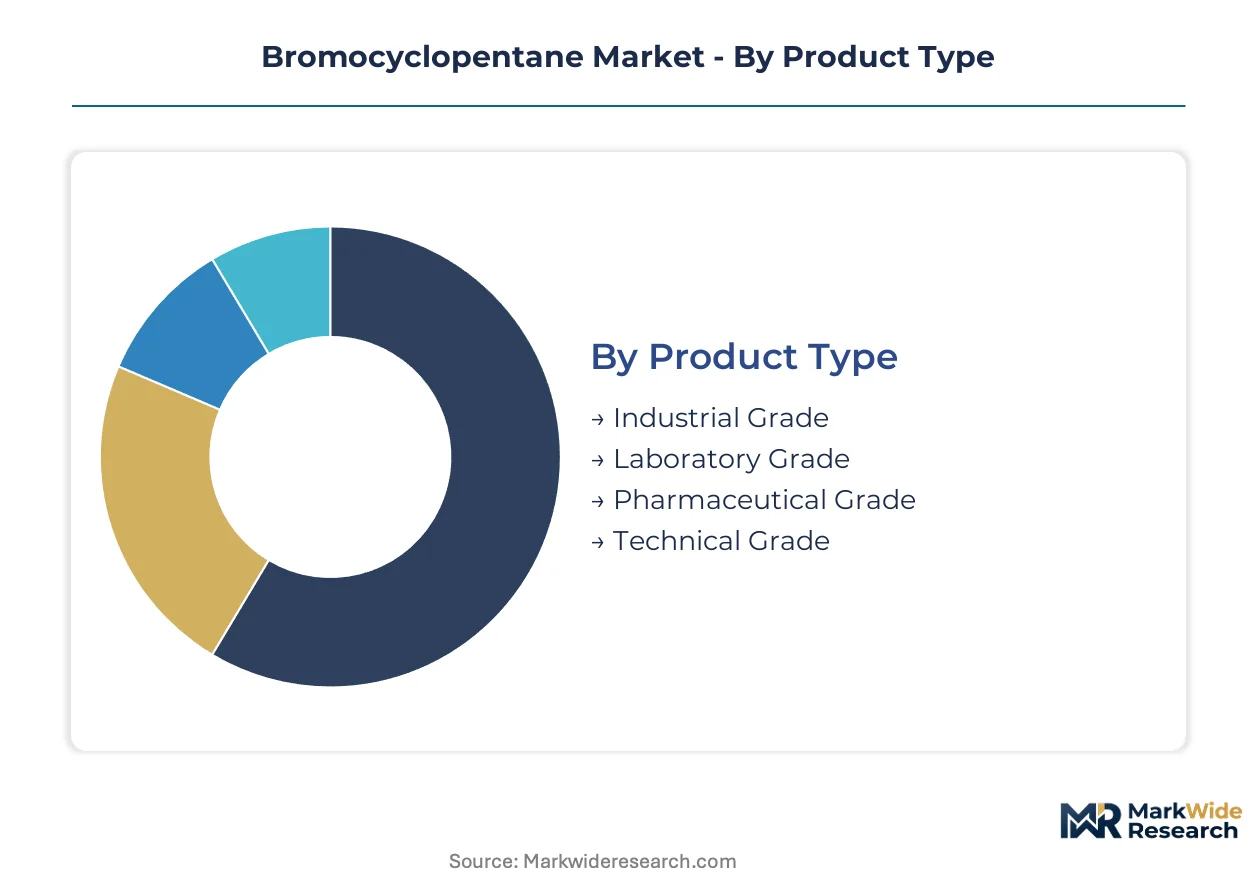
Bromocyclopentane procurement patterns diverge sharply across certification tiers, with pharmaceutical-grade specifications commanding structural premiums while industrial volumes flow through contract manufacturing channels. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economies dominate competitive positioning.
Product Type:
Volume flows concentrate in specification grades that balance purity thresholds against unit economics, while premium tiers extract value from documentation burdens and audit trails.
- Laboratory Grade:Stringent impurity specifications below 0.1% and lot-to-lot consistency requirements define this tier. Demand concentrates in German and Swiss custom synthesis shops adopting flow chemistry protocols that require pre-certified reagent inputs with full analytical packages.
- Pharmaceutical Grade:GMP-compliant production with FDA and EMA DMF filing support distinguishes this segment. Procurement is accelerating among Indian API manufacturers leveraging PLI scheme subsidies for antiviral and oncology intermediate production.
- Industrial Grade:Standard purity adequate for agrochemical contract manufacturing dominates volume flows. Specifications tolerate higher moisture content and broader batch variation.
- Technical Grade:Minimal certification requirements serve exploratory synthesis and process development applications. Price sensitivity peaks in this tier.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Functional roles in synthesis workflows determine procurement frequency, certification depth, and supplier relationship intensity across buyer segments.
- Reagent:Pre-packaged, analytically certified bromocyclopentane for direct use in bromination reactions without further purification. Demand climbs fastest among continuous-flow adopters in EU pharmaceutical CMOs requiring validated input streams.
- Intermediate:Building block status for downstream active pharmaceutical ingredient synthesis drives volume. Indian pharmaceutical manufacturers expanding under PLI incentives anchor consumption here.
- Solvent:Niche dissolution applications in specialty coatings and adhesive formulations face substitution pressure from REACH hazard reclassification of alternative alkyl bromides.
- Additive:Minor incorporation into polymer modification and lubricant formulations. Specification requirements remain less stringent than synthesis applications.
Intermediate applications retain the largest volume footprint. Reagent applications show the steepest expansion trajectory.
End Use Industry:
Regulatory exposure and synthesis complexity create divergent buyer profiles across downstream sectors.
- Pharmaceuticals:ADC linker chemistry for oncology therapeutics and antiviral API synthesis drives ultra-high-purity demand. EMA and FDA DMF requirements extend supplier validation timelines to 18-24 months.
- Agrochemicals:Crop protection intermediate production absorbs industrial-grade volume. Fluorinated substitute development threatens brominated building block demand in this sector.
- Chemical Manufacturing:Contract synthesis and custom manufacturing services span multiple purity tiers based on client specifications. Jiangsu province facilities supply this channel.
- Automotive:Minor consumption in specialty lubricant and sealant additives. Specification requirements align with industrial-grade standards.
Pharmaceuticals command the deepest certification requirements. Chemical Manufacturing offers the broadest volume base.
Purity Level:
Specification thresholds segment buyers by synthesis sensitivity and regulatory filing obligations.
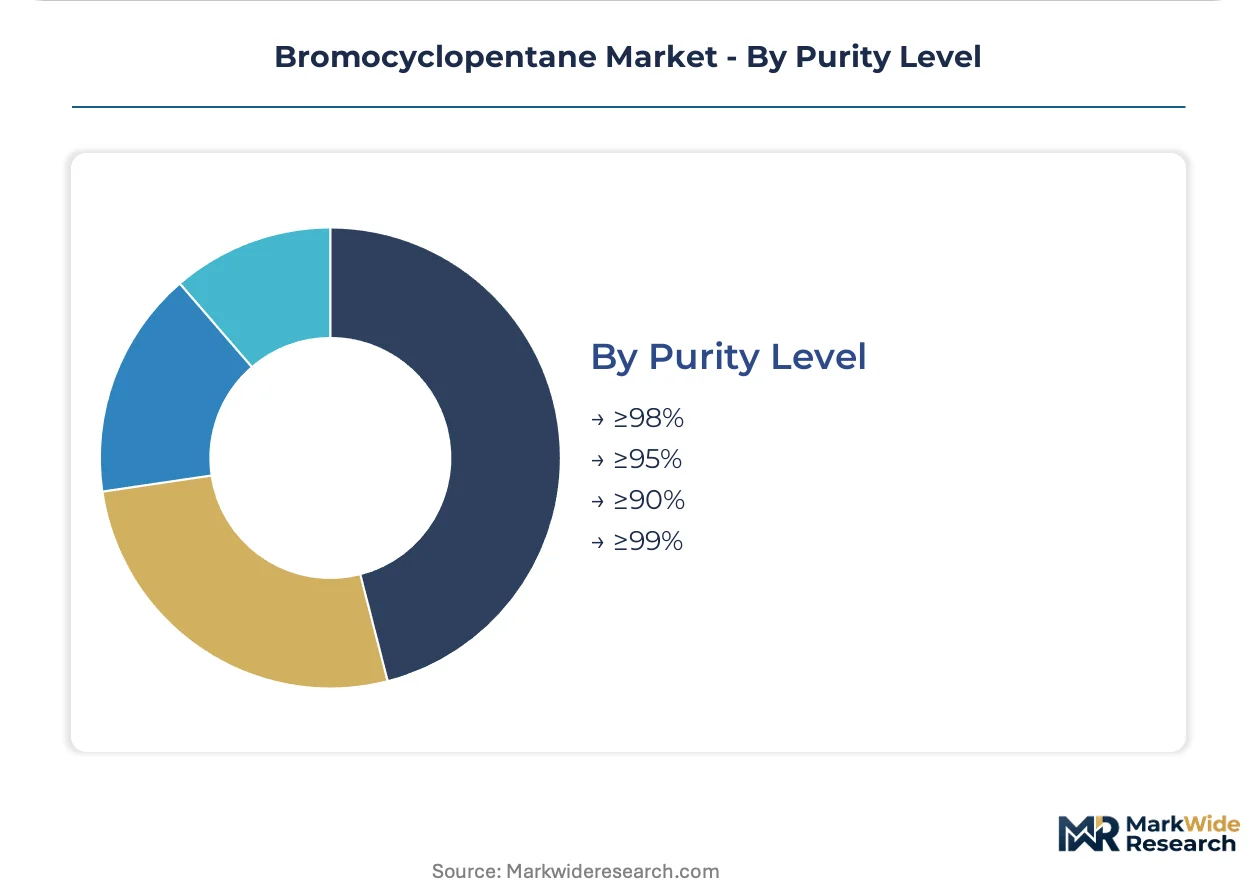
- ≥99%:Ultra-high-purity tier for bioconjugation and ADC linker chemistry. GMP-certified producers in Switzerland and Germany defend positioning through analytical package depth.
- ≥98%:Standard pharmaceutical-grade threshold for API intermediate synthesis. Indian and Chinese producers compete on validated supply security.
- ≥95%:Agrochemical and industrial chemical manufacturing specification. Volume flows through Jiangsu province bromination facilities.
- ≥90%:Technical and exploratory synthesis applications. Price competition intensifies at this threshold.
≥98% purity dominates current pharmaceutical procurement. ≥99% specifications are gaining share fastest in oncology therapeutic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Dahej Special Economic Zone and Jiangsu province's chemical industrial parks concentrate bromocyclopentane production through tax-advantaged infrastructure and integrated feedstock access. These zones anchor supply-side capacity across Asia-Pacific pharmaceutical corridors.
China
MEE wastewater discharge mandates are shuttering smaller bromination facilities in Jiangsu province, concentrating viable production among three dominant coastal operators. The Yangtze River Delta chemical cluster absorbs compliance-driven consolidation as pharmaceutical-grade demand flows toward certified producers with elemental bromine backward integration.
India
CDSCO filing requirements for API intermediates extend validation timelines to 18-24 months, freezing new supplier entry. The Gujarat industrial corridor anchors domestic bromocyclopentane consumption as PLI scheme subsidies draw contract manufacturers toward captive intermediate production for antiviral synthesis.
Germany
REACH substance evaluation under ECHA's 2024-2026 work program is narrowing approved alkyl bromide alternatives, preserving bromocyclopentane's regulatory standing. The Rhine-Ruhr chemical manufacturing belt integrates continuous-flow bromination protocols that demand pre-certified reagent inputs with full analytical packages.
Switzerland
Swissmedic GMP certification requirements defend premium positioning for ultra-high-purity cyclic alkyl bromide building blocks. Basel's pharmaceutical manufacturing cluster drives ADC linker chemistry demand for oncology therapeutics, opening premium pricing tiers for analytically validated suppliers.
United States
EPA oversight under the Toxic Substances Control Act shapes import access thresholds for bromocyclopentane. The Gulf Coast petrochemical corridor absorbs industrial-grade volume flows, though pharmaceutical procurement concentrates through qualified supplier programs bundling intermediates with complementary heterocyclic building blocks.
Bromocyclopentane Market Vendor Landscape
Chinese producers anchor volume-tier supply through integrated bromination capacity; European and Japanese specialists hold premium-grade positioning through GMP certification depth. The vendor base splits between consolidation-resistant commodity suppliers and entrenched pharmaceutical-grade incumbents. Three archetypes dominate: backward-integrated elemental bromine operators, catalog-focused ultra-high-purity specialists, and regional contract manufacturers serving API synthesis pipelines. Competitive moves center on M&A-driven consolidation in Jiangsu province and technology licensing for continuous-flow bromination protocols.
Within the integrated-production tier, Wuxi Gonghe Chemical exemplifies backward integration into elemental bromine sourcing that defends margin predictability against feedstock volatility. Merck KGaA occupies a position representing pharmaceutical-grade supply chain integration across EU member states. Tokyo Chemical Industry Co., Ltd sits within the ultra-high-purity catalog specialist archetype, differentiating through analytically certified offerings for research institutions requiring lot-to-lot consistency. These three anchors illustrate how geographic origin and certification depth stratify competitive positioning.
| Leading Market Players |
|---|
| Wuxi Gonghe Chemical |
| Merck KGaA |
| Feihe Chemical |
| Famouschem Technology |
| TNJ Chemical |
| Triveni Chemicals |
| Tokyo Chemical Industry Co., Ltd |
| Alfa Aesar |
| Ningbo Inno Pharmchem |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade procurement consolidation among Indian API manufacturers under CDSCO filing requirements is compressing spot-market liquidity and forcing supply-side certification investments that elevate pricing floors for compliant producers. This demand-side pressure transmits through Jiangsu province bromination facilities, where MEE wastewater mandates accelerate consolidation among three dominant coastal operators.
Pricing Analysis
Expedited lead-time premiums for GMP-certified bromocyclopentane lots command substantial markups over standard pharmaceutical-grade deliveries, while spot inventory discounts concentrate in technical-grade tiers with minimal documentation. Three-tier pricing structure across laboratory, pharmaceutical, and industrial grades reflects certification depth and analytical package comprehensiveness. Cost compression in industrial-grade volumes intensifies as fluorinated agrochemical substitutes erode brominated intermediate demand. Contract manufacturing buyers exhibit highest price sensitivity; ADC linker chemistry procurement for oncology therapeutics shows lowest.
Supply Chain Analysis
Reverse-logistics flows for expired or degraded bromocyclopentane inventory remain underdeveloped, with most returns directed to specialized halogen waste treatment rather than reclamation. Supply concentrates in China, India, and Germany, with Jiangsu province and Gujarat corridor anchoring Asian capacity. Feedstock draws from Dead Sea and Arkansas brine field elemental bromine output, tethering margin predictability to commodity volatility. Single-source vulnerability elevates as environmental enforcement shutters smaller Chinese operators. Distribution runs through qualified supplier programs bundling intermediates with complementary heterocyclic building blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bromocyclopentane market functions as a cost-of-compliance arena where ECHA REACH substance evaluation and FDA DMF filing requirements construct formidable barrier-to-entry moats favoring incumbent producers with validated regulatory dossiers.
For Market Incumbents: Deepen backward integration into elemental bromine sourcing to defend margin predictability against Dead Sea and Arkansas brine field output fluctuations. Expand GMP-certified capacity in Switzerland and Germany to capture ADC linker chemistry premiums for oncology therapeutics. Fluorinated substitute development in agrochemicals threatens volume erosion; pharmaceutical-grade certification depth represents the priority defensive lever. For New Entrants and Emerging Players: Begin with technical-grade supply to Vietnamese chemical parks in Dung Quat and Long Son zones, where MEE-equivalent standards apply with lower compliance overhead than Jiangsu province. Target exploratory synthesis shops and process development laboratories as the most penetrable buyer segment. Differentiate through solvent-free bromination process certifications that satisfy EU pharmaceutical procurement scorecards. For Investors and Strategic Acquirers: The window for entry favors backward-integrated Chinese producers with elemental bromine captive supply and surviving Jiangsu province environmental compliance. Long-term viability hinges on pharmaceutical-grade certification depth rather than industrial-scale commodity positioning. Monitor ECHA hazard reclassification decisions for alternative alkyl bromides as the critical inflection signal for bromocyclopentane's regulatory standing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elemental Bromine | Captive feedstock supply from Dead Sea brine fields insulates margin predictability against commodity volatility. |
| GMP Certification Investment | FDA and EMA DMF filing support unlocks pharmaceutical-grade premiums for ADC linker chemistry applications. |
| Continuous-Flow Bromination Scale-Up | Skid-mounted reactor deployment meets atom-economy criteria embedded in EU pharmaceutical procurement tenders. |
| Vietnam Chemical Park Relocation | Dung Quat and Long Son zones offer MEE-equivalent environmental standards with lower compliance overhead. |
| Long-Term Supply Agreement with Indian API Manufacturers | PLI scheme subsidies draw contract manufacturers toward captive intermediate consumption for antiviral synthesis. |
Methodological Framework
Independent corroboration across customs and trade data, CDSCO and FDA regulatory filings, and ACC sector reports underwrites the qualitative findings in this study. Primary interviews with plant managers at Jiangsu province bromination facilities, procurement leads at Indian API manufacturers, and technical R&D directors at European custom synthesis shops combined with secondary validation from SEC 10-K disclosures, ECHA substance evaluation dossiers, and elemental bromine market assessments. Bottom-up capacity modeling and top-down demand segmentation triangulation anchored volume and value estimates.
Historical reference periods spanning pre-pandemic baselines through recent MEE enforcement waves established trajectory anchors across the projection horizon. The analytical framework modeled segmentation across purity tier, end-use industry, certification grade, and regional production hub dimensions. CAGRs derived from production capacity buildout schedules, regulatory filing timelines, and substitution elasticity assessments for fluorinated alternatives. Forecast inputs incorporated PLI scheme disbursement trajectories and REACH substance evaluation milestone schedules.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications with validated DMF filings carry tighter precision than technical-grade exploratory synthesis volumes. Forecasts reflect assumptions regarding regulatory enforcement continuity, elemental bromine supply stability, and ADC therapeutic pipeline advancement that could materially revise projections. Practitioners should monitor ECHA hazard classification updates, MEE wastewater discharge mandate expansion, and fluorinated substitute commercialization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Stearates Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Biodegradable Chelating Agents Market