
 Polyglycolic Acid (PGA) Market | 2026-2036
Polyglycolic Acid (PGA) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglycolic Acid (PGA) Market Analytics
Buyer concentration in biomedical procurement is shifting as hospital networks consolidate sutures purchasing while decentralized surgical centers fragment specialty orders. Kureha Corporation anchors high-purity resin supply for Japanese medical device manufacturers. Evonik Industries AG leverages its specialty chemicals platform to extend PGA formulation capabilities across European pharmaceutical channels. Shenzhen Polymtek Biomaterial Co., Ltd. competes on cost-engineered fiber grades for domestic Chinese surgical markets.
Polyglycolic acid is a synthetic aliphatic polyester with a glass transition temperature near 36°C and crystallinity exceeding 45%, manufactured primarily through ring-opening polymerization of glycolide for applications requiring controlled hydrolytic degradation. Fiber segments dominate revenue as surgical sutures demand consistent tensile strength retention profiles, while drug delivery applications sustain premium pricing through complex microsphere and nanoparticle formulations. Coating technology occupies a narrower but defensible niche in stent and implant surface engineering where barrier precision commands technical qualification hurdles.
FDA enforces biocompatibility and sterility benchmarks under 21 CFR requirements for absorbable surgical devices, while EMA's Medical Device Regulation mandates clinical evidence trails for PGA-based implants entering European markets. Japan's PMDA applies Pharmaceutical and Medical Device Act standards that extend review timelines for novel biodegradable polymer platforms. Stakeholders must monitor evolving biodegradability certification protocols across these three jurisdictions to preempt formulation redesign costs and secure market access continuity.
Market Dynamics
Hospital network consolidation in the United States and Japan is compressing sutures procurement into centralized contracts, fragmenting specialty orders to ambulatory surgical centers and reshaping volume allocation across the PGA supply base.
Growth Catalysts
- FDA 21 CFR absorbable device standards:Biocompatibility and sterility mandates for surgical implants are institutionalizing PGA as the benchmark material for controlled hydrolytic degradation in Class II medical devices.
- Minimally invasive surgery expansion:Laparoscopic and robotic procedures requiring precision absorbable sutures are pulling fiber-grade resin demand through Japanese and German device OEM supply chains.
- China's pharmaceutical polymer localization:Domestic drug delivery microsphere manufacturing is accelerating substitution of imported PLGA with locally synthesized PGA copolymers for controlled-release formulations.
Market Restraints
- Glycolide monomer supply concentration:High-purity feedstock production clusters in Japan and Germany, exposing formulators to single-source risk and freight cost volatility from Kureha Corporation's Kashima facility.
- EMA MDR clinical evidence requirements:Extended review timelines for novel biodegradable implants are delaying European market entry and inflating pre-revenue R&D burn for mid-cap device developers.
- Polylactic acid substitution in packaging:PLA's lower cost per kilogram and established composting infrastructure are displacing PGA from industrial film applications where degradation speed is less critical.
Strategic Opportunities
- India's CDSCO fast-track pathway:Accelerated approval mechanisms for absorbable surgical devices are opening first-mover positioning for PGA suture manufacturers in Mumbai-Pune and Chennai medical device clusters.
- Orthopedic fixation device convergence:PGA-tricalcium phosphate composite screws for craniofacial and small-bone applications represent an untapped premium segment beyond traditional suture markets.
- Direct-to-hospital digital procurement platforms:B2B marketplaces are disintermediating regional distributors, enabling fiber-grade suppliers to capture margin previously allocated to surgical products wholesalers.
Industry Challenges
- Ring-opening polymerization process engineering talent:Scarce expertise in molecular weight control and residual monomer reduction is constraining capacity expansion at second-tier Chinese manufacturers.
- ISO 10993 biocompatibility certification timelines:Cytotoxicity and sensitization testing backlogs at notified bodies are extending product launch cycles by eight to fourteen months for novel PGA formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglycolic Acid (PGA) Market |
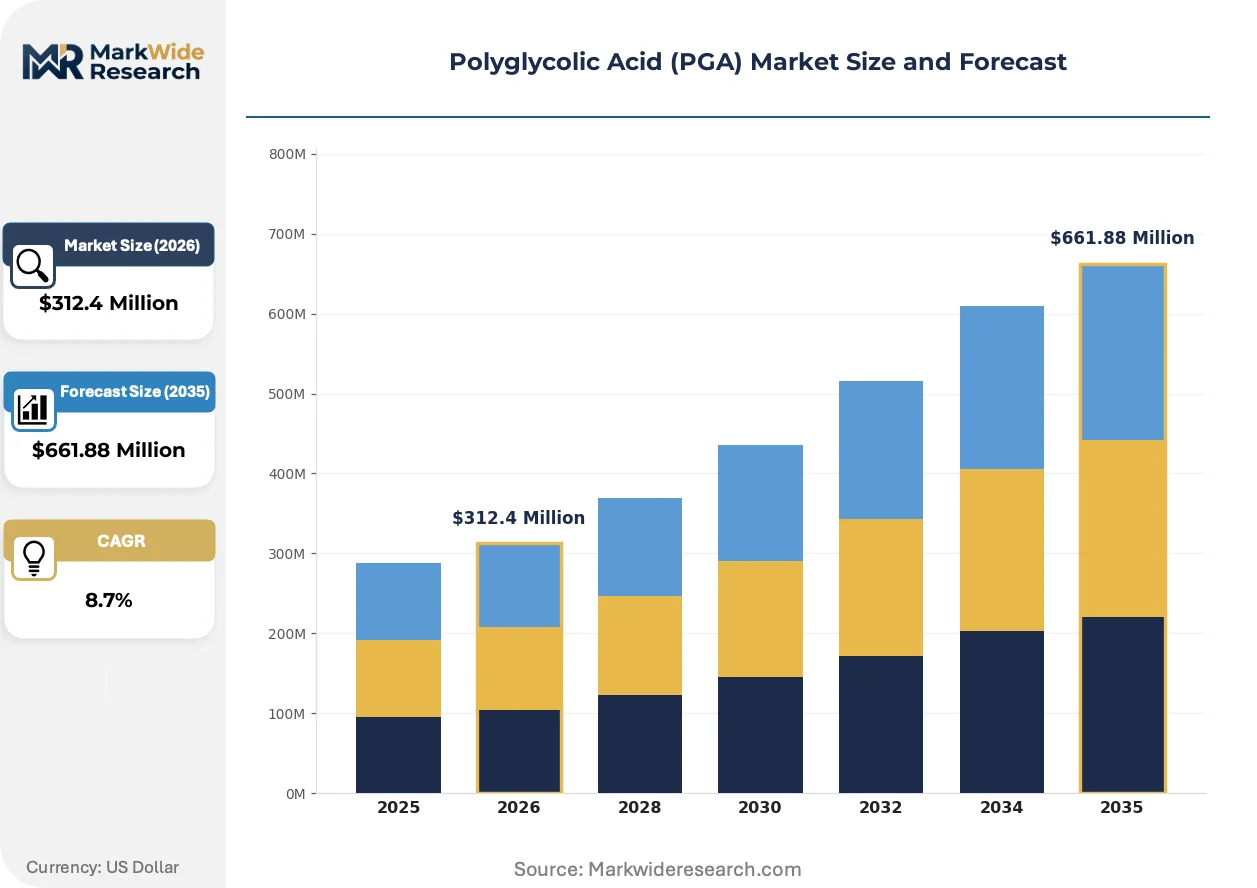
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Coating, Film, Granule End User: Biomedical, Packaging, Agriculture, Textile Application: Sutures, Stents, Drug Delivery, Biodegradable Films Technology: Polymerization, Extrusion, Injection Molding, Electrospinning |
| Companies Covered | Evonik Industries AG, Shenzhen Polymtek Biomaterial Co., Ltd., Kureha Corporation, Teleflex Incorporated, Huizhou Foryou Medical Devices Co., Ltd., Corbion N.V., Mitsubishi Chemical Corporation, Samyang Biopharmaceuticals, BMG Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglycolic Acid (PGA) Market Evolving Landscape
Electrospinning technology is enabling sub-micron PGA fiber architectures for tissue engineering scaffolds, while regulatory harmonization efforts across FDA, EMA, and PMDA are compressing multi-jurisdiction approval cycles. These forces are simultaneously expanding addressable applications and raising technical qualification barriers.
Electrospun PGA nanofiber matrices are converging with stem cell delivery platforms for dermal and orthopedic regeneration. Academic medical centers in Boston and Heidelberg are validating these scaffolds in preclinical models. The structural consequence is a bifurcation between commodity suture-grade resin and premium biomedical fiber commanding tenfold price multiples.
EMA's Medical Device Regulation (MDR) is tightening post-market surveillance requirements for absorbable implants, mandating clinical follow-up data that legacy PMA submissions never captured. European notified bodies are rejecting substantial equivalence claims for PGA-based devices predating 2017. High-risk implant categories—craniofacial plates and cardiovascular stent coatings—are absorbing disproportionate compliance investment.
Japanese hospital groups are consolidating sutures purchasing through GPOs while fragmenting specialty orders to independent ambulatory centers. Kobe and Osaka surgical clusters now split procurement between bulk absorbable suture contracts and small-lot braided PGA orders for ophthalmic microsurgery. This dual-channel structure is forcing suppliers to maintain parallel inventory and pricing systems.
Polyglycolic Acid (PGA) Market Segmentation
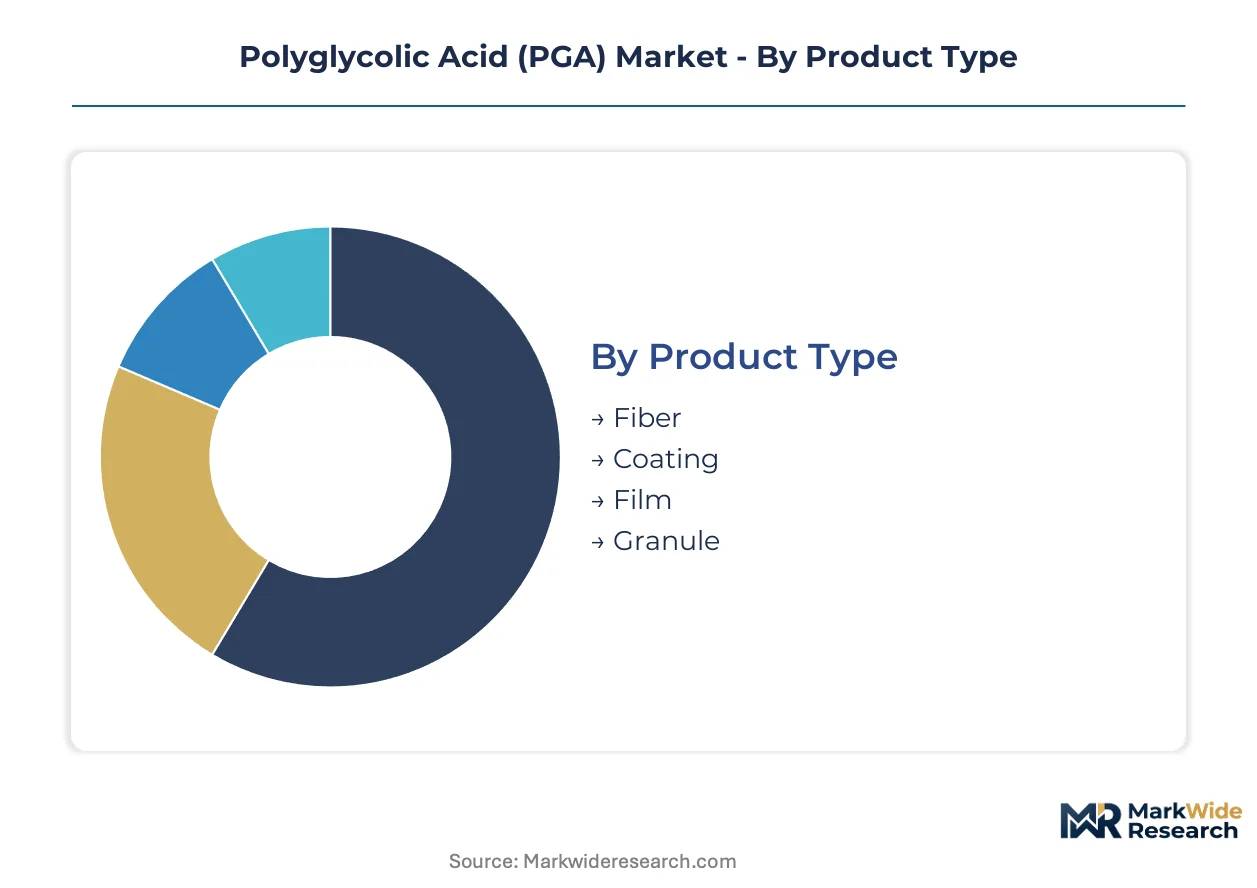
PGA's molecular architecture—high crystallinity above 45% and glass transition near 36°C—creates divergent performance profiles across physical forms. Segmentation discipline separates commodity resin from biomedical-grade fiber commanding certification premiums.
Product Type:
Standalone fiber applications dominate procurement volumes, while coating and film segments embed into finished device supply chains.
- Fiber:Surgical sutures and textile-grade filaments absorb the majority of high-purity resin output. Tensile strength retention profiles under hydrolytic degradation anchor FDA 21 CFR compliance for Class II absorbable devices.
- Coating:Stent and implant surface engineering demands sub-micron barrier precision. EMA MDR clinical evidence requirements extend qualification timelines for cardiovascular and orthopedic coating applications.
- Film:Industrial compostable packaging competes directly with polylactic acid on cost per kilogram.
- Granule:Feedstock for downstream compounding and copolymer synthesis supplies Chinese pharmaceutical microsphere manufacturers.
Volume placements concentrate in Fiber; the faster expansion belongs to Coating.
End User:
Cost tiers separate regulated biomedical procurement from price-sensitive agricultural and packaging offtake.
- Biomedical:Hospital network consolidation in the United States and Japan compresses sutures purchasing into centralized GPO contracts. FDA biocompatibility mandates and PMDA Pharmaceutical and Medical Device Act standards institutionalize PGA as the benchmark for controlled hydrolytic degradation.
- Packaging:Industrial film applications face displacement where degradation speed is less critical and PLA's established composting infrastructure offers lower landed cost.
- Agriculture:Mulch films and controlled-release matrices exploit PGA's rapid biodegradation in soil environments.
- Textile:Technical fiber applications for industrial geotextiles and filtration media compete on tensile performance rather than absorbability.
Revenue concentration sits with Biomedical; Packaging climbs fastest as sustainability mandates tighten.
Application:
Application maturity separates decades-validated sutures from emerging drug delivery platforms requiring novel formulation science.
- Sutures:Braided and monofilament constructions for general surgery, ophthalmic microsurgery, and orthopedics absorb consistent fiber-grade resin volumes. Kobe and Osaka surgical clusters split procurement between bulk absorbable contracts and small-lot specialty orders.
- Drug Delivery:Microsphere and nanoparticle formulations for controlled-release pharmaceuticals sustain premium pricing through complex copolymer engineering. China's domestic pharmaceutical polymer localization accelerates substitution of imported PLGA with locally synthesized PGA variants.
- Stents:Cardiovascular and urological device coatings command technical qualification hurdles for barrier precision.
- Biodegradable Films:Agricultural mulch and industrial packaging applications compete on cost-engineered resin grades.
Established volume flows through Sutures; Drug Delivery gains share fastest on formulation complexity premiums.
Technology:
Process sophistication tiers separate commodity extrusion from precision electrospinning requiring scarce polymerization engineering talent.
- Polymerization:Ring-opening polymerization of glycolide monomer demands molecular weight control and residual monomer reduction expertise. High-purity feedstock production clusters in Japan and Germany expose formulators to single-source concentration risk.
- Electrospinning:Sub-micron fiber architectures for tissue engineering scaffolds converge with stem cell delivery platforms. Academic medical centers in Boston and Heidelberg validate these matrices in preclinical dermal and orthopedic regeneration models.
- Extrusion:Continuous fiber and film production scales efficiently for suture and packaging volume.
- Injection Molding:Orthopedic fixation devices and craniofacial plates require composite formulation with tricalcium phosphate.
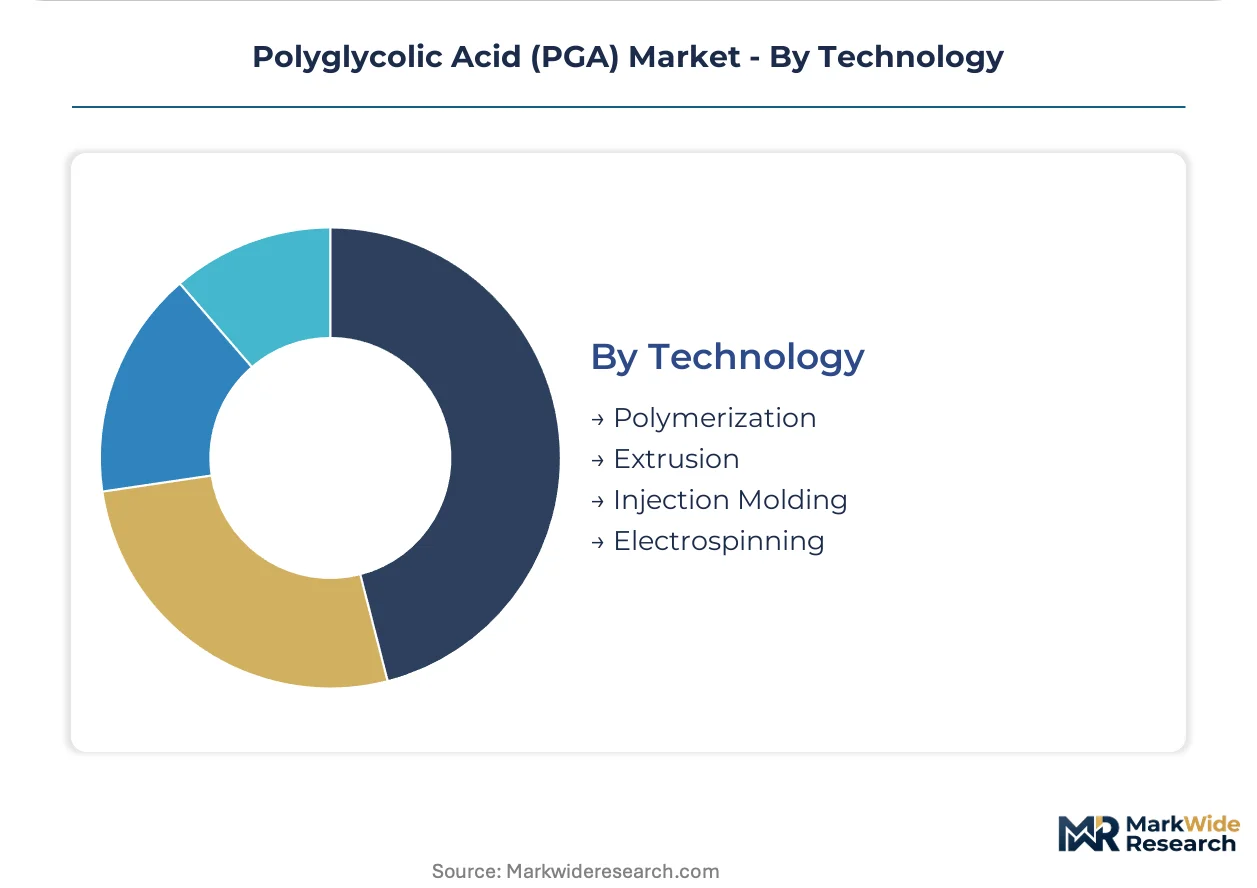
Capacity deployment clusters in Extrusion; Electrospinning expands most quickly on regenerative medicine investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical procurement concentrates in three distinct national clusters where hospital network consolidation and regulatory stringency intersect. Each geography exhibits unique demand drivers and compliance architectures that reshape PGA volume allocation.
United States
FDA 21 CFR absorbable device standards institutionalize PGA as the benchmark material for Class II surgical implants requiring controlled hydrolytic degradation. Hospital network consolidation compresses sutures purchasing into centralized GPO contracts while ambulatory surgical centers fragment specialty orders. The Boston-Worcester corridor anchors tissue engineering scaffold development through academic medical center partnerships.
Japan
PMDA Pharmaceutical and Medical Device Act standards extend review timelines for novel biodegradable polymer platforms, creating qualification barriers for new entrants. Kobe and Osaka surgical clusters split procurement between bulk absorbable suture contracts and small-lot braided PGA orders for ophthalmic microsurgery. Kureha Corporation's Kashima facility concentrates high-purity glycolide monomer supply for domestic device manufacturers.
Germany
EMA Medical Device Regulation mandates clinical evidence trails for PGA-based implants entering European markets, inflating pre-revenue R&D burn for mid-cap developers. Heidelberg academic medical centers validate electrospun nanofiber matrices in preclinical dermal regeneration models. The Rhine-Main industrial corridor hosts specialty chemical formulators serving pharmaceutical microsphere manufacturers.
China
NMPA biocompatibility certification requirements tighten as domestic pharmaceutical polymer localization accelerates substitution of imported PLGA with locally synthesized PGA copolymers. Shenzhen and Guangzhou medical device clusters drive cost-engineered fiber grade production for surgical markets. CDSCO-equivalent fast-track pathways for absorbable devices attract first-mover positioning in Mumbai-Pune and Chennai clusters through Indian regulatory arbitrage.
India
CDSCO accelerated approval mechanisms for absorbable surgical devices open first-mover positioning for PGA suture manufacturers. Mumbai-Pune and Chennai medical device clusters absorb technology transfer from Chinese and Japanese suppliers. Domestic pharmaceutical microsphere manufacturing scales through backward integration into glycolide monomer synthesis.
Polyglycolic Acid (PGA) Market Competitive Landscape
Japanese and German producers anchor the high-purity resin tier; Chinese specialists hold cost-engineered fiber grades. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive monomer supply, mid-cap biomedical formulators with ISO 10993 certification capabilities, and regional fiber extruders serving price-sensitive surgical markets. Strategic moves concentrate on capacity expansion in pharmaceutical-grade resin and technology licensing for electrospinning architectures.
Within the integrated chemical tier, Evonik Industries AG and Mitsubishi Chemical Corporation exemplify multinational platforms leveraging specialty chemicals infrastructure across European and Asian pharmaceutical channels. Kureha Corporation occupies a distinctive position as a high-purity glycolide monomer specialist supplying Japanese medical device OEMs. Shenzhen Polymtek Biomaterial Co., Ltd. represents the cost-optimized manufacturing archetype competing on fiber grades for domestic Chinese surgical procurement.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Shenzhen Polymtek Biomaterial Co., Ltd. |
| Kureha Corporation |
| Teleflex Incorporated |
| Huizhou Foryou Medical Devices Co., Ltd. |
| Corbion N.V. |
| Mitsubishi Chemical Corporation |
| Samyang Biopharmaceuticals |
| BMG Incorporated |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap Japanese chemical specialists anchor high-purity glycolide monomer production, creating asymmetric pricing power that feeds through to biomedical-grade fiber premiums while constraining cost-engineered grades in Chinese surgical markets.
Pricing Analysis
Volume placements concentrate in commodity suture-grade fiber with thin margins, while coating and electrospun scaffold applications sustain premium multiples through FDA 21 CFR certification tiers and ISO 10993 biocompatibility qualification. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical microsphere resin from ophthalmic microsurgery fiber from industrial packaging granules. Cost compression in standard-grade suture fiber is intensifying because Shenzhen and Guangzhou manufacturers are scaling extrusion capacity faster than hospital GPO consolidation can absorb. Ambulatory surgical centers exhibit highest price sensitivity due to small-lot procurement, while cardiovascular stent coating buyers accept premium positioning for barrier precision.
Supply Chain Analysis
Single-source vulnerability sits with Kureha Corporation's Kashima facility, which concentrates high-purity glycolide monomer output for Japanese medical device OEMs and European pharmaceutical formulators. Manufacturing gravity centers on Japan, Germany, and China, with ring-opening polymerization expertise clustering in the first two while extrusion capacity scales in the third. Feedstock supply rests on petrochemical-derived glycolide and bio-based glycolic acid variants, with catalyst systems for molecular weight control sourced from specialty chemical channels. Tariff exposure on glycolide monomer imports into China and India presents structural risk for cost-engineered fiber producers. Distribution runs through surgical products wholesalers, though B2B digital procurement platforms are disintermediating regional distributors in United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around FDA 21 CFR and EMA MDR compliance capabilities, forcing out second-tier Chinese manufacturers lacking ISO 10993 certification infrastructure.
For Market Incumbents: Acquire electrospinning technology platforms to secure premium scaffold positioning before regenerative medicine investment peaks. Lock in long-term glycolide monomer offtake agreements with Kureha Corporation's Kashima facility to defend against single-source supply disruption. Expand ISO 17025 testing laboratory capacity in Heidelberg or Boston-Worcester corridors to compress EMA MDR and FDA 21 CFR qualification timelines for novel biodegradable implants.
For New Entrants and Emerging Players: Launch via direct-to-hospital digital procurement platforms targeting ambulatory surgical centers in United States and Japanese ophthalmic microsurgery clusters with small-lot braided PGA orders. Penetrate India's CDSCO fast-track pathway for absorbable surgical devices before Mumbai-Pune and Chennai medical device clusters absorb technology transfer from established suppliers. White-space exists in PGA-tricalcium phosphate composite screws for craniofacial fixation, where orthopedic device convergence has yet to commoditize.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biomedical formulators with captive ISO 10993 certification capabilities in Germany or Japan, where EMA MDR compliance investment has strained pre-revenue R&D burn. Long-term viability hinges on electrospinning technology access and pharmaceutical-grade resin capacity expansion over a five-to-ten year window. Monitor CDSCO approval velocity for absorbable surgical devices as inflection indicator for Indian market timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycolide Monomer | Kureha Corporation's Kashima concentration creates acquisition logic for captive high-purity feedstock security. |
| ISO 10993 Biocompatibility Laboratory Buildout | Heidelberg and Boston academic medical center partnerships validate faster certification timelines for novel PGA formulations. |
| Electrospinning Technology Licensing | Sub-micron fiber architectures for tissue engineering scaffolds command tenfold price multiples over commodity suture grades. |
| Direct-to-Hospital Digital Procurement Platform | B2B marketplaces disintermediate surgical products wholesalers, capturing margin in United States GPO-contracted networks. |
| CDSCO Fast-Track Regulatory Entry | Accelerated approval mechanisms in India open first-mover positioning before Mumbai-Pune clusters mature. |
Research Methodology
Document review covered FDA 21 CFR device filings, EMA MDR submission databases, and PMDA Pharmaceutical and Medical Device Act registration records, complemented by interviews with biomedical engineers at academic medical centers, GPO contracts managers in United States hospital networks, procurement leads at Japanese surgical device OEMs, and technical R&D directors at specialty chemical formulators. Secondary validation drew from customs trade data on glycolide monomer shipments, SEC 10-K disclosures from listed medical device manufacturers, and ISO 10993 testing laboratory accreditation records. Bottom-up fiber-grade resin demand modeling and top-down biomedical procurement spend analysis were triangulated against ring-opening polymerization capacity estimates.
Segmented outputs across product type, end user, application, and technology dimensions were generated through the projection horizon, with CAGRs derived from hospital network consolidation trajectories and minimally invasive surgery adoption curves. The analytical framework incorporated pharmaceutical microsphere manufacturing localization rates in China, electrospun scaffold preclinical validation timelines at Heidelberg and Boston centers, and sutures procurement split between bulk GPO contracts and ambulatory specialty orders.
Glycolide monomer supply disruption, EMA MDR review timeline extension, and polylactic acid substitution acceleration in packaging applications are the dominant revision risks across the modeling period. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Esterquats Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Eco-Friendly Plasticizers Market