
 Global Sodium Hyaluronate-Based Products Market | 2026-2036
Global Sodium Hyaluronate-Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Hyaluronate-Based Products Market Foresight
Subscription-based maintenance programs for injection devices is realigning how manufacturers monetize recurring patient touchpoints. Allergan leverages its established injector training networks to sustain high-switching-cost relationships with dermatology practices. Galderma differentiates through vertically integrated hyaluronic acid fermentation capacity that anchors supply security for premium product lines.
Sodium hyaluronate-based products comprise formulations of the glycosaminoglycan sodium salt, typically at molecular weights spanning 50 kDa to 3 MDa, manufactured through bacterial fermentation or rooster comb extraction for viscoelastic, hydrating, or space-occupying functions in human tissue. Injectable formulations command the dominant margin pool given their sterile manufacturing requirements and practitioner-administered delivery, while ophthalmic solutions represent a mature volume base tied to cataract surgery incidence. Aesthetic treatments within dermatology applications absorb disproportionate R&D investment as cosmetic clinics expand service menus beyond wrinkle correction into facial contouring and skin quality protocols.
The FDA's device classification framework for hyaluronic acid dermal fillers shapes clinical trial requirements and post-market surveillance obligations for US market access. EMA's Medical Device Regulation imposes strengthened notified body scrutiny on cross-linked injectables sold across European Union member states. China's NMPA accelerates review timelines for innovative sodium hyaluronate formulations through priority review channels. Stakeholders must monitor regulatory divergence between major markets as it fragments approval strategies and localization requirements.
Market Dynamics
Cross-linking chemistry advances are compressing the performance gap between premium and mid-tier dermal fillers, forcing manufacturers to compete on injector education networks and maintenance program stickiness rather than formulation differentiation alone.
Growth Catalysts
- China's NMPA priority review channels:Accelerated approval timelines for novel sodium hyaluronate formulations are pulling multinational manufacturers into domestic partnership structures with Chinese biotech firms.
- Cataract surgery volume expansion:Aging demographics across Japan, Germany, and the United States are sustaining demand for ophthalmic viscoelastic devices in anterior segment procedures.
- Facial contouring protocol adoption:Cosmetic clinics in South Korea and Brazil are expanding service menus beyond wrinkle correction into jawline definition and temple volumization using high-G-prime fillers.
Market Restraints
- Rooster comb supply concentration:Non-fermentation extraction methods depend on avian sourcing clusters in specific European and Chinese agricultural regions exposed to avian influenza disruption.
- EMA MDR notified body scarcity:Strengthened scrutiny on cross-linked injectables has extended conformity assessment timelines for European market access by 8-14 months for mid-tier manufacturers.
- Collagen stimulator substitution:Poly-L-lactic acid and calcium hydroxylapatite microsphere products are capturing long-duration facial volumization cases previously served by high-crosslink-density hyaluronic acid.
Strategic Opportunities
- India's aesthetic medicine corridor:Mumbai and Delhi dermatology practices are expanding injection service capacity faster than domestic sodium hyaluronate manufacturing can match, creating import partnership windows.
- Combination therapy protocols:Convergence of hyaluronic acid fillers with energy-based devices and topical biostimulators is creating bundled service packages in South Korean and Thai cosmetic clinics.
- Subscription-based maintenance programs:Allergan and Galderma are piloting direct-to-clinic replenishment models that lock in recurring patient touchpoints through automated injection device resupply.
Industry Challenges
- Certified injector training bottlenecks:Manufacturer-sponsored education programs face capacity constraints as dermatology residents and nurse practitioners seek accreditation faster than training infrastructure can scale.
- Cold chain integrity for biofermentation-derived HA:High-molecular-weight sodium hyaluronate raw material requires precise temperature control through multi-modal logistics from fermentation facilities to sterile formulation plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Hyaluronate-Based Products Market |
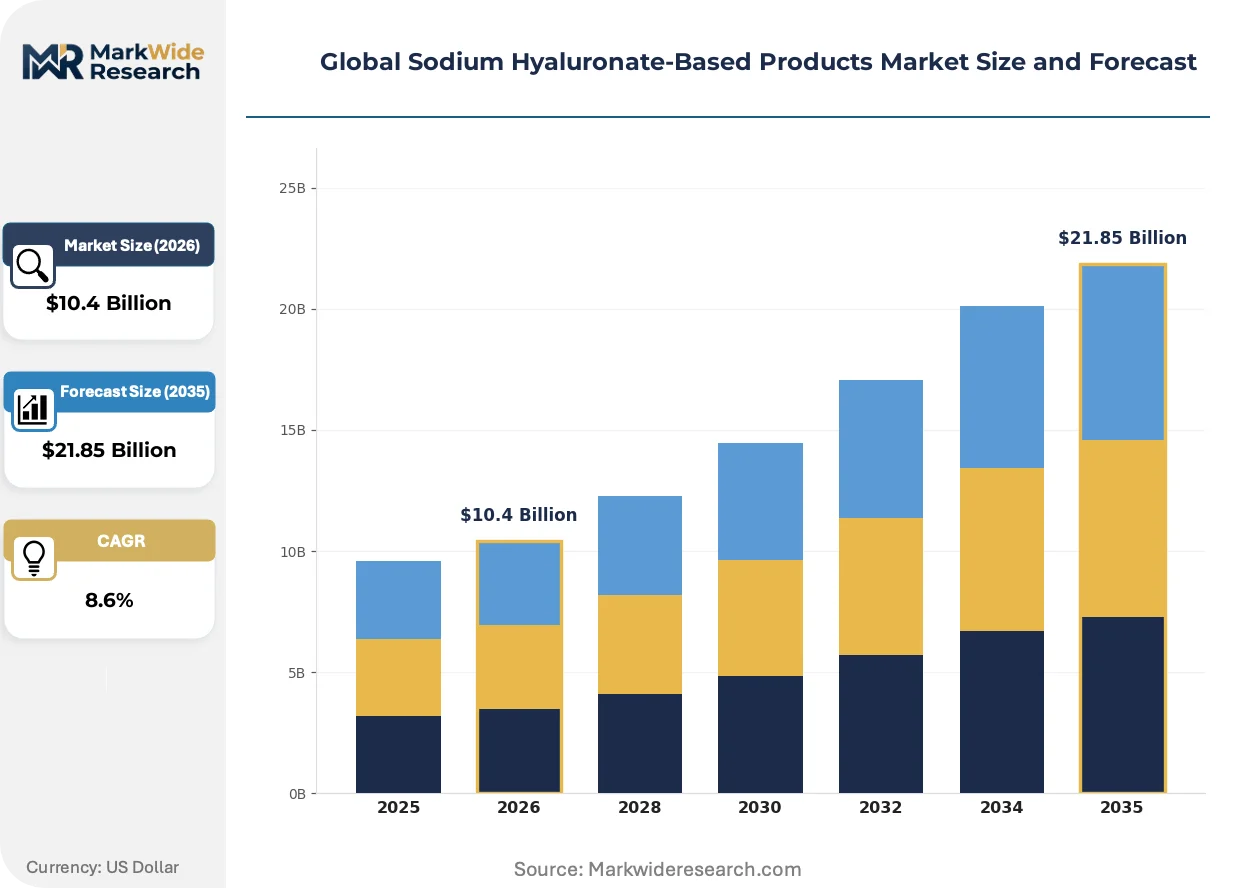
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $21.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Topical Gel, Ophthalmic Solution, Dietary Supplement, Nasal Spray Application: Ophthalmology, Orthopedics, Dermatology, Wound Care, Aesthetic Treatments End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Cosmetic Clinics, Rehabilitation Centers Packaging Type: Ampoule, Vial, Bottle, Sachet, Dropper |
| Companies Covered | Allergan, Galderma, Anika Therapeutics, LG Chem, Fidia Farmaceutici, Ferring Pharmaceuticals, Bohus BioTech, Syner-Med, Bloomage Bio-Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Hyaluronate-Based Products Market Shifts & Advancements
Manufacturing and delivery technologies are converging to reshape competitive positioning around real-time customization and practitioner workflow integration rather than static product specifications.
Dynamic viscosity modulation technology is unifying previously separate filler portfolios into single-platform systems. Galderma and Allergan are deploying variable-crosslink-density devices that allow clinicians to adjust gel characteristics intra-procedure. This compression of SKU proliferation into adaptable delivery systems is reducing inventory carrying costs for high-volume cosmetic clinics while capturing cases that previously required multiple product lines.
REACH substance registration requirements for novel cross-linking agents are extending pre-market toxicology timelines for European-bound formulations. ECHA's expanded data requirements on residual BDDE and DVS cross-linker concentrations are forcing reformulation investments. High-crosslink-density volumizing fillers face the steepest compliance burden, with several manufacturers prioritizing US FDA 510(k) pathways ahead of CE marking.
Direct procurement relationships between cosmetic clinic chains and fermentation houses are disintermediating traditional distributor networks in South Korea and Thailand. Large dermatology groups are negotiating captive supply agreements for hyaluronic acid raw material. This channel compression is most visible in Seoul's Gangnam district, where vertically integrated clinic chains now control formulation-to-injection value capture.
Global Sodium Hyaluronate-Based Products Market Segmentation
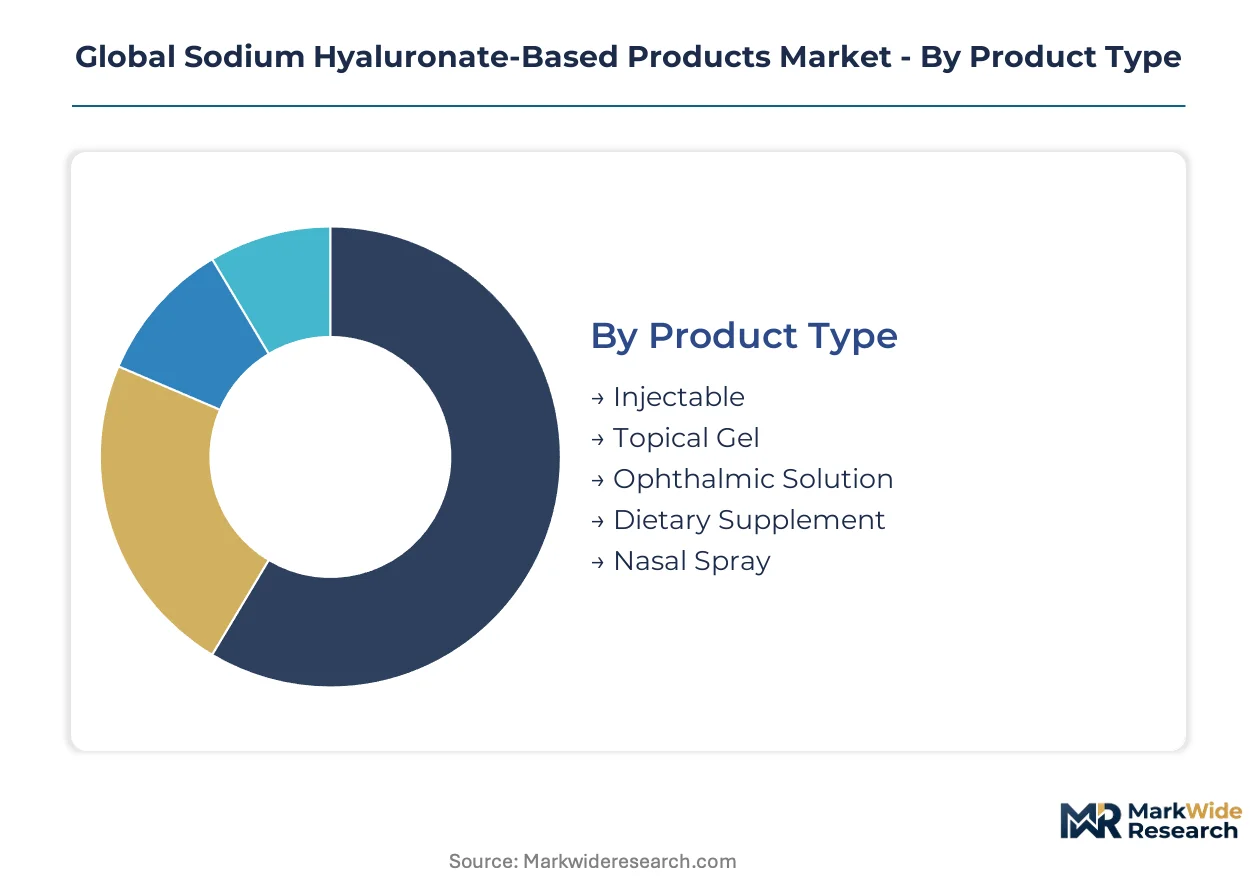
Sodium hyaluronate formulations span molecular weights from 50 kDa to 3 MDa, creating distinct margin profiles across delivery modalities. Injectable and ophthalmic segments anchor revenue concentration, while topical and nutraceutical lines expand addressable market boundaries through lower-barrier consumer access.
Product Type:
Volume concentration clusters in sterile formulations requiring aseptic manufacturing, while premium pricing accrues to cross-linked injectables with extended tissue residence times.
- Injectable:Cross-linked hyaluronic acid gels manufactured through BDDE or DVS chemistry achieve 6-18 month duration in dermal and subdermal placement. China's NMPA priority review channels are accelerating novel formulation approvals, pulling Galderma and Allergan into domestic partnership structures with Chinese biotech firms.
- Ophthalmic Solution:Viscoelastic devices at 1.6-4.0 MDa molecular weight maintain anterior chamber stability during phacoemulsification. Japan's aging surgical population and Germany's high cataract procedure volume sustain demand for single-use syringe formats.
- Topical Gel:Non-crosslinked formulations at 50-500 kDa penetrate stratum corneum for hydration protocols.
- Dietary Supplement:Oral sodium hyaluronate at 50-150 kDa targets joint mobility and skin hydration claims.
- Nasal Spray:Isotonic formulations deliver mucosal hydration for chronic rhinitis and post-surgical care.
Mature deployment sits with Ophthalmic Solution. Newer deployment is concentrated in Injectable formats.
Application:
Margin distribution follows practitioner-administered versus self-administered boundaries, with clinical settings capturing value through technical service bundling.
- Dermatology:Aesthetic protocols extend beyond rhytid correction into facial contouring, skin quality improvement, and combination therapy with energy-based devices. Seoul's Gangnam district and São Paulo's Jardins corridor are expanding service menus faster than domestic manufacturing can match.
- Aesthetic Treatments:Jawline definition, temple volumization, and non-surgical rhinoplasty absorb disproportionate R&D investment. South Korean and Thai cosmetic clinics are piloting bundled packages combining hyaluronic acid fillers with biostimulators and laser platforms.
- Ophthalmology:Cataract surgery volume expansion across Japan, Germany, and the United States sustains viscoelastic device demand.
- Orthopedics:Intra-articular injections target osteoarthritis management in knee and shoulder joints.
- Wound Care:Hydrogel dressings leverage hygroscopic properties for chronic ulcer and burn management.
Established revenue concentration rests with Ophthalmology. Steepest expansion trajectory belongs to Aesthetic Treatments.
End User:
Channel configuration separates institutional procurement from retail-accessible consumption, with certification requirements filtering practitioner eligibility.
- Cosmetic Clinics:Dermatology practices and medical spas command premium pricing through injector expertise and maintenance program enrollment. Allergan's training networks and Galderma's direct-to-clinic replenishment models are locking in recurring patient touchpoints.
- Hospitals:Integrated health systems drive volume contracting for ophthalmic viscoelastics and orthopedic formulations. India's Mumbai and Delhi hospital chains are expanding injection service capacity, creating import partnership windows.
- Specialty Clinics:Ophthalmology and orthopedic focused practices concentrate procedure-specific expertise.
- Ambulatory Surgical Centers:Outpatient cataract and joint procedures favor single-use, pre-filled delivery formats.
- Rehabilitation Centers:Post-operative and chronic care settings utilize topical and oral formulations for mobility protocols.
Volume leadership resides with Hospitals. Margin expansion concentrates in Cosmetic Clinics.
Packaging Type:
Primary packaging selection balances sterile barrier integrity against practitioner workflow efficiency and patient convenience requirements.
- Vial:Multi-dose glass or polymer containers serve compounding pharmacies and institutional settings with high-throughput requirements. EMA's MDR notified body scarcity has extended conformity assessment timelines for European-bound vial formats by 8-14 months.
- Ampoule:Single-unit glass containers eliminate preservative requirements for sensitive ophthalmic and injectable formulations. REACH substance registration for novel cross-linking agents is extending pre-market toxicology timelines for ampoule-packaged European formulations.
- Bottle:Multi-use containers with pump or squeeze delivery serve topical gel and ophthalmic solution segments.
- Sachet:Unit-dose foil pouches enable sample distribution and travel-format dietary supplements.
- Dropper:Pipette or integrated tip systems deliver precise volume control for ophthalmic and nasal applications.
Institutional preference centers on Vial formats. Patient-direct growth is gaining share fastest in Sachet configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in China and South Korea while consumption concentrates in aesthetic medicine corridors across the United States, Brazil, and Western Europe. This geographic split shapes cross-border supply agreements and regulatory filing strategies.
United States
Cosmetic clinics in Beverly Hills and Manhattan drive demand for high-G-prime volumizing fillers. FDA's evolving guidance on cross-linked hyaluronic acid devices accelerates product standardization timelines. Miami's aesthetic medicine corridor absorbs disproportionate injection device imports.
China
NMPA priority review channels pull multinational manufacturers into domestic partnership structures with local biotech firms. The regulator's accelerated timelines for novel sodium hyaluronate formulations compress market entry cycles. Shanghai's Zhangjiang Hi-Tech Park anchors fermentation-to-formulation vertical integration.
Germany
EMA's Medical Device Regulation imposes strengthened notified body scrutiny on cross-linked injectables. REACH substance registration requirements extend pre-market toxicology timelines for novel cross-linking agents. Heidelberg's ophthalmic device cluster sustains viscoelastic manufacturing for cataract surgery markets.
Brazil
São Paulo's Jardins corridor expands service menus faster than domestic sodium hyaluronate manufacturing can match. ANVISA's regulatory framework shapes import partnership windows for Asian fermentation houses. Rio de Janeiro's cosmetic clinic chains pilot bundled therapy protocols.
South Korea
Seoul's Gangnam district controls formulation-to-injection value capture through vertically integrated clinic chains. MFDS oversight of medical device quality systems filters market access for imported fillers. Busan's fermentation facilities supply raw material to domestic and export markets.
Global Sodium Hyaluronate-Based Products Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sodium hyaluronate value chain. Fermentation-scale manufacturers anchor supply security while formulation specialists capture premium pricing through branded delivery systems. Three archetypes dominate: integrated fermentation-to-filler houses, sterile formulation contractors, and regional private-label distributors. Competitive moves concentrate on captive supply agreements and direct-to-clinic replenishment models that lock in recurring patient touchpoints.
Among US and European incumbents, Allergan and Galderma occupy positions anchoring premium-tier portfolios through established injector training networks. LG Chem represents the Asian fermentation-scale archetype with backward integration into hyaluronic acid raw material production. Bloomage Bio-Technology exemplifies domestic Chinese players leveraging NMPA priority review channels to compress multinational market entry advantages.
| Leading Market Players |
|---|
| Allergan |
| Galderma |
| Anika Therapeutics |
| LG Chem |
| Fidia Farmaceutici |
| Ferring Pharmaceuticals |
| Bohus BioTech |
| Syner-Med |
| Bloomage Bio-Technology |
| Others |
Supply & Pricing Matrix
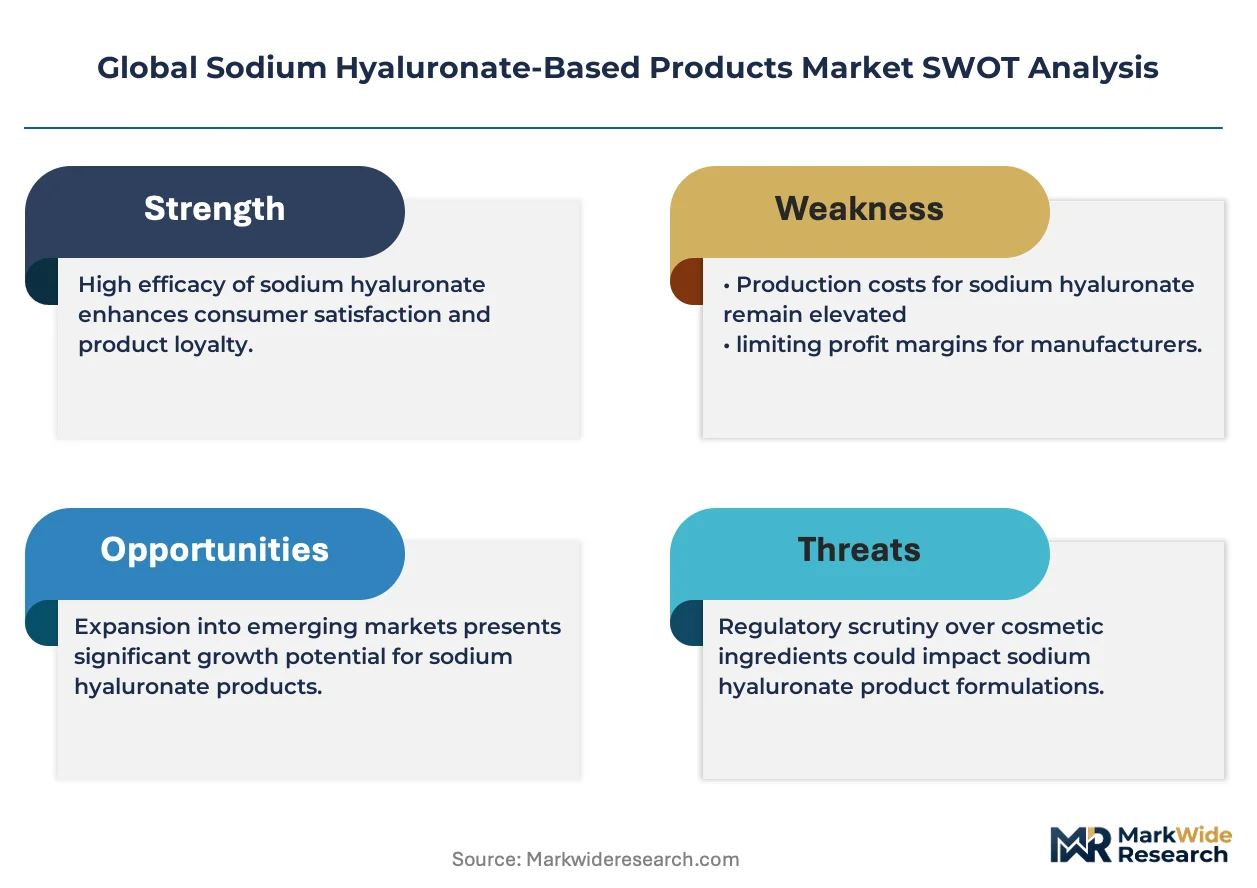
Rooster comb-derived hyaluronic acid feedstock volatility cascades through fermentation-to-formulation value chains, compressing margin pools at mid-tier manufacturers while premium players leverage backward integration into bacterial fermentation capacity to defend pricing power.
Pricing Analysis
Margin tightening in standard-grade injectables reflects cross-linking chemistry commoditization as BDDE and DVS chemistry advances compress performance gaps. Three-tier pricing structure across premium, standard, and economy levels separates Allergan and Galderma's training-network-anchored portfolios from regional private-label distributors. Pricing pressure stems from collagen stimulator substitution in long-duration volumization cases. Cosmetic clinics exhibit lowest price sensitivity due to maintenance program stickiness, while hospital procurement committees drive hardest bargain on ophthalmic viscoelastic contracts.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean fermentation clusters that anchor global hyaluronic acid raw material output. High-molecular-weight sodium hyaluronate draws from bacterial fermentation in Shanghai's Zhangjiang Hi-Tech Park and Busan's biotech corridor, with residual dependence on European and Chinese rooster comb extraction pockets exposed to avian influenza disruption. Cold chain integrity failures between fermentation facilities and sterile formulation plants represent the dominant structural risk. Distribution runs through direct procurement relationships disintermediating traditional distributor networks in Seoul's Gangnam district and Bangkok's aesthetic corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's Medical Device Regulation constructs a cost-of-compliance moat that favors incumbents with notified body relationships and quality management system certifications, raising effective barriers for capital-constrained challengers.
For Market Incumbents: To counter collagen stimulator substitution in facial volumization, Allergan and Galderma should deepen captive supply agreements with Chinese fermentation houses and expand dynamic viscosity modulation platform deployment. Certification investment in EMA MDR technical documentation accelerates European market access timelines relative to mid-tier competitors. For New Entrants and Emerging Players: Dermatology practice chains in Mumbai and Delhi represent the most penetrable channel partner type for import partnership structures, given India's aesthetic medicine corridor expansion outpacing domestic manufacturing capacity. NMPA priority review channel navigation through domestic Chinese biotech partnerships offers the clearest go-to-market angle for novel formulation entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor sterile formulation contractors with EMA quality system certifications in Germany and Switzerland, positioned for acquisition by fermentation-scale houses seeking forward integration. The signal to watch is notified body capacity expansion announcements as a leading indicator of European approval timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | LG Chem and Bloomage Bio-Technology anchor supply security for premium product lines through bacterial fermentation scale-up. |
| Dynamic Viscosity Modulation Platform | Galderma and Allergan compress SKU proliferation into adaptable delivery systems reducing clinic inventory carrying costs. |
| Direct-to-Clinic Replenishment Model | Subscription-based maintenance programs lock in recurring patient touchpoints through automated injection device resupply. |
| NMPA Priority Review Partnership | Multinational manufacturers compress market entry cycles through domestic Chinese biotech collaboration structures. |
| Certified Injector Training Network | Allergan's established education infrastructure sustains high-switching-cost relationships with dermatology practices. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and hospital procurement disclosures underwrites the qualitative findings. Primary interviews with fermentation facility operations directors, cosmetic clinic chain procurement managers, and EMA notified body technical assessors combined with secondary validation from FDA 510(k) clearances, NMPA registration certificates, and GPO contract databases. Bottom-up capacity utilization modeling and top-down demand segmentation triangulation anchor volume and value estimates.
Rate-of-change decomposition across molecular weight tiers, cross-linking chemistry types, and regional regulatory clusters structures the analytical framework. Segmentation dimensions span product type, application, end user, and packaging format with geographic production hub overlays. CAGRs derive from installed base growth in cataract surgery volumes, aesthetic procedure expansion rates, and fermentation capacity addition pipelines. Forecast inputs incorporate NMPA review timeline trends and EMA notified body queue depth indicators.
Caveats apply where avian influenza disruptions to rooster comb supply or EMA MDR implementation delays could materially shift the outlook. Forecasts reflect assumptions on regulatory pathway efficiency and clinic chain consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Optical Whitening Agents Market