
 UV Filters Market | 2026-2036
UV Filters Market Size, Share, and Industry Trends Forecast 2026-2036
UV Filters Market Analysis
Multi-source procurement for benzophenone and triazine intermediates is expanding as formulators reduce dependency on single-region supply chains. BASF SE anchors European production of broad-spectrum organic filters through integrated precursor manufacturing. Croda International Plc specializes in lipid-compatible dispersions that simplify cold-process cosmetic formulation. DSM-Firmenich AG competes on photostabilizer combinations that extend SPF durability in water-resistant applications.
UV filters are photoprotective compounds that absorb, reflect, or scatter ultraviolet radiation in the 290–400 nm range, with organic variants typically incorporating benzotriazole, camphor, or triazine chromophores synthesized through Friedel-Crafts alkylation and subsequent nitration. Their primary commercial purpose is preventing photodegradation of skin, polymers, and textile substrates while maintaining optical clarity in finished goods. Organic filters command the largest volume share due to cost-efficient synthesis and cosmetic compatibility, though inorganic filters gain ground where reef-safe and photostable mineral protection is mandated. Hybrid filters represent the fastest-expanding category as they combine organic absorbance with inorganic scattering to achieve broad-spectrum performance without whitening effects.
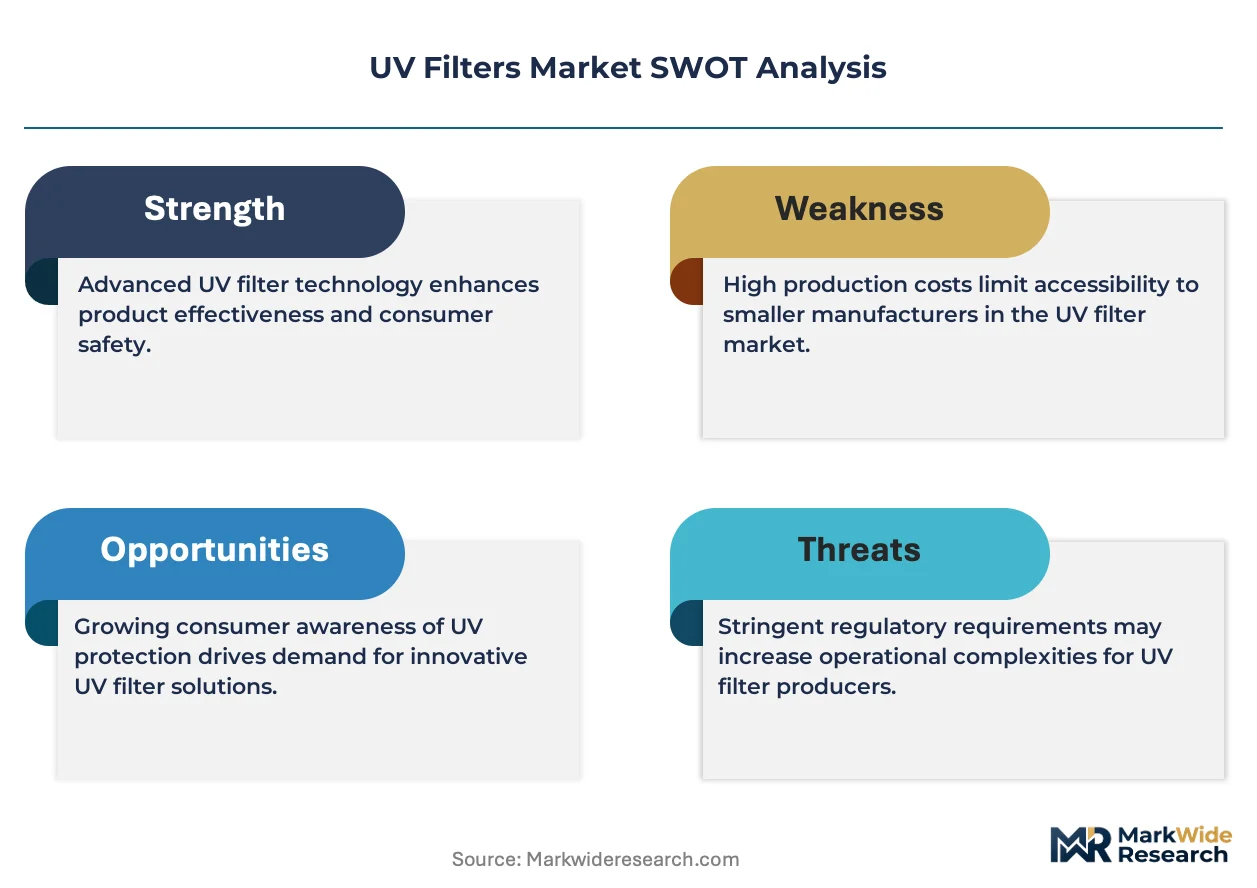
EMA and FDA both enforce stringent dermal safety thresholds that elevate toxicological testing burdens for new filter molecules seeking market authorization. REACH registration requirements in Europe further constrain import of unregistered aromatic UV absorbers, redirecting supply toward domestic and pre-certified producers. ISO 24443 and ISO 24444 standards govern in vitro and in vivo SPF validation, creating compliance moats for laboratories with certified testing infrastructure. Stakeholders must monitor pending FDA monograph reforms and emerging state-level bans on specific organic filters to anticipate reformulation cycles and raw material substitution waves.
Market Dynamics
REACH registration requirements and FDA monograph reforms are compressing the supplier base for organic UV filters, forcing formulators toward pre-certified producers with validated toxicological dossiers. This regulatory tightening is redrawing competitive boundaries around compliance infrastructure rather than synthesis scale alone.
Growth Catalysts
- Photostabilizer innovation:Advanced quencher combinations extend SPF durability in water-resistant sunscreen formulations, opening premium positioning for beach and sport cosmetic lines.
- East Asian formulation hub expansion:Procurement from Seoul and Shanghai is accelerating as regional cosmetics manufacturers scale domestic R&D capabilities.
- Reef-safe mandates:Hawaii and Key West bans on oxybenzone and octinoxate are redirecting demand toward mineral-hybrid filter architectures.
Market Restraints
- Aromatic precursor concentration:Benzophenone and triazine intermediate supply clusters in Germany and China create geographic vulnerability to single-point disruptions.
- EMA dermal safety thresholds:Extended toxicological testing timelines for new molecular entities delay market authorization by 18-36 months.
- Inorganic filter substitution:Zinc oxide and titanium dioxide advances threaten volume share in sensitive-skin and pediatric segments.
Strategic Opportunities
- Cold-process cosmetic compatibility:Lipid-dispersed organic filters eliminate heating stages, reducing energy costs for mid-tier contract manufacturers.
- Indian personal care expansion:BIS certification alignment with ISO 24443 creates entry pathway for validated European suppliers.
- Textile UV protection:Functional finishing of athletic and outdoor apparel represents underexploited volume channel beyond traditional cosmetics.
Industry Challenges
- ISO 24444 in vivo testing capacity:Certified laboratory scarcity creates bottlenecks for SPF validation, particularly for small-batch niche launches.
- Dual regulatory dossier maintenance:Parallel FDA monograph and REACH registration requirements strain regulatory affairs teams at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Filters Market |
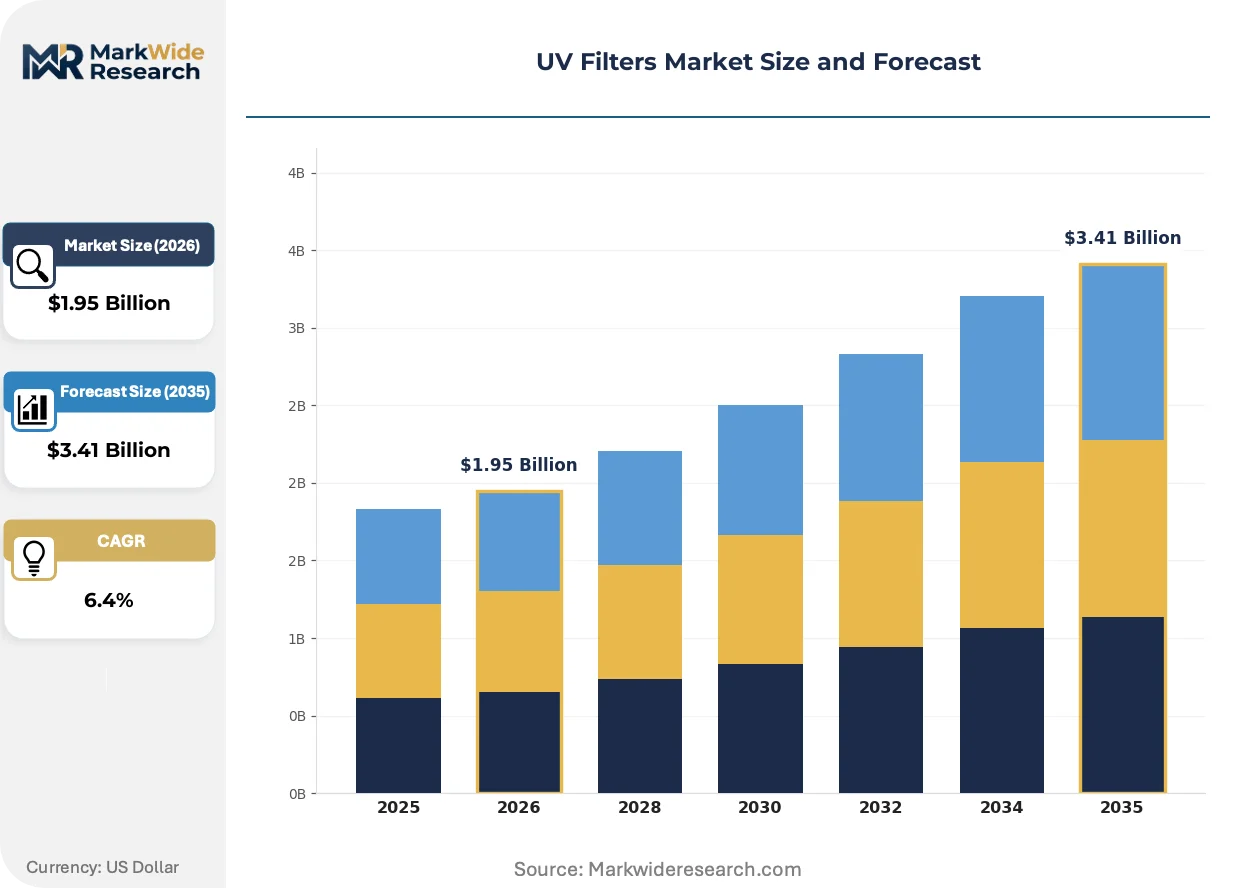
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Filters, Inorganic Filters, Hybrid Filters, Coatings Application: Cosmetics, Pharmaceuticals, Industrial Coatings, Textiles End User: Manufacturers, Retailers, Distributors, Consumers Form: Liquids, Powders, Pastes, Granules |
| Companies Covered | BASF SE, Croda International Plc, DSM-Firmenich AG, The Dow Chemical Company, Ashland Inc., Symrise AG, Sunjin Beauty Science, Givaudan, Kobo Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Filters Market Emerging Trajectories
Formulation science is pivoting toward hybrid architectures that merge organic absorbance with inorganic scattering, driven by performance demands that single-mechanism filters cannot satisfy. This convergence is compressing traditional category boundaries.
Encapsulation technology is decentralizing active delivery in UV filter systems. Microsphere and sol-gel matrices shield chromophores from premature photodegradation while enabling sustained release. Korean cosmetics manufacturers are adopting these systems fastest, integrating them into multi-functional BB and CC cream lines. The structural consequence is fragmenting supply relationships away from bulk chemical traders toward specialized dispersion houses.
REACH authorization requirements for aromatic UV absorbers are elevating registration costs for import-dependent formulators. ECHA's tightening substance evaluation protocols now demand extended environmental fate studies. European cosmetics producers are responding by consolidating procurement through domestic pre-registered suppliers, compressing the viable vendor base.
Direct technical collaboration between filter suppliers and finished goods manufacturers is displacing arm's-length commodity purchasing. Cosmetic brands now embed formulation scientists within supplier development programs to co-design photostable systems. This pattern is most pronounced in South Korea, where Amorepacific and LG Household & Health Care operate dedicated UV research consortia with raw material partners.
UV Filters Market Segmentation
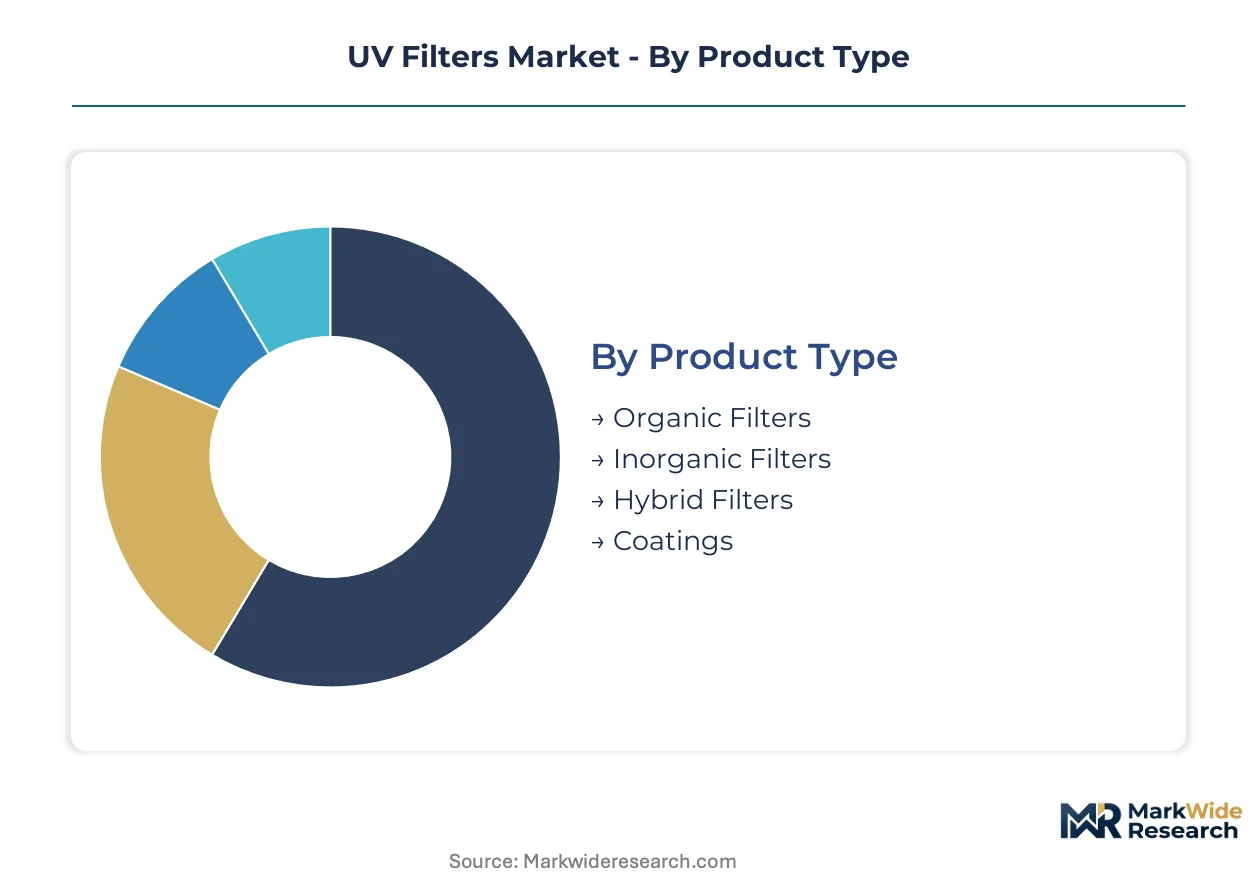
UV filter segmentation reveals distinct capital requirements across synthesis routes and formulation architectures. Investment intensity varies sharply between commodity organic production and specialized dispersion technologies.
Product Type:
Organic filter manufacturing demands the heaviest upfront commitment due to multi-stage Friedel-Crafts alkylation infrastructure and dedicated nitration containment systems.
- Organic Filters:Benzotriazole, camphor, and triazine chromophores synthesized through aromatic substitution chemistry dominate volume. Procurement concentrates among Seoul and Shanghai cosmetics formulators seeking cost-efficient broad-spectrum protection. REACH registration costs and FDA monograph compliance elevate barriers for new entrants.
- Inorganic Filters:Zinc oxide and titanium dioxide particulates require specialized milling and surface-coating equipment to achieve cosmetic-grade transparency. Demand clusters in Hawaii and Key West markets where reef-safe mandates prohibit oxybenzone and octinoxate.
- Hybrid Filters:Dual-mechanism architectures combining organic absorbance with mineral scattering.
- Coatings:Substrate-specific UV-barrier formulations for polymer and textile protection.
Most installed capacity flows through Organic Filters. Expansion is steepest in Hybrid Filters.
Application:
Volume concentration follows end-use sophistication, with cosmetic-grade specifications commanding premium positioning over industrial applications.
- Cosmetics:Facial and body sunscreens, BB creams, and daily moisturizers incorporate lipid-compatible dispersions for cold-process formulation. Korean manufacturers Amorepacific and LG Household & Health Care drive specification intensity through dedicated UV research consortia.
- Pharmaceuticals:Photoprotective dermatological treatments and photosensitive drug packaging require validated toxicological dossiers under EMA and FDA frameworks.
- Industrial Coatings:Automotive clearcoats and architectural finishes prioritize photostability over dermal safety thresholds.
- Textiles:Functional athletic and outdoor apparel finishing represents an underexploited channel beyond traditional personal care.
Cosmetics absorb the majority of high-purity output. Textiles claim the fastest-climbing demand trajectory.
End User:
Supply chain position determines technical engagement depth, with direct manufacturers capturing formulation collaboration benefits unavailable to downstream intermediaries.
- Manufacturers:Finished goods producers embed scientists within supplier development programs to co-design photostable systems. BASF SE and DSM-Firmenich AG operate dedicated technical service teams for this segment.
- Retailers:Private-label cosmetics brands and pharmacy chains specify filter performance through contract manufacturers.
- Distributors:Bulk chemical traders face margin compression as encapsulation technology fragments supply relationships toward specialized dispersion houses.
- Consumers:Direct purchasing of mineral sunscreens and reef-safe formulations through e-commerce channels.
Manufacturers control the deepest technical relationships. Retailers are gaining procurement sophistication fastest.
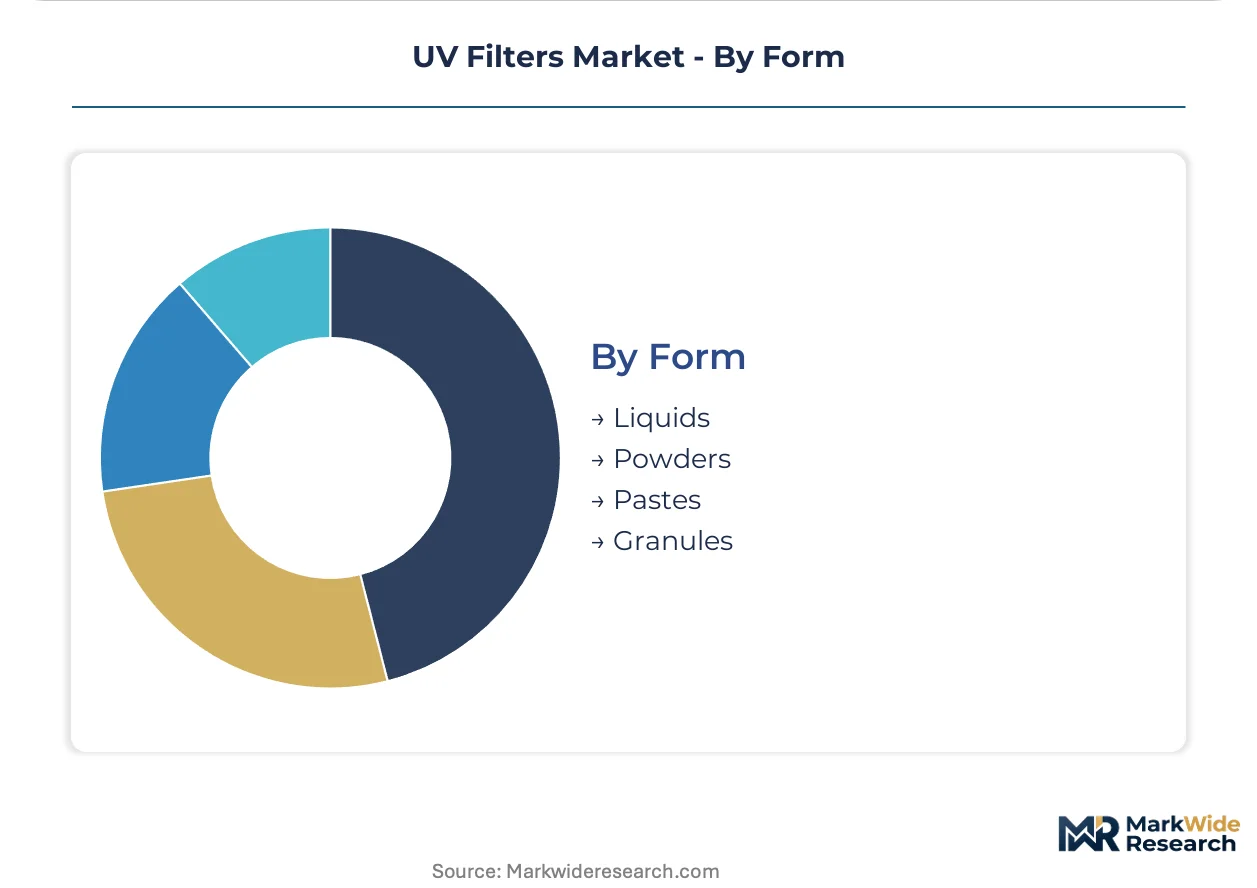
Form:
Physical state dictates handling infrastructure and formulation integration methods, with liquid dispersions requiring the most specialized storage and transport systems.
- Liquids:Pre-dispersed organic filters in cosmetic oils enable direct cold-process incorporation without heating stages. Croda International Plc specializes in lipid-compatible liquid systems that reduce energy costs for mid-tier contract manufacturers.
- Powders:Dry mineral filters and organic actives require dust containment and precise particle size distribution control.
- Pastes:Concentrated dispersions for high-SPF formulation.
- Granules:Solid masterbatch formats for polymer compounding.
Liquids dominate cosmetic formulation intake. Powders retain cost advantages in industrial polymer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors formulation demand for advanced organic UV filters as South Korean cosmetics manufacturers accelerate procurement of photostable systems. Procurement from Shanghai is accelerating as regional cosmetics manufacturers scale domestic R&D capabilities.
United States
Hawaii and Key West bans on oxybenzone and octinoxate are redirecting demand toward mineral-hybrid filter architectures. FDA sunscreen monograph updates are tightening purity benchmarks and expanding testing protocols. Formulation activity concentrates in New Jersey and California corridors where contract manufacturers serve premium beach and sport cosmetic lines.
Germany
BASF SE anchors European production of broad-spectrum organic filters through integrated precursor manufacturing. REACH compliance is elevating registration costs for import-dependent formulators and compressing the viable vendor base. The Ludwigshafen industrial cluster maintains captive supply of benzophenone and triazine intermediates for regional cosmetics producers.
China
Shanghai formulation hubs are scaling domestic R&D capabilities for lipid-compatible dispersions. SAMR alignment with ISO 24443 and ISO 24444 standards is creating compliance moats for laboratories with certified testing infrastructure. Yangtze River Delta cosmetics manufacturers are embedding scientists within supplier development programs to co-design photostable systems.
India
BIS certification alignment with ISO 24443 creates entry pathway for validated European suppliers. CDSCO dermal safety thresholds are extending toxicological testing timelines for new molecular entities. Mumbai and Ahmedabad personal care clusters are expanding cold-process formulation capacity for mid-tier contract manufacturers.
South Korea
Amorepacific and LG Household & Health Care operate dedicated UV research consortia with raw material partners. MFDS enforcement of stringent dermal safety thresholds elevates toxicological testing burdens for new filter molecules. Seoul cosmetics manufacturers are adopting encapsulation technology fastest, integrating microsphere matrices into multi-functional BB and CC cream lines.
UV Filters Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized dispersion technologies and hybrid filter architectures. The supplier base compresses around pre-certified producers with validated toxicological dossiers as REACH and FDA requirements tighten. Strategic archetypes include integrated precursor manufacturers, lipid-compatible dispersion specialists, and photostabilizer combination innovators. Capacity consolidation and direct technical collaboration with finished goods manufacturers represent the dominant competitive moves.
Among European-based chemical conglomerates, BASF SE, Croda International Plc, and DSM-Firmenich AG exemplify distinct positioning vectors. BASF SE represents the integrated manufacturing archetype with captive control over aromatic intermediate supply chains. Croda International Plc occupies the formulation-enablement tier through specialization in lipid-compatible systems that reduce energy costs for contract manufacturers. DSM-Firmenich AG anchors the photostability innovation segment where quencher combinations extend SPF durability in water-resistant applications.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| DSM-Firmenich AG |
| The Dow Chemical Company |
| Ashland Inc. |
| Symrise AG |
| Sunjin Beauty Science |
| Givaudan |
| Kobo Products Inc. |
| Others |
Supply Flow & Price Mechanics
Benzophenone and triazine intermediate costs cascade through three distinct pricing tiers as formulators balance REACH registration premiums against raw material volatility. Procurement officers at Seoul and Shanghai cosmetics hubs now weight certificate-of-origin documentation as heavily as unit price in supplier selection.
Pricing Analysis
Input-cost pass-through from aromatic precursor markets drives contract renegotiations every 12-18 months for organic filter buyers. Three-tier pricing structure across premium, standard, and economy levels separates photostabilizer-enhanced dispersions from commodity benzotriazole powders and unregistered import alternatives. Price differentiation hinges on REACH dossier completeness and ISO 24443 testing validation. Pricing pressure stems from zinc oxide substitution in pediatric segments. Mid-tier contract manufacturers exhibit highest price sensitivity; premium beach and sport cosmetic lines absorb cost increases with minimal volume elasticity.
Supply Chain Analysis
Dual-sourcing requirements now mandate qualified suppliers across at least two of Germany, China, and India for benzophenone intermediates. Raw material dependencies center on aniline derivatives, aluminum chloride catalysts, and cosmetic-grade mineral oils. Supply chain risk concentrates in Yangtze River Delta logistics chokepoints affecting Shanghai formulation hub access. Distribution runs through integrated dispersion houses that have displaced bulk chemical traders as encapsulation technology fragments traditional procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV filter procurement has shifted toward late-cycle quality specifications as Korean and Chinese cosmetics manufacturers prioritize photostability validation over per-kilogram cost minimization.
For Market Incumbents: Deploy photostabilizer R&D consortia to lock in formulation collaboration with finished goods manufacturers. BASF SE and DSM-Firmenich AG already embed technical service teams within Amorepacific and LG Household & Health Care development programs. Capacity addition in Ludwigshafen and Seoul secures captive intermediate supply against Yangtze River Delta disruption. Certification investment in pre-registered REACH dossiers compresses the viable vendor base and raises rival exclusion costs. For New Entrants and Emerging Players: Launch via specialized dispersion technology partnerships targeting mid-tier Indian contract manufacturers. Cold-process lipid-compatible systems represent the most penetrable segment as Mumbai and Ahmedabad personal care clusters expand formulation capacity. White-space exists in textile UV protection for athletic apparel beyond traditional cosmetics channels. Direct technical collaboration with regional brands bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where dual regulatory dossier maintenance strains mid-scale producer regulatory affairs capacity. Long-term viability favors integrated manufacturers with captive aromatic intermediate production or specialized dispersion houses with cold-process IP. Target acquisition archetype: European pre-certified suppliers with validated toxicological infrastructure and existing Seoul or Shanghai customer relationships. Signal to watch: FDA monograph reform timing and state-level organic filter ban proliferation as inflection indicators for raw material substitution waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Intermediates | BASF SE's Ludwigshafen cluster secures benzophenone supply against Yangtze River Delta disruption. |
| Photostabilizer R&D Consortium Formation | DSM-Firmenich AG extends SPF durability through quencher combinations for water-resistant beach lines. |
| Cold-Process Dispersion Technology Launch | Croda International Plc reduces energy costs for mid-tier Mumbai contract manufacturers. |
| REACH Pre-Registration Dossier Investment | European vendors raise rival exclusion costs as ECHA tightens substance evaluation protocols. |
| Textile UV Protection Channel Expansion | Functional athletic apparel finishing opens volume beyond traditional personal care applications. |
Methodological Framework
Multiple input streams — primary interviews with cosmetic formulators, regulatory affairs directors, and procurement leads at Seoul and Shanghai hubs; secondary validation through ECHA substance registration databases, FDA sunscreen monograph dockets, and ISO 24443/24444 certification records — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments across the projection horizon. Segmentation dimensions modeled include filter mechanism type, application end-use, physical form, and regional formulation hub concentration. CAGRs were derived from curve-fitting approaches calibrated to regulatory authorization timelines and substitution elasticity parameters. Industry-specific forecast inputs incorporated REACH registration cost inflation and photostabilizer patent expiration schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under simultaneous FDA monograph reform and ECHA authorization withdrawal scenarios. Deviation in Hawaii-style state-level organic filter bans would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Alkoxide Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Xanthene Derivatives Market