
 Global Cellulose Esters Market | 2026-2036
Global Cellulose Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cellulose Esters Market Foresight
Specialty chemical distribution is fragmenting as regional distributors lose ground to direct procurement platforms and integrated supplier networks. Eastman Chemical Company leverages its captive cellulose acetate flake capacity to secure long-term coating supply agreements. Celanese Corporation anchors North American demand through backward integration into acetic acid and anhydride feedstocks. Daicel Corporation dominates Asian membrane-grade ester supply with proprietary solvent recovery systems that lower unit costs.
Cellulose esters are modified polysaccharides produced by esterifying cellulose with acids or anhydrides, yielding thermoplastic polymers with controlled hydroxyl substitution degrees typically between 1.5 and 3.0 and molecular weights spanning 30,000 to 100,000 g/mol for film-grade grades. These materials function primarily as binders, film formers, and rheology modifiers in coatings, photographic substrates, and separation membranes where petroleum-derived alternatives fail on biodegradability or optical clarity. Cellulose acetate retains the largest volume share due to entrenched cigarette filter tow demand, though margin pools have shifted toward cellulose acetate butyrate in automotive refinish coatings where weathering resistance commands formulation premiums. Membrane applications represent the fastest-expanding consumption node as hollow-fiber and thin-film composite producers adopt cellulose ester substrates for water treatment and gas separation modules.
REACH registration requirements under ECHA govern phthalate plasticizer alternatives and solvent emissions across European coating value chains, pushing formulators toward cellulose acetate propionate grades with lower volatile organic compound footprints. EPA New Chemicals Program reviews in the United States constrain introduction of unregistered ester variants for food-contact and medical applications, while China's GB standards under SAMR set purity thresholds for imported cellulose nitrate used in lacquer formulations. Stakeholders must monitor regulatory divergence between jurisdictions on permissible residual acid content and plasticizer migration limits, as compliance costs will determine which ester chemistries sustain formulation access across major demand centers.
Market Dynamics
Automotive refinish coating specifications are tightening solvent tolerance thresholds, forcing formulators to reformulate around cellulose acetate butyrate and propionate grades with superior weathering resistance and reduced volatile organic compound footprints. This specification pivot is compressing demand for conventional cellulose acetate in coatings while expanding specialty ester volumes.
Growth Catalysts
- REACH solvent emission limits:ECHA-mandated reductions in coating volatile organic compounds are accelerating cellulose acetate propionate adoption in European automotive refinishing formulations.
- Membrane substrate demand:Hollow-fiber water treatment module producers are expanding cellulose ester consumption for thin-film composite separation layers.
- China film and plastics output:Domestic production scale-up in photographic and packaging substrates is concentrating regional cellulose acetate flake demand.
Market Restraints
- Acetic anhydride price volatility:Feedstock cost swings tied to petrochemical naphtha cracking economics compress margin stability for acetate-grade producers.
- Supplier concentration in East Asia:Membrane-grade ester supply clusters around Japanese and Korean producers with proprietary solvent recovery systems, creating procurement bottlenecks.
- Biopolymer substitution threat:Polylactic acid and polyhydroxyalkanoate alternatives are encroaching on biodegradable packaging applications previously served by cellulose esters.
Strategic Opportunities
- Indian pharmaceutical film coatings:CDSCO-registered cellulose acetate phthalate demand is expanding with domestic generic drug manufacturing scale-up.
- EU Green Deal bio-based mandates:Renewable content thresholds in consumer goods are creating formulation incentives for cellulose-derived thermoplastics.
- Direct procurement platforms:Specialty chemical distributors are losing ground to integrated supplier networks, opening channel restructuring possibilities for ester producers with captive flake capacity.
Industry Challenges
- Esterification process engineering expertise:Controlled hydroxyl substitution degree management requires specialized chemical engineering talent pools concentrated at legacy producers.
- Multi-jurisdiction registration timelines:EPA New Chemicals Program reviews for food-contact grades and ECHA substance evaluations create 18-36 month market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cellulose Esters Market |
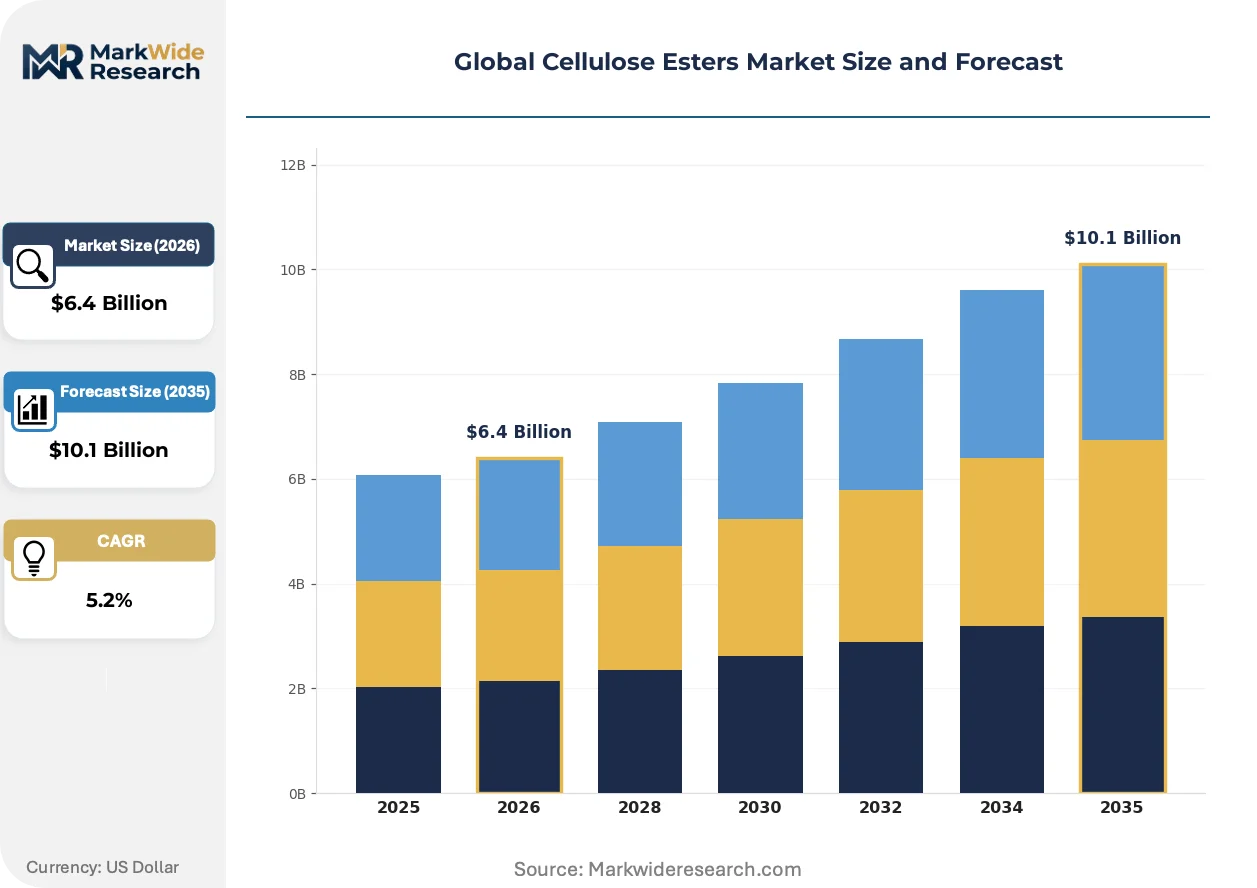
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Acetate, Cellulose Acetate Butyrate, Cellulose Acetate Propionate, Cellulose Nitrate, Mixed Esters Application: Film & Photography, Coatings & Paints, Membranes, Plastics, Textile Fibers End User Industry: Packaging Providers, Consumer Electronics Makers, Adhesive Manufacturers, Specialty Chemicals Producers, Textile Manufacturers Form: Powder, Granule, Flake, Sheet, Fiber |
| Companies Covered | Eastman Chemical Company, Celanese Corporation, Daicel Corporation, AkzoNobel, Borregaard, Rayonier Advanced Materials, Sappi, Mitsubishi Chemical Corporation, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cellulose Esters Market Shifts & Advancements
Reformulation activity across coating value chains is accelerating as regulatory pressure on solvent systems intensifies, with cellulose ester producers repositioning product portfolios around lower-substitution grades and aqueous dispersion technologies.
Continuous esterification reactor designs with real-time degree-of-substitution monitoring are rendering obsolete batch-wise acetylation processes that dominated cellulose acetate manufacturing for decades. Coating formulators in Germany and the United States are piloting these systems at pilot scale. The technology is compressing capital intensity per ton while tightening molecular weight distribution control for film-grade specifications.
REACH authorization requirements under ECHA are tightening phthalate plasticizer restrictions across European coating and packaging value chains. Formulators are substituting cellulose acetate propionate for legacy plasticized acetate grades in food-contact lacquers. The shift is most pronounced in Italian and French cosmetics packaging supply chains, where brand owners are accelerating compliance timelines ahead of regulatory deadlines.
Automotive refinish buyers are consolidating supplier relationships around integrated coating system providers with captive cellulose ester formulation libraries. Direct procurement agreements are displacing spot purchasing through regional distributors in North America and Western Europe. The pattern is most visible in German and US collision repair networks, where procurement centralization is compressing formulation approval cycles and locking in multi-year supply commitments.
Global Cellulose Esters Market Segmentation
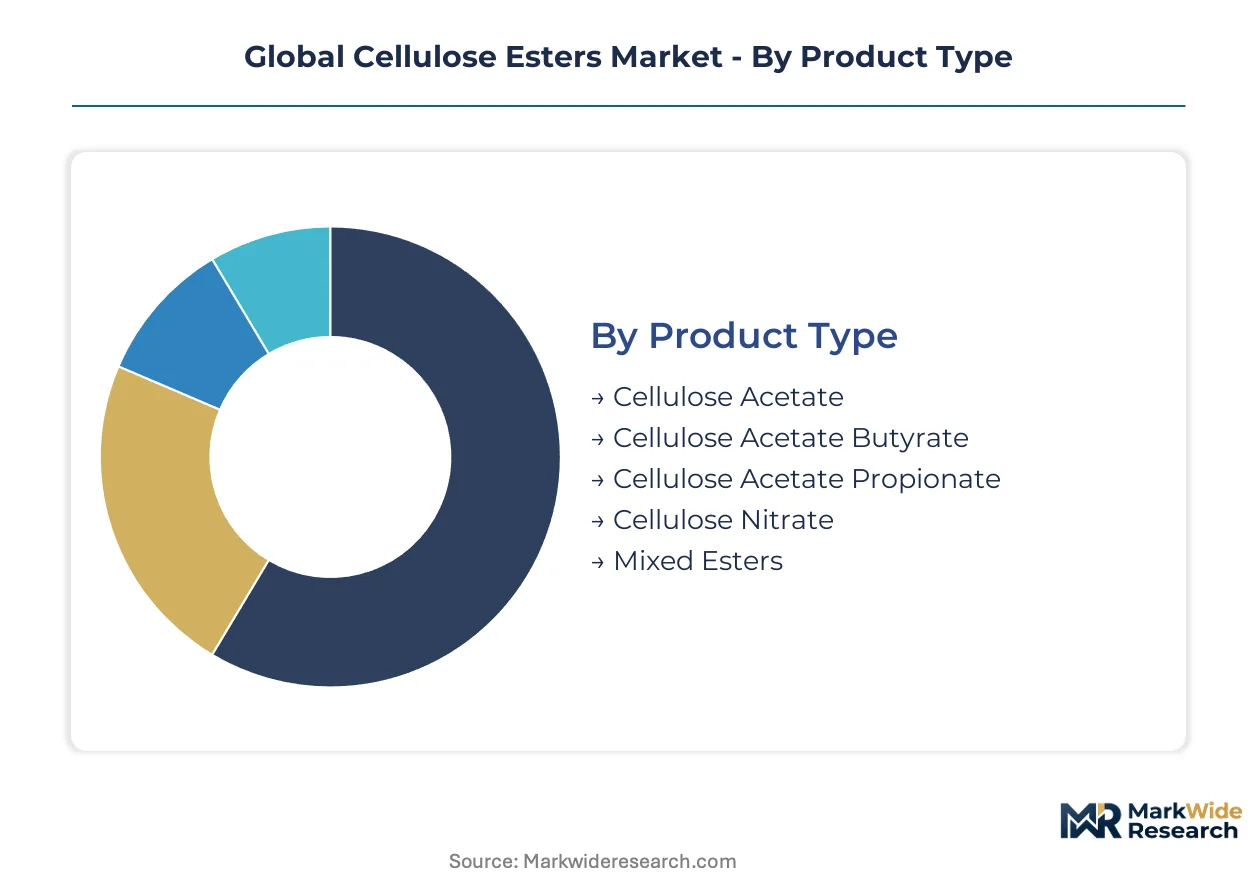
Segmentation in cellulose esters separates commodity acetate tow from specialty butyrate and propionate grades commanding formulation premiums. Product chemistry, application requirements, and physical form together determine procurement specifications, regulatory pathways, and margin structures across end-use value chains.
Product Type:
Chemistry defines performance boundaries, with substitution degree and acid moiety controlling solubility, weathering resistance, and biodegradation rates.
- Cellulose Acetate:The most widely manufactured grade features acetyl substitution degrees between 2.0 and 2.5, yielding thermoplastic properties suitable for cigarette filter tow and photographic film bases. Chinese domestic flake production scales are concentrating volume demand as local manufacturers displace imported material in packaging and substrate applications.
- Cellulose Acetate Butyrate:Mixed ester incorporating butyryl groups enhances weathering resistance and reduces moisture absorption versus straight acetate grades. Automotive refinish coatings in Germany and the United States specify this chemistry for exterior clearcoats where UV stability and humidity tolerance command premium pricing.
- Cellulose Acetate Propionate:Lower volatile organic compound solubility profiles align with ECHA REACH emission limits in European coating formulations.
- Cellulose Nitrate:High nitrogen content delivers rapid solvent release for lacquer applications in Italian and French cosmetics packaging.
- Mixed Esters:Custom substitution ratios balance properties for specialty membrane substrates in Japanese water treatment modules.
Cellulose acetate holds installed capacity. Cellulose acetate butyrate is rotating up the share rankings.
Application:
End-use performance requirements drive ester selection, with optical clarity, barrier properties, and mechanical strength determining formulation fit.
- Film & Photography:Cellulose triacetate and diacetate substrates provide dimensional stability and optical clarity for photographic and motion picture film bases. Japanese and Korean producers dominate supply for professional cinema stock where archival longevity specifications exceed 100 years.
- Coatings & Paints:Solvent-borne and water-borne systems employ cellulose esters as rheology modifiers and film formers in automotive refinish, wood finishes, and industrial maintenance coatings. ECHA REACH solvent emission thresholds are accelerating propionate-grade adoption in German and Italian automotive repair networks.
- Membranes:Hollow-fiber and thin-film composite separation layers utilize cellulose ester substrates for water treatment, gas separation, and medical dialysis applications.
- Plastics:Thermoplastic processing of cellulose ester compounds yields biodegradable alternatives to petroleum-derived materials in consumer goods.
- Textile Fibers:Acetate filament and staple fibers serve luxury apparel and lining applications where silk-like drape and moisture management justify material costs.
Coatings & paints generates the steepest expansion trajectory as regulatory pressure on solvent systems intensifies reformulation activity.
End User Industry:
Customer sophistication and volume scale determine supply relationship structures, with integrated producers favoring direct procurement over distributor channels.
- Packaging Providers:Folding carton, blister pack, and cosmetics container manufacturers specify cellulose ester films and coatings for clarity and printability. Italian and French brand owners are advancing ECHA REACH compliance timelines ahead of regulatory deadlines.
- Consumer Electronics Makers:Display substrates and optical films employ cellulose triacetate for polarizer protection layers in LCD and OLED panels. Korean and Japanese display manufacturers concentrate demand for ultra-pure grades with sub-ppm metallic contamination limits.
- Adhesive Manufacturers:Pressure-sensitive and hot-melt formulations utilize cellulose ester tackifiers and rheology modifiers.
- Specialty Chemicals Producers:Intermediates and performance additives incorporate cellulose esters as controlled-release matrices and encapsulation agents.
- Textile Manufacturers:Weaving and knitting operations process acetate filament for luxury apparel applications.
Packaging providers hold installed capacity. Consumer electronics makers are rotating up the share rankings.
Form:
Physical presentation determines handling economics, dissolution rates, and downstream processing compatibility.
- Flake:Standard presentation for cellulose acetate tow and film-grade applications enables controlled dissolution in acetone and other ketone solvents. Captive flake capacity at integrated producers like Eastman Chemical supports long-term coating supply agreements.
- Powder:Fine particle size distributions accelerate dissolution kinetics for coating formulators and adhesive compounders requiring rapid batch turnaround.
- Granule:Dust-free handling characteristics suit automated feeding systems in thermoplastic compounding operations.
- Sheet:Calendered and extruded sheet formats serve thermoforming and die-cutting operations in packaging and consumer goods.
- Fiber:Continuous filament and staple formats feed textile spinning and nonwoven manufacturing.
Flake holds installed capacity. Powder is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port underwrites China's dominance in cellulose ester flake imports, handling bulk chemical flows that feed domestic film and coating manufacturing clusters. This maritime infrastructure anchors the Asia-Pacific supply corridor while European and North American demand centers rely on integrated inland distribution networks.
China
Domestic photographic film and packaging substrate manufacturers are scaling cellulose acetate flake consumption as local production displaces imports. GB standards under SAMR set purity thresholds for cellulose nitrate in lacquer formulations, tightening quality compliance for foreign suppliers. The Yangtze River Delta concentration around Shanghai and Suzhou hosts expanding membrane-grade ester processing for water treatment module exports.
Germany
Automotive refinish coating formulators in Bavaria and Baden-Württemberg are reformulating around cellulose acetate butyrate to meet ECHA REACH solvent emission limits. The KBA maintains strict volatile organic compound thresholds for vehicle repair networks, accelerating specialty ester adoption. The Cologne-Düsseldorf chemical corridor houses integrated coating system providers consolidating direct procurement agreements with captive ester suppliers.
United States
EPA New Chemicals Program reviews constrain unregistered ester variants for food-contact applications, creating 18-36 month market access delays for new entrants. The Gulf Coast petrochemical corridor supplies acetic anhydride feedstock to acetate-grade producers, though naphtha cracking economics introduce margin volatility. Eastman Chemical's Tennessee operations anchor North American captive flake capacity for long-term coating supply agreements.
Japan
METI industrial standards govern cellulose ester purity for optical film applications in display manufacturing. The Osaka-Kobe industrial zone concentrates membrane-grade ester production with proprietary solvent recovery systems that lower unit costs for hollow-fiber water treatment substrates. Daicel Corporation's integrated operations dominate regional supply for thin-film composite separation layers.
India
CDSCO-registered cellulose acetate phthalate demand is expanding with domestic generic drug manufacturing scale-up in pharmaceutical film coatings. The Mumbai-Pune industrial belt hosts formulation facilities serving both export and domestic markets. Gujarat's chemical parks are attracting specialty ester distributors seeking channel access to South Asian packaging providers.
Global Cellulose Esters Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical producers with captive feedstock positions and long-term coating supply agreements. Three archetypes dominate competitive positioning: petrochemical majors with backward integration into acetic acid and anhydride feedstocks, Asian specialists with proprietary solvent recovery systems for membrane-grade esters, and diversified materials companies leveraging flake capacity for formulation partnerships. Dominant competitive moves include direct procurement platform development displacing regional distributors, and continuous esterification reactor investments compressing capital intensity per ton.
Among North American integrated producers, Eastman Chemical Company and Celanese Corporation occupy positions anchored by captive cellulose acetate flake capacity and acetic anhydride feedstock control respectively. Daicel Corporation exemplifies the Asian specialist archetype with proprietary manufacturing systems concentrated in Japanese industrial clusters. These three companies represent the tiered structure where feedstock integration, process technology, and regional market access determine competitive positioning across coating, membrane, and film applications.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Celanese Corporation |
| Daicel Corporation |
| AkzoNobel |
| Borregaard |
| Rayonier Advanced Materials |
| Sappi |
| Mitsubishi Chemical Corporation |
| Solvay |
| Others |
Supply & Pricing Matrix
The Shanghai Yangshan deep-water port freight corridor anchors Asia-Pacific cellulose ester flows, with container handling costs feeding directly into flake pricing tiers and coating formulator procurement decisions across German and US automotive refinish networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates membrane-grade specialty esters from commodity acetate tow and industrial flake grades. Price differentiation rests on acetic anhydride feedstock integration and ECHA REACH certification status for European coating applications. Cost compression in standard-grade acetate flake is intensifying because Chinese domestic production scales are displacing import volumes. Packaging providers exhibit highest price sensitivity due to thin conversion margins, while membrane module producers accept premium positioning for optical purity guarantees.
Supply Chain Analysis
Contract manufacturing concentration at Eastman Chemical's Tennessee operations, Daicel Corporation's Osaka-Kobe facilities, and Celanese Corporation's Gulf Coast sites holds captive flake capacity for long-term coating agreements. Geographic supply concentration clusters in the United States, Japan, and China, with acetic anhydride, high-alpha cellulose pulp, and proprietary solvent recovery systems serving as critical input dependencies. Single-source vulnerability around Japanese membrane-grade ester technology creates procurement bottlenecks for hollow-fiber water treatment module producers. Distribution runs through integrated supplier networks displacing regional chemical distributors in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose ester procurement is approaching a platform-economics inflection as direct-procurement systems and formulation libraries interoperate across automotive refinish networks, compressing spot-market participation.
For Market Incumbents: Harden captive flake capacity positions through backward integration into acetic anhydride feedstocks, particularly along the US Gulf Coast petrochemical corridor. Deepen formulation partnerships with German automotive refinish networks facing ECHA REACH solvent emission deadlines. Secure long-term coating supply agreements before direct procurement platforms fully displace distributor channels.
For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical film coatings where CDSCO-registered cellulose acetate phthalate demand is expanding with domestic generic drug manufacturing. Target membrane substrate supply to hollow-fiber water treatment module producers seeking alternatives to Japanese and Korean concentration. Lead with aqueous dispersion technology offerings that bypass incumbent solvent-based formulation lock-in.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized esterification assets and stranded flake capacity outside coating supply relationships. Long-term viability hinges on feedstock integration depth and regulatory registration breadth across EPA New Chemicals Program and ECHA substance evaluations. Watch for continuous esterification reactor adoption rates as capital efficiency inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Anhydride | Captive feedstock supply from Gulf Coast petrochemical cracking insulates margin volatility from naphtha price swings. |
| Continuous Esterification Reactor Deployment | Real-time degree-of-substitution monitoring at German pilot facilities compresses capital intensity per ton versus batch acetylation. |
| ECHA REACH Pre-Registration Acceleration | Early compliance timelines for cellulose acetate propionate grades secure formulation access ahead of Italian and French cosmetics packaging deadlines. |
| Direct Procurement Platform Development | Integrated supplier networks displace regional distributors in North American collision repair procurement centralization. |
| Membrane-Grade Specialty Ester Capacity Addition | Proprietary solvent recovery systems for hollow-fiber substrates lower unit costs in Japanese water treatment module supply. |
Research Methodology
A standing panel of coating formulation chemists, automotive refinish procurement directors, membrane module production engineers, and specialty chemical distribution executives provided ongoing calibration across the study period. Primary interviews with plant managers at acetic anhydride facilities, technical R&D directors at esterification operations, and channel partners in European coating supply chains combined with secondary validation from customs and trade data, SEC 10-K filings, and ACC industry reports. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity disclosures.
Scenario-bracketing around regulatory acceleration and feedstock price volatility frames the projection horizon across the analysis window. Segmentation dimensions modeled include ester chemistry tier, end-use application, physical form factor, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive refinish coating specifications, membrane substrate adoption curves, and cigarette filter tow demand trajectories. Forecast inputs center on ECHA REACH implementation pace and Chinese domestic flake production scale-up rates.
Sensitivities concentrate around acetic anhydride price volatility, ECHA substance evaluation timelines, and biopolymer substitution acceleration in biodegradable packaging applications. Forecasts reflect documented assumptions on regulatory compliance cost pass-through and coating reformulation cycle speeds. Quarterly review of CDSCO registration filings, German KBA emission threshold updates, and Yangtze River Delta membrane-grade processing capacity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Barium Fluoride Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
MLCC Silicone Release Film Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Decorative Surface Films Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Global Consumer Foam Market