
 Asia Pacific Methyl Glucose Market | 2026-2036
Asia Pacific Methyl Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Methyl Glucose Market Analysis
Consolidation among multinational cosmetic manufacturers is repositioning procurement leverage toward fewer buyers with larger volume contracts. BASF SE leverages its integrated oleochemicals platform to anchor supply security for methyl glucose esters across Northeast Asia. Kao Corporation sustains competitive differentiation through specialized grades tailored to Japanese cosmetic formulations. Guangzhou Tinci Materials Technology Co., Ltd. dominates regional production capacity with backward integration into glucose feedstock sourcing.
Methyl glucose refers to glucose derivatives where hydroxyl groups undergo methylation or esterification, yielding amphiphilic compounds with HLB values typically ranging from 8 to 16 depending on fatty acid substitution. These compounds function primarily as mild emulsifiers, solubilizers, and rheology modifiers in personal care and pharmaceutical applications. Methyl glucose sesquistearate leads product type demand due to its established performance in premium skin creams, while methyl glucose caprate represents the fastest-growing ester variant driven by natural-positioned hair care formulations. Personal care applications command the dominant value share, though pharmaceutical-grade specifications are deepening margin pools as drug formulators adopt excipient-grade methyl glucose for oral and topical delivery systems.
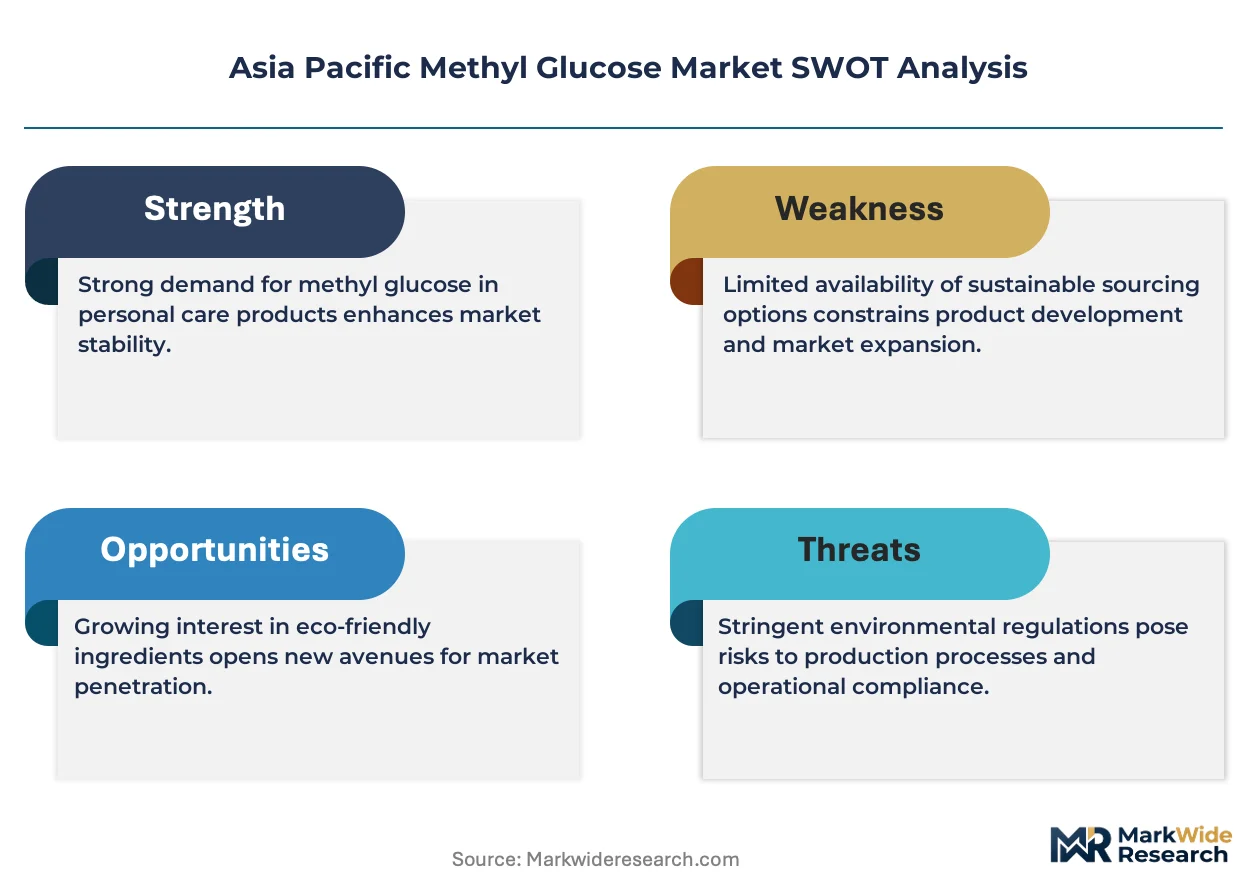
Japan's METI enforces chemical substance notification requirements under the Act on the Evaluation of Chemical Substances, directly influencing methyl glucose import documentation and purity certification thresholds for cosmetic applications. China's SAMR administers national food additive standards that restrict methyl glucose derivative usage in food industry applications to specified GRAS-equivalent categories, shaping domestic manufacturer formulation strategies. India's BIS cosmetic safety guidelines are converging with ASEAN harmonization protocols, creating cross-border compliance complexity for suppliers serving multiple national markets. Stakeholders must monitor regulatory divergence between Japan's stringent cosmetic chemical assessments and China's expanding domestic oleochemical standards to anticipate certification cost impacts on regional trade flows.
Market Dynamics
Consolidation among multinational cosmetic manufacturers is concentrating procurement leverage into fewer buyers commanding larger volume contracts, fundamentally altering supplier negotiation dynamics across Northeast and Southeast Asia.
Growth Catalysts
- Japan's METI cosmetic chemical standards:Tightening purity benchmarks for methyl glucose derivatives are accelerating domestic production upgrades and creating premium-grade supply shortages that regional producers are racing to fill.
- Guangdong and Jiangsu province clusters:Matured domestic raw material supply chains for glucose-based oleochemicals are reducing import dependency and shortening lead times for personal care formulators.
- Mild surfactant systems:Southeast Asian personal care formulators are expanding procurement of methyl glucose esters as sulfate-free formulations displace harsher alternatives in premium skin and hair care.
Market Restraints
- Glucose feedstock volatility:Corn and wheat starch price fluctuations directly compress margins for methyl glucose ester manufacturers lacking captive agricultural sourcing.
- Guangzhou Tinci production dominance:Regional capacity concentration in a single integrated producer creates supply security vulnerabilities for buyers seeking dual-source qualification.
- China's SAMR food additive restrictions:GRAS-equivalent category limitations block methyl glucose derivative expansion into food industry applications, constraining addressable market width.
Strategic Opportunities
- India's BIS-ASEAN convergence:Harmonizing cosmetic safety guidelines are simplifying cross-border compliance for suppliers establishing multi-country distribution networks.
- Pharmaceutical-grade specifications:Drug formulators adopting excipient-grade methyl glucose for oral and topical delivery systems are deepening margin pools beyond personal care commoditization.
- Enzymatic esterification:Biotechnology convergence with traditional oleochemical processing is enabling carbon footprint reduction claims that command premium positioning in Japanese and South Korean markets.
Industry Challenges
- Dual certification timelines:Manufacturers serving both Japan's METI notification requirements and China's SAMR standards face extended product registration cycles that delay revenue recognition.
- Specialized formulation chemistry talent:Shortages of professionals versed in HLB optimization for methyl glucose esters in mild surfactant systems constrain new product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Methyl Glucose Market |
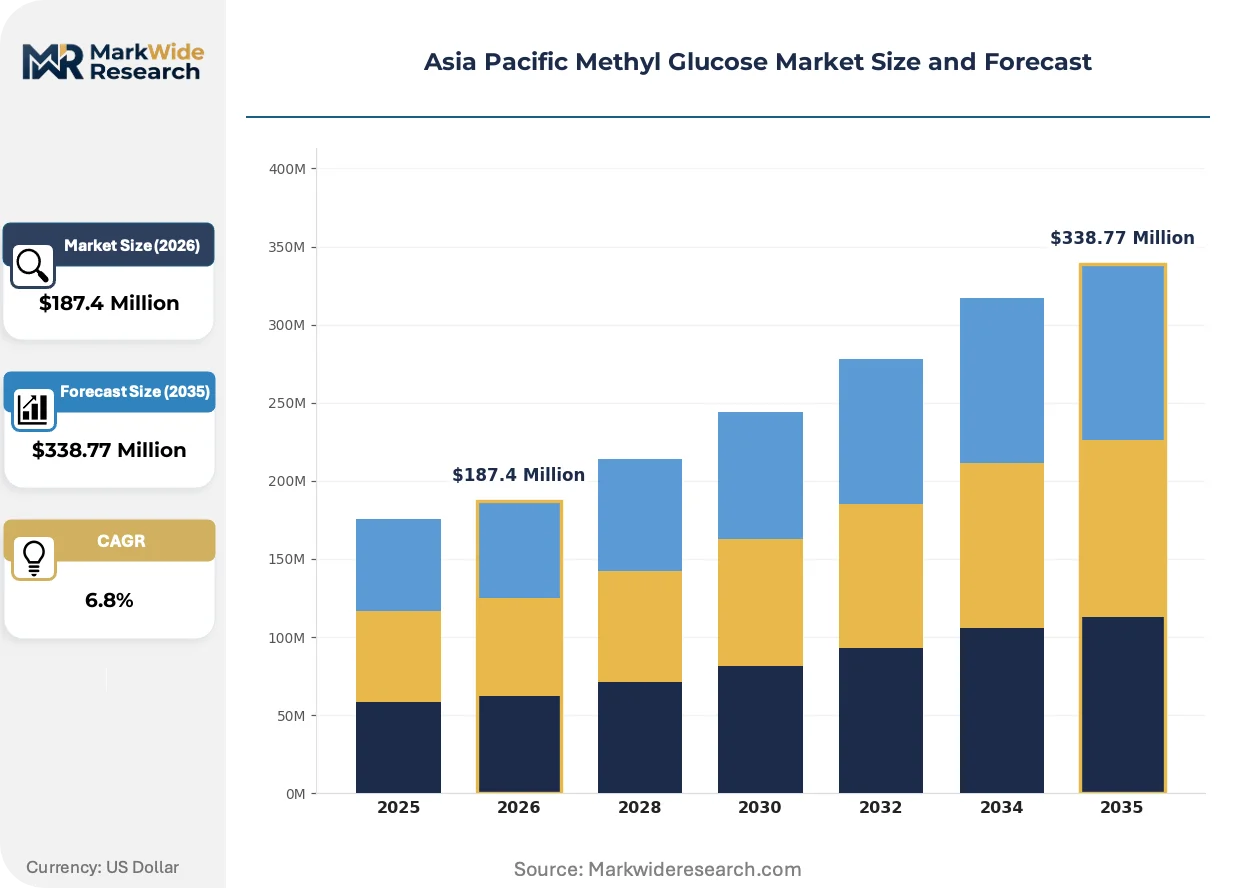
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Glucose Octanoate, Methyl Glucose Caprate, Methyl Glucose Sesquistearate, Methyl Glucose Laurate Application: Personal Care, Food Industry, Pharmaceutical Products, Agriculture End User: Cosmetic Manufacturers, Food Manufacturers, Drug Formulators, Agrochemical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | BASF SE, Evonik Industries AG, Guangzhou Tinci Materials Technology Co., Ltd., Foshan Hytop New Material Co., Kao Corporation, Croda International, Archer Daniels Midland Company, Cargill, Inc., Tokyo Chemical Industry Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Methyl Glucose Market Emerging Trajectories
Biotechnology integration with conventional oleochemical processing is redefining production economics and sustainability positioning for methyl glucose derivatives across the Asia Pacific region.
Enzymatic transesterification for methyl glucose sesquistearate production is converging with carbon accounting frameworks. Japanese cosmetic manufacturers are adopting these biocatalytic routes at pilot scale to secure Scope 3 emissions reductions. The technology is converging with premium pricing mechanisms as sustainability-linked procurement contracts displace conventional spot purchasing in Northeast Asian supply agreements.
Japan's Act on the Evaluation of Chemical Substances notification requirements are tightening import documentation thresholds for cosmetic-grade methyl glucose. Industrial consequence includes mandatory purity certification from accredited laboratories that adds three to six months to supplier qualification. Pharmaceutical-grade methyl glucose derivatives face the steepest compliance burden, with drug formulators accelerating domestic sourcing to circumvent documentation complexity.
Buyer concentration among consolidated multinational cosmetic manufacturers is compressing switching cycles and demanding multi-year supply security commitments. Regional distributors serving mid-tier formulators are being displaced by direct manufacturer relationships with volume guarantees. This pattern is most visible in China's Guangdong province, where domestic personal care OEMs are bypassing traditional chemical traders to secure backward-integrated supply from glucose feedstock producers.
Asia Pacific Methyl Glucose Market Segmentation
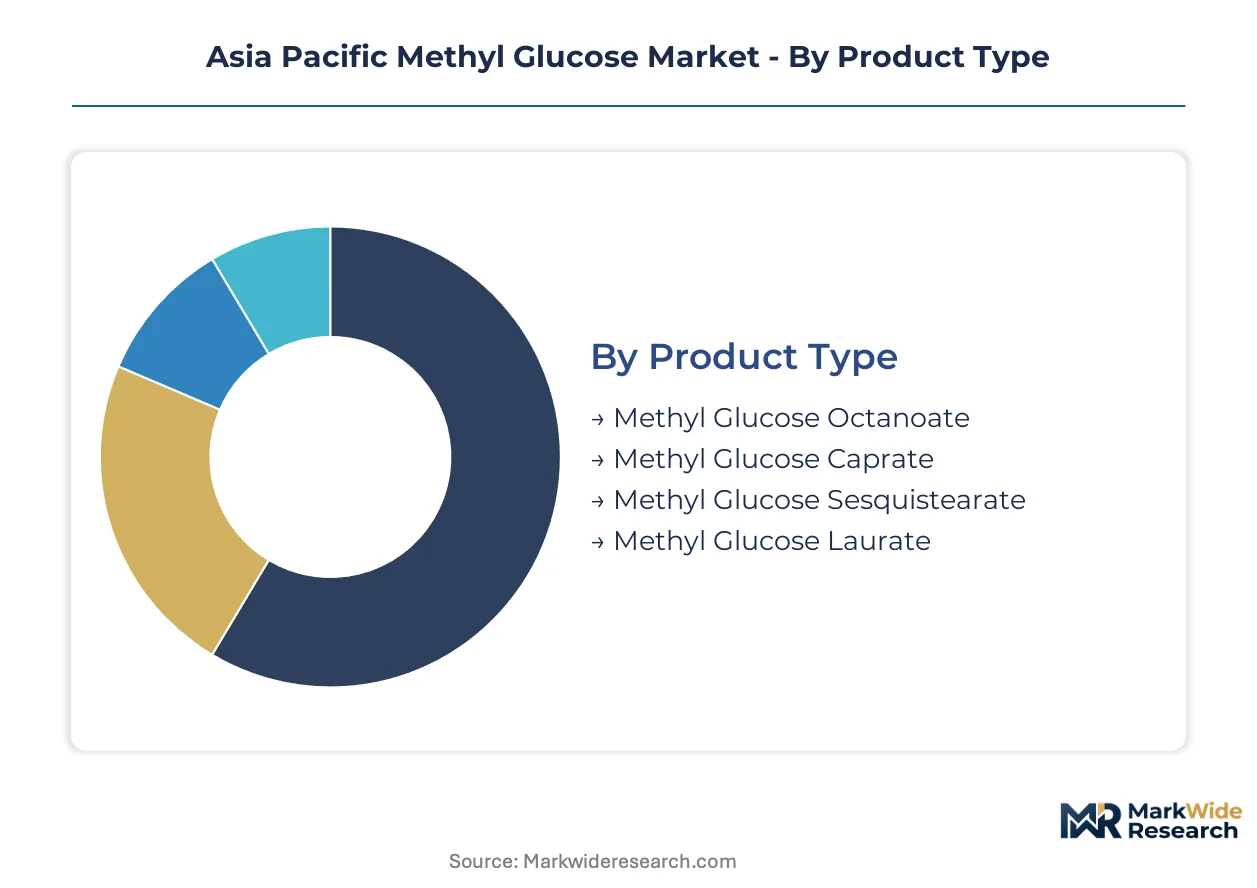
Segmentation in the Asia Pacific methyl glucose market reveals how functional chemistry requirements diverge across regulatory environments and end-use specifications. Manufacturers configure production lines around ester chain length and substitution patterns that determine HLB values and emulsification performance. Procurement patterns cluster around buyers with distinct purity thresholds, from pharmaceutical-grade excipients to cost-optimized personal care formulations.
Product Type:
Customization intensity spans from commodity esters with standardized fatty acid profiles to specialized variants requiring precise molecular architecture for premium applications.
- Methyl Glucose Sesquistearate:This C18-chain diester delivers HLB values around 6-8, positioning it as the workhorse emulsifier for rich skin creams and anhydrous formulations. Demand concentrates in Japan's Kansai region cosmetic OEMs, where METI purity certifications command premium positioning in anti-aging product lines.
- Methyl Glucose Caprate:Medium-chain C10 substitution yields water-dispersible esters with HLB 12-14, enabling clear shampoo and conditioning systems without sulfates. Procurement from Guangdong province formulators is accelerating as sulfate-free hair care displaces conventional surfactant systems across Southeast Asian markets.
- Methyl Glucose Octanoate:Short-chain C8 variant offers rapid skin penetration and light emolliency for sprayable formulations.
- Methyl Glucose Laurate:C12-chain ester balances solubility and substantivity, finding use in rinse-off applications where mildness claims differentiate mass-market positioning.
Leading the category by volume: Methyl Glucose Sesquistearate. Expanding most quickly: Methyl Glucose Caprate.
Application:
Margin architecture separates pharmaceutical-grade certification costs from personal care commoditization pressures, with regulatory burden determining addressable profit pools.
- Personal Care:Skin creams, hair conditioners, and color cosmetics utilize methyl glucose esters for mildness positioning and sensory modification. Formulators in China's Jiangsu province are standardizing on sesquistearate and caprate blends to achieve texture engineering without silicones.
- Pharmaceutical Products:Excipient-grade specifications for oral and topical drug delivery require documented impurity profiles and batch-to-batch consistency. Japan's PMDA notification requirements are concentrating demand among domestic API manufacturers seeking to circumvent import documentation complexity.
- Food Industry:China's SAMR restricts methyl glucose derivatives to specified GRAS-equivalent categories, blocking broad food emulsifier adoption despite technical suitability.
- Agriculture:Adjuvant applications for pesticide formulations leverage methyl glucose ester biodegradability in controlled-release systems.
Personal Care commands the dominant revenue position. Pharmaceutical Products deepens margin pools through certification barriers.
End User:
Buyer concentration dynamics concentrate procurement leverage among consolidated multinational cosmetic manufacturers while fragmenting agricultural demand across regional formulators.
- Cosmetic Manufacturers:Premium skin care and hair care brands in Japan and South Korea specify enzymatic-processed esters for carbon footprint claims. Direct supply relationships with glucose-integrated producers are displacing traditional chemical distribution in Guangdong province.
- Drug Formulators:Oral solid dosage and topical delivery system developers require excipient-grade documentation including residual solvent specifications and heavy metal testing.
- Food Manufacturers:Limited to SAMR-permitted additive categories, constraining formulation flexibility versus global food emulsifier alternatives.
- Agrochemical Companies:Biopesticide formulators in India leverage methyl glucose ester surfactancy for natural-positioned crop protection products.
Cosmetic Manufacturers anchor procurement volume. Drug Formulators generate steepest margin expansion through pharmaceutical-grade qualification.
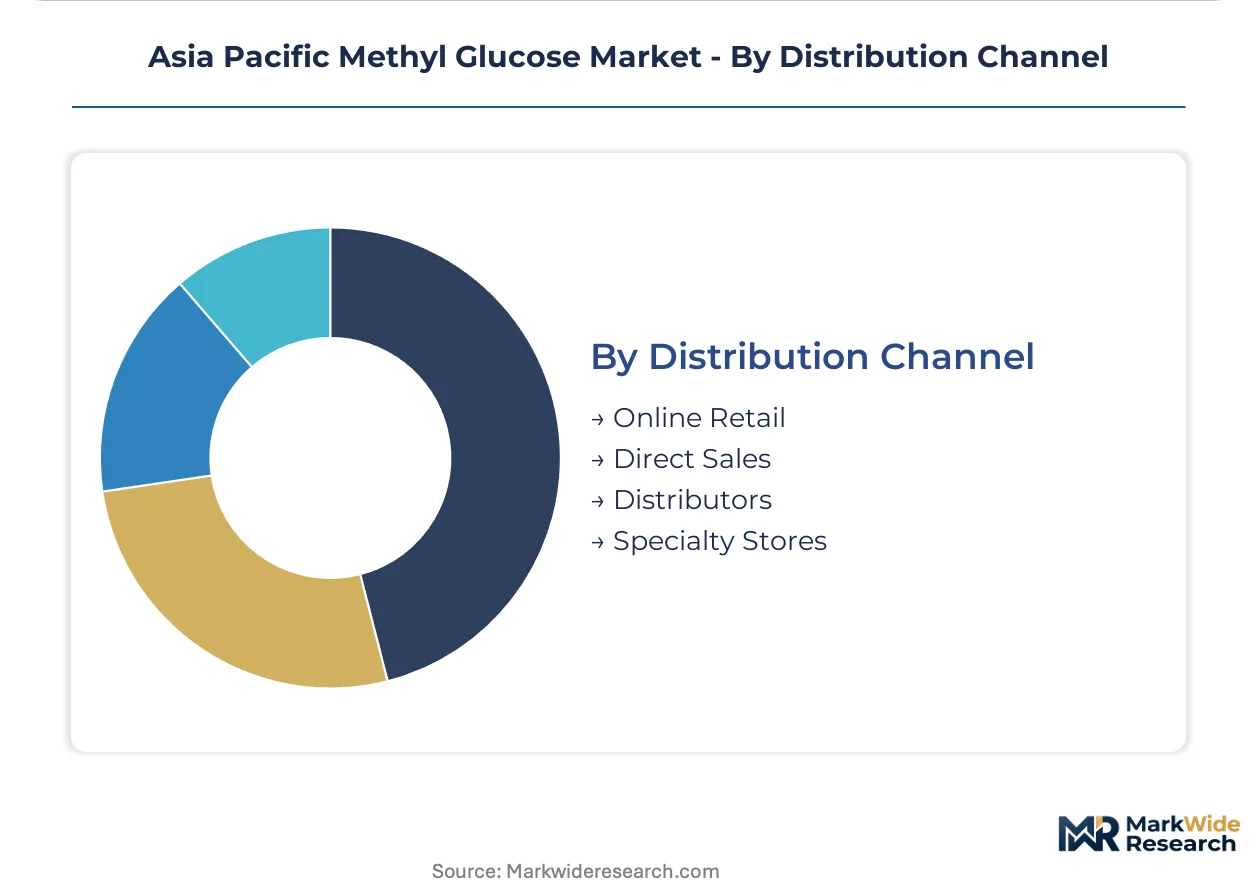
Distribution Channel:
Channel economics reflect the tension between technical specification complexity requiring direct manufacturer engagement and cost efficiency through consolidated procurement.
- Direct Sales:Volume-guaranteed multi-year contracts with multinational cosmetic manufacturers bypass distributor markups and enable supply security commitments. BASF SE and Kao Corporation anchor direct relationships across Northeast Asia.
- Distributors:Regional chemical traders serve mid-tier formulators lacking procurement scale for direct manufacturer qualification, though buyer consolidation is compressing this channel's relevance.
- Online Retail:E-procurement platforms facilitate spot purchasing for R&D sampling and small-batch formulation work.
- Specialty Stores:Cosmetic ingredient boutiques in Seoul and Tokyo serve independent formulators seeking niche ester variants.
Direct Sales captures the largest contract value. Distributors face structural compression from buyer consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Personal care formulators concentrate procurement leverage across four key Asia Pacific markets, each shaped by distinct regulatory postures and industrial clustering patterns. Japan's METI standards and China's SAMR frameworks create divergent compliance pathways that suppliers must navigate simultaneously.
China
Guangdong and Jiangsu provinces host matured glucose-based oleochemical supply chains that shorten lead times for domestic formulators. SAMR food additive restrictions block methyl glucose derivatives from broad food applications despite technical suitability. Guangzhou anchors regional production capacity through backward-integrated glucose feedstock sourcing.
Japan
Kansai region cosmetic OEMs specify METI-certified methyl glucose sesquistearate for premium anti-aging product lines. PMDA notification requirements for pharmaceutical-grade derivatives concentrate demand among domestic API manufacturers. METI's Act on the Evaluation of Chemical Substances extends supplier qualification timelines by three to six months.
South Korea
Seoul Capital Area cosmetic manufacturers adopt enzymatic-processed esters for carbon footprint claims in sustainability-linked procurement. MFDS cosmetic safety guidelines align with Japanese purity benchmarks while maintaining distinct documentation requirements. Busan-Ulsan chemical complexes support oleochemical conversion infrastructure for regional supply.
India
Maharashtra and Gujarat-based formulators leverage BIS cosmetic safety guidelines converging with ASEAN harmonization protocols. CDSCO pharmaceutical regulations create parallel certification tracks for excipient-grade methyl glucose targeting oral and topical drug delivery. Domestic agrochemical companies utilize methyl glucose ester surfactancy for biopesticide formulations.
Thailand
Bangkok-centered personal care manufacturers expand sulfate-free formulation procurement from Guangdong province suppliers. Thailand's FDA cosmetic registration requirements intermediate between Japanese stringency and Chinese domestic standards. Eastern Economic Corridor chemical parks attract methyl glucose ester distributors serving Southeast Asian mid-tier formulators.
Asia Pacific Methyl Glucose Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic processing and pharmaceutical-grade certification as differentiation vectors. The market structures around three archetypes: integrated glucose-to-ester producers commanding feedstock security, multinational chemical platforms leveraging regional distribution scale, and specialized cosmetic ingredient houses tailoring HLB specifications. Capacity expansion and strategic partnerships dominate competitive moves, with direct manufacturer relationships displacing traditional distributor channels.
Among Germany-based chemical platforms, BASF SE and Evonik Industries AG exemplify integrated oleochemicals positioning across Northeast Asia. Guangzhou Tinci Materials Technology Co., Ltd. occupies a dominant capacity position through captive glucose sourcing. Kao Corporation represents specialized-grade tailoring for Japanese cosmetic formulation requirements. These three anchors illustrate the tension between scale-driven supply security and customization-intensive premium positioning.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Guangzhou Tinci Materials Technology Co., Ltd. |
| Foshan Hytop New Material Co. |
| Kao Corporation |
| Croda International |
| Archer Daniels Midland Company |
| Cargill, Inc. |
| Tokyo Chemical Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Japan's METI Act on the Evaluation of Chemical Substances notification requirements gate both qualified supply and premium-tier pricing access, as three-to-six-month certification timelines concentrate pharmaceutical-grade methyl glucose sourcing among domestic API manufacturers willing to absorb documentation costs for margin protection.
Pricing Analysis
Volume concentrates in personal care commodity esters while margins deepen in pharmaceutical-grade certifications. Three-tier pricing structure across premium enzymatic-processed, standard cosmetic-grade, and economy industrial ester levels separates buyers by purity threshold and documentation burden. Cost compression in standard cosmetic grades is intensifying because Guangzhou Tinci's backward-integrated glucose sourcing enables aggressive spot pricing. Mid-tier formulators in Southeast Asia exhibit highest price sensitivity; Japanese cosmetic OEMs demonstrate lowest sensitivity due to METI compliance premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated multinational cosmetic manufacturers, displacing traditional chemical distributors across Guangdong province. Raw material supply draws from corn and wheat starch agricultural networks in China's Jiangsu and Hebei provinces, fatty acid feedstocks from Malaysia and Indonesia, and glucose refining infrastructure concentrated in Shandong. Single-source vulnerability permeates the regional market given Guangzhou Tinci's dominant capacity position. Distribution runs through manufacturer-direct contracts for volume buyers and residual distributor networks for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific methyl glucose market sits in a biotechnology-transition phase, as enzymatic esterification displaces conventional chemical transesterification for carbon footprint claims in Japanese and South Korean procurement.
For Market Incumbents: Deepen pharmaceutical-grade certification investments to capture excipient-grade margin pools as drug formulators accelerate domestic sourcing to circumvent METI import documentation complexity. Fortify supply security commitments through multi-year volume contracts with consolidated multinational cosmetic manufacturers, directly addressing the threat of buyer concentration compressing switching cycles. For New Entrants and Emerging Players: The price-point gap between premium enzymatic-processed esters and economy chemical-grade alternatives opens white-space targeting for mid-tier cosmetic formulators in Thailand and Vietnam seeking mild surfactant systems without full sustainability premiums. Penetrate India's Maharashtra-based agrochemical adjuvant segment where BIS-ASEAN convergence simplifies cross-border compliance. Pursue private-label supply partnerships with Guangdong province OEMs bypassing traditional chemical traders. For Investors and Strategic Acquirers: CDSCO pharmaceutical-grade approvals for Indian excipient manufacturers are the leading indicator that regional supply diversification will accelerate, reducing Japan-centric qualification bottlenecks. Position acquisition screening around enzymatic processing capability and dual METI-SAMR certification infrastructure. Monitor enzymatic transesterification pilot scale announcements from Kansai region cosmetic OEMs as the inflection signal for premium-tier pricing expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Scale-Up | Biocatalytic routes secure Scope 3 emissions reductions for Japanese sustainability-linked procurement contracts. |
| Backward Integration into Glucose Feedstock | Captive agricultural sourcing insulates margin compression from corn and wheat starch price volatility. |
| Dual Certification Infrastructure | Simultaneous METI and SAMR qualification expands addressable buyer base across Northeast Asian regulatory clusters. |
| Pharmaceutical-Grade Capacity Addition | Excipient-grade specifications deepen margin pools beyond personal care commoditization pressures. |
| Direct Manufacturer Relationships | Volume-guaranteed contracts displace distributor markups and secure supply security commitments from consolidated buyers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant managers at oleochemical conversion facilities, procurement leads at downstream cosmetic OEMs, technical R&D directors specializing in HLB optimization, and distribution channel partners serving Southeast Asian mid-tier formulators. Bottom-up volume modeling triangulated against top-down value estimates derived from SAMR food additive standard disclosures, METI chemical substance notification registries, and ASEAN harmonization protocol documentation.
Granularity-level modeling disaggregated projections across product type (sesquistearate, caprate, octanoate, laurate), application tier (personal care, pharmaceutical, food industry, agriculture), and end-user concentration (cosmetic manufacturers, drug formulators, agrochemical companies). CAGRs were synthesized from segment-level growth differentials and input cost trajectory assumptions. Forecast inputs incorporated enzymatic processing adoption curves, glucose feedstock price band sensitivity, and regulatory divergence cost impacts on cross-border trade flows.
Inputs from METI notification registries and CDSCO pharmaceutical filings were available through the study window; gaps in real-time enzymatic processing capacity utilization data introduce uncertainty bands around premium-tier supply elasticity assumptions. Forecasts reflect documented assumptions regarding biotechnology convergence timelines and buyer consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Inorganic Flame Retardants Market