
 Carnauba Wax Market | 2026-2036
Carnauba Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Carnauba Wax Market Analysis
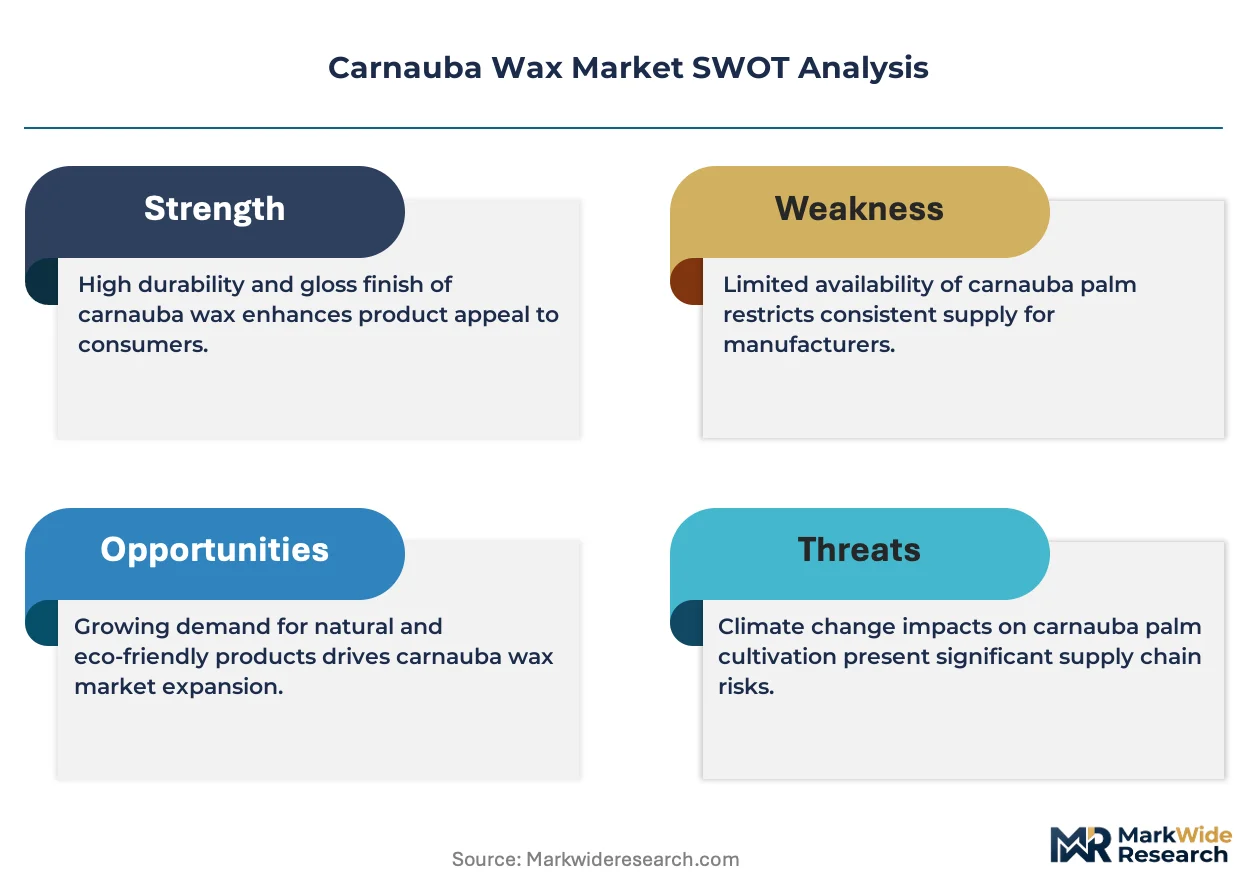
A capital-intensity divergence between integrated plantation operators and toll processors is rotating competitive advantage toward upstream asset control. Brasil Ceras leverages captive palm groves in Ceará to secure raw material continuity. Strahl & Pitsch, Inc. sustains North American market presence through refined product specialization and technical service capabilities.
Carnauba wax is a hard, high-melting-point vegetable wax obtained from the leaves of Copernicia prunifera palms, containing esters of long-chain fatty acids and alcohols with melting points between 78°C and 85°C. Its primary commercial purpose centers on surface finishing, protective coating, and viscosity modification across food, automotive, and personal care applications. Food Grade carnauba wax dominates volume flows through confectionery and fruit coating demand, while Cosmetics Grade commands premium positioning due to natural-origin certification requirements. Industrial Grade applications in automotive wax formulations represent a mature, price-sensitive segment where margin pools have compressed.
Brazil's national agricultural regulator oversees plantation licensing and export quality protocols, while REACH in Europe and FDA food additive regulations in the United States shape import specifications and end-use eligibility. ECHA classification reviews for natural wax derivatives influence formulation decisions by cosmetic manufacturers seeking hazard-free ingredient profiles. Stakeholders must monitor regulatory divergence between EU Green Deal sustainability criteria and emerging bio-based material standards in Asian import jurisdictions to anticipate compliance cost shifts.
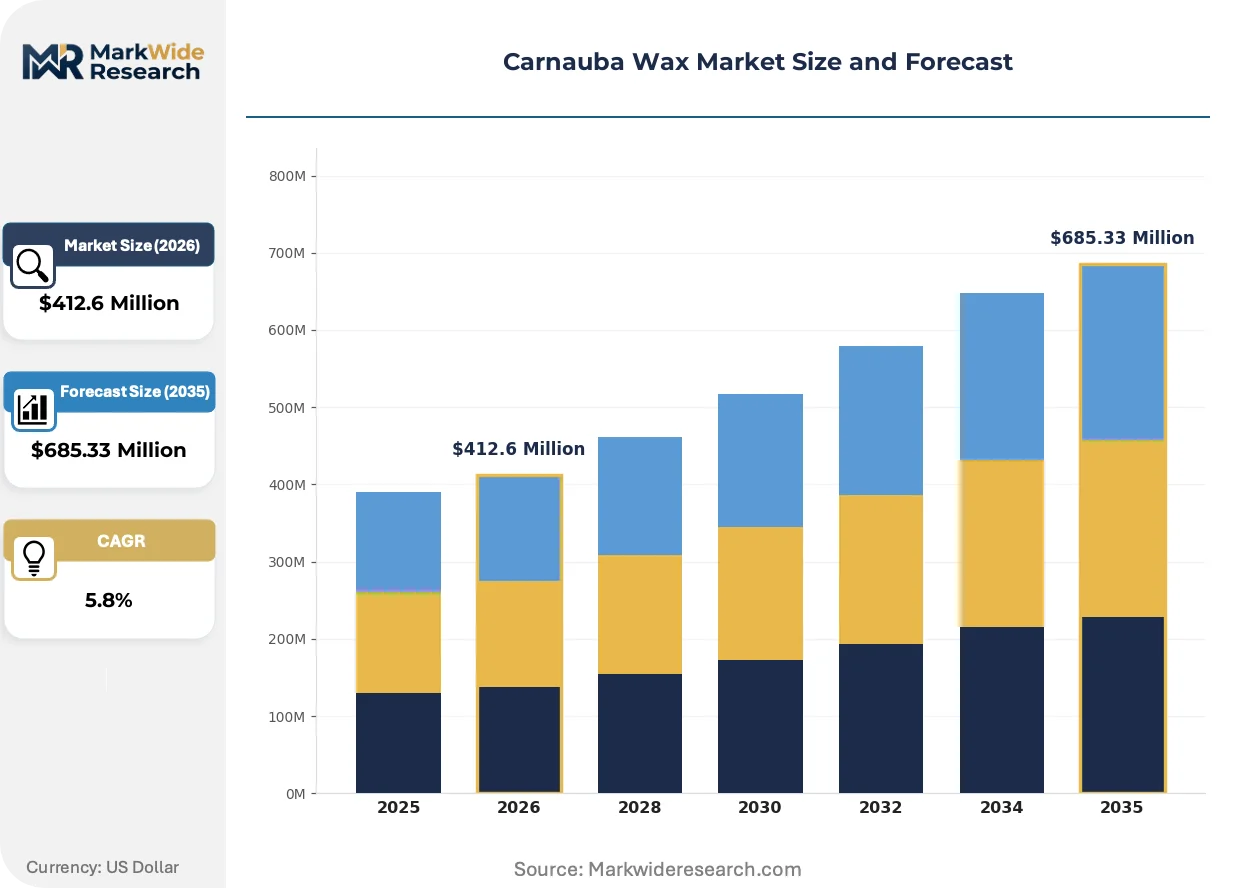
Market Dynamics
Raw material concentration within Brazil's Ceará and Piauí plantation belts is compressing supply security margins for downstream refiners, forcing asset-light processors to absorb yield volatility or surrender margin to integrated operators with captive grove access.
Growth Catalysts
- EU Green Deal sustainability criteria:Cosmetic formulators in France and Germany now mandate bio-based, hazard-free coating agents, elevating carnauba wax preference over petroleum-derived alternatives in premium personal care lines.
- Japan confectionery sector:Food manufacturers seek high-gloss, stable-melting coatings for summer distribution, driving specification of Food Grade carnauba wax with specific ester profiles above 80°C melting point.
- Natural ingredient substitution:South Korean skincare brands are displacing synthetic microcrystalline wax with Cosmetics Grade carnauba derivatives to secure clean-label positioning in export markets.
Market Restraints
- Input cost volatility:Brazilian drought cycles slash Copernicia prunifera leaf yields unpredictably, spiking raw wax prices and squeezing toll processors without long-term supply contracts.
- Supply concentration risk:Over 80% of global carnauba wax originates from Brazil's northeastern plantation belt, exposing buyers to single-country climate, labor, and currency shocks.
- Regulatory friction:REACH registration requirements for wax derivatives impose compliance costs that exclude small-scale Brazilian exporters from EU cosmetic supply chains.
Strategic Opportunities
- Underpenetrated South Korean market:Domestic cosmetic OEMs lack established carnauba wax supply relationships, creating first-mover advantage for refiners offering MFDS-compliant technical documentation.
- Automotive bio-based coatings:Water-based carnauba emulsions are displacing solvent-heavy synthetic waxes in vehicle surface protection, aligned with NHTSA and EPA volatile organic compound restrictions.
- Direct-to-formulator distribution:Bypassing traditional chemical distributors, integrated producers are building technical service relationships with mid-tier cosmetic compounders in France and Japan.
Industry Challenges
- Certification timeline compression:Food-grade and cosmetic-grade carnauba wax requires simultaneous FDA, EFSA, and ANVISA approvals, stretching quality assurance teams across divergent testing protocols.
- Refinery capex intensity:Achieving sub-5% moisture content and specified acid values demands solvent extraction and bleaching infrastructure that smaller plantation cooperatives cannot finance independently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carnauba Wax Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Cosmetics Grade, Industrial Grade, Pharmaceutical Grade Application: Food Coating, Automotive Wax, Cosmetics, Pharmaceutical End User: Food Manufacturers, Cosmetic Companies, Automotive Industry, Pharmaceutical Labs Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | FONCEPI Comercial Exportadora Ltda., Brasil Ceras, Carnauba do Brasil Ltda, Pontes Industria de Cera Ltda., Strahl & Pitsch, Inc., Kahl GmbH & Co. KG, Koster Keunen, TER INGREDIENTS GMBH & CO. KG, Norevo GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carnauba Wax Market Emerging Trajectories
Processing technology and regulatory classification are rewriting competitive boundaries between commodity wax traders and specialized refiners. Differentiation now hinges on certification depth and formulation support rather than volume throughput alone.
Supercritical CO2 extraction technology is bifurcating the refined carnauba wax market. This solvent-free process preserves ester integrity for high-end cosmetic applications. Premium skincare formulators in France and South Korea are adopting CO2-extracted grades at 15-20% price premiums over conventional solvent-refined material. The technology is bifurcating margin pools: commodity traders serving industrial automotive waxes face compression while integrated refiners with extraction assets capture cosmetic-grade premiums.
REACH Annex VI substance classification reviews are tightening hazard communication requirements for natural wax derivatives. ECHA's ongoing evaluation of respiratory sensitization potential is forcing cosmetic manufacturers to reformulate or secure expanded safety data packages. German and French personal care brands are accelerating supplier audits to preempt registration disruptions, favoring refiners with pre-submitted dossiers over spot-market sourcing.
Buyer specification consolidation is compressing supplier bases across food and cosmetic channels. Large confectionery manufacturers in Japan and Germany now mandate single-source carnauba wax with full traceability to plantation block, displacing multi-origin blending practices. Technical service capabilities—including customized melting point adjustment and emulsion stability testing—are becoming vendor selection criteria alongside price, rewarding refiners with in-house application laboratories.
Carnauba Wax Market Segmentation
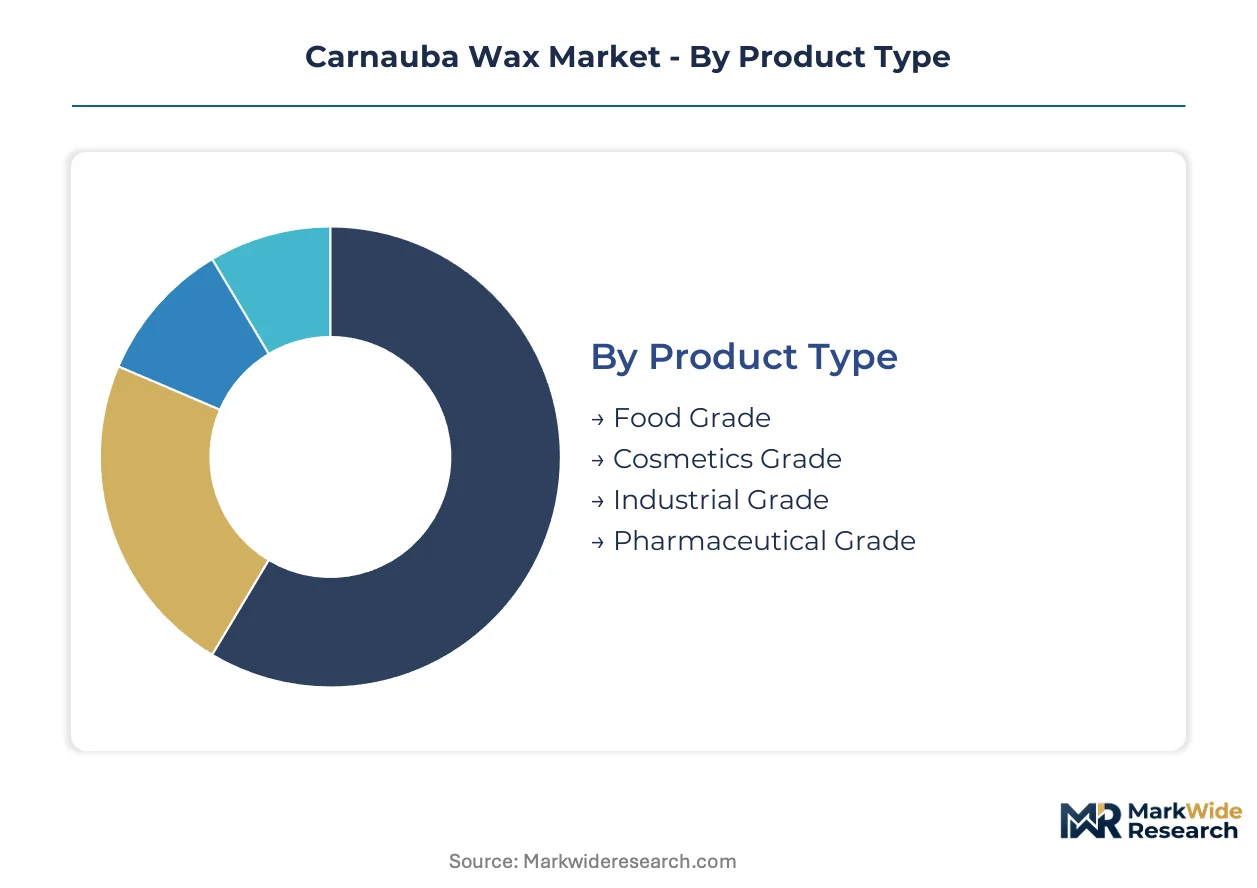
Segmentation in the carnauba wax market reflects divergent certification burdens and margin structures. Regulatory thresholds separate food-grade and pharmaceutical-grade specifications, while application-driven demand creates distinct procurement patterns across end-use industries.
Product Type:
REACH and FDA food additive regulations impose divergent purity thresholds across grades, fragmenting refinery investment requirements and compliance timelines.
- Food Grade:Carnauba wax for food coating applications meets FDA 21 CFR 184.1978 specifications for ester content and acid value. German and Japanese confectionery manufacturers drive specification of high-melting-point variants above 80°C for summer distribution stability. This grade handles the majority of throughput; Pharmaceutical Grade is climbing the fastest on share.
- Cosmetics Grade:Supercritical CO2 extraction preserves ester integrity for premium skincare formulations. South Korean clean-label brands and French personal care OEMs mandate ECHA-compliant hazard profiles with full traceability documentation.
- Industrial Grade:Automotive wax compounders in the United States specify this grade for water-based emulsion formulations aligned with EPA volatile organic compound restrictions.
- Pharmaceutical Grade:ANVISA and FDA joint inspections govern excipient certification for tablet coating and sustained-release applications.
Food Grade dominates volume flows through established confectionery supply chains; Cosmetics Grade captures the steepest expansion trajectory driven by natural-ingredient substitution in premium personal care.
Application:
End-use specifications determine wax refinement depth and pricing tiers, with cosmetic and pharmaceutical channels commanding premium positioning over industrial coatings.
- Food Coating:Fruit and confectionery surface finishing requires specific ester profiles and moisture content below 5%. Japanese food manufacturers specify single-source traceability to plantation block.
- Automotive Wax:Water-based carnauba emulsions displace solvent-heavy synthetic alternatives under NHTSA and EPA volatile organic compound phase-down schedules.
- Cosmetics:South Korean skincare brands displace synthetic microcrystalline wax with carnauba derivatives for clean-label export positioning. This segment concentrates demand for CO2-extracted grades at 15-20% premiums.
- Pharmaceutical:Tablet coating and controlled-release matrix applications require simultaneous FDA, EFSA, and ANVISA approvals, stretching quality assurance timelines.
Food Coating anchors baseline volume demand; Cosmetics is expanding most quickly as natural-origin certification requirements tighten across EU and Asian import jurisdictions.
End User:
Procurement sophistication varies sharply between multinational formulators with in-house laboratories and mid-tier compounders dependent on refiner technical support.
- Food Manufacturers:Large confectionery producers in Japan and Germany now mandate direct refiner relationships with customized melting point adjustment capabilities.
- Cosmetic Companies:French and South Korean OEMs accelerate supplier audits to preempt REACH registration disruptions, favoring refiners with pre-submitted dossiers.
- Automotive Industry:Vehicle surface protection formulators seek bio-based coating agents aligned with NHTSA sustainability criteria.
- Pharmaceutical Labs:Excipient buyers require expanded safety data packages as ECHA evaluates respiratory sensitization potential for natural wax derivatives.
Food Manufacturers represent the largest procurement volume; Cosmetic Companies are gaining share fastest on specification consolidation and clean-label momentum.
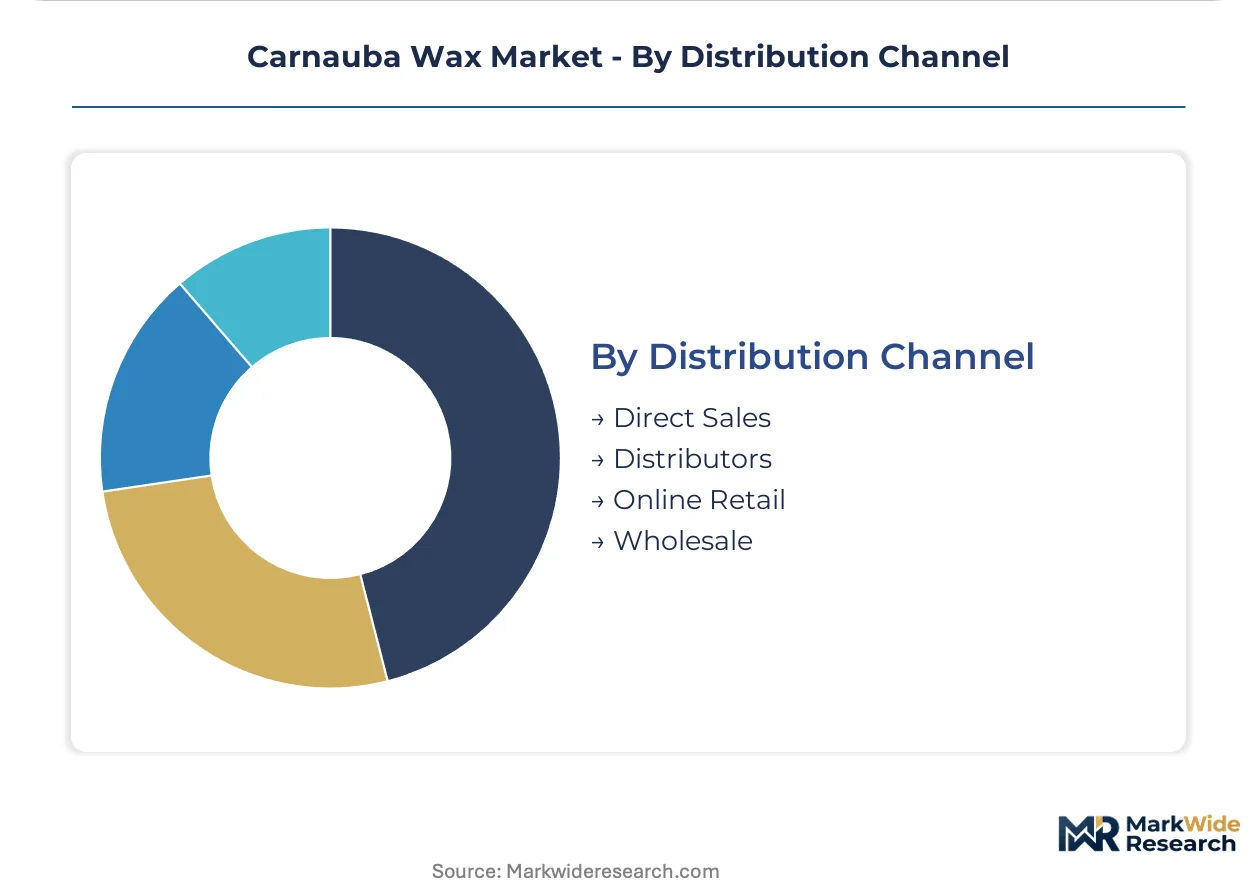
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with integrated producers bypassing traditional distributors to capture margin and relationship depth.
- Direct Sales:Integrated refiners with captive plantation access build technical service relationships with mid-tier cosmetic compounders in France and Japan.
- Distributors:Traditional chemical distributors serve smaller food manufacturers and automotive compounders lacking specification expertise.
- Online Retail:Specialty wax merchants target small-batch cosmetic formulators and artisan food producers with certified small-quantity packaging.
- Wholesale:Bulk traders handle industrial-grade volume flows to automotive wax manufacturers with mature, price-sensitive procurement practices.
Direct Sales channels are capturing share from distributors as buyers consolidate supplier bases and demand formulation support; Online Retail is expanding fastest on small-batch cosmetic and artisan food demand fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan favor high-specification food-grade coatings for confectionery, while South Korea and France drive cosmetic-grade demand for natural skincare formulations. Brazil remains the sole raw material source, concentrating supply risk in its northeastern plantation belt.
Brazil
ANVISA governs plantation licensing and export quality protocols for raw wax extraction. Ceará and Piauí plantation belts host the majority of Copernicia prunifera cultivation, with integrated operators controlling captive grove access to secure raw material continuity against drought-induced yield volatility.
Germany
Confectionery manufacturers specify REACH-compliant carnauba wax with customized melting point adjustment above 80°C for summer distribution stability. ECHA classification reviews for natural wax derivatives influence formulation decisions by cosmetic compounders seeking hazard-free ingredient profiles.
Japan
Food manufacturers seek high-gloss, stable-melting coatings for confectionery distributed during summer heatwaves. METI import standards align with FDA food additive regulations, driving specification of Food Grade carnauba wax with specific ester profiles and single-source traceability documentation.
France
EU Green Deal sustainability criteria elevate carnauba wax preference over petroleum-derived alternatives in premium personal care lines. Paris-based cosmetic OEMs accelerate supplier audits to preempt REACH registration disruptions, favoring refiners with pre-submitted dossiers.
South Korea
Seoul Capital Area skincare brands displace synthetic microcrystalline wax with Cosmetics Grade carnauba derivatives to secure clean-label positioning in export markets. MFDS-compliant technical documentation requirements create first-mover advantage for refiners establishing direct technical service relationships.
Carnauba Wax Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier of toll processors and regional distributors. Brasil Ceras exemplifies the upstream-integrated archetype through captive palm grove ownership, while Strahl & Pitsch, Inc. represents the refined-product specialization model. The competitive terrain rewards backward integration into plantation assets and technical service capabilities over volume throughput alone. Dominant moves include direct-to-formulator distribution bypass and supercritical CO2 extraction technology licensing.
Within the Brazilian integrated tier, FONCEPI Comercial Exportadora Ltda., Carnauba do Brasil Ltda, and Pontes Industria de Cera Ltda. exemplify plantation-origin supply control. Among European refiners, Kahl GmbH & Co. KG and Koster Keunen occupy positions emphasizing formulation support and certification depth. Strahl & Pitsch, Inc. anchors North American market presence through technical service capabilities rather than raw material ownership.
| Leading Market Players |
|---|
| FONCEPI Comercial Exportadora Ltda. |
| Brasil Ceras |
| Carnauba do Brasil Ltda |
| Pontes Industria de Cera Ltda. |
| Strahl & Pitsch, Inc. |
| Kahl GmbH & Co. KG |
| Koster Keunen |
| TER INGREDIENTS GMBH & CO. KG |
| Norevo GmbH |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between integrated Brazilian plantation operators and Japanese confectionery manufacturers lock in raw material continuity while capping price volatility exposure for buyers dependent on Food Grade carnauba wax with specified ester profiles above 80°C melting point.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume transactions, with spot markets serving only distressed buyers. Price differentiation separates CO2-extracted Cosmetics Grade from solvent-refined Industrial Grade based on certification depth and supercritical extraction asset access. Cost compression in Industrial Grade automotive waxes is intensifying because petroleum-derived synthetic alternatives compete on price. Automotive compounders show highest price sensitivity; South Korean skincare brands exhibit lowest sensitivity due to clean-label premium capture.
Supply Chain Analysis
Brazil and its Ceará-Piauí plantation belt anchor global carnauba wax extraction, with downstream refining capacity concentrated in Germany and the United States. Raw material supply draws from Copernicia prunifera leaf harvesting, solvent extraction infrastructure, and supercritical CO2 processing equipment. Single-source vulnerability runs through Brazil's drought-exposed northeastern growing regions. Distribution runs through direct technical service relationships for cosmetic and food formulators, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carnauba wax demand cycles track Brazilian rainfall patterns and EU cosmetic regulatory tightening, positioning the market for recovery as ECHA classification reviews accelerate natural-ingredient substitution.
For Market Incumbents: Consolidate captive grove access through lease arrangements or cooperative partnerships in Ceará and Piauí to defend against drought-induced yield volatility. Deepen supercritical CO2 extraction capacity to capture Cosmetics Grade premiums as South Korean and French formulators mandate ECHA-compliant hazard profiles. For New Entrants and Emerging Players: MFDS-compliant technical documentation fast-track offers entry into South Korea's underpenetrated cosmetic OEM supply base. Target direct-to-formulator distribution bypassing established chemical distributors, leveraging application laboratory capabilities to secure first-mover positioning with mid-tier compounders. For Investors and Strategic Acquirers: Integrated plantation-to-refinery operators with ANVISA licensing and REACH pre-submitted dossiers present durable acquisition targets. Monitor ECHA respiratory sensitization evaluation outcomes as inflection indicator for cosmetic-grade demand acceleration or formulation disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Secures raw material continuity against Brazilian drought cycles and currency shocks. |
| Supercritical CO2 Extraction Licensing | Captures 15-20% price premiums from French and South Korean cosmetic formulators. |
| Direct-to-Formulator Distribution Buildout | Bypasses margin-stripping chemical distributors for mid-tier cosmetic compounders in Japan. |
| REACH Pre-Submission Dossier Investment | Preempts ECHA registration disruptions for German and French personal care supply chains. |
| MFDS Technical Documentation Fast-Track | Unlocks first-mover positioning in South Korea's clean-label skincare export market. |
Methodological Framework
A spread of perspectives from plantation operations managers, refinery technical directors, cosmetic formulation chemists, and food industry procurement leads converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation through ANVISA export protocols, ECHA registration databases, FDA 21 CFR food additive specifications, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use applications.
Segmentation dimensions modeled include product grade tier, application channel, end-user procurement sophistication, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking regulatory impact assessments. Forecast inputs incorporated Brazilian agricultural yield variance, EU Green Deal sustainability criteria implementation timelines, and Asian import jurisdiction bio-based material standard developments.
Decision-makers should treat outputs as directional under stable Brazilian climate conditions and sustained EU regulatory tightening; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in ECHA classification reviews and ANVISA plantation licensing enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Prils Market