
 Cellulose Bioplastic Market | 2026-2036
Cellulose Bioplastic Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Bioplastic Market Intelligence
A shift from single-source pulp supply toward multi-source cellulose feedstock procurement is rebalancing raw-material security across the value chain. Solvay leverages its integrated acetylation capabilities to secure high-purity cellulose ester streams. Futamura Group anchors Asia-Pacific supply through its sustained investment in solvent-cast film capacity. Eastman competes on specialty cellulose derivatives for performance packaging where optical clarity and grease resistance command premium positioning.
Cellulose bioplastic denotes thermoplastic materials derived from regenerated or esterified cellulose, typically processed through solvent casting, extrusion, or injection molding at temperatures between 160°C and 220°C depending on the degree of substitution. These materials serve as drop-in replacements for conventional plastics in applications requiring biodegradability, barrier properties, or food-contact compliance. Films currently occupy the largest product-type position due to established converter infrastructure and brand-owner familiarity, while foam represents the fastest-growing category as cushioning and insulation applications migrate away from expanded polystyrene. Medical Devices within the application dimension attracts disproportionate margin pools because sterilization-grade cellulose materials must meet exacting purity and traceability standards that limit supplier eligibility.
The European Chemicals Agency enforces REACH registration for cellulose derivatives entering consumer applications, while the EU Green Deal's packaging-waste directives mandate minimum recycled and renewable content thresholds that directly expand addressable demand for certified bioplastics. In the United States, FDA food-contact notifications govern cellulose ester migration limits, creating a dual-compliance burden for exporters serving both jurisdictions. Stakeholders must monitor evolving compostability certification schemes and polymer-specific recycling infrastructure investments to align capacity commitments with end-of-life pathways that brand owners will enforce through procurement specifications.
Market Dynamics
EU Green Deal packaging mandates and REACH thresholds are compressing conventional plastic margins while redirecting converter capex toward cellulose ester compounding lines. This regulatory pressure is restructuring supply-chain relationships between pulp suppliers, acetylation specialists, and film converters.
Growth Catalysts
- EU Green Deal packaging-waste directives:Minimum renewable content thresholds force brand owners to certify bioplastic procurement, expanding addressable demand for cellulose films in food-contact applications.
- Solvent-cast film infrastructure:Dedicated production lines in Germany and Japan enable optical-grade cellulose output that meets premium barrier specifications for fresh-produce packaging.
- Expanded polystyrene displacement:Food-service operators facing municipal bans on petroleum-based foams are trialing cellulose cushioning for take-away containers and protective packaging.
Market Restraints
- Acetic anhydride price volatility:Cellulose acetate production absorbs swings in petrochemical-derived acetylation reagents that erode margin stability for mid-scale converters.
- Pulp supply concentration:Dissolving-grade cellulose availability clusters with Brazilian and Scandinavian forestry groups, creating geographic dependency for non-integrated compounders.
- Moisture sensitivity:Unmodified cellulose esters exhibit dimensional instability above 75% relative humidity, limiting deployment in tropical logistics corridors without secondary barrier coatings.
Strategic Opportunities
- Medical device sterilization-grade materials:Traceability-compliant cellulose derivatives command premium positioning in surgical packaging where ethylene oxide compatibility is mandatory.
- Compostability certification harmonization:Alignment between EN 13432 and ASTM D6400 standards would unlock cross-border procurement for multinational brand owners seeking unified specifications.
- Injection-molding grade compounds:Thermoplastic cellulose formulations with enhanced flow characteristics target durable goods previously reserved for petroleum-based engineering polymers.
Industry Challenges
- Acetylation process engineering talent:Scarcity of operators trained in solvent recovery and degree-of-substitution control constrains capacity expansion timelines for new market entrants.
- Dual-jurisdiction compliance burden:Exporters must simultaneously satisfy FDA food-contact notification migration limits and ECHA REACH registration dossier requirements, extending product launch cycles.
- Composting infrastructure misalignment:Industrial composting facility availability lags certified material supply in North American and Asian markets, creating end-of-life pathway uncertainty for brand-owner claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Bioplastic Market |
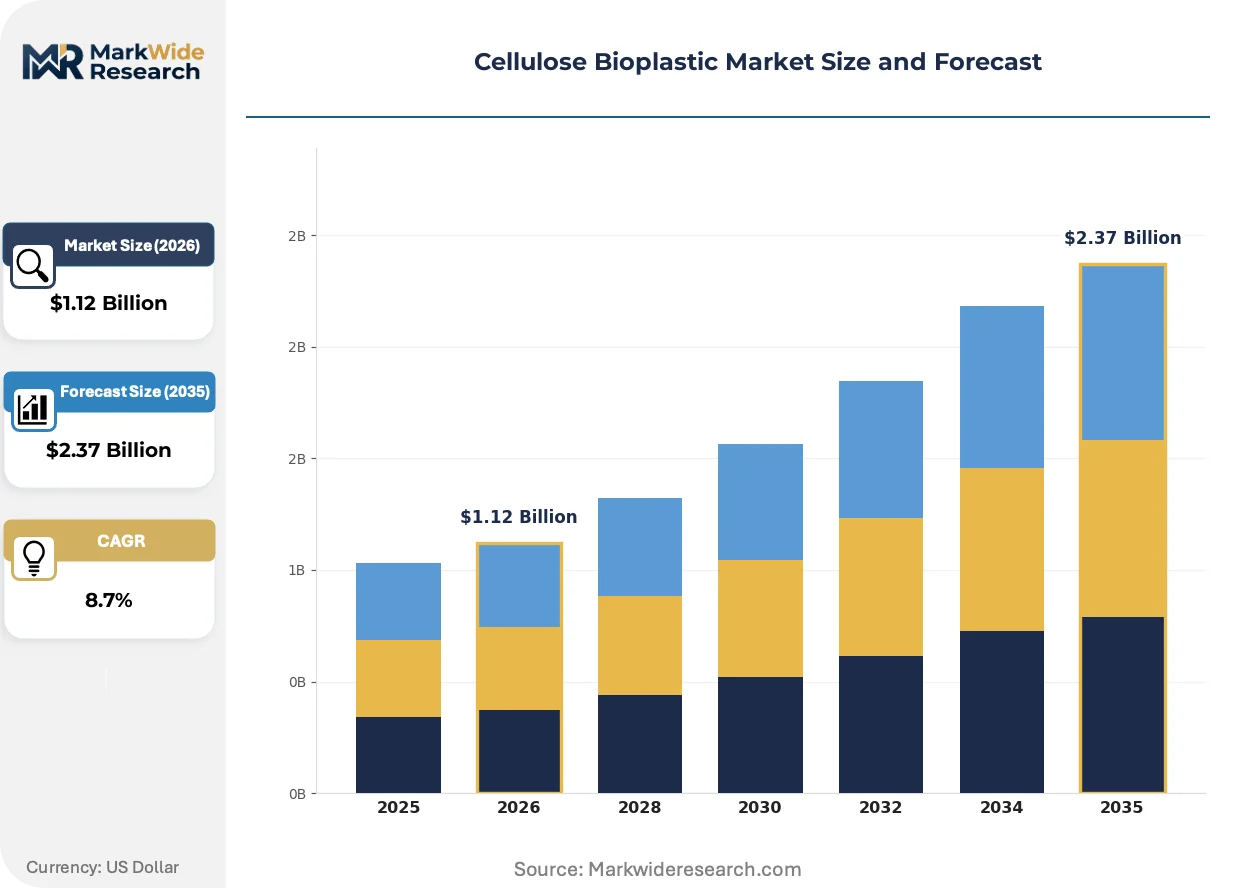
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.37 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Coatings, Packaging Materials, Foam Application: Food Packaging, Consumer Goods, Agriculture, Medical Devices End User: Food Industry, Healthcare Sector, Retail Sector, Agricultural Sector Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Solvay, Sappi, Eastman, Futamura Group, Mitsubishi Chemical, Celanese, Rayonier Advanced Materials, Biome Bioplastics, Daicel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Bioplastic Market Strategic Shifts & Innovations
Technology convergence between bio-based feedstock processing and precision acetylation is redefining performance benchmarks for cellulose materials. Regulatory sequencing across major economies is accelerating certification investments. Procurement specifications are tightening around traceability and end-of-life verification.
Regenerated cellulose films with tailored oxygen transmission rates are absorbing share from multilayer petroleum-based laminates in fresh-protein packaging. Major European retailers are specifying these materials for private-label meat and fish lines. The technology is absorbing capital that previously targeted conventional barrier film upgrades, compressing incumbent converter expansion plans.
REACH registration requirements for cellulose derivatives entering consumer applications are tightening purity documentation obligations. ECHA enforcement is pushing suppliers toward dedicated pharmaceutical-grade production lines to avoid cross-contamination risks. Medical device packaging and food-contact films are most affected, with German converters investing in segregated solvent-cast capacity to maintain dual-market eligibility.
Brand-owner procurement teams are consolidating supplier panels around certified compostability credentials rather than biodegradability claims alone. Food-service distributors are replacing spot-market purchasing with multi-year offtake agreements tied to specific facility certifications. This pattern is most visible in German and French supply chains, where retail consolidation gives buying groups leverage to enforce specification compliance through contract terms.
Cellulose Bioplastic Market Segmentation
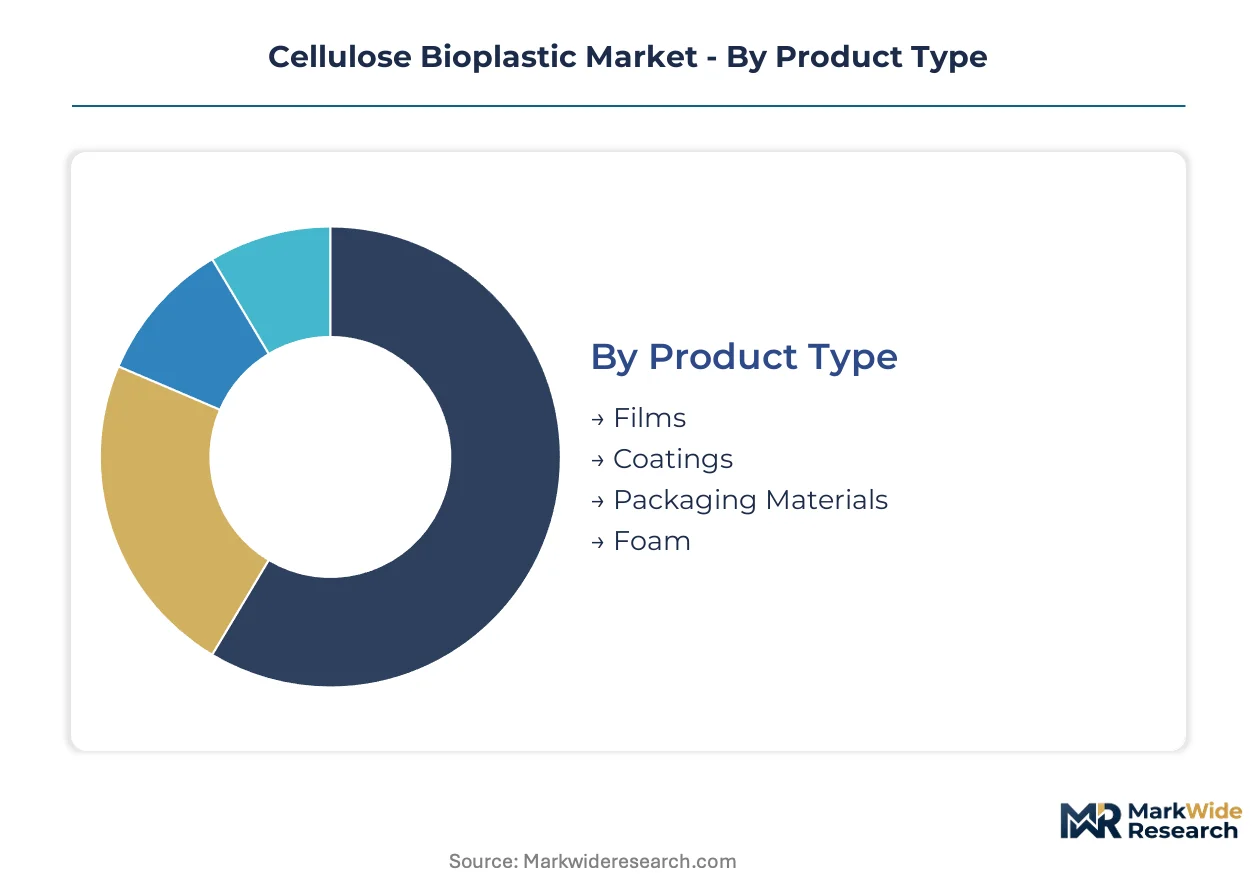
Cellulose bioplastic procurement specifications vary sharply across end-use contexts, with regulatory thresholds and performance requirements dictating material grade selection. Brand owners segment supplier panels by certification tier rather than commodity pricing, compressing interchangeability between segments.
Product Type:
Converter capex cycles favor equipment upgrades that handle multiple cellulose formats, with film lines retrofitting fastest due to established solvent-cast infrastructure.
- Films:Solvent-cast regenerated cellulose achieves optical clarity below 2% haze and oxygen transmission rates tailored for fresh-protein packaging. German retailers specify these films for private-label meat and fish lines, redirecting capital from multilayer petroleum-based laminate upgrades.
- Foam:Expanded cellulose cushioning targets take-away container insulation and protective packaging as municipal bans on expanded polystyrene proliferate across European food-service corridors. Trials are concentrating in France and Germany.
- Coatings:Secondary barrier layers address moisture sensitivity in tropical logistics, applied over base cellulose films to extend deployment range.
- Packaging Materials:Injection-molding and thermoforming grades serve rigid containers and trays, requiring modified flow characteristics for high-speed converter lines.
Films sit at the top of the volume ranking, with foam climbing the fastest as displacement of petroleum-based cushioning accelerates.
Application:
Margin pools diverge sharply by sterilization and traceability requirements, with medical and food-contact applications commanding specification premiums over industrial uses.
- Medical Devices:Ethylene oxide-compatible cellulose derivatives for surgical packaging require pharmaceutical-grade production lines and batch-level traceability. ECHA enforcement pushes suppliers toward segregated solvent-cast capacity to maintain dual-market eligibility.
- Food Packaging:Fresh-produce and protein applications drive demand for tailored oxygen transmission rates, with major brands phasing out petroleum-based films under EU Green Deal mandates. German converters are building dedicated cellulose compounding capacity to serve this procurement.
- Consumer Goods:Durable goods and electronics packaging utilize thermoplastic cellulose for rigid applications, competing with petroleum-based engineering polymers on flow characteristics.
- Agriculture:Mulch films and controlled-release applications exploit biodegradability in soil-contact contexts, though moisture sensitivity constrains deployment in high-humidity growing regions.
Food packaging holds the largest revenue position, while medical devices deliver the steepest margin expansion trajectory due to limited supplier eligibility.
End User:
Procurement consolidation patterns concentrate buying power differently across sectors, with retail and food-service distributors replacing spot-market purchasing with multi-year offtake agreements tied to certification compliance.
- Food Industry:Brand-owner procurement teams enforce compostability certification through contract terms, consolidating supplier panels around EN 13432 and ASTM D6400 credentials. French and German retail consolidation amplifies this leverage.
- Healthcare Sector:Sterilization-grade material requirements limit eligible suppliers to those with pharmaceutical-grade production segregation and REACH registration dossiers for cellulose derivatives.
- Retail Sector:Private-label specifications for fresh-protein packaging drive solvent-cast film demand, with specifications tightening around optical clarity and grease resistance.
- Agricultural Sector:Soil-biodegradable mulch film adoption varies by regional composting infrastructure availability, creating end-of-life pathway uncertainty for claims.
The food industry commands the dominant procurement volume, with healthcare expanding most quickly as sterilization-grade requirements proliferate.
Distribution Channel:
Channel selection reflects order scale and specification complexity, with certified materials favoring direct relationships over spot-market intermediation.
- Direct Sales:Large-volume converters and brand owners negotiate multi-year offtake agreements with cellulose ester compounders, embedding certification requirements into contract terms. German supply chains exhibit this pattern most visibly.
- Wholesale:Regional distributors stock standard-grade films and compounds for mid-scale converters lacking direct supplier relationships, carrying inventory risk on commodity specifications.
- Specialty Stores:Technical-grade cellulose derivatives for research and pilot-scale production reach smaller compounders through specialized chemical distributors with formulation support capabilities.
- Online Retail:Sample quantities and small-batch specialty grades move through digital channels, serving prototyping and niche application development.
Direct sales channels capture the largest transaction value, with wholesale maintaining the broadest geographic coverage for standard-grade materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters are building dedicated cellulose compounding capacity to serve branded-goods manufacturers phasing out petroleum-based films under EU mandates.
Germany
Food packaging demand from major retailers drives solvent-cast film investments. REACH registration requirements for cellulose derivatives entering consumer applications tighten purity documentation obligations. Frankfurt-Rhine-Main and Hamburg harbor zones concentrate acetylation and film conversion facilities serving pan-European supply chains.
United States
Medical device sterilization-grade materials attract premium positioning as ethylene oxide compatibility requirements proliferate. FDA food-contact notifications govern cellulose ester migration limits, creating compliance burdens for exporters. The Gulf Coast corridor hosts dissolving-grade pulp import terminals and compounding operations.
Japan
Solvent-cast film infrastructure enables optical-grade cellulose output for premium barrier specifications. METI guidelines on sustainable materials procurement accelerate brand-owner certification requirements. The Nagoya-Osaka industrial belt anchors Asia-Pacific supply through sustained investment in film capacity.
France
Food-service operators facing municipal bans on petroleum-based foams trial cellulose cushioning for take-away containers. EU Green Deal packaging-waste directives mandate minimum renewable content thresholds. The Lyon-Grenoble corridor concentrates research activity on modified cellulose esters for tropical logistics applications.
Brazil
Dissolving-grade cellulose availability clusters with forestry groups supplying global compounders. ANVISA pharmaceutical-grade standards limit supplier eligibility for medical packaging exports. São Paulo state hosts pulp processing and regional distribution hubs serving Latin American converters.
Cellulose Bioplastic Market Key Industry Players
Global majors compete with regional champions across acetylation capabilities and solvent-cast film infrastructure. The vendor base spans integrated chemical conglomerates, specialized cellulose derivative producers, and forestry-integrated material suppliers. Three archetypes dominate: pulp-integrated compounders controlling upstream dissolving-grade supply, acetylation specialists leveraging process chemistry expertise, and film converters building dedicated cellulose handling lines. Capacity expansion and certification investments constitute the dominant competitive moves as stakeholders align with EU Green Deal procurement specifications.
Within the integrated chemical tier, Solvay and Eastman exemplify acetylation-forward positioning, while Futamura Group anchors Asia-Pacific supply through sustained solvent-cast infrastructure. These three occupy distinct geographic and capability positions that shape competitive dynamics across premium film and specialty derivative segments.
| Leading Market Players |
|---|
| Solvay |
| Sappi |
| Eastman |
| Futamura Group |
| Mitsubishi Chemical |
| Celanese |
| Rayonier Advanced Materials |
| Biome Bioplastics |
| Daicel |
| Others |
Cost & Logistics Intelligence
EU Green Deal packaging mandates gate both qualified supply and premium-tier pricing access, restricting compounder eligibility to those with segregated pharmaceutical-grade production lines and REACH registration dossiers while concentrating procurement leverage among German and French retail buying groups.
Pricing Analysis
Acetic anhydride cost pass-through dominates cellulose acetate pricing, with petrochemical-derived acetylation reagent volatility compressing margin stability for mid-scale converters. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-grade certification levels separates medical device sterilization materials commanding specification premiums from commodity film grades facing spot-market pressure. Cost compression in standard-grade films is intensifying because Brazilian and Scandinavian pulp supply concentration amplifies raw-material bargaining power for integrated compounders. Food-service distributors exhibit highest price sensitivity due to municipal foam-ban compliance deadlines, while medical packaging buyers prioritize traceability over unit economics.
Supply Chain Analysis
Workforce availability constraints in German and Japanese solvent-cast film corridors limit capacity expansion timelines, with acetylation process engineering talent scarcity extending commissioning schedules for new market entrants. Supply concentrates in Germany, Japan, and Brazil—Frankfurt-Rhine-Main and Hamburg harbor zones host acetylation clusters, Nagoya-Osaka anchors Asia-Pacific film output, and São Paulo state processes dissolving-grade pulp for Latin American converters. Raw material dependencies center on Brazilian and Scandinavian dissolving-grade cellulose, petrochemical-derived acetic anhydride, and solvent recovery systems. Single-source vulnerability in pulp supply creates geographic dependency for non-integrated compounders. Distribution runs through direct multi-year offtake agreements for certified materials, with wholesale channels covering standard-grade spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU REACH registration costs and pharmaceutical-grade production segregation requirements in Germany create compliance barriers that Asian compounders can undercut through export-focused certification strategies.
For Market Incumbents: Anchor solvent-cast film capacity in Germany and Japan to defend against emerging Asia-Pacific compounders targeting premium barrier specifications. Secure captive dissolving-grade pulp supply through backward integration into Brazilian forestry assets or long-term offtake agreements with Scandinavian suppliers. Invest in segregated pharmaceutical-grade production lines to maintain dual-market eligibility for medical device and food-contact applications under tightening ECHA enforcement. For New Entrants and Emerging Players: Capture expanded polystyrene displacement opportunities in French and German food-service cushioning as municipal bans proliferate. Target medical device sterilization-grade materials where traceability requirements limit eligible suppliers and command premium positioning. Pursue compostability certification harmonization between EN 13432 and ASTM D6400 as a go-to-market wedge for multinational brand-owner procurement panels. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale acetylation specialists because certification concentration and REACH registration barriers prevent organic new entrant proliferation at scale. Focus acquisition screening on compounders with existing pharmaceutical-grade production segregation and established brand-owner offtake relationships. Watch industrial composting facility buildout rates in North American and Asian markets as the signal for end-of-life pathway viability and brand-owner claim durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive dissolving-grade cellulose from Brazilian forestry groups insulates compounders from geographic supply concentration. |
| Pharmaceutical-Grade Production Segregation | Dedicated solvent-cast lines satisfy ECHA REACH purity documentation for dual medical and food-contact market eligibility. |
| Compostability Certification Investment | EN 13432 and ASTM D6400 credentials unlock multi-year offtake agreements with consolidated French and German retail buying groups. |
| Acetylation Process Engineering Training | Operator development in solvent recovery and degree-of-substitution control accelerates capacity expansion timelines for new market entrants. |
| Long-Term Brand-Owner Offtake Agreements | Contractual certification requirements embed specification compliance into procurement terms ahead of spot-market intermediation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cellulose ester compounders, film converter plant managers, brand-owner procurement leads, and ECHA regulatory affairs specialists with secondary validation from customs trade data, Cefic chemical industry reports, SEC 10-K filings, and FDA food-contact notification databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers across the analysis window.
Comparable-period anchoring tied projection assumptions to historical cellulose derivative production volumes, trade flows, and certification adoption patterns across the modeling period. Segmentation dimensions included product type, application context, end-user industry, and geographic production hub. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal mandate sequencing, pulp supply availability, and composting infrastructure deployment rates.
Acetic anhydride price volatility, pulp supply disruption, and composting facility availability lag are the dominant revision risks to forecast assumptions. Regulatory enforcement intensity at ECHA and FDA, plus brand-owner procurement specification tightening, present additional forecast sensitivity vectors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biopolymer Films Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
US Bioplastics Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
North America Bioplastics Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Bio-Based Polyolefins Market