
 North America Polylactic Acid (PLA) Market | 2026-2036
North America Polylactic Acid (PLA) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polylactic Acid (PLA) Market Analytics
Petroleum-based polypropylene in food packaging is pivoting toward PLA as landfill fees and extended producer responsibility laws alter total cost of ownership. NatureWorks LLC leverages its Blair, Nebraska fermentation complex to anchor domestic supply. TotalEnergies Corbion competes through specialty-grade lactide purification that sustains medical and food-contact certifications.
Polylactic acid is an aliphatic polyester synthesized from fermented plant starch, typically corn or sugarcane, with a glass transition temperature near 60°C and melt processing range of 170–180°C; it serves as a drop-in thermoplastic for injection molding, extrusion, and additive manufacturing where end-of-life compostability carries regulatory or brand value. Film and sheet formats dominate packaging volumes, while 3D printing filament commands premium pricing due to diameter tolerance requirements and spool-to-spool consistency demands. Injection molded grades retain the broadest application footprint across consumer goods and automotive interior trim.
The EPA bio-preferred program and state-level plastic bans in California, New York, and Washington shape procurement mandates and retail shelf access. ASTM D6400 and BPI certification operate as de facto gatekeepers for industrial composting claims, filtering out uncertified imports. Stakeholders must monitor feedstock cost volatility against fossil resin parity and track composting infrastructure buildout in Texas and Florida municipalities.
Market Dynamics
State-level single-use plastic bans and landfill fee escalations are compressing the cost gap between petroleum-based packaging and bio-based alternatives, forcing rapid material substitution across food service and retail shelf applications.
Growth Catalysts
- EPA Bio-Preferred Procurement:Federal purchasing mandates now require compostable food service items in government cafeterias and national park concessions, creating guaranteed offtake volumes for domestic PLA producers.
- Extended Producer Responsibility Laws:California, New York, and Washington impose packaging waste fees that internalize end-of-life costs, making compostable alternatives economically competitive at shelf.
- Midwest Feedstock Proximity:Corn starch supply and fermentation infrastructure cluster within 200 miles of Blair, Nebraska, cutting logistics costs for domestic lactide production.
Market Restraints
- Corn Price Volatility:Drought cycles in Iowa and Illinois spike feedstock costs unpredictably, eroding margin stability for fermentation-based polymer producers.
- Industrial Composting Infrastructure Gaps:Texas and Florida municipalities lack ASTM D6400-certified composting facilities, forcing PLA waste into landfills where anaerobic decomposition produces methane.
- Technical Performance Ceiling:PLA's 60°C glass transition temperature limits hot-fill and microwave applications, capping penetration in ready-meal packaging against heat-stable polypropylene.
Strategic Opportunities
- Southeast US Composting Buildout:Florida and Georgia municipalities are piloting curbside organics collection with PLA acceptance, creating first-mover positioning for certified suppliers.
- 3D Printing Filament Premiumization:Diameter tolerance demands and spool-to-spool consistency requirements command pricing multiples over commodity resin grades.
- Medical Device Packaging Convergence:TotalEnergies Corbion's lactide purification capabilities unlock sterilizable tray and blister pack applications with FDA food-contact and USP Class VI certifications.
Industry Challenges
- ASTM D6400 Certification Timelines:BPI and CMA testing protocols require 6-12 month validation cycles, delaying product launches and locking out uncertified imports.
- Blown Film Processing Expertise Scarcity:PLA's narrow melt processing window demands precise temperature control that legacy polyethylene operators struggle to master.
- Legacy PET Recycling Stream Contamination:PLA look-alike cups disrupt optical sorting at MRFs, triggering facility bans and brand withdrawal risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polylactic Acid (PLA) Market |
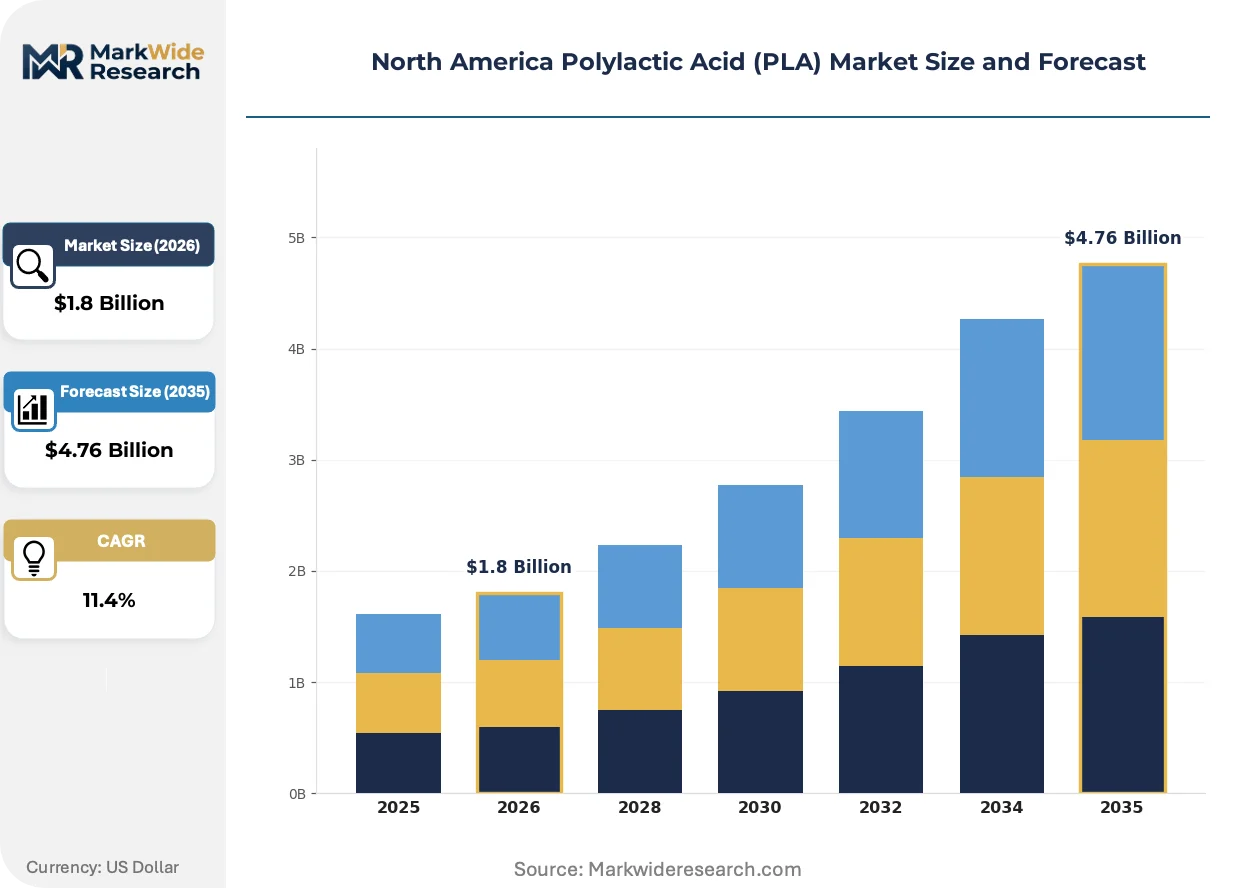
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molded, Blow Molded, Film & Sheet, 3D Printing Application: Packaging, Consumer Goods, Textile, Automotive End User: Food & Beverage, Healthcare, Agriculture, Electronics Distribution Channel: Direct Sales, E-commerce, Distributors, Retail |
| Companies Covered | NatureWorks LLC, TotalEnergies Corbion, BASF Corporation, Danimer Scientific, Evonik Corporation, DuPont de Nemours, Inc., Mitsubishi Chemical America, Inc., Dow Chemicals, Futerro, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polylactic Acid (PLA) Market Evolving Landscape
Continuous lactide purification and reactive extrusion advances are compressing conversion costs while regulatory pressure on fossil-based packaging intensifies specification demand across food service and medical sectors.
Continuous reactive extrusion with in-line molecular weight control is automating grade transitions between packaging film and injection molding resins. Compounders serving the food service sector adopt these systems to reduce batch-to-batch variability and cut changeover downtime. The technology is automating what previously required manual reactor adjustments, enabling smaller lot sizes for specialty medical grades.
California's SB 54 mandates 30% recycled or compostable content in single-use packaging by 2032, with interim targets beginning 2025. The law forces CPG brands to secure certified compostable supply chains or face shelf access restrictions. Food service disposables and fresh produce packaging face the steepest compliance curves, driving dual-sourcing strategies that split volumes between mechanical recycling and bio-based alternatives.
Brand sustainability teams now specify ASTM D6400 or BPI certification as a hard gate for supplier qualification, displacing self-declared compostability claims. Food service distributors and contract packaging operators respond by consolidating purchase orders with certified domestic mills, cutting uncertified Asian imports from approved vendor lists. This specification tightening concentrates most visible in California and Washington state procurement, where public disclosure requirements expose non-compliant sourcing.
North America Polylactic Acid (PLA) Market Segmentation
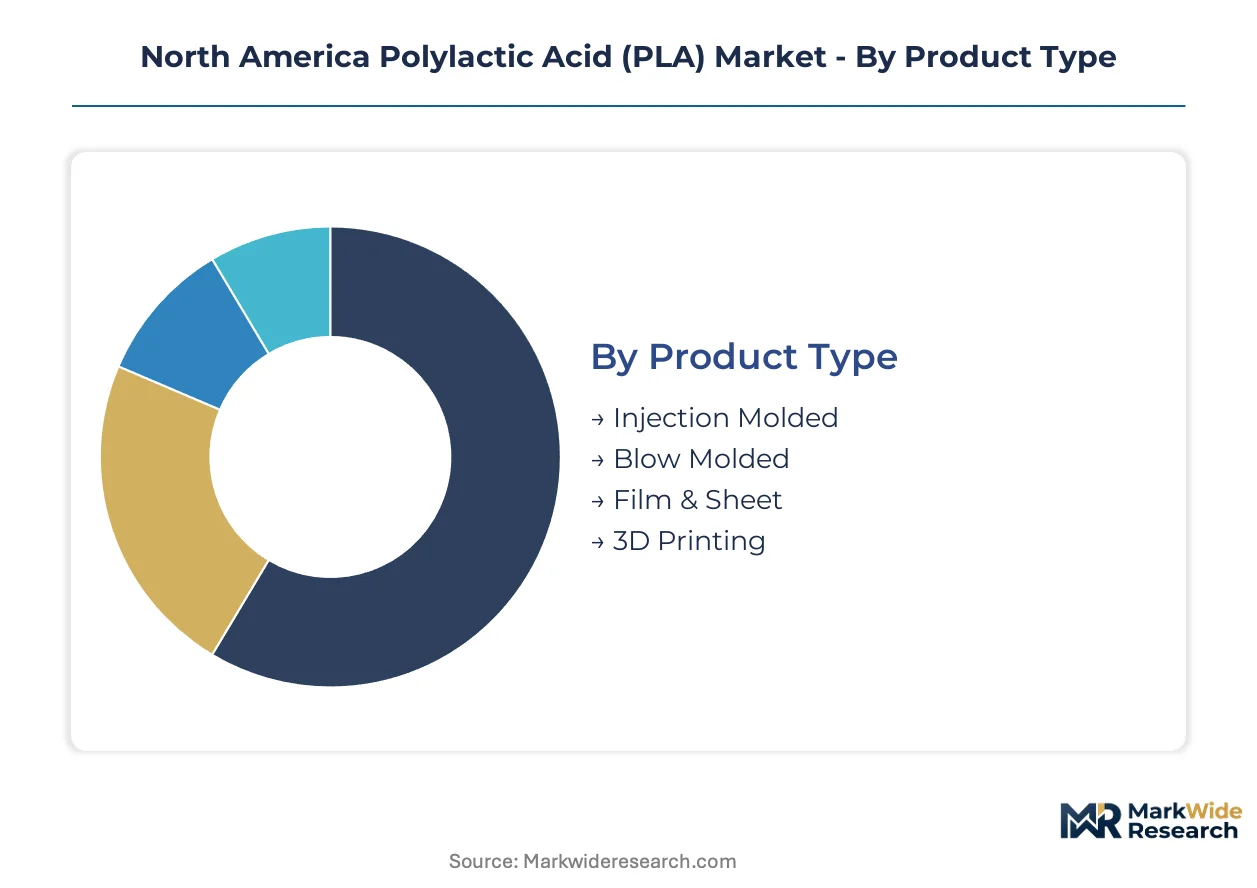
PLA market segmentation reveals distinct processing requirements and certification barriers that shape supplier-customer matching. Each category captures different value capture points across the polymer conversion chain, from raw lactide to finished goods.
Product Type:
Integration depth varies sharply: film and sheet formats operate as standalone converted products, while injection molded grades embed deeply into multi-component assemblies.
- Film & Sheet:Cast and oriented PLA films serve fresh produce packaging and food service disposables with gauge tolerances of ±5%. Demand clusters in California and Washington state procurement channels where SB 54 compliance mandates compostable content. NatureWorks and TotalEnergies Corbion dominate certified supply to major food distributors.
- Injection Molded:High-flow grades with melt indices of 10-30 g/10min fill thin-wall containers and cutlery molds. The segment penetrates quick-service restaurant supply chains and institutional food service, though heat deflection limits restrict hot-fill applications below 60°C.
- Blow Molded:Biaxially oriented bottles for cold-fill beverages and personal care products leverage PLA's clarity and dead-fold characteristics. Limited penetration due to narrow processing windows and moisture sensitivity during reheat stages.
- 3D Printing:Filament grades demand ±0.05mm diameter consistency and vacuum-sealed packaging to prevent hydrolytic degradation. Premium pricing reflects spool-to-spool lot control and color matching for professional prototyping services.
Film and sheet leads volumes today; 3D printing is gaining share fastest.
Application:
Cost tier stratification separates commodity packaging from specialty medical and automotive specifications requiring enhanced purity or heat resistance modifications.
- Packaging:Food contact trays, clamshells, and flexible wraps constitute the volume anchor, driven by California, New York, and Washington state single-use plastic bans. ASTM D6400 certification operates as a hard gate for retail shelf access.
- Consumer Goods:Disposable cutlery, straws, and serviceware target food service distributors seeking brand differentiation through compostability claims. Price sensitivity limits adoption to premium positioning or regulatory-mandated channels.
- Textile:PLA fiber applications in non-wovens and apparel remain nascent in North America, constrained by hydrolytic instability during washing cycles and limited domestic spinning infrastructure.
- Automotive:Interior trim components leverage PLA's low volatile organic compound emissions for cabin air quality compliance. Ford and tier suppliers pilot injection molded panels with natural fiber reinforcement.
Packaging commands the largest revenue pool; automotive applications show steepest expansion trajectory.
End User:
Customer type segmentation distinguishes price-tolerant regulated sectors from cost-driven commodity buyers with divergent certification requirements.
- Food & Beverage:Quick-service chains, institutional caterers, and fresh produce packagers drive specification demand. EPA Bio-Preferred procurement mandates secure volumes for government cafeteria and national park concession supply.
- Healthcare:Sterilizable trays and blister packs require USP Class VI and FDA food-contact certifications. TotalEnergies Corbion's lactide purification capabilities target this premium segment with validated supply chains.
- Agriculture:Mulch films and planting trays leverage soil biodegradability where industrial composting infrastructure is absent. Adoption limited by mechanical durability requirements and UV stability during growing seasons.
- Electronics:Anti-static packaging for semiconductors and consumer electronics employs PLA's surface resistivity characteristics. Niche positioning due to humidity sensitivity and ESD performance gaps versus petroleum-based alternatives.
Food and beverage anchors current demand; healthcare is climbing the fastest.
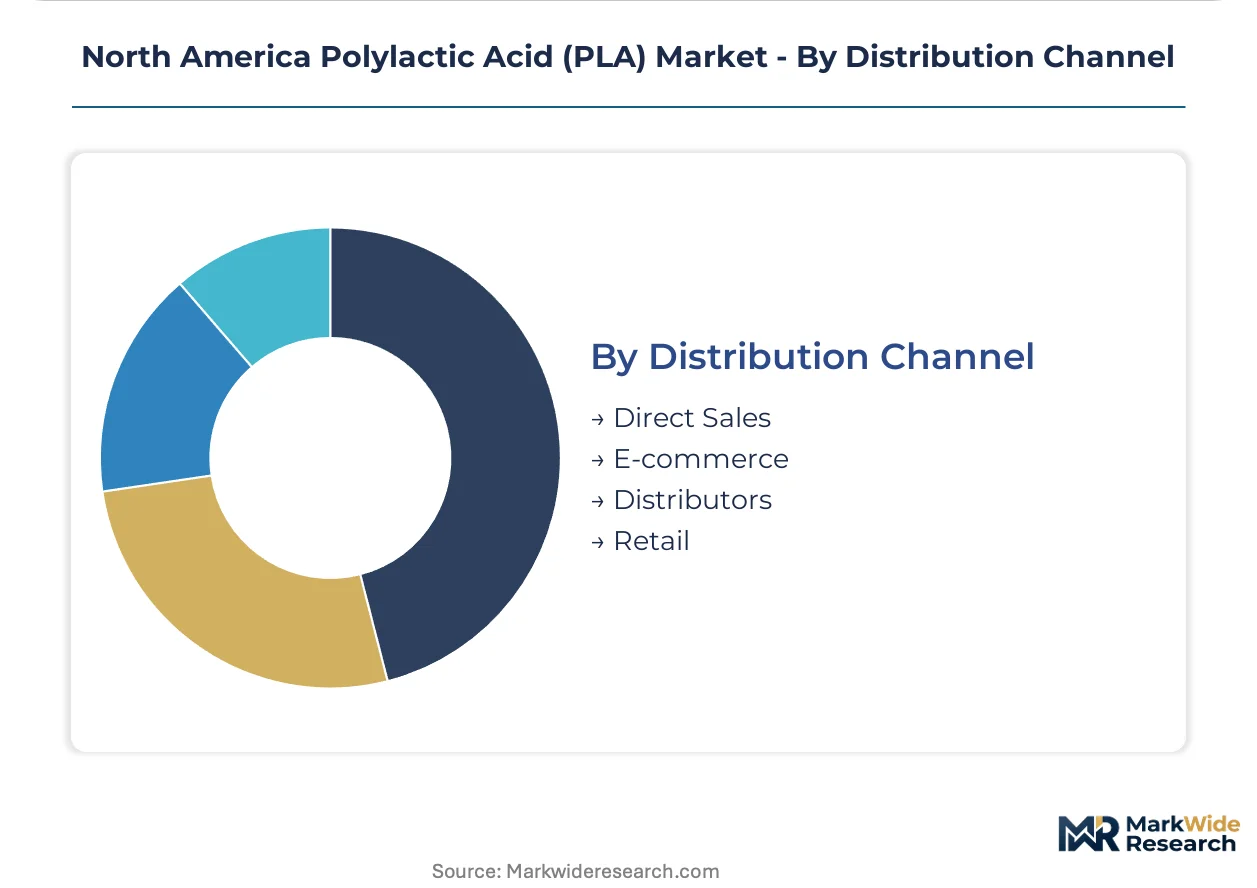
Distribution Channel:
Supply concentration dictates channel strategy: direct mill relationships dominate high-volume certified grades, while fragmented routes serve spot buyers and specialty formulations.
- Direct Sales:NatureWorks and TotalEnergies Corbion ship bulk resin and compounded pellets directly to major converters and brand owners. Long-term offtake agreements secure volume commitments and lock in ASTM D6400 certification documentation.
- Distributors:Regional compounders and resin distributors stock standard grades for mid-tier injection molders and extrusion operators. Inventory positioning in Chicago, Dallas, and Los Angeles logistics hubs cuts lead times for spot purchases.
- E-commerce:3D printing filament and small-lot specialty grades move through Amazon Business and dedicated additive manufacturing marketplaces. Spool packaging and moisture barrier requirements add handling complexity.
- Retail:Limited to consumer-facing finished goods—compostable tableware and food storage items—rather than industrial resin sales. Whole Foods and specialty grocers stock certified PLA serviceware for household purchase.
Direct sales capture the largest volume share; e-commerce channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Blair, Nebraska fermentation complex anchors North American PLA production capacity, leveraging proximity to Iowa and Illinois corn starch supply chains. EPA bio-preferred procurement standards and state-level single-use plastic bans in California, New York, and Washington shape demand distribution across the continent.
United States
Midwest corn belt infrastructure clusters lactide production near Blair, Nebraska, cutting feedstock logistics costs for domestic fermentation operations. EPA bio-preferred mandates require compostable food service items in government cafeterias and national park concessions, securing guaranteed offtake volumes. California's SB 54 imposes 30% recycled or compostable packaging content by 2032, forcing CPG brands to certify supply chains through ASTM D6400 protocols.
Canada
Provincial extended producer responsibility programs in British Columbia and Quebec impose packaging waste fees that internalize end-of-life costs for petroleum-based alternatives. Health Canada maintains food-contact safety standards for bio-based polymers entering food service applications. Ontario's Greater Toronto Area hosts compounding and conversion operations serving quick-service restaurant supply chains with certified resin grades.
Mexico
Export-oriented packaging converters in the Bajío Region and Mexico City Metro supply US retail chains seeking SB 54 compliance without domestic resin premiums. Mexican federal environmental standards lag California and Washington mandates, limiting domestic demand acceleration. Nuevo León's industrial corridor attracts toll compounding investments targeting cross-border food service disposable markets.
North America Polylactic Acid (PLA) Market Competitive Landscape
Global majors compete with regional champions across certification depth and feedstock integration. The market structure concentrates around fermentation-based lactide producers with ASTM D6400 documentation capabilities, while specialty compounders occupy formulation niches. Three archetypes dominate: integrated biopolymer producers controlling starch-to-resin value chains, toll compounders serving brand-specific color and additive requirements, and medical-grade purification specialists targeting FDA and USP Class VI certifications. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term corn supply agreements and composting facility alliances.
Within the integrated biopolymer tier, NatureWorks LLC and TotalEnergies Corbion exemplify contrasting geographic and technical positioning. NatureWorks anchors domestic supply through its Nebraska fermentation infrastructure, while TotalEnergies Corbion represents the specialty-grade purification archetype with lactide processing capabilities sustaining medical and food-contact certifications. BASF Corporation occupies the diversified chemical conglomerate position, leveraging polymer formulation expertise across multiple biodegradable resin platforms.
| Leading Market Players |
|---|
| NatureWorks LLC |
| TotalEnergies Corbion |
| BASF Corporation |
| Danimer Scientific |
| Evonik Corporation |
| DuPont de Nemours, Inc. |
| Mitsubishi Chemical America, Inc. |
| Dow Chemicals |
| Futerro |
| Others |
Value Network & Pricing Analysis
Government cafeteria procurement programs and national park concession operators anchor demand for ASTM D6400-certified grades, locking in contract-based long-term offtake structures that insulate domestic producers from spot resin volatility. This buyer concentration enables premium pricing for certified supply while forcing uncertified imports into commodity discount tiers.
Pricing Analysis
Corn starch pass-through mechanics dominate PLA resin economics, with Iowa and Illinois drought cycles transmitting directly into lactide production costs within one quarter. Three-tier pricing structure across medical-grade, food-contact, and industrial grades separates TotalEnergies Corbion's purified lactide from NatureWorks's commodity packaging volumes. Cost compression in standard injection molding grades is intensifying because Mexican toll compounders undercut domestic conversion margins. Quick-service restaurant supply chains exhibit highest price sensitivity, while healthcare sterilizable tray buyers tolerate premiums for USP Class VI documentation.
Supply Chain Analysis
Single-source vulnerability sits with Blair, Nebraska, where NatureWorks's fermentation complex processes over half of North American lactide capacity within a 200-mile corn belt radius. Raw material flows draw from Iowa and Illinois starch processing, Thailand sugarcane feedstock alternatives, and Louisiana dextrose refineries. Tariff exposure on Asian lactide imports compounds logistics chokepoints at Gulf Coast ports handling Brazilian sugarcane-derived resin. Distribution runs through direct mill relationships for certified bulk volumes, with regional distributors in Chicago and Dallas serving spot injection molding demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America PLA market reads as a late-cycle quality story, with California SB 54's 30% compostable content mandate tilting procurement specifications toward ASTM D6400-certified supply chains that command structural premiums.
For Market Incumbents: Cement certification moats by accelerating BPI validation timelines for specialty medical grades before European biopolymer producers secure FDA food-contact parity. Capacity addition in Georgia and Florida composting corridors captures first-mover positioning as curbside organics collection expands. Threat substitution from chemically recycled PET demands continuous lactide purification R&D to sustain clarity and heat-seal performance advantages. For New Entrants and Emerging Players: California SB 54 in the United States opens a window for toll compounding specialists to capture SB 54 compliance volumes from CPG brands seeking dual-sourcing beyond NatureWorks and TotalEnergies Corbion. Southeast US composting infrastructure gaps present the most penetrable geography, with Florida municipalities piloting PLA-accepting curbside collection. Go-to-market angle: partner with food service distributors consolidating purchase orders away from uncertified Asian imports. For Investors and Strategic Acquirers: Chemical conglomerates with polymer formulation expertise are the most active acquirer in this space, seeking fermentation-based biopolymer platforms to round out sustainability portfolios. Acquisition target archetype: toll compounders with ASTM D6400 documentation capabilities and established food distributor relationships. Signal to watch: BPI certification backlogs exceeding six months, indicating demand outstripping validated supply and supporting premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Starch Processing | Cuts feedstock logistics costs for Blair, Nebraska fermentation complexes against Thai sugarcane alternatives. |
| ASTM D6400 Certification Acceleration | Locks out uncertified imports as California SB 54 interim targets begin tightening retail shelf access. |
| Southeast US Composting Infrastructure Partnership | Positions suppliers for Florida and Georgia curbside organics pilots accepting PLA food service waste. |
| Medical-Grade Lactide Purification Scale-Up | Captures sterilizable tray demand from TotalEnergies Corbion's FDA and USP Class VI validated supply chains. |
| 3D Printing Filament Specialty Formulation | Commands pricing multiples through ±0.05mm diameter tolerance and vacuum-sealed moisture barrier packaging. |
Research Methodology
Multiple input streams — fermentation plant managers, food service distributor procurement leads, composting facility operators, and brand sustainability directors — were reconciled against EPA bio-preferred procurement databases, BPI certification registries, and California SB 54 compliance filings. Secondary validation drew from SEC 10-K disclosures of chemical conglomerates, USDA corn price reports, and municipal composting pilot program announcements. Bottom-up volume builds from lactide production capacity and top-down demand estimates from packaging waste regulations were triangulated to constrain forecast variance.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier penetration. Industry-specific forecast inputs included corn starch price volatility assumptions and industrial composting facility buildout timelines in Texas and Florida municipalities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended drought cycles in Iowa and Illinois or accelerated SB 54 enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Brazil Bioplastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
North America Bioplastics Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
China Bioplastics Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Biopolymer Films Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Global Bioplastic Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market