
 North America Bioplastics Market | 2026-2036
North America Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bioplastics Market Insights
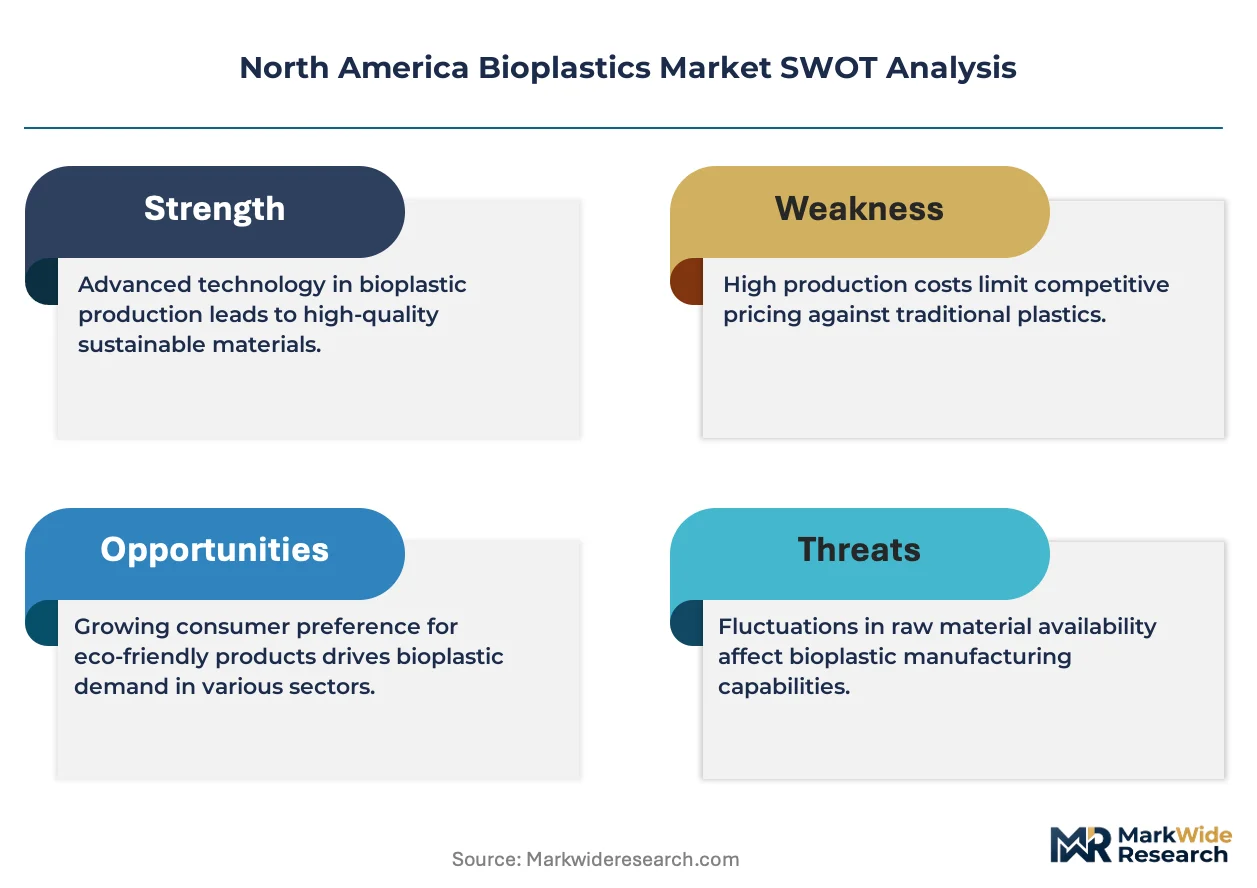
California's SB 54 extended producer responsibility mandate is recalibrating packaging procurement across North America by requiring 30% recycled or bio-based content in single-use plastics. NatureWorks LLC leverages its Blair, Nebraska PLA manufacturing complex to anchor supply for food-service brands seeking certified compostable alternatives. Braskem sustains its position through bio-polyethylene production from Brazilian sugarcane ethanol, competing for durable goods applications where drop-in compatibility matters. Danimer Scientific specializes in PHA fermentation technology, differentiating its resins for marine-degradable film formulations that target coastal state regulations.
North America bioplastics comprise polymers derived from renewable biomass sources such as corn starch, sugarcane, or cellulose, engineered to match or exceed the mechanical properties of conventional petroleum-based plastics while enabling compostability or biodegradation under specified conditions. These materials primarily serve packaging, agriculture, and consumer goods sectors seeking to reduce fossil dependence and comply with emerging waste diversion mandates. PLA dominates current volume due to mature fermentation and polymerization infrastructure, while PHA captures accelerating interest from buyers prioritizing marine and soil biodegradability without industrial composting infrastructure. Starch blends occupy cost-sensitive applications such as agricultural mulching films, where performance thresholds remain lower and disposal pathways align with on-field degradation.
The U.S. EPA bio-preferred program and California Department of Resources Recycling and Recovery (CalRecycle) enforcement frameworks shape product certification requirements and market access across the region. Canada's Health Canada and Environment and Climate Change Canada coordinate polymer notification and toxicity screening protocols that govern novel bioplastic introductions. Stakeholders must monitor pending U.S. Federal Trade Commission Green Guides revisions, which will clarify biodegradability marketing claims and reshape competitive positioning for suppliers with third-party certification versus self-declared performance.
Market Dynamics
California's SB 54 mandate for 30% recycled or bio-based content in single-use plastics is restructuring procurement specifications across the United States and Canada, forcing converters to requalify resin portfolios and redirect capital toward certified compostable feedstocks.
Growth Catalysts
- Extended Producer Responsibility Mandates:California SB 54 and Canada's proposed federal plastic registry are compelling brand owners to source certified biodegradable alternatives for food-service and flexible packaging applications.
- Agricultural Processing Infrastructure:Corn-starch fermentation capacity clusters around Nebraska and Iowa, anchoring PLA supply chains with feedstock proximity and existing grain-handling logistics.
- Marine-Degradable Formulation Demand:Coastal state regulations in Washington, Oregon, and Maine are accelerating PHA resin qualification for films and cutlery targeting ocean-end-of-life scenarios.
Market Restraints
- Industrial Composting Infrastructure Gaps:Limited commercial composting facility access across the U.S. Southeast and Mountain West restricts end-of-life pathways for PLA food-service items.
- Petrochemical Price Volatility:Crude oil price swings compress bioplastic premium tolerance in cost-sensitive agricultural mulch and single-use bag segments.
- Drop-In Substitution Thresholds:Bio-polyethylene from sugarcane ethanol faces performance gaps in high-temperature automotive and appliance applications against fossil-based HDPE.
Strategic Opportunities
- Canadian Federal Procurement Standards:Environment and Climate Change Canada's bio-preferred purchasing guidelines for federal agencies create a captive demand channel for certified compostable office and food-service products.
- PHA-Paper Lamination Convergence:Combining fermentation-derived PHA coatings with molded fiber substrates addresses barrier performance gaps in hot-fill liquid packaging for quick-service restaurant chains.
- Midwest Agricultural Film Replacement:Starch-blend mulch films targeting Nebraska, Iowa, and Illinois row-crop operations align degradation timelines with planting cycles and eliminate retrieval labor costs.
Industry Challenges
- ASTM D6400 and D6868 Certification Timelines:Third-party compostability verification for novel resin formulations extends 12-18 months, delaying product launches and locking working capital in testing protocols.
- Fermentation Scale-Up Expertise Scarcity:PHA production requires specialized biochemical engineering talent concentrated in limited university and industrial research clusters, constraining capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bioplastics Market |
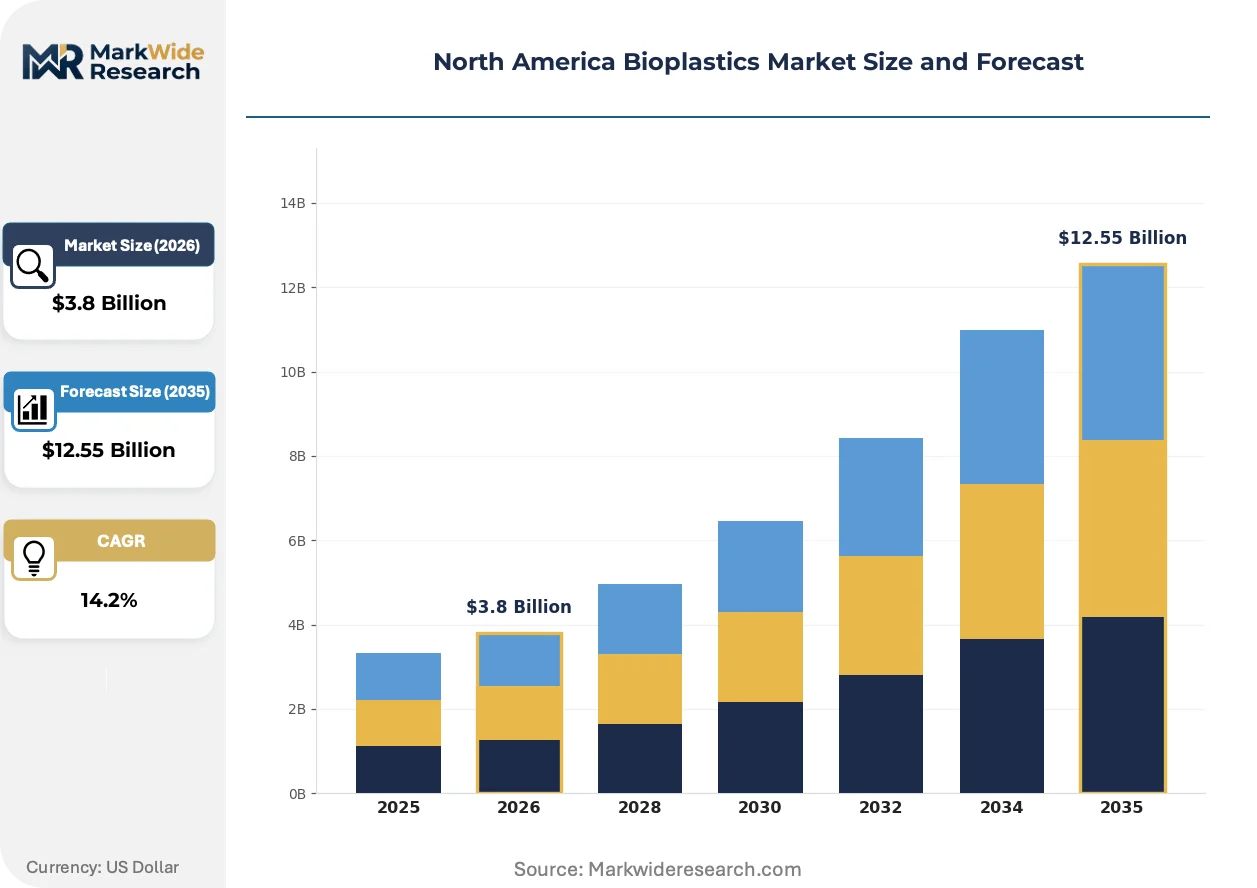
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Cellulose-based End User: Packaging, Agriculture, Consumer Goods, Automotive Form: Films, Rigid Containers, Flexible Packaging, Foams Technology: Extrusion, Injection Molding, Blow Molding, 3D Printing |
| Companies Covered | NatureWorks LLC, Braskem, BASF SE, Novamont SpA, Indorama Ventures Public Company Limited, Dow Inc., Eastman Chemical Company, Cargill Incorporated, Danimer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bioplastics Market Trends and Innovations
Continuous processing automation and regulatory specification tightening are compressing product development cycles while fragmenting resin procurement strategies across converter tiers.
Advanced process control systems using real-time rheology monitoring are automating quality consistency in PLA extrusion lines. Food packaging converters in the U.S. Midwest are retrofitting cast film equipment with these systems to reduce batch-to-batch viscosity variation. This automation is compressing qualification timelines for brand-owner specifications and reducing scrap rates in high-speed form-fill-seal operations.
The U.S. EPA's pending Green Guides revision is clarifying biodegradability marketing claim standards for consumer-facing products. This regulatory development is forcing suppliers to distinguish between industrial compostability, home compostability, and marine biodegradability in labeling. Food-service disposables sold through retail channels face the most stringent documentation requirements, driving consolidation around third-party certified resins.
Brand-owner direct contracting with biopolymer producers is displacing traditional distributor-centric purchasing for large-volume packaging programs. Quick-service restaurant chains and grocery private-label operators are establishing multi-year offtake agreements with NatureWorks and Danimer Scientific to secure capacity and lock pricing. This pattern is most pronounced in California and the U.S. Northeast, where EPR compliance deadlines concentrate procurement urgency among national account holders.
North America Bioplastics Market Segmentation
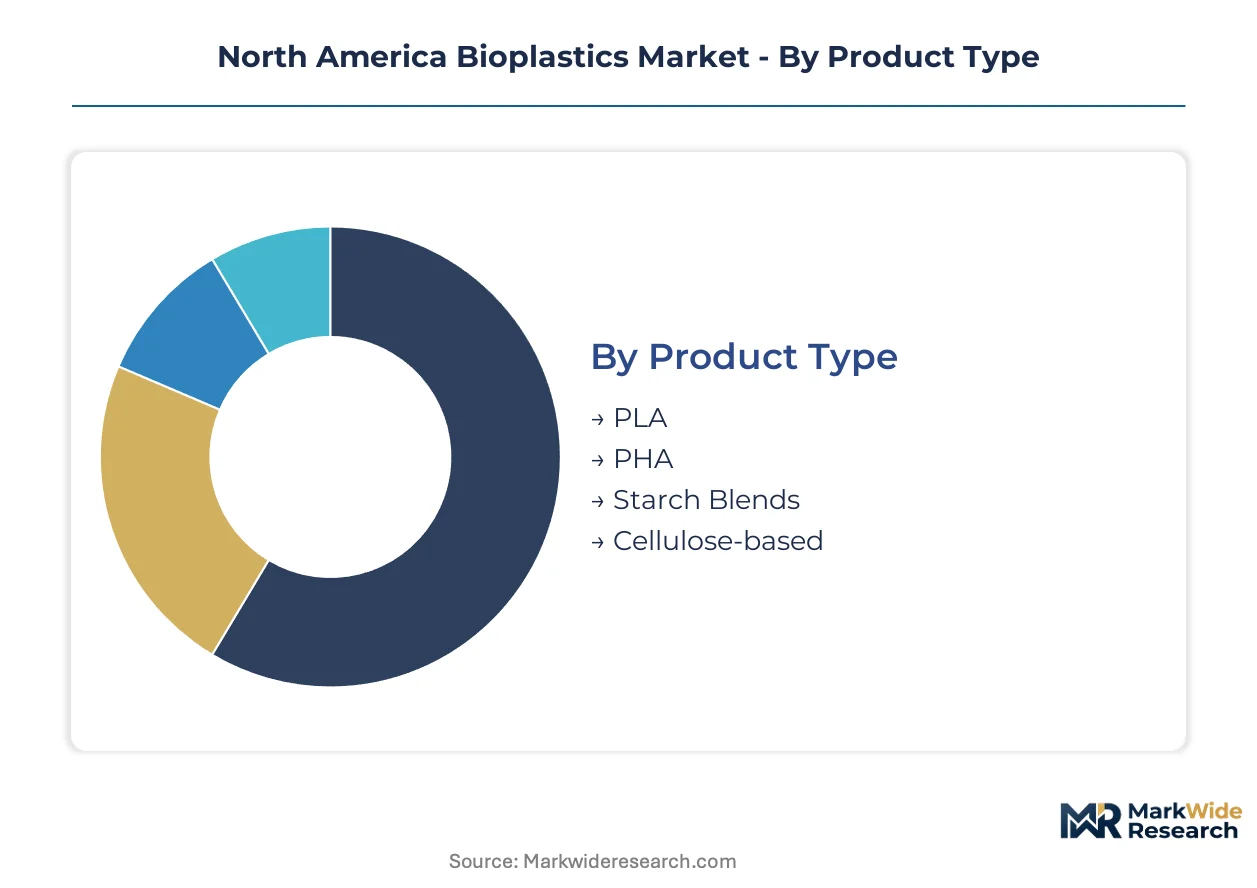
Bioplastics procurement across North America fragments sharply by performance requirements, composting infrastructure access, and drop-in compatibility needs. Converters must match resin chemistry to specific end-of-life pathways and processing equipment constraints.
Product Type:
Cost tolerance and biodegradation timeline differentiate buyers across the four polymer platforms.
- PLA:Polylactic acid derived from corn starch fermentation offers the most mature supply chain and crystallinity control for thermoformed food containers. Demand clusters in the U.S. Midwest near NatureWorks' Nebraska production complex, though industrial composting infrastructure gaps in the Southeast constrain food-service deployment.
- PHA:Polyhydroxyalkanoates produced via bacterial fermentation deliver marine and soil biodegradability without industrial composting. Coastal states including Washington and Oregon prioritize PHA films for ocean-end-of-life scenarios, driving premium positioning against PLA alternatives.
- Starch Blends:Cost-sensitive agricultural mulch applications in Iowa and Illinois favor these materials for on-field degradation aligned with planting cycles.
- Cellulose-based:Regenerated cellulose films serve high-barrier flexible packaging where transparency and grease resistance matter.
Volume sits with PLA; growth tilts toward PHA.
End User:
Regulatory pressure intensity and specification precision separate the four demand verticals.
- Packaging:California SB 54 mandates 30% bio-based content for single-use plastics, forcing converters toward certified compostable films and rigid containers. Quick-service restaurant chains and grocery private-label operators anchor procurement volume.
- Agriculture:Starch-blend mulch films eliminate retrieval labor costs for Nebraska and Iowa row-crop operations, though performance thresholds remain lower than packaging applications.
- Consumer Goods:Premium personal care and electronics packaging seek drop-in bio-polyethylene substitutes where fossil-based HDPE faces brand-owner pressure.
- Automotive:Bio-based interior trim and under-hood applications demand higher thermal stability than current PLA grades deliver, limiting penetration to non-structural components.
Packaging commands absolute volume; agriculture offers the steepest expansion trajectory as mulch film adoption accelerates.
Form:
Processing equipment compatibility and barrier requirements shape converter selection.
- Films:Cast and blown film extrusion of PLA and PHA dominates flexible food packaging, with real-time rheology monitoring systems reducing batch-to-batch viscosity variation in Midwest converter operations.
- Rigid Containers:Thermoformed PLA cups and clamshells serve food-service applications requiring transparency and stack strength, though heat deflection limits hot-fill capability.
- Flexible Packaging:Stand-up pouches and flow-wrap applications favor multi-layer structures combining bio-based sealant layers with conventional barriers.
- Foams:Expanded PLA loose-fill and food trays target protective packaging and institutional food service where cushioning or insulation properties matter.
Films absorb the largest resin tonnage; rigid containers gain share fastest as thermoforming lines retrofit for bio-based materials.
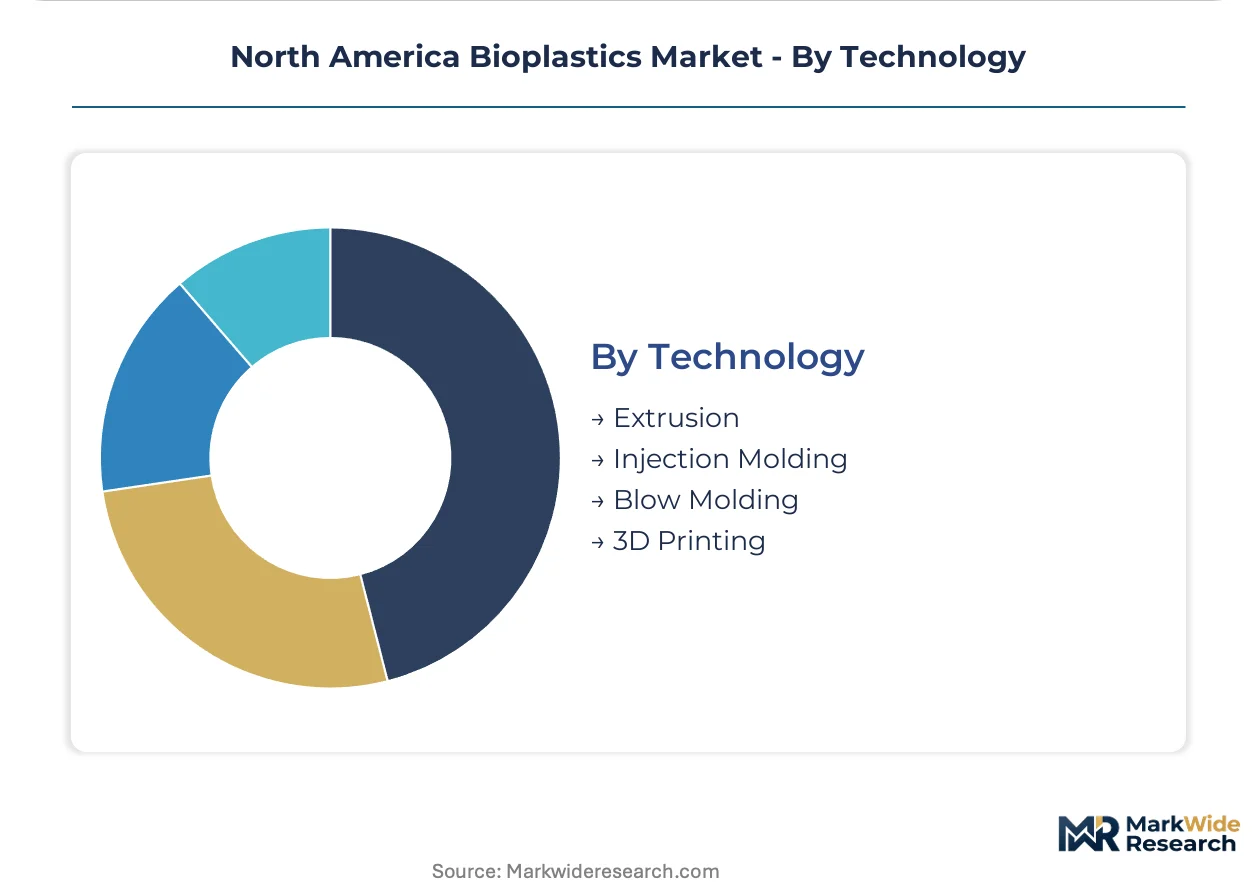
Technology:
Capital investment requirements and cycle time economics drive process selection.
- Extrusion:Continuous sheet and film production lines represent the most deployed conversion technology, with cast film equipment dominating PLA processing in the U.S. Midwest.
- Injection Molding:High-precision tooling for durable goods and consumer products requires modified screw designs and mold temperature control for PLA crystallization management.
- Blow Molding:Stretch blow molding of PLA bottles for beverage applications faces barrier performance gaps against PET, limiting adoption to short-shelf-life products.
- 3D Printing:Fused deposition modeling filaments represent a niche but expanding segment for prototyping and low-volume custom parts production.
Extrusion handles the greatest material throughput; injection molding expands most quickly as appliance and electronics housings specify bio-based content.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates bioplastics production capacity while Canada and Mexico expand consumption corridors. Nebraska anchors corn-starch fermentation infrastructure. California drives regulatory specification tightening.
United States
California's SB 54 mandate for 30% recycled or bio-based content in single-use plastics forces national brand owners to requalify resin portfolios. The U.S. EPA bio-preferred program shapes federal procurement specifications for compostable food-service items. Nebraska hosts NatureWorks' Blair manufacturing complex, anchoring PLA supply chains with direct feedstock access from surrounding corn belt operations.
Canada
Federal agencies accelerate procurement of certified compostable office and food-service products under Environment and Climate Change Canada guidelines. Health Canada coordinates polymer notification protocols that govern novel bioplastic introductions. Ontario converters retrofit cast film equipment for PLA processing to supply quick-service restaurant chains operating across the Great Lakes corridor.
Mexico
Cross-border supply chain integration positions Mexican converters as secondary processors for U.S. brand owners seeking cost-competitive thermoforming operations. The country's federal environmental prosecutor enforces emerging waste diversion standards in Mexico City and Guadalajara metropolitan zones. Jalisco's packaging industrial parks attract PLA resin toll processing contracts from California-based distributors.
North America Bioplastics Market Competitive Landscape
The competitive structure tilts toward fermentation-based specialists with captive agricultural feedstock access. Mid-cap chemical conglomerates and diversified materials multinationals occupy adjacent positions. Three archetypes dominate: corn-starch PLA pure-plays, sugarcane ethanol drop-in producers, and bacterial fermentation PHA specialists. Capacity expansion and strategic offtake contracting constitute the dominant competitive moves as converters seek supply security ahead of California compliance deadlines.
Within the PLA pure-play tier, NatureWorks LLC exemplifies vertical integration from corn processing through polymerization. Among diversified chemical conglomerates, BASF SE and Dow Inc. occupy positions bridging conventional petrochemicals and bio-based alternatives. Danimer Scientific represents the fermentation specialist archetype focused on marine-biodegradable resin platforms. These three anchors illustrate the strategic segmentation between feedstock-integrated, scale-driven, and performance-differentiated competitive positions.
| Leading Market Players |
|---|
| NatureWorks LLC |
| Braskem |
| BASF SE |
| Novamont SpA |
| Indorama Ventures Public Company Limited |
| Dow Inc. |
| Eastman Chemical Company |
| Cargill Incorporated |
| Danimer Scientific |
| Others |
Pricing and Supply Chain Analysis
California's SB 54 plastic pollution reduction mandate gates qualified bioplastics supply and premium-tier pricing access by requiring 30% bio-based content certification. Brand owners seeking compliance pay material premiums for ASTM D6400-certified resins, while uncertified alternatives face procurement exclusion.
Pricing Analysis
Outcome-based pricing anchors bioplastics procurement, with converters paying premiums tied to certified compostability performance and regulatory compliance assurance. Three-tier pricing structure across premium, standard, and economy levels separates PHA marine-biodegradable grades from PLA industrial-compostable tiers and uncertified starch blends. Cost compression in standard PLA tiers is intensifying because petrochemical price volatility narrows the fossil-to-bio premium gap. Agricultural mulch film buyers exhibit highest price sensitivity, while California quick-service restaurant chains prioritize certification over unit cost.
Supply Chain Analysis
ASTM D6400 and D6868 certification timelines gate supply chain participation, extending 12-18 months for novel resin qualification. Production concentrates in the United States, Brazil, and Thailand, with Nebraska anchoring corn-starch PLA fermentation and Brazilian sugarcane ethanol feeding Braskem's bio-polyethylene operations. Raw material dependencies center on corn starch, sugarcane bagasse, and bacterial fermentation feedstocks. Single-source vulnerability runs through NatureWorks' Blair complex, which supplies the majority of North American PLA resin. Distribution runs through direct brand-owner offtake agreements displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around fermentation-based specialists with captive feedstock access, as California SB 54 compliance deadlines force capital-constrained converters into acquisition or exit.
For Market Incumbents: Deepen backward integration into corn processing and fermentation capacity to secure feedstock cost advantage against Brazilian sugarcane ethanol competitors. Lock multi-year offtake agreements with quick-service restaurant chains before 2025-2026 EPR enforcement windows tighten further. Prioritize ASTM D6400 certification investment to maintain procurement eligibility as FTC Green Guides revisions clarify marketing claim standards. For New Entrants and Emerging Players: Marine-biodegradable PHA formulations targeting Washington and Oregon coastal regulations offer the most penetrable technology-first wedge. Starch-blend agricultural mulch films for Iowa and Nebraska row-crop operations present a second white-space target with lower certification barriers. Pursue toll-processing partnerships with existing PLA extrusion lines rather than greenfield capacity investment. For Investors and Strategic Acquirers: Brand-owner direct contracting announcements are the leading indicator that supply security premiums are shifting from spot markets to long-term agreements. Position acquisition screening around mid-cap fermentation specialists with commercial-scale PHA capacity and existing FDA food-contact approvals. Watch for FTC Green Guides finalization as the inflection signal that third-party certification becomes mandatory rather than optional.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Captive starch supply locks cost advantage against Brazilian ethanol imports for NatureWorks and Cargill. |
| Long-term Supply Agreement with QSR Chains | Multi-year offtake contracts with California-based restaurant operators secure volume ahead of SB 54 deadlines. |
| Joint Venture for PHA Scale-Up | Partnerships between Danimer Scientific and Midwest agricultural processors expand fermentation capacity beyond current bottlenecks. |
| Green Manufacturing Transition | Renewable energy sourcing for Nebraska PLA production reduces Scope 2 emissions for brand-owner ESG reporting. |
| Capacity Expansion in Coastal States | Washington and Oregon processing facilities shorten logistics chains for marine-biodegradable film demand. |
Research Methodology
Trade databases, EPA bio-preferred procurement records, and CalRecycle enforcement filings formed the secondary backbone of this analysis. Primary interviews with plant managers at PLA extrusion facilities, procurement leads at quick-service restaurant chains, distribution channel partners, and technical R&D directors at fermentation specialists validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and brand-owner sustainability disclosures.
Bottom-up modeling built from individual converter capacity and utilization rates, while top-down approaches validated against state-level procurement mandates and federal bio-preferred spending data. Segmentation dimensions included polymer chemistry, end-use vertical, processing technology, and regional regulatory cluster. CAGRs were derived from regression analysis of historical adoption curves against compliance deadline proximity. Industry-specific forecast inputs incorporated ASTM certification pipeline timelines and corn futures price correlation models.
Several conditions sit outside the modeled scope, including potential FTC Green Guides revisions that could accelerate or delay certification requirements, and breakthroughs in enzymatic recycling that might compete with composting pathways. Forecasts reflect assumptions about industrial composting infrastructure buildout rates and brand-owner ESG commitment durability. A model refresh is warranted upon material change in California SB 54 enforcement intensity or NatureWorks capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Automotive Bioplastic Market
Bioplastics
Bio-PET Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Biopolymers Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Polyhydroxy Butyrate Market