
 Southeast Asia Bioplastics Market | 2026-2036
Southeast Asia Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Bioplastics Market Analytics
A shortage of polymer chemists trained in fermentation-based production is unwinding capacity expansion timelines across Southeast Asian bioplastics plants. TotalEnergies Corbion leverages its Rayong facility to anchor regional PLA supply. NatureWorks LLC sustains technology leadership through continuous R&D on high-heat PLA grades. AN PHAT BIOPLASTICS dominates Vietnam's domestic film and bag segment with integrated starch sourcing.
Bioplastics encompass polymers derived from renewable biomass sources such as corn starch, sugarcane, or agricultural waste, synthesized through bacterial fermentation or chemical polymerization to achieve tensile strengths comparable to conventional plastics. These materials serve primarily as drop-in replacements for fossil-based polymers in disposable packaging and durable goods. PLA leads volume production due to mature fermentation infrastructure and feedstock access across Thailand and Vietnam. PBAT commands premium positioning in flexible film applications where compostability certification drives procurement decisions. Starch blends occupy cost-sensitive tiers in agricultural mulch and short-life consumer goods.
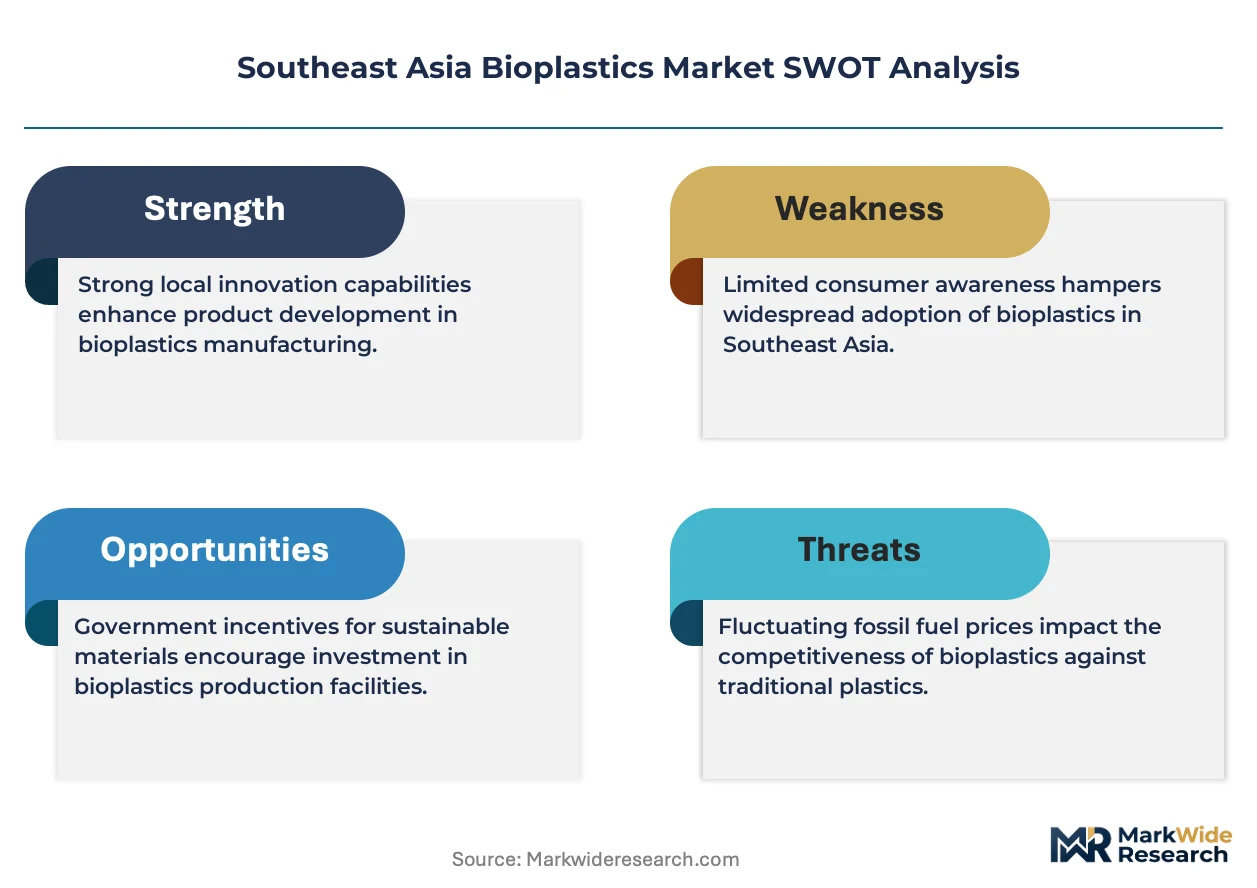
Thailand's Pollution Control Department enforces progressive single-use plastic restrictions that directly mandate biodegradable alternatives in retail and food service channels. Vietnam's Ministry of Natural Resources and Environment aligns national standards with EU REACH frameworks to facilitate export market access for domestic producers. Stakeholders must monitor feedstock price volatility and evolving composting infrastructure readiness as these determine actual substitution rates against conventional plastics.
Market Dynamics
Thailand's Pollution Control Department is compressing substitution timelines through mandatory biodegradable packaging quotas, forcing converters to requalify supply chains before domestic fermentation capacity matures.
Growth Catalysts
- Thailand's single-use plastic ban:The Pollution Control Department mandates compostable alternatives in retail and food service channels, creating guaranteed offtake for domestic PLA producers.
- Japanese packaging investment:Investors from Japan cluster in Vietnam's northern industrial corridor, transferring blown-film extrusion expertise to local bioplastics converters.
- Fermentation infrastructure:Existing sugarcane processing assets across Thailand enable rapid feedstock pivoting toward lactic acid precursors without greenfield construction.
Market Restraints
- Feedstock price volatility:Corn starch and sugarcane costs fluctuate with agricultural commodity cycles, compressing margin predictability for compounders.
- Composting infrastructure gaps:Industrial composting facilities remain concentrated in Bangkok and Ho Chi Minh City, limiting actual biodegradation rates for distributed packaging waste.
- Petroleum-based resin competition:Conventional polyethylene maintains cost advantages in bulk applications where compostability certification carries no procurement premium.
Strategic Opportunities
- Indonesian market entry:The archipelago's food packaging sector shows minimal bioplastics penetration, offering first-mover positioning for Thai and Vietnamese exporters.
- Agricultural mulch films:Starch-based biodegradable mulches address soil contamination concerns in Vietnam's Mekong Delta vegetable cultivation.
- EU REACH alignment:Vietnam's Ministry of Natural Resources and Environment harmonizes national standards with European frameworks, unlocking export certification pathways for domestic compounders.
Industry Challenges
- Polymer chemist scarcity:Fermentation-based production expertise remains concentrated in European and North American academic programs, delaying Southeast Asian plant commissioning.
- Compostability certification timelines:Industrial and home composting standards require 12-18 month validation cycles that misalign with customer procurement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Bioplastics Market |
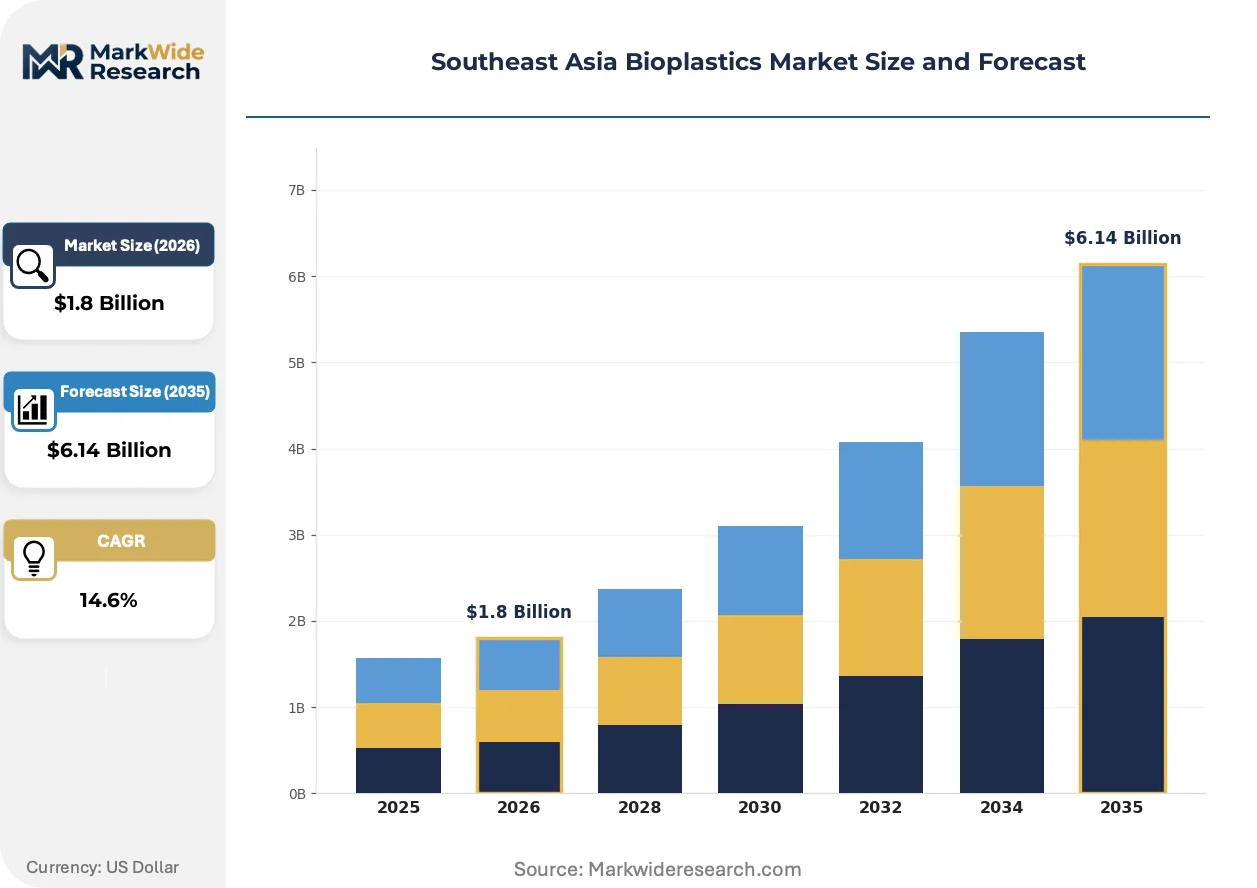
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, PBAT End Use: Packaging, Agriculture, Consumer Goods, Automotive Form: Films, Rigid Containers, Foam, Bags Technology: Injection Molding, Blow Molding, Extrusion, 3D Printing |
| Companies Covered | AN PHAT BIOPLASTICS, NatureWorks LLC, TotalEnergies Corbion, Bioways, Indo Rama Synthetics, PTT MCC Biochem Co Ltd, THANTAWAN INDUSTRY PLC, Prepack Thailand Co Ltd, Indorama Ventures Public Company Limited, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Bioplastics Market Evolving Landscape
Technology convergence between fermentation process control and blown-film extrusion is redefining performance benchmarks for flexible bioplastics across Thai and Vietnamese manufacturing bases.
High-heat PLA grades are decomposing the historical temperature-performance tradeoff that restricted bioplastics to cold-fill applications. Japanese beverage converters in Thailand's Eastern Economic Corridor are adopting these materials for hot-fill juice bottles at commercial scale. This thermal ceiling lift is decomposing rigid PET's monopoly in pasteurized food packaging.
Vietnam's Ministry of Natural Resources and Environment is accelerating REACH framework alignment to secure EU market access for domestic compounders. The regulatory harmonization forces reformulation of plasticizer and additive packages to meet migration limit standards. Northern Vietnamese producers are responding by substituting bio-based plasticizers for conventional petrochemical alternatives in flexible film grades.
Certification-driven procurement now dominates buyer decision matrices across Thai retail chains. Central Group and CP All are mandating industrial compostability logos for private-label food packaging, displacing price-only sourcing protocols. This preference shift concentrates contract awards among compounders with pre-certified resin grades, compressing qualification timelines for uncertified challengers.
Southeast Asia Bioplastics Market Segmentation
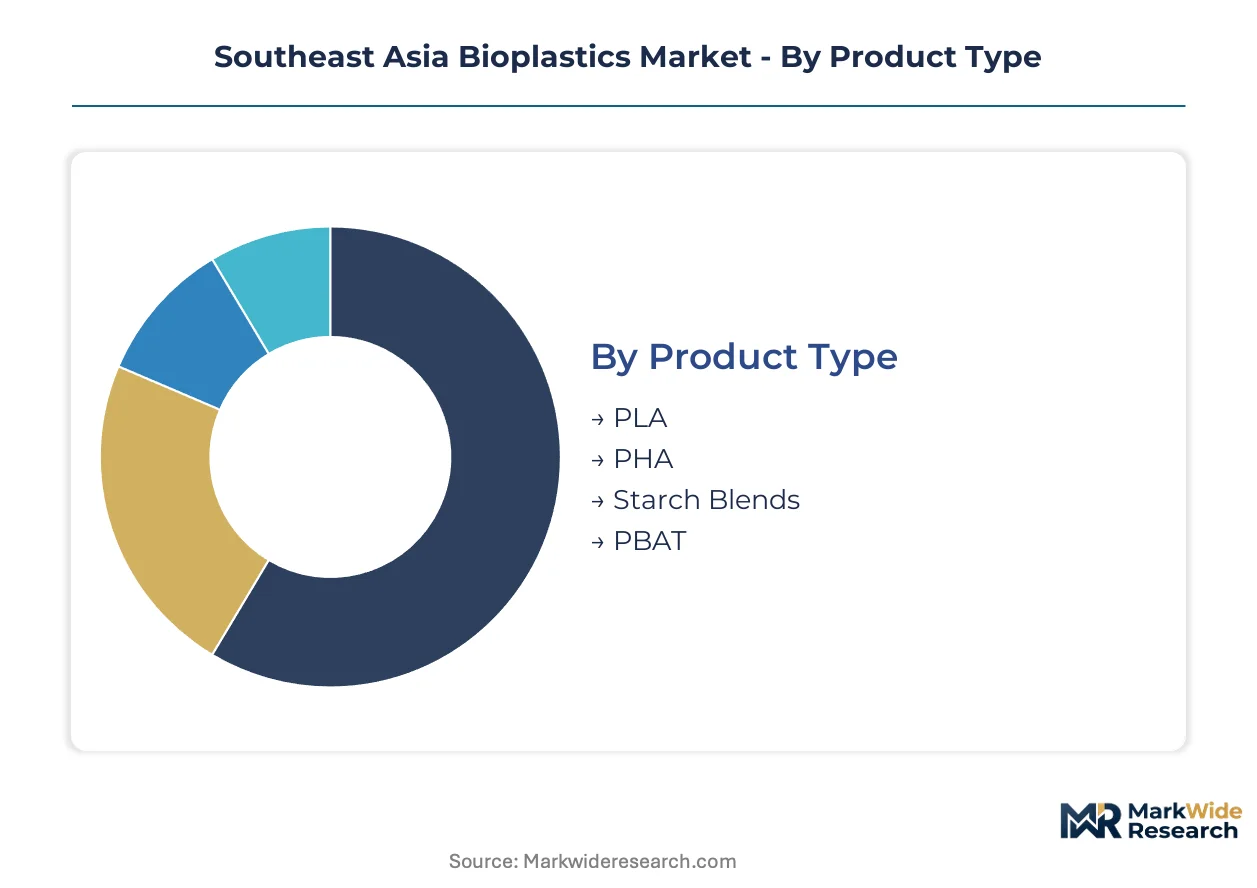
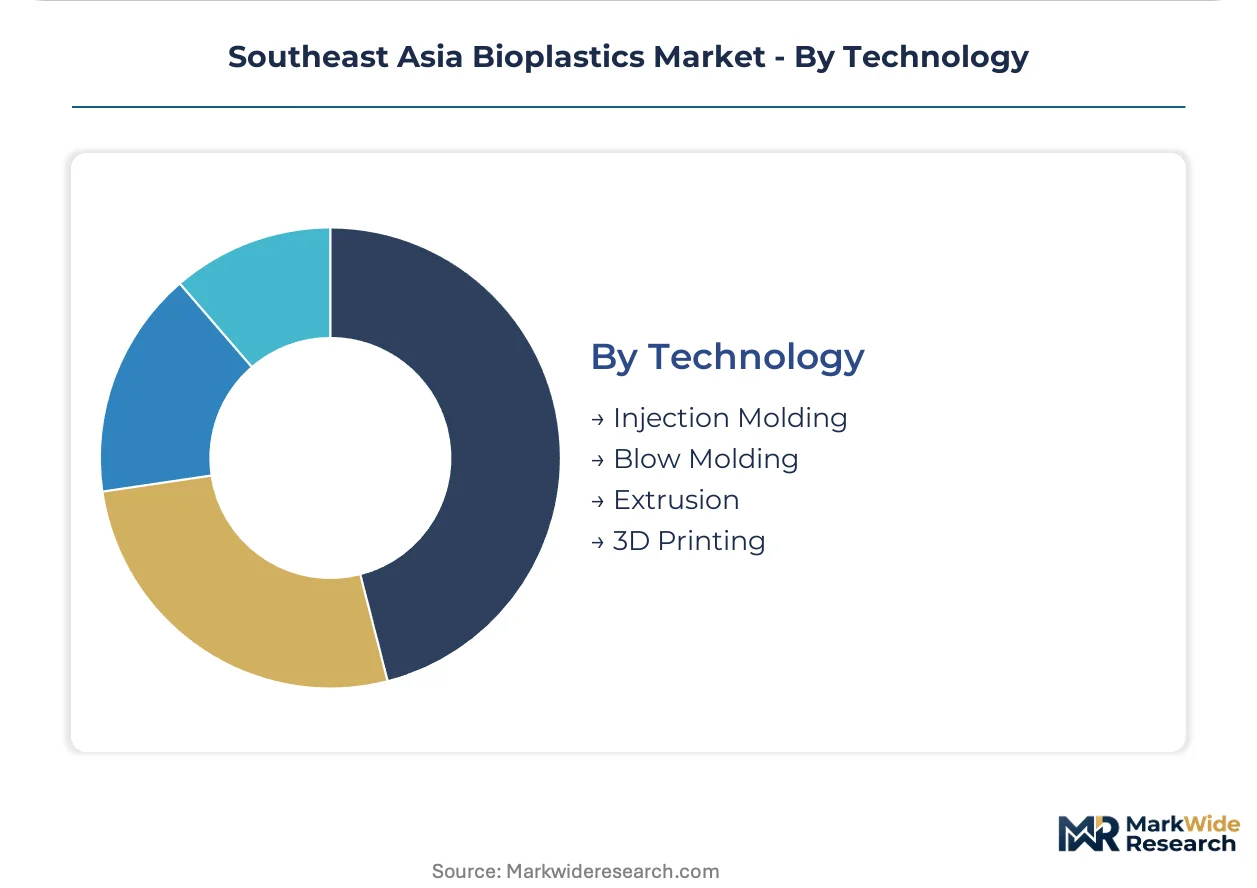
Segmentation reveals how Thailand's domestic demand pull diverges from Vietnam's export-oriented production across the Southeast Asia bioplastics value chain. Understanding these splits enables targeted capacity planning and regulatory positioning.
Product Type:
PLA anchors domestic Thai consumption through food packaging mandates, while PBAT and starch blends serve cross-border flexible film demand.
- PLA:Polylactic acid derived from fermented corn starch or sugarcane delivers tensile strength comparable to conventional polystyrene. Thai retail chains and food service operators concentrate procurement in Bangkok and Rayong, driven by the Pollution Control Department's mandatory biodegradable quotas for single-use items.
- PBAT:Polybutylene adipate terephthalate combines fossil-derived adipic acid with bio-based butanediol to achieve full compostability in industrial facilities. Japanese packaging investors in Vietnam's northern industrial corridor specify PBAT for blown-film applications where certification drives procurement premiums.
- PHA:Polyhydroxyalkanoates synthesized through bacterial fermentation of agricultural waste offer marine biodegradability but remain cost-prohibitive for mass-market adoption.
- Starch Blends:Thermoplastic starch compounded with synthetic polymers dominates Vietnam's agricultural mulch film segment through cost-sensitive Mekong Delta vegetable cultivation.
PLA commands the established base. The steepest expansion runs through PBAT.
End Use:
Cost tier stratification separates premium-certified packaging from commodity agricultural applications across Thai and Vietnamese manufacturing bases.
- Packaging:Food contact films, rigid containers, and flexible pouches substitute for polyethylene in retail and food service channels. Central Group and CP All mandate industrial compostability logos for private-label sourcing, concentrating contract awards among pre-certified compounders.
- Agriculture:Biodegradable mulch films and planting trays address soil plastic contamination in intensive vegetable cultivation. Mekong Delta farmers adopt starch-based mulches where tillage incorporation eliminates removal labor.
- Consumer Goods:Disposable cutlery, cups, and shopping bags serve Thailand's 2027 single-use plastic ban timeline with guaranteed offtake volumes.
- Automotive:Interior trim components and under-hood applications exploit PLA's rigidity for non-structural parts with limited heat exposure.
Packaging absorbs the dominant share. Agriculture is climbing the fastest as soil contamination regulations tighten.
Form:
Volume concentration tracks blown-film extrusion capacity clustering in Vietnam's northern provinces versus rigid container molding in Thailand's Eastern Economic Corridor.
- Films:Thin-gauge blown and cast films for food wrapping and agricultural mulching leverage Vietnamese converters' transferred Japanese extrusion expertise.
- Rigid Containers:Thermoformed trays and injection-molded cups serve Thai hot-fill juice bottling where high-heat PLA grades displace PET thermal ceilings.
- Foam:Expanded PLA and starch-based loose-fill packaging protect electronics and fragile goods in e-commerce fulfillment.
- Bags:Carry-out and produce bags face mandatory compostable substitution under Bangkok's progressive retail channel restrictions.
Films lead current output. Rigid containers are gaining share fastest through thermal performance advances.
Technology:
Customer type splits between high-volume extrusion converters serving retail chains and precision molders targeting automotive tier suppliers.
- Injection Molding:High-pressure molding of PLA and starch blends produces rigid containers, cutlery, and automotive interior components with tight dimensional tolerances.
- Blow Molding:Extrusion and injection blow processes form bottles and jars for beverage and personal care applications where high-heat PLA enables hot-fill capability.
- Extrusion:Single and multi-layer film extrusion dominates Vietnamese flexible packaging output with transferred Japanese blown-film expertise.
- 3D Printing:Fused deposition modeling filaments serve prototyping and low-volume custom manufacturing with PLA's ease of processing.
Extrusion holds the production base. Injection molding is expanding most quickly through rigid food service substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Pollution Control Department anchors regional demand through mandatory biodegradable packaging quotas that compress substitution timelines for converters.
Thailand
Retail chains in Bangkok and Rayong drive PLA procurement for food service applications. The Pollution Control Department's 2027 single-use plastic ban creates guaranteed offtake volumes. TotalEnergies Corbion's Rayong facility anchors domestic fermentation capacity for lactic acid precursors.
Vietnam
Japanese packaging investors cluster in the northern industrial corridor around Hanoi and Hai Phong. The Ministry of Natural Resources and Environment aligns national standards with EU REACH frameworks to unlock export certification. AN PHAT BIOPLASTICS dominates domestic film production through integrated starch sourcing from Mekong Delta agricultural networks.
Indonesia
Food packaging chains across Java show minimal bioplastics penetration despite archipelago-scale waste management pressures. The national government lacks equivalent mandatory substitution frameworks seen in neighboring markets. Jakarta and Surabaya industrial zones remain dependent on conventional polyethylene converters.
Malaysia
Penang and Selangor manufacturing bases serve as secondary conversion hubs for Thai-sourced PLA resins. The Department of Environment maintains voluntary sustainability guidelines without binding biodegradable mandates. Electronics packaging demand in the Bayan Lepas free trade zone drives niche adoption of starch-based protective foams.
Philippines
Metro Manila food service operators face fragmented regulatory pressure from local government ordinances rather than national mandates. The Department of Environment and Natural Resources prioritizes marine plastic reduction without specifying compostable alternatives. Cebu and Davao converters remain price-sensitive to petroleum-based resin competition.
Southeast Asia Bioplastics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Southeast Asian bioplastics value chain. Fermentation-based PLA specialists compete against starch-blend compounders on performance-versus-price matrices. Three archetypes dominate: integrated petrochemical-biotech hybrids, agricultural-originated compounders, and packaging-converter backward integrators. Capacity expansion and certification pre-qualification represent the dominant competitive moves as procurement deadlines compress.
Among fermentation-anchored producers, TotalEnergies Corbion and NatureWorks LLC exemplify technology leadership archetypes with European and North American headquarters respectively. AN PHAT BIOPLASTICS occupies a position within the agricultural-integrated tier, representing Vietnamese domestic cost leadership through captive starch supply chains.
| Leading Market Players |
|---|
| AN PHAT BIOPLASTICS |
| NatureWorks LLC |
| TotalEnergies Corbion |
| Bioways |
| Indo Rama Synthetics |
| PTT MCC Biochem Co Ltd |
| THANTAWAN INDUSTRY PLC |
| Prepack Thailand Co Ltd |
| Indorama Ventures Public Company Limited |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Thai PLA producers and Bangkok-based retail chains lock in both fermentation capacity access and three-year price visibility against agricultural commodity swings. These contracts transfer feedstock risk to compounders while guaranteeing volume commitments that justify lactic acid precursor investments.
Pricing Analysis
Thai domestic PLA commands a 15-20% premium over Vietnamese flexible film grades, reflecting Bangkok's mandatory compostable quotas versus Hanoi's export-driven cost competition. Pricing stratifies across premium-certified, standard-industrial, and economy-agricultural tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy starch-blend tiers is intensifying because Mekong Delta farmers prioritize tillage-incorporation savings over compostability logos. Agricultural mulch buyers exhibit highest price sensitivity, while Japanese packaging investors in Vietnam's northern corridor demonstrate lowest sensitivity due to EU export certification requirements.
Supply Chain Analysis
Just-in-time lactic acid delivery dominates Thai fermentation plants, while Vietnamese starch compounders maintain strategic stockpiles of Mekong Delta cassava to hedge harvest seasonality. Supply concentrates in Thailand, Vietnam, and emerging Indonesian conversion capacity. Raw material dependencies center on corn starch, sugarcane juice, and adipic acid for PBAT copolymerization. Single-source vulnerability runs through European fermentation equipment suppliers, where polymer chemist scarcity delays plant commissioning. Distribution runs through Japanese trading houses that aggregate Vietnamese flexible film output for EU retail certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against conventional polyethylene cost advantages in bulk applications where compostability certification carries no procurement premium. Incumbents must navigate petroleum-based resin competition that maintains 30-40% cost gaps in price-sensitive agricultural tiers.
For Market Incumbents: Shield fermentation capacity investments through backward integration into captive sugarcane processing assets across Thailand's Eastern Economic Corridor. Anchor pricing power by securing pre-certification for industrial compostability logos ahead of Bangkok's 2027 retail mandates, compressing qualification timelines for uncertified challengers. For New Entrants and Emerging Players: Certification fast-track through Vietnam's Ministry of Natural Resources and Environment REACH alignment offers the most penetrable pathway for EU market access. Target Indonesia's Java-based food packaging sector, where minimal bioplastics penetration meets archipelago-scale waste management pressures without mandatory substitution frameworks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among agricultural-integrated compounders with captive starch supply chains and multi-year mulch film contracts. Long-term viability hinges on composting infrastructure buildout pace across secondary cities. Acquisition targets should demonstrate pre-qualified resin grades with 12-18 month certification validation completed. Revision becomes warranted when industrial composting facility deployment crosses thresholds that enable actual biodegradation rates for distributed packaging waste.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive sugarcane processing across Thailand's Rayong corridor secures lactic acid precursor supply against agricultural commodity volatility. |
| Compostability Certification Fast-Track | Pre-qualified resin grades align with Central Group and CP All procurement deadlines under Bangkok's mandatory biodegradable quotas. |
| EU REACH Framework Alignment | Vietnam's regulatory harmonization unlocks export certification pathways for domestic compounders targeting European retail chains. |
| Indonesian Market Entry | First-mover positioning in Java's food packaging sector exploits minimal bioplastics penetration despite waste management pressures. |
| High-Heat PLA Grade Development | Thermal performance advances decompose rigid PET's monopoly in Thai hot-fill juice bottling applications. |
Research Methodology
A spread of perspectives from fermentation plant managers, Japanese packaging investors, Thai retail procurement leads, and Vietnamese agricultural cooperative directors converged on the working assumptions that shape this analysis. Primary interviews with these stakeholders combined with secondary validation from Thailand's Pollution Control Department regulatory filings, Vietnam's Ministry of Natural Resources and Environment standards documentation, EU REACH framework texts, and ASEAN customs trade data. Bottom-up capacity assessments triangulated against top-down demand modeling from retail chain substitution mandates.
Segmentation dimensions modeled include product type tier, end-use application, manufacturing technology, and geographic production cluster across the analysis window. CAGRs were derived from capacity expansion timelines, regulatory mandate enforcement schedules, and feedstock price trajectory assumptions. Industry-specific forecast inputs incorporate fermentation infrastructure commissioning delays from polymer chemist scarcity and composting facility deployment rates in Bangkok versus Ho Chi Minh City.
Decision-makers should treat outputs as directional under assumptions of sustained Thai single-use plastic ban enforcement and Vietnamese REACH alignment completion; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside agricultural commodity price stability and industrial composting infrastructure investment continuity. Revision becomes warranted when petroleum-based resin cost advantages compress substitution rates below procurement mandate compliance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Global Bioplastic Market
Bioplastics
Biopolymers Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Biopolymer Films Market