
 Global Synthetic and Bio Based Polypropylene Market | 2026-2036
Global Synthetic and Bio Based Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Synthetic and Bio Based Polypropylene Market Foresight
Automotive lightweighting is recalibrating material specifications across interior and under-hood applications. Braskem leverages its Brazilian sugarcane feedstock chain to anchor bio-polypropylene supply for European OEMs. LyondellBasell Industries Holdings B.V. sustains technology leadership in metallocene catalysis for high-clarity packaging grades. Dow Inc. competes through integrated propylene production on the US Gulf Coast.
Synthetic and bio based polypropylene denotes thermoplastic polymers derived from petroleum refining or renewable biomass feedstocks, polymerized through catalytic processes to achieve melt flow indices between 0.3 and 3000 g/10 min for injection molding, fiber extrusion, or film casting applications. Homopolymer grades dominate rigid packaging and textile fiber markets where stiffness and heat resistance command premium pricing. Random copolymer formulations lead thin-wall food container applications, while bio-polypropylene remains supply-constrained despite Neste Oyj's renewable naphtha partnerships with European crackers. Metallocene catalysis is displacing Ziegler-Natta systems in specialty film segments where optical clarity and seal-strength consistency justify higher catalyst costs.
The EPA regulates volatile organic compound emissions from polypropylene resin production under Clean Air Act standards, while REACH mandates disclosure of additive substances exceeding 0.1% w/w in finished articles sold into Europe. China's MEE enforces dual carbon goals that incentivize bio-based feedstock trials at Sinopec subsidiaries. Stakeholders must monitor catalyst technology licensing costs and renewable feedstock certification schemes as margin structures diverge between fossil and bio-based production pathways.
Market Dynamics
Metallocene catalysis is fragmenting polymerization economics by enabling specialty-grade production at smaller scale, eroding the volume advantages historically held by Ziegler-Natta integrated complexes and redistributing margin capture toward technology licensors.
Growth Catalysts
- EU Green Deal automotive mandates:Brussels' binding recycled content thresholds for vehicle interiors are pulling bio-polypropylene through Tier 1 supplier specifications ahead of cost parity.
- Flexible packaging grade premiums:Metallocene-based random copolymers command pricing power in thin-wall food containers where optical clarity and seal consistency reduce downstream scrap rates.
- China MEE dual carbon enforcement:Provincial emissions intensity targets at Sinopec subsidiaries are accelerating pilot trials of renewable naphtha co-feeding at existing steam crackers.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker margins swing with crude differentials, compressing compounder hedging windows and amplifying working capital requirements.
- Bio-based certification fragmentation:Competing ISCC PLUS, RSB, and Bonsucro chain-of-custody standards create audit stacking costs that deter mid-volume converters from multi-sourcing.
- Homopolymer substitution pressure:Polylactic acid formulations are capturing premium rigid packaging niches where heat resistance requirements sit below polypropylene thresholds.
Strategic Opportunities
- India BIS standards harmonization:Pending alignment of food-contact migration limits with Codex Alimentarius would unlock import substitution for random copolymer container grades currently sourced from Southeast Asia.
- Chemical recycling integration:Pyrolysis oil purification technologies reaching commercial scale in Rotterdam and Houston are creating circular propylene feedstock pools outside fossil value chains.
- Direct-to-brand polymer sales:E-commerce packaging specifications from Amazon and Alibaba are bypassing traditional distributor networks, enabling margin capture by producers with formulation agility.
Industry Challenges
- Metallocene licensing concentration:Patent thickets around single-site catalyst architectures limit technology access to three incumbent licensors, constraining independent producer R&D pathways.
- REACH SCIP database compliance:Article 33 disclosure obligations for substances of very high concern are forcing resin compounders to reconfigure additive packages and revalidate customer formulations.
- Skilled catalysis engineer scarcity:Retirement waves at European and North American polymer research centers are narrowing the talent pipeline for next-generation Ziegler-Natta process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Synthetic and Bio Based Polypropylene Market |
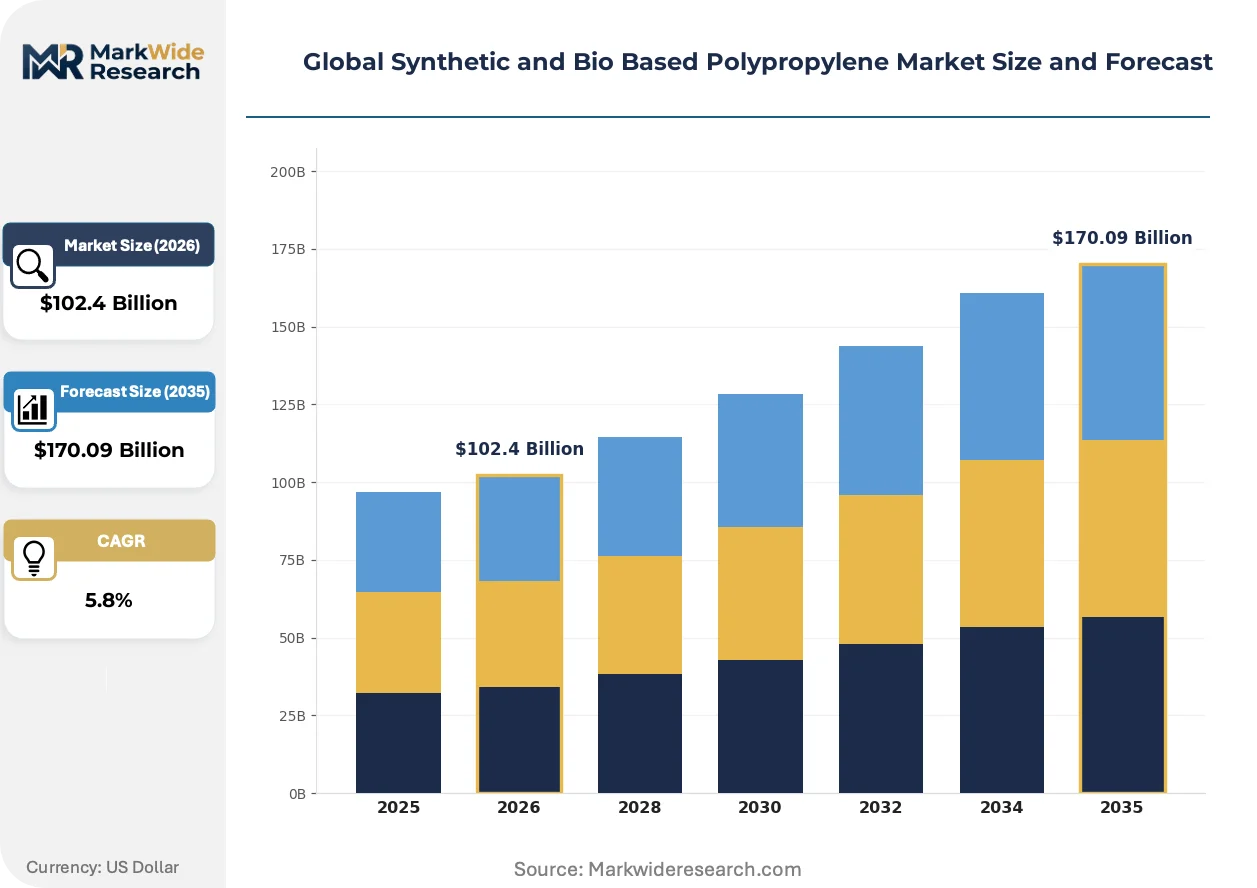
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $170.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Random Copolymer, Impact Copolymer, Bio-Polypropylene Application: Packaging Films, Automotive Components, Consumer Goods, Electrical Appliances End User Industry: Consumer Electronics, Construction, Agriculture Equipment, Household Products Technology: Metallocene Catalysis, Ziegler-Natta Catalysts, Gas Phase Polymerization, Solution Polymerization |
| Companies Covered | Braskem, Dow Inc., Borealis AG, LyondellBasell Industries Holdings B.V., TotalEnergies, SABIC, Mitsui Chemicals, Inc., Neste Oyj, INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Synthetic and Bio Based Polypropylene Market Shifts & Advancements
Process intensification and molecular design tools are compressing development cycles for specialty grades, while regulatory disclosure requirements are embedding traceability infrastructure into supply chain operations.
Single-reactor metallocene systems are decentralizing production economics by enabling rapid grade transitions without catalyst changeover downtime. Regional compounders in Poland and Thailand are adopting these systems to serve just-in-time orders from medical device molders. The technology is decentralizing volume concentration away from mega-complexes toward distributed, specialty-focused assets.
REACH SCIP database obligations are forcing resin suppliers to map additive substances across complex formulation hierarchies. The regulation is compressing formulation flexibility as compounders pre-certify packages against anticipated SVHC candidate list expansions. Medical packaging converters in Germany are responding by consolidating supplier bases to reduce audit surface area.
Brand-led sustainable packaging commitments are compressing traditional distributor intermediation. Major food retailers in France and the United Kingdom are issuing direct polymer specifications to producers, bypassing historical compounder relationships. This disintermediation is most visible in rigid dairy container applications where recycled content claims require chain-of-custody documentation that distributors cannot reliably provide.
Global Synthetic and Bio Based Polypropylene Market Segmentation
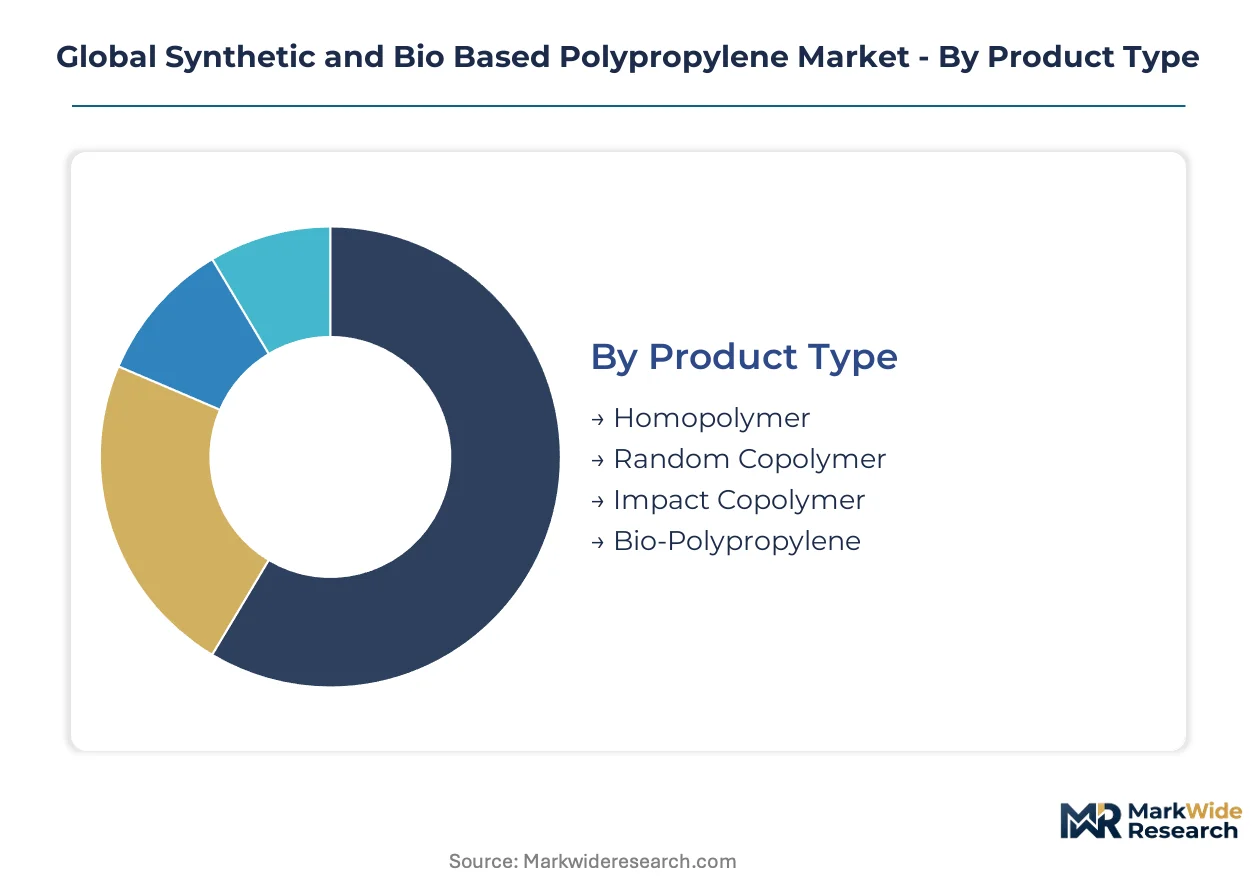
Polypropylene segmentation reveals divergent margin structures across catalytic pathways and end-use specifications. Buyers prioritize melt flow indices, thermal stability, and regulatory compliance credentials depending on application criticality.
Product Type:
Cost tiers separate commodity converters from specialty compounders seeking performance premiums.
- Homopolymer:High crystallinity grades deliver stiffness and heat resistance for rigid packaging and textile fibers. Demand concentrates in China's flexible packaging sector as domestic converters scale metallocene-grade production to reduce import dependency.
- Random Copolymer:Ethylene-modified chains achieve optical clarity and seal strength for thin-wall food containers. European dairy packaging specifications are pulling random copolymer volumes ahead of homopolymer substitution threats from polylactic acid formulations.
- Impact Copolymer:Rubber-toughened structures balance stiffness with low-temperature ductility for automotive bumpers and appliance housings.
- Bio-Polypropylene:ISCC PLUS-certified grades from sugarcane naphtha remain supply-constrained despite Braskem's Brazilian feedstock integration.
Homopolymer leads volumes today; bio-polypropylene is gaining share fastest.
Application:
Application selection dictates catalytic technology requirements and certification burdens.
- Packaging Films:Biaxially oriented structures demand precise thickness control and seal-layer consistency. Metallocene-based random copolymers command pricing power where optical clarity reduces downstream scrap rates in German medical packaging lines.
- Automotive Components:Interior trim and under-hood applications face EU Green Deal recycled content mandates. Brussels' binding thresholds are pulling bio-polypropylene through Tier 1 supplier specifications ahead of cost parity.
- Consumer Goods:Durable housewares and furniture components prioritize impact resistance and UV stability for outdoor exposure.
- Electrical Appliances:Flame-retardant compounded grades serve connector housings and cable insulation with UL94 V-0 certification requirements.
Packaging films dominate revenue today; automotive components show the steepest expansion trajectory.
End User Industry:
Industry selection determines formulation complexity and regulatory audit depth.
- Consumer Electronics:Miniaturized connector housings and structural frames require tight dimensional tolerance and halogen-free flame retardancy. REACH SCIP database obligations are forcing resin compounders to reconfigure additive packages for smartphone manufacturers assembling in Poland.
- Construction:Geotextiles and vapor barrier membranes prioritize UV stabilization and tensile strength for infrastructure longevity.
- Agriculture Equipment:UV-resistant twine and greenhouse films face seasonal demand volatility tied to planting cycles.
- Household Products:Storage containers and furniture components balance aesthetics with dishwasher-safe thermal resistance.
Consumer electronics leads value capture today; construction is expanding most quickly.
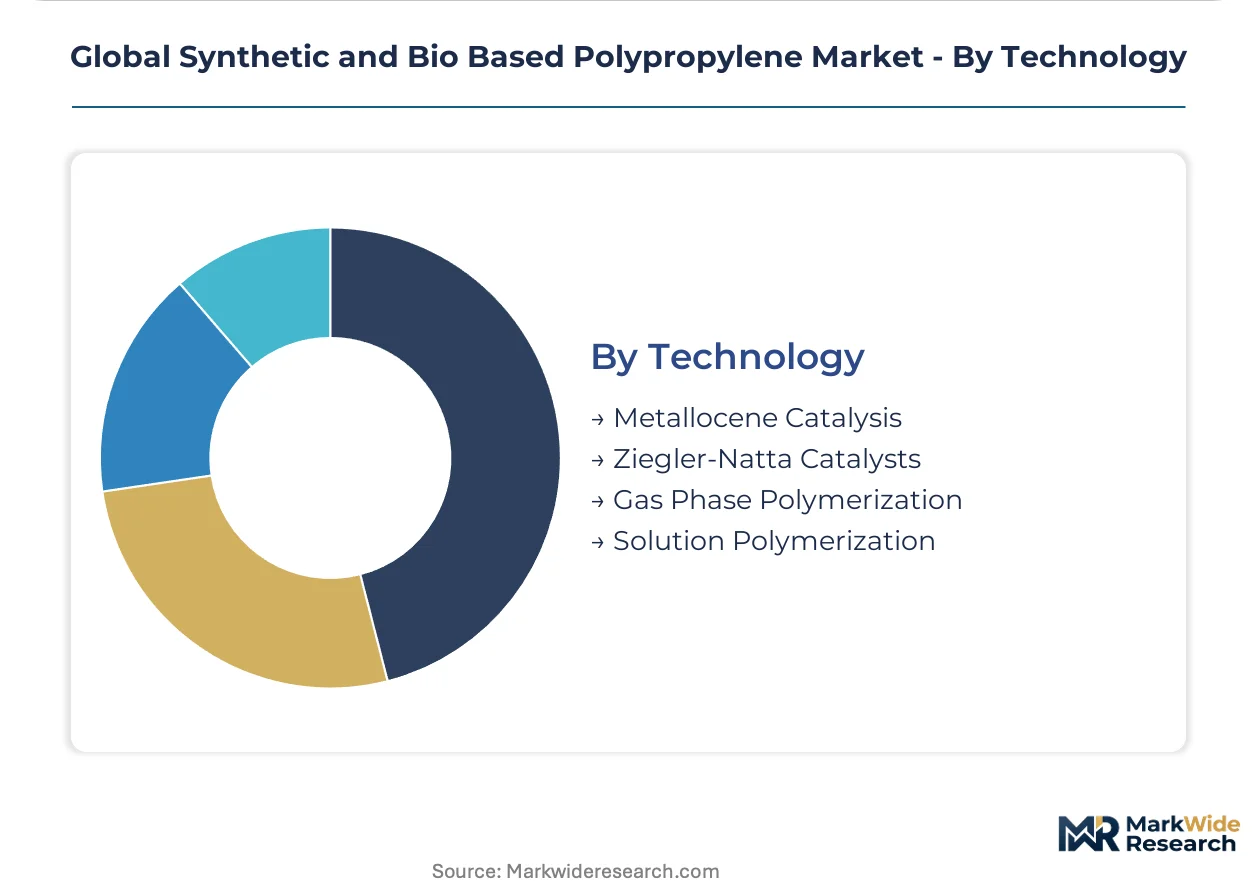
Technology:
Technology choice fragments capital intensity and licensing access across producer scale tiers.
- Metallocene Catalysis:Single-site catalysts enable narrow molecular weight distribution for specialty film and medical grades. Patent thickets around single-site architectures limit technology access to three incumbent licensors, constraining independent producer R&D pathways.
- Ziegler-Natta Catalysts:Multi-site systems dominate commodity homopolymer production with lower catalyst costs but broader polydispersity.
- Gas Phase Polymerization:Fluidized bed reactors achieve high throughput with reduced solvent recovery burdens for bulk homopolymer output.
- Solution Polymerization:Dissolved-phase systems enable precise comonomer incorporation for specialty random copolymers at smaller scale.
Ziegler-Natta leads installed capacity today; metallocene catalysis is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing polypropylene production capacity toward jurisdictions with lower carbon-compliance burdens and cheaper feedstock access. Producers are relocating steam cracker investments to evade EU carbon border adjustments while capturing US shale gas economics.
United States
Gulf Coast petrochemical clusters exploit abundant shale-derived propane feedstock for propylene production. EPA Clean Air Act standards on volatile organic compound emissions shape plant design specifications for new crackers. Houston-area integrated complexes are expanding metallocene-grade capacity to serve medical packaging converters in the Midwest.
China
Domestic converters scale metallocene-grade production for flexible packaging applications, reducing import dependency on South Korean and Singaporean suppliers. MEE dual carbon enforcement at Sinopec subsidiaries accelerates renewable naphtha co-feeding trials at existing steam crackers. Yangtze River Delta chemical parks concentrate new polymerization capacity serving e-commerce packaging demand.
Germany
Automotive interior specifications under EU Green Deal recycled content mandates pull bio-polypropylene through Tier 1 supplier networks. REACH Article 33 SCIP database obligations force resin compounders to reconfigure additive packages and revalidate customer formulations. Ruhr Valley chemical sites face feedstock cost pressure from Russian naphtha supply disruptions.
Brazil
Braskem leverages sugarcane ethanol feedstock integration to anchor bio-polypropylene supply for European OEMs seeking ISCC PLUS certification. National biofuel policy frameworks under ANP regulation sustain ethanol pricing advantages over fossil naphtha. São Paulo-state petrochemical complexes serve as the primary export hub for renewable-grade polymer.
Saudi Arabia
SABIC operates integrated propane dehydrogenation complexes with access to subsidized domestic feedstock. The kingdom's industrial diversification programs under Vision 2030 incentivize downstream polymer conversion investments. Jubail Industrial City hosts expanding compounding capacity targeting African and South Asian export markets.
Global Synthetic and Bio Based Polypropylene Market Competitive Landscape
Capacity expansion dominates the current landscape as producers race to capture metallocene-grade premiums before technology licensing windows narrow. The vendor base clusters around three strategic tiers: integrated petrochemical majors with captive propylene supply, technology licensors controlling single-site catalyst patents, and regional compounders serving just-in-time specialty orders. Competitive positioning hinges on feedstock integration depth, catalyst technology access, and renewable certification credibility. M&A activity concentrates on pyrolysis oil purification assets, while strategic partnerships proliferate between resin producers and brand-led sustainable packaging coalitions.
Among integrated petrochemical majors, Braskem, Dow Inc., and LyondellBasell Industries Holdings B.V. exemplify divergent strategic archetypes. Braskem occupies a position as the reference point for bio-based feedstock integration, anchoring renewable-grade supply through Brazilian sugarcane value chain control. Dow Inc. represents Gulf Coast shale gas economics, with its geographic namesake indicating feedstock access advantages. LyondellBasell Industries Holdings B.V. sits within the technology-licensor tier, its Dutch corporate structure signaling European regulatory compliance capabilities and metallocene catalyst expertise. These three entities collectively illustrate how feedstock geography, renewable certification, and catalytic technology access fragment competitive positioning across the industry.
| Leading Market Players |
|---|
| Braskem |
| Dow Inc. |
| Borealis AG |
| LyondellBasell Industries Holdings B.V. |
| TotalEnergies |
| SABIC |
| Mitsui Chemicals, Inc. |
| Neste Oyj |
| INEOS |
| Others |
Supply & Pricing Matrix
Propylene feedstock costs from naphtha crackers and PDH units cascade through three pricing tiers, with metallocene-grade premiums widening as catalyst licensing fees concentrate margin capture among technology holders serving European medical packaging converters.
Pricing Analysis
Distributor margins compress in commodity homopolymer grades where Chinese domestic production scales erode historical import premiums. Three-tier pricing structure across specialty metallocene, certified bio-based, and commodity Ziegler-Natta grades separates buyers by formulation complexity and regulatory documentation burden. Pricing pressure stems from renewable naphtha co-feeding trials at Sinopec subsidiaries expanding supply elasticity. Small-volume medical device molders in Poland exhibit highest price sensitivity due to working capital constraints, while German automotive Tier 1 suppliers accept bio-polypropylene premiums to secure EU Green Deal compliance documentation.
Supply Chain Analysis
Catalyst supply rests on three incumbent licensors controlling single-site metallocene patent architectures, constraining independent producer access to premium-grade production economics. Propylene monomer concentrates in China, the United States, and Saudi Arabia, with feedstock sourcing from shale gas, naphtha cracking, and PDH units respectively. Logistics chokepoints at Rotterdam and Houston pyrolysis oil purification hubs threaten circular feedstock scalability. Distribution runs through regional compounders in Poland and Thailand serving just-in-time orders from medical device and flexible packaging converters, bypassing traditional distributor networks for direct brand specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as automotive lightweighting mandates and flexible packaging grade premiums sustain demand expansion across multiple end-use verticals.
For Market Incumbents: To counter metallocene licensing concentration among three technology holders, secure backward integration into renewable naphtha supply through partnerships with Neste Oyj or comparable bio-feedstock refiners. Add compounding capacity in the Yangtze River Delta to capture e-commerce packaging demand from Alibaba and domestic brand direct specifications. Invest in ISCC PLUS certification infrastructure to defend margin position as EU Green Deal recycled content thresholds tighten. For New Entrants and Emerging Players: Regional compounders in India offer the most penetrable entry point pending BIS food-contact migration limit harmonization with Codex Alimentarius standards. Target medical packaging converters in Germany seeking reduced supplier audit surface area under REACH SCIP database obligations. Partner with pyrolysis oil purification technology developers in Rotterdam or Houston to establish circular propylene feedstock credentials outside fossil value chains. For Investors and Strategic Acquirers: Roll-up economics work for regional specialty compounders with metallocene reactor assets and established medical device molder relationships because single-reactor systems enable rapid grade transitions without catalyst changeover downtime. Platform consolidation targets compounders in Poland and Thailand serving just-in-time orders with ISCC PLUS or comparable bio-certification. Watch for inflection when chemical recycling integration reaches commercial scale at Rotterdam and Houston hubs, signaling circular feedstock pool viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock | Braskem's sugarcane naphtha chain demonstrates margin protection against fossil propylene volatility. |
| Metallocene Capacity Expansion | LyondellBasell's catalyst licensing sustains premium capture in German medical packaging segments. |
| Chemical Recycling Integration | Pyrolysis oil purification at Rotterdam creates circular propylene pools outside conventional supply chains. |
| Direct-to-Brand Polymer Sales | Amazon and Alibaba e-commerce specifications bypass distributor intermediation for formulation-agile producers. |
| ISCC PLUS Certification Investment | European OEM procurement mandates pull certified bio-polypropylene through Tier 1 supplier networks. |
Research Methodology
Multiple input streams — primary interviews with polymer plant managers, procurement leads at automotive Tier 1 suppliers, and distribution channel partners in Europe and Asia-Pacific — were reconciled against secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up volume modeling across grade tiers and end-use applications was cross-referenced with top-down macroeconomic indicators to establish market sizing boundaries.
Historical capacity utilization patterns were cross-referenced against expert panel input from catalysis engineers and resin compounders to derive expansion trajectories across the analysis window. Segmentation dimensions modeled include catalytic technology pathway, polymer grade specification, end-use industry vertical, and regional production hub clustering. CAGRs reflect weighted averages of demand elasticity coefficients and feedstock cost projection scenarios, with specific sensitivity to metallocene licensing fee structures and renewable naphtha premium differentials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation timing and Chinese MEE dual carbon enforcement intensity. Forecasts reflect documented assumptions regarding catalyst technology diffusion rates and bio-feedstock certification scheme harmonization. A small set of triggers — REACH SCIP database expansion, pyrolysis oil purification commercialization, and India BIS standards alignment — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biopolymers Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
US Bioplastics Market
Bioplastics
Cellulose Bioplastic Market