
 Automotive Bioplastic Market | 2026-2036
Automotive Bioplastic Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bioplastic Market Intelligence
ISO 14021 environmental self-declaration compliance is rotating as a baseline qualification for Tier-1 supplier status across European and North American automotive programs. BASF leverages its integrated polyamide R&D pipeline to anchor technical partnerships with German OEM sustainability roadmaps. NatureWorks LLC specializes in high-purity PLA resin architectures that compete on thermal performance against conventional petroleum-based interior substrates. Braskem controls captive bio-ethylene supply chains that extend cost predictability for starch blend formulations.
Automotive bioplastics comprise thermoplastic resins derived from annually renewable biomass feedstocks including corn starch, sugarcane bagasse, and microbial fermentation outputs, formulated to achieve heat deflection temperatures exceeding 100°C for underhood durability requirements. Their primary industrial purpose centers on reducing cradle-to-gate carbon intensity in vehicle mass production while maintaining crashworthiness and surface finish specifications comparable to fossil-derived counterparts. PLA formulations dominate current interior panel applications where lower thermal loads permit glass transition temperature limitations, while polyamide segments command premium positioning in underhood connectors and cooling system housings where hydrolysis resistance proves critical. Injection molding infrastructure absorbs the majority of processing capital as OEMs retrofit existing tool cavities for bioplastic melt flow characteristics rather than commissioning entirely new thermoforming lines.
The EPA's renewable fuel standard pathways and REACH bio-based substance registration requirements collectively shape material qualification timelines and cross-border market access protocols for compounders serving multinational vehicle platforms. Japan's METI has established bioplastic content benchmarks for domestic automotive procurement that mirror EU regulatory stringency, creating dual compliance obligations for suppliers with transcontinental manufacturing footprints. Stakeholders must monitor feedstock price volatility in agricultural commodity markets and pre-emptively qualify second-generation cellulose-derived intermediates before first-generation starch economics deteriorate.
Market Dynamics
EU Green Deal material circularity mandates are compressing bio-based feedstock qualification timelines from 36 months to 18 months, forcing compounders to accelerate polymer validation cycles while maintaining thermal performance benchmarks for underhood applications.
Growth Catalysts
- REACH bio-based substance registration:European chemical compliance frameworks now fast-track automotive bioplastic approvals, reducing regulatory friction for starch-derived polyamide formulations entering German OEM supply chains.
- Interior panel lightweighting:PLA-glass fiber composites are displacing ABS in dashboard substrates where cabin sustainability targets drive material substitution at Volkswagen, BMW, and Mercedes-Benz program offices.
- Japan METI procurement benchmarks:Domestic automotive content mandates mirror EU stringency, creating dual-qualification incentives for suppliers operating transcontinental manufacturing footprints.
Market Restraints
- Corn starch price volatility:Agricultural commodity futures expose first-generation bioplastic producers to margin compression when feedstock costs spike during planting season disruptions.
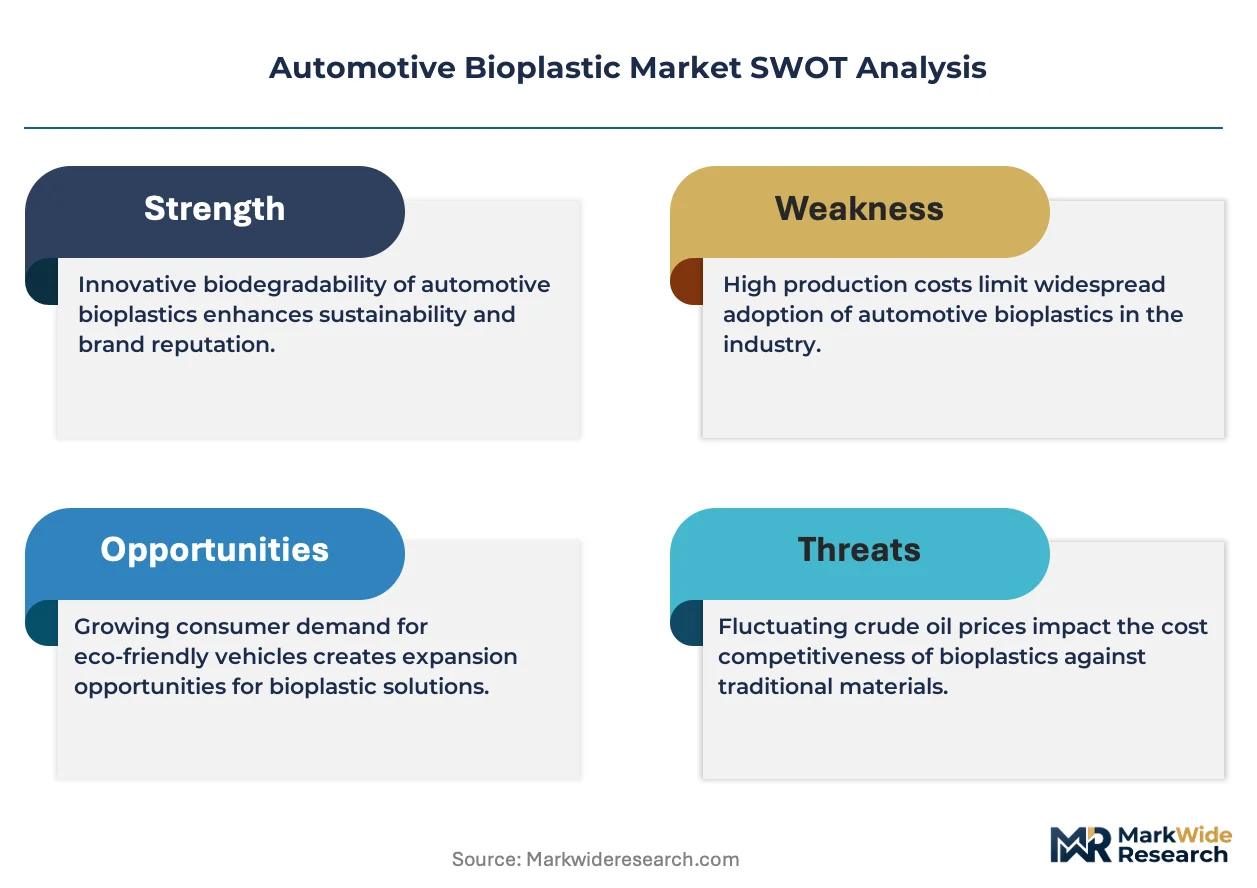
- Hydrolysis resistance limitations:PLA glass transition temperatures below 60°C exclude the material from cooling system housings and underhood connectors where polyamide commands premium positioning.
- Injection molding retrofit costs:Existing tool cavity modifications for bioplastic melt flow characteristics absorb capital that OEMs divert from entirely new thermoforming line commissioning.
Strategic Opportunities
- Second-generation cellulose intermediates:Agricultural residue feedstocks from sugarcane bagasse and wheat straw offer cost predictability before first-generation starch economics deteriorate.
- EPA renewable fuel standard pathways:US regulatory credit structures incentivize bio-ethylene production for starch blend formulations serving Detroit Three sustainability roadmaps.
- Microbial fermentation outputs:Engineered bacterial polymer precursors enable novel polyhydroxyalkanoate architectures with heat deflection temperatures exceeding conventional PLA limitations.
Industry Challenges
- ISO 14021 environmental self-declaration complexity:Tier-1 suppliers face documentation burdens proving cradle-to-gate carbon intensity reductions without standardized third-party verification protocols.
- Cross-border qualification timeline misalignment:Japanese OEMs demand 12-month validation cycles while European programs tolerate 24-month windows, straining compounder R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bioplastic Market |
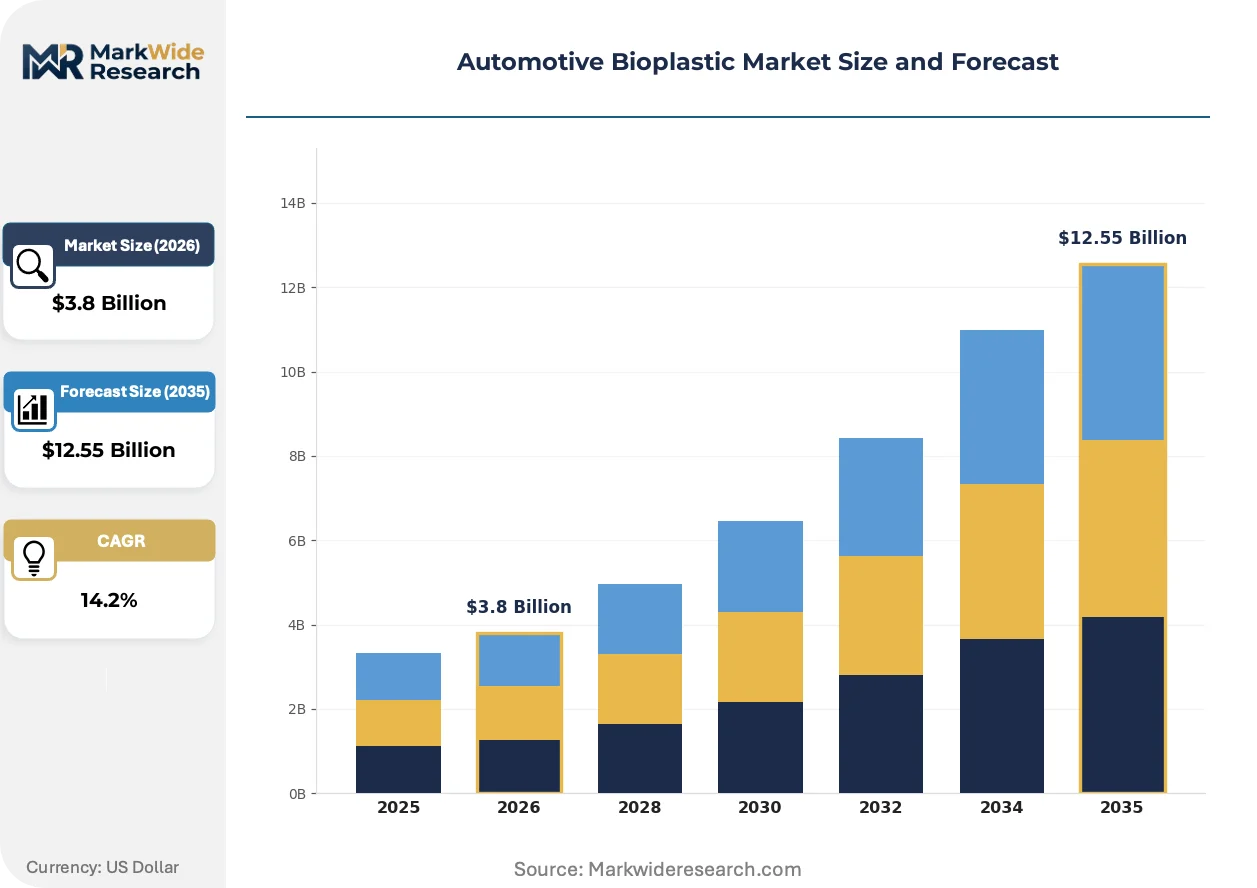
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Polyamide Application: Interior, Exterior, Underhood, Others End User: OEMs, Tier-1 Suppliers, Aftermarket Services, Vehicle Assemblers Manufacturing Stage: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | Arkema, Toray Industries, BASF, Solvay, Covestro AG, NatureWorks LLC, Mitsubishi Chemical Corporation, DuPont, Braskem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bioplastic Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization efforts are converging to redefine automotive polymer specifications. Three developments are compressing traditional petroleum-based supply relationships.
High-purity PLA resin architectures with tailored crystallinity profiles are supplanting conventional petroleum-based interior substrates in door panel and trim applications. German OEM sustainability procurement teams now specify bio-based content minimums of 30 percent for non-structural cabin components. This substitution is compressing ABS and polycarbonate compounder margins in European passenger vehicle programs.
EU Green Deal circular economy action plan implementation timelines are accelerating bio-based material mandates across automotive value chains. The regulation requires 25 percent recycled or renewable content in plastic automotive components by 2030. Polyamide segments serving underhood applications face the steepest compliance ramps as cooling system housings fall under scope expansion proposals.
Fleet sustainability scorecards now weight supplier bioplastic content in contract renewal decisions. Procurement teams at Stellantis and Ford Motor Company have unbundled material origin verification from traditional price-volume negotiations. This behavioral shift is most visible in North American light truck programs where EPA fuel economy credits intersect with supply chain decarbonization targets.
Automotive Bioplastic Market Segmentation
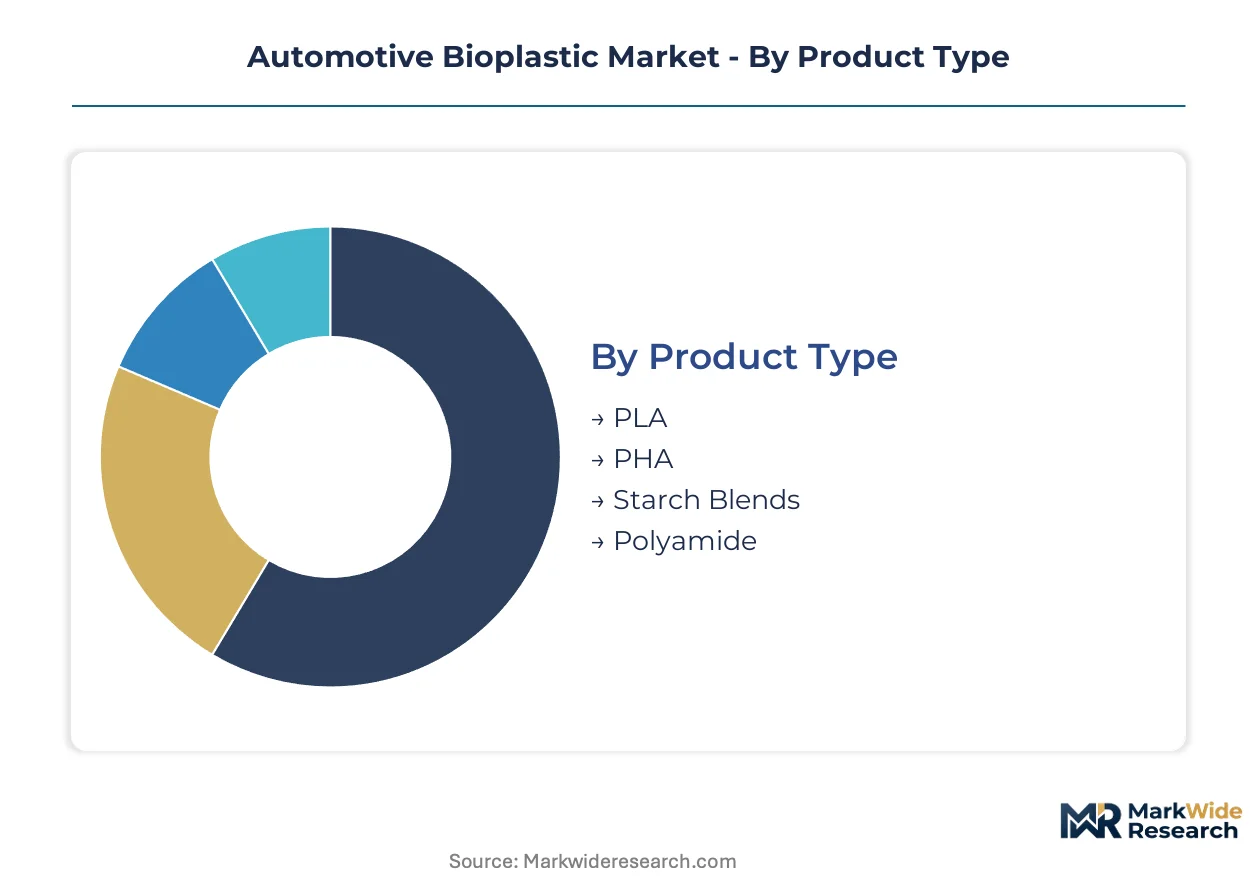
Automotive bioplastic procurement decisions cascade through four intersecting dimensions. Product chemistry determines thermal performance ceilings. Application location dictates hydrolysis resistance requirements. Manufacturing stage compatibility governs capital retrofit economics.
Product Type:
Margin pools concentrate in polyamide formulations where heat deflection specifications command premium positioning against petroleum-based alternatives.
- Polyamide:Engineered bio-based polyamides achieve heat deflection temperatures exceeding 150°C through long-chain fatty acid polymerization from castor oil feedstocks. German OEM cooling system programs at BMW and Mercedes-Benz specify these grades for underhood connectors where hydrolysis resistance proves critical.
- PLA:Polylactic acid resins derived from corn starch fermentation offer glass transition temperatures of 55-60°C, constraining deployment to interior panels and door trim where cabin thermal loads remain moderate. Volkswagen sustainability procurement teams now mandate minimum bio-based content thresholds for dashboard substrates using PLA-glass fiber composites.
- PHA:Polyhydroxyalkanoates from microbial fermentation deliver biodegradable characteristics with inferior thermal stability versus polyamide, finding niche adoption in disposable interior trim components.
- Starch Blends:Thermoplastic starch compounds from cassava or potato sources provide cost-competitive options for non-structural applications with limited durability requirements.
The dominant share belongs to PLA, while polyamide is closing the gap fastest.
Application:
Application segmentation tracks thermal load severity and regulatory exposure across vehicle zones.
- Interior:Door panels, dashboard substrates, and trim components absorb the majority of PLA and starch blend volumes where cabin sustainability targets drive material substitution. EU Green Deal circularity mandates now require bio-based content verification for these components entering German and French OEM supply chains.
- Underhood:Cooling system housings, connectors, and sensor brackets demand polyamide grades with hydrolysis resistance and continuous-use temperatures above 120°C. REACH bio-based substance registration fast-tracks approvals for these high-performance formulations.
- Exterior:Bumper fascias and body trim pieces face UV degradation challenges that limit current bioplastic penetration pending stabilizer package advances.
- Others:Fuel system components and acoustic insulation represent emerging qualification targets with stringent permeation and flame-retardancy specifications.
Interior applications command volume leadership, while underhood segments are expanding most quickly.
End User:
Customer type determines specification authority and contract structure complexity.
- OEMs:Volkswagen, Stellantis, and Ford Motor Company sustainability procurement teams now unbundle material origin verification from price-volume negotiations, weighting bioplastic content in fleet scorecard assessments.
- Tier-1 Suppliers:Interior component manufacturers face ISO 14021 environmental self-declaration documentation burdens to maintain program status with European and North American automotive clients.
- Vehicle Assemblers:Contract manufacturing operations adopt bioplastic specifications dictated by brand-owner sustainability roadmaps with limited independent sourcing authority.
- Aftermarket Services:Repair and replacement part distributors represent price-sensitive demand with minimal bio-based material premiums.
OEMs retain specification control, while Tier-1 suppliers are gaining sourcing influence fastest.
Manufacturing Stage:
Processing method selection hinges on existing capital deployment and melt flow adaptation costs.
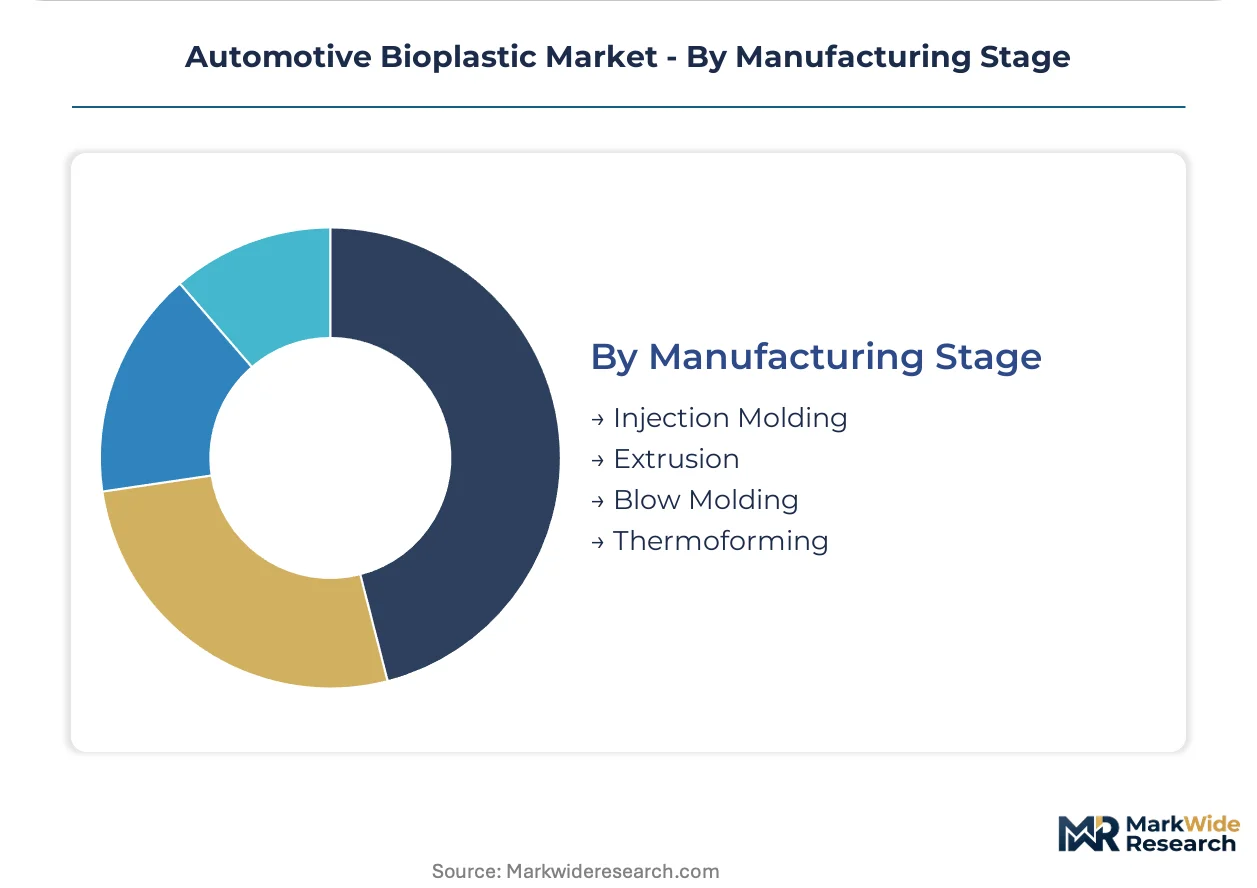
- Injection Molding:Existing tool cavity modifications for bioplastic shear sensitivity and crystallization kinetics absorb the majority of OEM processing capital rather than greenfield thermoforming line commissioning. German and Japanese Tier-1 suppliers dominate retrofit expertise.
- Extrusion:Profile and sheet production for interior panel substrates requires screw design adjustments to manage PLA moisture sensitivity during melt processing.
- Blow Molding:Hollow component fabrication for fluid reservoirs and ducts remains limited by bioplastic parison sag and wall thickness control challenges.
- Thermoforming:Vacuum and pressure forming of extruded sheet for large interior panels offers lower tooling costs but constrained design complexity versus injection molding.
Injection molding holds installed base dominance, while extrusion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's bio-based chemical handling infrastructure anchors European bioplastic feedstock flows, while the Houston Ship Channel's petrochemical corridor enables North American bio-ethylene distribution networks serving automotive compounders.
United States
Detroit Three sustainability procurement teams drive bio-based content mandates in light truck and SUV programs. EPA renewable fuel standard pathways incentivize bio-ethylene production for starch blend formulations. Michigan's automotive corridor hosts Tier-1 supplier retrofit operations adapting injection molding infrastructure for PLA-glass fiber composites.
Germany
BMW, Mercedes-Benz, and Volkswagen sustainability roadmaps specify minimum bio-based thresholds for interior cabin components. EU Green Deal circular economy mandates compress material qualification timelines to 18 months. The Rhine-Ruhr industrial belt concentrates polyamide compounding operations serving underhood cooling system applications.
Japan
Domestic OEM procurement offices enforce METI bioplastic content benchmarks matching EU regulatory stringency. JIS standards govern thermal performance verification for polyamide grades in connector applications. The Nagoya-Toyota industrial corridor anchors microbial fermentation R&D for novel polyhydroxyalkanoate architectures.
Brazil
Sugarcane bagasse residue streams offer second-generation cellulose feedstock cost predictability versus first-generation starch economics. Braskem's captive bio-ethylene supply chains extend from São Paulo state plantation networks. The Campinas technology cluster hosts fermentation-based polymer precursor development for export-qualified automotive grades.
China
Dual carbon policy targets accelerate domestic OEM bioplastic qualification for NEV interior applications. MIIT standards govern bio-based content verification in supplier certification protocols. The Yangtze River Delta automotive manufacturing belt pilots PLA dashboard substrate production for European export programs.
Automotive Bioplastic Market Key Industry Players
Listed leaders compete with private specialists across integrated versus modular supply chain architectures. The vendor base clusters around three strategic archetypes: diversified chemical conglomerates with captive feedstock operations, pure-play biopolymer specialists with fermentation-based technology platforms, and regional compounders serving single-geography OEM programs. Capacity expansion and backward integration into agricultural residue processing represent the dominant competitive vectors as qualification timelines compress.
Within the diversified chemical tier, BASF and Covestro AG exemplify integrated polyamide R&D pipelines anchored to German OEM sustainability roadmaps. NatureWorks LLC occupies a specialist position as a pure-play PLA resin architect competing on thermal performance against petroleum-based interior substrates. Braskem represents the feedstock-integrated archetype through captive bio-ethylene supply chains extending cost predictability for starch blend formulations.
| Leading Market Players |
|---|
| Arkema |
| Toray Industries |
| BASF |
| Solvay |
| Covestro AG |
| NatureWorks LLC |
| Mitsubishi Chemical Corporation |
| DuPont |
| Braskem |
| Others |
Cost & Logistics Intelligence
ISO 14021 environmental self-declaration compliance gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified compounders while allowing verified producers to command bio-based content premiums in German and Japanese OEM procurement programs.
Pricing Analysis
Volume-discount tiering structures separate certified polyamide grades for underhood applications from uncertified PLA formulations in interior panels. Three-tier pricing stratifies across REACH-registered premium grades, ISO-compliant standard tiers, and economy starch blends lacking third-party verification. Cost compression in first-generation corn starch feedstocks is intensifying because agricultural commodity futures expose producers to planting season disruptions. Aftermarket service distributors exhibit highest price sensitivity, while BMW and Mercedes-Benz sustainability procurement teams absorb bio-based premiums without volume negotiation leverage.
Supply Chain Analysis
The Port of Rotterdam's bio-based chemical handling infrastructure anchors European feedstock flows, creating a chokepoint where customs delays cascade through German Tier-1 supplier schedules. Manufacturing concentrates in Germany, Brazil, and Japan, with Braskem's São Paulo bio-ethylene operations and BASF's Ludwigshafen polyamide compounding serving as anchor nodes. Raw material dependencies rest on castor oil derivatives, sugarcane bagasse cellulose, and microbial fermentation outputs. Single-source vulnerability in agricultural residue preprocessing equipment threatens second-generation feedstock scaling. Distribution runs through captive OEM supply agreements rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through OEM sustainability procurement team consolidation, with Volkswagen, Stellantis, and Ford Motor Company unbundling material origin verification from traditional price-volume negotiations to compress supplier margins.
For Market Incumbents: Shield polyamide margin pools by accelerating backward integration into castor oil feedstock cultivation before second-generation cellulose intermediates erode cost advantages. Prioritize REACH bio-based substance registration fast-tracks for underhood cooling system grades to lock out PLA substitutes in high-temperature applications. Defend against microbial fermentation entrants by securing exclusive German OEM technical partnership extensions. For New Entrants and Emerging Players: METI bioplastic content benchmark compliance creates a certification fast-track for suppliers targeting Japanese domestic OEM procurement offices with polyhydroxyalkanoate architectures. The most penetrable white space sits in disposable interior trim components where biodegradability commands sustainability scorecard weighting. A go-to-market angle through Nagoya-Toyota industrial corridor microbial fermentation R&D partnerships bypasses established PLA incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pure-play biopolymer specialists lacking captive feedstock operations. Long-term viability hinges on qualification timeline compression capabilities as EU Green Deal mandates compress validation windows. The acquisition target archetype is regional compounders with backward integration into agricultural residue preprocessing. The signal to watch is Japanese OEM validation cycle harmonization with European programs as inflection indicator for transcontinental manufacturing footprint premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Processing | Braskem's São Paulo plantation networks demonstrate cost predictability for starch blend formulations. |
| REACH Bio-based Substance Registration Fast-Track | ECHA compliance frameworks accelerate polyamide approvals for German OEM cooling system programs. |
| Joint Venture with Microbial Fermentation Platform | Nagoya-Toyota corridor R&D partnerships enable novel polyhydroxyalkanoate architectures exceeding PLA thermal limits. |
| Long-term Supply Agreement with Castor Oil Cultivators | BMW and Mercedes-Benz underhood connector specifications anchor bio-based polyamide demand. |
| Capacity Expansion in Rhine-Ruhr Industrial Belt | German OEM sustainability roadmaps specify minimum bio-based thresholds compressing regional supply gaps. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations heads; and secondary validation through customs/trade data, ACC/Cefic chemical industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up triangulation across injection molding retrofit capital expenditure disclosures and top-down reconciliation with bio-based content mandate implementation timelines anchored volume and value estimates.
Across the analysis window, the forecast framework modeled segmentation dimensions including product chemistry tier, application thermal load severity, end-user specification authority, and manufacturing stage capital intensity. CAGRs derived from regression analysis of historical qualification timeline compression and feedstock price elasticity coefficients. Industry-specific inputs incorporated EPA renewable fuel standard credit structures and METI procurement benchmark adoption curves.
Underlying assumptions cover EU Green Deal circular economy mandate implementation pace and agricultural commodity price stability, with deviation risk concentrated in corn starch futures volatility and second-generation cellulose intermediate scale-up delays. Practitioners should keep alternative scenarios live as Japanese-European regulatory harmonization timelines and microbial fermentation yield improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Bioplastic Textile Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
US Bioplastics Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Starch Blended Biodegradable Polymer Market
Bioplastics
Asia-Pacific Lactic Acid Market