
 Cellulose Ether and Derivatives Market | 2026-2036
Cellulose Ether and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Ether and Derivatives Market Outlook
Aftermarket formulation services is tilting margin pools away from commodity-grade cellulose ethers toward application-specific blends. The Dow Chemical Company leverages its integrated propylene oxide supply chain to control feedstock costs for hydroxypropyl methylcellulose production. Ashland Global Holdings, Inc. anchors its position through pharmaceutical-grade excipient certifications that command premium pricing in oral solid dosage applications. Nouryon Chemicals Holdings B.V. competes on construction-sector technical service depth across European building chemistry accounts.
Cellulose ethers comprise cellulose polymers modified through etherification with alkyl or hydroxyalkyl substituents, yielding water-soluble or organosoluble derivatives with controlled viscosity profiles and thermal gelation behavior; these properties make them indispensable as rheology modifiers, binders, and controlled-release matrices across construction, pharmaceutical, and personal care systems. Hydroxypropyl methylcellulose dominates pharmaceutical tablet coating and ophthalmic formulations where film-forming precision and dissolution control determine product performance. Carboxymethylcellulose occupies mature positions in food stabilization and oilfield drilling fluids, while methylcellulose extends into construction-grade tile adhesives and cement plasters where water retention governs open-time and bond strength.
EMA pharmaceutical excipient guidelines, EPA TSCA chemical substance notifications, and REACH Annex XIV authorization requirements collectively elevate purity documentation and supply-chain traceability obligations for cellulose ether manufacturers serving regulated end uses. FDA excipient qualification pathways for inhalation and parenteral applications impose additional toxicological testing burdens that favor suppliers with dedicated pharmaceutical-grade manufacturing suites. Stakeholders must monitor evolving biopharma manufacturing trends toward continuous processing, as these platforms demand cellulose derivatives with narrower particle-size distributions and batch-to-batch consistency thresholds that strain conventional production assets.
Market Dynamics
REACH Annex XIV authorization requirements and tightening VOC standards across industrialized economies are redirecting formulation chemistry toward water-soluble cellulose derivatives, compressing demand for solvent-based alternatives while elevating purity documentation burdens across construction, pharmaceutical, and personal care supply chains.
Growth Catalysts
- Construction sector cement and gypsum additive demand:Water retention requirements in tile adhesives and cement plasters continue to broaden the addressable base for methylcellulose and hydroxyethyl cellulose grades across residential and commercial building chemistry applications.
- EMA pharmaceutical excipient guidelines:Certification pathways for oral solid dosage and ophthalmic formulations create pull-through demand for pharmaceutical-grade hydroxypropyl methylcellulose with documented batch-to-batch consistency.
- China and India capacity expansion:Concentrated derivative production growth in these manufacturing hubs is lowering regional feedstock costs and shortening supply chains for Asia-Pacific construction and personal care formulators.
Market Restraints
- Propylene oxide and methyl chloride feedstock volatility:Hydroxypropyl methylcellulose production remains exposed to petrochemical input cost swings that compress margin stability for non-integrated manufacturers.
- European supply concentration risk:REACH compliance costs and energy intensity have driven capacity rationalization, leaving construction-grade cellulose ether supply dependent on a narrowing base of specialized chemical producers.
- Guar gum substitution in oilfield drilling:Carboxymethylcellulose faces displacement in mature drilling fluid applications where guar-based alternatives offer cost advantages in price-sensitive exploration budgets.
Strategic Opportunities
- Continuous bioprocessing pharmaceutical manufacturing:Narrower particle-size distribution requirements for cellulose excipients create premium positioning opportunities for suppliers with dedicated pharmaceutical-grade manufacturing suites and advanced milling capabilities.
- EU Green Deal sustainable chemistry mandates:Bio-based etherification processes and renewable feedstock integration align with emerging procurement criteria for construction chemicals in European public infrastructure projects.
- Aftermarket formulation services:Technical service depth in application-specific blending is tilting margin pools away from commodity-grade ethers toward customized rheology packages for specialized building chemistry accounts.
Industry Challenges
- Pharmaceutical-grade toxicological testing timelines:FDA excipient qualification pathways for inhalation and parenteral applications impose extended validation periods that strain working capital for manufacturers expanding into regulated dosage forms.
- Legacy batch processing asset constraints:Conventional cellulose ether production lines face retrofitting costs to achieve the batch-to-batch consistency thresholds demanded by continuous pharmaceutical manufacturing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Ether and Derivatives Market |
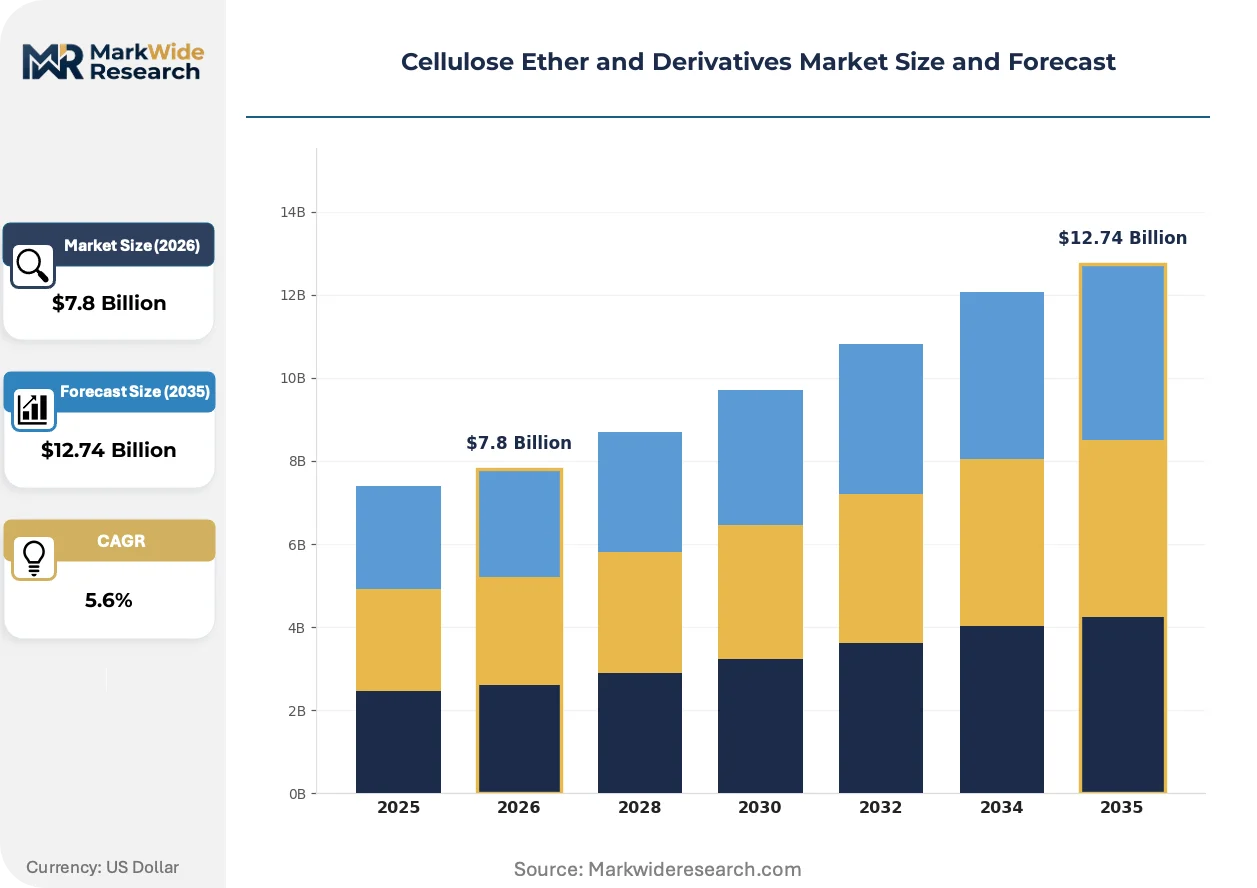
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
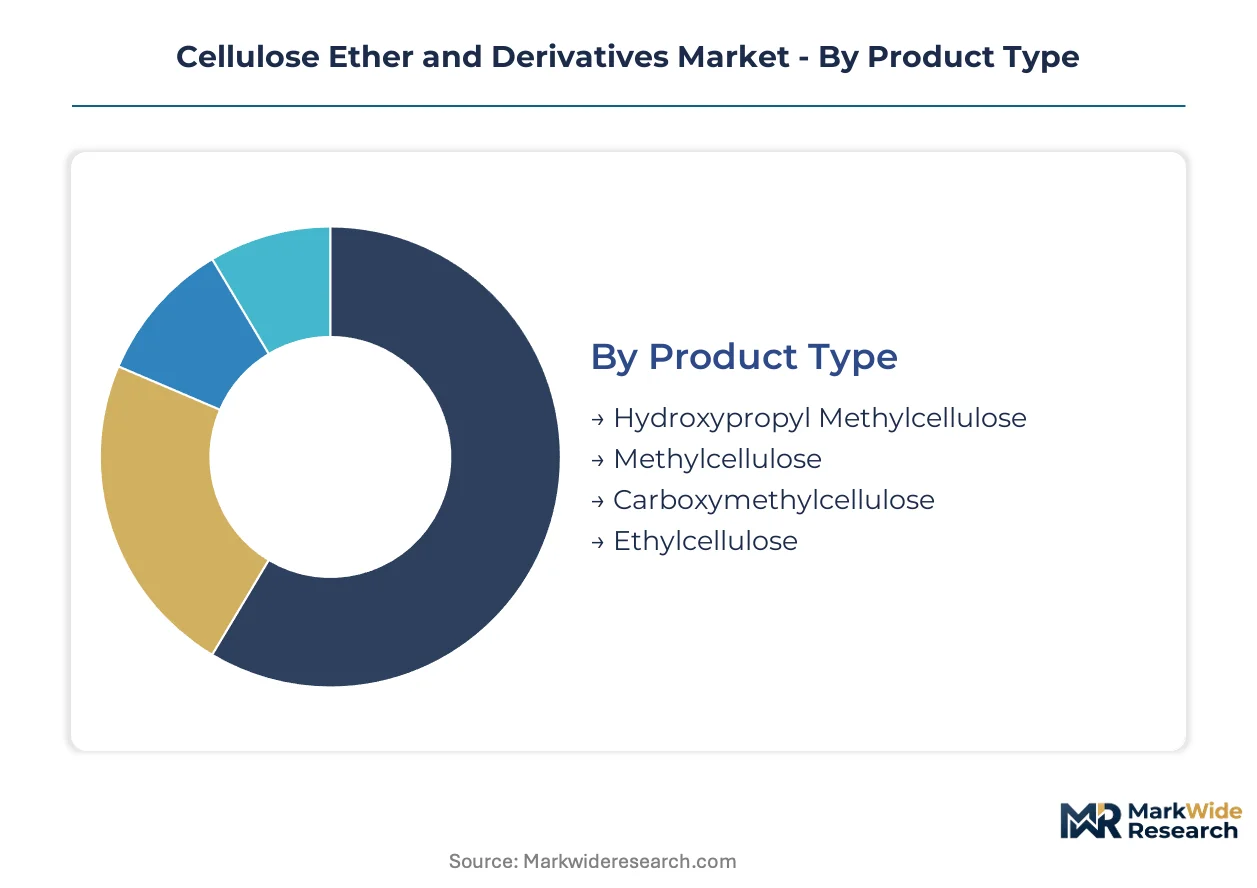
| Segmentation | Product Type: Hydroxypropyl Methylcellulose, Methylcellulose, Carboxymethylcellulose, Ethylcellulose End Use Industry: Pharmaceuticals, Food Industry, Construction, Personal Care Functionality: Thickening Agent, Binder, Dispersant, Film-forming Agent Form: Powder, Granules, Liquid, Paste |
| Companies Covered | The Dow Chemical Company, Shin-Etsu Chemical Co., Ltd., Ashland Global Holdings, Inc., Lotte Fine Chemicals, Nouryon Chemicals Holdings B.V., DKS Co. Ltd., J.M. Huber Corporation, Rayonier Advanced Materials, RETTENMAIER SOHNE GmbH + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Ether and Derivatives Market Strategic Shifts
Digital formulation platforms and advanced process analytical technologies are compressing product development cycles while regulatory data integrity requirements are reshaping how cellulose ether specifications are documented and transmitted across supply chains.
Process analytical technology (PAT) implementation is virtualizing quality control workflows in cellulose ether manufacturing. Pharmaceutical excipient producers are adopting real-time release testing protocols at the fastest pace among all buyer segments. This technology is virtualizing traditional laboratory-based batch release procedures, compressing lead times for certified pharmaceutical-grade hydroxypropyl methylcellulose while elevating capital requirements for competitive participation.
REACH Annex XIV authorization requirements for substances of very high concern continue tightening purity thresholds for cellulose derivatives entering European construction and personal care applications. Industrial consequence includes mandatory supply-chain traceability documentation extending back to pulp sourcing. Construction-grade methylcellulose formulations face the most acute compliance burden, with formulators reformulating to exclude authorized substances ahead of sunset dates.
Buyer concentration among multinational construction chemical formulators is consolidating procurement decisions for cement and gypsum additives. Technical service capabilities and application-specific blending expertise are displacing price-only sourcing criteria in vendor selection. This behavioral shift is most visible in German and French building chemistry markets, where specification-driven procurement now favors integrated suppliers with dedicated construction sector laboratories.
Cellulose Ether and Derivatives Market Segmentation
Cellulose ether specifications diverge sharply across regulated and industrial end uses, with pharmaceutical-grade purity commanding manufacturing protocols entirely distinct from construction-grade volume production. Derivative selection hinges on dissolution kinetics, thermal gelation points, and substitution patterns that align with specific formulation architectures.
Product Type:
Cost tier differentiation separates pharmaceutical-certified grades from commodity construction ethers, with feedstock integration and purification depth determining margin structure.
- Hydroxypropyl Methylcellulose:Dual substitution with methoxyl and hydroxypropyl groups yields thermal gelation between 50°C and 70°C, enabling controlled-release matrices and ophthalmic formulations. Demand concentrates in oral solid dosage applications across Germany and India, where EMA and CDSCO excipient certifications filter supplier qualification. FDA qualification pathways for inhalation grades impose toxicological testing burdens that favor dedicated pharmaceutical suites.
- Methylcellulose:Single methoxyl substitution delivers water retention and open-time extension in cement plasters and tile adhesives. Construction sector procurement in China anchors volume offtake, with technical service depth displacing price-only sourcing among multinational building chemical formulators.
- Carboxymethylcellulose:Anionic etherification produces high-viscosity solutions for food stabilization and oilfield drilling fluids. Guar gum substitution pressures mature drilling applications.
- Ethylcellulose:Organosoluble derivative insoluble in water, employed in sustained-release coatings and solvent-based protective films. REACH Annex XIV compliance redirects formulation toward aqueous alternatives.
Hydroxypropyl methylcellulose holds installed capacity. Methylcellulose is rotating up the share rankings.
End Use Industry:
Application requirements range from batch-to-batch consistency thresholds in continuous bioprocessing to water retention specifications in ambient-cure construction systems.
- Pharmaceuticals:Excipient functionality spans tablet binders, controlled-release matrices, and film-forming coatings for oral and ophthalmic delivery. Hydroxypropyl methylcellulose dominates where dissolution precision determines bioavailability. PAT implementation compresses release testing timelines for certified grades.
- Construction:Cement and gypsum additive demand governs methylcellulose and hydroxyethyl cellulose consumption, with water retention directly controlling open-time and bond strength in tile adhesives. German and French specification-driven procurement favors integrated suppliers with dedicated construction laboratories.
- Food Industry:Carboxymethylcellulose stabilizes emulsions and controls viscosity in processed foods. FSSAI and FDA food additive regulations govern purity documentation.
- Personal Care:Rheology modification and film-forming properties drive shampoo and lotion formulations. REACH compliance elevates traceability requirements for European personal care supply chains.
Construction anchors volume throughput. Pharmaceuticals is climbing the fastest on value contribution.
Functionality:
Volume scale separates commodity thickeners from specialized binders and film-forming agents requiring narrow particle-size distributions.
- Thickening Agent:Viscosity modification across aqueous systems represents the largest functional deployment by volume. Carboxymethylcellulose and methylcellulose grades serve construction, food, and personal care applications where rheology control governs processing and sensory properties.
- Binder:Cohesive strength in tablet matrices and ceramic extrusion depends on polymer molecular weight and substitution uniformity. Continuous pharmaceutical manufacturing demands narrower particle-size distributions than conventional batch processing assets deliver.
- Dispersant:Surface-active etherification products stabilize particulate suspensions in oilfield drilling and pigment systems. Guar gum displacement in price-sensitive exploration budgets pressures this functional segment.
- Film-forming Agent:Surface coating precision for pharmaceutical tablets and ophthalmic formulations requires documented batch-to-batch consistency. Hydroxypropyl methylcellulose and ethylcellulose grades compete on dissolution control and moisture barrier performance.
Thickening applications hold installed capacity. Film-forming functionality is rotating up the share rankings.
Form:
Customer type and handling infrastructure determine powder, granule, liquid, or paste selection, with dissolution kinetics and dust exposure regulations shaping preferences.
- Powder:Standard delivery format for cellulose ethers across all end uses, requiring controlled particle-size distribution for dissolution performance. Dust exposure regulations in European and North American manufacturing facilities elevate handling costs.
- Granules:Reduced dust generation and improved flow properties suit automated pharmaceutical and food processing lines. Premium positioning reflects additional processing steps.
- Liquid:Pre-dispersed solutions eliminate dissolution time in continuous manufacturing and ready-mix construction systems. Higher logistics costs constrain geographic reach.
- Paste:Concentrated dispersions for specialized construction and personal care blending operations. Application-specific rheology packages favor paste intermediates in aftermarket formulation services.
Powder form holds installed capacity. Granules are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction-grade buyers in China and India exhibit acute price sensitivity, while pharmaceutical formulators in Germany and the United States absorb substantial premiums for certified excipient consistency.
China
Residential and commercial building chemistry applications drive methylcellulose consumption across cement plasters and tile adhesives. The country's GB standards for construction chemicals mandate water retention specifications that favor domestic ether production. Capacity expansion clusters in Shandong Province, where integrated pulp-to-ether operations shorten feedstock supply chains for regional formulators.
Germany
Specification-driven procurement for cement and gypsum additives elevates technical service requirements among multinational construction chemical accounts. REACH Annex XIV authorization deadlines force reformulation away from substances of very high concern in methylcellulose grades. The Rhine-Ruhr industrial corridor hosts specialized production assets serving pharmaceutical and building chemistry end uses with dedicated manufacturing suites.
India
CDSCO excipient certification pathways create pull-through demand for hydroxypropyl methylcellulose in oral solid dosage applications across domestic and export pharmaceutical markets. FSSAI food additive regulations govern carboxymethylcellulose purity documentation for processed food stabilization. Gujarat and Maharashtra concentrate derivative production capacity serving both construction sector volume demand and pharmaceutical-grade specialty requirements.
United States
EPA TSCA chemical substance notifications elevate purity documentation burdens for cellulose ethers entering personal care and construction applications. FDA excipient qualification pathways for inhalation and parenteral dosage forms impose extended toxicological testing timelines that favor established suppliers. The Gulf Coast petrochemical corridor provides propylene oxide feedstock integration for hydroxypropyl methylcellulose manufacturers with backward-integrated supply chains.
Japan
PMDA pharmaceutical regulations demand documented batch-to-batch consistency for excipients used in ophthalmic and controlled-release formulations. METI industrial standards govern construction chemical performance specifications in seismic-resistant building applications. The Kansai region around Osaka maintains specialized etherification capacity serving domestic pharmaceutical and electronics-grade film applications.
Cellulose Ether and Derivatives Market Competitive Environment
Integrated petrochemical conglomerates and specialized excipient manufacturers split the market along feedstock control versus certification depth lines. Three archetypes dominate: propylene oxide-integrated chemical majors, pharmaceutical-grade purity specialists, and construction-sector technical service providers. Competitive moves concentrate on capacity expansion in Asia-Pacific manufacturing hubs and strategic partnerships for continuous bioprocessing excipient development.
Among North American-based chemical majors, The Dow Chemical Company exemplifies the integrated archetype through captive propylene oxide supply. Ashland Global Holdings, Inc. occupies a position representing pharmaceutical-grade certification depth, while Nouryon Chemicals Holdings B.V. anchors the European technical service tier. Shin-Etsu Chemical Co., Ltd. sits within the Asia-Pacific scale-driven segment. These entities collectively illustrate how feedstock integration, regulatory certification, and application-specific formulation expertise stratify competitive positioning across construction, pharmaceutical, and personal care demand verticals.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Shin-Etsu Chemical Co., Ltd. |
| Ashland Global Holdings, Inc. |
| Lotte Fine Chemicals |
| Nouryon Chemicals Holdings B.V. |
| DKS Co. Ltd. |
| J.M. Huber Corporation |
| Rayonier Advanced Materials |
| RETTENMAIER SOHNE GmbH + Co KG |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's logistics cost dynamics amplify supply concentration effects in cellulose ether markets, with Shandong Province production clusters commanding pricing power over European construction-grade buyers while downstream pharmaceutical formulators absorb certification-driven premiums that widen spreads between commodity methylcellulose and excipient-grade hydroxypropyl methylcellulose.
Pricing Analysis
Aftermarket formulation services now drive lifetime value for integrated suppliers, displacing pure product margins. Three-tier pricing structure across pharmaceutical-certified, construction-grade, and industrial-commodity levels stratifies by purity documentation depth and batch-to-batch consistency thresholds. Cost compression in construction-grade methylcellulose intensifies because Chinese capacity expansion feeds price-sensitive Asian building chemistry procurement. Pharmaceutical formulators in Germany and the United States exhibit lowest price sensitivity, absorbing substantial premiums for EMA and FDA excipient certifications, while cement additive buyers in China and India anchor the economy tier with acute spot-market reactivity.
Supply Chain Analysis
Propylene oxide and methyl chloride feedstock positions determine cost competitiveness for hydroxypropyl methylcellulose manufacturers. Production concentrates in China, India, and Germany, with Shandong Province and Gujarat hosting integrated pulp-to-ether operations that shorten regional supply chains. Raw material dependencies span wood pulp for cellulose backbone, petrochemical derivatives for etherification, and specialized catalysts for substitution control. Single-source vulnerability runs through concentrated European capacity for pharmaceutical-grade production, where REACH compliance costs have driven rationalization. Distribution runs through multinational construction chemical formulators in building chemistry and dedicated pharmaceutical excipient distributors in regulated dosage forms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing pharmaceutical manufacturing represents a high-growth disruption, with PAT implementation and narrow particle-size distribution requirements creating premium positioning opportunities that favor suppliers with dedicated manufacturing suites over conventional batch-processing assets.
For Market Incumbents: Harden pharmaceutical-grade certification depth through dedicated manufacturing suite investments that meet FDA inhalation and parenteral excipient qualification pathways, defending against specialty chemical entrants targeting continuous processing platforms. Deepen backward integration into propylene oxide supply to control feedstock cost volatility that compresses margin stability for non-integrated competitors. Anchor technical service capabilities in European construction sector accounts where specification-driven procurement displaces price-only sourcing.
For New Entrants and Emerging Players: Establish a beachhead in aftermarket formulation services for specialized building chemistry applications, where application-specific blending expertise captures margin pools away from commodity-grade ether producers. Target Indian pharmaceutical excipient markets where CDSCO certification pathways create pull-through demand for hydroxypropyl methylcellulose in oral solid dosage exports. Lead with digital formulation platforms that compress product development cycles for regional construction chemical formulators lacking in-house rheology expertise.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates seeking to divest non-core cellulose ether assets amid feedstock volatility and energy intensity pressures. Long-term viability centers on suppliers with pharmaceutical-grade manufacturing infrastructure capable of serving continuous bioprocessing platforms. The signal to watch is FDA qualification pathway completion rates for inhalation-grade hydroxypropyl methylcellulose, indicating which suppliers can capture premium positioning in next-generation dosage form manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Manufacturing Suite Investment | FDA and EMA excipient certifications command premium pricing in oral solid dosage and ophthalmic applications. |
| Backward Integration into Propylene Oxide Supply | Dow Chemical's captive feedstock control demonstrates margin stability advantages over non-integrated producers. |
| Aftermarket Formulation Services Expansion | Technical service depth in application-specific blending tilts margin pools away from commodity-grade ethers. |
| Continuous Processing Excipient Development | PAT implementation demands narrower particle-size distributions that strain conventional batch processing assets. |
| EU Green Deal Bio-Based Process Alignment | Renewable feedstock integration aligns with emerging procurement criteria for European public infrastructure projects. |
Study Parameters
Desk research of customs and trade databases, SEC and regulatory filings, and industry association reports preceded structured interviews with cellulose ether plant managers, procurement leads at multinational construction chemical formulators, pharmaceutical excipient regulatory affairs directors, and technical R&D directors at personal care ingredient suppliers. Bottom-up capacity and production estimates triangulated against top-down demand modeling across end-use industries. Primary fieldwork validated substitution patterns between cellulose ethers and guar gum in oilfield applications, while secondary sources anchored purity documentation requirements under REACH Annex XIV and FDA excipient qualification pathways.
Assumptions held fixed include regulatory compliance timelines under EMA and FDA frameworks, while variables spanned propylene oxide feedstock cost trajectories and Chinese capacity expansion rates. The analytical framework modeled demand across product type, end-use industry, functionality, and form dimensions over the projection horizon. CAGRs derived from segment-level volume and value buildups, with pharmaceutical-grade hydroxypropyl methylcellulose growth calibrated against continuous bioprocessing adoption curves and construction-grade methylcellulose tied to residential building chemistry forecasts in China and India.
Macroeconomic conditions sit as an overlay; deviation in construction sector investment cycles or pharmaceutical R&D spending trajectories would shift the trajectory. Forecasts reflect assumptions about REACH enforcement intensity and CDSCO certification pathway streamlining. Cross-checking against EIA petrochemical feedstock price benchmarks and Cefic construction chemical demand indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
High-K and CVD ALD Metal Precursors Market
Specialty Chemicals
Silanes and Silicones Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market