
 US Bioplastics Market | 2026-2036
US Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
US Bioplastics Market Insights
Market Context
Iowa's expanding polylactic acid production corridor is rewriting the domestic supply map for corn-derived biopolymers. NatureWorks LLC leverages its Blair, Nebraska manufacturing complex to anchor North American PLA resin output with integrated fermentation and polymerization stages. Danimer Scientific specializes in PHA production through bacterial fermentation at its Winchester, Kentucky facility, competing with petroleum-based polyesters on marine biodegradability credentials. Genomatica positions its bio-based intermediate chemicals platform to extend feedstock options beyond first-generation starch sources.
Technical Definition and Structural Segments
US bioplastics comprise thermoplastic materials derived from annually renewable biomass feedstocks, including polylactic acid synthesized through ring-opening polymerization of lactide monomers with molecular weights typically exceeding 100,000 g/mol, serving primarily as drop-in replacements for conventional polyethylene and polypropylene in single-use and durable applications. PLA dominates installed production capacity and captures the largest share of food service and fresh produce packaging volumes, while PHA commands premium positioning in marine-degradable and soil-compostable film applications where end-of-life certification drives margin pools. Starch blends occupy cost-sensitive molded goods and loose-fill segments, whereas Bio-PE from Brazilian sugarcane ethanol imports sustains rigid container demand among brand owners seeking mass-balance carbon accounting without processing line retrofits.
Regulatory Framework and Outlook
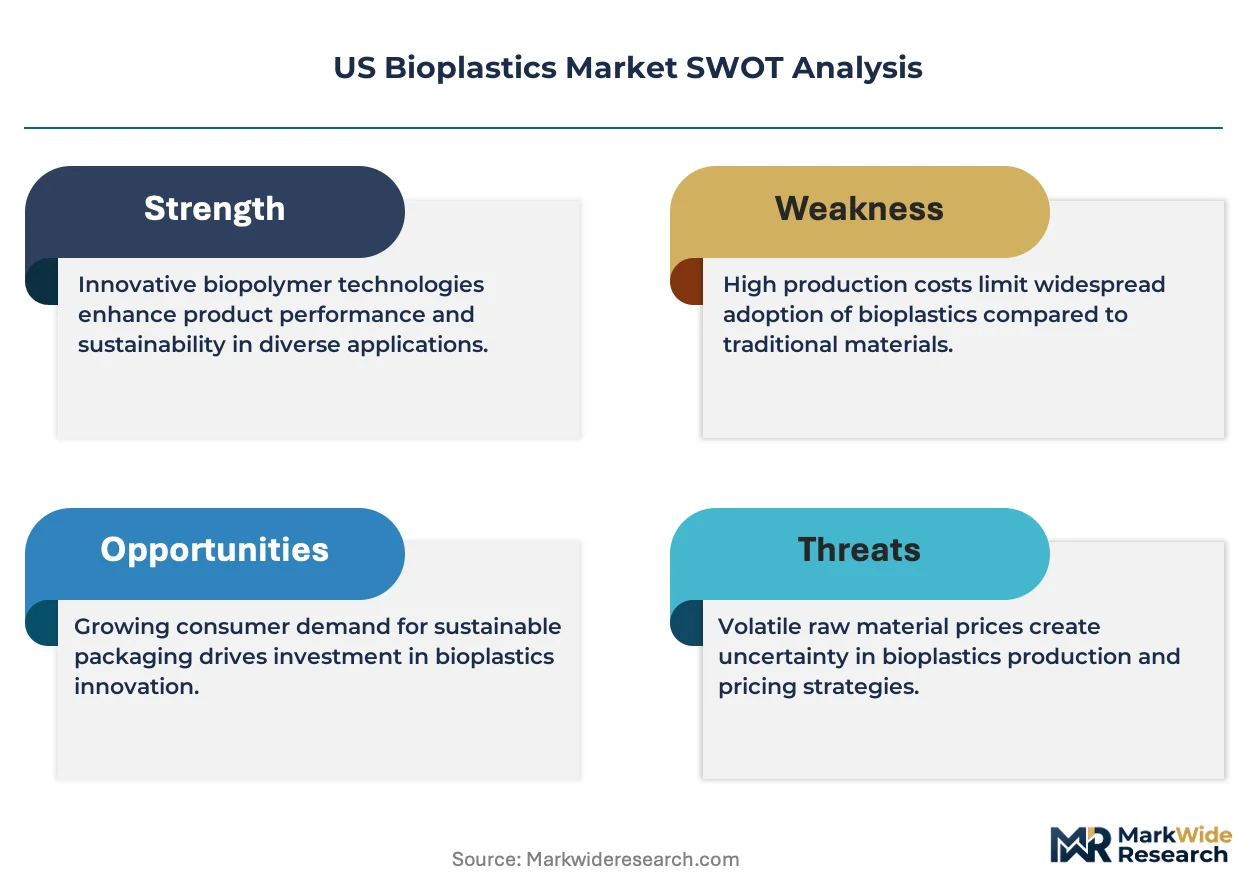
EPA sustainable materials management protocols, California SB 54 extended producer responsibility mandates, and FTC Green Guides on environmental marketing claims collectively shape product certification requirements and demand pull-through across state procurement programs. USDA BioPreferred labeling standards and ASTM D6400/D6868 compostability specifications further constrain market access to tested and certified formulations. Stakeholders must monitor pending state-level restrictions on per- and polyfluoroalkyl substances in food packaging, as these intersect directly with bioplastic barrier coating strategies and determine which material platforms secure shelf space with national quick-service restaurant chains.
Market Dynamics
California's SB 54 extended producer responsibility mandates are forcing national food packaging chains to reconfigure material specifications across their entire US supply footprint, triggering cascading procurement shifts in Midwest and Southeast distribution networks.
Growth Catalysts
- EPA Sustainable Materials Management Protocols:Federal waste diversion targets are compelling municipal composting facilities to expand capacity, creating direct offtake infrastructure for ASTM D6400-certified bioplastic films and rigid containers.
- PHA Marine Biodegradability Credentials:Quick-service restaurant chains seeking ocean-degradable packaging alternatives are specifying polyhydroxyalkanoate resins for coastal market distribution where marine litter regulations apply.
- Midwest Corn Belt Concentration:Iowa and Nebraska's integrated fermentation-to-polymerization corridors are shortening feedstock-to-resin supply loops, reducing logistics exposure for PLA compounders serving domestic converters.
Market Restraints
- First-Generation Feedstock Cost Volatility:Corn starch and sugarcane ethanol prices fluctuate with agricultural commodity cycles, compressing margin stability for PLA and Bio-PE producers without long-term supply contracts.
- Composting Infrastructure Geographic Gaps:Industrial composting facilities capable of processing ASTM D6868-certified packaging remain concentrated in California and the Pacific Northwest, limiting end-of-life value propositions in Mountain and Plains states.
- Petroleum-Based Polyester Substitution:Recycled PET and mechanically recycled polypropylene offer lower unit costs and established collection streams, constraining bioplastic penetration in cost-sensitive bottled beverage and thermoformed tray segments.
Strategic Opportunities
- Southeast Municipal Composting Buildout:Georgia and Florida counties are piloting curbside organics collection programs that could replicate California's demand pull-through for certified compostable food service items.
- Barrier Coating Convergence:Integration of bio-based polyhydroxyalkanoate coatings with PLA substrates is enabling high-moisture food packaging applications previously reserved for fluorinated petroleum films.
- USDA BioPreferred Federal Procurement:Mandatory biobased content specifications for federal food service contracts are creating a stable demand floor insulated from retail price competition.
Industry Challenges
- ASTM D6400 Certification Timeline Compression:Third-party compostability testing requires 180-day field and laboratory validation cycles, delaying product launches and locking working capital in pre-commercial inventory.
- Fermentation Scale-Up Capex Intensity:Commercial PHA production demands specialized bioreactor infrastructure with sterile process controls, elevating barrier-to-entry for mid-cap compounders seeking backward integration into resin production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bioplastics Market |
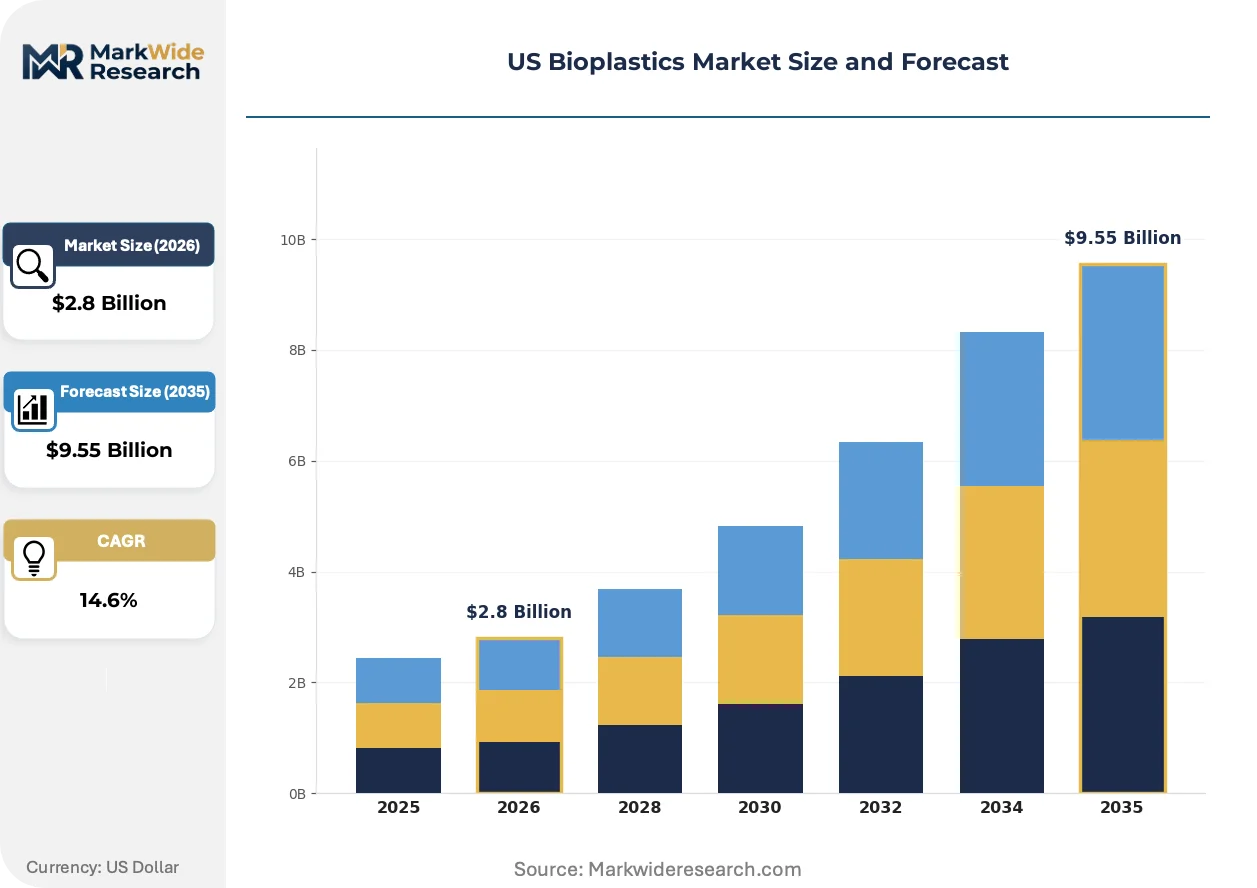
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Bio-PE End User: Packing, Automotive, Consumer Goods, Textiles Form: Films, Rigid Containers, Foams, Application Mouldings Technology: Injection Moulding, Blow Moulding, Extrusion, 3D Printing |
| Companies Covered | Trinseo, Hallstar Industrial, NatureWorks LLC, Total Corbion PLA, Amcor Rigid Plastics USA, LLC, Danimer Scientific, Genomatica, Bioplastics International, Dow Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bioplastics Market Trends and Innovations
Second-generation lignocellulosic feedstock processing is disrupting first-generation starch-based biopolymer economics, while regulatory precision on compostability claims is filtering out uncertified market entrants.
Advanced lactide purification systems are rendering obsolete conventional polylactic acid grades with limited thermal stability. Food packaging converters in the Upper Midwest are adopting high-heat PLA variants for hot-fill applications previously restricted to polypropylene. This thermal performance leap is compressing the price-performance gap against petroleum-based alternatives in ready-meal tray segments.
The FTC's updated Green Guides enforcement priorities are tightening substantiation requirements for biodegradability and compostability marketing claims. Brand owners now face civil penalty exposure for unqualified "eco-friendly" labeling on food service items. California's district attorneys have initiated targeted enforcement actions against imported bioplastic products lacking ASTM certification documentation.
Quick-service restaurant chains are consolidating supplier relationships around vertically integrated resin-to-converter partnerships capable of mass-balance carbon accounting. National account procurement teams are bypassing traditional distribution intermediaries to contract directly with Nebraska and Kentucky manufacturing complexes. This channel compression is most visible in California and Washington state markets where corporate sustainability reporting mandates require supply chain emissions transparency.
US Bioplastics Market Segmentation
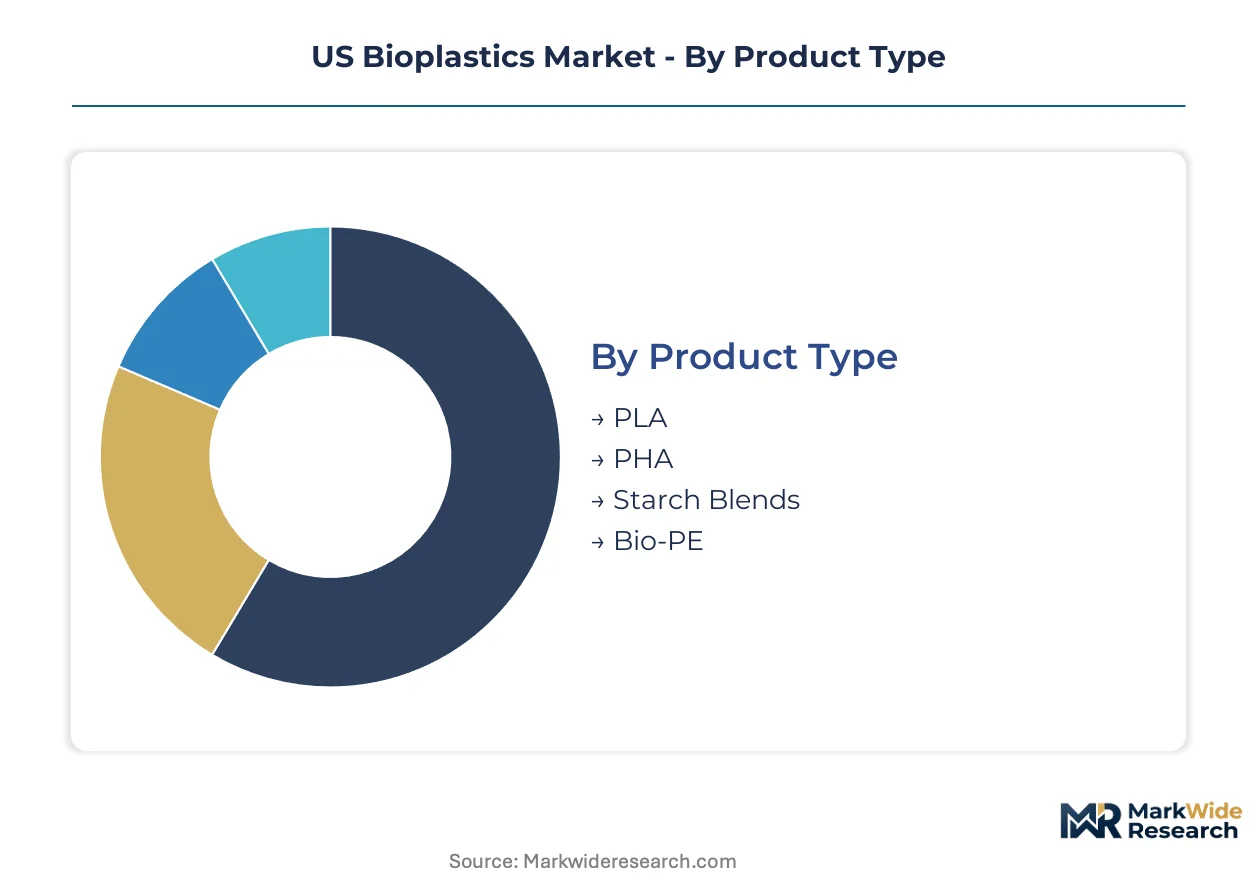
US bioplastics procurement cycles vary dramatically across material platforms and conversion technologies, with food packaging converters turning inventory monthly while automotive qualification timelines extend across multiple years. Understanding these velocity differentials helps suppliers calibrate working capital requirements and certification investments against specific segment entry points.
Product Type:
PLA resin batches turn every 45-60 days through Nebraska fermentation complexes, whereas PHA bioreactor runs demand 90-120 day sterile cycles that constrain output cadence.
- PLA:Ring-opening polymerization of corn-derived lactide yields thermoplastic aliphatic polyesters with molecular weights exceeding 100,000 g/mol. Fresh produce clamshell demand concentrates in California retail chains where municipal composting infrastructure validates ASTM D6400 certification claims.
- PHA:Bacterial fermentation of plant oils and sugars produces marine-biodegradable polyhydroxyalkanoates with crystallinity tunable through copolymer ratios. Quick-service restaurant chains specify PHA for coastal distribution where ocean-degradable end-of-life credentials command shelf space.
- Starch Blends:Thermoplastic starch compounded with synthetic polymers serves cost-sensitive loose-fill and molded goods segments through Midwest distribution networks.
- Bio-PE:Brazilian sugarcane ethanol imports sustain mass-balance carbon accounting for rigid containers without processing line retrofits at Ohio and Illinois converters.
PLA anchors the volume base while PHA gains share at the steepest rate.
End User:
Premium pricing tolerance stratifies sharply across customer categories, with federal procurement programs accepting 15-25% premiums over petroleum alternatives while automotive OEMs demand cost parity at volume.
- Packing:Food contact applications dominate resin offtake, spanning fresh produce films, hot-fill trays, and quick-service disposable serviceware. USDA BioPreferred federal contracts create stable demand floors insulated from retail price competition.
- Automotive:Interior trim and under-hood components specify bio-based polyamides and polyesters for corporate fleet emissions reporting. Tier-1 suppliers in Michigan and Ohio qualify materials through 24-36 month OEM validation protocols.
- Consumer Goods:Personal care and electronics packaging segments prioritize aesthetic surface finish and dimensional stability over compostability credentials.
- Textiles:Fiber applications for apparel and nonwovens compete directly with recycled polyester on moisture management and dye uptake performance.
Packing commands the revenue concentration while automotive applications expand most quickly as OEMs accelerate scope-3 emissions reduction targets.
Form:
Film extrusion lines achieve fastest capital payback at 18-24 months, whereas foaming equipment specialization extends amortization horizons toward 48 months.
- Films:Blown and cast extrusion of PLA and PHA resins produces compostable fresh produce wraps and laminated barrier structures. California SB 54 procurement mandates drive specification shifts across national food packaging chains.
- Rigid Containers:Thermoformed trays and injection-molded cups serve ready-meal and dairy segments where high-heat PLA variants now compete with polypropylene hot-fill performance.
- Foams:Expanded starch and PLA bead foams replace polystyrene protective packaging through e-commerce fulfillment networks.
- Application Mouldings:Custom injection-molded components span automotive interior trim, consumer electronics housings, and durable goods applications.
Films generate the highest throughput tonnage while rigid containers climb the fastest on quick-service restaurant substitution cycles.
Technology:
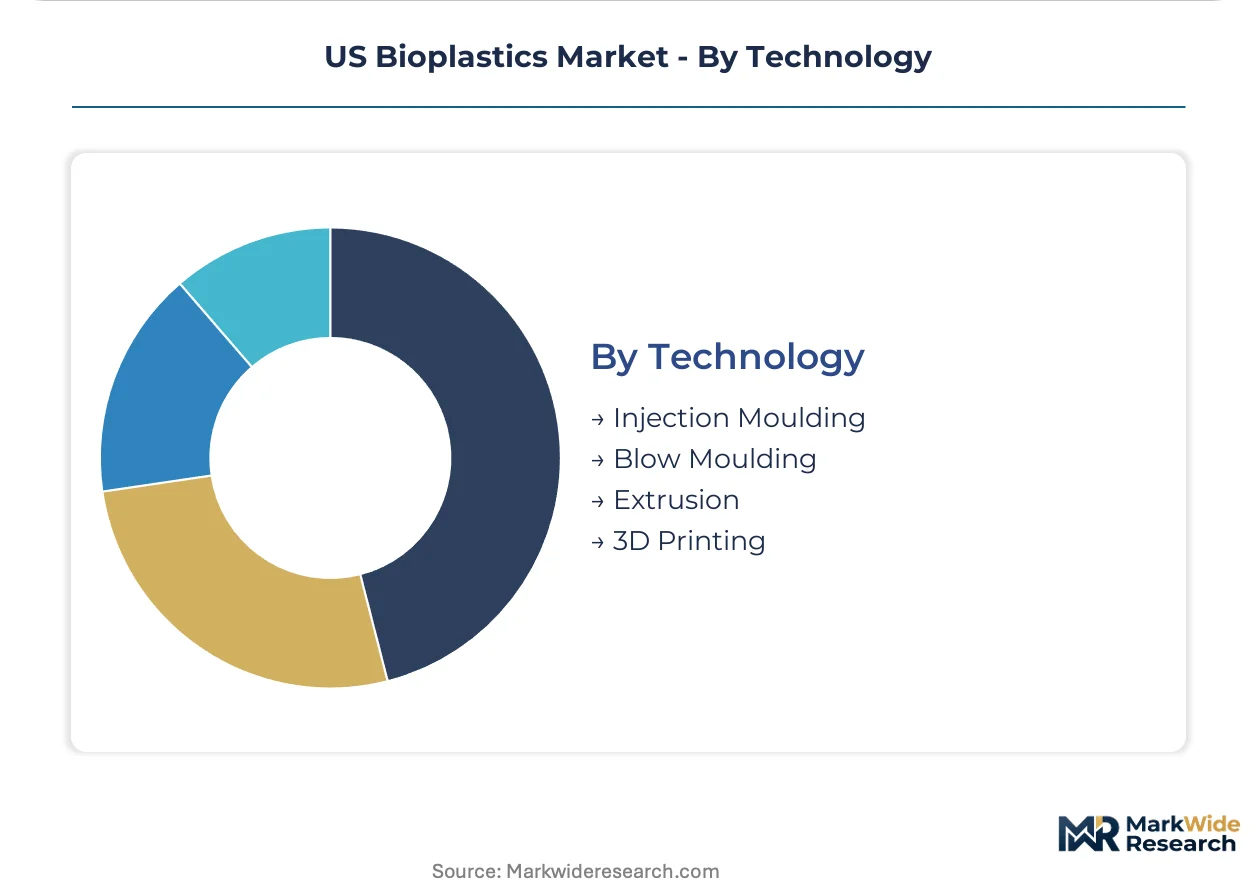
Equipment utilization rates diverge substantially, with extrusion lines running 85-90% uptime versus 3D printing systems at 30-40% effective capacity due to batch sizing constraints.
- Injection Moulding:High-pressure resin injection into precision tooling produces complex geometries with tight dimensional tolerances for automotive and consumer electronics housings. Nebraska and Kentucky resin producers co-locate technical service teams at major Midwest molding clusters.
- Blow Moulding:Extrusion and injection blow processes form hollow containers for beverage and personal care applications where Bio-PE drops into existing polyethylene tooling.
- Extrusion:Continuous profile and sheet production dominates film, sheet, and fiber applications with fastest line speeds and lowest unit conversion costs.
- 3D Printing:Fused deposition modeling of PLA filament serves prototyping and low-volume custom manufacturing with extended lead times and premium pricing.
Extrusion holds the installed capacity base while injection moulding captures the steepest expansion trajectory on automotive interior component qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach's container terminals anchor California's bioplastic import and distribution infrastructure, handling resin shipments from Brazilian ethanol feedstock suppliers and Asian compounders while connecting to the Central Valley's packaging manufacturing belt via the Alameda Corridor rail link.
California
Los Angeles and San Francisco municipal composting facilities process over half the nation's ASTM D6400-certified packaging. SB 54 extended producer responsibility mandates force national food chains to specify certified compostable films for California distribution, creating procurement pull-through that reshapes specifications across entire US supply footprints. The Central Valley's fresh produce packing houses cluster around Fresno and Salinas, consuming high volumes of PLA clamshells.
Midwest Corn Belt
Iowa and Nebraska's integrated fermentation-to-polymerization corridors shorten feedstock-to-resin supply loops for corn-derived PLA. The Blair, Nebraska manufacturing complex anchors North American polylactic acid output with captive fermentation and polymerization stages. NatureWorks LLC operates this integrated facility, supplying compounders across Illinois, Ohio, and Michigan converting clusters without transoceanic logistics exposure.
Southeast
Georgia and Florida counties pilot curbside organics collection programs that could replicate California's demand infrastructure. Atlanta's quick-service restaurant headquarters specify marine-degradable packaging for coastal distribution networks. Danimer Scientific's Winchester, Kentucky PHA facility supplies bacterial fermentation-derived resins to converters in Tennessee and the Carolinas seeking ocean-biodegradable credentials.
Pacific Northwest
Seattle and Portland municipal composting infrastructure predates California's buildout, sustaining early-adopter demand for food service bioplastics. The region's retail grocery chains enforced plastic bag bans ahead of national trends, conditioning consumer acceptance of compostable alternatives. Washington state's corporate sustainability reporting mandates drive supply chain emissions transparency requirements that favor mass-balance carbon accounting.
Northeast Corridor
New York and New Jersey distribution hubs receive Brazilian Bio-PE shipments through Port Newark, supplying Ohio and Pennsylvania rigid container manufacturers. The region's limited industrial composting capacity constrains end-of-life value propositions compared to West Coast markets. Federal procurement offices in Washington DC and Boston anchor USDA BioPreferred contract demand for food service applications.
US Bioplastics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The US bioplastics market structures around three tiers: integrated resin-to-converter partnerships, standalone compounders, and import-dependent distributors. Strategic archetypes include fermentation-based biopolymer producers, petroleum incumbent diversifiers, and specialty chemical platform developers. Dominant competitive moves encompass backward integration into feedstock cultivation and capacity expansion along the Nebraska-Iowa corridor.
Within the integrated biopolymer tier, NatureWorks LLC and Danimer Scientific exemplify contrasting fermentation platforms—corn-derived lactide versus bacterial polyhydroxyalkanoate production. Total Corbion PLA represents the multinational petrochemical pivot toward renewable feedstocks. These three anchors illustrate how geographic proximity to Midwest agricultural supply and coastal regulatory demand shapes competitive positioning without requiring identical technical approaches or end-market focus.
| Leading Market Players |
|---|
| Trinseo |
| Hallstar Industrial |
| NatureWorks LLC |
| Total Corbion PLA |
| Amcor Rigid Plastics USA, LLC |
| Danimer Scientific |
| Genomatica |
| Bioplastics International |
| Dow Inc. |
| Others |
Pricing and Supply Chain Analysis
Nebraska fermentation complex utilization rates above 85% are compressing spot resin availability and emboldening compounders to push through formula-based price adjustments tied to corn starch futures. This tightness propagates downstream to Illinois and Ohio converters, who face compressed margins unless they secure long-term offtake agreements or backward integrate into blending operations.
Pricing Analysis
California SB 54 dictates the pricing tier structure across the US bioplastics market, separating ASTM D6400-certified premium grades from uncertified commodity alternatives. Three-tier pricing stratifies across certified compostable, industrially compostable without municipal verification, and conventional petroleum-based substitutes. Cost compression in standard-grade PLA intensifies because recycled PET offers lower unit costs in bottled beverage segments. Federal procurement programs exhibit the lowest price sensitivity, while quick-service restaurant chains negotiate aggressively on volume contracts.
Supply Chain Analysis
Export-control regimes on fermentation biotechnology equipment limit US domestic capacity expansion for bacterial polyhydroxyalkanoate production, constraining Danimer Scientific's Kentucky facility as the primary marine-biodegradable resin source. Supply draws from Brazilian sugarcane ethanol for Bio-PE, Midwest corn starch for PLA, and imported Asian lactide intermediates. Single-source vulnerability concentrates in Nebraska's integrated fermentation-to-polymerization corridor, where NatureWorks anchors North American polylactic acid output. Distribution runs through California Central Valley packaging clusters and Midwest converter networks serving national food chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against mechanically recycled polypropylene and PET, which offer established collection infrastructure and lower unit costs in rigid container applications. Incumbents must differentiate on end-of-life certification rather than compete on price alone.
For Market Incumbents: Entrench ASTM D6400 certification moats by accelerating testing timelines and co-locating technical service teams at major Midwest molding clusters. Defend against petroleum incumbent diversifiers by locking long-term supply contracts with California quick-service restaurant chains facing SB 54 mandates. Prioritize barrier coating R&D to displace fluorinated films in high-moisture food packaging.
For New Entrants and Emerging Players: Build out Southeast municipal composting infrastructure partnerships in Georgia and Florida counties piloting curbside organics collection. Target the rigid container segment in Ohio and Illinois, where Bio-PE drops into existing polyethylene tooling without processing line retrofits. Pursue USDA BioPreferred federal procurement contracts as a stable demand floor insulated from retail price competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across PHA bioreactor scale-up, elevating barriers for mid-cap compounders seeking backward integration into resin production. Five-to-ten-year viability hinges on second-generation lignocellulosic feedstock commercialization displacing first-generation starch economics. Target fermentation-based biopolymer producers with captive agricultural supply agreements. Monitor EPA sustainable materials management protocol enforcement as an inflection signal for municipal composting capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Corn belt supply agreements with Iowa and Nebraska agricultural cooperatives reduce logistics exposure and margin volatility. |
| ASTM D6400 Certification Acceleration | Third-party validation investments compress 180-day testing cycles and lock shelf space with California retail chains. |
| Barrier Coating Convergence | PHA-PLA laminate integration enables high-moisture food packaging previously reserved for fluorinated petroleum films. |
| Southeast Municipal Composting Partnership | Georgia and Florida county pilot programs replicate California's demand infrastructure for certified food service items. |
| Federal Procurement Contract Capture | USDA BioPreferred specifications create stable offtake insulated from retail price competition in food service applications. |
Research Methodology
Initial hypotheses were tested against primary input from PLA compounders, PHA fermentation engineers, food packaging procurement directors, and municipal composting facility operators and refined through secondary validation against EPA sustainable materials management reports, USDA BioPreferred program databases, ASTM International certification registries, and SEC filings from disclosed market participants. Bottom-up resin production estimates triangulated with top-down food packaging demand assessments.
Demand-supply balance modeling across the projection horizon incorporated segmentation by material platform, conversion technology, end-use application, and regional regulatory cluster. CAGRs were derived from installed capacity expansion timelines, municipal composting infrastructure buildout trajectories, and state-level extended producer responsibility implementation schedules. Industry-specific inputs included NatureWorks Nebraska facility output cadence, Danimer Kentucky bioreactor yield rates, and California SB 54 procurement mandate compliance deadlines.
Practitioners should monitor EPA enforcement priorities, agricultural commodity futures volatility, and municipal composting facility permitting velocity for early signals. Forecasts reflect documented assumptions regarding fermentation scale-up economics and state-level plastic ban adoption rates. Material shifts in second-generation lignocellulosic feedstock cost structures or federal preemption of state extended producer responsibility laws would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
China Bioplastics Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Global Bioplastic Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Biodegradable Superabsorbent Materials Market