
 Biodegradable Microbeads Market | 2026-2036
Biodegradable Microbeads Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Microbeads Market Outlook
The EU REACH microplastic restriction is hardening compliance timelines for cosmetic and personal care manufacturers across member states. BASF leverages its Ludwigshafen biopolymer complex to supply plant-derived microbead feedstock to European formulators. Evonik Industries anchors specialty silica and biobased particle development from its German operations. Croda competes through lipid-based exfoliant technologies that bypass polymer classification entirely.
Biodegradable microbeads are spherical particulates typically 5–500 micrometers in diameter, engineered from plant-based polymers, algae, starch, or cellulose to deliver controlled mechanical exfoliation before environmental degradation. These particles replace persistent polyethylene microplastics in rinse-off cosmetic and cleaning applications where aquatic toxicity concerns have eliminated conventional synthetic options. Facial scrubs and exfoliants lead product-type demand due to direct consumer exposure and visible performance requirements. Plant-based polymers dominate the material category because supply chains for polylactic acid and polyhydroxyalkanoates have achieved commercial scale. Oral care applications within skin care, oral care, cleaning products, and cosmetic products are gaining fastest as toothpaste manufacturers reformulate ahead of regulatory deadlines.
EMA cosmetic ingredient oversight, ECHA REACH enforcement, and EU Green Deal circular economy targets collectively define the compliance perimeter for biodegradable microbead market access in Europe. EFSA biodegradability certification criteria determine whether alternative particles qualify for exempt status under pending microplastic restrictions. Formulators and material suppliers must monitor regulatory divergence between EU member-state implementation timelines and emerging national standards in France and Germany.

Market Dynamics
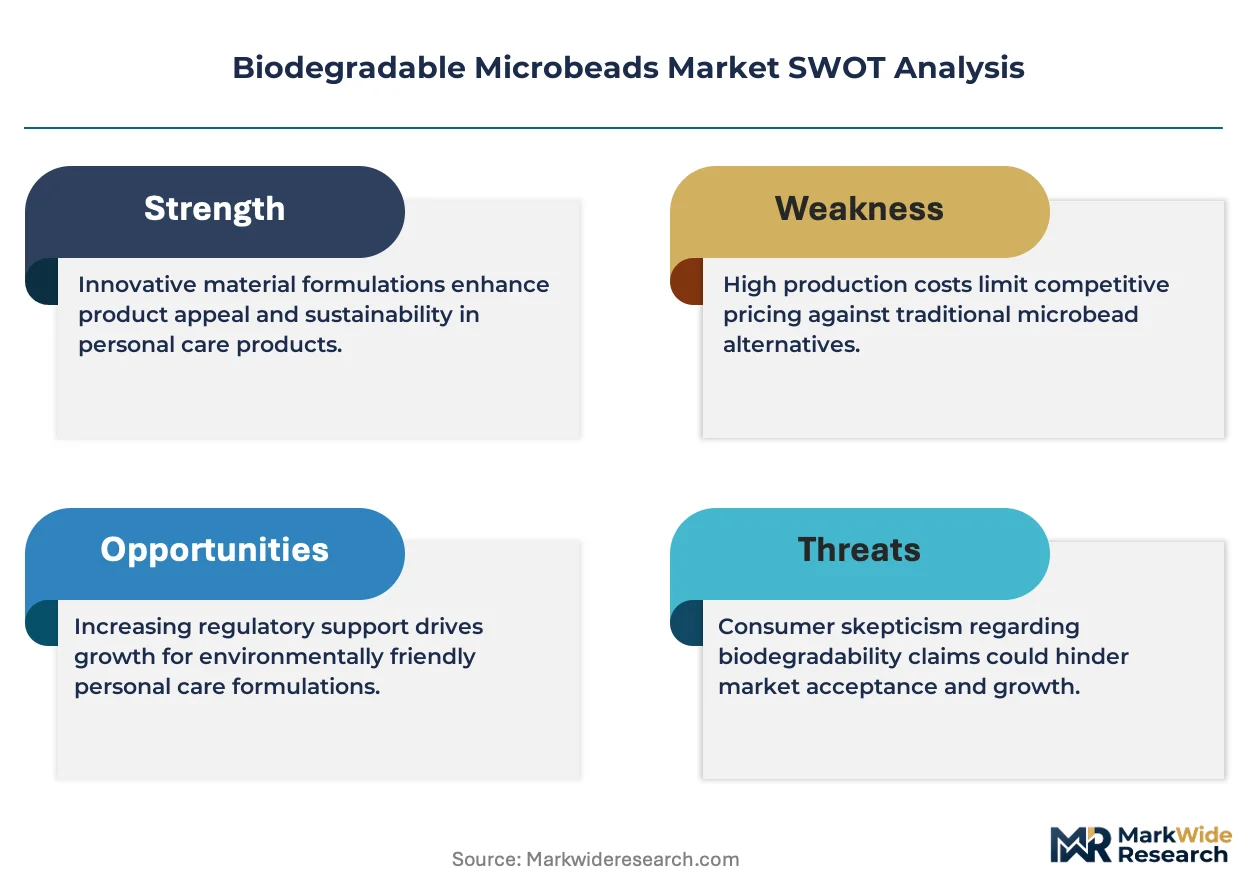
The EU REACH microplastic restriction is compressing formulation timelines for cosmetic and personal care manufacturers, forcing immediate material substitution decisions across European production networks.
Growth Catalysts
- REACH Annex XVII microplastic ban:European rinse-off cosmetics manufacturers must eliminate synthetic polyethylene beads, creating mandatory demand pull for certified biodegradable alternatives.
- Polylactic acid supply chain maturation:Fermentation-based PLA production has achieved cost parity with petroleum-derived polymers for high-volume bead applications.
- Oral care reformulation wave:Toothpaste manufacturers are accelerating biodegradable abrasive adoption ahead of regulatory enforcement deadlines.
Market Restraints
- Biopolymer feedstock cost volatility:Corn starch and sugarcane prices fluctuate with agricultural commodity cycles, compressing margins for plant-based bead producers.
- German production concentration:Ludwigshafen and Marl industrial clusters control disproportionate European biopolymer capacity, creating geographic supply risk.
- Marine biodegradability certification delays:EFSA evaluation timelines for OECD 306 compliance extend 18-24 months, blocking market access for novel materials.
Strategic Opportunities
- French national microplastic standard ANSM-2024-001:Stricter national implementation than baseline REACH creates premium positioning for early-certified suppliers.
- Cellulose nanocrystal hybrid beads:Combining plant polymers with nanocellulose structures enables tunable degradation rates for diverse water chemistries.
- Direct-to-formulator digital channels:Specialty chemical marketplaces bypass traditional distributor markups for mid-volume personal care manufacturers.
Industry Challenges
- Biopolymer processing expertise scarcity:Extrusion and spheronization technicians trained on petroleum polymers require 12-18 month retraining for starch-based systems.
- Legacy equipment retrofit costs:Existing microbead production lines need temperature and humidity control upgrades to handle hydrophilic plant polymers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Microbeads Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $619.77 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Scrubs, Body Washes, Toothpaste, Exfoliants End User: Personal Care, Household, Industrial, Medical Material: Plant-Based Polymers, Algae, Starch, Cellulose Application: Skin Care, Oral Care, Cleaning Products, Cosmetic Products |
| Companies Covered | BASF, Evonik Industries, Ajinomoto Co., TerraVerdae Bioworks, Croda, Asahi Kasei Corporation, Daicel Corporation, Trelleborg AB, NatureWorks LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Microbeads Market Strategic Shifts
Formulation science is converging with regulatory toxicology to redefine acceptable particle performance, shifting competitive advantage toward materials with validated environmental fate data.
Plant-based polymer microbead technology is consolidating supplier power among fermentation-scale biopolymer producers. Facial scrub formulators are adopting PLA-PHA copolymer beads at accelerating rates as stock-keeping unit rationalization favors multi-regulatory-compliant ingredients. This consolidation is compressing the addressable market for niche specialty particle developers without captive biopolymer supply.
EU REACH Annex XVII restrictions on intentionally added microplastics entered force with staggered deadlines through 2035. Cosmetic manufacturers face immediate obligations for rinse-off products while leave-on reformulations gain transitional periods. German formulators are responding fastest, with BASF and Evonik leveraging domestic regulatory intelligence to pre-certify bead portfolios.
Ingredient procurement is fragmenting as personal care brands bypass traditional distributors for direct biopolymer offtake agreements. Mid-sized formulators in the Netherlands and Belgium are establishing captive supply relationships with fermentation facilities. This disintermediation is most visible in oral care, where toothpaste manufacturers consolidate volumes to secure price stability against agricultural commodity swings.
Biodegradable Microbeads Market Segmentation
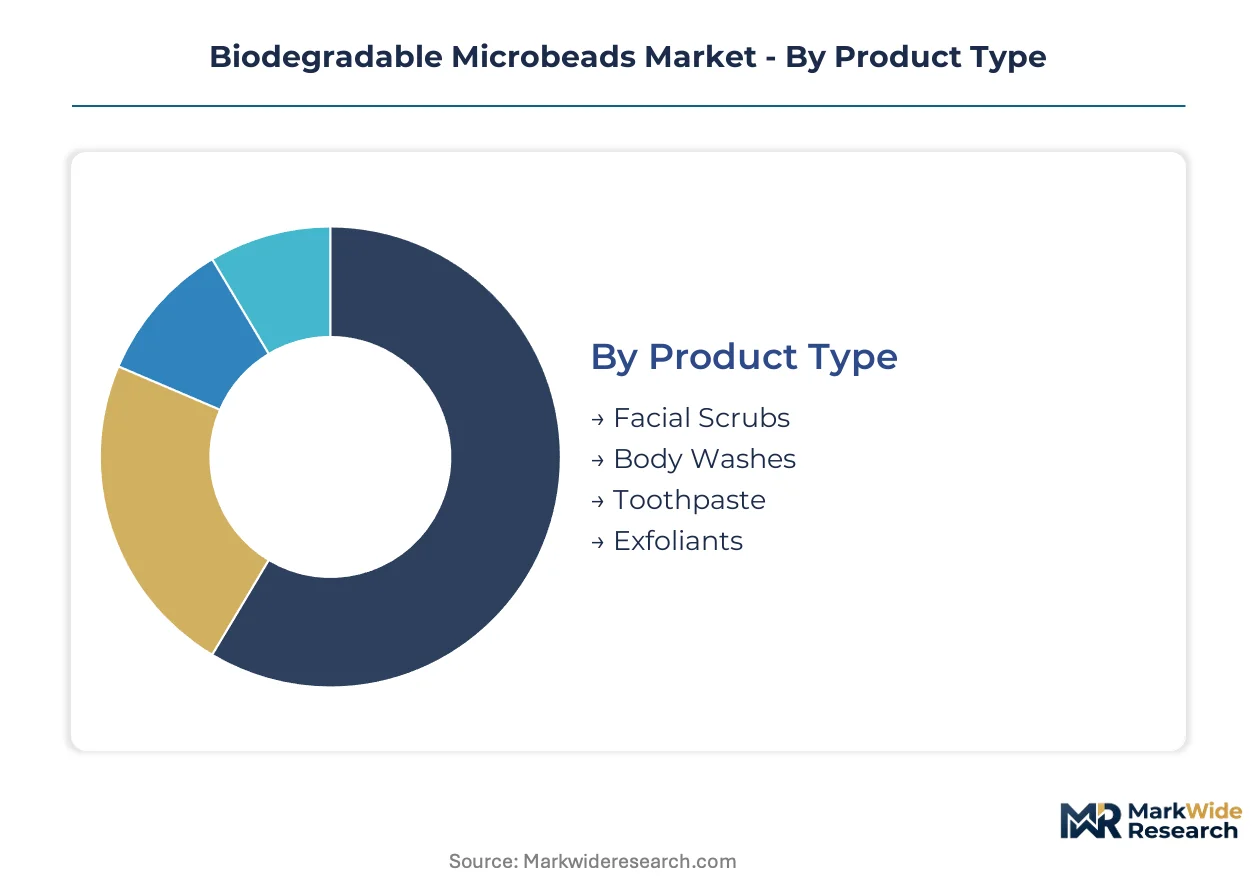
Segmentation in biodegradable microbeads tracks how regulatory pressure and formulation science reshape procurement across distinct performance tiers. Manufacturers segment supply to match certification requirements against cost constraints.
Product Type:
Standardization dominates mass-market rinse-off formats while specialty applications demand customized particle engineering.
- Facial Scrubs:Polylactic acid and polyhydroxyalkanoate beads engineered to 100-300 micrometer diameter deliver controlled mechanical exfoliation without dermal abrasion. Demand concentrates in German and French premium cosmetic lines where ECHA REACH compliance deadlines force immediate synthetic substitution.
- Body Washes:Larger-diameter cellulose and starch-based beads dissolve across variable shower temperatures and water hardness levels. Formulators in the Netherlands prioritize these for mid-tier product lines balancing performance against agricultural commodity price volatility.
- Toothpaste:Abrasive-grade particles require ISO 11609 certification for enamel safety alongside marine biodegradability validation.
- Exfoliants:Professional spa and clinic formats use tunable-degradation beads for controlled-release active ingredient delivery.
Most installed capacity flows through facial scrubs. Expansion is steepest in toothpaste as oral care manufacturers consolidate reformulation timelines ahead of regulatory enforcement.
End User:
Volume concentration separates commodity household applications from margin-rich medical specialties.
- Personal Care:Cosmetic and toiletry manufacturers drive specification standards through direct biopolymer offtake agreements with fermentation facilities.
- Household:Cleaning product formulators in Belgium source standardized bead grades through specialty chemical marketplaces to bypass distributor markups.
- Industrial:Precision polishing and surface preparation applications require engineered particle size distributions with batch-to-batch consistency.
- Medical:Wound debridement and dermatological preparations demand EMA-validated biocompatibility with documented degradation kinetics in physiological conditions.
Personal care commands the largest volume share. Medical applications are expanding most quickly as device manufacturers seek absorbable particulate alternatives to synthetic options.
Material:
Supply maturity varies sharply between fermentation-scale biopolymers and emerging cultivation-based feedstocks.
- Plant-Based Polymers:Polylactic acid from corn starch fermentation and polyhydroxyalkanoates from bacterial cultivation have achieved commercial scale with validated OECD 306 marine biodegradability. BASF's Ludwigshafen complex anchors European supply for personal care formulators requiring REACH Annex XVII compliance.
- Algae:Cultivated microalgal biomass processed into spherical particles offers tunable degradation rates through lipid content adjustment. Norwegian and Portuguese cultivation facilities are scaling supply for Nordic cosmetic brands seeking differentiated sustainability positioning.
- Starch:Native and modified corn and potato starch beads provide lowest-cost options for price-sensitive household cleaning applications.
- Cellulose:Nanocellulose-reinforced beads enable hybrid structures with mechanical strength from plant polymers and controlled dissolution from crystalline cellulose domains.
Plant-based polymers absorb the majority of fermentation capacity. Algae cultivation is gaining share fastest as coastal European facilities achieve cost reductions through integrated biorefinery economics.
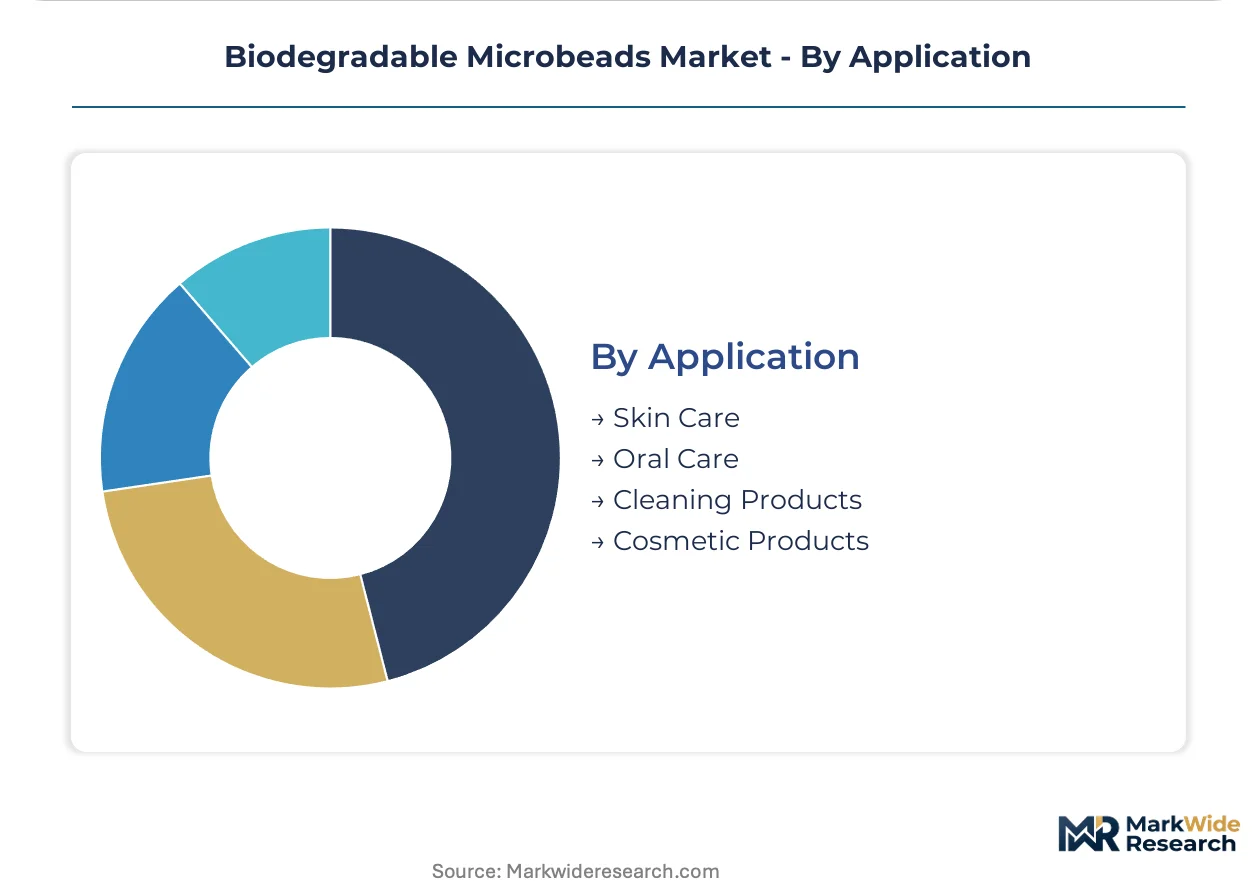
Application:
Regulatory timeline divergence creates distinct urgency levels across rinse-off versus leave-on product categories.
- Skin Care:Facial and body exfoliation products face immediate synthetic microbead elimination requirements under EU REACH Annex XVII with staggered deadlines through 2035. German formulators are responding fastest with pre-certified bead portfolios from domestic suppliers.
- Oral Care:Toothpaste manufacturers accelerate biodegradable abrasive adoption as ANSM-2024-001 and parallel national standards compress compliance windows. Mid-sized producers in the Netherlands and Belgium are establishing captive supply relationships to secure price stability.
- Cleaning Products:Household and industrial scrub formulations prioritize cost-optimized starch and cellulose options for non-cosmetic applications with less stringent certification requirements.
- Cosmetic Products:Decorative color cosmetics and leave-on treatments gain transitional periods under REACH implementation, allowing gradual reformulation toward certified biodegradable options.
Skin care channels the bulk of current certified bead procurement. Oral care is climbing the fastest as toothpaste manufacturers consolidate volumes ahead of enforcement deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biodegradable microbead production first achieved industrial scale in Germany during the early commercialization of polylactic acid fermentation. Ludwigshafen and Marl emerged as the continent's primary biopolymer clusters, anchoring European supply chains before regulatory pressure accelerated global capacity expansion.
Germany
Facial scrub manufacturers in Düsseldorf and Hamburg drive specification standards for REACH-compliant beads. ECHA enforcement of Annex XVII microplastic restrictions compresses formulation timelines for rinse-off cosmetics. BASF's Ludwigshafen complex supplies fermentation-derived PLA feedstock to personal care formulators across the Rhine-Ruhr industrial corridor.
France
ANSM-2024-001 national standards create premium positioning opportunities for early-certified suppliers ahead of baseline EU implementation. The country's national pharmaceutical regulator enforces stricter biodegradability documentation than neighboring member states. Cosmetic formulators in Île-de-France source algae-derived particles from Normandy cultivation facilities for differentiated sustainability claims.
Netherlands
Mid-sized toothpaste manufacturers in Rotterdam and Utrecht consolidate volumes through captive supply agreements with fermentation facilities. The Dutch national chemicals regulator coordinates with ECHA on transitional compliance timelines for oral care applications. Specialty chemical marketplaces in Amsterdam bypass traditional distributor markups for household cleaning product formulators.
United States
Oral care reformulation in New Jersey and Pennsylvania accelerates ahead of state-level microplastic legislation. FDA cosmetic ingredient oversight lacks federal microbead restrictions, creating a patchwork of California and New York state standards. NatureWorks operates fermentation capacity in Blair, Nebraska, supplying PLA feedstock to domestic personal care manufacturers.
Japan
Precision particle engineering for professional exfoliation applications concentrates in Osaka and Nagoya industrial zones. METI promotes biobased material adoption through procurement guidelines for government-sanctioned personal care products. Asahi Kasei and Daicel maintain integrated polymer-particle production chains for cosmetic and medical grade specifications.
Biodegradable Microbeads Market Competitive Environment
Capital-heavy fermentation-scale producers compete with asset-light particle engineering specialists for formulation partnerships. The market structures around three tiers: integrated biopolymer manufacturers with captive bead production, independent particle processors sourcing third-party feedstock, and cultivation-based alternatives developers. Dominant competitive moves include backward integration into fermentation capacity and direct-to-formulator digital channel establishment.
Among German-integrated chemical conglomerates, BASF and Evonik Industries exemplify the capital-intensive archetype with Ludwigshafen and Marl-based biopolymer complexes. Croda represents the specialty lipid-based alternative path that bypasses polymer classification entirely. Japanese diversified material groups Asahi Kasei and Daicel occupy positions linking fermentation science to precision particle engineering for regulated cosmetic and medical applications.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| Ajinomoto Co. |
| TerraVerdae Bioworks |
| Croda |
| Asahi Kasei Corporation |
| Daicel Corporation |
| Trelleborg AB |
| NatureWorks LLC |
| Others |
Value Chain & Pricing Dynamics
Captive biopolymer fermentation anchors supply positioning and pricing power for European microbead producers, with BASF and Evonik leveraging Ludwigshafen and Marl complexes to control both feedstock cost and bead certification timelines. This integration insulates integrated players from agricultural commodity swings while forcing independent processors to absorb margin compression from corn starch and sugarcane price volatility.
Pricing Analysis
Three-tier pricing structure across REACH-certified premium, transitional standard, and uncertified economy levels separates formulators by regulatory urgency. Certification grade and volume scale drive price differentiation, with toothpaste manufacturers consolidating volumes to offset agricultural input cost compression. Pricing pressure stems from biopolymer feedstock volatility as corn and sugarcane markets fluctuate with harvest cycles. Household cleaning product formulators exhibit highest price sensitivity, while medical-grade buyers prioritize batch consistency over unit cost.
Supply Chain Analysis
Biopolymer feedstock supply rests on German fermentation capacity, American corn belt agriculture, and Thai sugarcane processing infrastructure. Corn starch, bacterial cultivation media, and specialized spheronization equipment constitute critical input dependencies. Single-source vulnerability concentrates in Ludwigshafen's PLA output, where any disruption cascades through European personal care formulation networks. Distribution runs through direct-to-formulator digital channels for mid-volume buyers and long-term offtake agreements for oral care consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as REACH Annex XVII enforcement drives demand-shift toward EFSA-validated marine biodegradability specifications. Formulators now pay premiums for documented environmental fate data that earlier procurement cycles ignored.
For Market Incumbents: Hedge against algae-based substitute encroachment by locking multi-year corn starch supply contracts before harvest volatility intensifies. Prioritize OECD 306 certification pipeline expansion to maintain premium positioning against emerging Nordic cultivation competitors. Channel control through direct digital platforms protects margin structure from distributor disintermediation.
For New Entrants and Emerging Players: Specialty chemical marketplaces offer lowest-friction entry for mid-volume personal care manufacturers seeking bypass from traditional distribution markups. French ANSM-2024-001 implementation creates the most penetrable geography for early-certified suppliers willing to front-load documentation investment. Target oral care reformulation timelines with abrasive-grade particle portfolios that consolidate toothpaste manufacturer volumes.
For Investors and Strategic Acquirers: Roll-up economics work for independent particle processors with established formulator relationships because certification backlog creates acquisition currency for integrated biopolymer players seeking downstream access. Five-to-ten year viability hinges on EFSA evaluation capacity expansion rather than regulatory relaxation. Watch marine biodegradability certification queue length as the inflection signal for supply-constrained pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | BASF's Ludwigshafen complex demonstrates how captive PLA supply insulates margins from agricultural commodity cycles. |
| Direct-to-Formulator Digital Channel Launch | Amsterdam-based specialty chemical marketplaces bypass traditional distributor markups for mid-volume personal care manufacturers. |
| EFSA Marine Biodegradability Certification Investment | OECD 306 compliance documentation unlocks premium pricing under REACH Annex XVII enforcement timelines. |
| Long-term Supply Agreement with Oral Care Consolidators | Rotterdam and Utrecht toothpaste manufacturers consolidate volumes to secure price stability against feedstock volatility. |
| Joint Venture with Nordic Algae Cultivation Facilities | Norwegian and Portuguese coastal biorefineries offer differentiated sustainability positioning for premium cosmetic lines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biopolymer plant managers, personal care procurement leads, ECHA regulatory affairs specialists, and fermentation facility technical directors with secondary validation from EFSA guidance documents, REACH Annex XVII implementation notices, OECD 306 test protocols, and customs trade data for biopolymer feedstock flows. Bottom-up bead volume estimates triangulated against top-down personal care formulation demand models.
Historical reference periods anchored the projection horizon to pre-REACH restriction baseline demand and post-implementation substitution trajectories across skin care, oral care, cleaning products, and cosmetic applications. Segmentation dimensions modeled include product type, material category, end-user industry, and regional regulatory cluster complexity. CAGRs derived from fermentation capacity expansion curves and formulator reformulation timeline assumptions, with agricultural commodity price cycles and certification queue lengths as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for algae-derived particle commercialization would alter the outlook if cultivation cost curves steepen faster than projected. Forecasts reflect assumptions about EFSA evaluation throughput and member-state enforcement coordination. Regulatory divergence between EU baseline and national implementations, plus marine biodegradability validation delays, constitute the primary revision triggers. A small set of certification queue length, corn starch futures volatility, and French ANSM enforcement strictness warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Brazil Bioplastics Market
Bioplastics
China Bioplastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Biopolymer Films Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Bio-PET Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
North America Bioplastics Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
Asia-Pacific Bio Plasticizers Market