
 Bio-Degradable Polymers Market | 2026-2036
Bio-Degradable Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Degradable Polymers Market Outlook
Food-grade compostable certification is rotating from niche premium to baseline procurement requirement across European packaging supply chains. BASF SE leverages its integrated PBAT production network to anchor supply security for brand owners. NatureWorks LLC specializes in PLA fermentation technology, dominating North American biopolymer feedstock capacity. Novamont S.p.A. competes through proprietary starch-blend formulations that extend performance into agricultural film applications.
Bio-degradable polymers comprise macromolecular materials engineered to decompose into carbon dioxide, water, and biomass through microbial action under composting conditions, typically requiring controlled temperature, humidity, and oxygen levels above 50 degrees Celsius for complete mineralization within 180 days. These materials serve as drop-in replacements for conventional plastics in applications where end-of-life collection and industrial composting infrastructure exist. PLA currently occupies the largest production volume position due to mature fermentation and polymerization infrastructure, while PHA attracts R&D investment because its marine biodegradability opens ocean-facing packaging segments that other biopolymers cannot access. Starch blends sustain cost-competitive positioning in disposable tableware where thermal performance requirements remain modest.
The EU Single-Use Plastics Directive, administered by ECHA and national regulators, mandates specific labeling and material restrictions that directly expand addressable demand for certified compostable alternatives. FDA food-contact notifications and USDA bio-preferred procurement standards in the United States create parallel compliance pathways that shape product formulation decisions for exporters. BIS certification requirements in India add another layer of technical specification that manufacturers must navigate for market access. Stakeholders should monitor composting infrastructure buildout rates against polymer capacity announcements to avoid supply-demand mismatches in regional offtake corridors.
Market Dynamics
The EU Single-Use Plastics Directive creates immediate displacement pressure across European packaging supply chains, forcing reformulation of food-contact applications toward certified compostable substrates while industrial composting infrastructure races to match polymer capacity announcements.
Growth Catalysts
- EU Single-Use Plastics Directive:ECHA-administered bans on petroleum-based cutlery and plates mandate compostable alternatives, expanding addressable demand for PLA and PHA in food service applications.
- Industrial composting infrastructure buildout:Germany's expanded anaerobic digestion and composting facility network enables large-scale offtake of certified biodegradable packaging from food service operators.
- Marine biodegradability differentiation:PHA's unique ocean-degradation pathway opens packaging segments for fishing gear and coastal tourism where other biopolymers fail certification standards.
Market Restraints
- Feedstock cost volatility:Corn and sugarcane price swings directly compress PLA margins, linking biopolymer economics to agricultural commodity cycles without hedging mechanisms.
- Composting infrastructure gaps:Limited industrial composting availability in Eastern European markets strands certified compostable packaging in landfill streams, undermining value proposition.
- Performance limitations in high-heat applications:PLA's thermal ceiling below 60 degrees Celsius excludes hot-fill beverage and microwaveable food segments from conversion.
Strategic Opportunities
- Indian BIS certification pathway:Early compliance with Bureau of Indian Standards biodegradable requirements secures first-mover positioning in food packaging as urban composting infrastructure develops.
- Agricultural film conversion:Mulch film and silage wrap applications represent underpenetrated volume opportunity where soil-biodegradability standards match starch-blend performance characteristics.
- USDA BioPreferred procurement mandate:Federal purchasing preference for certified biobased products creates guaranteed offtake channel for compostable food service disposables in government cafeterias.
Industry Challenges
- Home composting certification complexity:Divergent OK Compost HOME and BPI home-compostable standards across jurisdictions force redundant testing and labeling investments for exporters.
- Contamination sorting infrastructure:MRF optical sorting systems lack polymer-specific detection for PLA and PHA, causing compostable packaging to contaminate conventional plastic recycling streams.
- Fermentation scale-up talent scarcity:Industrial microbiology and bioprocess engineering expertise concentrates in pharmaceutical and biofuel sectors, constraining polymer plant operational readiness.
Report Scope
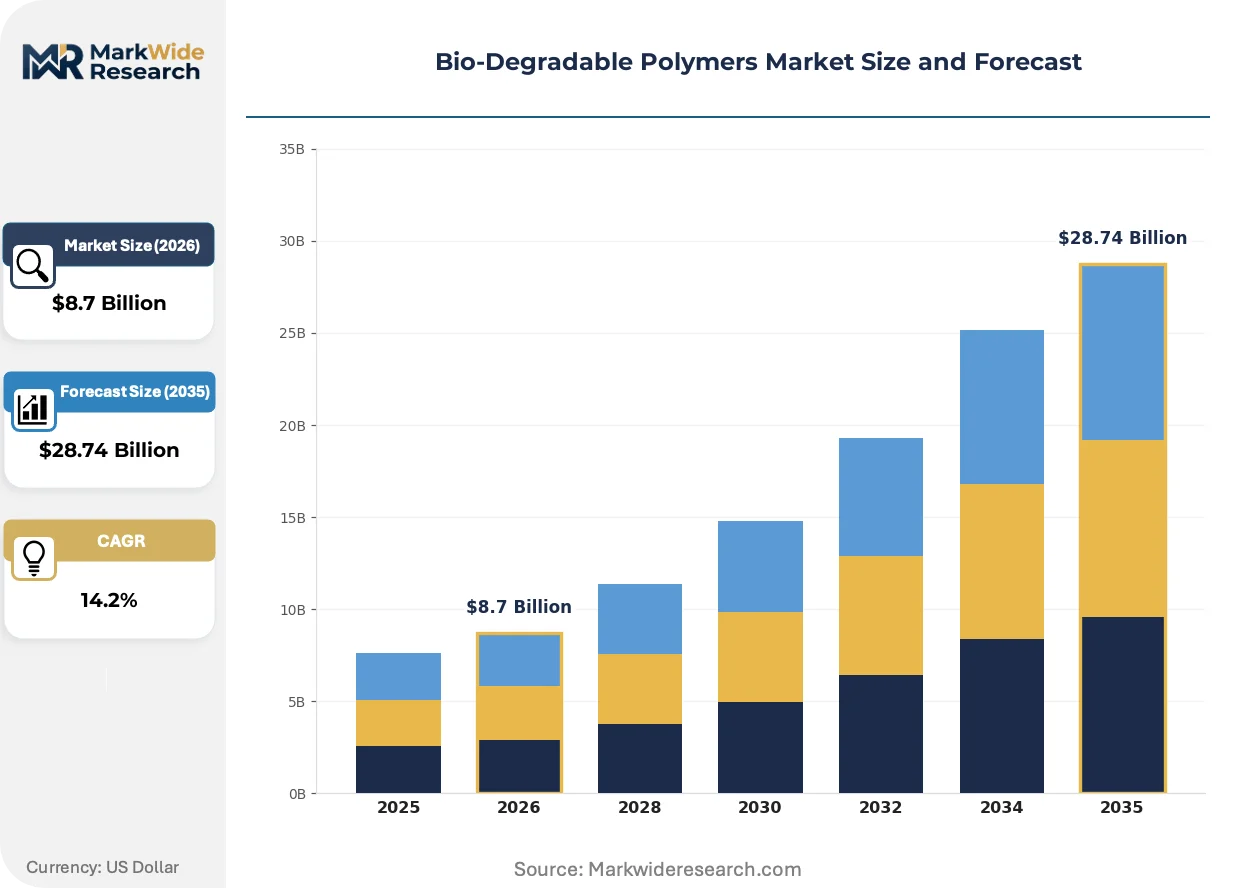
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Degradable Polymers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, PBAT Application: Packing Materials, Agricultural Films, Disposable Tableware, Pharmaceutical Packaging End User: Packaging Industry, Agriculture, Food Service, Consumer Goods Delivery Mode: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | BASF SE, NatureWorks LLC, TotalEnergies Corbion, Novamont S.p.A., Mitsubishi Chemical Group, Biome Bioplastics, Danimer Scientific, Evonik Industries, FKuR Kunststoff GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Degradable Polymers Market Strategic Shifts
Active reformulation across polymer architectures is compressing performance gaps with conventional plastics while regulatory mandates accelerate certification standardization and end-of-life infrastructure investment.
PHA copolymer formulations engineered for marine biodegradability are displacing conventional polypropylene in fishing gear and aquaculture equipment. Norwegian and Japanese fishing cooperatives pilot PHA net and line replacements to preempt lost-gear plastic pollution penalties. The technology is displacing petroleum-based alternatives in coastal regulatory zones where ocean-degradability certification determines procurement eligibility.
REACH registration requirements for biodegradable polymers are tightening substance safety documentation across EU member states. ECHA's expanded dossier demands for polymer additives and processing aids extend compliance timelines for new market entrants. Food-contact notification pathways at EFSA now require composting degradation product toxicology, affecting PLA and starch-blend importers most acutely.
Food service distributors now bundle compostable packaging with organic waste collection services, converting transactional product sales into integrated waste-management contracts. Sodexo and Compass Group procurement teams specify vendor-provided composting logistics alongside material certification. This bundled-service model concentrates most visibly in German and French institutional catering contracts where waste diversion targets bind operators.
Bio-Degradable Polymers Market Segmentation
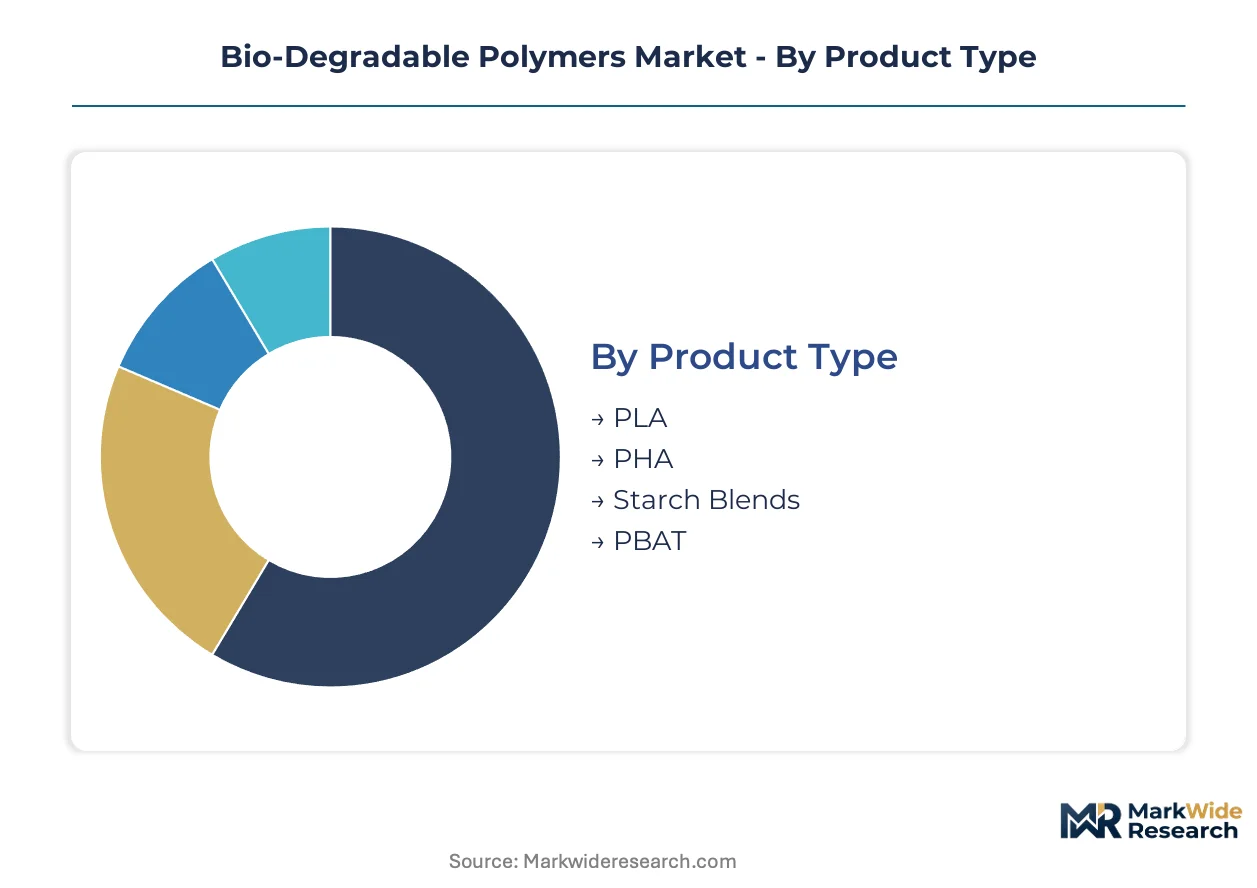
Biodegradable polymer procurement splits along technical performance requirements and end-of-life infrastructure availability. Margin pools concentrate where certification complexity creates supplier scarcity and where composting logistics bundle with material supply.
Product Type:
PLA commands premium pricing in food-contact applications where fermentation scale and polymerization maturity reduce unit costs. PHA extracts margin premiums from marine biodegradability certifications that exclude competing chemistries.
- PLA:Polylactic acid derives from corn starch or sugarcane fermentation, polymerized to crystalline or amorphous grades. German food service operators and North American brand owners anchor demand where industrial composting infrastructure validates end-of-life claims. ECHA-administered EU Single-Use Plastics Directive mandates displace petroleum-based cutlery toward PLA alternatives.
- PHA:Polyhydroxyalkanoates accumulate intracellularly through bacterial fermentation of feedstocks ranging from sugars to waste oils. Norwegian and Japanese fishing cooperatives pilot PHA net and line replacements where ocean-degradability certification determines procurement eligibility against lost-gear plastic pollution penalties.
- Starch Blends:Thermoplastic starch compounded with biodegradable polyesters serves cost-sensitive disposable tableware in French and German institutional catering.
- PBAT:Polybutylene adipate terephthalate delivers flexibility and toughness in mulch films and compost bags where BASF SE anchors European supply security.
The dominant share belongs to PLA, while PHA is closing the gap fastest.
Application:
Volume concentrates in packaging where regulatory bans on petroleum-based items create immediate substitution demand. Agricultural film applications expand where soil-biodegradability standards align with starch-blend performance.
- Packing Materials:Flexible films, rigid trays, and protective cushioning for food and consumer goods. German and French distributors bundle compostable packaging with organic waste collection services under Sodexo and Compass Group procurement specifications.
- Agricultural Films:Mulch films, silage wraps, and greenhouse covers designed for soil biodegradation. Italian and Spanish vegetable producers drive adoption where till-in disposal eliminates collection costs.
- Disposable Tableware:Cutlery, plates, cups, and containers for food service. PLA thermal ceiling below 60 degrees Celsius excludes hot-fill beverage applications.
- Pharmaceutical Packaging:Blister packs, bottles, and delivery devices requiring EMA compliance and degradation product toxicology documentation.
Packing Materials holds the volume lead, though Agricultural Films is expanding most quickly as soil-biodegradability certifications proliferate.
End User:
Procurement authority concentrates in packaging industry buyers who specify material certifications and composting logistics simultaneously. Food service operators convert transactional supply relationships into integrated waste-management contracts.
- Packaging Industry:Converters and brand owners specifying substrate performance for food, consumer goods, and industrial applications. REACH registration requirements and EFSA food-contact notifications constrain formulation choices.
- Agriculture:Farmers and cooperatives deploying soil-biodegradable films for crop management. Italian tomato and strawberry producers anchor Mediterranean demand.
- Food Service:Restaurants, cafeterias, and catering operations replacing petroleum-based disposables. USDA BioPreferred procurement standards create guaranteed offtake in US government facilities.
- Consumer Goods:Retail brands and household product manufacturers seeking shelf differentiation through compostable packaging.
Packaging Industry retains the largest procurement volume, while Food Service is gaining share fastest through bundled composting service models.
Delivery Mode:
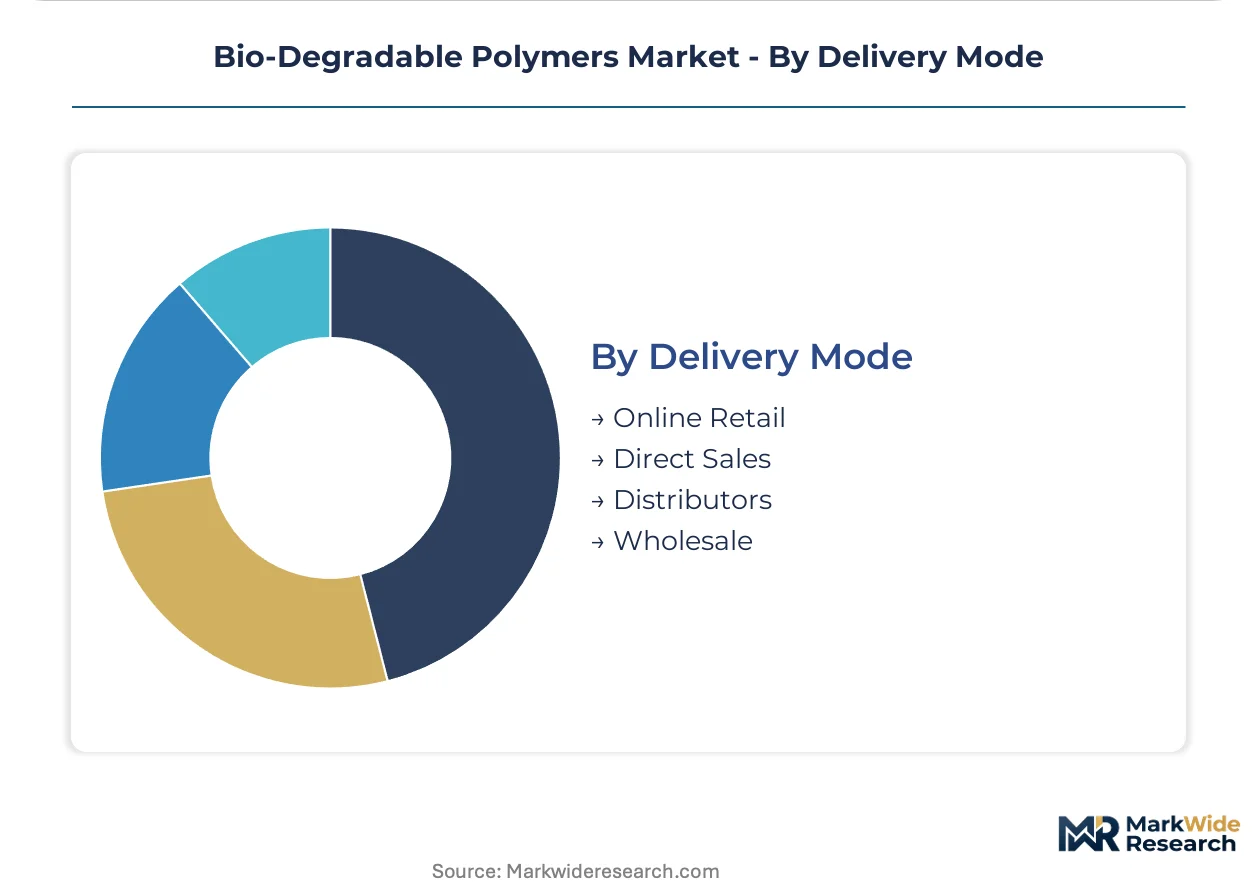
Channel selection tracks customer scale and technical service requirements. Large food service operators demand direct supply with logistics integration, while fragmented buyers rely on distributor inventory.
- Direct Sales:Manufacturer relationships with large food service operators and packaging converters. BASF SE and NatureWorks LLC anchor supply security through long-term offtake agreements.
- Distributors:Regional inventory and technical support for mid-size converters. German and French packaging supply chains rely on distributor certification documentation.
- Online Retail:E-commerce platforms serving small-scale buyers and specialized applications.
- Wholesale:Bulk transactions for commodity-grade starch blends in agricultural and tableware segments.
Direct Sales commands the highest value share, while Distributors is climbing the fastest as mid-market food service adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for bio-degradable polymers concentrates in Asian packaging markets while European producers leverage integrated fermentation capacity to capture export premiums. Trade flows track regulatory arbitrage opportunities as jurisdictions with mature composting infrastructure absorb polymer supply from regions where end-of-life validation remains underdeveloped.
Germany
Industrial composting facility density in Bavaria and North Rhine-Westphalia enables large-scale offtake of PLA and PHA from food service operators. ECHA-administered REACH registration requirements constrain new market entrants through extended substance safety documentation timelines. BASF SE anchors European PBAT supply security from its Ludwigshafen production complex, serving brand owners with integrated polymer and certification pathways.
United States
USDA BioPreferred procurement standards create guaranteed offtake channels for compostable food service disposables across federal government cafeterias. FDA food-contact notification pathways shape formulation decisions for exporters targeting North American food packaging applications. NatureWorks LLC dominates domestic biopolymer feedstock capacity through its Blair, Nebraska fermentation facility, supplying brand owners with PLA resin certified for industrial composting.
India
Urban composting infrastructure development in Maharashtra and Gujarat drives demand for certified biodegradable packaging from quick-service restaurant chains. BIS certification requirements for biodegradable products add technical specification layers that manufacturers must navigate for market access. Mumbai-based converters are piloting starch-blend tableware production to serve institutional catering contracts with municipal waste diversion mandates.
Japan
Fishing cooperative demand for marine-biodegradable gear in Hokkaido and Kyushu anchors PHA adoption where ocean-degradability certification determines procurement eligibility. METI guidelines on plastic resource circulation establish performance benchmarks for biodegradable alternatives in coastal regulatory zones. Osaka polymer processors are developing PHA copolymer formulations for aquaculture equipment to preempt lost-gear plastic pollution penalties.
France
Institutional catering procurement in Île-de-France specifies bundled compostable packaging with organic waste collection services under Sodexo and Compass Group contracts. EFSA food-contact notification requirements now mandate composting degradation product toxicology documentation for PLA importers. Lyon-based distributors are consolidating mid-market food service supply chains through certification documentation and logistics integration services.
Bio-Degradable Polymers Market Competitive Environment
Listed leaders compete with private specialists across certification complexity and fermentation scale dimensions. Market structure tieres between integrated chemical conglomerates with captive feedstock positions and dedicated biopolymer specialists with proprietary fermentation technology. Three archetypes dominate: diversified chemical majors leveraging polymerization infrastructure, pure-play biopolymer developers with microbial engineering capabilities, and regional compounders serving niche certification requirements. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players race to match polymer announcements with offtake agreements.
Within the integrated chemical major tier, BASF SE and Mitsubishi Chemical Group exemplify scale-driven positioning through backward control over petrochemical and fermentation feedstocks. Among dedicated biopolymer specialists, NatureWorks LLC and Danimer Scientific occupy positions defined by microbial engineering capabilities and proprietary strain development. Novamont S.p.A. represents the regional compounder archetype with starch-blend formulations extending into agricultural film applications where soil-biodegradability standards create supplier scarcity.
| Leading Market Players |
|---|
| BASF SE |
| NatureWorks LLC |
| TotalEnergies Corbion |
| Novamont S.p.A. |
| Mitsubishi Chemical Group |
| Biome Bioplastics |
| Danimer Scientific |
| Evonik Industries |
| FKuR Kunststoff GmbH |
| Others |
Value Chain & Pricing Dynamics
PLA displacing petroleum-based polypropylene in German food service packaging simultaneously shifts supply geography toward corn-belt fermentation clusters and compresses pricing premiums as NatureWorks LLC scales Blair, Nebraska capacity. This substitution dynamic concentrates pricing power with integrated producers while fragmenting margin pools among regional compounders lacking captive feedstock positions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock resin volumes against agricultural commodity volatility. Price differentiation separates FDA food-contact certified grades from industrial composting tiers, with EFSA degradation product toxicology documentation commanding additional premiums. Cost compression in standard PLA grades is intensifying because BASF SE and TotalEnergies Corbion are expanding European PBAT and PLA nameplate capacity ahead of offtake agreements. Quick-service restaurant chains exhibit highest price sensitivity, while pharmaceutical packaging converters tolerate premium positioning for EMA-compliant documentation.
Supply Chain Analysis
Fermentation scale-up talent scarcity in industrial microbiology acts as a chokepoint constraining operational readiness at new polymer plants. Geographic supply concentrates in the United States, Germany, and Thailand, where NatureWorks LLC, BASF SE, and TotalEnergies Corbion anchor respective regional hubs. Raw material dependencies draw from corn starch, sugarcane bagasse, and waste glycerol feedstocks. Single-source vulnerability in bacterial strain IP exposes producers to licensing disputes. Distribution runs through direct sales relationships with large food service operators, supplemented by regional distributors serving mid-market converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial bioprocess engineering expertise pools in pharmaceutical and biofuel sectors, leaving polymer plant operations chronically understaffed and creating persistent capability gaps that favor incumbents with captive training pipelines.
For Market Incumbents: Compound fermentation capacity advantages by securing long-term corn and sugarcane supply agreements with agricultural cooperatives in Iowa and São Paulo before commodity hedging costs escalate. Defend margin position against Novamont S.p.A. starch-blend competition through accelerated marine biodegradability certification for PHA copolymers targeting Japanese fishing cooperatives. For New Entrants and Emerging Players: Lead with BIS certification compliance for the Indian quick-service restaurant segment, where urban composting infrastructure development in Maharashtra outpaces certified resin supply. Agricultural film applications in Italian tomato production represent underpenetrated volume opportunity where soil-biodegradability standards match lower-performance starch-blend specifications. Bundle composting logistics with material supply to replicate Sodexo procurement models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biopolymer specialists holding proprietary bacterial strains but lacking integrated polymerization infrastructure. Five-to-ten year viability hinges on composting infrastructure buildout rates matching capacity announcements rather than fermentation technology differentiation alone. Monitor ECHA REACH registration timeline extensions as inflection indicator for competitive entry barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn and sugarcane supply agreements with Iowa and São Paulo agricultural cooperatives reduce margin volatility. |
| Marine Biodegradability Certification | PHA copolymer ocean-degradability documentation unlocks Japanese fishing gear procurement eligibility. |
| Composting Logistics Bundling | Integrated organic waste collection services replicate Sodexo and Compass Group contract specifications. |
| BIS Certification Compliance | Bureau of Indian Standards biodegradable requirements secure first-mover positioning in Maharashtra food packaging. |
| Fermentation Scale-Up Talent Acquisition | Industrial microbiology expertise recruitment from pharmaceutical sectors accelerates polymer plant operational readiness. |
Study Parameters
Operator-level perspectives from plant managers at fermentation facilities, procurement leads at German food service distributors, technical R&D directors at starch-blend compounders, and composting facility operators anchored the qualitative base. Secondary validation drew from ECHA REACH registration databases, USDA BioPreferred procurement records, BIS certification filings, and SEC 10-K disclosures from integrated chemical majors. Bottom-up resin capacity buildouts and top-down packaging demand projections were triangulated against industrial composting infrastructure development timelines.
Sensitivity analysis tested forecast outputs against feedstock cost volatility scenarios and regulatory implementation delays across the projection horizon. Segmentation dimensions modeled include polymer chemistry tier, food-contact certification grade, end-use application cluster, and regional composting infrastructure maturity. CAGRs were derived from elasticity-adjusted demand projections and capacity absorption rates. Industry-specific inputs incorporated EFSA degradation product toxicology documentation timelines and METI marine biodegradability certification pathways.
Forecasts assume regulatory continuity in EU Single-Use Plastics Directive enforcement and USDA BioPreferred procurement standards; material policy shifts would require re-modeling demand elasticity assumptions. Practitioners should keep alternative scenarios live as industrial composting facility permitting delays and agricultural commodity price spikes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
China Bioplastics Market
Bioplastics
Bio-PET Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Biopolymers Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Automotive Bioplastic Market
Bioplastics
North America Bioplastics Market