
 Asia-Pacific Lactic Acid Market | 2026-2036
Asia-Pacific Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lactic Acid Market Outlook
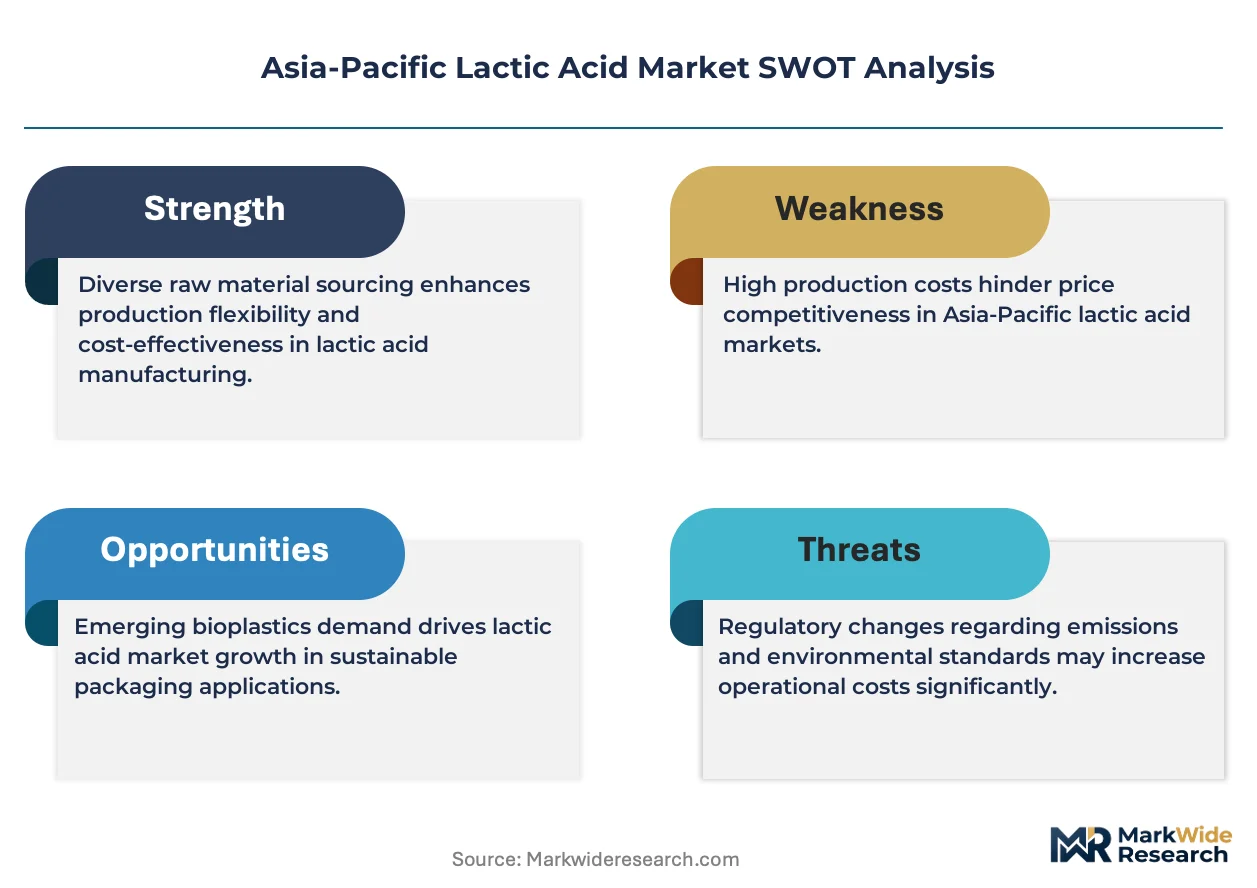
REACH-equivalent substance registration under China's MEE Order 12 is unwinding market access for smaller fermentation-derived chemical exporters. Corbion NV leverages its Thai fermentation complex to sustain pharmaceutical-grade supply chains across Southeast Asia. Henan Jindan Lactic Acid Technology anchors domestic food-grade volume through integrated corn starch processing in Henan province. BASF SE competes on synthetic route purity for industrial polymer applications where petrochemical-derived material still holds specification advantages.
Lactic acid is a chiral alpha-hydroxy acid produced through carbohydrate fermentation or petrochemical synthesis, typically supplied at 80-88% aqueous concentration for industrial use and higher purities for pharmaceutical and food applications. Its primary commercial purpose spans pH modulation, preservative action, and as a monomer precursor for polylactic acid bioplastics. Food-grade material dominates current volume flows across the region, while biodegradable plastics represents the fastest-expanding application segment as brand owners mandate polymer feedstock transitions. Pharmaceutical-grade production commands the deepest margin pool due to sterility validation and documentation burdens that constrain supplier counts.
China's MEE enforces fermentation effluent discharge limits that raise capital requirements for new lactic acid capacity, while Japan's METI chemical substance management framework shapes import documentation for cross-border bioplastic raw material trade. India's BIS certification for food additives creates additional gatekeeping for suppliers targeting processed food manufacturers in Maharashtra and Gujarat. Stakeholders must monitor how evolving green chemistry procurement mandates from downstream packaging and textile buyers redirect specification requirements across the regional supply base.
Market Dynamics
China's MEE Order 12 registration requirements are compressing market access for smaller fermentation-derived acidulant exporters, while eastern China's chemical processing corridors concentrate capacity expansion and downstream bioplastic integration accelerates specification divergence between food-grade and polymer-grade supply chains.
Growth Catalysts
- Bioplastic feedstock mandates:Brand owners across packaging and textiles are mandating polylactic acid polymer transitions, pulling fermentation-derived lactic acid into industrial monomer applications at volumes previously reserved for petrochemical routes.
- Japan's positive chemical substance listings:METI's streamlined import documentation for listed bioplastic raw materials reduces cross-border friction for fermentation-derived acidulants meeting purity thresholds.
- Henan province corn starch integration:Central China's agricultural processing base anchors captive carbohydrate supply for fermentation economics, lowering input cost volatility against synthetic route competitors.
Market Restraints
- Feedstock price volatility:Corn starch and molasses input costs fluctuate with regional harvest cycles and biofuel policy arbitrage, compressing fermentation margin stability against fixed-cost synthetic production.
- Supplier concentration in eastern China:Shandong and Jiangsu provinces host disproportionate fermentation capacity, creating geographic single-point vulnerability for regional supply security.
- Purification ceiling for polymer-grade material:Optical purity requirements exceeding 99.5% L-lactic acid constrain fermentation yield economics and require capital-intensive chromatographic separation.
Strategic Opportunities
- Southeast Asia greenfield fermentation:Thailand and Vietnam offer untapped molasses feedstock access and less stringent MEE-equivalent discharge limits for new capacity targeting ASEAN bioplastic demand.
- Pharmaceutical-grade sterility validation:Injectable and ophthalmic application documentation burdens limit qualified suppliers, deepening margin pools for GMP-certified fermentation operations.
- Dual carbon policy alignment:China's national carbon intensity targets create procurement preference for bio-based acidulants in state-owned enterprise chemical purchasing.
Industry Challenges
- Chromatographic separation engineering talent:Polymer-grade optical purity production requires scarce biochemical process engineers familiar with simulated moving bed or membrane electrodialysis systems.
- MEE effluent compliance capex:New fermentation capacity requires anaerobic digestion and nutrient recovery systems that extend project payback periods beyond synthetic route alternatives.
- BIS certification timeline compression:India's food additive approval process creates 18-24 month market entry delays for suppliers targeting Maharashtra and Gujarat processed food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lactic Acid Market |
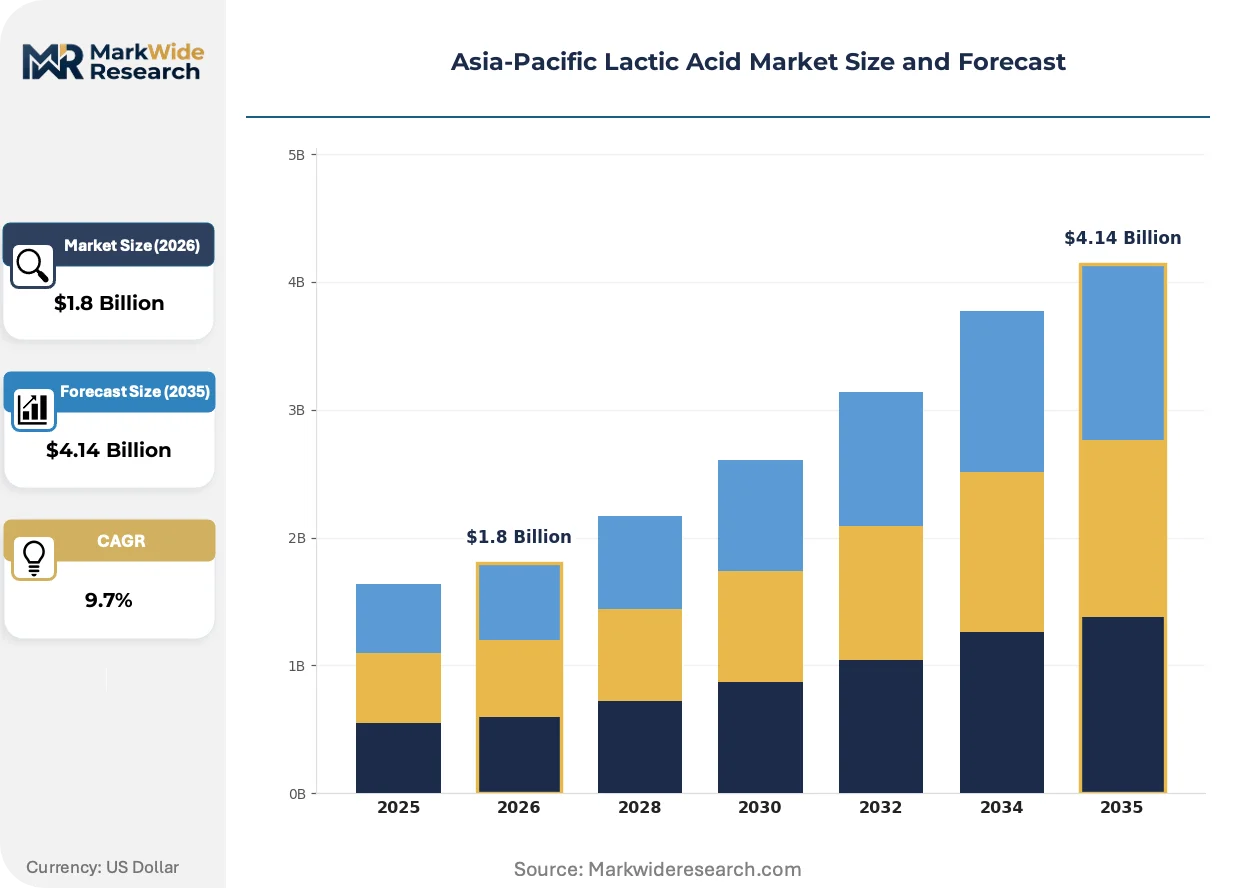
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food Preservation, Biodegradable Plastics, Personal Care Products, Pharmaceuticals Form: Liquid, Powder, Granular, Tablet End User: Food & Beverage, Healthcare, Cosmetics, Agriculture |
| Companies Covered | Corbion NV, Henan Jindan Lactic Acid Technology Co., Ltd, BASF SE, Cargill, Incorporated, Galactic, NatureWorks LLC, DuPont, Teijin Ltd., Cellulac, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lactic Acid Market Strategic Shifts
Continuous fermentation process control and downstream membrane filtration advances are compressing unit economics for high-purity production, while regulatory frameworks across the region harden purity documentation requirements that favor integrated fermentation-to-polymer operations.
Membrane electrodialysis purification is decomposing traditional calcium salt precipitation and sulfuric acid regeneration steps in lactic acid recovery. Bioplastic polymer producers in Jiangsu and Zhejiang are adopting this technology at pilot scale. The shift is decomposing capital intensity barriers that previously locked fermentation-derived material out of specification-critical industrial monomer applications.
China's MEE Order 12 implements REACH-equivalent substance registration for fermentation-derived chemicals crossing into industrial polymer supply chains. The framework requires full toxicological dossiers and environmental fate data that smaller exporters cannot assemble. Importers in Shanghai and Ningbo free-trade zones are consolidating supplier panels to documented registrants exclusively.
Brand-owner green chemistry mandates are compressing procurement evaluation cycles from annual to quarterly reviews. Packaging and textile manufacturers in Japan and South Korea now require chain-of-custody documentation for bioplastic feedstock carbon intensity. Supplier qualification friction is most visible in cross-border trade where METI and MFDS documentation requirements overlap.
Asia-Pacific Lactic Acid Market Segmentation
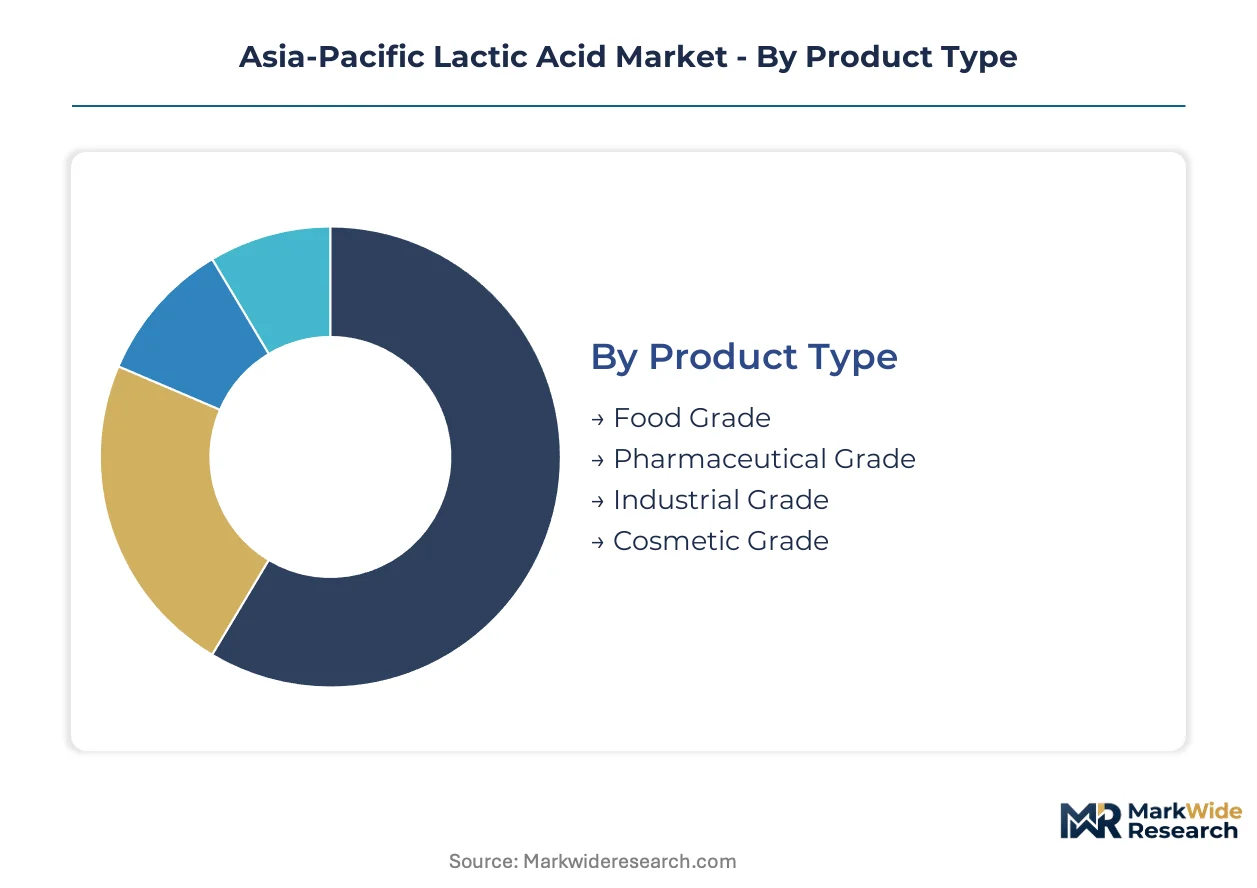
Lactic acid specification tiers command divergent margin structures across the Asia-Pacific supply base. Pharmaceutical and polymer-grade material extracts premium pricing through documentation burdens and optical purity thresholds that constrain qualified supplier counts.
Product Type:
Margin pools deepen with sterility validation requirements and optical purity thresholds that limit fermentation yield economics.
- Food Grade:Typically supplied at 80-88% aqueous concentration with pH modulation and preservative functionality as core specifications. Demand concentrates in eastern China's processed food manufacturing corridors where Shandong and Jiangsu provinces host disproportionate fermentation capacity serving clean-label preservation mandates.
- Pharmaceutical Grade:Requires sterility validation, endotoxin testing, and comprehensive documentation for injectable and ophthalmic applications. Maharashtra and Gujarat pharmaceutical manufacturers in India drive procurement through BIS certification requirements that create 18-24 month supplier qualification timelines.
- Industrial Grade:Synthetic route material from petrochemical feedstocks competes on fixed-cost stability against fermentation volatility.
- Cosmetic Grade:Lower volume tier serving pH adjustment and exfoliant applications in South Korean and Japanese personal care formulations.
Food Grade holds installed capacity. Pharmaceutical Grade is rotating up the share rankings.
Application:
Application segmentation tracks how downstream specification requirements reshape procurement evaluation cycles from annual to quarterly reviews.
- Food Preservation:Dominates current volume flows through pH control and antimicrobial action in processed meat, dairy, and ready-to-eat categories. China's national food safety standards tighten purity requirements for imported acidulants while domestic Henan province corn starch integration anchors captive supply economics.
- Biodegradable Plastics:Polylactic acid polymer feedstock demand climbs fastest as brand owners across Japanese and South Korean packaging and textile sectors mandate chain-of-custody documentation for carbon intensity verification.
- Personal Care Products:pH buffering and skin conditioning functions in ASEAN cosmetic manufacturing.
- Pharmaceuticals:Injectable and ophthalmic documentation burdens limit qualified suppliers to GMP-certified fermentation operations.
Food Preservation commands current volume leadership. Biodegradable Plastics posts the steepest expansion trajectory.
Form:
Form factor selection correlates with transportation economics and downstream handling infrastructure across the regional supply base.
- Liquid:Standard 80-88% aqueous concentration dominates industrial procurement through tanker and IBC distribution networks serving chemical processing corridors.
- Powder:Spray-dried material serves pharmaceutical and food manufacturers requiring extended shelf stability and precise dosing control.
- Granular:Intermediate handling characteristics for agricultural and select industrial applications.
- Tablet:Specialized direct-compression feedstock for pharmaceutical tableting operations.
Liquid holds installed capacity. Powder is rotating up the share rankings.
End User:
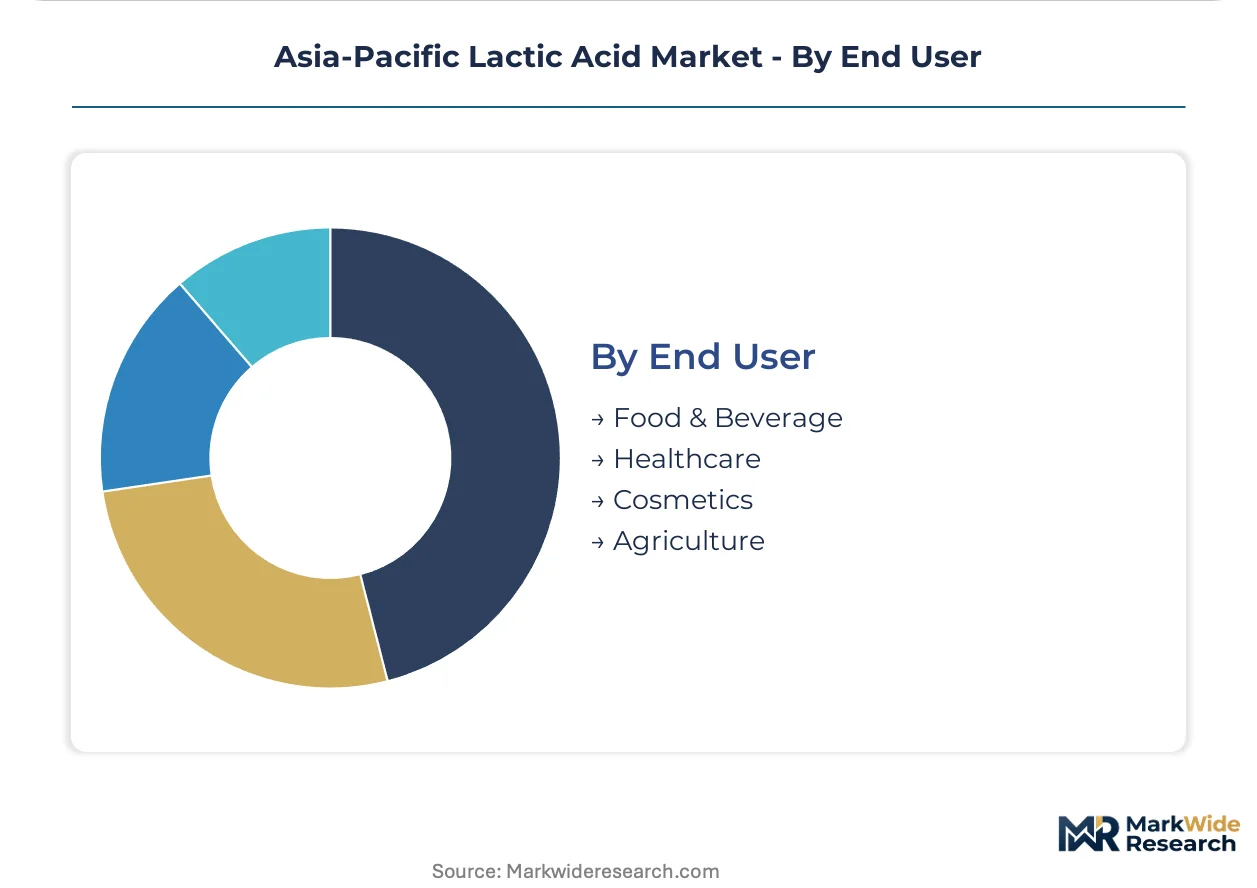
End user segmentation reveals how green chemistry procurement mandates redirect specification requirements across state-owned enterprise and private purchasing frameworks.
- Food & Beverage:Clean-label preservation demand from processed food manufacturers in Maharashtra, Gujarat, and eastern China's chemical corridors. China's dual carbon policy alignment creates procurement preference for bio-based acidulants in state-owned enterprise chemical purchasing.
- Healthcare:Pharmaceutical-grade sterility requirements concentrate demand among GMP-certified Thai and Chinese fermentation complexes serving Southeast Asia injectable markets.
- Cosmetics:pH modulation and exfoliant functionality in South Korean and Japanese personal care formulation.
- Agriculture:Silage preservation and feed acidification in Australian and New Zealand dairy operations.
Food & Beverage holds installed capacity. Healthcare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex underwrites eastern China's dominance in lactic acid trade flows, handling bulk liquid acidulant shipments and bioplastic raw material exports across the Pacific Rim. This maritime infrastructure anchors the region's chemical processing corridors where fermentation capacity clusters.
China
Shandong and Jiangsu provinces concentrate fermentation capacity serving food-grade and polymer-grade demand. MEE Order 12 registration requirements compress market access for smaller exporters while tightening purity documentation. The Yangtze River Delta chemical corridor integrates downstream bioplastic production with captive lactic acid supply.
Japan
METI's positive chemical substance listings streamline import documentation for fermentation-derived acidulants meeting pharmaceutical and polymer-grade thresholds. Kanto region packaging manufacturers mandate chain-of-custody carbon intensity verification for polylactic acid feedstock procurement.
India
Maharashtra and Gujarat processed food manufacturers drive food-grade acidulant demand through BIS certification requirements. The 18-24 month supplier qualification timeline creates procurement consolidation among documented registrants. Western India pharmaceutical clusters source injectable-grade material through GMP-certified supply chains.
Thailand
Corbion NV's Thai fermentation complex anchors pharmaceutical-grade supply chains across Southeast Asia. The country's molasses feedstock access and less stringent effluent discharge limits attract greenfield capacity targeting ASEAN bioplastic demand. Bangkok-based distributors serve regional personal care and food manufacturing.
South Korea
MFDS documentation requirements overlap with METI frameworks for cross-border bioplastic raw material trade. Seoul Capital Area packaging manufacturers compress procurement evaluation cycles to quarterly reviews under brand-owner green chemistry mandates. Busan-Ulsan chemical processors integrate membrane electrodialysis purification at pilot scale.
Asia-Pacific Lactic Acid Market Competitive Environment
Listed leaders compete with private specialists across fermentation capacity and synthetic route purity. The market structures around three tiers: integrated agri-processing conglomerates with captive starch supply, standalone fermentation specialists with GMP certification, and petrochemical majors competing on fixed-cost stability. Strategic moves concentrate on backward integration into corn starch processing and chromatographic separation capacity for polymer-grade optical purity.
Within the fermentation specialist tier, Henan Jindan Lactic Acid Technology Co., Ltd exemplifies private Chinese manufacturers with provincial agri-processing integration. Corbion NV and BASF SE occupy positions representing the divergence between bio-based and synthetic route positioning. These anchors illustrate how supplier archetypes map to specification tiers from food-grade volume through pharmaceutical-grade sterility validation.
| Leading Market Players |
|---|
| Corbion NV |
| Henan Jindan Lactic Acid Technology Co., Ltd |
| BASF SE |
| Cargill, Incorporated |
| Galactic |
| NatureWorks LLC |
| DuPont |
| Teijin Ltd. |
| Cellulac |
| Others |
Value Chain & Pricing Dynamics
Scale economies in eastern China's fermentation corridors concentrate polymer-grade capacity among integrated operators, compressing unit cost floors while elevating documentation burdens that smaller exporters cannot absorb. This concentration simultaneously anchors regional price benchmarks and fragments procurement access for buyers lacking MEE Order 12 registration pathways.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade sterility validation from food-grade commodity flows, with optical purity thresholds exceeding 99.5% L-lactic acid commanding substantial premiums. Price differentiation hinges on certification grade against MEE Order 12 registrant status and chromatographic separation capability. Cost compression in polymer-grade tiers is intensifying because membrane electrodialysis adoption decomposes traditional calcium salt precipitation economics. Food-grade buyers in Maharashtra and Gujarat exhibit highest price sensitivity, while injectable-grade pharmaceutical manufacturers demonstrate lowest elasticity due to GMP validation switching costs.
Supply Chain Analysis
Inventory lead times stretch 18-24 months for BIS-certified suppliers targeting Indian processed food manufacturers, compressing procurement flexibility against spot-market alternatives. Supply concentrates in China's Shandong and Jiangsu provinces, Thailand's molasses corridor, and Japan's METI-listed import channels. Raw material dependencies center on corn starch from Henan province, Southeast Asian molasses, and petrochemical feedstocks for synthetic routes. Single-source vulnerability runs through eastern China's disproportionate fermentation capacity. Distribution runs through Ningbo-Zhoushan Port bulk liquid handling and Bangkok-based regional distributors serving ASEAN personal care manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a bioplastic feedstock mandate recovery, as brand-owner green chemistry procurement compresses evaluation cycles and redirects specification requirements toward fermentation-derived supply chains.
For Market Incumbents: Secure chromatographic separation engineering talent through targeted recruitment in Jiangsu and Zhejiang membrane electrodialysis pilot operations. Defend against synthetic route price competition by deepening backward integration into Henan province corn starch processing. GMP certification investment in Thai fermentation complexes anchors pharmaceutical-grade margin pools against emerging ASEAN capacity. For New Entrants and Emerging Players: Anchor in Vietnam's molasses feedstock access and less stringent effluent discharge limits for greenfield capacity targeting ASEAN bioplastic demand. White-space availability concentrates in cosmetic-grade pH adjustment for South Korean personal care formulators and silage preservation for Australian dairy operations. Go-to-market positioning through Bangkok-based distributors bypasses MEE Order 12 registration barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fermentation-to-polymer operations with captive carbohydrate supply and membrane purification capability. Long-term viability across the projection horizon rests on dual carbon policy alignment in Chinese state-owned enterprise procurement frameworks. Acquisition targeting should concentrate on GMP-certified specialists with MEE Order 12 dossier completion. The inflection signal to watch is brand-owner chain-of-custody documentation mandates spreading from Japanese packaging to South Korean textile manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrodialysis Capacity Expansion | Jiangsu and Zhejiang bioplastic producers adopt pilot-scale purification, decomposing calcium salt precipitation economics. |
| Backward Integration into Corn Starch Processing | Henan province agricultural base anchors captive carbohydrate supply, lowering input cost volatility against synthetic competitors. |
| MEE Order 12 Registration Completion | Full toxicological dossiers unlock industrial polymer supply chain access for fermentation-derived acidulants in Shanghai free-trade zones. |
| GMP Certification Investment | Thai fermentation complexes deepen pharmaceutical-grade margin pools through sterility validation for Southeast Asia injectable markets. |
| Long-term Supply Agreement with Brand Owners | Japanese packaging manufacturers mandate quarterly chain-of-custody reviews, consolidating procurement panels to documented registrants. |
Study Parameters
A spread of perspectives from fermentation plant managers, downstream bioplastic procurement leads, MEE regulatory consultants, and Bangkok-based ASEAN distributors converged on the working assumptions underlying supply concentration and specification divergence. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings from listed chemical processors, MEE substance registration databases, and METI positive chemical substance listings. Bottom-up capacity modeling triangulated against top-down demand segmentation across food preservation, pharmaceutical, and polymer-grade application tiers.
Segmentation dimensions modeled span product grade tier, end-use industry vertical, downstream form factor, and regional production hub concentration across the analysis window. CAGRs were derived from installed capacity utilization trajectories and brand-owner procurement mandate diffusion patterns. Industry-specific forecast inputs incorporated MEE Order 12 registration timeline compression and membrane electrodialysis adoption curves in Jiangsu and Zhejiang chemical corridors.
Material uncertainties — feedstock price volatility from biofuel policy arbitrage, BIS certification timeline delays, and chromatographic separation yield constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory documentation burden stability and bioplastic feedstock mandate penetration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Biocomposite Materials Market
Bioplastics
China Bioplastics Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Global Bioplastic Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Biodegradable Plastics Market