
 Biodegradable Plastics Market | 2026-2036
Biodegradable Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Plastics Market Intelligence
The shift toward flexible and rigid packaging applications from traditional agricultural mulch films is rebalancing the end-use composition of the biodegradable plastics market. NatureWorks LLC leverages its scale in Polylactic Acid (PLA) production to serve high-volume packaging converters. BASF SE competes with a diversified portfolio including both PLA and compostable copolyesters. Meanwhile, Novamont S.p.A. specializes in starch-based bioplastics for applications like carrier bags and food service items.
Biodegradable plastics are polymers designed to break down through the action of living organisms into water, carbon dioxide, and biomass. These materials, such as Polylactic Acid (PLA), derive from renewable feedstocks like corn starch or sugarcane and offer an alternative to fossil-fuel-based plastics. Within product types, PLA and starch blends command the largest market share due to their cost-effectiveness and processability for packaging films. Polyhydroxyalkanoates (PHAs) represent a high-growth segment, valued for their biodegradability in marine and soil environments.
Regulatory mandates are a primary catalyst, with frameworks like the European Union's REACH and single-use plastics directives setting strict material standards. In parallel, policies in the United States under the EPA and China's national 'dual carbon' goals encourage the adoption of bio-based materials to reduce landfill waste. Navigating the fragmented landscape of composting infrastructure and certification standards remains a critical challenge for material suppliers and consumer goods firms.
Market Dynamics
The central tension shaping the biodegradable plastics market is the conflict between strong regulatory tailwinds mandating substitution away from conventional plastics and the persistent, practical deficit in global composting infrastructure required for proper end-of-life management of these materials.
Growth Catalysts
- Regulatory Mandates:Directives from bodies like the European Union targeting single-use plastics are compelling brand owners in food service and consumer goods to adopt compostable alternatives, directly stimulating material demand in packaging applications.
- Food & Beverage Packaging Shift:Demand from food and beverage manufacturers for compostable films and rigid containers is a primary growth engine, driven by consumer preference for sustainable packaging and corporate sustainability goals.
- Material Innovation:The development of polymers like Polyhydroxyalkanoates (PHAs), which offer certified biodegradability in soil and marine environments, opens new applications where industrial composting is not a viable end-of-life option.
Market Restraints
- Cost Disparity:Biodegradable polymers carry a significant price premium over their petroleum-based counterparts, a differential linked to the higher cost and price volatility of agricultural feedstocks like corn and sugarcane.
- Performance Gaps:Certain biodegradable materials exhibit lower thermal stability, moisture barrier properties, or mechanical strength compared to conventional plastics, limiting their use in demanding packaging and durable goods applications.
- Infrastructure Deficit:A widespread lack of industrial composting facilities capable of processing biodegradable plastics at scale remains a critical structural barrier, limiting circularity and creating consumer confusion about proper disposal.
Strategic Opportunities
- High-Value Medical Applications:There is a significant opportunity in developing bioresorbable polymers for medical devices, such as sutures, stents, and drug delivery systems, where biodegradability inside the human body is a key performance requirement.
- Geographic Expansion:Markets in Southeast Asia and Latin America, where governments are beginning to implement stricter plastic waste regulations, present untapped growth potential for suppliers of biodegradable resins and finished products.
- Hybrid Polymer Development:Blending different bioplastics, such as PLA with PHA or starch blends, allows for the creation of customized compounds with tailored performance characteristics, opening new functional application segments.
Industry Challenges
- Certification Fragmentation:Manufacturers face complexity and cost in navigating a fragmented landscape of compostability standards, requiring separate testing and certification for different regional markets, such as BPI in the United States and TÜV AUSTRIA in Europe.
- Consumer Education Gap:A significant challenge lies in educating end-users on the correct disposal pathways for biodegradable products to prevent contamination of conventional plastic recycling streams, which undermines the value proposition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Plastics Market |
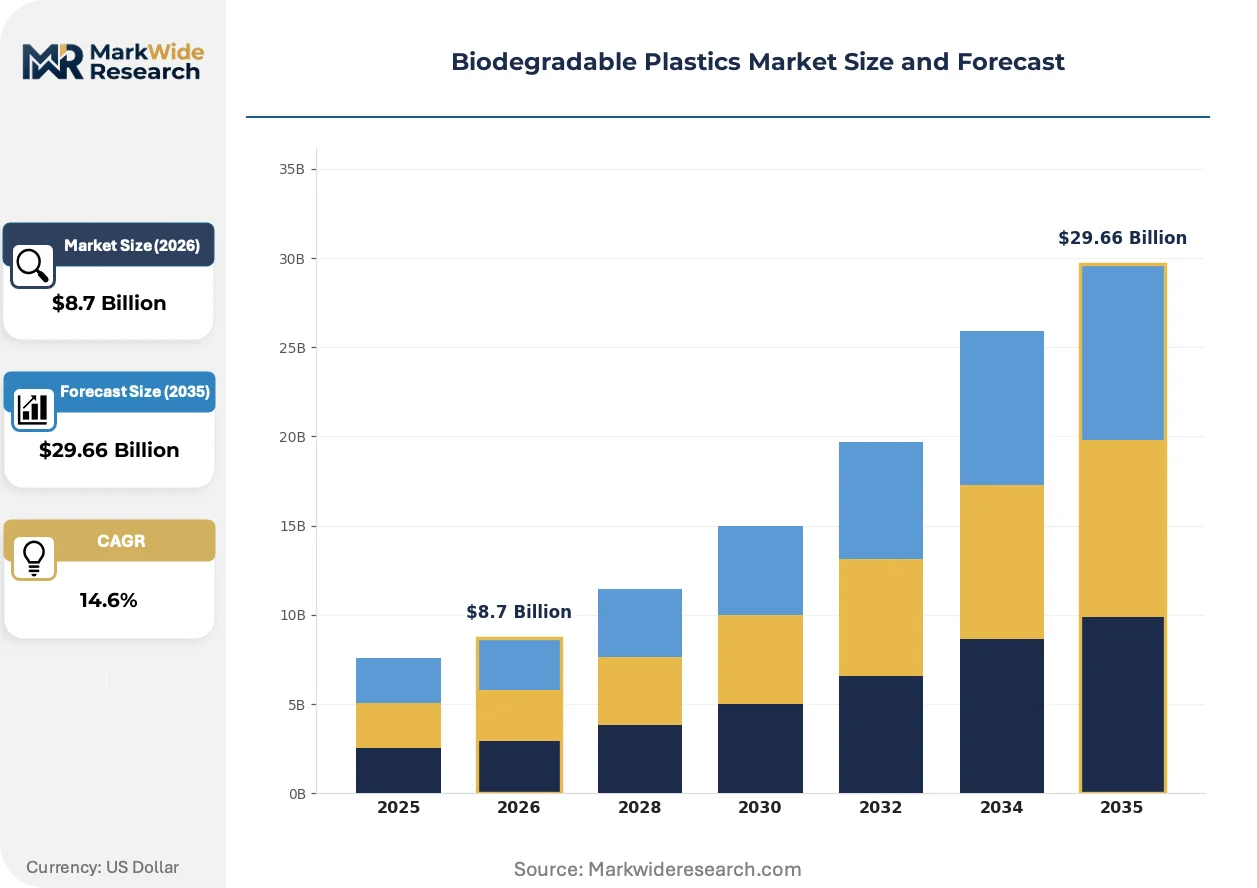
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Polyhydroxyalkanoates, Starch Blends, Cellulose-Based Polymers, Polycaprolactone Application: Packaging Films, Agricultural Mulch, Disposable Tableware, Medical Implants, Textile Fibers End User: Food & Beverage Manufacturers, Agriculture Sector, Medical Device Companies, Textile Producers, Consumer Goods Firms Biodegradability Technology: Composting, Enzymatic Degradation, Hydrolytic Degradation, Photodegradation, Microbial Action |
| Companies Covered | NatureWorks LLC, BASF SE, TotalEnergies Corbion, Cargill Incorporated, Danimer Scientific, Mitsubishi Chemical Group Corporation, Novamont S.p.A., Biome Technologies plc, Plantic Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Plastics Market Strategic Shifts & Innovations
Performance enhancements and specialized material grades are moving biodegradable plastics beyond basic applications. This evolution is enabling penetration into more demanding segments, aligning material capabilities with specific end-of-life environments and regulatory requirements across different geographies.
High-performance Polyhydroxyalkanoates (PHAs) are advanced biopolymers valued for their ability to biodegrade in natural settings like soil and water. CPG firms and food service operators are adopting PHAs for premium single-use items where collection for industrial composting is unlikely. The material’s superior environmental degradation profile is overtaking earlier-generation bioplastics in applications where preventing persistent pollution in open environments is the primary goal.
China's national 'dual carbon' goals are creating powerful domestic incentives to reduce reliance on fossil-fuel-based materials. This policy framework directly stimulates demand for biodegradable alternatives like PLA and PBAT in sectors such as agriculture and e-commerce logistics. Consequently, the country's material producers are rapidly expanding production capacity to meet this state-driven demand for compostable plastics.
Brand owners are increasingly making material choices based on verifiable end-of-life credentials. This shift prioritizes polymers that have achieved third-party compostability certifications, moving selection criteria beyond price to include brand reputation and regulatory compliance. This trend is most visible within the European rigid food packaging and food service sectors, where certification logos are a key consumer-facing signal of sustainability.
Biodegradable Plastics Market Segmentation
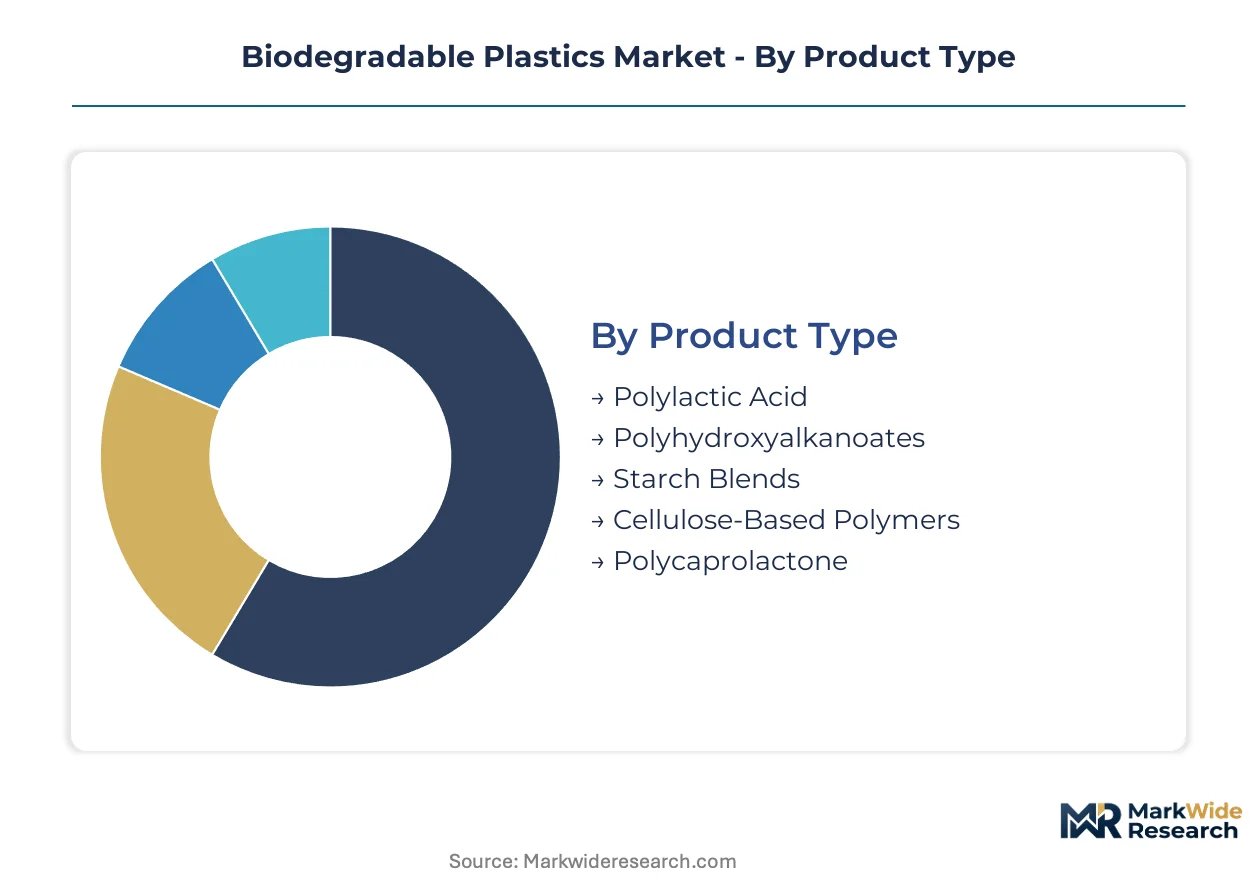
The biodegradable plastics market diversifies across various product types, applications, end-users, and biodegradability technologies. Understanding these distinct segments is essential for identifying specific growth pockets and material substitution opportunities. This analysis delineates the market's structure, highlighting areas of concentrated demand and emerging innovation.
Product Type:
The product type segmentation reveals a clear distinction between high-volume, cost-effective materials and premium, performance-driven biopolymers.
- Polylactic Acid:Derived from renewable resources like corn starch, PLA is a versatile thermoplastic. Demand concentrates in food and beverage packaging, driven by cost-effectiveness and EU regulatory support.
- Polyhydroxyalkanoates:PHAs are naturally occurring polyesters produced by microorganisms, offering certified biodegradability in diverse environments. Demand accelerates in premium single-use items and medical applications.
- Starch Blends:These combine starch with other biopolymers to improve processability and reduce cost, primarily for compostable packaging.
- Cellulose-Based Polymers:Sourced from wood pulp, these polymers offer good mechanical properties and biodegradability for specialty films.
- Polycaprolactone:PCL is a synthetic biodegradable polyester known for low melting point and compatibility, finding niches in medical and packaging.
Mature deployment sits with Polylactic Acid. Newer deployment is concentrated in Polyhydroxyalkanoates.
Application:
The application segment highlights the diverse utility of biodegradable plastics, ranging from high-volume consumer goods to specialized industrial uses.
- Packaging Films:Flexible bioplastic films for food wraps, pouches, and bags offer compostable alternatives. Demand is robust from F&B manufacturers due to consumer preference and EU directives.
- Agricultural Mulch:Biodegradable films replace polyethylene mulch in farming, reducing plastic waste and labor. European agricultural practices increasingly adopt these films to comply with regulations.
- Disposable Tableware:This includes cups, plates, and cutlery from bioplastics, driven by the need for sustainable single-use items in food service.
- Medical Implants:Bioresorbable polymers are utilized in sutures, stents, and drug delivery systems, where in-body biodegradability is critical.
- Textile Fibers:Biodegradable plastics are processed into fibers for apparel and technical textiles, offering sustainable options.
Packaging Films maintain the largest share, while Medical Implants represent a high-value segment with significant expansion potential.
End User:
The end-user segmentation illustrates how various industries are integrating biodegradable plastics to meet sustainability goals and regulatory mandates.
- Food & Beverage Manufacturers:These firms adopt biodegradable plastics for packaging, containers, and tableware, responding to consumer demand and EU directives. Their procurement drives volume.
- Agriculture Sector:Farmers utilize biodegradable plastics for mulch films and seedling pots, reducing pollution and improving soil health. China's 'dual carbon' goals incentivize adoption.
- Medical Device Companies:Manufacturers employ bioresorbable polymers for implants and surgical devices, valuing biocompatibility and controlled degradation.
- Textile Producers:This industry seeks biodegradable fibers for apparel and technical textiles, addressing environmental concerns.
- Consumer Goods Firms:These companies incorporate biodegradable plastics into various products, enhancing sustainability profiles for household and personal care.
Food & Beverage Manufacturers remain the largest consumer segment, with Medical Device Companies exhibiting rapid growth due to specialized requirements.
Biodegradability Technology:
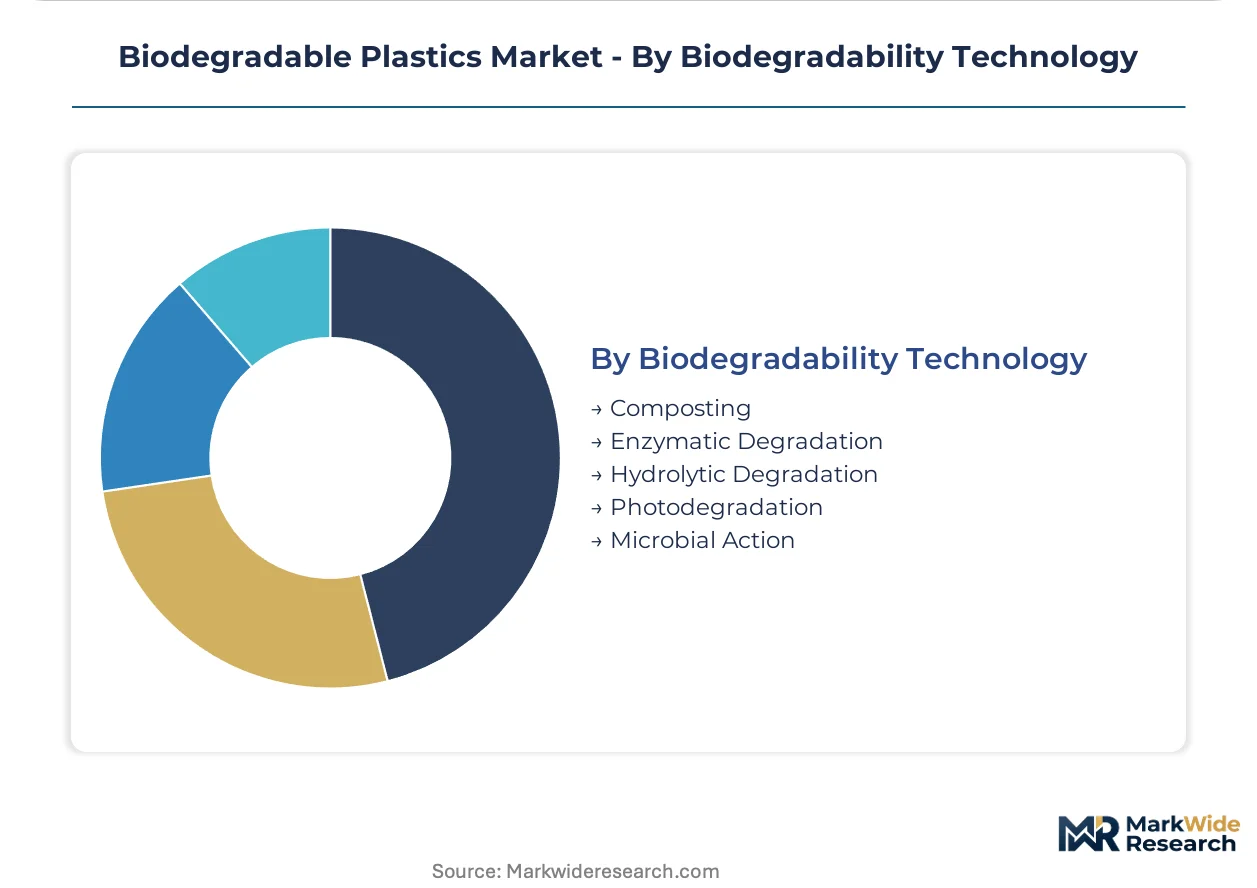
The biodegradability technology segment differentiates materials based on their specific degradation mechanisms and required environmental conditions.
- Composting:This relies on controlled biological decomposition in industrial facilities, breaking down plastics into humus, CO2, and water. EU mandates drive demand for compostable packaging.
- Microbial Action:Plastics designed for microbial action degrade through microorganisms in natural environments. PHAs exemplify this, gaining traction where collection is unlikely.
- Enzymatic Degradation:This process uses specific enzymes to break down polymer chains, often employed in controlled industrial or medical settings.
- Hydrolytic Degradation:Polymers degrade through water action, accelerated by temperature or pH, relevant for medical and packaging materials.
- Photodegradation:This mechanism involves plastic breakdown by UV radiation, though it often leads to fragmentation rather than full biodegradation.
Composting remains the most established technology, while Microbial Action is gaining share due to its suitability for open environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Single-Use Plastics Directive, acting as a powerful regulatory zone, drives significant market concentration for biodegradable plastics across member states. This framework compels brand owners to adopt compostable alternatives, directly stimulating material demand in packaging applications. European economies like Germany lead this transition.
Germany
Demand for compostable packaging films from food and beverage manufacturers is particularly strong in Germany. The EU directive on single-use plastics directly compels brand owners to adopt compostable alternatives. North Rhine-Westphalia, a prominent chemical industry hub, advances bioplastics formulation and production technologies.
United States
Consumer preference for sustainable packaging drives substantial demand for biodegradable materials in the United States. The Environmental Protection Agency (EPA) encourages bio-based material adoption through various federal and state-level programs. The Midwest region, with its vast corn-producing states, supports bioplastics feedstock and processing innovation.
China
National 'dual carbon' goals strongly stimulate demand for biodegradable plastics in China's rapidly expanding economy. Government policies mandate plastic reduction across agriculture and e-commerce logistics sectors. The Yangtze River Delta region rapidly expands production capacity for compostable polymers, becoming a global manufacturing center.
Brazil
Latin America's largest economy, Brazil, shows increasing demand for sustainable packaging and agricultural films derived from renewable resources. The National Solid Waste Policy (PNRS) promotes material substitution away from conventional plastics. São Paulo state, rich in sugarcane production, supports bio-based chemical manufacturing and research.
India
Developing economies like India are seeing growing demand for biodegradable disposable tableware and food packaging solutions. State-level plastic bans and the Swachh Bharat Abhiyan initiative encourage eco-friendly alternatives. Gujarat's industrial corridors are emerging as hubs for bioplastics conversion and processing, attracting new investments.
Biodegradable Plastics Market Key Industry Players
Top-tier vendors anchor the global biodegradable plastics market, while specialized material producers and regional converters form the mid-tier. The market exhibits consolidation among primary resin manufacturers, with fragmentation characterizing downstream processing and application development. Integrated chemical giants, dedicated bioplastics specialists, and innovative compounders represent key strategic archetypes. Capacity expansion, portfolio diversification, and strategic partnerships are dominant competitive moves among these players.
Specialists in biopolymer production include NatureWorks LLC, known for its scale in Polylactic Acid (PLA) manufacturing. This US-based company represents a pure-play bioplastics producer focusing on high-volume applications. BASF SE, a German-based chemical conglomerate, occupies a position with a diversified portfolio encompassing both PLA and compostable copolyesters, exemplifying an integrated chemical giant's approach. Novamont S.p.A., an Italian company, exemplifies expertise in starch-based bioplastics for various applications like carrier bags and food service items, anchoring the segment for sustainable specialty materials. These entities collectively drive material innovation and market development across different product types.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| TotalEnergies Corbion |
| Cargill Incorporated |
| Danimer Scientific |
| Mitsubishi Chemical Group Corporation |
| Novamont S.p.A. |
| Biome Technologies plc |
| Plantic Technologies Limited |
Cost & Logistics Intelligence
The development of high-performance Polyhydroxyalkanoates (PHAs) simultaneously reshapes cost economics and supply concentration within the biodegradable plastics market. This material innovation drives premium pricing in specialized applications while influencing feedstock sourcing.
Pricing Analysis
Premium pricing for short lead times characterizes the biodegradable plastics market, with discounts offered for longer-term, contract-based orders. The dominant pricing model is contract-based long-term offtake for high-volume materials like PLA, complemented by commodity spot pricing for specialized biopolymers. Price differentiation stems from certification level, such as TÜV AUSTRIA or BPI standards, and the volume scale of procurement. Pricing softness runs through starch blend materials due to their cost-effectiveness, while medical device companies prioritize performance and certification over cost for bioresorbable polymers.
Supply Chain Analysis
Single-source vulnerability sits with agricultural feedstocks like corn starch from the United States and sugarcane from Brazil, which are primary inputs for PLA production. China and Germany also demonstrate significant supply concentration for finished biopolymer resins. The supply chain draws from these regions, creating exposure to commodity price volatility for key raw materials. Distribution runs through a network of specialized compounders and packaging converters, directly serving brand owners in food service and consumer goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodegradable plastics market is evolving into a vertical-integration race, as players pursue upstream control over feedstock supply to mitigate cost volatility and ensure material availability. This strategic move aims to secure competitive advantage and stabilize production economics.
For Market Incumbents: Extend production capacity for high-volume biopolymers like PLA in key regions such as China and the United States to counter emerging regional competitors. Invest in advanced R&D for next-generation PHAs to address performance gaps against conventional plastics, a critical threat to broader adoption. Secure long-term supply agreements for agricultural feedstocks to stabilize input costs. Pursue strategic partnerships with industrial composting facilities to streamline end-of-life management and enhance circularity claims.
For New Entrants and Emerging Players: Capture niche medical applications requiring bioresorbable polymers, where performance and certification command premium pricing. Target underpenetrated geographic markets in Southeast Asia and Latin America, focusing on disposable tableware and agricultural mulch films. Develop specialized compounding solutions for hybrid bioplastics, leveraging material innovation as a go-to-market angle. Focus on transparent end-of-life credentials and certifications to build brand trust in consumer-facing segments.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated biopolymer producers given increasing regulatory mandates for plastic substitution and growing consumer demand for sustainable materials. Long-term viability hinges on companies with diversified feedstock sources and robust intellectual property in advanced materials like PHAs. Acquisition targets should include specialized compounders with unique blending capabilities or regional converters. The signal to watch is the expansion of industrial composting infrastructure, which will unlock significant market volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for PLA | This initiative addresses the growing demand from food and beverage manufacturers for cost-effective compostable packaging. |
| R&D in Marine Biodegradable PHAs | Developing PHAs suitable for marine environments enables penetration into new applications where plastic pollution is a critical concern. |
| Partnerships with Composting Operators | Collaborating with industrial composting facilities improves end-of-life solutions for compostable packaging, enhancing circularity. |
| Geographic Expansion into Southeast Asia | Entering Southeast Asian markets leverages nascent regulatory support and rising consumer awareness for sustainable alternatives. |
| Customized Hybrid Polymer Development | Creating tailored bioplastic blends allows brand owners to meet specific performance requirements for diverse packaging applications. |
Research Approach
Document review covered regulatory filings, academic literature, and trade association reports, complemented by interviews with industry stakeholders. Primary research included discussions with biopolymer production managers, packaging engineers, and sustainability leads at consumer goods firms. Secondary data sources comprised customs and trade databases, corporate sustainability reports, and environmental agency publications. This approach enabled bottom-up market sizing and top-down validation.
Volume and value forecasts were generated across the analysis window by segmenting the market by product type, application, end-user, and biodegradability technology. Compound Annual Growth Rates were derived from historical growth trends and projected material substitution rates. Key forecast inputs included feedstock price volatility and new regulatory mandates from the European Union and China. This framework provides a robust outlook on market progression.
The model holds under current regulatory trajectories and feedstock availability; deviation in global economic conditions or unforeseen technological breakthroughs would shift these projections. Forecasts reflect assumptions regarding industrial composting infrastructure development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Biopolymer Films Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Global Bioplastic Market
Bioplastics
Bio-PET Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Cellulose Plastics Market
Bioplastics
North America Bioplastics Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Asia-Pacific Bio Plasticizers Market