
 Biodegradable Insulated Panel Market | 2026-2036
Biodegradable Insulated Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Insulated Panel Market Outlook
Multi-source procurement of bio-based feedstocks is consolidating around certified cellulose and mycelium suppliers as lead times for conventional petrochemical cores lengthen. Kingspan Group leverages its European manufacturing footprint to secure rapeseed oil supply contracts for polyurethane alternatives. Ecovative Design anchors mycelium-composite production in upstate New York facilities with direct agricultural waste sourcing. Steico SE dominates Central European distribution of wood-fiber boards through builder-merchant channel control.
Biodegradable insulated panels are structural envelope components engineered from renewable or compostable matrices such as mycelium-bound agricultural residue, cellulose fiber, or plant-oil-derived foam, delivering thermal resistance values comparable to synthetic equivalents while enabling end-of-life decomposition or industrial composting. Bio-composite formulations achieve lambda values near 0.038 W/mK through high-density compression of hemp or flax shiv bound with lime or bio-resin. Among product type categories, bio-composite panels capture the steepest growth trajectory as architects specify visible-grade natural finishes, while mineral wool retains margin density in fire-rated industrial applications where regulatory thresholds remain stringent.
The EU Green Deal and F-Gas Regulation are tightening embodied-carbon thresholds for building materials across member states, directly shaping product certification requirements under CE marking and redirecting public procurement toward bio-based alternatives. EPA guidelines on construction and demolition waste diversion in the United States are creating parallel compliance obligations for commercial developers seeking LEED v4.1 credits. Stakeholders must track evolving biodegradability certification protocols from ISO and national standards bodies to avoid stranded inventory as verification rules tighten.
Market Dynamics
The EU F-Gas Regulation is compressing synthetic foam core availability across member states, forcing cold chain operators and building envelope specifiers toward bio-based thermal barriers with certified end-of-life pathways.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Public procurement rules in Germany and France now require bio-based content thresholds for thermal envelope materials, redirecting warehouse and district heating retrofit specifications.
- Cold chain logistics expansion:Refrigerated warehouse operators in Bavaria and the Paris metropolitan corridor are specifying mycelium and cellulose-core panels to meet operational carbon targets.
- F-Gas synthetic foam substitution:The phasedown of hydrofluorocarbon blowing agents under EU regulation is eliminating conventional polyurethane core supply for sub-zero applications.
Market Restraints
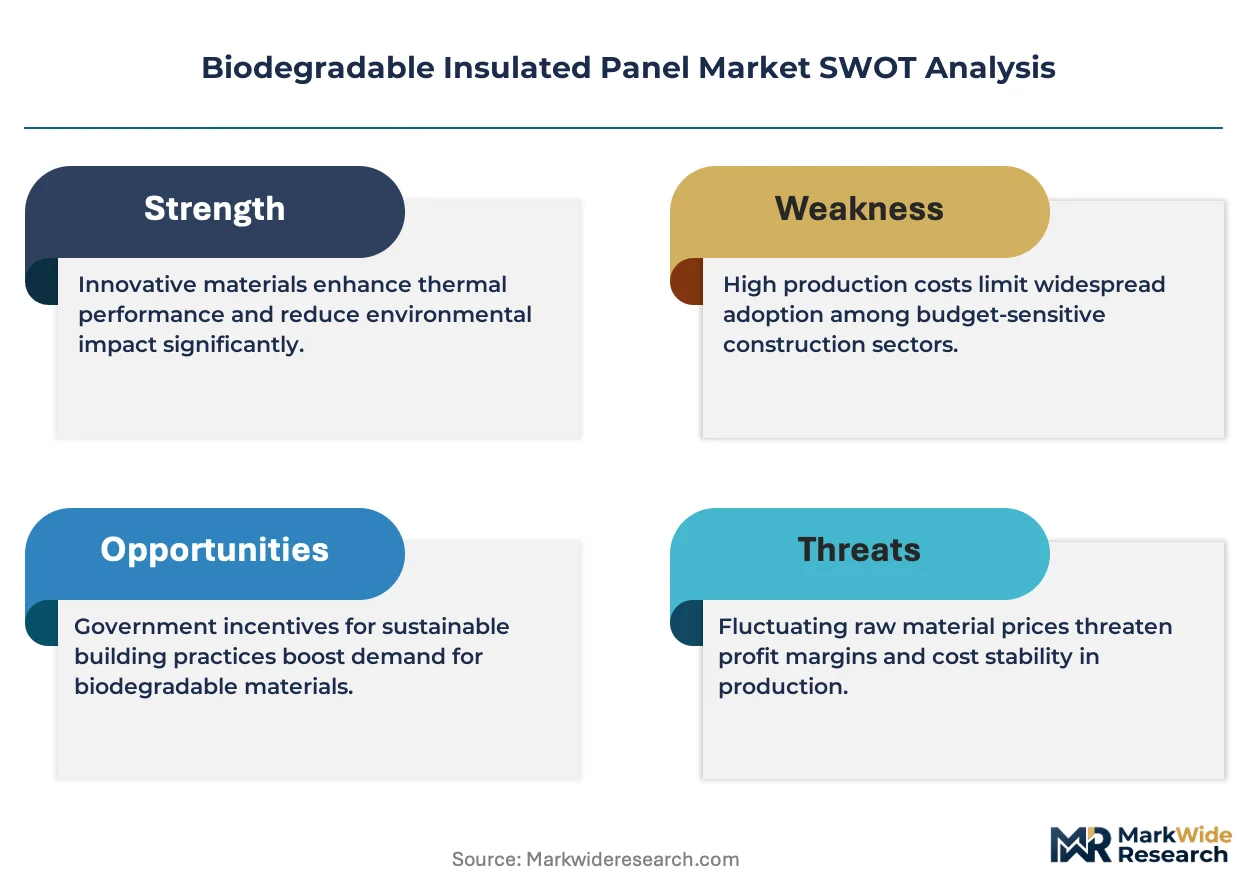
- Agricultural residue input volatility:Hemp shiv and flax fiber prices fluctuate with crop yields in Poland and Romania, compressing bio-composite panel margins during poor harvest seasons.
- Mycelium spawn supply concentration:Certified fungal inoculum production clusters in the Netherlands and upstate New York, creating bottleneck risk for panel manufacturers scaling output.
- Fire performance certification gaps:Bio-based cores struggle to achieve Euroclass A2 ratings required for high-rise facades under EN 13501-1, limiting addressable building height segments.
Strategic Opportunities
- Industrial composting infrastructure integration:Panel manufacturers partnering with German and Austrian composting facility networks can offer closed-loop take-back programs that differentiate bids for public tenders.
- Visible-grade architectural finishes:Architects in Copenhagen and Stockholm are specifying exposed bio-composite surfaces for interior atrium walls, opening premium pricing tiers beyond concealed insulation.
- CSRD scope 3 reporting alignment:Corporate sustainability disclosure requirements are pushing real estate developers toward materials with verified cradle-to-grave carbon data, favoring certified bio-based suppliers.
Industry Challenges
- Biodegradability certification timeline compression:ISO and national standards bodies are tightening compostability test protocols, risking stranded inventory for panels certified under older EN 13432 versions.
- Cross-trade installation skill gaps:Conventional insulation contractors lack training in handling moisture-sensitive bio-fiber boards, requiring manufacturer-led field education programs that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Insulated Panel Market |
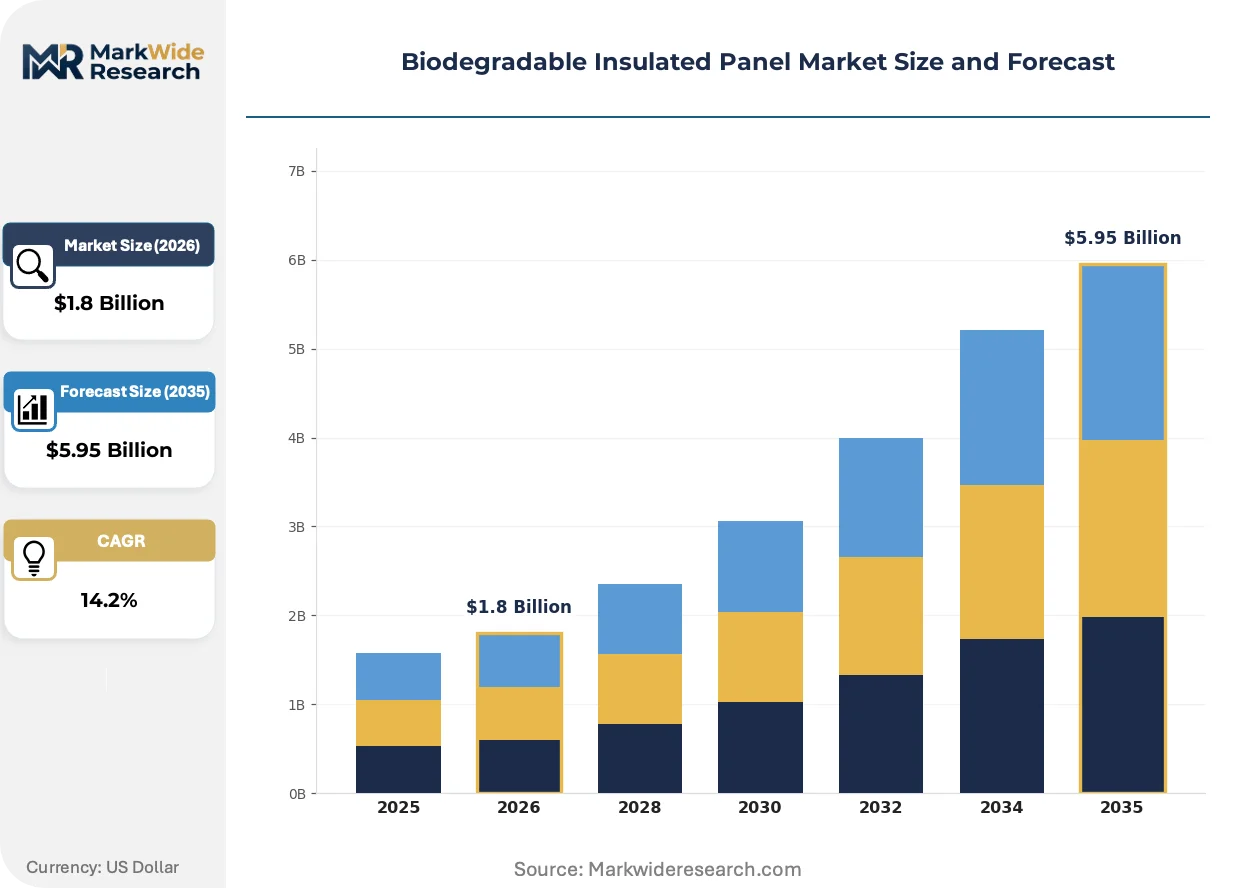
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Bio-composite, Mineral Wool Application: Residential, Commercial, Industrial, Agricultural End User: Builders, Architects, Contractors, Manufacturers Installation Type: New Construction, Renovation, Retrofitting, Modular |
| Companies Covered | Kingspan Group, Saint-Gobain, BASF SE, Owens Corning, Steico SE, Ecovative Design, Rockwool International, Pavatex SA, Knauf Insulation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Insulated Panel Market Strategic Shifts
Mycelium-bound agricultural waste formulations are displacing petroleum-derived foam cores in visible-grade applications, while regulatory pressure on embodied carbon accelerates certification-driven procurement behavior across European construction markets.
Mycelium-composite core technology is rewriting competitive positioning in cold chain envelope specifications. This bio-fabricated material delivers lambda values approaching synthetic polyurethane while enabling industrial composting at end-of-life. Cold storage developers in Germany and the Netherlands are specifying mycelium panels for new warehouse builds at accelerating pace. The technology is compressing the addressable market for conventional expanded polystyrene in sub-zero applications where regulatory pressure on synthetic foam intensifies.
The EU F-Gas Regulation is tightening hydrofluorocarbon blowing agent quotas through 2030, eliminating supply security for conventional foam core manufacturers. This policy is redirecting R&D expenditure toward plant-oil-derived polyurethane alternatives and compressed cellulose formulations. Cold chain equipment OEMs are most affected, with several German and French operators now mandating bio-based core options in supplier qualification questionnaires.
Certification-driven procurement is displacing price-first sourcing in commercial envelope specifications. Real estate developers pursuing LEED v4.1 or BREEAM Outstanding ratings are requiring Environmental Product Declarations and biodegradability certificates as gate criteria for thermal material bids. This behavior is most visible in Scandinavian markets and the Paris metropolitan corridor, where municipal planning permissions increasingly tie material specifications to circular economy criteria.
Biodegradable Insulated Panel Market Segmentation
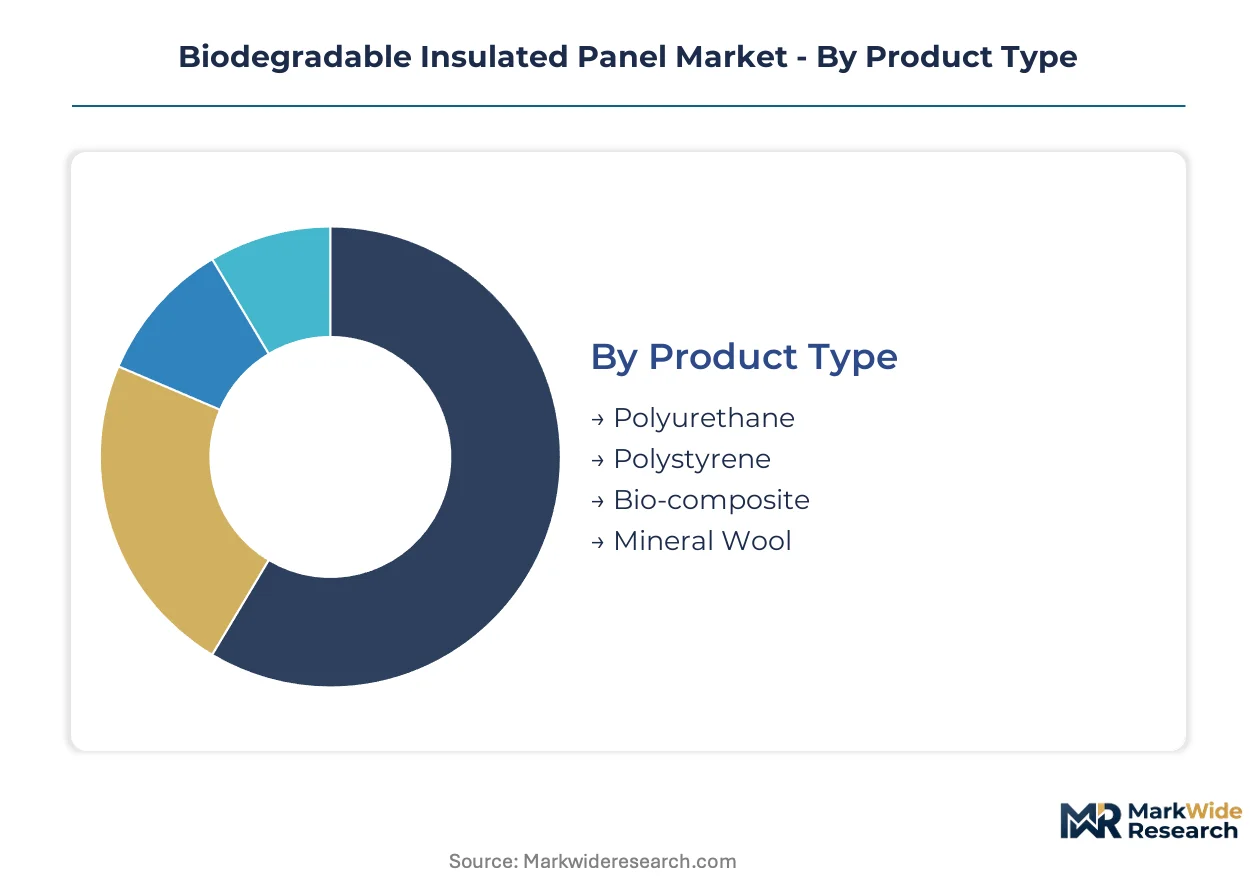
Segmentation in the biodegradable insulated panel market reveals how bio-based feedstock availability and end-of-life certification requirements reshape procurement patterns across construction value chains. Understanding these divides exposes where margin concentrates and which specifications drive substitution of synthetic foam cores.
Product Type:
Supply concentration for bio-based cores clusters around certified cellulose and mycelium producers, compressing availability for conventional petrochemical alternatives under tightening F-Gas quotas.
- Bio-composite:High-density compression of hemp or flax shiv bound with lime or bio-resin achieves lambda values near 0.038 W/mK. Demand concentrates in Copenhagen and Stockholm where architects specify exposed natural finishes for interior atrium walls, with district energy retrofits in Bavaria accelerating volume uptake.
- Mineral Wool:Fire-rated industrial applications retain this segment where Euroclass A2 ratings remain mandatory under EN 13501-1. Cold chain warehouses in the Paris metropolitan corridor specify mineral wool for high-bay freezer envelopes where regulatory thresholds for bio-based alternatives have not yet cleared.
- Polyurethane:Plant-oil-derived formulations from rapeseed supply contracts are displacing petroleum-based cores as blowing agent quotas tighten.
- Polystyrene:Expanded polystyrene faces compressed addressability as mycelium alternatives capture sub-zero cold chain specifications.
Today's leader: Mineral Wool. Tomorrow's challenger: Bio-composite.
Application:
Cost tier stratification separates premium architectural specifications from commodity thermal envelope retrofits, with visible-grade finishes commanding pricing multiples over concealed insulation.
- Industrial:Refrigerated warehouse operators in Germany and France mandate bio-based core options in supplier qualification questionnaires. Cold chain logistics expansion across Bavaria and the Paris corridor drives specification of mycelium and cellulose-core panels to meet operational carbon targets under EU Green Deal procurement rules.
- Commercial:Real estate developers pursuing BREEAM Outstanding ratings require Environmental Product Declarations as gate criteria. Scandinavian municipal planning permissions increasingly tie material specifications to circular economy criteria, favoring certified bio-based suppliers with cradle-to-grave carbon data.
- Residential:Builder-merchant channel control in Central Europe distributes wood-fiber boards for single-family envelope upgrades.
- Agricultural:Controlled-environment food production facilities specify bio-composite panels for humidity-stable growing chambers.
Industrial applications expand most quickly; commercial specifications gain share fastest where CSRD scope 3 reporting alignment pressures material selection.
End User:
Customer type fragmentation splits between specification authority and procurement execution, with architects wielding design-phase influence that contractors convert to purchase orders.
- Architects:Copenhagen and Stockholm practices specify visible-grade bio-composite surfaces for premium interior atrium walls, opening pricing tiers beyond concealed insulation. Certification-driven procurement behavior displaces price-first sourcing as LEED v4.1 and BREEAM gate criteria harden.
- Builders:Cold chain logistics operators in Germany expanding warehouse builds with bio-based thermal barriers consolidate procurement around certified cellulose and mycelium suppliers.
- Contractors:Installation skill gaps in handling moisture-sensitive bio-fiber boards require manufacturer-led field education programs that extend project timelines.
- Manufacturers:Panel producers partnering with German and Austrian composting facility networks offer closed-loop take-back programs that differentiate bids for public tenders.
Architects set specifications; builders control volume commitment.
Installation Type:
Maturity divides separate established new construction workflows from emerging retrofit methodologies that demand specialized labor and disassembly logistics.
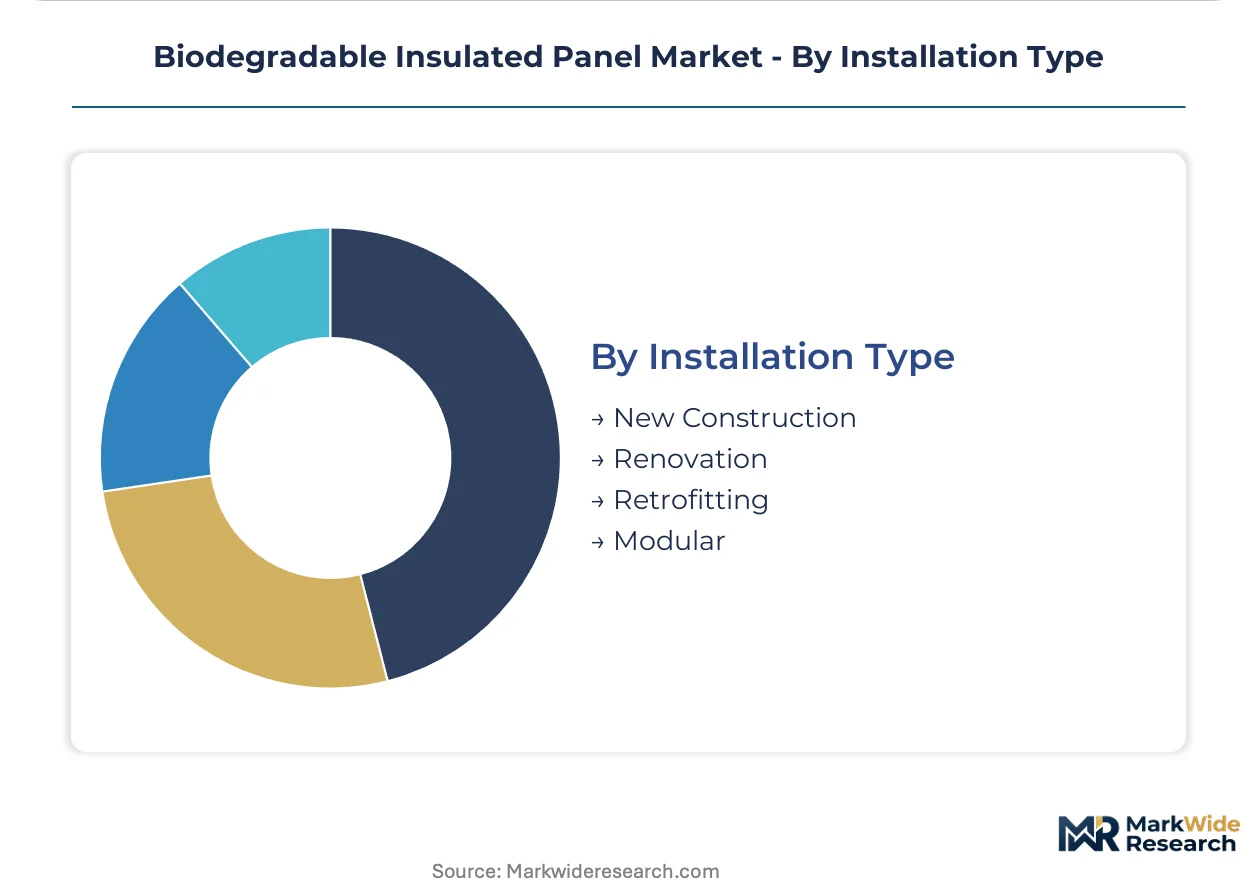
- Renovation:District energy retrofits scaling in Bavaria and the Paris metropolitan corridor drive demand for bio-composite panels compatible with existing masonry envelopes. Public procurement rules in Germany and France now require bio-based content thresholds for thermal envelope materials in retrofit specifications.
- New Construction:Cold storage developers in Germany and the Netherlands specify mycelium panels for warehouse builds at accelerating pace as synthetic foam core supply security erodes.
- Retrofitting:Existing building stock upgrades face fire performance certification gaps where bio-based cores struggle to achieve Euroclass A2 ratings for high-rise facades.
- Modular:Prefabricated envelope assemblies integrate bio-composite panels for rapid-deployment cold chain infrastructure.
Renovation volumes dominate near-term; new construction specifications climb the fastest as F-Gas regulation eliminates conventional alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paris metropolitan corridor anchors near-term demand expansion as district energy retrofits and cold chain warehouse builds concentrate procurement authority for bio-based thermal envelope materials.
Germany
Bavaria drives specification volume through refrigerated warehouse expansion and public procurement mandates under EU Green Deal thresholds. The F-Gas Regulation eliminates conventional polyurethane core supply security for sub-zero applications. Cold chain operators in Munich and Nuremberg consolidate procurement around certified cellulose and mycelium suppliers.
France
The Île-de-France region accelerates bio-composite panel adoption through municipal planning permissions tied to circular economy criteria. BREEAM Outstanding rating requirements redirect commercial envelope specifications toward suppliers with verified cradle-to-grave carbon data. District heating retrofits across the Paris metropolitan corridor scale demand for compatible thermal barriers.
Netherlands
Industrial composting infrastructure integration creates closed-loop differentiation for panel manufacturers partnering with Dutch facility networks. Mycelium spawn production concentrates in Dutch biotechnology clusters, positioning the country as a critical input supplier for European panel fabricators. Amsterdam and Rotterdam cold storage developers specify bio-based cores at accelerating pace.
Sweden
Architects in Stockholm specify visible-grade bio-composite surfaces for premium interior atrium walls, opening pricing tiers beyond concealed insulation applications. Certification-driven procurement behavior displaces price-first sourcing as LEED v4.1 and BREEAM gate criteria harden in Scandinavian markets. Municipal planning permissions increasingly tie material specifications to circular economy criteria.
United States
EPA guidelines on construction and demolition waste diversion create compliance obligations for commercial developers seeking LEED v4.1 credits. Upstate New York facilities anchor mycelium-composite production with direct agricultural waste sourcing. The Northeast corridor exhibits emerging specification behavior as corporate sustainability disclosure requirements pressure real estate developers toward verified bio-based materials.
Biodegradable Insulated Panel Market Competitive Environment
Global majors compete with regional champions across feedstock access and certification depth, creating a tiered structure where scale advantages in synthetic foam conversion clash with localized bio-based supply chain control. The market fragments across three strategic archetypes: diversified building materials conglomerates pivoting plant-oil-derived formulations, specialized bio-composite fabricators with captive agricultural residue sourcing, and mycelium biotechnology platforms integrating spawn production with panel manufacturing. Competitive moves concentrate on strategic partnerships with composting facility networks and backward integration into certified cellulose supply.
Among European building materials specialists, Kingspan Group, Saint-Gobain, and Steico SE exemplify contrasting scale and specialization archetypes. Kingspan represents the diversified industrial platform with European manufacturing footprint leverage. Saint-Gobain occupies the position of integrated materials science conglomerate with broad envelope system capabilities. Steico SE anchors the specialized bio-fiber segment through Central European distribution channel control. These three players illustrate how market position depends on feedstock contract security and certification protocol depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Kingspan Group |
| Saint-Gobain |
| BASF SE |
| Owens Corning |
| Steico SE |
| Ecovative Design |
| Rockwool International |
| Pavatex SA |
| Knauf Insulation |
| Others |
Value Chain & Pricing Dynamics
Backward integration into certified cellulose and mycelium spawn production anchors both supply security and pricing power for panel manufacturers navigating EU F-Gas quota compression. Captive agricultural residue sourcing from Polish hemp fields and Dutch fungal biotechnology clusters insulates producers from input-cost volatility while enabling premium positioning against petrochemical-core competitors.
Pricing Analysis
Input-cost pass-through from agricultural residue volatility compresses margins for bio-composite panel producers during poor harvest seasons in Poland and Romania. Three-tier pricing structure across premium, standard, and economy levels separates visible-grade architectural finishes with natural aesthetics from concealed insulation specifications. Certification-driven procurement under CSRD scope 3 reporting requirements intensifies pricing pressure on uncertified suppliers. Cold chain logistics operators in Germany exhibit lowest price sensitivity due to operational carbon targets, while residential builder-merchant channels in Central Europe remain most cost-conscious.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cold chain operator demand in Germany and France, while builder-merchant networks distribute wood-fiber boards across Central European residential markets. Geographic supply concentration clusters in the Netherlands for mycelium spawn production, Poland and Romania for hemp shiv, and upstate New York for Ecovative's agricultural waste sourcing. Raw material dependencies center on certified fungal inoculum, rapeseed oil for polyurethane alternatives, and compressed cellulose feedstocks. Single-source vulnerability in Dutch mycelium biotechnology creates bottleneck risk for European panel fabricants scaling output. Distribution runs through composting facility partnerships in Germany and Austria that enable closed-loop take-back programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications for visible-grade architectural finishes and certified end-of-life pathways now dominate procurement behavior, compressing commodity-grade alternatives as the market matures toward premium differentiation.
For Market Incumbents: Hedge against mycelium-composite substitution by securing long-term rapeseed oil supply contracts for plant-oil-derived polyurethane formulations. Invest in Euroclass A2 fire performance certification for bio-based cores to unlock high-rise facade specifications currently reserved for mineral wool. Channel control through builder-merchant networks in Central Europe defends volume position against specialized bio-composite fabricants. For New Entrants and Emerging Players: Digital specification platforms targeting Copenhagen and Stockholm architectural practices offer route-to-market acceleration for visible-grade bio-composite finishes. White-space concentration exists in industrial composting infrastructure partnerships across German and Austrian facility networks, where closed-loop take-back programs differentiate public tender bids. Agricultural controlled-environment food production facilities represent underpenetrated application segment with humidity-stable panel requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional bio-composite fabricators with captive agricultural residue sourcing because feedstock contract security determines margin sustainability under F-Gas quota compression. Five-to-ten year viability hinges on certification protocol depth rather than manufacturing scale alone. Acquisition targets should demonstrate verified cradle-to-grave carbon data alignment with CSRD disclosure requirements. The signal to watch is tightening ISO compostability test protocols that risk stranding inventory certified under older EN 13432 versions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spawn Production | Captive mycelium inoculum supply insulates Dutch and New York facilities from bottleneck risk. |
| Certification Investment in Euroclass A2 Ratings | Fire performance clearance unlocks high-rise facade specifications under EN 13501-1 thresholds. |
| Composting Facility Partnership Networks | German and Austrian closed-loop take-back programs differentiate bids for EU Green Deal public tenders. |
| Visible-Grade Architectural Finish Development | Natural aesthetic surfaces command premium pricing tiers in Copenhagen and Stockholm atrium specifications. |
| Agricultural Residue Supply Contracts | Direct sourcing from Polish hemp and Romanian flax growers compresses input-cost volatility exposure. |
Study Parameters
Direct dialogue with cold chain logistics procurement directors, architectural specification leads, bio-composite plant managers, composting facility operators, and building envelope contractors grounded qualitative findings in operational reality. Secondary validation drew from EU F-Gas Regulation filings, EPA construction waste diversion reports, EN 13432 compostability certification databases, and trade data on agricultural residue flows. Bottom-up volume builds across product type and application segments triangulated against top-down macroeconomic drivers to ensure internal consistency.
Segment-level projections across bio-composite, mineral wool, polyurethane, and polystyrene categories incorporated installation type splits between renovation and new construction workflows. End-user behavior modeling captured architect specification authority versus builder procurement execution dynamics. CAGRs derived from elasticity-adjusted demand curves that account for regulatory threshold effects under EU Green Deal embodied-carbon mandates. Industry-specific inputs included F-Gas quota phase-down schedules and municipal planning permission criteria in the Paris metropolitan corridor.
The model assumes a particular technology adoption path for mycelium-composite cores; alternative pathways for compressed cellulose or plant-oil-derived polyurethane would alter the competitive intensity outlook. Forecasts reflect assumptions on certification timeline compression and agricultural yield stability that material supply disruptions or protocol revisions could revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Asia-Pacific Polylactic Acid (PLA) Market
Bioplastics
Canada Bioplastics Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Biopolymer Films Market