
 Global Bio-Plasticizers Market | 2026-2036
Global Bio-Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Plasticizers Market Foresight
Phthalate-free specification tiers is bifurcating the competitive landscape into premium bio-based suppliers and conventional converters racing to reformulate. BASF SE leverages its integrated epoxygenation capabilities to secure feedstock access for epoxidized soybean oil output. Cargill, Incorporated anchors North American oleochemical supply through its soybean processing infrastructure. Evonik Industries AG specializes in high-purity sebacate esters for medical-grade applications where migration limits are tightest.
Bio-plasticizers are non-phthalate additives derived from renewable feedstocks such as vegetable oils, citric acid, and castor oil derivatives, designed to impart flexibility and processability to thermoplastic resins without persistent toxicological profiles. Epoxidized soybean oil dominates current volume due to its cost-competitive epoxide functionality and compatibility with PVC stabilization chemistry. Citrate esters command premium positioning in food-contact flexible packaging where FDA and EFSA migration thresholds are most restrictive. Glycerol esters occupy a maturing niche in low-durability consumer goods where performance trade-offs against petrochemical benchmarks are acceptable.
REACH phthalate restrictions, FDA food-contact substance notifications, and the EU Green Deal's sustainable chemistry transition timeline collectively constrain conventional plasticizer availability while creating compliance-driven demand for certified bio-based alternatives. ECHA substance evaluation protocols now require extensive endocrine disruption screening that legacy ortho-phthalates struggle to pass. Stakeholders must monitor evolving migration limit harmonization between EPA and EFSA frameworks, as divergent standards threaten to fragment formulation strategies across Atlantic supply chains.
Market Dynamics
REACH phthalate restrictions and the EU Green Deal's chemical sustainability targets are redirecting formulation decisions across European compounding facilities, forcing automotive wire and cable producers into binding substitution mandates that reshape supplier relationships.
Growth Catalysts
- REACH Annex XVII phthalate bans:ECHA substance evaluation protocols now require extensive endocrine disruption screening that legacy ortho-phthalates struggle to pass, redirecting demand toward certified bio-based alternatives in Germany's industrial Rhine corridor.
- Epoxidized soybean oil compatibility:Cost-competitive epoxide functionality integrates seamlessly with existing PVC stabilization chemistry, accelerating uptake among flexible packaging converters facing FDA and EFSA migration thresholds.
- Automotive wire and cable mandates:Binding substitution requirements in Germany, France, and Italy are concentrating demand for citrate ester formulations among European automotive suppliers.
Market Restraints
- Soybean feedstock volatility:Epoxidized soybean oil output depends on North American oleochemical supply chains vulnerable to weather-driven crop yield fluctuations and commodity price swings.
- High-purity sebacate ester scarcity:Medical-grade applications requiring tightest migration limits face concentrated supply among specialized European producers, creating bottleneck risk.
- Performance trade-off acceptance:Glycerol esters in low-durability consumer goods struggle to match petrochemical benchmark flexibility, limiting addressable market expansion.
Strategic Opportunities
- India's PLI scheme for chemicals:Production-linked incentives for sustainable chemistry create manufacturing cost advantages for bio-plasticizer facilities serving Asian flexible packaging growth.
- FDA-EFSA migration limit harmonization:Divergent trans-Atlantic standards threaten to fragment formulation strategies, creating first-mover advantage for suppliers achieving dual certification.
- Epoxygenation-citrate hybrid formulations:Convergence of BASF's integrated epoxygenation capabilities with citrate ester chemistry opens premium positioning in food-contact applications.
Industry Challenges
- Endocrine disruption screening expertise:ECHA evaluation protocols demand toxicological assessment capabilities scarce among mid-tier compounders, slowing reformulation timelines.
- Multi-jurisdiction certification complexity:Simultaneous EPA and EFSA compliance requirements extend product qualification cycles for suppliers without established regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Plasticizers Market |
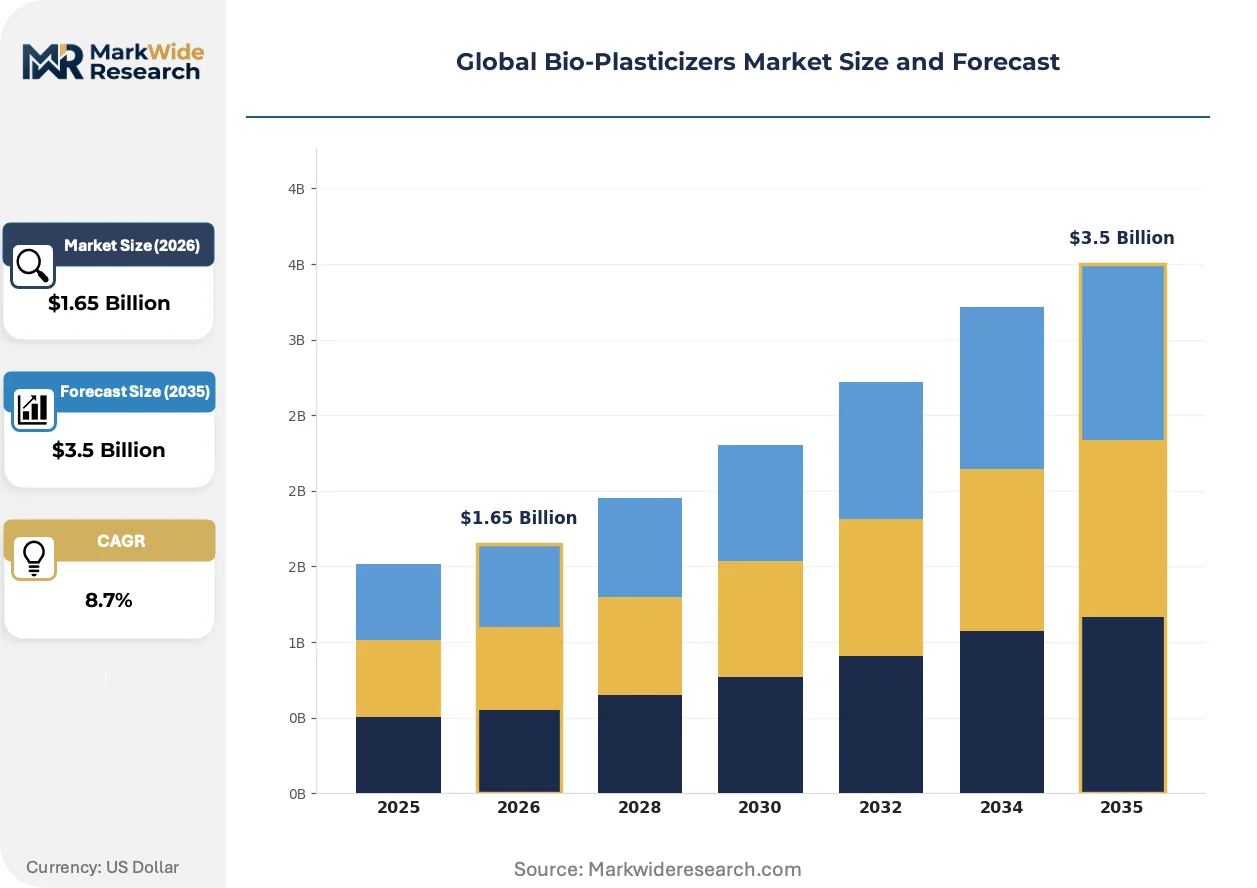
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.5 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxidized Soybean Oil, Citrate Esters, Glycerol Esters, Sebacates, Acetylated Monoglycerides Application: Flexible Packaging, Wire & Cable, Automotive Components, Medical Devices, Consumer Goods End User Industry: Packaging Manufacturers, Electrical & Electronics, Vehicle Assemblers, Medical Equipment Suppliers, Household Products Form: Liquid, Paste, Powder, Pellet, Resin |
| Companies Covered | BASF SE, Cargill, Incorporated, Evonik Industries AG, Avient Corporation, Lanxess AG, Dow, Inc., DIC Corporation, Emery Oleochemicals, Valtris Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Plasticizers Market Shifts & Advancements
Formulation science is advancing through precision epoxidation control, regulatory test method harmonization, and procurement criteria that embed sustainability metrics into supplier selection. These forces compress development cycles while elevating performance thresholds.
Advanced epoxygenation reactor design is miniaturizing. Precision temperature and pressure control systems enable distributed production units co-located with soybean processing facilities. Automotive wire harness manufacturers in Germany's Rhine corridor are adopting these modular systems to secure captive feedstock access. The technology is compressing logistics costs and lead times for epoxidized soybean oil supply.
REACH restriction updates and ECHA substance evaluation protocols are tightening migration limit enforcement across European flexible packaging. Industrial consequence includes mandatory reformulation timelines that invalidate legacy phthalate certificates. Food-contact film producers in Italy and France face the most acute compliance pressure, accelerating citrate ester qualification programs.
Automotive OEMs now embed bio-content percentage requirements into wire and cable procurement specifications. Tier-1 suppliers must document renewable feedstock sourcing through mass-balance certification. This behavioral shift displaces price-only supplier selection with sustainability-scored vendor ranking systems. The transformation is most visible in Germany, where Volkswagen and BMW have published binding plasticizer substitution roadmaps.
Global Bio-Plasticizers Market Segmentation
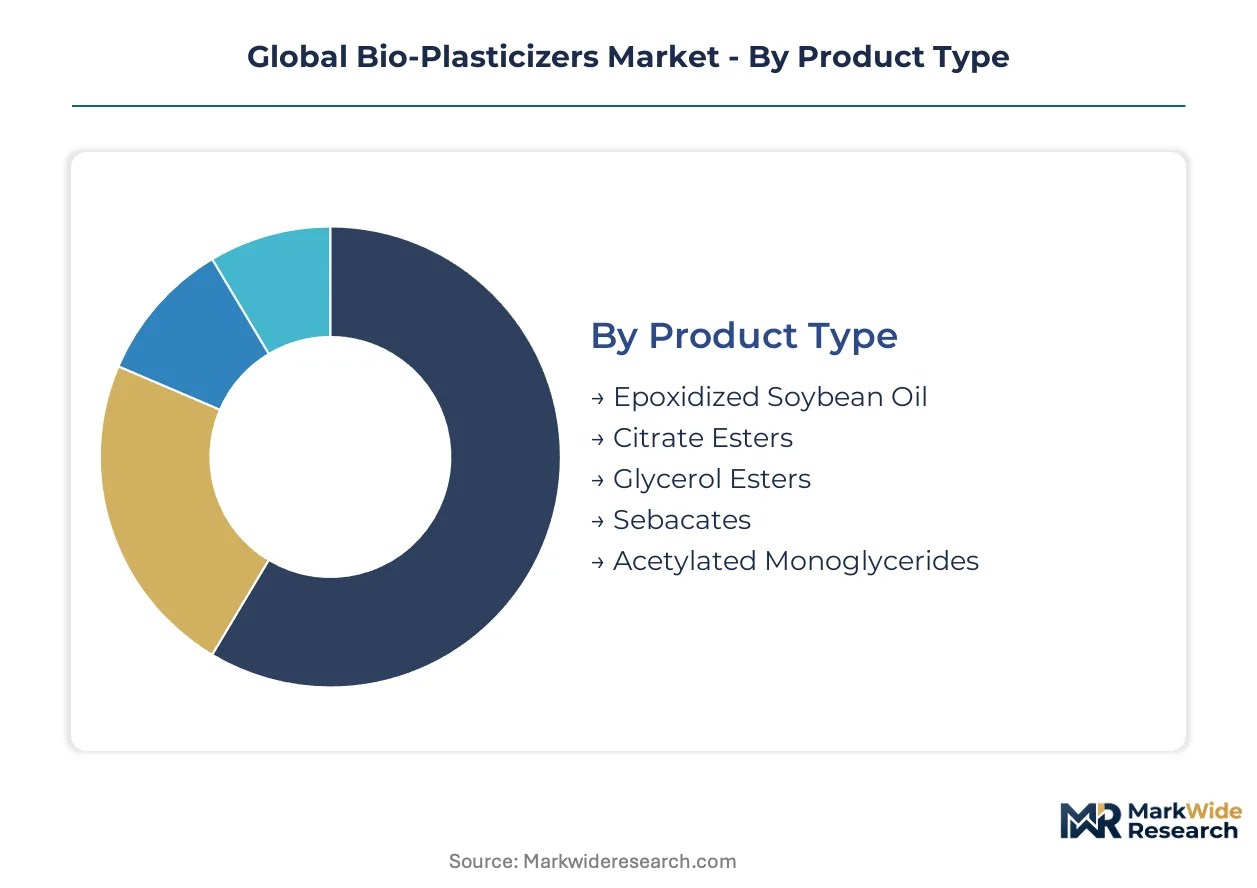
Bio-plasticizer procurement flows through distinct technical and commercial channels. Product chemistry determines compatibility with PVC stabilization systems. Application requirements dictate migration limit thresholds and certification complexity.
Product Type:
Channel mix varies sharply by epoxide content and feedstock origin. Epoxidized soybean oil moves through commodity chemical distributors serving high-volume PVC compounders. Citrate esters and sebacates route through specialty distributors with regulatory documentation capabilities.
- Epoxidized Soybean Oil:Derived from soybean oil through peracetic or performic acid epoxidation, yielding 6.0-7.0% oxirane oxygen content. Demand concentrates in Germany's automotive wire harness sector where REACH substitution mandates eliminate ortho-phthalate alternatives. BASF's integrated epoxygenation capabilities anchor European supply security.
- Citrate Esters:Synthesized from citric acid and C4-C8 alcohols, offering low volatility and excellent food-contact compliance. Italian and French flexible packaging converters accelerate qualification programs to meet EFSA migration thresholds for fatty food contact. Premium positioning reflects dual FDA-EFSA certification requirements.
- Glycerol Esters:Partial esters of glycerol with C12-C18 fatty acids, serving cost-sensitive applications where performance trade-offs are acceptable.
- Sebacates:Diesters of sebacic acid, prized for low-temperature flexibility in medical-grade tubing.
- Acetylated Monoglycerides:Modified glycerol esters with enhanced hydrophobicity for moisture-sensitive film applications.
Epoxidized soybean oil dominates installed base. Citrate esters are where expansion concentrates.
Application:
Cost tier stratification separates premium-certified medical and food-contact segments from standard industrial grades. Wire and cable applications command formulation expertise premiums. Consumer goods absorb lowest-purity grades with minimal regulatory documentation.
- Flexible Packaging:Multilayer film and sheet requiring plasticizers with FDA food-contact substance notifications and EFSA compliance. Migration limits for fatty foods drive citrate ester preference over conventional alternatives. Italian converters face acute reformulation pressure from REACH restriction updates.
- Wire & Cable:PVC insulation and jacketing for automotive harnesses, building wire, and appliance cords. Germany's industrial Rhine corridor concentrates demand as Volkswagen and BMW enforce bio-content percentage requirements in procurement specifications. Epoxidized soybean oil integrates with calcium-zinc stabilization systems.
- Automotive Components:Interior trim, seals, and underhood applications beyond wiring.
- Medical Devices:Tubing, blood bags, and IV sets where USP Class VI and ISO 10993 biocompatibility are mandatory.
- Consumer Goods:Toys, footwear, and sporting goods with minimal performance specifications.
Wire and cable applications anchor volume commitments. Flexible packaging is climbing the fastest on regulatory substitution deadlines.
End User Industry:
Customer type determines contract structure and technical service intensity. Vehicle assemblers impose sustainability-scored vendor rankings. Medical equipment suppliers demand batch-level traceability.
- Packaging Manufacturers:Film extruders and converters in Germany, France, and Italy purchasing citrate esters through distributors with regulatory documentation libraries. ECHA substance evaluation protocols invalidate legacy phthalate certificates, forcing immediate reformulation.
- Electrical & Electronics:Wire and cable producers facing binding substitution mandates. Tier-1 suppliers must document renewable feedstock sourcing through mass-balance certification. Procurement criteria embed bio-content percentages that displace price-only selection.
- Vehicle Assemblers:OEMs publishing plasticizer substitution roadmaps with binding timelines.
- Medical Equipment Suppliers:Manufacturers requiring high-purity sebacates with tightest migration limits.
- Household Products:Producers of low-durability goods accepting glycerol ester performance trade-offs.
Electrical and electronics procurement anchors long-term supply agreements. Packaging manufacturers are gaining share fastest on accelerated reformulation timelines.
Form:
Supply concentration favors liquid forms with established bulk handling infrastructure. Powder and pellet forms serve specialized compounding operations with dust containment requirements.
- Liquid:Dominant form for epoxidized soybean oil and citrate esters, enabling direct pump-fed addition to PVC dry blend systems. Bulk tank installations at German compounding facilities minimize handling costs.
- Paste:Dispersions for plastisol applications requiring controlled rheology.
- Powder:Spray-dried formulations for dust-free handling in medical cleanroom environments.
- Pellet:Masterbatch concentrates for precise dosing in automated compounding lines.
- Resin:Solid grades for specialty adhesive and coating applications.
Liquid forms dominate installed base. Pellet concentrates are expanding most quickly on automation investments in European compounding facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epoxidized soybean oil supply chains concentrate in North American oleochemical processing corridors, while European demand clusters around REACH-mandated substitution zones. Regulatory divergence between FDA and EFSA migration limits fragments formulation strategies across Atlantic markets.
United States
Flexible packaging converters in the Midwest accelerate citrate ester adoption as FDA food-contact substance notifications tighten. The EPA maintains divergent migration thresholds from European counterparts, complicating dual-certification efforts. Chicago-area compounding facilities stockpile epoxidized soybean oil to hedge against soybean crop volatility.
Germany
Volkswagen and BMW enforce bio-content percentage requirements in wire harness procurement specifications. REACH Annex XVII phthalate bans invalidate legacy certificates across the industrial Rhine corridor. BASF's Ludwigshafen complex anchors integrated epoxygenation capacity for captive automotive supply.
China
MIIT dual carbon goals redirect PVC additive demand toward certified bio-based alternatives. Yangtze River Delta flexible packaging producers qualify citrate esters for export-oriented food-contact film. NMPA registration requirements extend product qualification cycles for foreign suppliers.
India
PLI scheme incentives for sustainable chemistry attract bio-plasticizer manufacturing investments serving Asian packaging growth. Maharashtra and Gujarat-based compounders reformulate for domestic food-contact applications. BIS standards harmonization with EFSA frameworks remains incomplete.
Italy
Flexible packaging converters in Emilia-Romagna face acute ECHA substance evaluation pressure on legacy phthalate certificates. Citrate ester qualification programs compress development timelines for fatty food-contact films. Milan-area distributors build regulatory documentation libraries to support converter compliance.
Global Bio-Plasticizers Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling upstream oleochemical feedstock access. The competitive landscape tiers between premium-certified specialists and volume-scale commodity suppliers. Three archetypes dominate: epoxygenation-integrated petrochemical majors, oleochemical processors with captive crop supply, and high-purity ester specialists serving medical-grade niches. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with modular reactor deployment co-located with processing facilities.
Among German-based chemical conglomerates, BASF SE and Evonik Industries AG occupy positions reflecting divergent specialization vectors—integrated epoxygenation capabilities versus high-purity sebacate ester production. Cargill, Incorporated exemplifies the oleochemical processor archetype with North American soybean processing infrastructure anchoring feedstock security. These three entities represent distinct competitive positioning strategies: backward integration into crop processing, premium-tier medical certification, and large-scale commodity epoxygenation output.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| Evonik Industries AG |
| Avient Corporation |
| Lanxess AG |
| Dow, Inc. |
| DIC Corporation |
| Emery Oleochemicals |
| Valtris Specialty Chemicals |
| Others |
Supply & Pricing Matrix
Sixty-day inventory cycles at German compounding facilities signal supply-chain tightness that concentrates pricing power among epoxygenation-integrated suppliers serving REACH-mandated substitution zones. This lead-time compression reflects the structural coupling between North American oleochemical feedstock availability and European regulatory compliance deadlines.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the bio-plasticizer landscape, separating FDA-EFSA dual-certified citrate esters from commodity-grade glycerol esters. Three-tier pricing stratifies across premium medical-grade sebacates, standard automotive epoxidized soybean oil, and economy glycerol formulations. Cost compression in the standard tier intensifies as soybean crop volatility feeds raw material uncertainty. Packaging manufacturers in Italy exhibit highest price sensitivity due to acute reformulation timelines, while medical device suppliers accept premium positioning for migration-limit compliance.
Supply Chain Analysis
Forty-five-day lead times for European citrate ester deliveries expose dependency on specialized esterification capacity concentrated in Germany, Italy, and France. Epoxidized soybean oil output draws from North American soybean crushing infrastructure vulnerable to weather-driven yield fluctuations. Single-source vulnerability sits with high-purity sebacate production among limited European specialists. Distribution runs through commodity chemical distributors for volume grades and specialty distributors with regulatory documentation libraries for certified tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment—REACH substitution mandates and ECHA evaluation protocols create switching costs that lock compounders into qualified supplier relationships.
For Market Incumbents: Shield market position through captive feedstock arrangements with North American soybean processors and accelerated FDA-EFSA dual certification investments. Capacity addition in India's PLI-incentivized zones addresses Asian packaging growth while insulating against European supply disruption. Regulatory documentation libraries at distributor partners constitute critical channel control levers against emerging specialty ester producers.
For New Entrants and Emerging Players: Lead with modular epoxygenation reactor deployment co-located with regional soybean processing to bypass incumbent logistics advantages. India's Maharashtra and Gujarat compounders present the most penetrable entry point for domestic food-contact qualification. A certification-first go-to-market angle—securing EFSA compliance before volume scale—opens converter relationships faster than price competition.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because substitution mandates compound annually with REACH restriction updates. Acquisition target archetype: mid-tier European ester specialists with existing ECHA substance evaluation dossiers and underutilized medical-grade cleanroom capacity. Watch for FDA-EFSA migration limit harmonization announcements as the signal for trans-Atlantic formulation consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Processing | Cargill's North American crushing infrastructure secures epoxidized soybean oil feedstock cost stability against commodity volatility. |
| Modular Epoxygenation Deployment | BASF's distributed reactor systems co-located with automotive clusters compress lead times for German wire harness manufacturers. |
| FDA-EFSA Dual Certification Investment | Italian flexible packaging converters prioritize suppliers with harmonized migration limit documentation for fatty food contact. |
| Medical-Grade Cleanroom Capacity Expansion | Evonik's high-purity sebacate production addresses concentrated supply bottleneck for USP Class VI tubing applications. |
| PLI Scheme Manufacturing Localization | India's production-linked incentives attract bio-plasticizer facilities serving Asian packaging growth with cost-advantaged output. |
Research Methodology
A standing panel of PVC compounding plant managers, automotive Tier 1 procurement leads, flexible packaging technical directors, and specialty chemical distribution partners provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA substance evaluation protocols, FDA food-contact substance notifications, EU Green Deal implementation documents, and customs trade flow data. Bottom-up volume builds across product chemistry and application segments triangulated against top-down market sizing from oleochemical processing capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including plasticizer chemistry type, end-use application tier, regulatory certification grade, and regional production hub clustering. CAGRs were derived from demand elasticity modeling against substitution mandate timelines and feedstock cost trajectory assumptions. Industry-specific forecast inputs incorporated REACH restriction update schedules and automotive OEM bio-content procurement roadmaps.
Underlying assumptions cover sustained REACH enforcement stringency and stable North American soybean supply availability, with deviation risk concentrated in ECHA evaluation protocol changes and trans-Atlantic regulatory divergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Global Bioplastic Market
Bioplastics
US Bioplastics Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Biopolymer Films Market
Bioplastics
Bio-PET Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
China Bioplastics Market