
 Biodegradable Disposable Tableware Market | 2026-2036
Biodegradable Disposable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Disposable Tableware Market Analysis
Subscription-based replenishment programs for foodservice operators is hardening into a standard commercial arrangement across the biodegradable tableware sector. Huhtamaki leverages its European manufacturing footprint to anchor large-format catering contracts. World Centric specializes in carbon-neutral distribution models that sustain premium positioning among independent cafes. Eco-Products, Inc. dominates the North American institutional channel through direct relationships with university and corporate dining operators.
Biodegradable disposable tableware comprises single-use serving items engineered from plant-derived polymers, agricultural residues, or rapidly renewable fibers such as bagasse, polylactic acid, bamboo, and palm leaf, typically manufactured through thermoforming, pressing, or injection molding to achieve oil and moisture resistance for food contact applications. PLA formulations currently occupy the highest-margin tier due to crystallization improvements that extend heat tolerance, while bagasse plates and bowls lead volume flows because sugarcane processing waste streams lower feedstock costs. The online retail distribution channel registers the fastest expansion as foodservice procurement managers shift purchasing to digital platforms, though wholesale still controls the bulk of institutional volume.
The EU F-Gas Regulation and REACH chemical frameworks constrain conventional plastic additives, while the US FDA maintains food-contact substance notifications that PLA and bagasse suppliers must satisfy for interstate commerce. India's BIS certification requirements for compostable plastics create additional compliance thresholds for exporters targeting institutional buyers. Stakeholders must monitor evolving compostability standards across municipal waste systems, as facility acceptance criteria increasingly determine which material formats achieve circular end-of-life performance.
Market Dynamics
Municipal composting infrastructure gaps are fragmenting end-of-life value capture across the biodegradable tableware sector, forcing manufacturers to optimize material formulations for regional facility capabilities rather than universal compostability standards.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for conventional plastic serviceware are accelerating material substitution across foodservice channels in Germany, France, and Italy.
- Bagasse fiber processing:Sugarcane waste stream utilization is lowering feedstock costs for molded pulp manufacturers serving institutional catering contracts.
- Quick-service restaurant chains:North American and European QSR operators are standardizing compostable packaging specifications across franchise networks.
Market Restraints
- PLA resin price volatility:Corn starch feedstock costs fluctuate with agricultural commodity markets, squeezing margin stability for heat-tolerant formulations.
- Composting facility concentration:Industrial composting infrastructure clusters in Germany, the Netherlands, and select US West Coast metros, leaving Atlantic and Central European markets with landfill-dominant end-of-life pathways.
- Heat tolerance ceiling:Polylactic acid crystallization limits prevent sustained contact with foods above 110°C, restricting applications in hot-oil service contexts.
Strategic Opportunities
- Indian institutional procurement:BIS certification requirements for compostable plastics are creating compliant-supplier scarcity that early entrants can exploit in university and hospital channels.
- Palm leaf segment expansion:Areca nut plantation waste valorization offers premium positioning for artisanal dining formats seeking rustic aesthetic differentiation.
- California and New York state mandates:Subnational regulatory acceleration ahead of federal standards is concentrating demand pull for fiber-based alternatives in coastal urban corridors.
Industry Challenges
- Compostability certification timelines:ASTM D6400 and EN 13432 testing protocols require 6-18 month validation cycles that delay product launches and tie up R&D capital.
- Material science talent scarcity:Formulation chemists with expertise in bio-based polymer barrier coatings command premium compensation, constraining mid-scale manufacturer technical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Disposable Tableware Market |
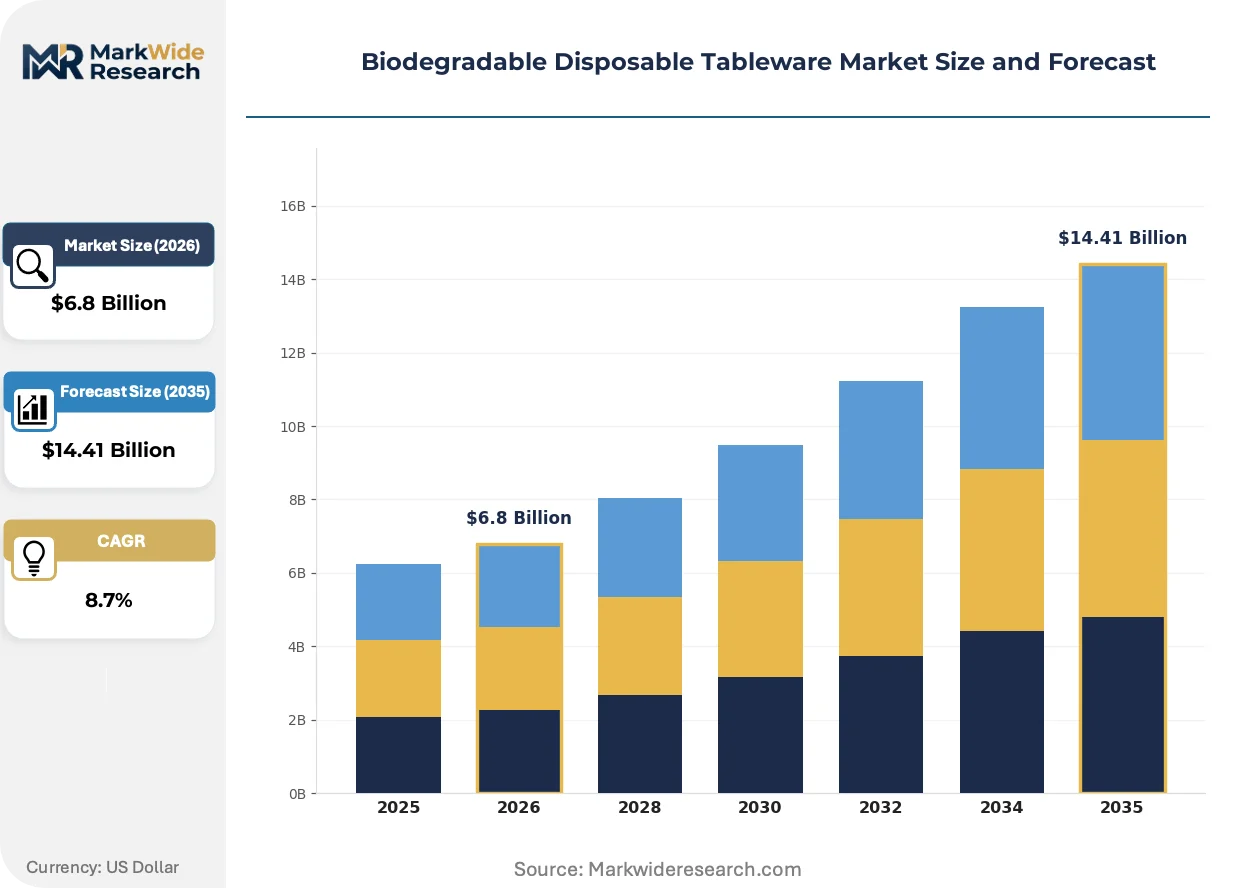
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, Bagasse, Bamboo, Palm Leaf Product Form: Plates, Bowls, Cutlery, Cups End User: Restaurants, Cafes, Catering Services, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Eco-Products, Inc., World Centric, BioPak, Green Paper Products LLC, Sabert Corporation, Huhtamaki, Genpak LLC, Novolex, Pactiv Evergreen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Disposable Tableware Market Emerging Trajectories
Digital procurement platforms are compressing buyer-supplier matching cycles while material scientists engineer multi-layer bio-barrier films that replicate petroleum-based performance at commercial scale.
Barrier-coated bagasse is converging with high-speed thermoforming lines to produce grease-resistant clamshells that withstand 48-hour hold times in food delivery logistics. National pizza chains and ghost kitchen operators in the United Kingdom and Australia are piloting these formulations for hot-oil applications previously reserved for polypropylene. The convergence is compressing price premiums between fiber-based and conventional plastic serviceware in contracted foodservice procurement.
The EU F-Gas Regulation and REACH chemical frameworks are constraining conventional plastic additives used in food-contact applications, redirecting formulation R&D budgets toward bio-based alternatives. Industrial consequences include accelerated phase-out of per- and polyfluoroalkyl substances in grease-resistant coatings. Quick-service restaurant supply chains across Northern Europe are responding by qualifying PLA and molded fiber alternatives ahead of 2025 enforcement milestones.
Subscription-based replenishment programs are displacing spot purchasing for foodservice operators managing multi-location inventory. Digital platforms connecting manufacturers directly with procurement managers are consolidating order aggregation for independent cafes and regional catering groups. This behavioral shift is most visible in Germany, where municipal composting infrastructure supports predictable volume commitments that justify automated reorder algorithms.
Biodegradable Disposable Tableware Market Segmentation
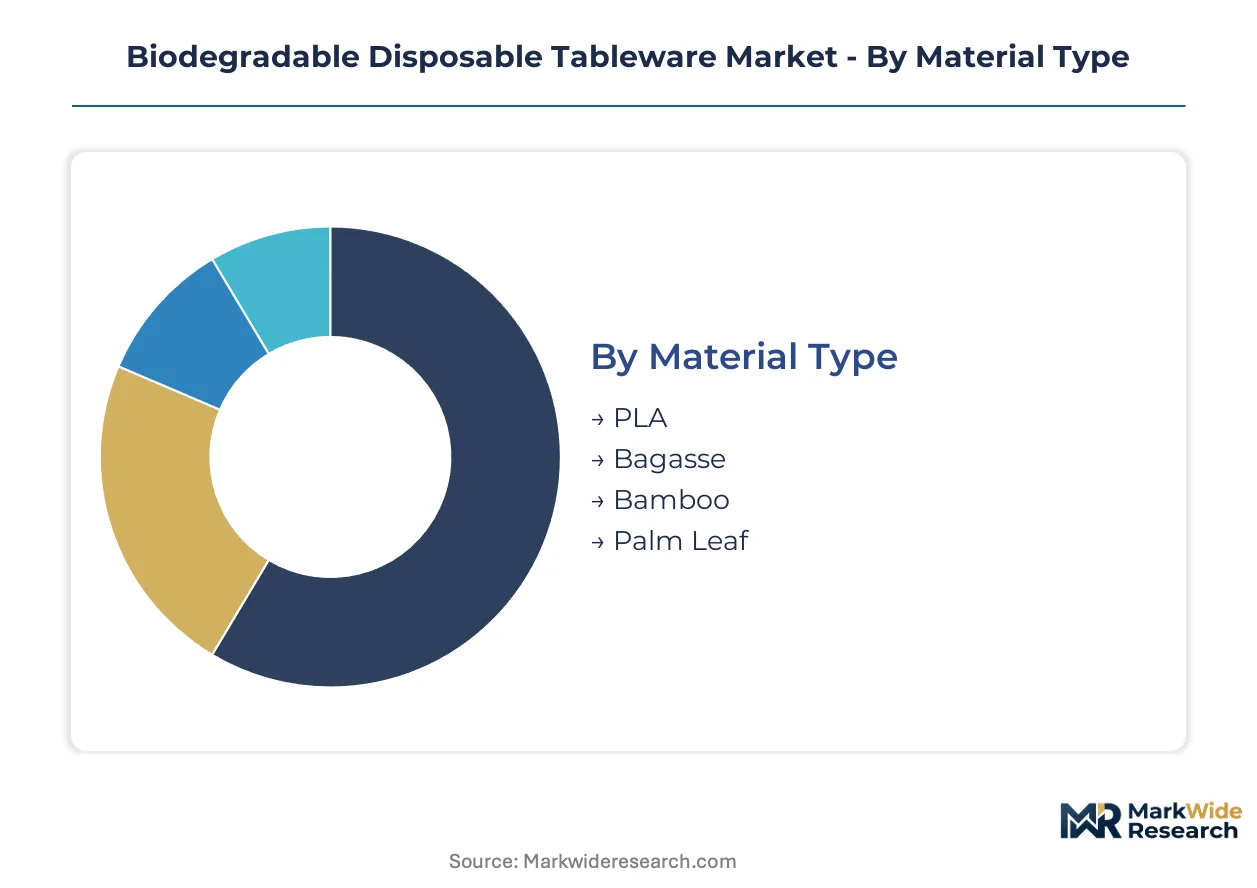
Material chemistry and thermal performance specifications determine procurement decisions across foodservice channels. Manufacturers optimize formulations for regional composting infrastructure while balancing oil resistance against crystallization costs.
Material Type:
Capital intensity escalates sharply with polymer processing sophistication and barrier coating requirements.
- PLA:Corn starch-derived polylactic acid requires crystallization ovens and nucleating agent integration to achieve heat tolerance above 100°C. German quick-service chains specify PLA for hot beverage lids where municipal composting infrastructure supports industrial facility acceptance.
- Bagasse:Sugarcane fiber pulp demands lower upfront thermoforming investment than synthetic polymers. Indian institutional buyers prioritize bagasse for cost-sensitive catering contracts where BIS certification compliance creates supplier scarcity.
- Bamboo:Grass fiber pulping requires specialized defibration equipment for lignin separation. Japanese retail channels source bamboo for premium positioning in bento box applications.
- Palm Leaf:Areca nut plantation waste valorization uses heated pressing molds without chemical binders. United Kingdom artisanal dining operators specify palm leaf for rustic aesthetic differentiation in farm-to-table formats.
Bagasse absorbs the bulk of installed capacity; PLA is expanding most quickly.
Product Form:
Volume concentration aligns with foodservice operational complexity and holding-time requirements.
- Plates:Flat molded pulp surfaces dominate institutional catering procurement. California state mandates accelerate fiber-based plate substitution across corporate dining contracts.
- Bowls:Deep-drawn bagasse formulations with aqueous barrier coatings serve soup and grain applications. Netherlands quick-service operators specify bowls for hot cereal breakfast programs.
- Cutlery:PLA injection molding tolerances require precision tooling for tine strength. France enforces single-use plastic cutlery bans that redirect procurement toward crystallized biopolymer alternatives.
- Cups:Double-wall PLA construction with bio-based lining achieves insulated performance for hot beverages. New York City municipal composting pilots support cup collection infrastructure in urban corridors.
Plates command the highest shipment volumes; cups are climbing the fastest on delivery-format proliferation.
End User:
Procurement sophistication varies with inventory scale and sustainability disclosure obligations.
- Restaurants:Full-service operators balance aesthetic presentation against compostability certification. Italy's EFSA-aligned food contact regulations constrain coating chemistry selections for dine-in applications.
- Cafes:Independent coffee shops prioritize carbon-neutral supply chain credentials. Australian metropolitan clusters demonstrate highest per-capita compostable cup penetration.
- Catering Services:Event-based volume spikes demand flexible fulfillment with consistent specification. German municipal composting infrastructure supports predictable post-event waste stream processing.
- Households:Retail-packaged assortments concentrate in urban sustainability-conscious demographics. California and New York state-level plastic restrictions accelerate consumer substitution patterns.
Restaurants anchor commercial demand; households are gaining share fastest on retail channel expansion.
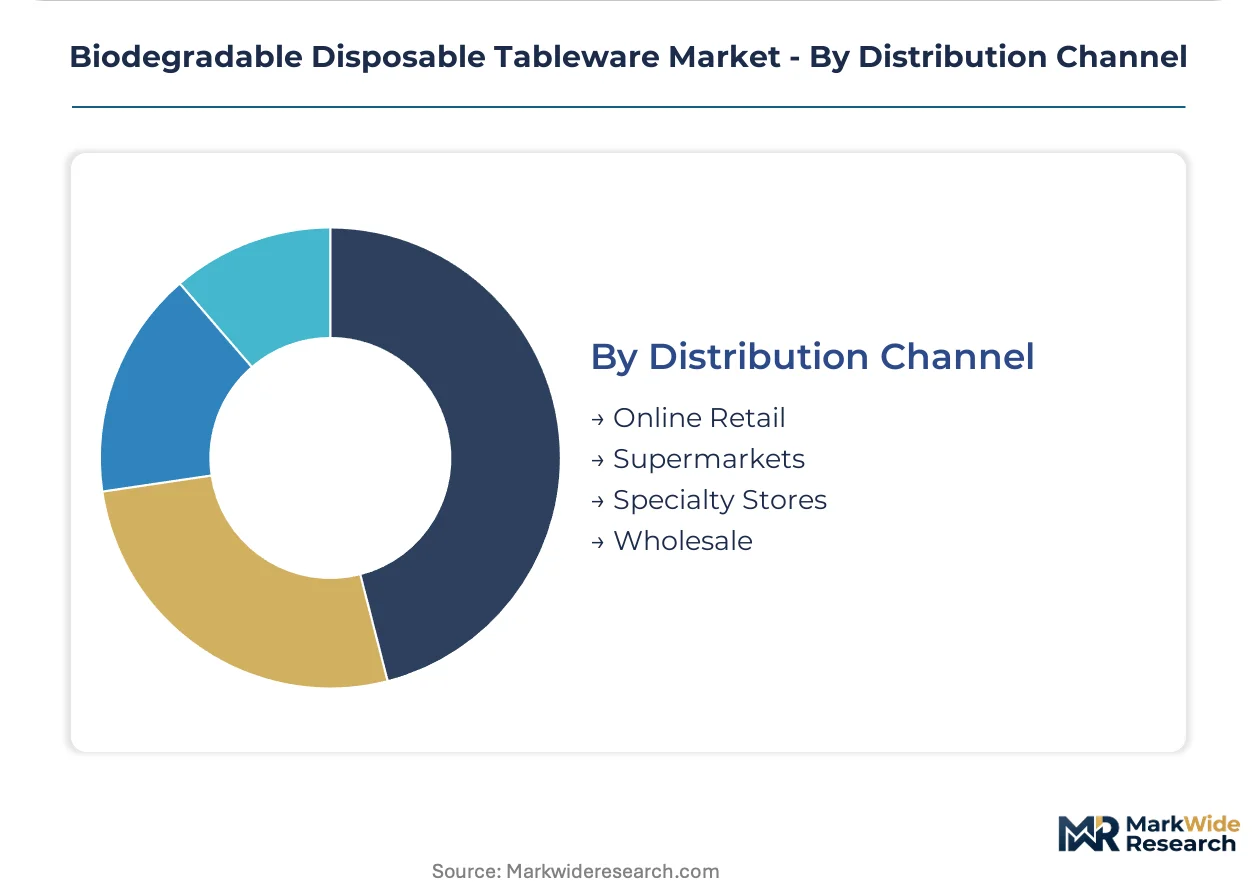
Distribution Channel:
Channel selection determines margin structure and technical specification depth in buyer relationships.
- Online Retail:Digital platforms aggregate fragmented foodservice procurement with automated reorder algorithms. Netherlands-based operators leverage subscription models for multi-location inventory management.
- Supermarkets:Mass retail placement requires standardized SKUs with consumer-facing compostability labeling. French hypermarket chains dedicate shelf space to PLA and fiber-based alternatives under EU directive compliance.
- Specialty Stores:Curated assortments serve artisanal food producers and zero-waste retail formats. United Kingdom independent eco-retailers stock palm leaf and bamboo for premium positioning.
- Wholesale:Direct manufacturer relationships dominate institutional contract fulfillment. Indian BIS-certified suppliers penetrate university and hospital channels through compliant wholesale partnerships.
Wholesale controls institutional volume; online retail shows the steepest expansion trajectory on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in India and China while consumption concentrates in Western European and North American foodservice markets. This geographic split shapes trade flows and regulatory compliance requirements across the biodegradable tableware sector.
Germany
Quick-service restaurant chains and municipal catering contracts absorb substantial bagasse and PLA volumes. The EU Single-Use Plastics Directive and national packaging ordinances mandate compostable alternatives for on-premise dining. Industrial composting infrastructure in Bavaria and Baden-Württemberg supports closed-loop waste processing for Berlin-based foodservice operators.
United States
California and New York state-level plastic restrictions are accelerating procurement shifts among corporate dining operators and university foodservice programs. The FDA maintains food-contact substance notification requirements that PLA and bagasse suppliers must satisfy for interstate commerce. West Coast metropolitan clusters demonstrate the highest per-capita compostable tableware penetration due to municipal collection infrastructure.
India
Institutional buyers in university and hospital channels prioritize cost-sensitive bagasse contracts where BIS certification creates compliant-supplier scarcity. The Bureau of Indian Standards mandates compostable plastics testing for food-contact applications. Manufacturing concentrates in Maharashtra and Gujarat where sugarcane processing waste streams lower feedstock costs for molded pulp exporters.
United Kingdom
National pizza chains and ghost kitchen operators pilot barrier-coated bagasse formulations for hot-oil delivery applications. The Environment Agency enforces waste hierarchy regulations that prioritize compostable serviceware in municipal procurement. London metropolitan foodservice clusters drive premium demand for palm leaf and bamboo alternatives in artisanal dining formats.
Netherlands
Quick-service operators specify deep-drawn bagasse bowls for hot cereal breakfast programs across franchise networks. REACH chemical frameworks constrain conventional plastic additives in food-contact applications. Randstad urban corridors support subscription-based replenishment programs through automated reorder algorithms tied to municipal composting collection.
Biodegradable Disposable Tableware Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the biodegradable tableware sector. Consolidated multinational packaging groups control institutional contract fulfillment through direct manufacturing footprints. Three strategic archetypes dominate: European-based diversified packaging conglomerates, North American sustainability-focused specialists, and Asian commodity-scale molded fiber producers. Competitive moves center on geographic licensing agreements and backward integration into agricultural residue supply chains.
Among sustainability-focused specialists, Eco-Products, Inc., World Centric, and BioPak occupy positions anchored by carbon-neutral distribution models and foodservice channel relationships. These companies exemplify the asset-light designer archetype that relies on contract manufacturing rather than captive production assets. Their market presence reflects procurement digitization trends and municipal composting infrastructure alignment rather than manufacturing scale advantages.
| Leading Market Players |
|---|
| Eco-Products, Inc. |
| World Centric |
| BioPak |
| Green Paper Products LLC |
| Sabert Corporation |
| Huhtamaki |
| Genpak LLC |
| Novolex |
| Pactiv Evergreen Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into sugarcane bagasse supply chains anchors cost positioning for Asian molded fiber producers while European PLA compounders rely on outsourced corn starch feedstock, creating divergent margin structures across material tiers. This supply architecture concentrates pricing power with feedstock-advantaged manufacturers in Maharashtra and Gujarat, while crystallization-equipped processors in Germany command premiums for heat-tolerant formulations.
Pricing Analysis
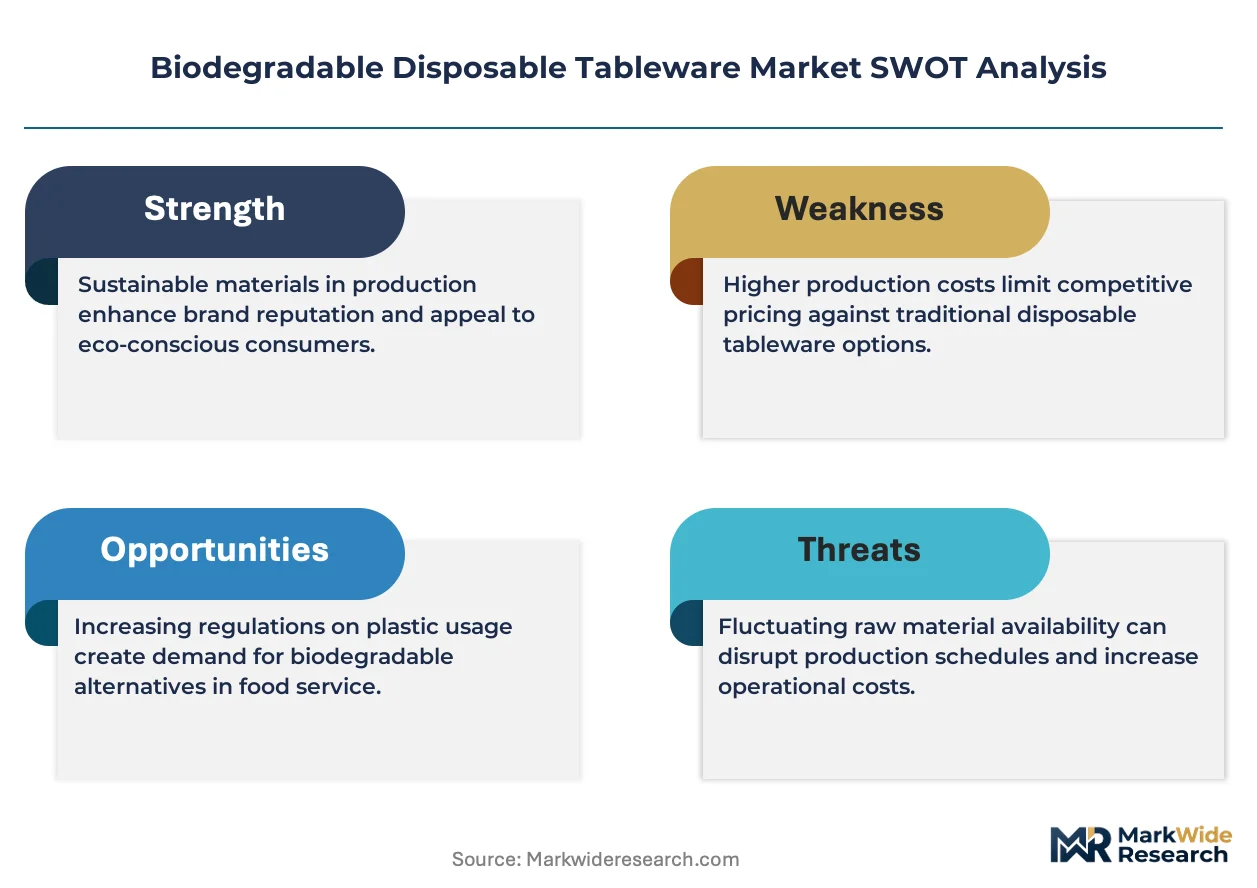
Price erosion across standard-grade bagasse traces to capacity expansion in Indian sugarcane processing regions compressing per-unit feedstock costs. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D6400-certified PLA from uncertified fiber alternatives and commodity pulp grades. Cost compression in economy tiers accelerates because municipal composting infrastructure gaps force landfill-bound products to compete on raw material cost alone. Quick-service restaurant chains exhibit lowest price sensitivity due to franchise-standardization requirements, while independent cafes demonstrate highest sensitivity to per-unit differentials.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns serving Northern European quick-service networks with predictable replenishment cycles. Manufacturing concentrates in India, China, and Germany, with raw material dependencies on sugarcane bagasse, corn starch, and areca nut plantation waste. Tariff exposure on PLA resin imports into the European Union creates margin vulnerability for non-captive compounders. Distribution runs through wholesale channels for institutional contracts and direct digital platforms for independent foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained crystallization capacity for heat-tolerant PLA formulations props pricing premiums, creating defensive moats for equipped manufacturers while limiting volume scalability for aspirants.
For Market Incumbents: Hedge against bagasse feedstock cost volatility through long-term supply agreements with Maharashtra sugarcane processors. Secure ASTM D6400 and EN 13432 certification assets ahead of EU enforcement milestones to defend position against emerging Asian exporters. Prioritize R&D investment in barrier-coated fiber formulations that bypass PLA crystallization bottlenecks for hot-oil applications. For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany, France, and Italy opens a window for BIS-certified Indian suppliers to penetrate university and hospital procurement channels where compliant-supplier scarcity persists. Target California and New York state mandate corridors for fiber-based plate and bowl substitution ahead of federal standardization. Pursue carbon-neutral distribution partnerships with independent cafe networks as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in sustainability-focused specialist acquisitions by diversified packaging conglomerates seeking foodservice channel relationships. Five-to-ten-year viability hinges on municipal composting infrastructure buildout rates rather than manufacturing scale advantages. Monitor industrial composting facility permitting velocity in Atlantic US metros and Central European markets as the critical inflection signal for end-of-life value capture realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Supply | Captive bagasse access from Maharashtra sugarcane processors locks in feedstock cost advantages against volatile corn starch markets. |
| Multi-Compostability Certification Investment | ASTM D6400 and EN 13432 dual qualification opens German QSR and US institutional procurement channels simultaneously. |
| Barrier-Coated Fiber R&D Scale-Up | Aqueous barrier formulations achieving 48-hour grease resistance unlock hot-oil applications previously reserved for polypropylene. |
| Subscription-Based Replenishment Platform Launch | Automated reorder algorithms tied to municipal composting collection infrastructure secure predictable volume commitments from multi-location operators. |
| Regional Distribution Center Expansion | Rotterdam and Hamburg hub capacity additions compress lead times for Northern European quick-service franchise networks. |
Methodological Framework
Document review covered EU regulatory filings, BIS certification registries, and municipal composting infrastructure databases, complemented by interviews with foodservice procurement managers, PLA formulation chemists, sugarcane processing plant managers, and wholesale distribution channel partners. Secondary validation drew from FDA food-contact substance notifications, REACH chemical framework disclosures, and trade flow data. Bottom-up volume modeling triangulated against top-down market sizing from material consumption patterns.
Historical capacity utilization rates cross-referenced against panel input from thermoforming equipment manufacturers and agricultural residue processors shaped the analytical framework. Segmentation dimensions modeled include material chemistry tier, product form specification, end-user procurement sophistication, and regional composting infrastructure maturity. CAGRs derived from installed capacity expansion trajectories and substitution elasticity coefficients across foodservice channels. Forecast inputs incorporated PLA crystallization yield improvements and barrier coating adoption curves.
The model assumes a particular technology adoption path; alternative pathways for bio-based polymer barrier films would alter the outlook if petroleum-based coating phase-outs accelerate beyond REACH timelines. Forecasts reflect assumptions on municipal composting facility acceptance criteria evolution and EU directive enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Starch-Based Plastics Market
Bioplastics
US Bioplastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Global Bioplastic Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
North America Bioplastics Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Global Bioplastic Composites Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market