
 Cellulose Plastics Market | 2026-2036
Cellulose Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Plastics Market Outlook
ISO 17025 laboratory accreditation is collapsing the supplier base for cellulose acetate pellet certification in medical and food-contact grades. Borregaard leverages its Norwegian wood-pulp backward integration to secure hemicellulose feedstock at scale. Celanese Corporation anchors North American supply through controlled acetylation capacity in Kentucky and Virginia. Daicel Corporation dominates Asian cellulose derivative output with captive film extrusion for eyeglass and display applications.
Cellulose plastics comprise thermoplastic materials derived from regenerated cellulose through esterification, yielding products with tensile strengths of 15-60 MPa and degradation temperatures above 200°C depending on substituent degree; these materials serve as petrochemical alternatives where optical clarity, dimensional stability, or compostability prove essential. Cellulose acetate leads product type revenue due to mature cigarette filter and photographic film infrastructure, while carboxymethyl cellulose claims the fastest application growth in water-based adhesive formulations. Films and coatings command margin concentration through pharmaceutical blister pack and luxury packaging specifications that reward optical-grade consistency.
REACH registration requirements and EU Green Deal bioeconomy targets compel European compounders to document renewable carbon content above 50 percent for packaging qualifications. EPA renewable fuel standard pathways and FDA food-contact notification rules shape parallel compliance burdens in United States cellulose ester markets. Stakeholders must monitor how Japan's METI bioplastic certification and China's GB standards for biodegradable plastics redefine cross-border material equivalence before committing to regional capacity expansion.
Market Dynamics
REACH compliance deadlines are forcing packaging converters across Europe to abandon petrochemical films, triggering a wholesale feedstock transition toward cellulose esters with verified renewable carbon content above 50 percent.
Growth Catalysts
- EU Green Deal bioeconomy targets:Mandatory renewable content thresholds for automotive interior specifications in Germany and France are pulling acetate pellet volumes into Tier-1 supplier contracts.
- Eyewear and display manufacturers:Captive film extrusion capacity in Japan and China is locking in long-term offtake agreements for optical-grade cellulose derivatives.
- Water-based adhesive formulations:Carboxymethyl cellulose is capturing share from synthetic thickeners as formulators face EPA discharge limits on petrochemical additives.
Market Restraints
- Wood-pulp feedstock volatility:Norwegian and Brazilian pulp price swings transmit directly into acetate pellet margins, compressing compounder profitability during supply shocks.
- ISO 17025 accreditation scarcity:Collapsing laboratory certification capacity for medical and food-contact grades is bottlenecking supplier qualification timelines.
- Polylactic acid substitution:PLA film producers are underbidding cellulose acetate on compostability claims in single-use packaging segments.
Strategic Opportunities
- Pharmaceutical blister packs:Optical-grade consistency requirements are creating margin concentration for certified producers able to meet US FDA notification rules.
- India's PLI scheme for bioplastics:Production-linked incentives are attracting cellulose ester capacity targeting domestic packaging and textile fiber markets.
- 3D printing filament:Cellulose acetate butyrate is penetrating fused deposition modeling applications where dimensional stability exceeds polylactic acid performance.
Industry Challenges
- Acetylation chemistry expertise:The shrinking pool of process engineers capable of controlling degree-of-substitution in continuous reactors is constraining capacity expansion.
- Multi-jurisdiction notification timelines:Parallel FDA food-contact and EFSA safety assessments are extending product launch cycles by 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Plastics Market |
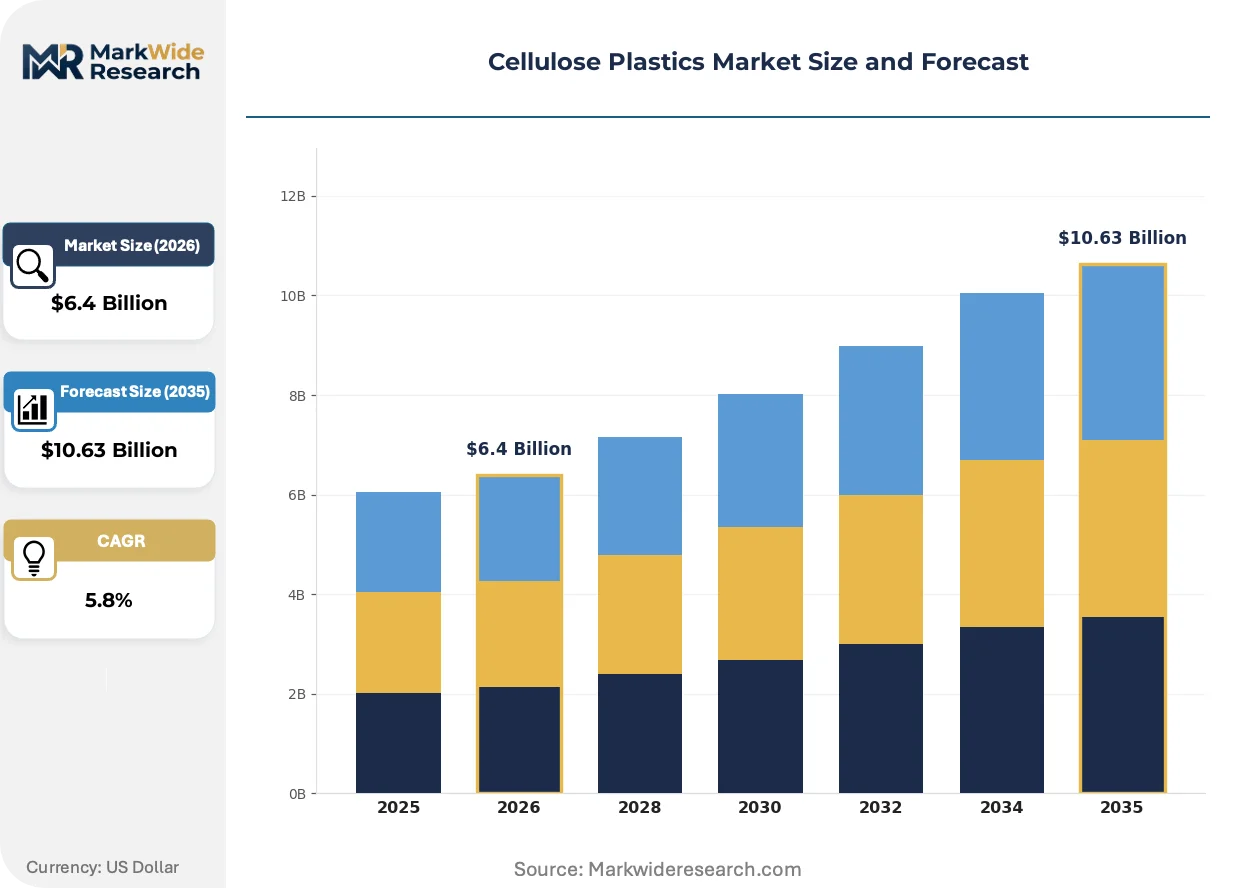
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose Acetate, Cellulose Butyrate, Cellulose Nitrate, Carboxymethyl Cellulose End User: Packaging, Automotive, Electronics, Consumer Goods Application: Films, Coatings, Fibers, Adhesives Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Solvay S.A., Borregaard, Celanese Corporation, UPM, Stora Enso, Eastman Chemical Company, Sappi Limited, Mitsubishi Chemical Group, Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Plastics Market Strategic Shifts
Acetylation process intensification and downstream film coextrusion advances are compressing cost structures while regulatory mandates in three major economies are locking in bio-based procurement preferences.
Continuous reactor acetylation technology is supplanting batch processing in new capacity installations. Kentucky-based producers are adopting plug-flow reactor designs that cut solvent recovery costs by half. This technology shift is enabling price parity with polystyrene in commodity packaging grades.
REACH registration requirements are tightening documentation burdens for imported cellulose derivatives. ECHA substance evaluation protocols now demand full supply chain mass-balance certification. German and Italian compounders are responding by consolidating procurement around vertically integrated Nordic pulp suppliers.
Automotive interior buyers are embedding renewable content clauses directly into Tier-2 supply agreements. Specifications from Stuttgart and Munich engineering centers now mandate cellulose acetate fiber content in dashboard substrates. This specification cascade is visible across German OEM supply chains and is propagating into Chinese joint-venture assembly plants.
Cellulose Plastics Market Segmentation
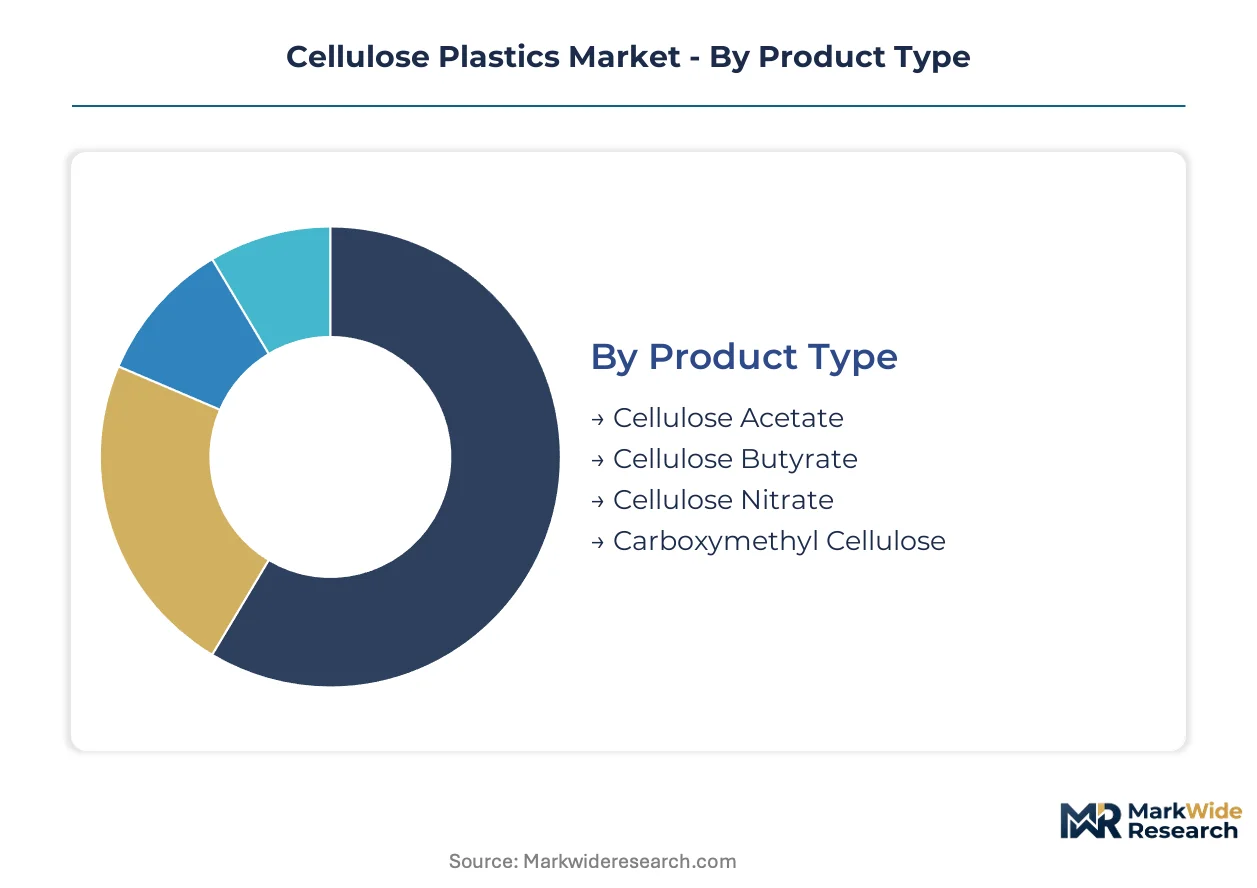
Cellulose plastics derive commercial value from substituent chemistry and degree-of-esterification precision. Segmentation by product type, end-use, and application channel reveals where REACH compliance and ISO 17025 certification create margin separation.
Product Type:
REACH registration tiers and FDA food-contact notification pathways differentiate commercial viability across ester chemistries.
- Cellulose Acetate:The most mature ester chemistry with degree-of-substitution specifications between 2.0 and 2.5. Cigarette filter and optical film demand in Germany and China concentrates procurement around certified pellet producers. ECHA substance evaluation protocols now mandate full supply chain mass-balance documentation for imported grades.
- Carboxymethyl Cellulose:Water-soluble ether derivative dominating adhesive and pharmaceutical excipient formulations. EPA discharge limits on synthetic thickeners are pulling formulation share in United States water-based adhesives. India's PLI scheme for bioplastics is attracting regional capacity targeting textile sizing and construction additives.
- Cellulose Butyrate:Higher butyryl content delivers improved weather resistance and dimensional stability for automotive and construction films.
- Cellulose Nitrate:Legacy chemistry now concentrated in lacquer and printing ink applications with restricted medical use due to flammability profiles.
Established volume favors cellulose acetate; emerging adoption favors carboxymethyl cellulose.
End User:
Automotive and packaging buyers now embed renewable content clauses directly into Tier-2 supply agreements.
- Packaging:Blister packs and luxury wrapping drive optical-grade consistency premiums. German and Italian compounders are consolidating procurement around Nordic pulp suppliers with verified renewable carbon content above 50 percent.
- Automotive:Dashboard substrates and interior trim specifications from Stuttgart engineering centers mandate cellulose acetate fiber content. This specification cascade propagates into Chinese joint-venture assembly plants.
- Electronics:Display polarizer films and eyeglass frames require ultra-low birefringence grades.
- Consumer Goods:Eyewear frames and tool handles exploit thermoplastic processability with bio-based positioning.
Regulatory pull concentrates in automotive; cost-driven substitution dominates consumer goods.
Application:
Film extrusion and coating lines reward optical-grade consistency with 15-30 percent margin premiums over commodity grades.
- Films:Pharmaceutical blister packs and display polarizers command the strictest certification requirements. US FDA notification rules and EFSA safety assessments extend product launch cycles by 18-24 months for global suppliers.
- Adhesives:Carboxymethyl cellulose thickening efficiency is displacing petrochemical alternatives in water-based construction and packaging adhesives.
- Coatings:Lacquer and wood finish applications exploit rapid solvent release and high gloss.
- Fibers:Cigarette tow and textile yarn spinning represent mature demand with limited growth trajectory.
Margin concentration sits in films; volume scale sits in fibers.
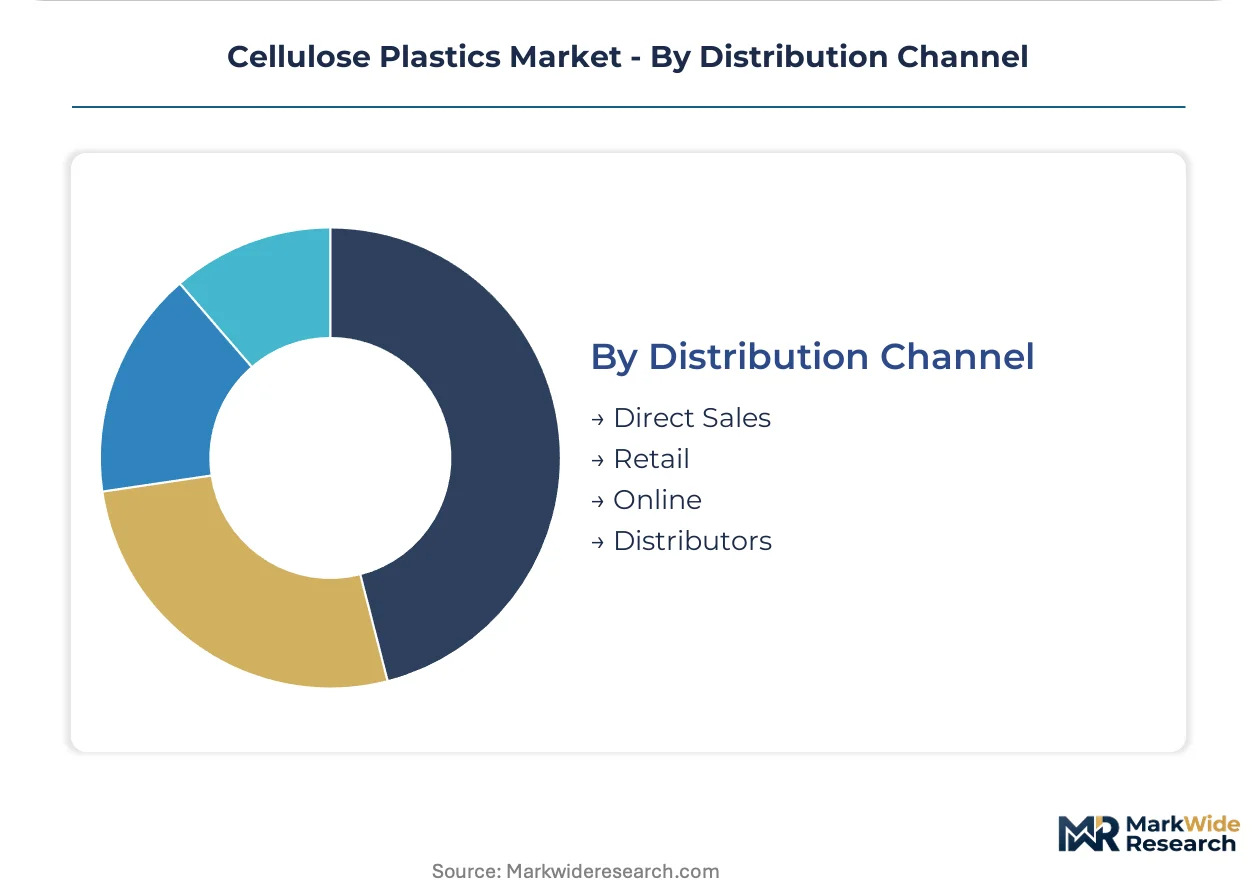
Distribution Channel:
ISO 17025 accreditation scarcity is collapsing qualified supplier bases and pushing procurement toward direct mill relationships.
- Direct Sales:Tier-1 automotive and pharmaceutical buyers require batch-level certification and audit rights. Kentucky and Virginia producers anchor North American supply through controlled acetylation capacity with captive technical service.
- Distributors:Regional compounders in Europe and Asia rely on stocked pellet grades with pre-cleared REACH documentation.
- Online:3D printing filament and small-batch specialty grades for research laboratories.
- Retail:Limited to consumer-facing craft and hobby applications with minimal commercial significance.
Compliance complexity favors direct sales; geographic fragmentation favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive interior buyers in Stuttgart and Munich engineering centers concentrate procurement power for cellulose acetate fiber specifications. Packaging converters across German and Italian hubs consolidate procurement around Nordic pulp suppliers with verified renewable carbon content thresholds.
Germany
Stuttgart and Munich engineering centers mandate renewable content thresholds in dashboard substrate specifications. EU Green Deal bioeconomy targets and REACH compliance deadlines force Tier-1 suppliers to document mass-balance certification. Bavarian and Baden-Württemberg automotive clusters anchor acetate pellet demand for interior trim applications.
China
Joint-venture assembly plants propagate German OEM cellulose acetate specifications into domestic supply chains. GB standards for biodegradable plastics and dual carbon goals reshape material equivalence definitions. Yangtze River Delta and Pearl River Delta display manufacturers lock in long-term offtake for optical-grade cellulose derivatives.
United States
Kentucky and Virginia acetylation capacity anchors North American supply through controlled production infrastructure. EPA renewable fuel standard pathways and FDA food-contact notification rules create parallel compliance burdens for medical and pharmaceutical grades. Southeast packaging converters face tightening discharge limits on petrochemical additives.
Japan
METI bioplastic certification redefines cross-border material equivalence for cellulose ester imports. Eyewear frame and display polarizer manufacturers in Kanto and Kansai regions require ultra-low birefringence grades with captive film extrusion capacity. Nagoya engineering centers specify renewable content for automotive interior components.
India
PLI scheme for bioplastics attracts cellulose ester capacity targeting domestic packaging and textile fiber markets. Maharashtra and Gujarat chemical hubs compound water-based adhesives with carboxymethyl cellulose displacing synthetic thickeners. BIS standards alignment with EU REACH documentation accelerates supplier qualification timelines.
Cellulose Plastics Market Competitive Environment
Player mix skews toward pulp-integrated chemical specialists and acetylation-focused compounders with captive technical service. Market structure concentrates around vertically integrated Nordic wood-pulp suppliers and North American acetylation hubs. Two strategic archetypes dominate: backward-integrated pulp-to-ester producers controlling feedstock costs, and optical-grade specialists commanding certification premiums. Competitive moves center on continuous reactor technology licensing and ISO 17025 laboratory accreditation consolidation.
Among Nordic pulp-integrated specialists, Borregaard exemplifies backward integration into Norwegian wood-pulp feedstock securing hemicellulose supply at scale. Celanese Corporation anchors North American positioning through Kentucky and Virginia acetylation infrastructure with controlled capacity. Daicel Corporation occupies the optical-grade specialist tier dominating Asian cellulose derivative output with captive film extrusion for display applications.
| Leading Market Players |
|---|
| Solvay S.A. |
| Borregaard |
| Celanese Corporation |
| UPM |
| Stora Enso |
| Eastman Chemical Company |
| Sappi Limited |
| Mitsubishi Chemical Group |
| Daicel Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 17025 accreditation scarcity gates both supplier qualification timelines and price premiums across medical and food-contact cellulose ester grades. REACH mass-balance documentation requirements compound certification costs, forcing compounders to absorb audit expenses or pass them downstream through tiered pricing structures.
Pricing Analysis
Long-term offtake contracts with wood-pulp indexation dominate procurement between Nordic suppliers and German automotive Tier-1s. Three-tier pricing structure across optical-grade, medical-certified, and commodity packaging levels separates certified producers from uncertified competitors. Cost compression in commodity acetate pellets is intensifying because PLA film producers underbid on compostability claims. Packaging converters show highest price sensitivity, while pharmaceutical blister pack buyers accept premiums for batch-level traceability.
Supply Chain Analysis
Norway and Brazil anchor hemicellulose feedstock supply through Borregaard's pulp backward integration and South American eucalyptus plantations. Kentucky and Virginia acetylation hubs draw from Appalachian hardwood pulp and Gulf Coast chemical inputs. Single-source vulnerability concentrates in optical-grade film extrusion, where Daicel's captive capacity in Japan locks Asian display manufacturers into sole-source dependencies. Distribution runs through direct mill relationships for certified grades and regional distributors for commodity pellets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and certification audit subscriptions now expand faster than base pellet volumes, creating recurring-revenue layers that compound customer lifetime value. This service-attach dynamic favors incumbents with captive laboratory infrastructure.
For Market Incumbents: Compound certification moats by acquiring distressed ISO 17025 laboratories facing accreditation collapse. Add continuous reactor capacity in Kentucky or Virginia to cut solvent recovery costs against PLA substitution threats. Lock Tier-2 automotive suppliers into renewable content clauses before Chinese joint-ventures propagate German specifications. For New Entrants and Emerging Players: FDA food-contact notification fast-tracks offer entry into pharmaceutical blister pack white space where 18-24 month launch cycles deter commodity competitors. Target India's PLI scheme for bioplastics to capture carboxymethyl cellulose demand in water-based adhesives. Lead with technical service partnerships rather than price undercutting. For Investors and Strategic Acquirers: ECHA substance evaluation protocol expansion reshapes the acquisition landscape toward Nordic pulp-integrated specialists with verified mass-balance documentation. Five-to-ten year viability hinges on backward integration depth rather than spot-market trading. Watch for cellulose acetate butyrate filament adoption in 3D printing as inflection signal for specialty grade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wood-Pulp Feedstock | Borregaard's Norwegian hemicellulose control secures margin insulation against Brazilian pulp volatility. |
| Continuous Reactor Technology Licensing | Kentucky plug-flow designs cut solvent recovery costs by half, enabling polystyrene price parity. |
| ISO 17025 Laboratory Accreditation Consolidation | Acquisition of collapsing certifiers bottlenecks competitor qualification timelines for medical grades. |
| Long-Term Optical-Grade Film Offtake Agreements | Daicel's captive extrusion locks Kanto and Kansai display manufacturers into sole-source dependencies. |
| Joint Venture in India PLI Bioplastics Scheme | Maharashtra and Gujarat hubs target domestic packaging with carboxymethyl cellulose adhesive formulations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at acetylation facilities, procurement leads at German automotive Tier-1 suppliers, distribution channel partners in European compounding hubs, and technical R&D directors at cellulose derivative producers; and secondary validation through customs and trade data, Cefic chemical industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up volume builds triangulated against top-down macroeconomic drivers.
Across the analysis window, forecasts segment by ester chemistry type, end-use industry vertical, certification grade tier, and regional production hub. CAGRs derive from elasticity-adjusted demand curves incorporating automotive renewable content mandates and packaging converter feedstock transition rates. Modeled inputs include wood-pulp price index trajectories and laboratory accreditation capacity constraints.
Underlying assumptions cover REACH enforcement continuity and ISO 17025 laboratory survival rates, with deviation risk concentrated in PLA substitution acceleration and Chinese GB standards divergence from EU mass-balance definitions. Recalibration cycles align with ECHA substance evaluation protocol expansions and major automotive OEM specification releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Automotive Bioplastic Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Biopolymer Films Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Europe Bioplastics Market
Bioplastics
US Bioplastics Market