
 Bio-Polyamide, Specialty Polyamide and Precursors Market | 2026-2036
Bio-Polyamide, Specialty Polyamide and Precursors Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Polyamide, Specialty Polyamide and Precursors Market Insights
Castor oil-derived sebacic acid is expanding its displacement of petroleum-based adipic acid in long-chain polyamide production. BASF leverages integrated precursor manufacturing in Europe to sustain cost-competitive bio-polyamide supply chains. Evonik Industries anchors its position through specialized polyamide 12 expertise in medical tubing and pneumatic systems. Arkema differentiates via high-performance polyamide 11 derived from renewable castor beans, dominating offshore oil and gas flexible pipe applications.
Bio-polyamide, specialty polyamide and precursors comprise engineered thermoplastic polymers synthesized partly or wholly from renewable feedstocks, with melting points typically ranging from 178°C to 295°C and tensile strength exceeding 80 MPa in reinforced grades, serving industries requiring chemical resistance, dimensional stability, and reduced carbon footprint versus conventional aliphatic polyamides. Polyamide 12 granules command premium positioning in automotive fuel lines and pneumatic brake tubing where low moisture absorption proves critical. Precursor intermediates such as aminoundecanoic acid and laurolactam represent the fastest-expanding value pool as manufacturers backward-integrate into bio-based feedstock security. Molded parts in electrical insulation applications occupy mature volume positions with steady replacement demand from household appliances and consumer electronics sectors.
REACH registration requirements and the EU Green Deal's carbon border adjustments constrain petrochemical-based polyamide imports while incentivizing certified bio-based content. China's MIIT enforces dual carbon targets that redirect state-supported capacity toward castor and soybean oil derivative pathways. The US EPA's renewable chemical evaluations under the Toxic Substances Control Act shape market access for novel bio-polyamide chemistries. Stakeholders must monitor precursor feedstock origination certifications and regional carbon accounting methodologies to secure offtake agreements in automotive and electronics supply chains.
Market Dynamics
Automotive lightweighting mandates and REACH restrictions on petrochemical feedstocks are forcing a structural reconfiguration of polyamide supply chains toward castor oil and soybean oil derivatives. Manufacturers must secure certified bio-based precursor streams to maintain offtake agreements with German and Japanese automotive OEMs.
Growth Catalysts
- EU Green Deal carbon border adjustments:Petrochemical-based polyamide imports face escalating compliance costs, redirecting procurement toward certified bio-based alternatives in automotive under-the-hood applications.
- China's dual carbon targets:MIIT enforcement redirects state-supported capacity investments toward castor and soybean oil derivative pathways, expanding domestic precursor production.
- Polyamide 12 in pneumatic brake tubing:Low moisture absorption specifications in automotive fuel systems are accelerating specification upgrades from conventional aliphatic grades.
Market Restraints
- Castor bean supply concentration:Over 80% of global castor oil originates from Indian subcontinent agricultural regions, exposing precursor costs to monsoon volatility and export policy shifts.
- Sebacic acid production bottlenecks:Alkaline cleavage of castor oil remains energy-intensive, constraining cost-competitive scaling against petroleum-based adipic acid at current crude price levels.
- REACH registration timelines:Novel bio-polyamide chemistries face extended evaluation periods under ECHA substance assessment protocols, delaying market entry.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic value-addition incentives for castor oil derivatives are attracting backward-integrated precursor investments from European polyamide compounders.
- Medical tubing specification upgrades:Polyamide 12 expertise in catheters and surgical instruments offers premium positioning as healthcare systems prioritize single-use sterilization compatibility.
- Blockchain-enabled feedstock traceability:Immutable certification of renewable content origin is unlocking automotive OEM long-term supply agreements with verified carbon accounting.
Industry Challenges
- Polymerization process engineering talent:Scarcity of specialists in bio-based lactam ring-closing chemistry limits capacity expansion timelines for new market entrants.
- Multi-standard certification complexity:Reconciling USDA BioPreferred, TUV Austria OK Compost, and automotive IATF 16949 requirements extends product qualification cycles.
- Legacy equipment retrofit costs:Conventional polyamide 6,6 production lines require substantial modification to handle bio-based feedstock viscosity profiles and thermal behavior.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Polyamide, Specialty Polyamide and Precursors Market |
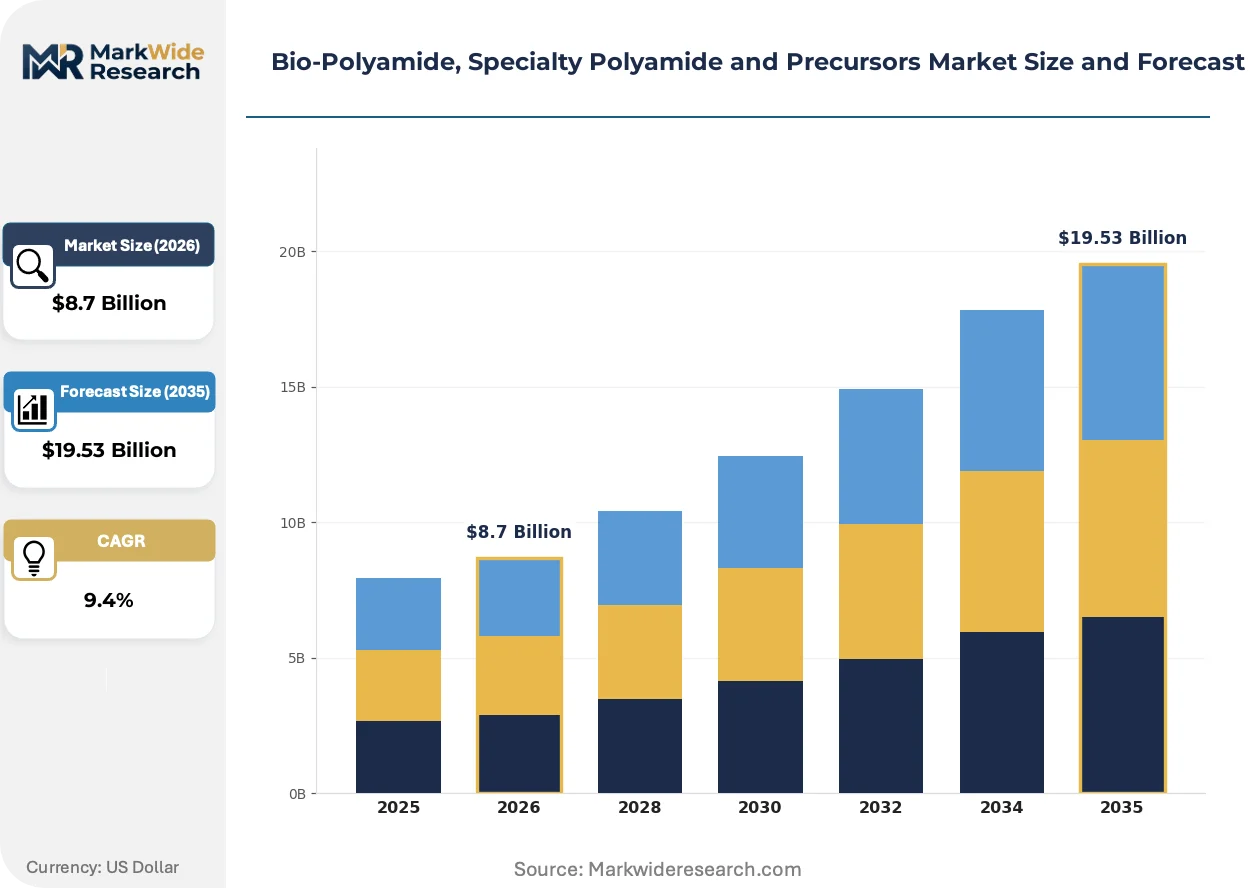
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Polyamide 6, Specialty Polyamide 11, Polyamide 12, Precursors Application: Textile Fibers, Automotive Components, Electrical Insulation, Packaging Films, Sports Equipment End User Industry: Consumer Electronics, Household Appliances, Footwear Manufacturing, Industrial Machinery Form: Granules, Films, Fibers, Powders, Molded Parts |
| Companies Covered | Arkema, BASF, Evonik Industries, RadiciGroup, DuPont, Asahi Kasei, DOMO Chemicals, Invista, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Polyamide, Specialty Polyamide and Precursors Market Trends and Innovations
Enzymatic catalysis for sebacic acid production is compressing energy requirements and carbon intensity in precursor manufacturing. Regulatory carbon accounting methodologies are rewriting competitive positioning between petrochemical and bio-based supply chains.
Second-generation fermentation pathways for aminoundecanoic acid are rewriting the economics of polyamide 11 production. Specialty compounders in Western Europe are piloting these routes to reduce dependency on castor oil agricultural constraints. The technology is rewriting margin structures by enabling C11 monomer synthesis from sugar feedstocks with 40% lower thermal energy input.
REACH restrictions on C9-C14 aliphatic hydrocarbons are tightening petrochemical polyamide precursor availability. German automotive suppliers are accelerating bio-based specification approvals to preempt supply disruption. Electrical insulation system manufacturers in France and Italy face compressed qualification timelines to maintain CE marking compliance.
Automotive OEMs are consolidating approved supplier lists around vertically integrated bio-polyamide compounders with captive precursor production. Tier-2 component manufacturers in Japan are accepting longer lead times for certified renewable content. Procurement concentration is most visible in fuel line and pneumatic tubing applications where material traceability requirements have intensified.
Bio-Polyamide, Specialty Polyamide and Precursors Market Segmentation
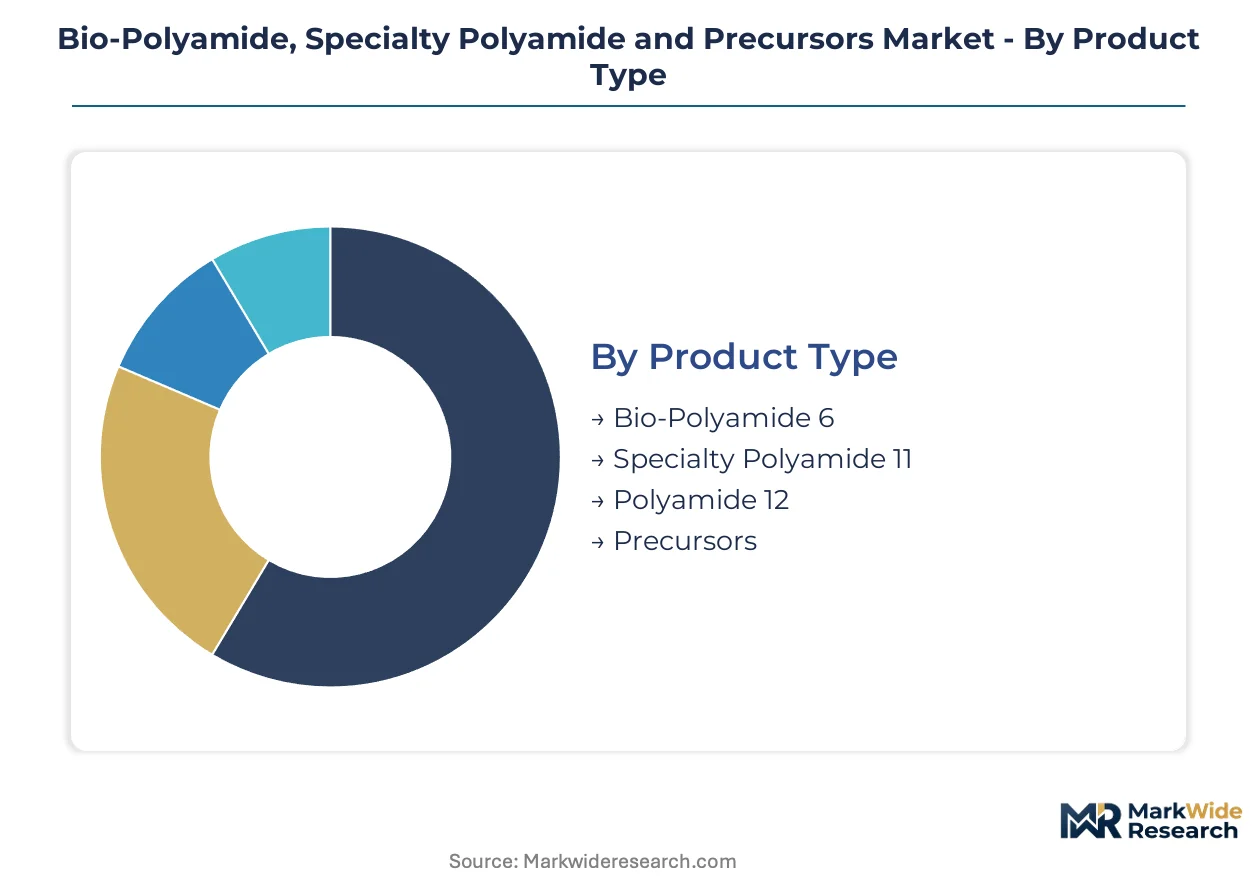
Segmentation in bio-polyamides reveals how feedstock security, polymerization complexity, and end-use certification requirements stratify value capture across the supply chain. Each dimension exposes different vulnerability points—from castor bean harvest volatility to automotive material qualification timelines.
Product Type:
Supply concentration in castor oil derivatives and petroleum-based lactam intermediates dictates which product families command pricing power and backward integration investments.
- Specialty Polyamide 11:Derived entirely from castor oil via aminoundecanoic acid polymerization, this grade delivers exceptional chemical resistance and dimensional stability for offshore flexible pipes. German automotive OEMs specify PA11 for fuel line applications where renewable content verification is mandatory, though Indian monsoon patterns constrain feedstock security.
- Polyamide 12:Laurolactam-based polymerization yields the lowest moisture absorption among commercial polyamides, critical for pneumatic brake tubing and medical catheters. Japanese tier-1 suppliers concentrate procurement around PA12 compounders with captive precursor production to satisfy material traceability requirements.
- Bio-Polyamide 6:Partially bio-based caprolactam variants offer drop-in compatibility with conventional PA6 processing equipment. Household appliance manufacturers in Italy specify these grades for visible components requiring carbon footprint reduction without mold retooling.
- Precursors:Sebacic acid, aminoundecanoic acid, and laurolactam intermediates represent the value pool where feedstock origination certification determines offtake agreement viability. European compounders are backward-integrating into Indian castor oil crushing to secure renewable content documentation.
Today's leader: Specialty Polyamide 11. Tomorrow's challenger: Precursors.
Application:
Application-driven segmentation exposes how performance specifications and regulatory exposure create divergent margin profiles across end-use markets.
- Automotive Components:Under-the-hood applications demand thermal stability above 150°C combined with resistance to automotive fluids. German KBA type-approval requirements for fuel system materials are forcing specification upgrades toward bio-based PA11 and PA12 grades with verified supply chain documentation.
- Electrical Insulation:Molded connectors and housings require UL94 V-0 flammability ratings and comparative tracking indices above 600V. French appliance manufacturers face compressed CE marking compliance timelines as REACH restrictions tighten on halogenated flame retardant alternatives.
- Textile Fibers:High-tenacity filaments for industrial yarn and carpet applications compete on cost with conventional PA6,6. Footwear brands in Vietnam specify bio-based content for export to EU markets subject to carbon border adjustments.
- Packaging Films:Biaxially oriented PA films for food packaging require oxygen barrier properties and thermoformability. Japanese converters are qualifying bio-polyamide alternatives to meet corporate sustainability commitments without sacrificing line speeds.
- Sports Equipment:Ski bindings, bicycle components, and protective gear leverage high-impact resistance and fatigue performance. Premium positioning depends on renewable content certification visible to consumer purchasers.
Automotive Components commands current volume concentration. Electrical Insulation is climbing the fastest as appliance electrification accelerates.
End User Industry:
Customer-type segmentation reveals how procurement sophistication and sustainability disclosure obligations fragment addressable markets.
- Consumer Electronics:Laptop chassis, smartphone structural components, and connector housings demand thin-wall moldability and EMI shielding compatibility. Chinese ODMs are integrating bio-based content specifications to satisfy brand-owner Scope 3 reduction targets.
- Industrial Machinery:Gears, bearings, and conveyor components prioritize wear resistance and dimensional stability over renewable content. Cost-competitive positioning against cast metals and engineering thermoplastics limits bio-polyamide penetration.
- Footwear Manufacturing:Midsole plates, eyelets, and structural reinforcements in athletic shoes exploit high strength-to-weight ratios. Vietnam and Indonesia production facilities are qualifying bio-based grades for EU and US brand owner supply chains.
- Household Appliances:Washing machine pulleys, dishwasher racks, and vacuum cleaner housings represent mature replacement demand with steady specification continuity. Italian and Polish appliance clusters maintain volume positions through established compounder relationships.
Consumer Electronics leads procurement sophistication. Footwear Manufacturing is gaining share fastest on sustainability marketing differentiation.
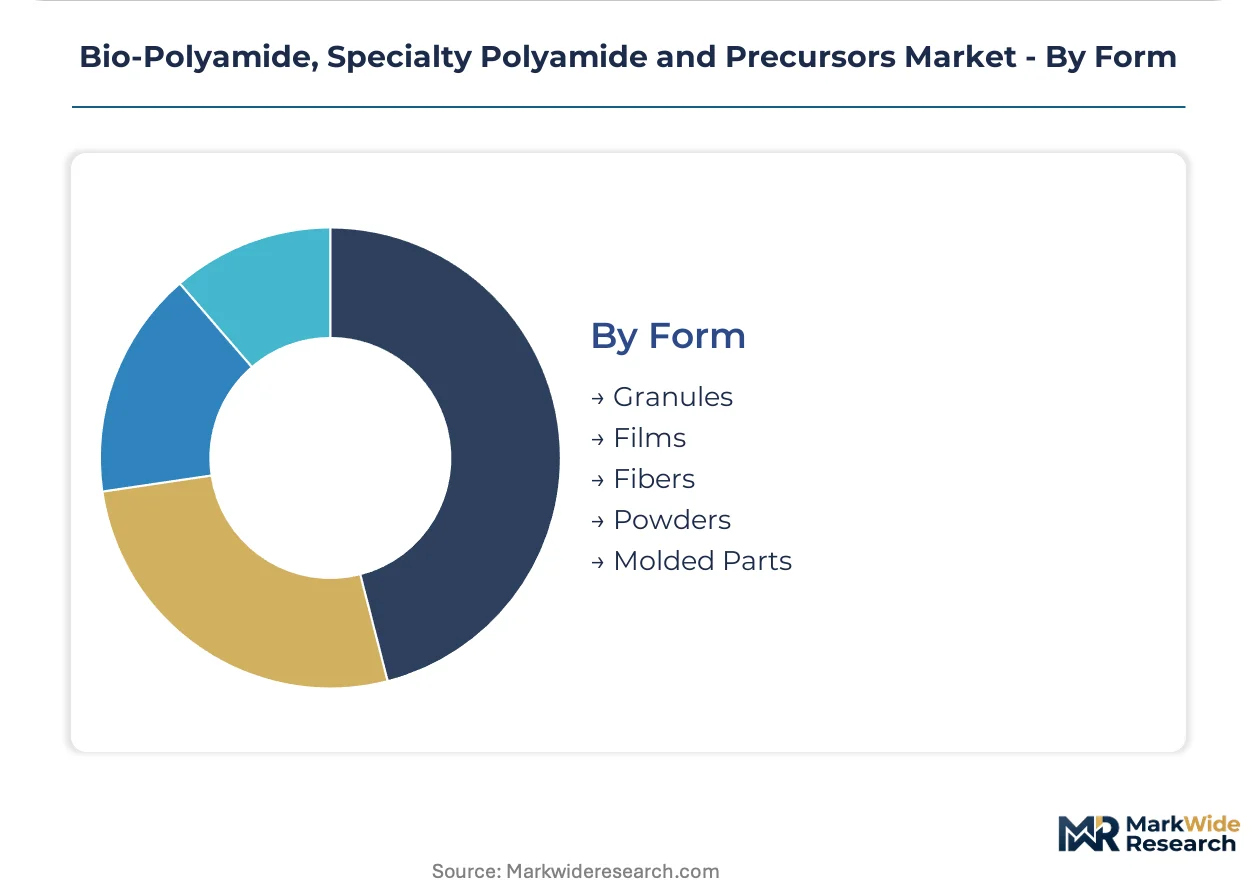
Form:
Physical form determines processing technology requirements and the distribution channel structure connecting resin producers to end-users.
- Granules:Standard injection molding and extrusion feedstock dominates volume throughput. Automotive and appliance compounders in Germany and Japan specify melt flow indices and moisture content tolerances that constrain supplier qualification.
- Molded Parts:Direct-to-component manufacturing bypasses compounder intermediaries for high-volume, long-term contracts. Medical device manufacturers in Switzerland specify PA12 catheter components with ISO 13485 traceability requirements.
- Fibers:Melt-spun and solution-spun filaments for textile and industrial yarn applications require precise molecular weight distribution control. South Korean fiber producers are qualifying bio-based feedstocks for export to EU technical textile markets.
- Films:Cast and oriented film structures for packaging and industrial applications demand specialized extrusion equipment and slitting capabilities. French flexible packaging converters face margin pressure from bio-based raw material premiums.
- Powders:Selective laser sintering and rotational molding feedstocks serve emerging additive manufacturing and tank fabrication niches. Aerospace prototyping applications in the US specify PA12 powders with batch-level certification.
Granules retains volume leadership. Molded Parts represents the steepest expansion trajectory as OEMs consolidate around vertically integrated supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor anchors bio-polyamide procurement intensity, with OEM lightweighting mandates and KBA type-approval requirements creating concentrated specification pressure across the supply chain.
United States
Automotive fuel system manufacturers in Michigan and Ohio specify bio-based PA11 and PA12 grades for under-the-hood components. EPA renewable chemical evaluations under the Toxic Substances Control Act shape market access protocols for novel bio-polyamide chemistries. The Southeast industrial belt, particularly Tennessee and South Carolina polymer compounding clusters, is attracting precursor import partnerships to serve domestic automotive OEMs.
Germany
KBA type-approval requirements for fuel system materials mandate renewable content verification in automotive applications. EU Green Deal carbon border adjustments impose escalating compliance costs on petrochemical-based polyamide imports. The Ruhr industrial region and Bavarian automotive corridor concentrate specification upgrades toward bio-based grades with captive precursor production.
China
MIIT enforcement of dual carbon targets redirects state-supported capacity investments toward castor and soybean oil derivative pathways. Domestic appliance manufacturers in Yangtze River Delta clusters specify partially bio-based PA6 grades for visible components. Zhejiang and Jiangsu provinces are expanding precursor production to reduce import dependency for renewable content documentation.
Japan
METI industrial standards for automotive materials prioritize low moisture absorption specifications in fuel line and pneumatic tubing applications. Tier-1 suppliers in Aichi Prefecture and Kanagawa industrial zones accept extended lead times for certified renewable content. The Chubu region around Nagoya anchors procurement concentration around vertically integrated compounders with material traceability systems.
India
PLI scheme incentives for specialty chemicals attract backward-integrated precursor investments from European polyamide compounders. Over 80% of global castor oil originates from Gujarat and Rajasthan agricultural regions, exposing supply security to monsoon volatility. The Mumbai-Pune industrial corridor is emerging as a value-addition hub for sebacic acid and aminoundecanoic acid production.
Bio-Polyamide, Specialty Polyamide and Precursors Market Competitive Landscape
Global majors compete with regional champions across precursor manufacturing and compounding capabilities, producing a tiered structure where feedstock security and certification depth determine positioning. European and Asian incumbents dominate long-chain polyamide expertise, while specialty compounders carve niches in medical and automotive specification tiers. Three archetypes prevail: integrated petrochemical diversifiers, bio-based specialists with captive agriculture linkages, and regional compounders serving proximity-sensitive OEMs. Competitive moves concentrate on backward integration into Indian castor oil crushing and blockchain-enabled feedstock traceability systems.
Among integrated chemical conglomerates, BASF and Arkema exemplify divergent strategic positions—BASF leveraging European precursor manufacturing scale while Arkema anchors renewable castor bean derivation. Evonik Industries occupies a specialist tier focused on high-performance polymer expertise. These three represent the competitive spectrum from commodity-scale diversification through bio-based vertical control to application-specific technical positioning.
| Leading Market Players |
|---|
| Arkema |
| BASF |
| Evonik Industries |
| RadiciGroup |
| DuPont |
| Asahi Kasei |
| DOMO Chemicals |
| Invista |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
German automotive OEM procurement consolidation around certified renewable content is forcing precursor suppliers to absorb feedstock origination documentation costs, compressing margins at the sebacic acid and aminoundecanoic acid tiers while elevating pricing power for compounders with captive Indian castor oil linkages.
Pricing Analysis
Input-cost pass-through from castor oil agricultural volatility dominates pricing dynamics, with monsoon-dependent Indian harvests transmitting directly to sebacic acid quotations. Contract-based long-term offtake agreements predominate in automotive fuel line applications, where KBA type-approval requirements enforce supply continuity premiums. Price differentiation separates ISO 13485-certified medical grades from standard industrial tiers, with pneumatic brake tubing specifications commanding the lowest buyer price sensitivity due to non-negotiable low moisture absorption requirements. Cost compression in partially bio-based PA6 runs through household appliance channels as Italian manufacturers prioritize drop-in compatibility over renewable content verification.
Supply Chain Analysis
Freight cost differentials between Indian castor oil crushing hubs and European compounding centers are reshourcing precursor investments toward Gujarat and Rajasthan value-addition facilities. Raw material dependencies center on castor bean agricultural output, petroleum-based adipic acid for hybrid grades, and sugar feedstocks for second-generation fermentation pathways. Single-source vulnerability concentrates in Indian monsoon-exposed harvest regions, where export policy shifts can disrupt sebacic acid availability within weeks. Distribution runs through vertically integrated compounders serving German and Japanese automotive OEMs directly, bypassing traditional distributor intermediaries for certified renewable content documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon border adjustment exposure and Indian PLI scheme subsidized precursor production, with cost differentials widening as REACH restrictions tighten petrochemical feedstock compliance.
For Market Incumbents: Anticipate second-generation fermentation pathway disruption to castor oil economics by securing sugar-feedstock pilot partnerships before C11 monomer synthesis scales. Backward integration into Indian castor crushing insulates against export duty volatility, while blockchain-enabled feedstock traceability investments defend specification-tier positioning against emerging compounders lacking certification depth. For New Entrants and Emerging Players: Vietnamese footwear manufacturers seeking EU carbon border adjustment-compliant bio-based content represent the most penetrable buyer archetype, with sustainability marketing differentiation unlocking brand-owner supply chain access. Target medical tubing specification upgrades where ISO 13485 qualification barriers deter commodity compounders, deploying specialized PA12 extrusion expertise as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap compounders possessing captive precursor production and automotive OEM approved supplier list status, positioned for margin expansion as procurement consolidation accelerates. Five-to-ten year viability hinges on second-generation fermentation technology maturation. The inflection signal to monitor is Indian PLI scheme capacity absorption rates relative to European backward integration announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive sebacic acid manufacturing secures renewable content documentation for German automotive offtake agreements. |
| Blockchain-Enabled Feedstock Traceability | Immutable certification unlocks long-term supply contracts with Japanese tier-1 suppliers demanding material origination proof. |
| Second-Generation Fermentation Scale-Up | Sugar-derived C11 monomer synthesis reduces thermal energy input and loosens Indian castor oil supply dependency. |
| Medical Tubing Specification Investment | ISO 13485-qualified PA12 extrusion capabilities capture premium positioning in single-use sterilization-compatible catheter markets. |
| Joint Venture with Indian Castor Processors | PLI scheme partnerships establish localized value-addition hubs serving European compounder import requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polyamide plant managers, automotive Tier 1 procurement leads, medical device regulatory affairs directors, and Indian specialty chemicals distribution partners with secondary validation against customs trade data, SEC 10-K chemical segment disclosures, ECHA REACH registration databases, and automotive OEM supplier qualification records. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Historical reference periods anchored the projection horizon through comparable-period analysis of precursor price volatility and automotive specification upgrade cycles. Segmentation dimensions modeled included polymer grade tier, end-use industry vertical, renewable content certification level, and regional production hub clustering. CAGRs derived from iterative reconciliation of feedstock availability constraints and OEM procurement volume commitments, with castor oil harvest yield variance and REACH registration timeline uncertainty as primary forecast sensitivity inputs.
Inputs from ECHA substance databases and Indian Ministry of Chemicals production statistics were available through the study window; gaps in proprietary automotive OEM supplier qualification timelines introduce uncertainty bands around market penetration assumptions for bio-based grade specifications. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity shifts or agricultural commodity price dislocations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Europe Bioplastics Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Biopolymers Market
Bioplastics
Starch Blended Biodegradable Polymer Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
North America Bioplastics Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Bioplastic Textile Market
Bioplastics
Bio-PET Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market