
 Adeno Associated Virus Vector Manufacturing Market | 2026-2036
Adeno Associated Virus Vector Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Adeno Associated Virus Vector Manufacturing Market Intelligence
Suspension-based bioreactor platforms is tilting AAV manufacturing away from traditional adherent culture systems, enabling single-use scalability and reduced contamination risk. Lonza leverages its global cell-and-gene therapy network to anchor large-scale viral vector production across multiple continents. Catalent sustains competitive differentiation through integrated plasmid-to-viral-vector services that compress development timelines. Thermo Fisher Scientific dominates analytical testing and raw material supply, controlling critical inputs that downstream manufacturers require.
Adeno associated virus vector manufacturing encompasses the production of recombinant AAV particles through triple-transfection or baculovirus-mediated systems, typically yielding titers of 10^14 to 10^16 vector genomes per liter in optimized suspension cultures, for delivery of therapeutic genetic payloads to target tissues. The process serves gene therapy, vaccine, and gene editing applications where stable, non-integrating transgene expression remains clinically essential. Viral vector products command the largest revenue share given their irreplaceable role as the functional therapeutic entity, while transduction reagents represent the fastest-expanding category as developers seek higher-efficiency, lower-immunogenicity delivery tools. Gene therapy applications absorb the majority of current capacity, though gene editing pipelines are accelerating fastest as CRISPR-AAV combinations advance through clinical validation.
FDA guidance on gene therapy CMC and EMA's ATMP framework collectively shape product characterization standards, lot release criteria, and comparability protocols that manufacturers must satisfy for market authorization. The EPA and OSHA additionally govern biosafety containment levels and environmental discharge limits for facilities handling recombinant viral agents. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on potency assay harmonization, as divergent standards threaten to fragment manufacturing strategies and inflate compliance costs for multi-jurisdictional programs.
Market Dynamics
Suspension-based bioreactor platforms are restructuring manufacturing economics by collapsing batch-to-batch variability and enabling single-use scalability that adherent systems cannot match.
Growth Catalysts
- FDA Gene Therapy CMC Guidance:The FDA's Chemistry, Manufacturing, and Controls framework provides clarity on potency assays and lot release criteria, accelerating IND-to-BLA timelines for developers.
- NIH Funding Concentration:Federal research investment in the United States creates a self-reinforcing innovation cluster that attracts vector manufacturing capacity.
- CRISPR-AAV Combinations:Gene editing pipelines advancing through clinical validation are expanding addressable therapeutic targets beyond monogenic disorders.
Market Restraints
- Plasmid DNA Supply Concentration:Critical raw material production clusters in North American and European contract manufacturers, creating single-source vulnerability for GMP-grade plasmids.
- EMA-FDA Potency Assay Divergence:Harmonization gaps between European and American regulators threaten to fragment manufacturing strategies and inflate compliance costs.
- Empty Capsid Contamination:Persistent technical limitation in triple-transfection systems reduces functional titer yields and complicates downstream purification.
Strategic Opportunities
- Japan's PMDA Regenerative Medicine Framework:Accelerated approval pathways for gene therapies create regulatory tailwind for manufacturers establishing Japanese production nodes.
- In Vivo Gene Editing:Emerging application segment combining AAV delivery with base editors and prime editors opens therapeutic categories previously inaccessible to ex vivo approaches.
- Continuous Bioprocessing:Perfusion-based upstream technologies converging with inline analytics enable real-time quality control and reduced facility footprints.
Industry Challenges
- Analytical Development Talent Scarcity:Vector potency assay development requires rare expertise in qPCR, ELISA, and cell-based transduction assays that outpaces academic pipeline output.
- Multi-Product Facility Qualification:Campaign changeover protocols for AAV serotype switching demand extensive cleaning validation and environmental monitoring that compresses facility utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adeno Associated Virus Vector Manufacturing Market |
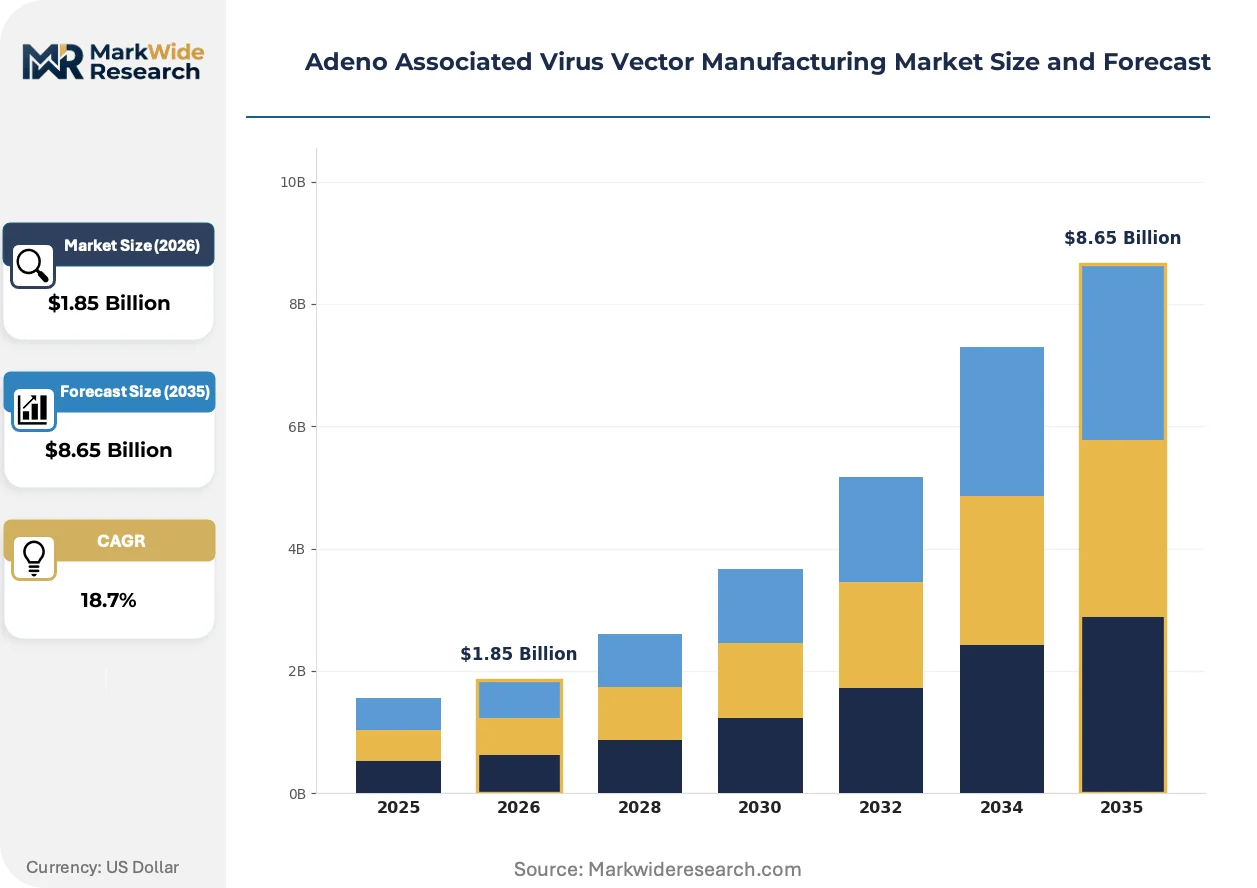
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmid DNA, Viral Vector, Cell Lines, Transduction Reagents Technology: Transfection, Electroporation, Viral Packaging, Chromatin-based Systems End User: Contract Manufacturing Organizations, Biopharmaceutical Companies, Research Institutions, Gene Therapy Developers Application: Gene Therapy, Vaccines, Gene Editing, Regenerative Medicine |
| Companies Covered | Lonza, Catalent, Thermo Fisher Scientific, Oxford Biomedica, WuXi AppTec, FUJIFILM Diosynth Biotechnologies, Charles River Laboratories, MilliporeSigma, REGENXBIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adeno Associated Virus Vector Manufacturing Market Strategic Shifts & Innovations
Digital twins and process analytical technology are compressing development cycles by enabling predictive modeling of critical quality attributes before physical manufacturing campaigns commence.
Artificial intelligence-driven in silico capsid engineering is virtualizing the directed evolution workflow, allowing gene therapy developers to screen billions of variant sequences computationally rather than through iterative wet-lab selection. Large pharmaceutical sponsors and specialized biotechs alike are integrating these platforms into early-stage programs. The structural consequence is a compression of preclinical timelines from years to months for novel tissue-targeting vectors.
EMA's ATMP framework revisions are tightening post-authorization safety monitoring requirements for gene therapies, mandating extended follow-up protocols that extend manufacturing liability windows. European developers are responding by building dedicated pharmacovigilance infrastructure and negotiating risk-sharing arrangements with contract manufacturers. The cell-and-gene therapy segment bears the heaviest compliance burden as these obligations retroactively apply to approved products.
Biopharma procurement departments are consolidating vector supply contracts under multi-year, multi-program master service agreements that lock in capacity and pricing. CDMOs are displacing spot-market transactions with partnership structures that embed analytical development and regulatory support. This pattern is most pronounced in the United States, where gene therapy developers facing clinical trial enrollment pressures prioritize supply security over unit cost minimization.
Adeno Associated Virus Vector Manufacturing Market Segmentation
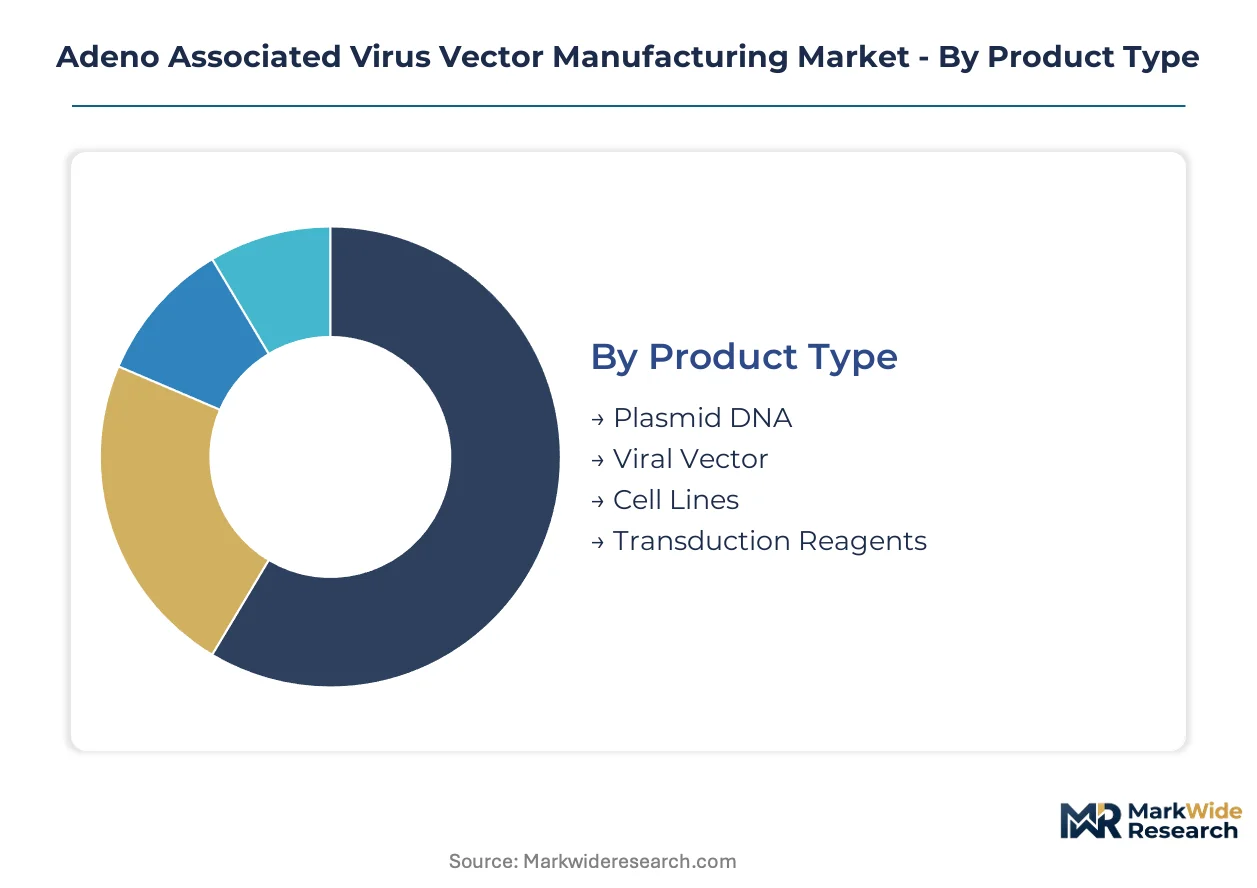
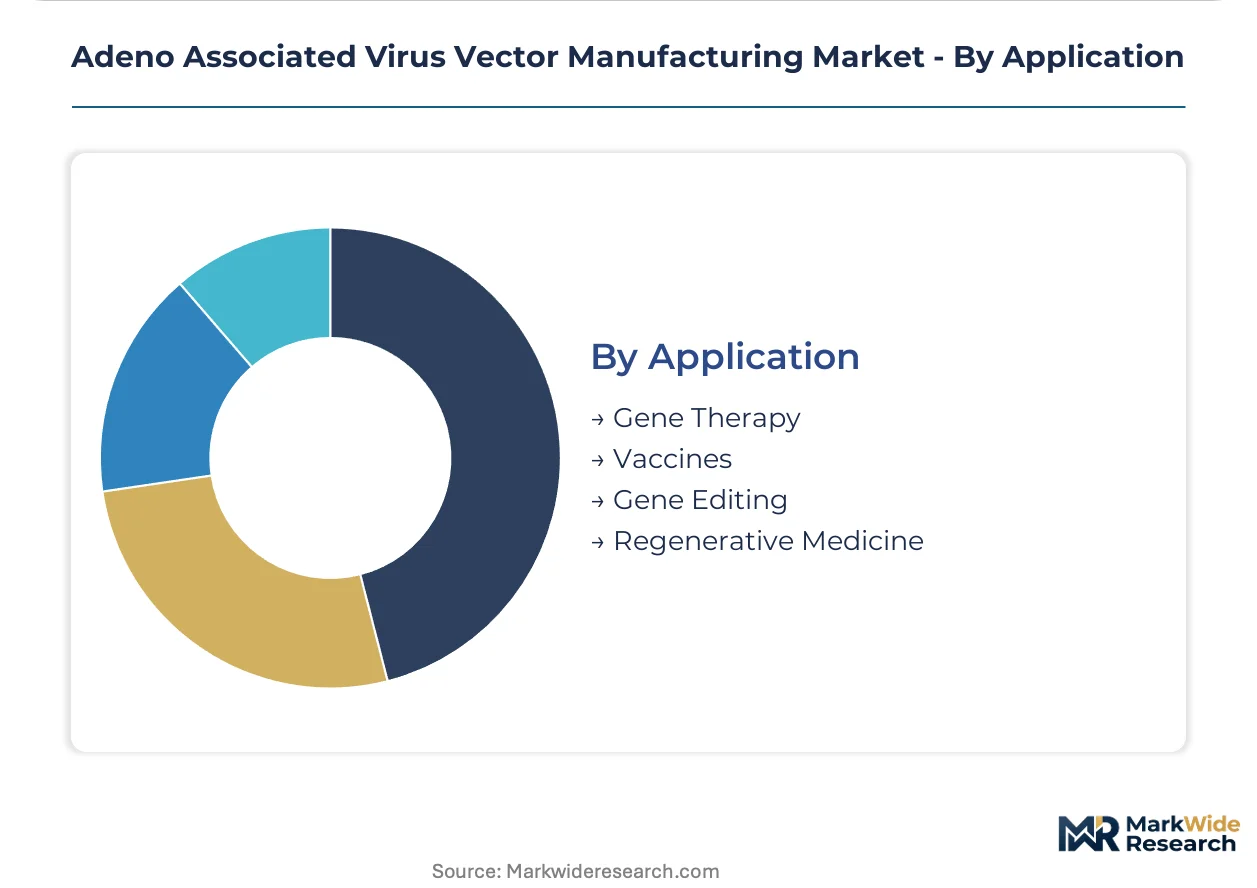
AAV manufacturing segmentation reveals how value pools concentrate across upstream inputs, production technologies, and therapeutic applications. Each dimension carries distinct margin profiles and technical barriers that reshape competitive positioning.
Product Type:
Mature consumables dominate transaction volumes while engineered biological inputs command premium pricing.
- Viral Vector:Recombinant AAV particles constitute the functional therapeutic entity, requiring GMP-grade serotype-specific production with titers reaching 10^14 to 10^16 vector genomes per liter. Gene therapy developers in the United States absorb the majority of current capacity as clinical pipeline maturation accelerates BLA submissions.
- Transduction Reagents:Engineered capsid variants and targeting ligands enable higher-efficiency, lower-immunogenicity delivery. Demand concentrates among developers seeking tissue-specific tropism beyond natural serotype limitations.
- Plasmid DNA:Critical raw material for triple-transfection systems, with GMP-grade production clustering among North American and European contract manufacturers.
- Cell Lines:HEK293 and SF9 suspension-adapted derivatives serve as production hosts, with proprietary variants differentiating CDMO capabilities.
Viral Vector retains volume leadership; Transduction Reagents holds the steepest expansion curve.
Technology:
Cost tier stratification separates legacy adherent platforms from next-generation suspension systems.
- Transfection:Triple-transfection of plasmid DNA into producer cells remains the dominant commercial method, though empty capsid contamination persists as a yield-limiting technical constraint.
- Viral Packaging:Baculovirus-mediated systems in insect cells enable scalable production with reduced batch-to-batch variability, attracting sponsors with late-stage pipeline assets.
- Electroporation:Physical DNA delivery methods show promise for plasmid-free manufacturing, though GMP validation lags behind chemical transfection approaches.
- Chromatin-based Systems:Synthetic promoter and enhancer engineering optimizes transgene expression kinetics, with academic origins limiting immediate commercial penetration.
Transfection maintains installed base dominance; Viral Packaging is climbing the fastest on capacity expansion metrics.
End User:
Customer type determines contract structure, with spot purchasing giving way to multi-year master service agreements.
- Gene Therapy Developers:The fastest-expanding cohort, drawn by clinical pipeline maturation and FDA gene therapy approval precedents. These sponsors prioritize supply security over unit cost minimization.
- Contract Manufacturing Organizations:Integrated plasmid-to-viral-vector service providers compress development timelines through embedded analytical and regulatory support.
- Biopharmaceutical Companies:Large pharmaceutical sponsors consolidate vector supply under multi-program agreements, locking in capacity and pricing across therapeutic portfolios.
- Research Institutions:NIH-funded academic centers generate early-stage vector demand, though GMP translation gaps limit direct commercial relevance.
Gene Therapy Developers are gaining share fastest; Contract Manufacturing Organizations retain margin leadership through vertical service integration.
Application:
Volume concentration in gene therapy contrasts with expansion velocity in emerging modalities.
- Gene Therapy:Monogenic disorder treatments absorb majority manufacturing capacity, with stable non-integrating transgene expression remaining clinically essential for inherited disease indications.
- Gene Editing:CRISPR-AAV combinations advance through clinical validation, opening therapeutic categories previously inaccessible to ex vivo approaches. Base editors and prime editors drive vector demand for in vivo delivery.
- Vaccines:AAV-vectored immunization platforms leverage established manufacturing infrastructure, though commercial prioritization lags behind curative gene therapy applications.
- Regenerative Medicine:Tissue repair applications remain preclinical, with Japan's PMDA accelerated approval pathways creating regulatory tailwind for future manufacturing investment.
Gene Therapy holds current volume primacy; Gene Editing shows the steepest trajectory on pipeline advancement rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports AAV manufacturing services to European and Asian gene therapy developers seeking FDA-aligned quality standards and established GMP infrastructure. German CDMOs supply vector products to Swiss and UK biopharmaceutical sponsors under EMA's ATMP framework. Japanese developers increasingly source manufacturing from domestic facilities to satisfy PMDA's localized production preferences for regenerative medicine products.
United States
FDA gene therapy approvals and NIH funding concentration drive demand from Boston and San Francisco biotech clusters. The FDA's Chemistry, Manufacturing, and Controls framework accelerates IND-to-BLA timelines for domestic sponsors. Massachusetts hosts the densest concentration of vector manufacturing facilities, with Cambridge and Waltham emerging as the primary production nodes for late-stage clinical supply.
Germany
EMA-aligned ATMP manufacturing standards attract cross-border demand from French and Dutch gene therapy developers. The country's national pharmaceutical regulator enforces stringent lot release criteria that satisfy multi-jurisdictional approval requirements. North Rhine-Westphalia anchors the largest European viral vector production cluster, with Cologne and Düsseldorf hosting integrated plasmid-to-vector service operations.
Switzerland
Swissmedic's alignment with EMA standards enables seamless market access for vector products destined across the European Economic Area. Basel's pharmaceutical heritage supports specialized CDMO capabilities in analytical development and regulatory dossier preparation. The Lake Geneva region concentrates contract manufacturing investment from sponsors seeking premium-tier GMP compliance.
Japan
PMDA's regenerative medicine accelerated approval pathways create regulatory tailwind for domestic vector production capacity. METI funding programs support facility construction for in vivo gene editing applications. The Kanto region surrounding Tokyo hosts the primary manufacturing infrastructure, with Yokohama emerging as a hub for AAV supply to Asia-Pacific clinical trials.
United Kingdom
MHRA post-Brexit regulatory autonomy enables differentiated approval pathways for novel AAV serotypes. Oxford and Cambridge academic spinouts generate early-stage vector demand that translates into commercial manufacturing contracts. The Oxford-Cambridge arc concentrates cell-and-gene therapy investment, with Harwell hosting dedicated viral vector production facilities.
Adeno Associated Virus Vector Manufacturing Market Key Industry Players
On the supply side, the industry is consolidating around integrated service providers capable of spanning plasmid supply through fill-finish operations. Three strategic archetypes dominate: global CDMO networks with multi-continent GMP capacity, specialized viral vector boutiques with proprietary platform technologies, and diversified life science conglomerates controlling critical raw material and analytical inputs. Competitive moves center on multi-year master service agreements that lock in sponsor relationships and backward integration into plasmid DNA production to secure supply chains.
Within the global CDMO tier, Lonza exemplifies the multi-continent production network archetype, while Catalent occupies a position emphasizing integrated development-to-commercial services. Thermo Fisher Scientific anchors the diversified conglomerate segment, controlling analytical testing and raw material supply chains that downstream manufacturers require. These three entities represent distinct strategic postures without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| Thermo Fisher Scientific |
| Oxford Biomedica |
| WuXi AppTec |
| FUJIFILM Diosynth Biotechnologies |
| Charles River Laboratories |
| MilliporeSigma |
| REGENXBIO |
| Others |
Cost & Logistics Intelligence
Cold-chain logistics corridors connecting Massachusetts manufacturing clusters to European clinical trial sites impose freight premiums that compound with plasmid DNA supply concentration to widen price spreads between GMP-grade viral vectors and research-use materials. These transportation cost dynamics force sponsors to bundle multi-program orders or absorb tiered pricing penalties on single-batch shipments.
Pricing Analysis
Suspension-based bioreactor platforms command 40-60% premiums over legacy adherent systems due to reduced batch-to-batch variability and higher functional titers. Price differentiation hinges on FDA CMC compliance tier and volume scale, with multi-year master service agreements locking in lower unit costs than spot-market transactions. Cost compression in research-grade vectors is intensifying because HEK293 cell line commoditization erodes proprietary platform rents. Gene therapy developers with BLA-track assets show lowest price sensitivity, prioritizing supply security over per-dose minimization.
Supply Chain Analysis
Lonza, Catalent, and Thermo Fisher Scientific hold dominant positions in contract manufacturing capacity for clinical and commercial-grade AAV production. GMP-grade plasmid DNA production clusters in the United States, Germany, and Switzerland, while HEK293 suspension cell lines draw from North American and European bioreagent suppliers. Single-source vulnerability for GMP plasmids poses structural risk as triple-transfection systems remain tethered to qualified DNA templates. Distribution runs through integrated CDMO networks that bundle analytical testing, regulatory dossier preparation, and fill-finish operations under unified master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of vector potency assay developers with expertise in qPCR, ELISA, and cell-based transduction assays constrains manufacturing scale-up velocity across sponsor pipelines. This talent gap elevates the strategic value of CDMOs with embedded analytical development capabilities.
For Market Incumbents: Build regulatory dossier expertise as a moat by expanding FDA CMC and EMA ATMP submission support services to capture sponsor outsourcing demand. Incumbent CDMOs should add dedicated pharmacovigilance infrastructure to address post-authorization safety monitoring obligations, while securing backward integration into plasmid DNA production to eliminate single-source supply risk from qualified vendor lists. For New Entrants and Emerging Players: Japan's domestic manufacturing capacity underpenetration relative to PMDA's accelerated approval pathway volume creates white-space opportunity for GMP facility investment in the Kanto region. New entrants should target gene editing pipeline sponsors seeking AAV supply for CRISPR-AAV combinations, positioning on rapid analytical development timelines as the primary go-to-market angle against established CDMO incumbents. For Investors and Strategic Acquirers: Boutique viral vector specialists with proprietary HEK293 or SF9 cell line variants represent the highest-conviction acquisition archetype for capability augmentation. Long-term viability in AAV manufacturing rests on regulatory convergence between FDA and EMA potency assay standards, with harmonization gaps threatening to fragment manufacturing strategies. Investors should monitor EMA-FDA joint guidance publication timelines as the critical inflection signal for multi-jurisdictional program economics.| Strategic Initiative | Industry Significance |
|---|---|
| Plasmid DNA Backward Integration | Captive supply of GMP-grade templates eliminates qualified vendor single-source vulnerability for triple-transfection systems. |
| Suspension Bioreactor Capacity Expansion | Single-use scalability reduces batch-to-batch variability and cuts production costs below adherent platform economics. |
| AI-Driven Capsid Engineering Platform | In silico screening compresses preclinical timelines from years to months for novel tissue-targeting vectors. |
| Multi-Product Facility Qualification | Cleaning validation and environmental monitoring protocols enable serotype switching without cross-contamination risk. |
| Japan PMDA Manufacturing Node Establishment | Localized production satisfies regulatory preference for regenerative medicine products under accelerated approval pathways. |
Research Approach
Desk research of FDA gene therapy CMC guidance documents, EMA ATMP framework revisions, ClinicalTrials.gov pipeline databases, and NIH funding disbursement records preceded structured interviews with vector manufacturing executives, regulatory affairs leads at gene therapy sponsors, CDMO procurement directors, and academic technology transfer officers. Primary fieldwork combined with secondary validation through SEC 10-K filings and contract manufacturing agreement announcements enabled bottom-up capacity modeling and top-down demand triangulation across the analysis window.
Forecast assumptions held FDA and EMA regulatory frameworks stable while varying clinical trial advancement rates, suspension bioreactor adoption curves, and gene editing pipeline maturation timelines. The analytical framework segmented volume and value projections across product type, production technology, end-user archetype, and therapeutic application dimensions. CAGRs were derived from installed base growth in suspension platforms, sponsor pipeline progression from IND to BLA, and regional regulatory approval velocity without specifying discrete annual milestones.
Practitioners should monitor EMA-FDA potency assay harmonization progress, plasmid DNA supplier consolidation activity, and CRISPR-AAV clinical readout announcements for early signals of forecast revision triggers. Quarterly review of CDMO master service agreement pricing terms and GMP facility utilization rates is advised to detect inflection in manufacturing capacity tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market