
 Automated and Closed Cell Therapy Processing Systems Market | 2026-2036
Automated and Closed Cell Therapy Processing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated and Closed Cell Therapy Processing Systems Market Intelligence
Specialized distribution channels serving cell therapy manufacturers is reconfiguring as equipment vendors build direct service arms alongside traditional life-science distributors. Thermo Fisher Scientific leverages its integrated supply chain to control reagent-to-instrument bundling across major cell therapy hubs. Lonza anchors European access through its Walkersville and Houston manufacturing sites, where closed-system workflows dominate. Miltenyi Biotec specializes in magnetic cell separation platforms that compete with broader automated processing suites.
Automated and closed cell therapy processing systems integrate sterile fluid management, environmental isolation, and programmable electromechanical control to execute cell expansion, selection, and cryopreservation without operator exposure to open culture conditions. These systems maintain ISO 5-equivalent environments through closed fluid paths and single-use consumables, serving the primary purpose of reducing contamination risk during autologous and allogeneic cell product manufacturing. Cell expansion systems and cryopreservation systems occupy the deepest margin pools within the product type dimension, reflecting high consumables attachment rates and regulatory validation burdens that lock in replacement demand. Oncology commands the largest therapy area share, though immunotherapy applications are gaining fastest as bispecific and TIL therapies advance through clinical pipelines.
The FDA enforces current Good Manufacturing Practice requirements for cell therapy equipment through its Center for Biologics Evaluation and Research, while the EMA's Annex 1 revisions on sterile manufacturing push European facilities toward fully closed processing architectures. ISO 14644 cleanroom standards and the EU's Medical Device Regulation together shape equipment design specifications and market access timelines on both sides of the Atlantic. Stakeholders must monitor how rapidly evolving guidance on point-of-care manufacturing will redefine the boundary between centralized production and distributed processing models.
Market Dynamics
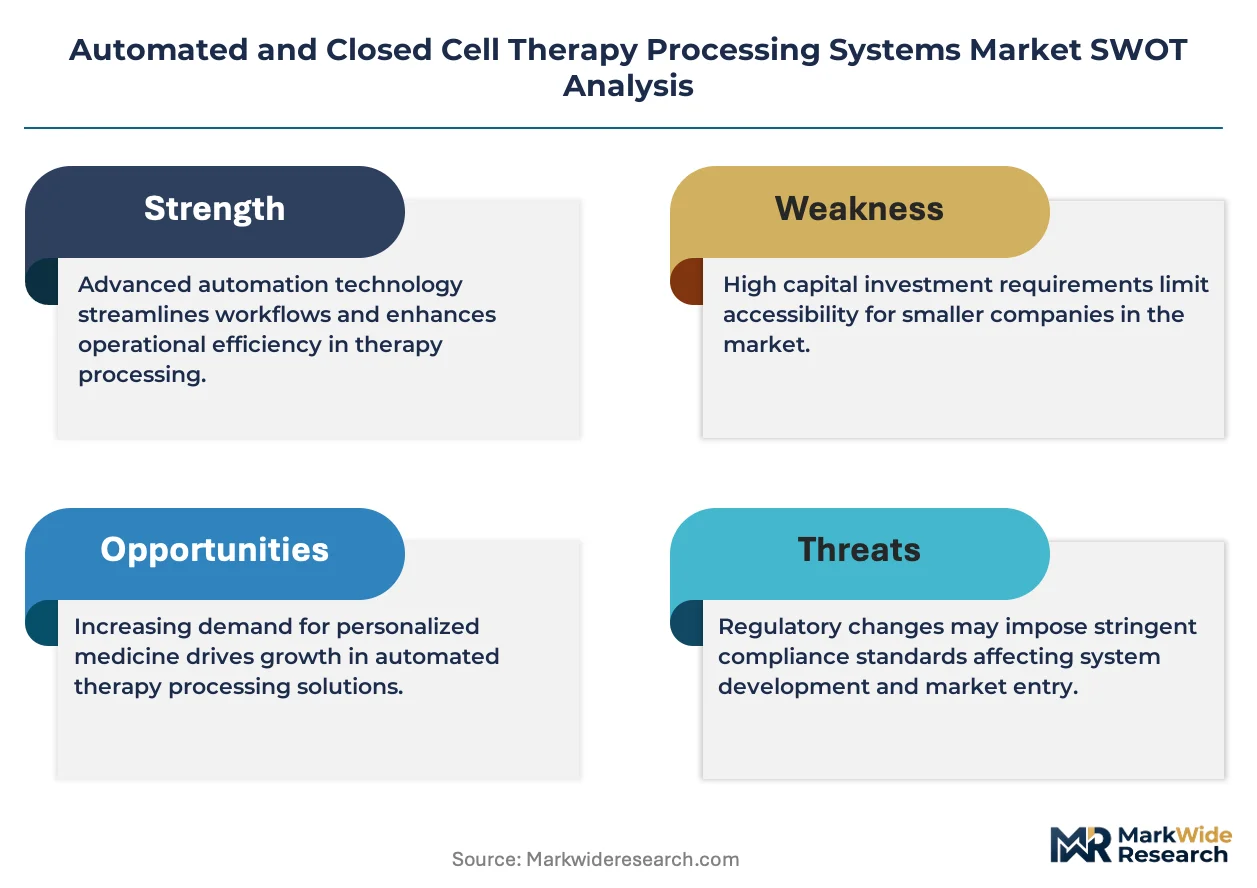
The FDA's evolving guidance on closed-system operations is compressing equipment replacement cycles across academic medical centers and hospital-affiliated cell therapy units, forcing facilities to abandon open-culture workflows before end-of-life depreciation schedules conclude.
Growth Catalysts
- CAR-T Manufacturing Scale-Up:Academic medical centers and hospital-affiliated units are expanding procurement of closed-system bioprocessing equipment to reduce contamination risk during autologous cell therapy production.
- EMA Annex 1 Revisions:The European regulator's sterile manufacturing mandates are pushing European facilities toward fully closed processing architectures, accelerating equipment turnover.
- ISO 14644 Cleanroom Standards:These international specifications shape equipment design requirements, creating compliance-driven replacement demand across certified manufacturing sites.
Market Restraints
- Single-Use Consumables Cost Structure:High attachment rates for proprietary reagents and disposables lock buyers into recurring expenditure streams that strain operational budgets.
- Regulatory Validation Burdens:The FDA's Center for Biologics Evaluation and Research enforces current Good Manufacturing Practice requirements that extend equipment qualification timelines.
- Technical Integration Complexity:Closed-system workflows demand seamless interoperability between cell expansion, selection, and cryopreservation modules that legacy facilities lack.
Strategic Opportunities
- Point-of-Care Manufacturing:Evolving FDA guidance on distributed processing models is redefining the boundary between centralized production and bedside cell therapy preparation.
- Immunotherapy Pipeline Expansion:Bispecific and TIL therapies advancing through clinical pipelines are creating demand for flexible processing platforms beyond traditional oncology applications.
- Magnetic Cell Separation Convergence:Integration of magnetic selection technologies with broader automated processing suites offers pathway to workflow consolidation.
Industry Challenges
- Specialized Technician Scarcity:Operation of programmable electromechanical control systems and sterile fluid management protocols requires cross-trained personnel that cell therapy facilities struggle to recruit.
- Legacy Equipment Obsolescence:Integration of new closed-system architectures with existing cleanroom infrastructure and quality management systems creates deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated and Closed Cell Therapy Processing Systems Market |
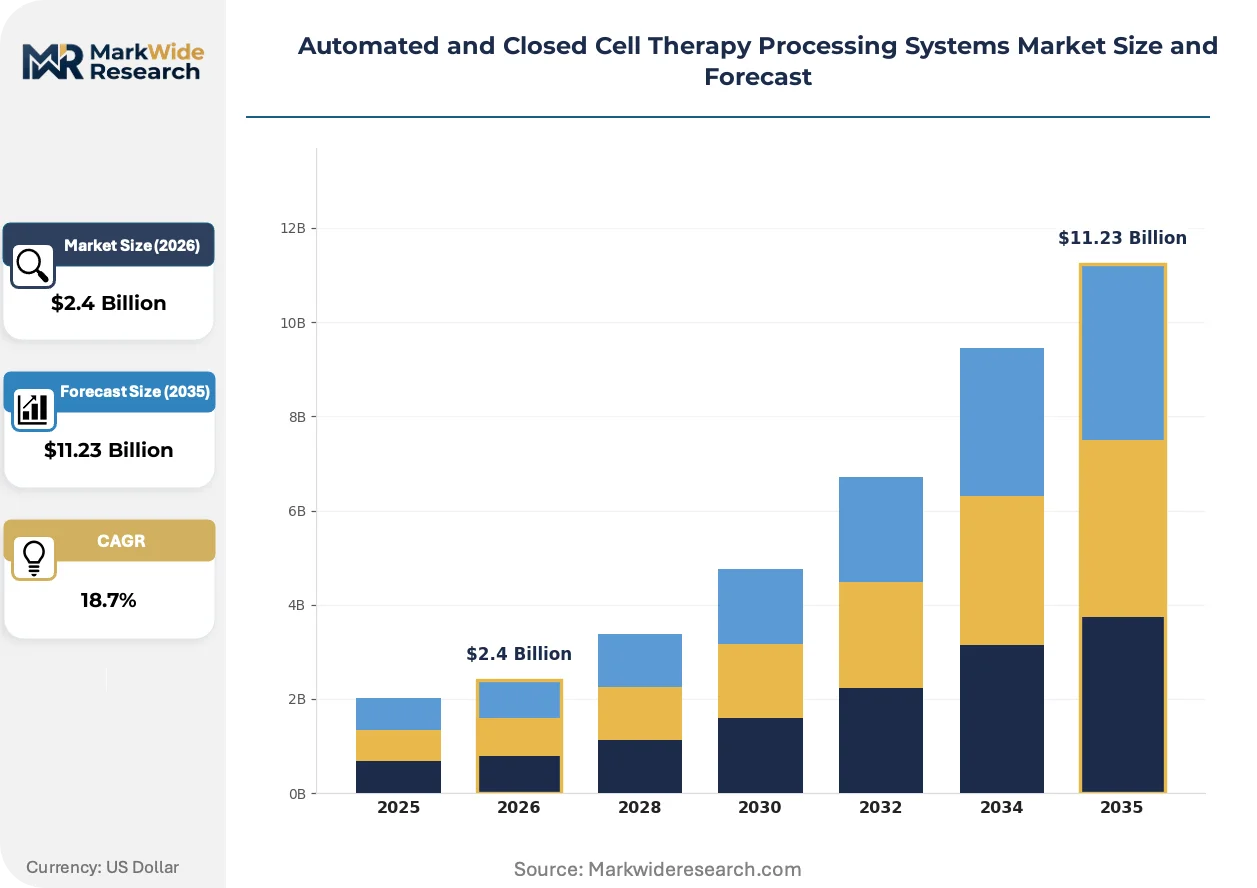
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Expansion Systems, Cell Sorting Systems, Cryopreservation Systems, Bioreactors Therapy Area: Oncology, Genetics, Immunotherapy, Rare Diseases Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intraosseous End User: Hospitals, Research Institutes, Pharmaceutical Companies, Contract Manufacturing Organizations |
| Companies Covered | Thermo Fisher Scientific, Lonza, Miltenyi Biotec, Danaher, Sartorius, Fresenius Kabi, Terumo Corporation, ThermoGenesis Holdings, Cellares, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated and Closed Cell Therapy Processing Systems Market Strategic Shifts & Innovations
Processing architectures are converging around environmental isolation and programmable control systems that eliminate operator exposure to open culture conditions, reshaping how autologous and allogeneic cell products reach commercial scale.
Digital twin technology is virtualizing equipment qualification and process validation workflows. Cell therapy manufacturers are adopting simulation-based approaches to reduce physical testing burdens. This virtualization is compressing time-to-market for new manufacturing lines while maintaining ISO 5-equivalent environmental guarantees.
The EU's Medical Device Regulation together with ISO 14644 standards is mandating more rigorous design documentation and post-market surveillance. European facilities face extended market access timelines as they adapt to combined regulatory frameworks. Cell expansion system vendors are restructuring quality management systems to satisfy dual compliance requirements.
Equipment vendors are building direct service arms alongside traditional life-science distributors. Specialized distribution channels serving cell therapy manufacturers are reconfiguring as suppliers seek tighter control over reagent-to-instrument bundling and field technical support. The United States exhibits this channel shift most visibly, where manufacturing capacity buildouts concentrate demand.
Automated and Closed Cell Therapy Processing Systems Market Segmentation
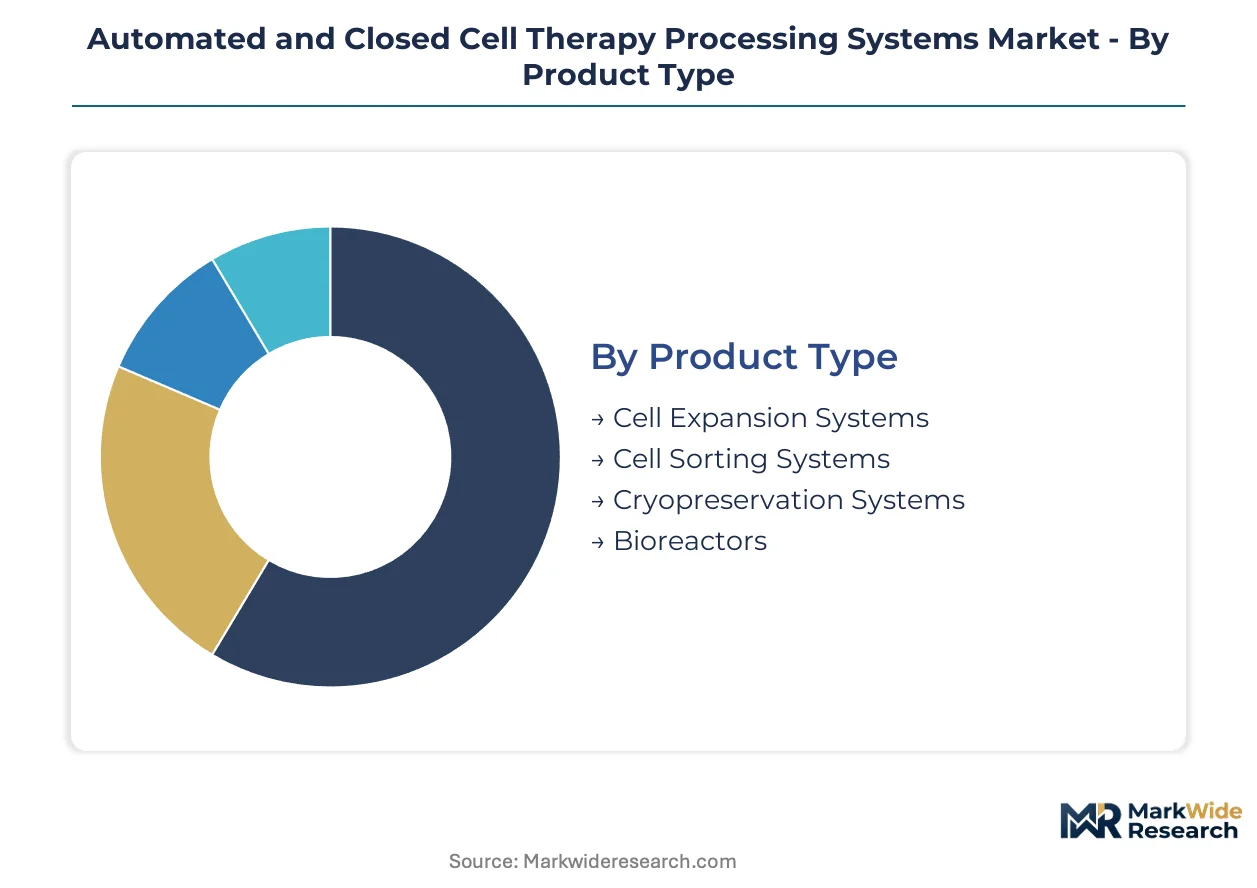
Segmentation in automated and closed cell therapy processing systems reveals how equipment specifications, therapeutic applications, and customer workflows create distinct procurement patterns. Vendors structure service contracts and consumables bundling differently across each dimension, with replacement cycles and validation burdens varying substantially by segment.
Product Type:
After-sales-service intensity varies sharply across product categories, with systems requiring continuous reagent supply and environmental monitoring commanding the most intensive field support footprints.
- Cell Expansion Systems:These platforms integrate sterile fluid management with programmable electromechanical control to execute large-scale cell culture without operator exposure. Demand concentrates at academic medical centers in the United States building CAR-T manufacturing capacity, where FDA guidance on closed-system operations accelerates replacement of open-culture equipment. By volume, Cell Expansion Systems leads. By growth pace, Cryopreservation Systems is ahead.
- Cryopreservation Systems:Automated freezing and storage platforms maintain ISO 5-equivalent environments through closed fluid paths and single-use consumables, locking buyers into high-attachment-rate reagent streams. European facilities responding to EMA Annex 1 revisions on sterile manufacturing are prioritizing these systems to eliminate contamination risk during allogeneic cell product banking.
- Cell Sorting Systems:Magnetic and flow-based selection platforms compete with broader automated processing suites for workflow integration.
- Bioreactors:Scalable culture vessels serve both autologous and allogeneic production lines with varying degrees of environmental isolation.
Margin pools deepen where consumables attachment rates are highest and regulatory validation burdens lock in replacement demand.
Therapy Area:
Application-specific equipment configurations reflect how oncology workflows differ from emerging immunotherapy protocols in throughput requirements and environmental control specifications.
- Oncology:CAR-T and tumor-infiltrating lymphocyte manufacturing dominates current installed base, with hospital-affiliated cell therapy units in the United States representing the primary demand concentration. FDA enforcement of current Good Manufacturing Practice through its Center for Biologics Evaluation and Research shapes equipment qualification timelines for this segment.
- Immunotherapy:Bispecific and TIL therapies advancing through clinical pipelines are creating demand for flexible processing platforms that accommodate smaller batch sizes and faster turnaround times than traditional oncology applications.
- Genetics:Gene therapy manufacturing requires specialized containment and viral vector handling capabilities.
- Rare Diseases:Low-volume, high-complexity production lines prioritize modular equipment configurations.
Oncology maintains the largest revenue share, while Immunotherapy applications are climbing the fastest as clinical pipelines mature.
Delivery Mode:
Route-of-administration requirements influence how processing systems configure final formulation, fill-finish, and container-closure integrity testing modules.
- Intravenous:Dominant delivery route for approved CAR-T products, requiring processing systems that maintain cell viability through cryopreservation and thawing protocols. Demand concentrates at contract manufacturing organizations building capacity to serve multiple sponsor programs.
- Subcutaneous:Emerging route for allogeneic cell therapies is gaining equipment attention as formulation scientists develop stable cell suspensions suitable for injection.
- Intramuscular:Specialized applications in regenerative medicine drive niche equipment configurations.
- Intraosseous:Pediatric and emergency access applications represent limited but technically demanding processing requirements.
Intravenous configurations dominate current procurement, though Subcutaneous-capable systems are gaining share fastest as allogeneic platforms advance.
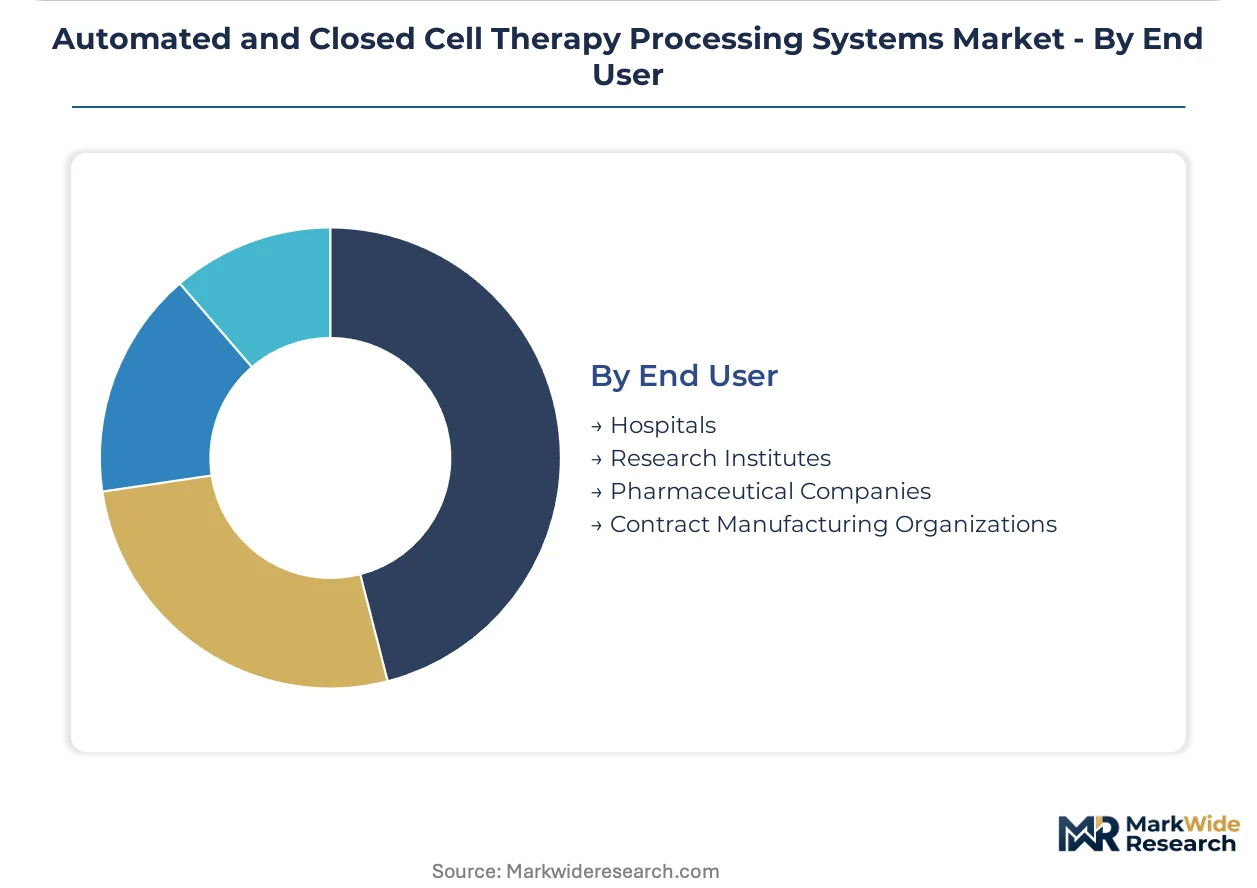
End User:
Customer-type segmentation determines whether equipment vendors emphasize direct service arms or traditional life-science distributor relationships.
- Contract Manufacturing Organizations:Multi-product facilities require the most flexible platform configurations, with equipment vendors building dedicated field technical support teams to manage complex integration projects. FDA's evolving guidance on point-of-care manufacturing is redefining boundaries between centralized CMO production and distributed hospital-based processing.
- Pharmaceutical Companies:Sponsor-owned manufacturing sites prioritize equipment standardization across global networks to simplify technology transfer and regulatory filing consistency.
- Hospitals:Academic medical centers and hospital-affiliated cell therapy units are expanding procurement most visibly in the United States.
- Research Institutes:Early-stage development facilities drive demand for smaller-scale, modular systems with lower capital barriers.
Contract Manufacturing Organizations lead by installed base expansion, while Hospitals are expanding procurement fastest as bedside manufacturing models emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in automated cell therapy processing systems concentrates in the United States, where FDA-validated equipment commands substantial premiums over systems serving emerging manufacturing clusters in India and Southeast Asia.
United States
Academic medical centers in Boston and Houston are expanding CAR-T manufacturing capacity at the fastest pace globally. FDA guidance on closed-system operations through its Center for Biologics Evaluation and Research is compressing equipment replacement cycles before depreciation schedules conclude. The Greater Boston cell therapy cluster hosts the highest density of hospital-affiliated processing units retrofitting open-culture workflows.
Germany
EMA Annex 1 revisions on sterile manufacturing are pushing Frankfurt and Munich facilities toward fully closed processing architectures. German pharmaceutical manufacturers face dual compliance burdens from the EU Medical Device Regulation and ISO 14644 cleanroom standards. The Rhine-Main biotech corridor is consolidating demand for cryopreservation systems with integrated environmental monitoring.
China
NMPA regulatory pathways for cell therapy products are maturing, driving procurement of automated expansion systems in Shanghai and Suzhou manufacturing zones. China's dual carbon goals are influencing equipment energy efficiency specifications in the Yangtze River Delta. Beijing-Tianjin-Hebei biotech parks are importing closed-system architectures originally validated for Western regulatory submissions.
Japan
PMDA accelerated approval pathways for regenerative medicines are stimulating demand for point-of-care processing platforms. METI industrial policy is channeling investment into automated cell sorting systems for allogeneic therapy production. The Kansai region around Osaka hosts specialized CMOs integrating Japanese precision manufacturing standards with global closed-system protocols.
Switzerland
Swissmedic's rigorous device qualification requirements are extending market access timelines for new equipment entrants. Basel's pharmaceutical manufacturing ecosystem is standardizing on closed-system bioreactors that satisfy both European and FDA filing requirements. Swiss facilities are prioritizing equipment vendors with dedicated field service arms over traditional distributor relationships.
Automated and Closed Cell Therapy Processing Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying magnetic separation modules, sterile fluid management consumables, and programmable control interfaces. The vendor base organizes around three archetypes: diversified life-science conglomerates with integrated supply chains, European automation specialists with regulatory validation expertise, and emerging platform developers focused on point-of-care manufacturing. Consolidation pressure is intensifying as equipment vendors build direct service capabilities and reagent-to-instrument bundling locks in recurring revenue streams.
Among diversified platform developers, Thermo Fisher Scientific and Danaher exemplify the integrated supply chain archetype, while Lonza occupies a position bridging European regulatory expertise with North American manufacturing access. These three entities anchor the competitive structure through their control of validation documentation, field technical support networks, and consumables attachment strategies that shape procurement decisions at academic medical centers and contract manufacturing organizations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza |
| Miltenyi Biotec |
| Danaher |
| Sartorius |
| Fresenius Kabi |
| Terumo Corporation |
| ThermoGenesis Holdings |
| Cellares |
| Others |
Cost & Logistics Intelligence
The Rhine-Main freight corridor's escalating logistics costs are compressing margins for European cryopreservation system vendors while amplifying price differentiation between FDA-validated and CE-marked equipment tiers. Supply concentration in German precision manufacturing hubs and Swiss device qualification centers feeds directly into downstream pricing power at academic medical centers.
Pricing Analysis
Configured-to-order pricing for closed-system bioprocessing suites commands substantial premiums over standard catalog configurations. The dominant pricing structure rests on tiered premium-mid-economy differentiation across FDA validation tiers, ISO 14644 certification grades, and after-sales service bundling intensity. Cost compression in standard-tier equipment is intensifying because contract manufacturing organizations are consolidating procurement volumes and demanding volume-scale discounts. Hospital-affiliated cell therapy units exhibit the highest price sensitivity due to constrained capital budgets, while pharmaceutical sponsor-owned sites show the least sensitivity given technology transfer standardization requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for magnetic cell separation module suppliers. Manufacturing concentration centers on Germany, Switzerland, and the United States for precision electromechanical components, while single-use consumables production draws from Chinese polymer processing and Mexican sterile packaging facilities. Single-source vulnerability persists for programmable control interfaces sourced from specialized European automation houses. Distribution runs through direct vendor service arms alongside traditional life-science distributors, with equipment vendors prioritizing field technical support teams for complex integration projects at contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward contract manufacturing organizations as these multi-product facilities consolidate procurement decisions and demand standardized equipment platforms across global networks. This consolidation among downstream buyers is compressing vendor margins and reconfiguring channel relationships.
For Market Incumbents: Insulate installed base positions by deepening captive supply of proprietary single-use consumables and expanding dedicated field service teams in the Greater Boston and Houston manufacturing clusters. The emerging threat of point-of-care platform developers with simplified workflow architectures demands defensive certification investments in FDA Master Files and EU Medical Device Regulation technical documentation. Backward integration into sterile fluid management consumables production represents the critical lever for locking in replacement revenue streams.
For New Entrants and Emerging Players: Mid-scale hospital-affiliated cell therapy units in the Asia-Pacific region represent the most penetrable entry point for automated expansion systems with modular, lower-capital configurations. Research institutes advancing bispecific and TIL therapies through early clinical pipelines offer a second white-space target for flexible processing platforms accommodating smaller batch sizes. A go-to-market angle anchored in digital twin-enabled virtual qualification workflows can compress deployment timelines and differentiate against incumbent validation burdens.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life-science conglomerates seeking to divest non-core cell therapy equipment divisions amid portfolio rationalization pressures. Long-term viability over the coming decade hinges on regulatory validation documentation depth and consumables attachment rate sustainability. The signal to watch as an inflection indicator is FDA guidance evolution on point-of-care manufacturing boundaries, which would redistribute value between centralized and distributed processing architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Pathway Investment | EMA Annex 1 and FDA CBER dual compliance documentation accelerates market access timelines for European and North American facilities. |
| Consumables Bundling Strategy | Proprietary reagent-to-instrument attachment rates lock in recurring revenue and raise switching costs at academic medical centers. |
| Direct Service Arm Expansion | Dedicated field technical support teams control integration quality and capture service margin pools alongside equipment sales. |
| Point-of-Care Platform Development | Distributed processing architectures aligned with evolving FDA guidance on bedside manufacturing redefine competitive boundaries. |
| Digital Twin Integration | Virtual equipment qualification workflows compress physical testing burdens and accelerate time-to-market for new manufacturing lines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, EMA device registration databases, ISO 14644 certification records, and hospital procurement contract disclosures. Interviews with cell therapy manufacturing directors, regulatory affairs leads at equipment vendors, biomedical engineers at academic medical centers, and GPO contracts managers inform demand-side validation. Secondary sources include SEC 10-K equipment revenue disclosures, clinical trial registry entries for CAR-T and TIL therapies, and customs trade data for bioprocessing instrument imports. Bottom-up equipment unit forecasting triangulates against top-down market size estimates derived from consumables throughput analysis.
Forecast inputs span cell expansion system capacity utilization rates, cryopreservation consumables attachment velocities, and replacement cycle compression driven by regulatory guidance evolution. Segmentation dimensions modeled include product type, therapy area, delivery mode, and end user category across the projection horizon. CAGRs derive from fitted growth curves anchored to historical procurement patterns and regulatory milestone timelines. Industry-specific forecast inputs incorporate FDA CBER enforcement activity levels and EMA Annex 1 implementation pace across European manufacturing sites.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at pharmaceutical companies, healthcare reimbursement policy shifts, and trade tariff trajectories would shift the trajectory of equipment procurement demand. Forecasts reflect documented assumptions regarding regulatory guidance stability and cleanroom construction pipeline visibility. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Systems Market