
 Middle East and Africa Stem Cell Therapy Market | 2026-2036
Middle East and Africa Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Stem Cell Therapy Market Foresight
Saudi Arabia is narrowing the gap between research capacity and clinical translation through new GMP-compliant cell processing facilities in Riyadh and Jeddah. Lonza Group AG anchors regional supply chains with specialized cell culture media manufacturing. STEMCELL Technologies competes through educational partnerships with African research institutes. Thermo Fisher Scientific Inc extends its footprint via distribution agreements covering Gulf Cooperation Council states.
Stem cell therapy encompasses the administration of undifferentiated or partially differentiated cells capable of self-renewal and tissue-specific differentiation, typically requiring cryopreservation at minus 150 degrees Celsius and viability thresholds exceeding 70 percent post-thaw, to restore or replace damaged tissues in therapeutic interventions. Mesenchymal stem cells dominate current revenue pools due to broader regulatory acceptance and simpler isolation protocols from adipose tissue and bone marrow. Autoimmune diseases represent the fastest-expanding treatment indication as lupus and multiple sclerosis protocols advance through Phase II trials across Israeli and South African sites. Intravenous injection maintains volume leadership while local administration commands premium positioning in orthopedic and dermatological applications.
Saudi FDA protocols, South African Health Products Regulatory Authority guidelines, and Israel's Ministry of Health cell therapy frameworks collectively determine market access timelines and manufacturing quality benchmarks across the region. The UAE's personalized medicine mandate under its National Genome Strategy further tightens documentation requirements for imported cell lines. Stakeholders must weigh regulatory reciprocity agreements against the cost of establishing standalone GMP facilities in each target jurisdiction.
Market Dynamics
The convergence of GMP facility investments and streamlined advanced therapy licensing across Gulf Cooperation Council states is compressing the research-to-clinic timeline for autologous cell therapies. Saudi Arabia's dual-track regulatory pathway now permits parallel manufacturing qualification and clinical trial enrollment.
Growth Catalysts
- Saudi FDA Trial Protocols:The Saudi Food and Drug Authority's regenerative medicine framework has approved multiple investigator-initiated studies for orthopedic and cardiovascular applications, accelerating patient access timelines.
- Adipose-Derived MSC Isolation:Simplified extraction protocols from lipoaspirate tissue are reducing processing costs and expanding treatable patient populations beyond bone marrow sourcing.
- South Africa:Tertiary hospital oncology departments in Johannesburg and Cape Town are scaling autologous transplant capacity to address hematological malignancy backlogs.
Market Restraints
- Cryopreservation Supply Concentration:Liquid nitrogen logistics and vapor-phase storage infrastructure concentrate in UAE and Saudi Arabia, leaving Sub-Saharan African sites dependent on air-freight cold chain with 48-hour viability windows.
- SFDA Manufacturing Audits:Saudi Arabia's mandatory GMP facility inspections for imported cell lines add 9-14 months to foreign product registration timelines.
- Allogeneic Cell Banking:HLA-matched donor registries remain underdeveloped across the region, limiting allogeneic transplant scalability compared to autologous alternatives.
Strategic Opportunities
- Nigeria and Kenya:Private hospital networks in Lagos and Nairobi are piloting cord blood banking services for pediatric hematology, creating first-mover positioning in East and West African markets.
- UAE National Genome Strategy:The personalized medicine mandate requires cell therapy documentation to include donor genetic profiles, creating demand for integrated bioinformatics and cell processing services.
- 3D Bioprinting Convergence:Scaffold-integrated MSC delivery systems are advancing through Dubai-based research partnerships, combining cell therapy with orthopedic implant manufacturing.
Industry Challenges
- Cell Processing Technicians:GMP-compliant cleanroom operations require certified aseptic handling specialists, with training programs currently limited to South Africa and Israel.
- Quality Control Assay Standardization:Potency testing for mesenchymal stem cell products lacks harmonized protocols across SFDA, SAHPRA, and Israel's Ministry of Health, forcing duplicate validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Stem Cell Therapy Market |
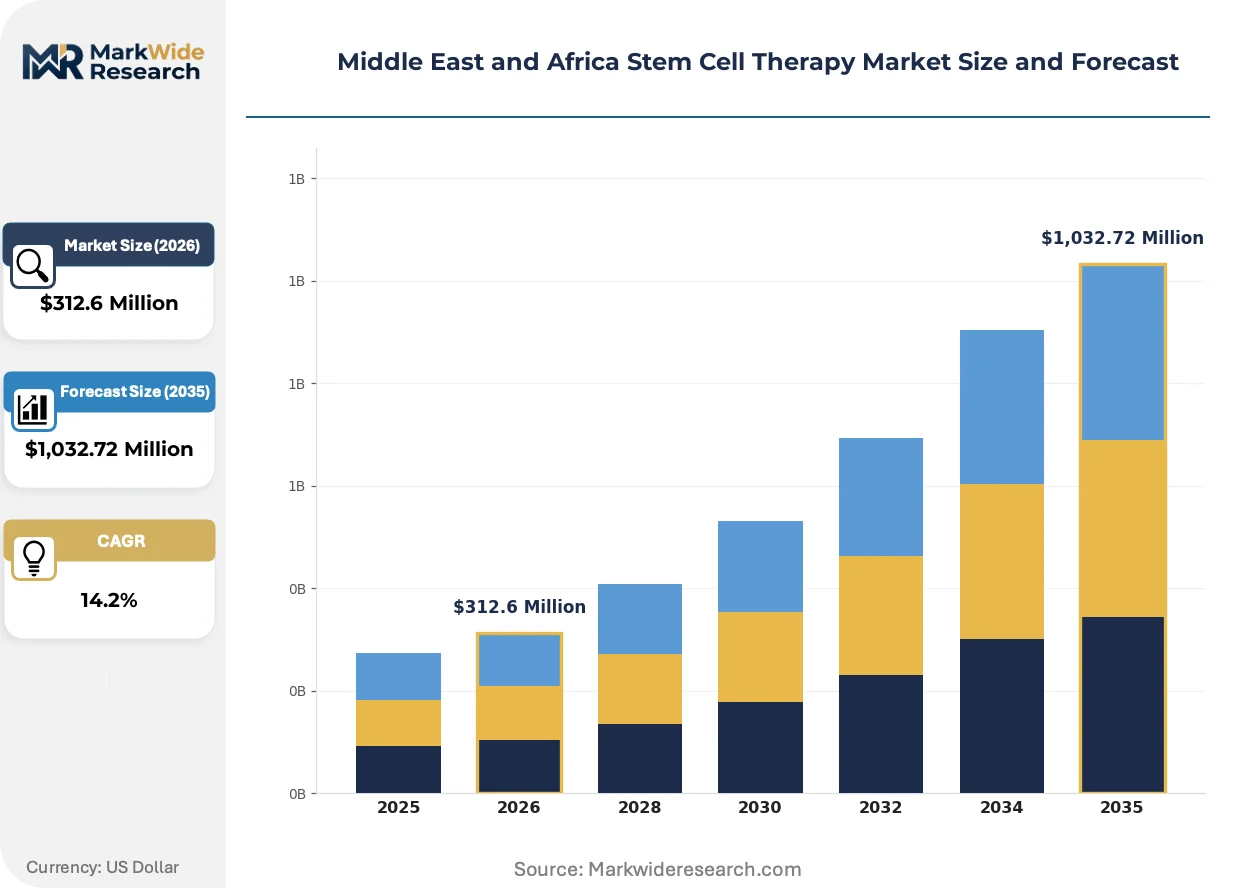
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,032.72 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematopoietic Stem Cells, Mesenchymal Stem Cells, Neural Stem Cells, Epithelial Stem Cells Treatment Indication: Cardiovascular Diseases, Neurodegenerative Disorders, Autoimmune Diseases, Orthopedic Injuries Delivery Method: Intravenous Injection, Bone Marrow Aspiration, Intramuscular Injection, Local Administration End User: Hospitals, Research Institutes, Specialty Clinics, Pharmaceutical Companies |
| Companies Covered | TiGenix NV, STEMCELL Technologies, Lonza Group AG, Merck KGaA, Takara Bio Inc, Pluri Inc, Thermo Fisher Scientific Inc, Charles River Laboratories International Inc, Smith & Nephew Plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Stem Cell Therapy Market Shifts & Advancements
Cell therapy logistics and patient matching systems are undergoing platform-level transformation across the Middle East and Africa. Three developments are compressing treatment timelines and reshaping competitive positioning.
Blockchain-enabled chain-of-custody systems are digitizing cryogenic sample tracking from collection through infusion. South African blood services and UAE hospital networks are piloting distributed ledger verification for cross-border cell shipments. This is digitizing regulatory audit trails and reducing documentation disputes between manufacturing sites and clinical endpoints.
Saudi Arabia's advanced therapy medicinal products framework now mandates real-time adverse event reporting to the Saudi FDA within 24 hours of serious incidents. Manufacturers must deploy pharmacovigilance infrastructure that integrates with national health data exchanges. Hematology-oncology centers are responding by embedding clinical data managers within transplant units rather than relying on centralized hospital IT.
Hospital procurement departments are consolidating cell therapy sourcing through single preferred vendor agreements rather than maintaining multiple supplier relationships. This consolidation concentrates volume with manufacturers offering integrated cryopreservation logistics and on-site technical training. The shift is most visible in Saudi Arabia's Ministry of Health hospital clusters, where three-year framework contracts now dominate mesenchymal stem cell acquisitions.
Middle East and Africa Stem Cell Therapy Market Segmentation
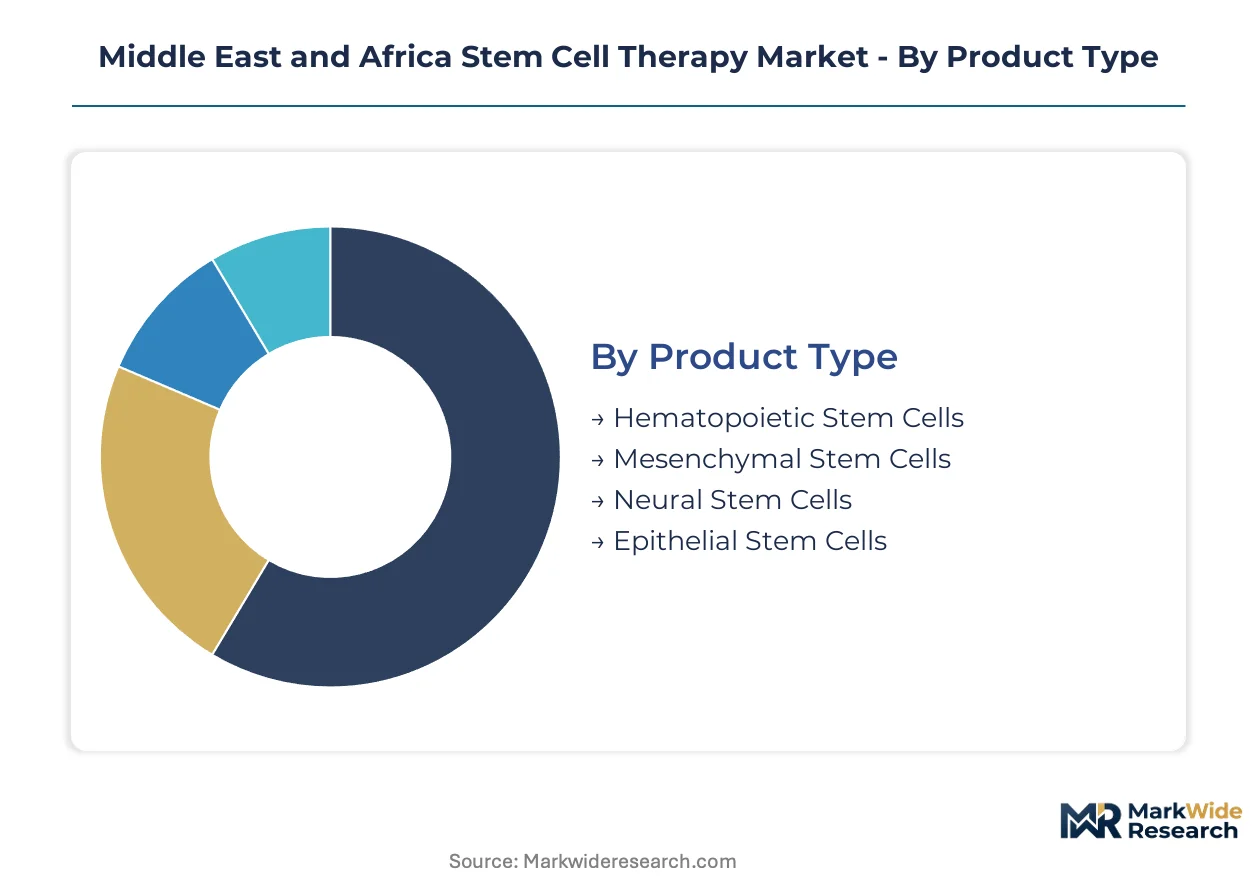
Cell therapy segmentation in the Middle East and Africa reflects divergent technical requirements across hematopoietic and mesenchymal platforms, with each product category demanding distinct cold chain infrastructure and regulatory documentation. Treatment indication and delivery method choices directly determine reimbursement pathways and facility investment profiles across Saudi Arabia, South Africa, and the UAE.
Product Type:
After-sales service intensity varies sharply across cell types, with hematopoietic products requiring continuous donor registry coordination and long-term engraftment monitoring.
- Mesenchymal Stem Cells:Isolated from adipose tissue and bone marrow with simpler expansion protocols than pluripotent alternatives. Demand concentrates in Saudi Arabia's orthopedic and regenerative medicine clinics where SFDA-approved protocols for cartilage repair and wound healing are expanding treatable populations. Adipose-derived sourcing reduces processing costs and shortens patient preparation timelines.
- Hematopoietic Stem Cells:CD34+ progenitor cells requiring HLA-matched donor registries and myeloablative conditioning protocols. South Africa's tertiary hospital networks in Johannesburg and Cape Town are scaling autologous transplant capacity to address hematological malignancy backlogs, driving infrastructure investment in cryopreservation and apheresis units.
- Neural Stem Cells:Multipotent cells capable of neuronal and glial differentiation, currently restricted to early-phase trials for Parkinson's and spinal cord injury protocols.
- Epithelial Stem Cells:Skin and corneal progenitors with established burn treatment applications, limited by specialized culture requirements and narrow therapeutic windows.
Mesenchymal Stem Cells hold the largest share; momentum sits with Hematopoietic Stem Cells as transplant infrastructure expands.
Treatment Indication:
Cost tier differentiation separates high-complexity oncology protocols from outpatient orthopedic applications, with reimbursement rates varying by therapeutic category.
- Autoimmune Diseases:Lupus and multiple sclerosis protocols are advancing through Phase II trials across Israeli and South African sites, with intravenous mesenchymal stem cell infusions showing promise for disease modification. Clinical investigators are prioritizing biomarker-defined responder populations to accelerate regulatory submissions.
- Orthopedic Injuries:Local administration of adipose-derived MSCs for cartilage defects and tendon repair commands premium positioning in UAE and Saudi private hospital networks. Dubai-based research partnerships are advancing scaffold-integrated delivery systems combining cell therapy with implant manufacturing.
- Cardiovascular Diseases:Ischemic heart failure and peripheral artery applications require specialized catheterization infrastructure, limiting adoption to tertiary cardiac centers.
- Neurodegenerative Disorders:Parkinson's and ALS protocols remain experimental with restricted patient access due to blood-brain barrier delivery challenges and extended safety monitoring requirements.
Orthopedic Injuries commands current revenue concentration; Autoimmune Diseases are climbing the fastest as immunomodulatory mechanisms gain clinical validation.
Delivery Method:
Volume concentration favors intravenous administration, while margin structures reward localized delivery requiring specialized interventional infrastructure.
- Intravenous Injection:Systemic MSC distribution for immunomodulatory and regenerative applications, dominating treatment volumes across hematology-oncology departments. Standardized infusion protocols reduce technical training requirements and enable broader facility adoption.
- Local Administration:Direct injection into joints, cardiac tissue, or dermal layers for orthopedic and dermatological applications, commanding premium pricing in Saudi and UAE private clinics. Requires imaging guidance and specialized interventional suites.
- Bone Marrow Aspiration:Harvest procedure for autologous hematopoietic stem cell collection, concentrated in South African transplant centers addressing lymphoma and myeloma backlogs.
- Intramuscular Injection:Peripheral administration for muscular dystrophy and ischemic limb protocols, limited by uneven cell distribution and variable retention rates.
Intravenous Injection maintains volume leadership; Local Administration is gaining share fastest through premium positioning in Gulf private healthcare markets.
End User:
Customer type determines procurement scale and technical support requirements, with hospital networks consolidating vendor relationships through multi-year framework agreements.
- Hospitals:Tertiary medical centers in Riyadh, Jeddah, Johannesburg, and Dubai anchor regional demand, with Saudi Ministry of Health clusters implementing three-year preferred vendor contracts for mesenchymal stem cell sourcing. Embedded clinical data managers are replacing centralized hospital IT for pharmacovigilance compliance.
- Research Institutes:University medical centers and dedicated cell therapy facilities drive protocol development and early-phase trials, requiring GMP-compliant cell processing partnerships and specialized training programs.
- Specialty Clinics:Orthopedic and aesthetic medicine practices in UAE and Saudi Arabia offer outpatient MSC therapies, dependent on third-party cell processing laboratories.
- Pharmaceutical Companies:Sponsors of multi-center trials across the region, navigating divergent SFDA, SAHPRA, and Israel Ministry of Health quality control requirements.
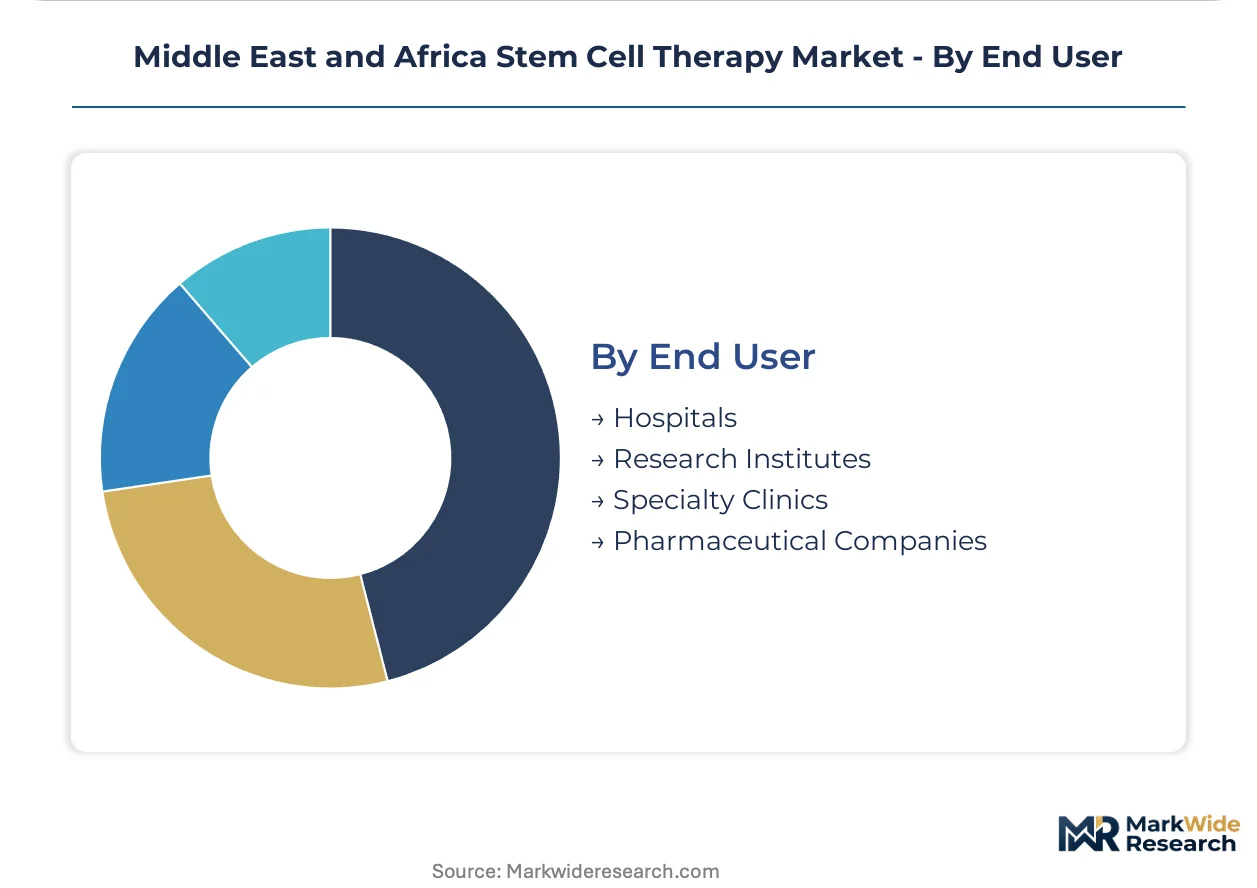
Hospitals hold the largest share; momentum sits with Research Institutes as GMP facility investments accelerate clinical translation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi Food and Drug Authority anchors the Middle East and Africa stem cell therapy landscape through its regenerative medicine framework, while regulatory divergence across the Gulf Cooperation Council and Sub-Saharan Africa fragments market access timelines.
Saudi Arabia
Riyadh and Jeddah host GMP-compliant cell processing facilities that compress research-to-clinic timelines for autologous therapies. The Saudi FDA's dual-track regulatory pathway permits parallel manufacturing qualification and clinical trial enrollment, accelerating orthopedic and cardiovascular protocol approvals. Ministry of Health hospital clusters in Riyadh consolidate mesenchymal stem cell procurement through three-year framework contracts.
United Arab Emirates
Dubai's private hospital networks drive demand for premium-positioned local administration therapies in orthopedic and aesthetic applications. The Ministry of Health and Prevention's advanced therapy medicinal products framework streamlines cell therapy licensing while mandating real-time adverse event reporting within 24 hours. Dubai-based research partnerships advance scaffold-integrated MSC delivery systems combining cell therapy with implant manufacturing.
South Africa
Johannesburg and Cape Town tertiary hospitals scale autologous transplant capacity to address hematological malignancy backlogs, anchoring regional hematopoietic stem cell demand. The South African Health Products Regulatory Authority guidelines determine manufacturing quality benchmarks alongside Israel's Ministry of Health frameworks. Oncology departments embed clinical data managers within transplant units to meet pharmacovigilance requirements.
Israel
Tel Aviv and Jerusalem research institutes drive Phase II autoimmune disease trials for lupus and multiple sclerosis protocols using intravenous mesenchymal stem cell infusions. The Ministry of Health cell therapy framework establishes quality control standards that influence regional harmonization efforts. Clinical investigators prioritize biomarker-defined responder populations to accelerate regulatory submissions.
Nigeria
Lagos private hospital networks pilot cord blood banking services for pediatric hematology, creating first-mover positioning in West African markets. The country's national pharmaceutical regulator develops oversight capacity for emerging cell therapy applications. Healthcare infrastructure gaps concentrate demand in Lagos and Abuja urban corridors while cold chain limitations constrain expansion.
Middle East and Africa Stem Cell Therapy Market Competitive Landscape
Integrated supply chain specialists and research-focused technology providers split the market between infrastructure-heavy and knowledge-intensive positioning. The vendor base concentrates around three strategic archetypes: multinational life sciences conglomerates with regional distribution networks, specialized cell culture media and reagent manufacturers, and contract research organizations with GMP facility partnerships. Competitive moves center on distribution agreement expansion across Gulf Cooperation Council states and educational partnerships with African research institutes.
Within the multinational tier, Thermo Fisher Scientific Inc and Lonza Group AG exemplify divergent strategic positioning. Thermo Fisher extends regional footprint through distribution agreements covering Gulf Cooperation Council states, while Lonza anchors supply chains with specialized cell culture media manufacturing. STEMCELL Technologies occupies a research-focused position, competing through educational partnerships with African research institutes. These three entities collectively represent the spectrum from infrastructure-scale supply to knowledge-transfer positioning across the Middle East and Africa.
| Leading Market Players |
|---|
| TiGenix NV |
| STEMCELL Technologies |
| Lonza Group AG |
| Merck KGaA |
| Takara Bio Inc |
| Pluri Inc |
| Thermo Fisher Scientific Inc |
| Charles River Laboratories International Inc |
| Smith & Nephew Plc |
| Others |
Supply & Pricing Matrix
Liquid nitrogen logistics and vapor-phase storage infrastructure concentrate in the UAE and Saudi Arabia, anchoring margin pools with cryopreservation service providers and GMP facility operators while Sub-Saharan African sites absorb freight premiums for air-cold chain with compressed viability windows.
Pricing Analysis
Intravenous MSC infusions in Johannesburg and Cape Town command 40-60 percent discounts versus local administration therapies in Dubai's private orthopedic clinics. Price differentiation rests on GMP certification tier and integrated cryopreservation logistics bundling. Cost compression in hematopoietic stem cell processing is intensifying as South African tertiary hospitals consolidate procurement through multi-year framework contracts. Research institutes exhibit highest price sensitivity; Gulf private hospital networks show lowest sensitivity due to premium positioning mandates.
Supply Chain Analysis
Extended payment terms from Saudi Ministry of Health clusters are forcing working capital adjustments among cell culture media suppliers serving Riyadh and Jeddah facilities. Manufacturing inputs draw from Switzerland for specialized bioreactors, the United States for analytical instrumentation, and Singapore for cryogenic shipping containers. Single-source vulnerability concentrates in liquid nitrogen distribution networks spanning the Gulf Cooperation Council. Distribution runs through hospital procurement departments consolidating vendor relationships rather than maintaining multiple supplier contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Saudi Arabia's Ministry of Health hospital clusters implementing three-year preferred vendor agreements, shifting negotiation leverage toward institutional procurement departments and away from fragmented specialty clinic buyers.
For Market Incumbents: Entrench position through captive GMP facility investments in Riyadh and Jeddah to preempt SFDA manufacturing audit delays, while embedding clinical data managers within transplant units to meet 24-hour adverse event reporting mandates. Threat substitution from 3D bioprinting scaffold-integrated delivery systems demands accelerated orthopedic protocol partnerships. For New Entrants and Emerging Players: Build out cord blood banking infrastructure in Lagos and Nairobi where private hospital networks are piloting pediatric hematology services with minimal incumbent presence. Nigeria and Kenya represent the most penetrable geographies. Go-to-market angle: partner with established cold chain logistics providers to overcome 48-hour viability constraints. For Investors and Strategic Acquirers: Capital is best deployed toward integrated bioinformatics and cell processing service providers positioned to capture UAE National Genome Strategy documentation requirements. Long-term viability favors entities with dual GMP-SFDA and GMP-SAHPRA qualification capacity. Signal to watch: harmonization of potency testing protocols across Saudi, South African, and Israeli regulatory frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Expansion | Riyadh and Jeddah sites compress research-to-clinic timelines under SFDA dual-track pathways. |
| Cord Blood Banking Pilot | Lagos and Nairobi networks create first-mover positioning in underserved West and East African markets. |
| Blockchain Chain-of-Custody | South African blood services digitize cryogenic sample tracking for cross-border regulatory audit trails. |
| Educational Partnership | STEMCELL Technologies' African research institute collaborations transfer GMP cleanroom certification capacity. |
| Scaffold-Integrated Delivery | Dubai-based research partnerships combine MSC therapy with orthopedic implant manufacturing convergence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cell processing technicians, GMP facility quality managers, hospital procurement directors, and SFDA regulatory affairs specialists. Secondary validation drew from ClinicalTrials.gov stem cell protocol registrations, Saudi FDA advanced therapy guidance documents, SAHPRA manufacturing guidelines, and South African tertiary hospital procurement databases. Bottom-up demand modeling and top-down market sizing were triangulated to ensure consistency across segments.
Calibration against historical GMP facility investment cycles and clinical trial enrollment rates anchored volume projections across the analysis window. Segmentation dimensions modeled include cell type, treatment indication, delivery method, and end-user category with regulatory cluster overlays. CAGRs were derived from regression analysis of facility capacity expansion timelines and protocol approval trajectories. Key inputs incorporated SFDA dual-track pathway adoption rates and cryopreservation infrastructure deployment schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by contract research organizations with integrated GMP partnerships would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market