
 RNA Therapy Clinical Trials Market | 2026-2036
RNA Therapy Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
RNA Therapy Clinical Trials Market Analytics
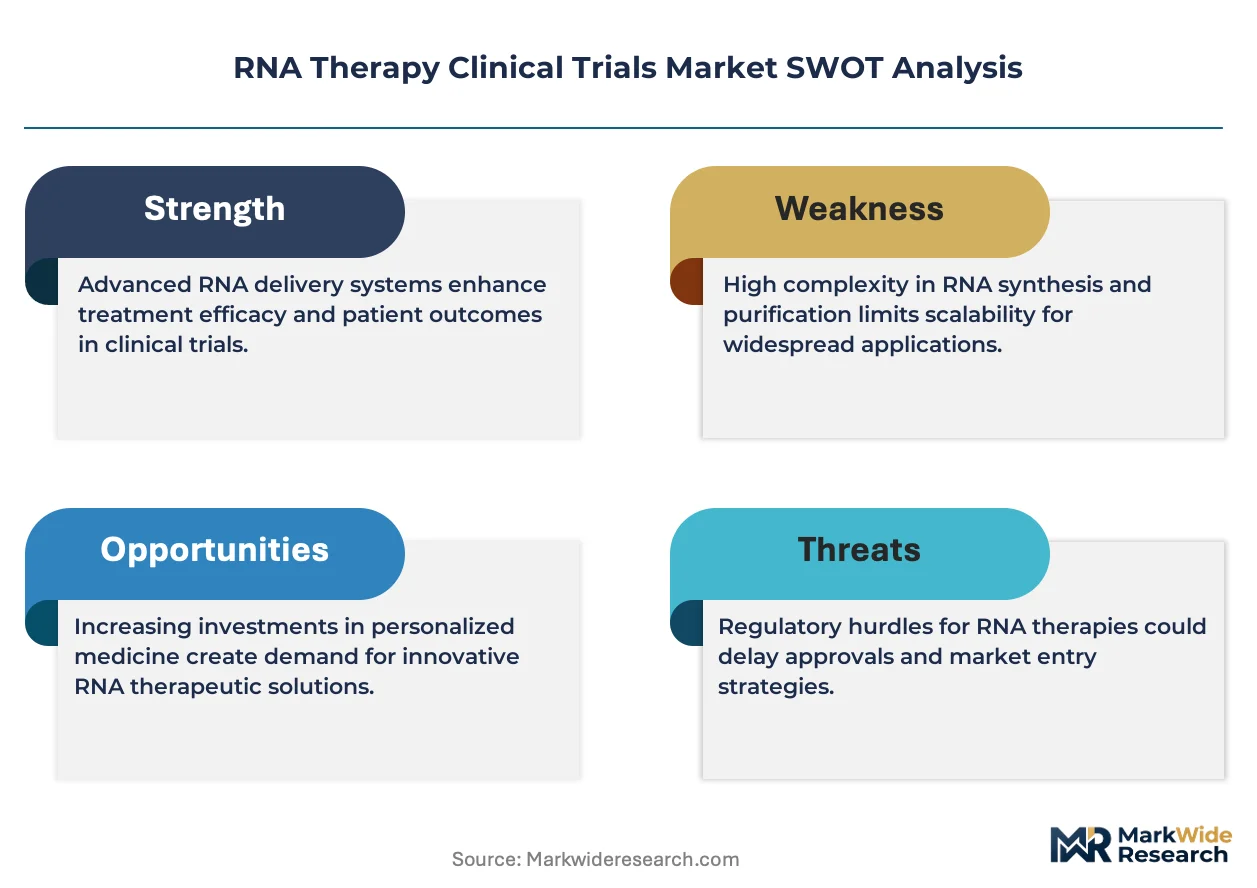
Modular trial service bundling is hardening as the dominant procurement pattern among RNA therapy sponsors. IQVIA leverages its integrated data and site network to anchor large-scale mRNA vaccine studies across multiple continents. Charles River Laboratories International, Inc. specializes in preclinical RNA safety assessment, sustaining its position as a mandatory upstream gatekeeper before human dosing begins. PAREXEL International Corp. competes on adaptive trial design expertise, differentiating its offerings for sponsors pursuing expedited regulatory pathways.
RNA therapy clinical trials constitute the structured evaluation of nucleic acid-based therapeutics—messenger RNA, small interfering RNA, microRNA, and RNA interference constructs—administered to human subjects to establish safety, efficacy, and optimal dosing parameters, typically requiring cold-chain logistics for lipid nanoparticle stability and precise dosing cohorts due to immunogenicity concerns. The primary purpose is to generate regulatory-grade evidence for conditional or full approval of therapies targeting previously undruggable genetic and infectious disease mechanisms. Oncology applications dominate current pipeline value, with siRNA and RNAi modalities commanding premium trial complexity fees due to chronic dosing protocols and specialized biomarker monitoring requirements. mRNA trials for infectious diseases represent the fastest-expanding segment, though margin pools remain thinner due to competitive commoditization of COVID-19-era platform validation.
FDA breakthrough therapy designation and EMA PRIME eligibility reshape trial economics by enabling rolling reviews and compressed phase transitions for RNA candidates meeting unmet need criteria. ISO 14155 and ICH-GCP standards govern clinical conduct, while FDA's Chemistry, Manufacturing, and Controls guidance for lipid nanoparticle formulations imposes escalating quality benchmarks that filter out undercapitalized sponsors. Stakeholders must monitor evolving FDA guidance on long-term follow-up for gene-modifying RNA therapeutics, as post-marketing surveillance obligations will reshape trial budgeting and site selection criteria for late-phase programs.
Market Dynamics
Adaptive regulatory pathways and lipid nanoparticle manufacturing bottlenecks are compressing RNA therapy trial timelines while concentrating sponsor relationships with full-service CROs possessing integrated cold-chain capabilities.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Rolling review protocols accelerate phase transitions for oncology RNA candidates targeting previously undruggable genetic mechanisms. Sponsors leverage this pathway to compress development timelines by 12-18 months.
- mRNA platform validation:Infectious disease applications validated during COVID-19 trials now enable rapid pivoting to cancer vaccines and personalized neoantigen therapies. Platform familiarity reduces investigator training burdens and site activation delays.
- NIH funding concentration:Dense venture capital clustering in Boston and San Francisco creates self-reinforcing ecosystems of specialized RNA manufacturing and clinical operations talent. Geographic proximity accelerates protocol amendments and patient recruitment.
Market Restraints
- Specialized manufacturing concentration:Lipid nanoparticle formulation capabilities cluster with a limited number of CDMOs in Switzerland and the United States. Supply concentration creates queue bottlenecks that delay trial initiations by 6-9 months.
- Ultra-cold chain infrastructure costs:-70°C storage requirements for mRNA stability impose capital intensity on site selection. Rural and community oncology centers face exclusion from RNA trials due to equipment gaps.
- Immunogenicity monitoring complexity:Cytokine release syndrome and innate immune activation require specialized biomarker panels and extended observation windows. Protocol complexity inflates per-patient costs beyond conventional biologics benchmarks.
Strategic Opportunities
- Central and Eastern European expansion:Poland and Czech Republic offer concentrated oncology patient populations with limited access to approved targeted therapies. Regulatory alignment with EMA standards enables seamless data integration for EU marketing applications.
- AI-driven patient stratification:Machine learning integration with RNA sequencing data enables predictive biomarker identification before phase II initiation. Convergence of computational biology and clinical operations compresses cohort optimization timelines.
- Japan's Sakigake designation:PMDA's priority review system for innovative nucleic acid therapies creates a regulatory tailwind for sponsors willing to commit to domestic trial infrastructure. Early approval in Japan anchors Asia-Pacific commercialization strategies.
Industry Challenges
- Gene therapy crossover talent scarcity:Clinical investigators with experience in both viral vector and lipid nanoparticle delivery remain concentrated at academic medical centers in Germany and the United States. Site expansion into second-tier markets requires substantial training investment.
- Long-term follow-up protocol design:FDA guidance on durability monitoring for gene-modifying RNA therapeutics remains in draft form. Sponsors face budgeting uncertainty for post-marketing surveillance obligations extending 5-15 years beyond initial approval.
- Cross-border data transfer friction:GDPR compliance for EU patient genomic data complicates centralized monitoring models. CROs must maintain redundant data residency infrastructure, inflating operational overhead for multinational trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNA Therapy Clinical Trials Market |
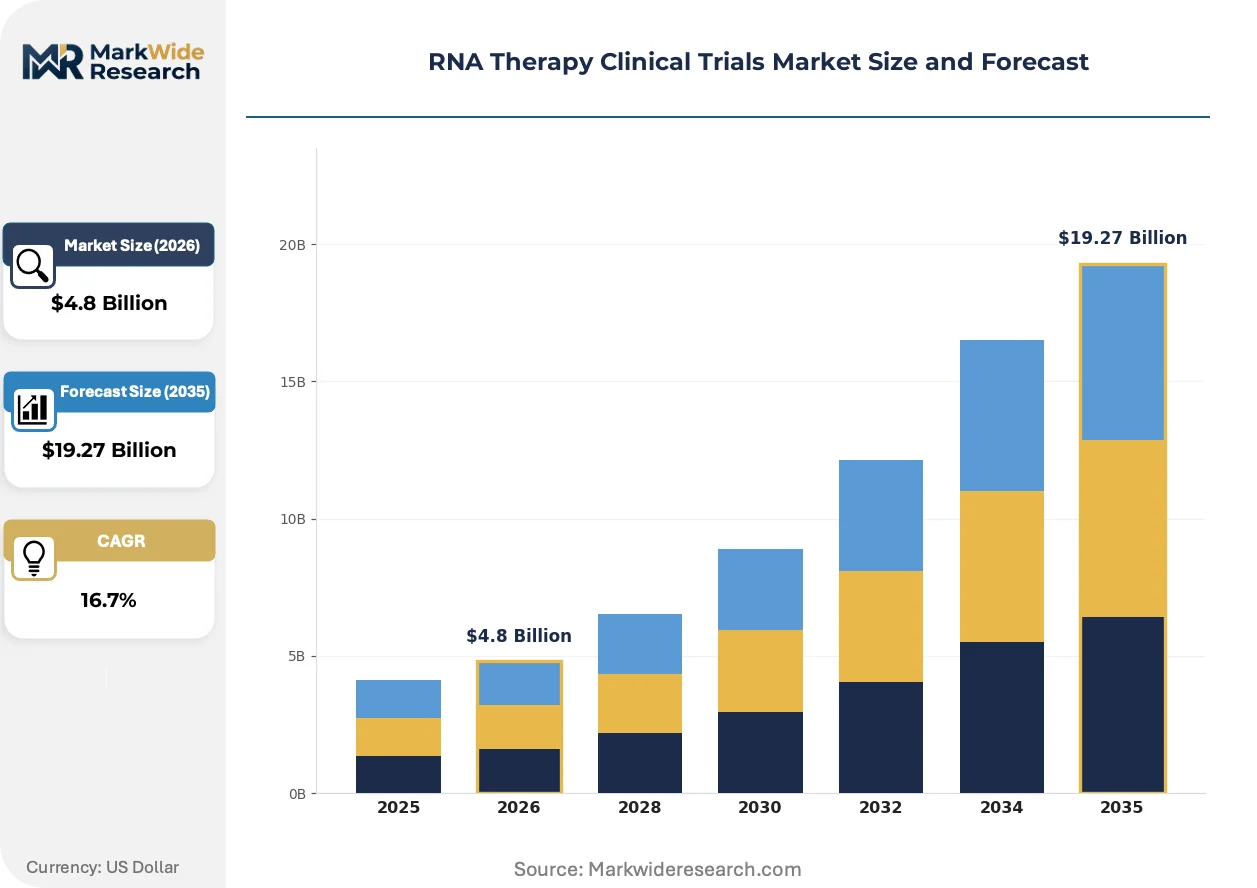
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: mRNA, siRNA, miRNA, RNAi Application: Oncology, Infectious Diseases, Genetic Disorders, Cardiovascular End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Contract Research Organizations Delivery Mode: Liposomes, Viral Vectors, Nanoparticles, Electroporation |
| Companies Covered | IQVIA, ICON Plc, Laboratory Corporation of America Holdings, Charles River Laboratories International, Inc., PAREXEL International Corp., Syneos Health, Medpace Holdings, Inc., PPD Inc., Novotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNA Therapy Clinical Trials Market Evolving Landscape
Digital biomarker integration and decentralized trial modalities are restructuring how RNA therapy sponsors capture real-time safety and efficacy signals outside traditional site-based monitoring frameworks.
Self-amplifying RNA (saRNA) constructs is expanding into infectious disease and oncology applications by reducing required dose volumes tenfold compared to conventional mRNA. Vaccine developers at academic research hospitals in the United Kingdom and Australia are adopting saRNA platforms for seasonal influenza and personalized cancer vaccine programs. Lower dose requirements are enabling broader site activation into community settings previously excluded by cold-chain constraints.
EMA's PRIME eligibility criteria now explicitly reward RNA therapies addressing antimicrobial resistance and rare genetic disorders with accelerated scientific advice and rapporteur assignment. Pharmaceutical sponsors filing in parallel with FDA breakthrough designation receive coordinated EMA-FDA feedback that harmonizes protocol designs across jurisdictions. Oncology applications with companion diagnostic requirements capture disproportionate benefit from this regulatory convergence.
Modular service bundling now dominates sponsor-CRO negotiations, with sponsors unbundling preclinical toxicology, clinical operations, and regulatory submission functions across specialized providers rather than defaulting to full-service relationships. Large pharmaceutical companies with internal RNA manufacturing capabilities increasingly retain clinical operations in-house while outsourcing only patient recruitment and data management. This pattern concentrates most visibly among sponsors headquartered in the Boston-Cambridge corridor with established platform expertise.
RNA Therapy Clinical Trials Market Segmentation
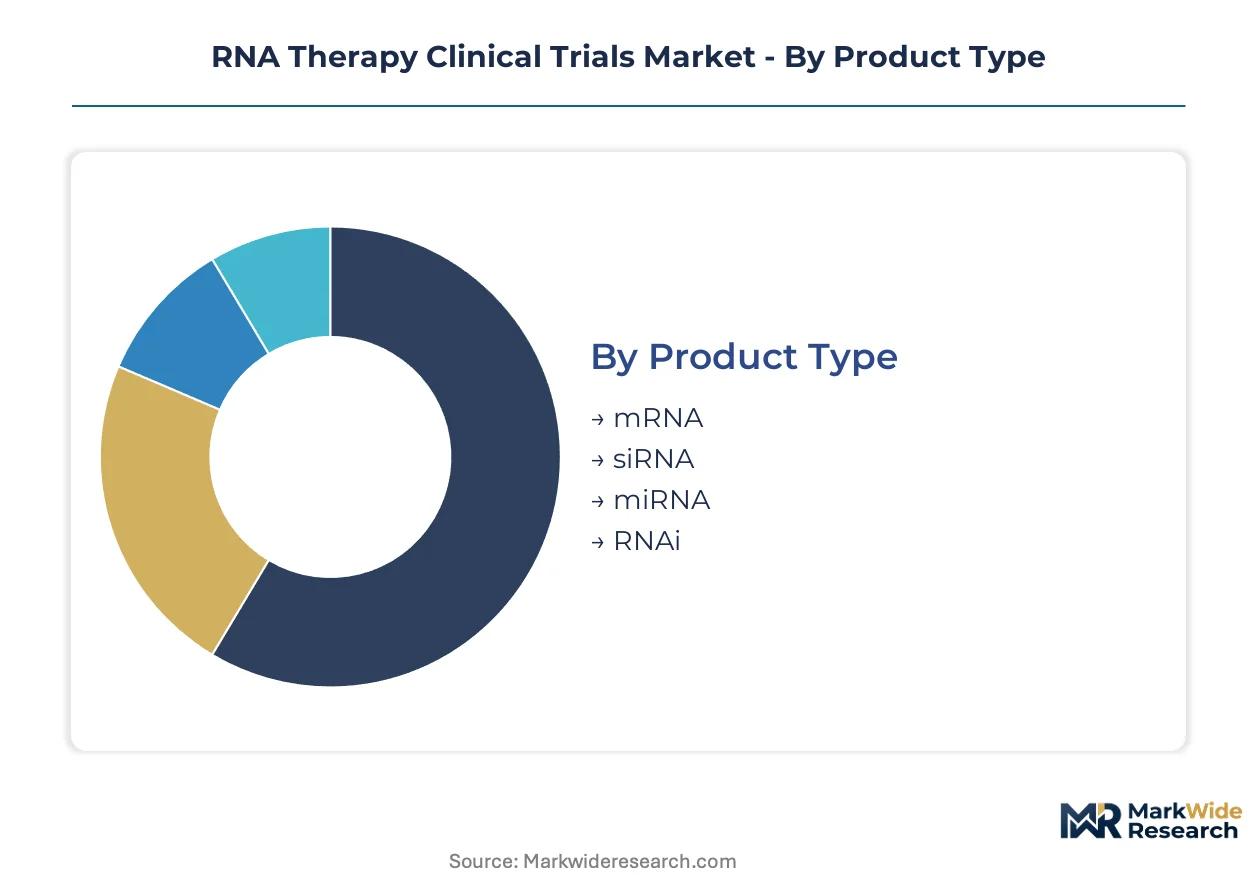
RNA therapy trial sponsors segment procurement across molecular modality, therapeutic area, and delivery complexity to match specialized CRO capabilities with protocol requirements. Each dimension carries distinct cold-chain, biomarker, and regulatory implications that reshape vendor selection and site geography.
Product Type:
Standardized platform manufacturing dominates mRNA and siRNA, while miRNA and RNAi retain bespoke process development dependencies.
- mRNA:Linear nucleic acid constructs encoding therapeutic proteins, stabilized through modified nucleosides and lipid nanoparticle encapsulation. Demand concentrates in infectious disease and oncology vaccine applications across United States and Germany, where FDA and EMA breakthrough pathways compress development timelines for platform-validated sponsors.
- siRNA:Small interfering RNA molecules triggering catalytic mRNA degradation via RISC complex recruitment. Chronic dosing protocols for genetic disorders drive trial complexity premiums in Switzerland and United Kingdom, where specialized CDMOs cluster for lipid nanoparticle formulation scale-up.
- miRNA:Endogenous microRNA mimics or antagonists modulating multiple mRNA targets simultaneously. Academic medical centers in Japan and Australia pioneer cardiovascular and fibrosis applications.
- RNAi:Synthetic double-stranded RNA constructs enabling prolonged gene silencing. Rare disease sponsors in Massachusetts and California leverage accumulated platform expertise from prior approved therapies.
Most installed capacity flows through mRNA. Expansion is steepest in RNAi.
Application:
Oncology commands premium trial fees while infectious disease trials scale through platform standardization.
- Oncology:Personalized neoantigen vaccines and tumor suppressor restoration require patient-specific manufacturing and companion diagnostic integration. Phase II-III programs cluster in Boston, Basel, and Singapore where biomarker infrastructure supports adaptive enrollment.
- Infectious Diseases:Prophylactic vaccines against influenza, HIV, and emerging pathogens leverage validated COVID-19 manufacturing templates. Trial density concentrates in United States and United Kingdom where mRNA platform familiarity reduces investigator training cycles.
- Genetic Disorders:Transthyretin amyloidosis, hemophilia, and primary hyperoxaluria targets require ultra-rare disease recruitment networks spanning European reference centers.
- Cardiovascular:Cholesterol management and heart failure applications trail oncology in pipeline maturity but attract Big Pharma investment for population-scale commercial potential.
Revenue pools concentrate in oncology. Patient recruitment velocity peaks in infectious diseases.
End User:
Internal capability depth determines outsourcing scope across sponsor categories.
- Pharmaceutical Companies:Large-cap sponsors with captive manufacturing retain clinical operations in-house while unbundling patient recruitment and data management to specialized vendors. Boston-Cambridge corridor sponsors exhibit highest vertical integration rates.
- Academic Institutions:Principal investigator-led early-phase studies rely on NIH funding and shared research infrastructure. University of Pennsylvania and Karolinska Institutet anchor investigator-initiated RNA trial networks.
- Research Organizations:Non-profit disease foundations commission natural history studies and biomarker qualification trials to de-risk subsequent pharmaceutical partnerships.
- Contract Research Organizations:Full-service and niche CROs capture modular outsourcing from capital-constrained biotechs lacking internal clinical operations.
Pharmaceutical sponsors deploy the most capital per trial. Academic institutions generate the highest volume of phase I initiations.
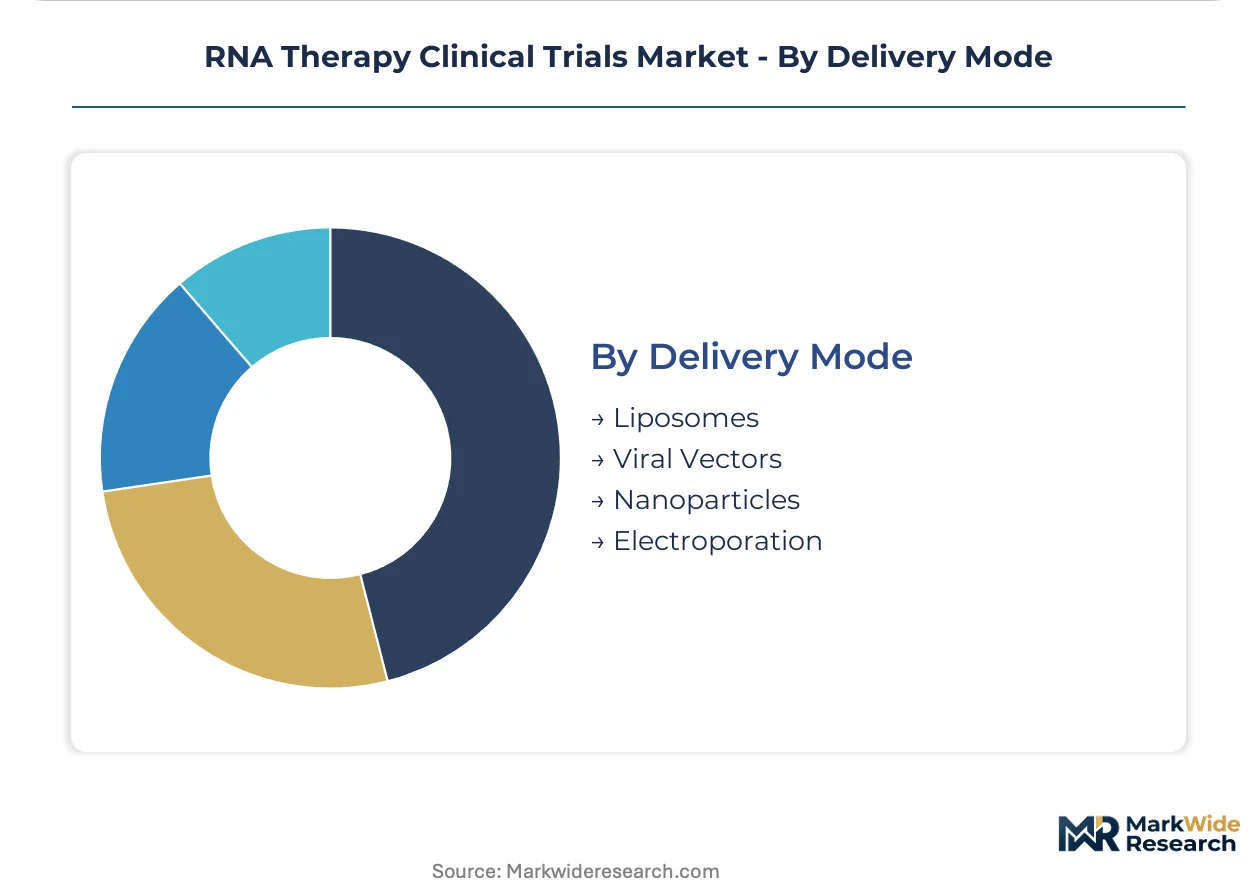
Delivery Mode:
Manufacturing sophistication and stability requirements segment delivery technology selection.
- Lipid Nanoparticles:Ionizable lipids, phospholipids, cholesterol, and PEG-lipid formulations encapsulating mRNA and siRNA for intracellular release. CDMO concentration in Switzerland and United States creates queue bottlenecks extending trial initiation timelines.
- Viral Vectors:Adeno-associated virus and lentiviral platforms for liver-directed and ex vivo applications. Manufacturing scale-up constraints in Germany and France limit availability for large-phase programs.
- Liposomes:Conventional phospholipid bilayer systems for localized delivery and reduced immunogenicity profiles. Dermatology and ophthalmology applications favor this modality.
- Electroporation:Physical membrane disruption enabling naked RNA entry, applied in ex vivo cell therapy manufacturing and intratumoral injection protocols.
Lipid nanoparticles carry the highest manufacturing investment. Viral vectors face the steepest capacity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The RNA therapy clinical trials industry traces its commercial lineage to the United States, where mRNA platform validation during COVID-19 established regulatory precedents and manufacturing templates now replicated across multiple jurisdictions.
United States
NIH funding density and venture capital clustering in Boston and San Francisco create self-reinforcing ecosystems of specialized talent. FDA breakthrough therapy designation compresses phase transitions by 12-18 months for oncology RNA candidates. The Greater Boston corridor hosts the highest concentration of vertically integrated pharmaceutical sponsors retaining clinical operations in-house.
Germany
Academic medical centers in Heidelberg and Berlin anchor investigator-initiated networks for rare disease RNAi applications. EMA PRIME eligibility enables accelerated scientific advice and rapporteur assignment for nucleic acid therapies. The country's national pharmaceutical regulator coordinates with FDA on harmonized protocol designs for multinational programs.
Switzerland
Specialized CDMO concentration for lipid nanoparticle formulation creates manufacturing bottlenecks extending trial initiation timelines. Swissmedic maintains stringent quality benchmarks for lipid nanoparticle stability that filter undercapitalized sponsors. Basel clusters phase II-III oncology programs with companion diagnostic integration requirements.
United Kingdom
Academic research hospitals pioneer self-amplifying RNA platforms for seasonal influenza and personalized cancer vaccines. MHRA rolling review protocols align with EMA-FDA feedback mechanisms for breakthrough-designated candidates. Oxford and Cambridge sustain early-phase initiation velocity through NIH-funded shared research infrastructure.
Japan
PMDA's Sakigake priority review system creates regulatory tailwinds for sponsors committing to domestic trial infrastructure. Tokyo and Osaka academic centers concentrate clinical investigators with viral vector and lipid nanoparticle delivery experience. Early approval in Japan anchors Asia-Pacific commercialization strategies for gene-modifying RNA therapeutics.
RNA Therapy Clinical Trials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with full-service CROs commanding pricing power through captive cold-chain capabilities and specialized toxicology providers defending position through mandatory upstream gatekeeping. The vendor base organizes into three tiers: integrated data-and-site networks, preclinical safety specialists, and adaptive design boutiques. Consolidation pressure favors scale-driven acquisition of regional patient recruitment assets and technology licensing for AI-driven biomarker integration.
Within the integrated service tier, IQVIA anchors large-scale mRNA vaccine studies across multiple continents through its data and site network density. Charles River Laboratories International, Inc. occupies the mandatory upstream position for preclinical RNA safety assessment before human dosing authorization. PAREXEL International Corp. exemplifies the adaptive design specialization vector, differentiating offerings for sponsors pursuing expedited regulatory pathways.
| Leading Market Players |
|---|
| IQVIA |
| ICON Plc |
| Laboratory Corporation of America Holdings |
| Charles River Laboratories International, Inc. |
| PAREXEL International Corp. |
| Syneos Health |
| Medpace Holdings, Inc. |
| PPD Inc. |
| Novotech |
| Others |
Value Network & Pricing Analysis
Modular trial service bundling by large pharmaceutical sponsors is compressing margins for full-service CROs while concentrating procurement power with vendors possessing integrated cold-chain capabilities. This buyer consolidation forces specialized providers to absorb lipid nanoparticle storage costs or exit the RNA therapy segment entirely.
Pricing Analysis
Project-based fee structures with complexity-adjusted premiums dominate RNA therapy trial procurement. Price differentiation rests on biomarker panel sophistication and adaptive design certification, with FDA breakthrough-designated programs commanding 40-60% premiums over standard oncology trials. Cost compression in infectious disease mRNA trials is intensifying because COVID-19 platform validation commoditized manufacturing templates. Small biotechs lacking internal clinical operations exhibit highest price sensitivity, while vertically integrated pharmaceutical sponsors in the Boston-Cambridge corridor negotiate from positions of supply security.
Supply Chain Analysis
Reverse-logistics for temperature-deviated investigational products remains underdeveloped, with most sites destroying rather than returning compromised vials. Lipid nanoparticle formulation capacity concentrates in Switzerland, the United States, and Germany, where CDMO queues extend trial initiation timelines. Manufacturing draws from ionizable lipid libraries, cholesterol supplies, and specialized PEG-lipid chemistries anchored in Swiss and American chemical production. Single-source vulnerability pervades the -70°C cold-chain equipment layer, where two manufacturers control 80% of ultra-low freezer installation. Distribution runs through specialized clinical logistics providers with redundant cryogenic monitoring rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA therapy clinical trials function as a regulatory compounder where FDA breakthrough therapy designation and EMA PRIME eligibility create accelerating returns for sponsors navigating adaptive pathways successfully.
For Market Incumbents: Lock in exclusive lipid nanoparticle manufacturing partnerships with Swiss and American CDMOs before queue bottlenecks worsen. Secure investigator networks at academic medical centers in Heidelberg and Boston where gene therapy crossover talent concentrates, insulating against emerging competition from AI-driven patient stratification platforms. For New Entrants and Emerging Players: Direct-to-sponsor digital platforms for decentralized trial patient recruitment offer the most penetrable entry vector. Target community oncology centers in Central and Eastern Europe previously excluded by cold-chain infrastructure gaps. Lead with self-amplifying RNA platform expertise to differentiate from commoditized mRNA offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with adaptive trial design boutiques possessing proprietary biomarker algorithms and FDA rapporteur relationships. Five-to-ten year viability hinges on regulatory convergence between FDA and EMA accelerating rather than fragmenting. Monitor draft FDA guidance on long-term follow-up obligations for gene-modifying therapeutics as the critical inflection signal for late-phase trial budgeting models.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Certification | FDA breakthrough pathway access compresses development timelines for oncology RNA candidates. |
| Lipid Nanoparticle Manufacturing Scale-Up | Swiss and American CDMO partnerships resolve queue bottlenecks extending trial initiations. |
| AI-Driven Patient Stratification Integration | Machine learning with RNA sequencing data compresses cohort optimization before phase II. |
| Central and Eastern European Site Activation | Poland and Czech Republic offer concentrated oncology populations with EMA-aligned regulations. |
| Sakigake Designation Pursuit | PMDA priority review anchors Asia-Pacific commercialization for gene-modifying therapeutics. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and clinical operations directors; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; plus bottom-up and top-down triangulation — were reconciled to construct market estimates. Conversations with CRO procurement officers and site activation specialists at academic medical centers in Boston, Basel, and Singapore informed service bundling patterns and pricing dynamics.
Historical trial initiation velocity was cross-referenced against expert panel assessments of pipeline progression across the analysis window. Segmentation modeling incorporated molecular modality, therapeutic area, delivery complexity, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of phase transition timelines and sponsor investment patterns, with lipid nanoparticle manufacturing capacity constraints and immunogenicity monitoring protocol inflation treated as specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for self-amplifying RNA or electroporation delivery would alter the outlook if manufacturing scale-up outpaces lipid nanoparticle bottlenecks. Forecasts reflect assumptions about FDA-EMA regulatory convergence and NIH funding continuity. Practitioners should monitor draft FDA guidance on long-term follow-up obligations and CDMO queue duration reports for early signals of timeline compression or extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market