
 Viral Vector and Plasmid DNA Testing Service Market | 2026-2036
Viral Vector and Plasmid DNA Testing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Vector and Plasmid DNA Testing Service Market Insights
Gene therapy developers is consolidating around contract testing partners capable of potency, identity, and sterility validation under accelerated timelines. Charles River Laboratories leverages its integrated biologics testing footprint to capture multi-phase programs from early characterization through lot release. Lonza anchors European viral vector testing capacity with dedicated facilities in Switzerland and the UK. Thermo Fisher Scientific Inc. competes through its combined reagent and service portfolio, reducing transfer risk for sponsor firms.
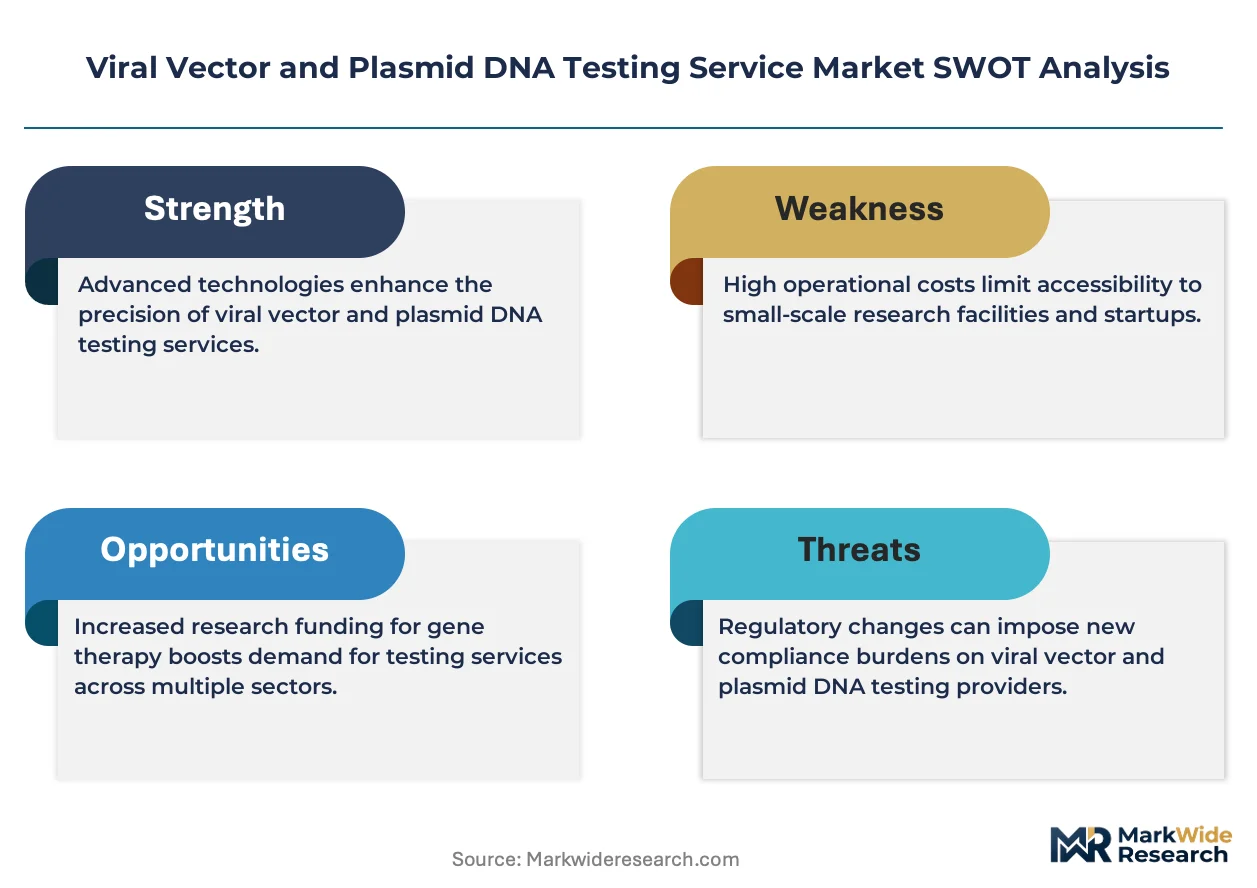
Viral vector and plasmid DNA testing services encompass analytical methods for characterizing recombinant viral particles and circular DNA vectors used to deliver genetic payloads, including qPCR titration, next-generation sequencing for identity confirmation, and transmission electron microscopy for physical particle count. These services ensure safety, potency, and consistency before clinical or commercial release of cell and gene therapy products. Viral vectors lead testing service revenue due to complex manufacturing and stringent release panels, while plasmid DNA represents the fastest-growing segment as linear DNA and minicircle alternatives gain traction in non-viral delivery programs. Sequencing technology commands premium pricing within the analytical stack as identity and adventitious agent testing migrate toward higher-resolution platforms.
FDA, EMA, and ISO 13485 standards govern viral vector release testing, with FDA's Chemistry, Manufacturing, and Controls guidance driving sponsor investment in validated potency assays ahead of IND and BLA submissions. The EU's ATMP Regulation and associated GMP Annexes enforce comparability requirements that expand testing scope for products manufactured across multiple sites. Stakeholders must monitor evolving regulatory science around replication-competent virus detection and reference standard harmonization as agency expectations outpace standardized method availability.
Market Dynamics
FDA potency assay guidelines and EMA ATMP comparability requirements are compressing sponsor timelines while fragmenting qualified testing capacity across geographies, forcing developers to lock in multi-year service contracts before manufacturing scale-up.
Growth Catalysts
- EMA ATMP Regulation:The EU's Advanced Therapy Medicinal Products framework mandates extended release panels for cross-site manufacturing, expanding testing scope for viral vector products moving through Swiss and UK facilities.
- qPCR titration:Quantitative polymerase chain reaction methods for viral particle enumeration are becoming the standard release assay, pulling demand toward service providers with validated platform transfers.
- Boston-San Diego corridor:Gene therapy developer concentration in these US biotech clusters is generating localized demand spikes that outpace in-house testing buildout.
Market Restraints
- Reference standard scarcity:Harmonized potency reference materials remain unavailable from NIST or WHO, forcing sponsors to run parallel qualification studies that extend timelines by 6-12 months.
- Transmission electron microscopy capacity:Physical particle counting requires specialized equipment and trained operators, creating a supply bottleneck concentrated among European and North American contract labs.
- Plasmid DNA price compression:Linear DNA and minicircle alternatives are eroding pricing power for conventional circular plasmid testing services.
Strategic Opportunities
- Japan PMDA pathway:The regenerative medicine regulatory framework offers accelerated approval timelines for gene therapies, creating first-mover advantage for testing services establishing local partnerships.
- Next-generation sequencing identity testing:NGS platforms for adventitious agent detection and vector genome confirmation represent premium service tiers with limited qualified competition.
- Integrated biologics testing:Service providers combining viral vector, cell therapy, and plasmid capabilities under one quality system can capture full program lifecycles from IND through commercial release.
Industry Challenges
- Replication-competent virus detection:RCV assay validation lacks standardized methods, forcing each sponsor to develop and qualify custom qPCR or infectivity assays that resist cross-program standardization.
- ISO 13485 certification timelines:Medical device quality system implementation for testing services requires 12-18 months of documentation and audit preparation before agency inspection readiness.
- Vector genome sequencing expertise:Bioinformatics interpretation of NGS data for identity confirmation requires computational biology talent scarce among traditional analytical chemistry organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Vector and Plasmid DNA Testing Service Market |
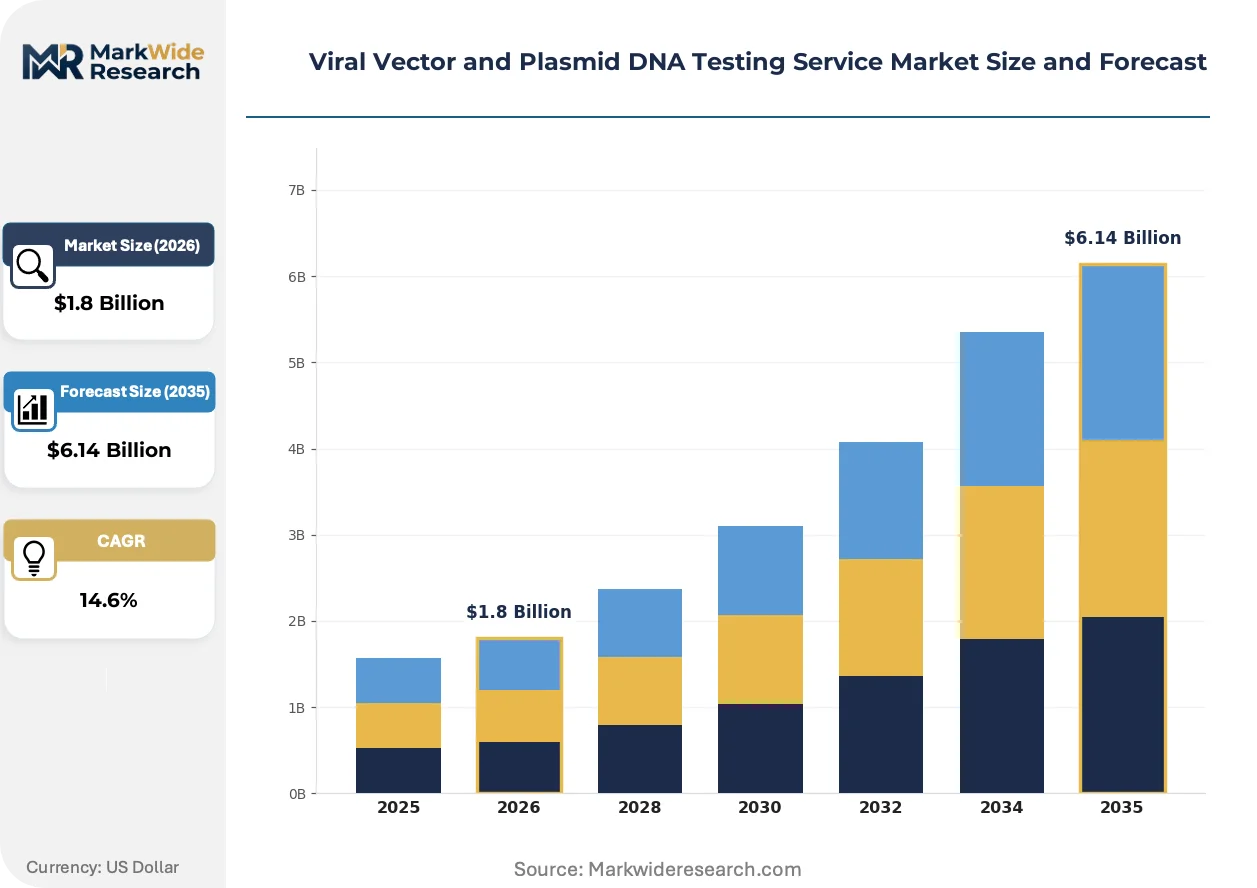
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viral Vectors, Plasmid DNA, Recombinant Proteins, Nucleic Acids End User: Pharmaceutical Companies, Academic Research, Biotechnology Firms, Contract Research Organizations Application: Gene Therapy, Vaccine Development, Genetic Engineering, Bioproduction Technology: Transfection, Electroporation, Viral Packaging, Sequencing |
| Companies Covered | Charles River Laboratories, Thermo Fisher Scientific Inc., Merck KGaA, PathoQuest, BioReliance, Coriolis Pharma, Lonza, AGC Biologics, Exothera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Vector and Plasmid DNA Testing Service Market Trends and Innovations
Testing service architecture is pivoting from discrete assay outsourcing toward integrated platform partnerships that span characterization, validation, and lot release under unified quality agreements.
Digital PCR is consolidating absolute quantification workflows for viral vector titer and residual DNA detection. Gene therapy developers with accelerated IND timelines are adopting droplet-based dPCR platforms to bypass standard curve dependencies. This technology shift is consolidating analytical method transfers toward service providers with validated dPCR infrastructure and trained operators.
EMA's GMP Annex 2A revisions for ATMP manufacturing impose stricter environmental monitoring and raw material qualification requirements on viral vector production sites. The industrial consequence is expanded testing scope for mycoplasma, endotoxin, and sterility panels at contract testing organizations supporting European manufacturing. Sponsors with EU commercialization plans are prioritizing service partners with existing Annex 2A audit histories.
Biotech sponsors are compressing vendor qualification cycles from 18-24 months toward 6-9 month accelerated pathways. Large gene therapy developers with multiple pipeline assets are displacing project-based contracting with master service agreements that lock in capacity and pricing across three to five year horizons. This behavioral shift is most visible among Boston and San Diego headquartered sponsors with Series C or later funding stages.
Viral Vector and Plasmid DNA Testing Service Market Segmentation
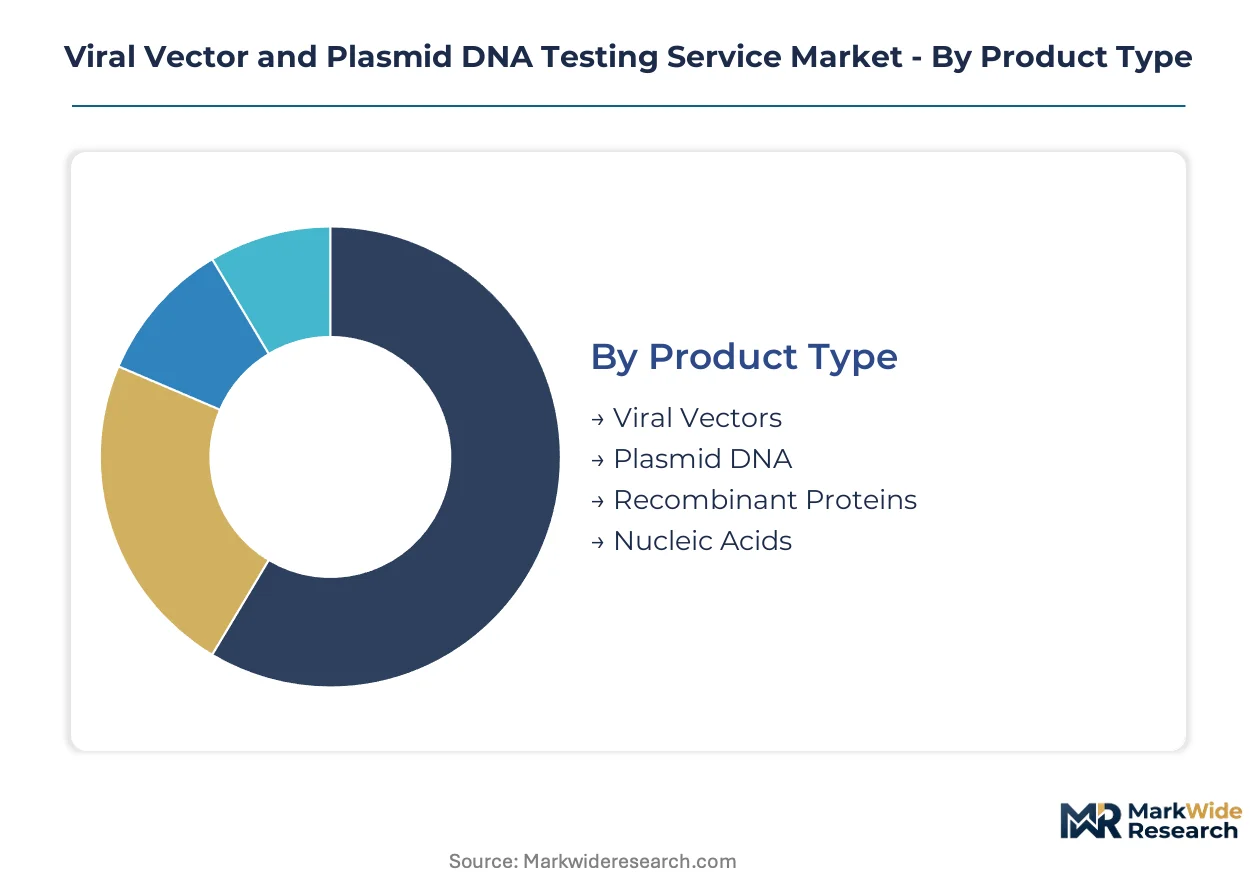
Testing service procurement decisions hinge on vector complexity, regulatory jurisdiction, and manufacturing scale. Sponsors select analytical partners based on validated platform coverage across their specific product modality and intended commercial geography.
Product Type:
Cost tier determines service selection, with complex viral programs commanding premium pricing and extended validation timelines.
- Viral Vectors:Recombinant viral particles including AAV, lentivirus, and adenovirus require multi-panel release testing covering potency, identity, and adventitious agents. Demand concentrates among gene therapy developers in the United States, particularly around Boston and San Diego, where FDA Chemistry, Manufacturing, and Controls timelines compress vendor qualification cycles.
- Plasmid DNA:Circular DNA vectors serve as starting material for viral packaging and direct non-viral gene delivery applications. Biotechnology firms in Switzerland and the United Kingdom are driving demand as EMA ATMP comparability requirements expand testing scope for plasmid-based programs.
- Recombinant Proteins:Purified protein products used as transduction enhancers or process contaminants require host cell protein and residual DNA quantification.
- Nucleic Acids:Linear DNA and minicircle alternatives are gaining traction in non-viral delivery programs with simplified regulatory pathways.
Volume sits with Viral Vectors; growth tilts toward Plasmid DNA.
End User:
Customer type shapes contracting structure, with large developers locking in multi-year master service agreements and smaller players accepting spot pricing.
- Pharmaceutical Companies:Multinational drug developers with commercial gene therapy portfolios require integrated testing platforms spanning IND through BLA submission. These sponsors in the United States and Germany are displacing project-based contracts with capacity reservations extending three to five years.
- Biotechnology Firms:Venture-backed gene therapy developers with single-asset pipelines prioritize speed over integration, selecting partners with validated qPCR titration and rapid sterility turnaround.
- Academic Research:University laboratories conducting early-stage vector characterization require flexible, low-volume testing arrangements without full GMP release documentation.
- Contract Research Organizations:CROs serving as manufacturing intermediates for sponsor firms need transferable analytical methods that support tech transfer to commercial partners.
Revenue concentrates among Pharmaceutical Companies; biotechnology firms are expanding most quickly.
Application:
Application maturity determines which analytical technologies sponsors prioritize, with commercial-stage programs requiring more extensive validation.
- Gene Therapy:In vivo and ex vivo genetic medicine applications demand the most comprehensive release panels, including replication-competent virus detection and vector genome sequencing. Developers in Japan are accelerating PMDA pathway submissions, creating localized demand for testing partners with regenerative medicine regulatory experience.
- Vaccine Development:Viral vector-based vaccines require streamlined potency and sterility testing with faster turnaround than gene therapy programs.
- Genetic Engineering:Research-grade vector production for cell line development and target validation requires identity confirmation without full commercial release documentation.
- Bioproduction:Plasmid DNA and viral vector manufacturing for third-party supply demands lot release testing aligned with client quality agreements.
Testing volume clusters in Gene Therapy; Vaccine Development shows the steepest expansion trajectory.
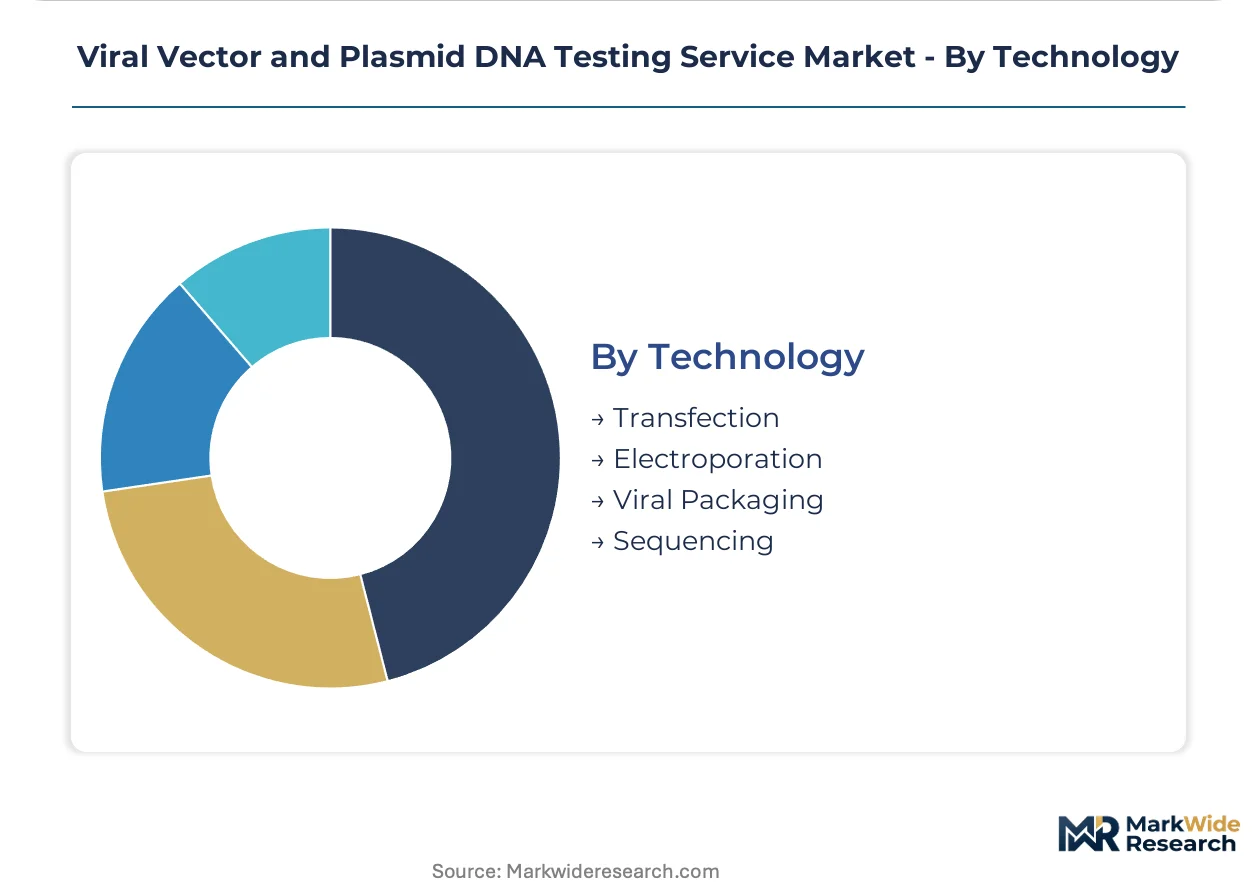
Technology:
Platform infrastructure investment separates qualified service providers from commodity competitors, with digital PCR and sequencing commanding premium positioning.
- Sequencing:Next-generation sequencing platforms for vector genome identity confirmation and adventitious agent detection represent the highest-margin service tier. Sponsors in the United Kingdom and Switzerland are migrating from Sanger methods toward higher-resolution NGS panels as EMA GMP Annex 2A revisions tighten raw material qualification requirements.
- qPCR Titration:Quantitative polymerase chain reaction for viral particle enumeration has become the standard release assay across AAV and lentivirus programs.
- Transfection:Analytical methods supporting plasmid DNA quality assessment for transient expression systems.
- Electroporation:Testing services validating non-viral delivery efficiency for linear DNA and mRNA applications.
- Viral Packaging:Process analytical technology supporting upstream manufacturing optimization rather than lot release.
Sequencing captures premium pricing; qPCR Titration anchors transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Massachusetts and California are concentrating gene therapy development, pulling testing demand toward contract laboratories within 50 miles of manufacturing sites.
United States
FDA Chemistry, Manufacturing, and Controls timelines compress vendor qualification cycles to 6-9 months. The agency's potency assay guidance drives sponsor investment in validated release assays ahead of IND submissions. Boston and San Diego biotech clusters generate localized demand spikes that outpace in-house testing buildout.
Switzerland
Swissmedic enforces GMP Annex 2A revisions that expand environmental monitoring requirements for viral vector production. Lonza anchors European testing capacity with dedicated facilities serving cross-border ATMP programs. Basel and Zurich host concentrated contract testing infrastructure for plasmid DNA qualification.
United Kingdom
EMA ATMP comparability requirements extend testing scope for products manufactured across multiple sites. The Medicines and Healthcare products Regulatory Agency aligns with EU GMP standards post-Brexit, preserving testing protocol continuity. Oxford and Cambridge biotech corridors drive demand for next-generation sequencing identity panels.
Japan
PMDA's regenerative medicine regulatory framework offers accelerated approval timelines for gene therapies. METI funding programs support local manufacturing scale-up, creating first-mover advantage for testing services establishing partnerships. Tokyo and Osaka clusters are expanding viral vector production capacity.
Germany
BfArM enforces medical device quality system requirements that extend ISO 13485 certification timelines to 12-18 months. The country's central European location supports multi-site manufacturing comparability testing. Munich and Heidelberg biotech regions concentrate gene therapy developer headquarters.
Viral Vector and Plasmid DNA Testing Service Market Competitive Landscape
Top-tier vendors anchor integrated biologics testing platforms, while mid-tier specialists compete on assay-specific turnaround speed. The market structure reflects consolidation around multi-phase service providers capable of spanning early characterization through commercial lot release. Three archetypes dominate: integrated contract testing organizations, vector-focused analytical specialists, and diversified life science conglomerates with reagent-service bundles. Capacity reservation agreements and master service contracts represent the dominant competitive moves, displacing project-based procurement.
Within the integrated testing tier, Charles River Laboratories and Lonza occupy positions that exemplify platform breadth across viral vector, cell therapy, and plasmid capabilities. Thermo Fisher Scientific Inc. represents the diversified archetype, combining reagent supply with service delivery to reduce transfer risk. These three anchors collectively illustrate how vendor selection criteria have shifted toward unified quality systems spanning IND through BLA submission timelines.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| PathoQuest |
| BioReliance |
| Coriolis Pharma |
| Lonza |
| AGC Biologics |
| Exothera |
| Others |
Pricing and Supply Chain Analysis
Reference standard scarcity drives cost layering across viral vector testing tiers, with NIST-qualified potency materials commanding premium positioning while unqualified alternatives force sponsors into parallel qualification studies that extend timelines and inflate project pricing. This input cost structure cascades through to sponsor firms, where Boston and San Diego gene therapy developers absorb higher per-assay pricing to secure validated platform access ahead of IND submissions.
Pricing Analysis
Expedited lead times for IND-enabling potency assays command 40-60% premiums over standard 12-week turnaround slots, while spot-market sterility testing availability fluctuates with seasonal demand from vaccine programs. Three-tier pricing structure across premium, standard, and economy levels separates GMP-release validation from research-grade characterization and exploratory screening panels. Price differentiation rests on ISO 13485 certification status and FDA audit history, with uncertified European labs undercutting established players by 15-25% on basic qPCR titration. Pricing pressure stems from plasmid DNA commoditization as linear DNA alternatives erode circular vector margins. Biotechnology firms with Series C funding show highest price sensitivity, while pharmaceutical companies prioritize capacity assurance over per-assay economics.
Supply Chain Analysis
Regional distribution centers in Basel, Boston, and San Diego anchor hub-and-spoke patterns for reference materials and critical reagents, with 48-hour replenishment radii covering major gene therapy manufacturing clusters. Supply concentrates in the United States, Switzerland, and the United Kingdom, where Lonza, Charles River Laboratories, and Thermo Fisher Scientific anchor qualified testing capacity. Raw material dependencies span synthetic oligonucleotides, cell culture media, and specialized electron microscopy grids sourced from single-qualified vendors. Single-source vulnerability for transmission electron microscopy operators creates bottleneck risk, as European and North American labs compete for limited trained personnel. Distribution runs through direct sponsor-laboratory contracts rather than third-party logistics, with master service agreements locking in multi-year capacity reservations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transmission electron microscopy capacity scarcity props pricing power for qualified operators, as sponsor demand for physical particle counting outstrips trained analyst supply across North America and Europe. This structural bottleneck sustains margin premiums for incumbents with validated infrastructure while forcing developers into extended queue positions or higher-cost expedited slots.
For Market Incumbents: Anticipate digital PCR platform consolidation by securing droplet-based dPCR infrastructure ahead of sponsor migration from standard qPCR methods, as gene therapy developers with accelerated IND timelines bypass curve-dependent assays. Lock in multi-year master service agreements with Boston and San Diego sponsors before manufacturing scale-up compresses vendor qualification windows. Prioritize ISO 13485 certification investment to capture pharmaceutical company contracts that exclude uncertified competitors from GMP-release panels. For New Entrants and Emerging Players: PMDA's regenerative medicine regulatory framework in Japan opens a window for testing services establishing local partnerships ahead of Tokyo and Osaka manufacturing expansion, as METI funding programs accelerate viral vector production capacity. Target the NGS identity testing segment, where limited qualified competition and premium pricing create penetrable white space for bioinformatics-capable entrants. Pursue academic research laboratories as initial reference clients, converting flexible low-volume arrangements into GMP validation contracts as programs advance toward IND submission. For Investors and Strategic Acquirers: FDA potency assay guidance publication is the leading indicator that sponsor investment in validated release assays will accelerate, signaling expanded contract testing demand ahead of IND and BLA submission waves. Frame long-term viability around integrated biologics testing platforms spanning viral vector, cell therapy, and plasmid capabilities, as sponsor consolidation favors unified quality systems over discrete assay outsourcing. Target acquisition candidates with existing Annex 2A audit histories and validated dPCR infrastructure. Monitor EMA GMP Annex 2A revision implementation timelines as the inflection signal for European environmental monitoring and raw material qualification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Digital PCR Platform Validation | Droplet-based dPCR infrastructure captures sponsor migration from standard qPCR titration methods. |
| ISO 13485 Certification Investment | Medical device quality system implementation unlocks pharmaceutical company GMP-release contracts. |
| Master Service Agreement Expansion | Multi-year capacity reservations with Boston and San Diego sponsors secure revenue visibility. |
| NGS Bioinformatics Capability Buildout | Next-generation sequencing expertise addresses computational biology talent scarcity among traditional analytical organizations. |
| Japan PMDA Partnership Establishment | Local regulatory experience positions services for METI-funded manufacturing scale-up in Tokyo and Osaka clusters. |
Research Methodology
FDA Chemistry, Manufacturing, and Controls guidance documents, EMA ATMP regulatory filings, and ClinicalTrials.gov gene therapy protocol databases formed the secondary backbone, cross-referenced against SEC 10-K disclosures from publicly traded contract testing organizations. Primary interviews with gene therapy development executives, regulatory affairs leads at sponsor firms, quality control directors at viral vector manufacturing sites, and procurement managers at pharmaceutical companies validated secondary findings and informed demand-side assumptions. Bottom-up triangulation aggregated individual assay pricing and volume estimates across viral vector, plasmid DNA, and nucleic acid testing segments, while top-down analysis cross-checked totals against disclosed contract testing revenue allocations.
Historical trendline analysis of viral vector IND and BLA submission volumes established baseline demand patterns, with projection modeling incorporating qPCR titration adoption curves, digital PCR platform migration timelines, and NGS identity testing penetration rates across the analysis window. Segmentation dimensions spanned product type, end user, application, technology platform, and regional regulatory cluster. CAGRs were derived from fitted growth curves adjusted for capacity constraints and reference standard availability delays. Industry-specific forecast inputs included sponsor funding stage distributions, manufacturing scale-up timelines, and EMA GMP Annex 2A revision implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for digital PCR standardization or NGS platform consolidation would alter the outlook for qPCR titration demand and sequencing service premiums. Forecasts reflect assumptions around regulatory guidance stability, reference material harmonization progress, and sponsor outsourcing behavior continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market