
 Osteoarthritis Gene Therapy Market | 2026-2036
Osteoarthritis Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Osteoarthritis Gene Therapy Market Analytics
Adeno-associated viral vectors are consolidating market share as the preferred delivery vehicle over lentiviral alternatives in knee osteoarthritis programs, driven by superior safety profiles and reduced immunogenicity. Novartis AG leverages its cell-and-gene therapy manufacturing footprint across multiple continents to sustain supply chain reliability for complex biologics. Genascence anchors its position through sustained-release interleukin-1 receptor antagonist gene therapy platforms designed for single-injection durability. Kolon TissueGene competes in the same intra-articular segment with a distinct focus on transforming growth factor-beta expression constructs.
Osteoarthritis gene therapy encompasses nucleic acid-based interventions delivered to synovial joints to modify disease progression through sustained expression of therapeutic proteins, anti-inflammatory cytokines, or cartilage-anabolic factors, typically administered via arthroscopic or image-guided intra-articular injection. The primary commercial purpose centers on halting structural joint degradation rather than merely masking pain symptoms, distinguishing these therapies from conventional hyaluronic acid or corticosteroid injections. Adenoviral vectors dominate current clinical pipelines due to established large-scale production methods and transient expression kinetics suited to locally acting payloads. CRISPR-based gene editing approaches represent the fastest-growing technology segment, though most programs remain preclinical with margin pools still concentrated in viral delivery platforms. RNA therapeutics occupy an emerging niche where rapid development timelines and reduced manufacturing complexity attract biotechnology company partnerships.
FDA oversight through its Office of Cellular, Tissue, and Gene Therapies shapes trial endpoints and chemistry-manufacturing-controls requirements, while EMA's ATMP classification determines market access pathways and reimbursement negotiations across European member states. Japan's PMDA regenerative medicine framework accelerates conditional approval timelines, creating regulatory arbitrage opportunities for first movers in Asia-Pacific. Stakeholders must monitor evolving payer evidence requirements for durable clinical benefit versus symptomatic relief as gene therapy candidates advance toward commercialization.
Market Dynamics
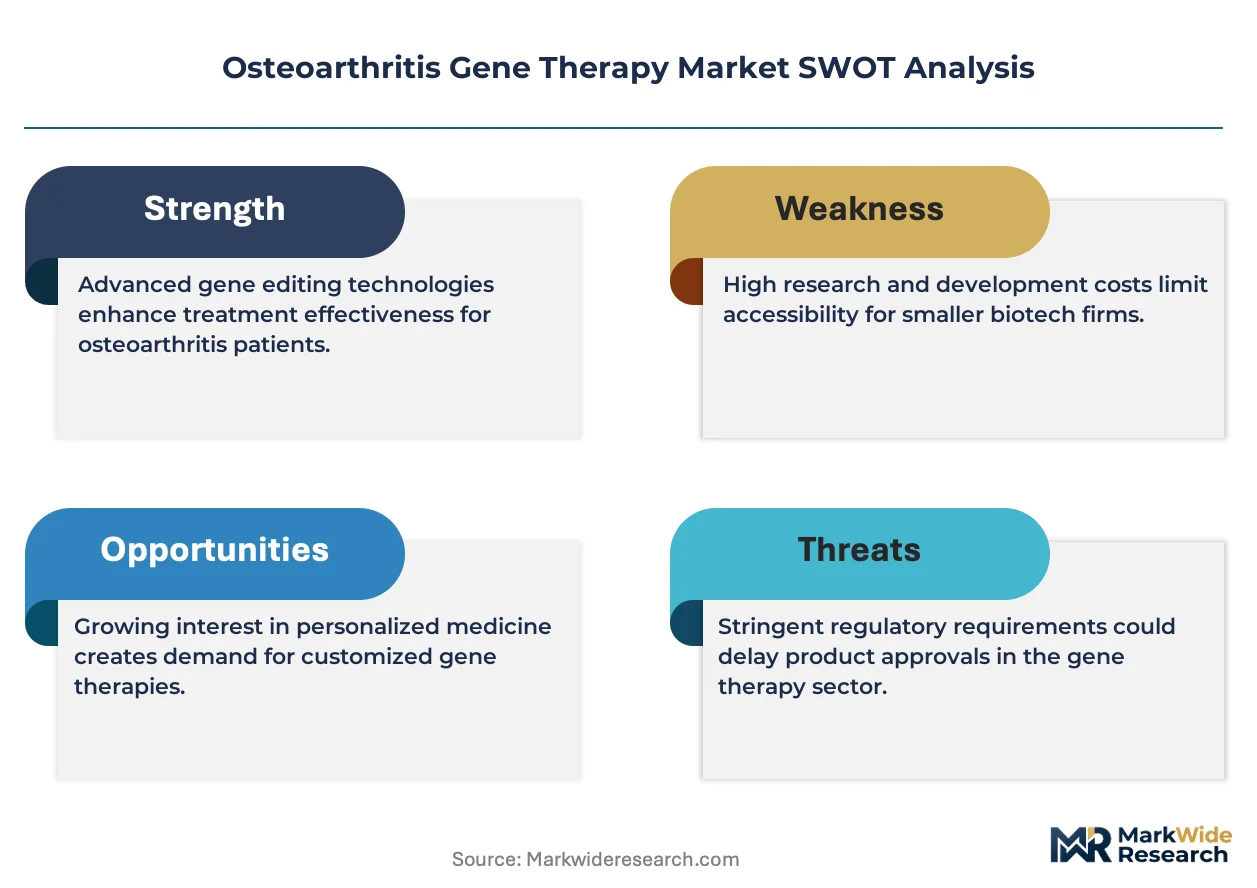
The osteoarthritis gene therapy sector faces a structural tension between durable therapeutic ambition and transient expression kinetics, forcing developers to optimize vector persistence while regulators demand long-term safety data that outpaces clinical trial timelines.
Growth Catalysts
- PMDA Conditional Approval Pathway:Japan's accelerated regenerative medicine framework compresses commercialization timelines for intra-articular gene therapies, attracting pipeline investment toward Asia-Pacific first launches.
- Hospital Orthopedic Departments:Mature arthroscopic delivery protocols and image-guided injection capabilities position these settings as primary adoption channels for single-administration gene therapies.
- CRISPR Editing Platforms:Preclinical programs targeting cartilage-anabolic gene activation are expanding addressable patient populations beyond inflammatory cytokine modulation.
Market Restraints
- Plasmid DNA Supply Concentration:GMP-grade nucleic acid manufacturing clusters in the United States and Germany, creating single-source vulnerability for viral vector production.
- EMA ATMP Reimbursement Negotiations:European member state-level pricing disputes for advanced therapy medicinal products delay market access despite centralized approval.
- Transient Expression Kinetics:Adenoviral vectors require repeat dosing for sustained therapeutic effect, undermining the single-injection value proposition against hyaluronic acid alternatives.
Strategic Opportunities
- RNA Therapeutics Convergence:Synthetic mRNA platforms bypass nuclear delivery barriers while reducing immunogenicity risks associated with viral packaging.
- Underpenetrated German Market:Specialized cell-and-gene therapy manufacturing infrastructure in Heidelberg and Cologne supports localized production for EU distribution.
- Telemedicine-Enabled Patient Identification:Remote radiographic screening protocols expand reach into rural orthopedic populations previously excluded from trial recruitment.
Industry Challenges
- Vector Manufacturing Scale-Up:Suspension bioreactor optimization for AAV production requires capital deployment exceeding traditional biologics capacity.
- Chemistry-Manufacturing-Controls Documentation:FDA Office of Cellular, Tissue, and Gene Therapies demands extensive lot-to-lot consistency data that extends IND-to-NDA intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteoarthritis Gene Therapy Market |
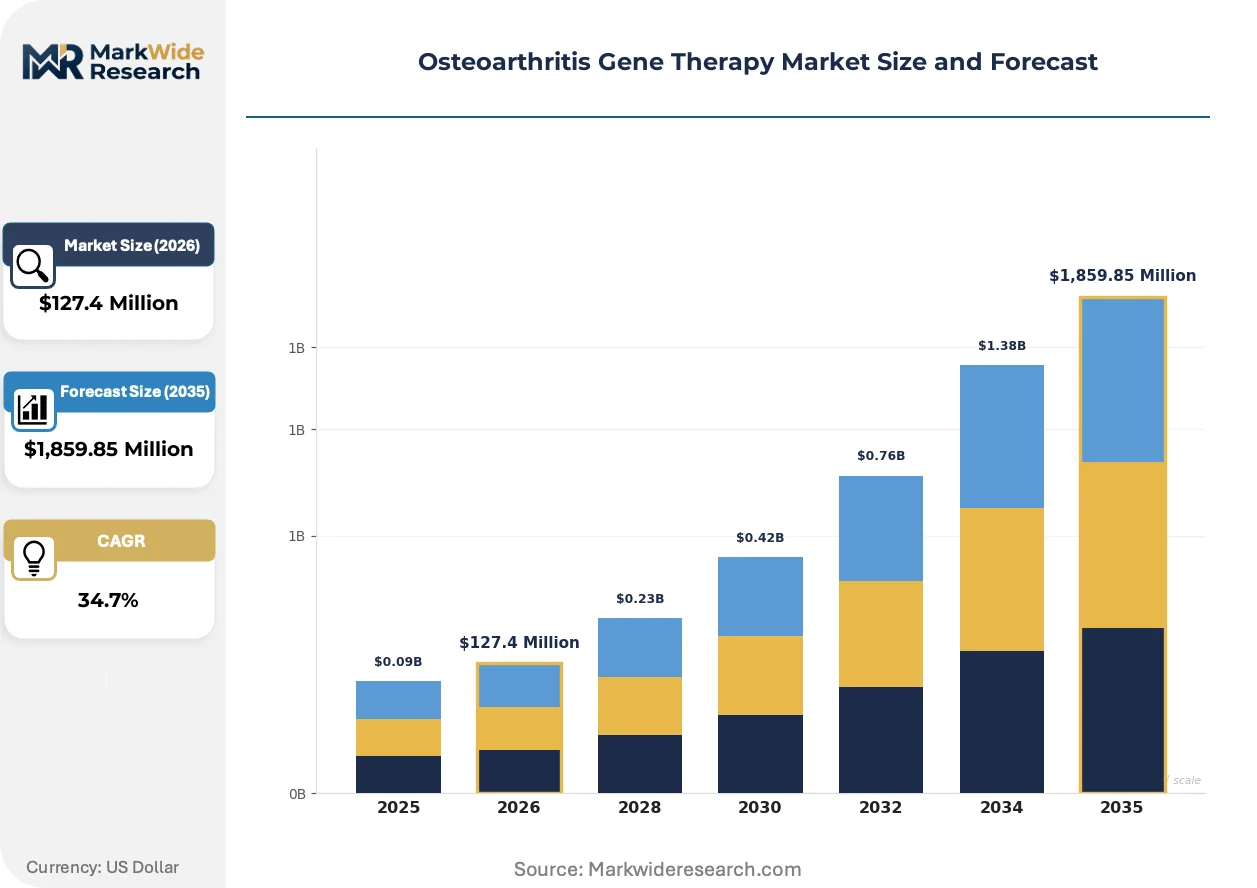
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $1,859.85 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviral Vectors, Lentiviral Vectors, Plasmid DNA, RNA Therapeutics Technology: CRISPR, Gene Editing, RNA Interference, Viral Delivery End User: Hospitals, Research Institutes, Clinics, Biotechnology Companies Application: Joint Pain Management, Cartilage Regeneration, Inflammation Reduction, Disease Modification |
| Companies Covered | Kolon TissueGene, Genascence, Novartis AG, Pacira BioSciences, Xalud Therapeutics, GeneQuine Biotherapeutics, Flexion Therapeutics, Belief BioMed, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteoarthritis Gene Therapy Market Evolving Landscape
Vector engineering and regulatory science are converging to redefine therapeutic durability standards, with developers racing to match expression persistence with payer expectations for single-administration value.
Adeno-associated viral vectors are consolidating market position as the preferred intra-articular delivery vehicle for knee osteoarthritis programs. Hospital-based orthopedic departments in the United States and Japan are prioritizing AAV candidates for their superior safety profiles and reduced immunogenicity relative to lentiviral alternatives. This vector preference is compressing investment into transient expression platforms while concentrating manufacturing expertise in established bioreactor facilities.
EMA advanced therapy medicinal product frameworks are standardizing chemistry-manufacturing-controls requirements across European member states. The classification system determines centralized assessment pathways and post-authorization evidence obligations for gene therapies. German and French regulators are aligning lot release testing protocols, reducing redundant quality reviews that previously fragmented EU market entry timelines.
Specialized orthopedic centers are demanding outcome-based contracting structures that tie reimbursement to structural joint preservation rather than symptomatic relief metrics. Hospital procurement committees in Japan and the United States are piloting multi-year payment models contingent on MRI-verified cartilage thickness maintenance. This behavioral shift pressures developers to invest in radiographic endpoint validation earlier in clinical development than traditional pain-score primary outcomes required.
Osteoarthritis Gene Therapy Market Segmentation
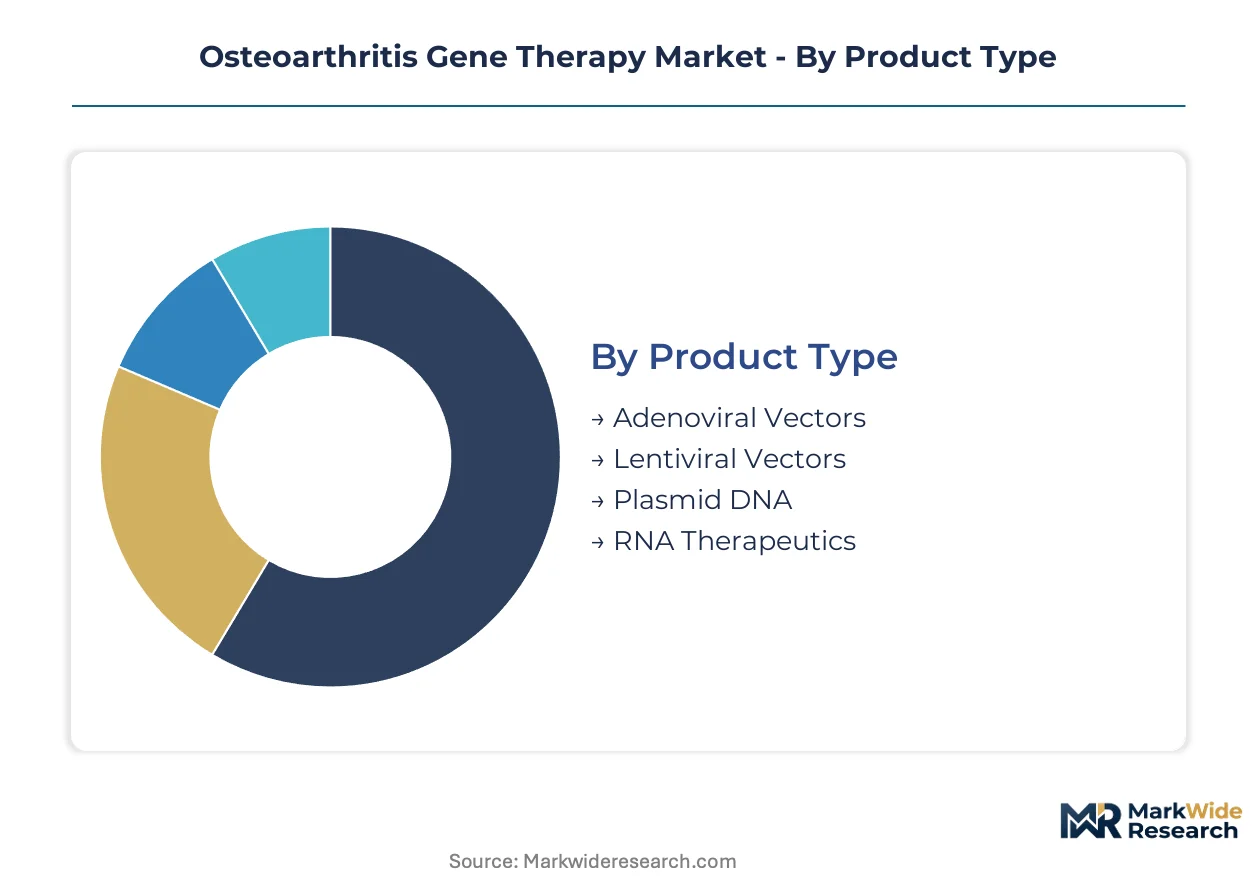
Segmentation in osteoarthritis gene therapy reveals distinct commercial pathways where vector selection determines manufacturing complexity, regulatory strategy, and reimbursement negotiation leverage. Understanding these divisions exposes where development capital concentrates and which technology platforms face scaling constraints.
Product Type:
Adenoviral vectors dominate standalone intra-articular applications where transient expression suits localized cytokine modulation, while lentiviral alternatives embed into systemic delivery research programs requiring genomic integration.
- Adenoviral Vectors:These non-integrating DNA vectors achieve high transduction efficiency in synovial tissue with established GMP production protocols at contract manufacturers in the United States and Germany. Hospital orthopedic departments in Japan favor adenoviral candidates for their predictable clearance kinetics and lower immunogenicity risk compared to persistent alternatives. Demand clusters where regulatory pathways prioritize safety documentation over long-term integration studies.
- Lentiviral Vectors:Integrating RNA-based platforms enable sustained therapeutic protein expression through genomic incorporation, attracting research institute partnerships targeting cartilage-anabolic gene activation. Manufacturing complexity limits commercial deployment to specialized facilities with biosafety level containment, concentrating supply in Heidelberg and Boston cell therapy clusters. The technology carries higher FDA chemistry-manufacturing-controls scrutiny due to insertional mutagenesis risk profiles.
- Plasmid DNA:Direct nucleic acid delivery bypasses viral packaging constraints with simplified cold-chain logistics and reduced immunogenicity.
- RNA Therapeutics:Synthetic mRNA platforms enable rapid program initiation without nuclear delivery requirements, appealing to biotechnology company discovery pipelines.
Volume placements concentrate in adenoviral vectors; the faster expansion belongs to RNA therapeutics.
Technology:
Cost tier stratification separates premium-priced precision editing platforms from standardized viral delivery infrastructure, with RNA interference occupying a mid-tier development efficiency position.
- CRISPR:Programmable nuclease systems enable permanent cartilage-anabolic gene activation with single-administration durability potential that aligns with payer demands for structural joint preservation outcomes. Preclinical pipelines at German and Japanese research institutes concentrate on collagen-modifying targets, though clinical translation awaits delivery optimization and off-target validation studies. The platform commands the highest technical valuation in partnership negotiations.
- Gene Editing:Zinc finger and TALEN alternatives provide established intellectual property positions with reduced licensing complexity for commercial-stage developers. Manufacturing integration at dedicated cell therapy facilities in Cologne and Singapore supports earlier-stage clinical programs seeking differentiation from CRISPR-saturated competitive landscapes. These platforms trade some flexibility for predictable regulatory precedent.
- RNA Interference:Transient gene silencing via synthetic oligonucleotides offers reduced manufacturing scale requirements and faster toxicology timelines.
- Viral Delivery:Constrained to natural tropism engineering rather than genomic modification, this mature technology anchors near-term revenue potential.
Margin capture clusters around CRISPR platforms; steepest expansion trajectory belongs to RNA interference as development timelines compress.
End User:
Customer type segmentation distinguishes volume purchasers with standardized procurement protocols from specialized adopters requiring customized clinical support and outcome-based contracting structures.
- Hospitals:Orthopedic departments with arthroscopic capabilities and image-guided injection infrastructure represent the primary commercial channel for intra-articular gene therapy administration. Japanese hospital networks leverage PMDA conditional approval pathways to compress adoption timelines, while United States academic medical centers anchor Phase III trial recruitment and post-market surveillance obligations.
- Research Institutes:Heidelberg, Boston, and Tokyo clusters drive preclinical vector optimization and biomarker validation for cartilage preservation endpoints.
- Clinics:Ambulatory settings with specialized rheumatology or sports medicine focus require simplified cold-chain handling and reduced administration complexity.
- Biotechnology Companies:Development-stage firms lacking in-house viral manufacturing partner with contract organizations for IND-enabling toxicology and GMP lot production.
Procurement volume concentrates in hospitals; clinics are gaining share fastest as administration protocols simplify.
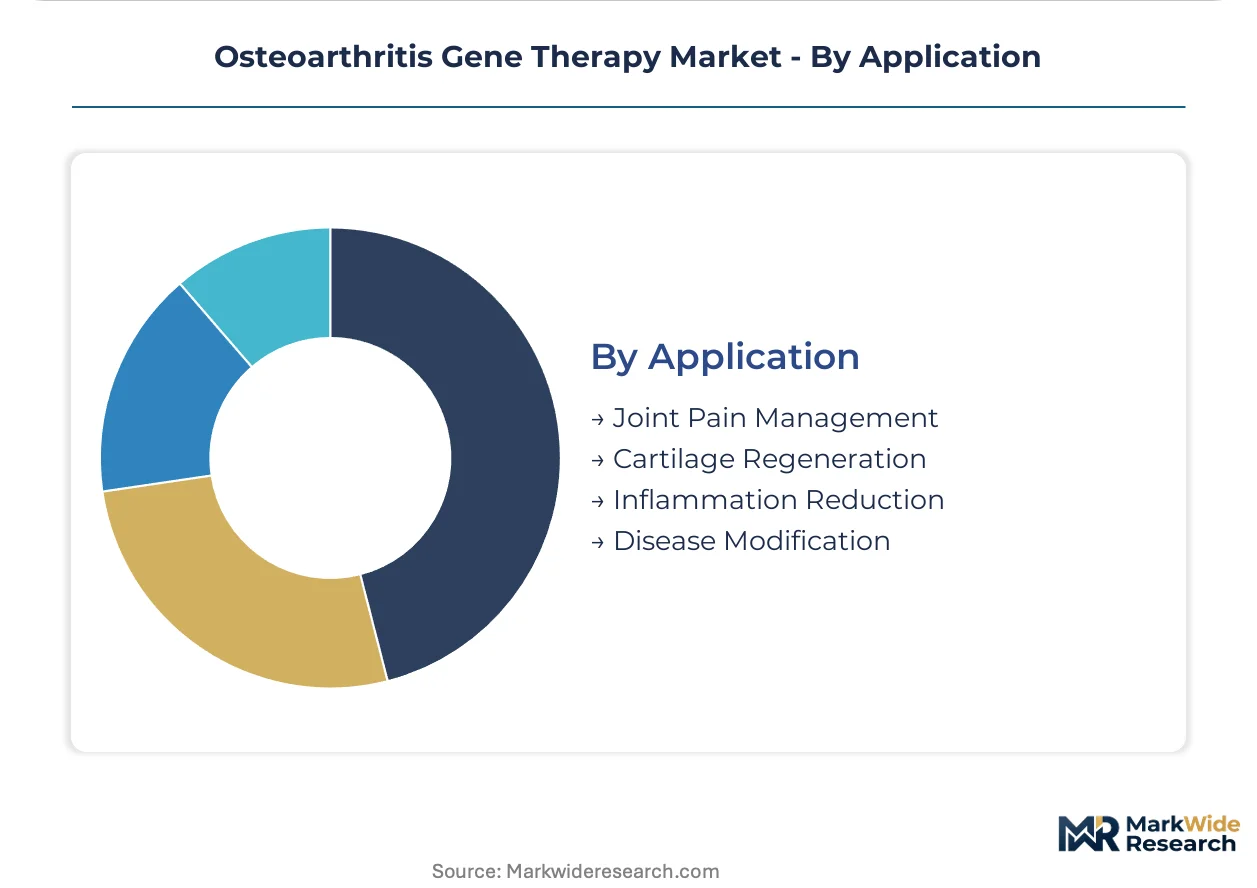
Application:
Application maturity separates symptomatic relief indications with established reimbursement codes from disease-modifying claims requiring novel endpoint validation and long-term structural benefit evidence.
- Joint Pain Management:Symptomatic endpoints align with existing orthopedic reimbursement frameworks, enabling faster commercial access though limiting pricing power against generic hyaluronic acid alternatives. United States hospital procurement committees evaluate gene therapy candidates against established corticosteroid cost benchmarks, pressuring developers to demonstrate durability advantages.
- Cartilage Regeneration:Structural joint preservation claims require MRI-validated endpoint protocols and multi-year follow-up data that extend development timelines but support premium pricing in outcome-based contracts. German orthopedic centers pilot radiographic monitoring protocols that may standardize across EMA member states.
- Inflammation Reduction:Cytokine modulation via interleukin-1 pathway targeting offers mechanistic clarity for regulatory submissions with established biomarker readouts.
- Disease Modification:Halting radiographic progression represents the highest-evidence threshold with corresponding reimbursement negotiation complexity.
Current placements concentrate in joint pain management; cartilage regeneration is climbing the fastest toward commercial priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where specialized cell-and-gene therapy manufacturing infrastructure supports clinical development and commercial production.
United States
Hospital-based orthopedic departments in academic medical centers drive clinical trial recruitment and post-market surveillance for intra-articular gene therapies. FDA Office of Cellular, Tissue, and Gene Therapies shapes chemistry-manufacturing-controls requirements and trial endpoints. The Greater Boston and San Francisco Bay Area clusters anchor contract manufacturing organizations producing GMP-grade viral vectors.
Germany
Specialized orthopedic centers in Heidelberg and Cologne pilot radiographic monitoring protocols for cartilage preservation endpoints. EMA advanced therapy medicinal product frameworks determine centralized assessment pathways and post-authorization evidence obligations. The Heidelberg cell therapy cluster supports lentiviral vector production with biosafety level containment capabilities.
Japan
PMDA conditional approval pathways compress commercialization timelines for regenerative medicine products including intra-articular gene therapies. Hospital networks leverage accelerated frameworks to adopt single-administration therapies ahead of other Asia-Pacific markets. Tokyo and Osaka academic medical centers anchor Phase III trial recruitment and real-world evidence collection.
United Kingdom
Research institutes in London and Cambridge drive preclinical vector optimization and biomarker validation for disease-modification claims. MHRA alignment with EMA ATMP classifications streamlines regulatory submissions following Brexit transition periods. The Cambridge biotech cluster attracts biotechnology company partnerships for RNA therapeutic platform development.
Switzerland
Swissmedic oversight of advanced therapy medicinal products provides regulatory precedent for European market access strategies. Basel and Zurich host specialized manufacturing facilities supporting viral vector production for orthopedic gene therapy candidates. The country's pricing and reimbursement negotiations for ATMPs influence parallel discussions across neighboring EMA member states.
Osteoarthritis Gene Therapy Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek manufacturing scale and regulatory expertise. The market structures around three tiers: multinational pharmaceutical conglomerates with cell-and-gene therapy infrastructure, mid-cap biotechnology firms with platform specialization, and emerging entities focused on single-vector modalities. Two archetypes predominate: integrated manufacturers controlling supply chains from plasmid to finished vector, and platform licensors monetizing delivery technologies through partnership structures. Competitive moves center on manufacturing capacity expansion and outcome-based contracting capabilities.
Among the integrated pharmaceutical tier, Novartis AG anchors multi-continental manufacturing footprints for complex biologics. Genascence occupies a position within the sustained-release platform specialist archetype, while Kolon TissueGene exemplifies the regional biotechnology model with distinct vector engineering approaches. These three entities represent divergent strategic postures toward intra-articular delivery optimization and single-injection durability claims.
| Leading Market Players |
|---|
| Kolon TissueGene |
| Genascence |
| Novartis AG |
| Pacira BioSciences |
| Xalud Therapeutics |
| GeneQuine Biotherapeutics |
| Flexion Therapeutics |
| Belief BioMed |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Plasmid DNA spot pricing volatility in United States and German manufacturing hubs cascades through viral vector production tiers, compressing margins for adenoviral-based therapies while amplifying pricing power for developers with captive nucleic acid supply.
Pricing Analysis
High-volume adenoviral vector contracts anchor the lower pricing tier through standardized GMP production protocols, while CRISPR-edited platforms and sustained-release formulations capture premium positioning via single-administration durability claims. Price differentiation hinges on FDA Office of Cellular, Tissue, and Gene Therapies approval tier and lot-to-lot consistency documentation. Cost compression in the adenoviral segment is intensifying as contract manufacturers compete for hospital orthopedic department procurement contracts. Biotechnology companies with in-house viral packaging capabilities exhibit the lowest price sensitivity; ambulatory clinics purchasing through group purchasing organizations face the highest.
Supply Chain Analysis
Regional distribution centers in Boston, Heidelberg, and Tokyo operate hub-and-spoke patterns for temperature-controlled vector shipments to hospital networks. GMP-grade plasmid DNA production concentrates in the United States and Germany, with AAV packaging services clustered in the same geographies plus Singapore. Raw material dependencies include fetal bovine serum, transfection reagents, and specialized chromatography resins. Single-source vulnerability in plasmid DNA supply creates concentration risk for developers lacking dual-source qualification. Distribution runs through specialized cold-chain logistics providers with real-time temperature monitoring to orthopedic surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race. Developers are pursuing backward integration into plasmid DNA manufacturing to secure supply and defend margin position against contract manufacturer pricing power.
For Market Incumbents: Acquire GMP-grade plasmid DNA manufacturing assets to reduce dependency on United States and German contract suppliers. Secure long-term supply agreements with hospital orthopedic departments before PMDA conditional approval pathways attract additional competitors. The threat of RNA therapeutic platforms with reduced manufacturing complexity pressures adenoviral-dependent revenue streams. Capacity addition in Singapore or Japan provides geographic diversification against trans-Atlantic logistics disruption. For New Entrants and Emerging Players: Telemedicine-enabled patient identification routes offer lowest customer acquisition cost for rural orthopedic populations excluded from traditional trial recruitment. Target German orthopedic centers piloting radiographic monitoring protocols for cartilage regeneration endpoints, as these settings seek novel disease-modifying therapies with validated structural benefit claims. A licensing partnership with established AAV packaging facilities accelerates IND timelines without capital-intensive manufacturing buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-specialist biotechnology firms with validated intra-articular delivery data in Japan or United States Phase II trials. Long-term viability across a five-to-ten year horizon rests on outcome-based contracting capabilities and reimbursement negotiation infrastructure rather than pipeline breadth alone. Watch for EMA ATMP reimbursement resolution in Germany and France as the signal indicating European market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Suspension bioreactor deployment at Heidelberg and Boston facilities secures AAV supply for Phase III programs. |
| Regulatory Approval Pathway | PMDA conditional approval compresses Japan commercialization timelines ahead of FDA standard review. |
| Licensing Agreement | RNA therapeutic platform partnerships bypass viral packaging constraints and accelerate development timelines. |
| Clinical Trial Advancement | MRI-validated cartilage preservation endpoints support outcome-based contracting with hospital procurement committees. |
| Pipeline Diversification | CRISPR-based gene editing programs expand addressable populations beyond cytokine modulation targets. |
Research Methodology
FDA filings, EMA centralized assessment records, and ClinicalTrials.gov protocol databases formed the secondary backbone, cross-referenced with primary interviews involving gene therapy development executives, regulatory affairs leads at ATMP sponsors, hospital procurement managers, and payer access specialists. Bottom-up and top-down triangulation validated segment-level assumptions against contract manufacturer capacity disclosures and orthopedic department adoption surveys.
Bottom-up modeling anchored volume projections to hospital-based administration capacity and intra-articular injection protocol penetration, while top-down analysis tested aggregate market evolution against cell-and-gene therapy infrastructure investment patterns. Segmentation dimensions included vector type, technology platform, end-user setting, and application claim tier. CAGRs were derived from logistic diffusion curves fitted to regulatory approval probability-weighted revenue streams, with inputs from GMP manufacturing cost trajectories and reimbursement negotiation timelines.
The model holds under stable FDA and EMA ATMP regulatory frameworks; deviation in Japan PMDA conditional approval criteria or EMA member state reimbursement disputes would shift commercialization timing assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market